
 Europe Thermal Power Market | 2026-2036
Europe Thermal Power Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Thermal Power Market Foresight
Modular plant configurations is expanding buyer choice across Europe as utilities seek scalable capacity additions without committing to full-scale greenfield builds. Engie SA leverages its distributed generation expertise to deploy flexible gas turbine modules in France and Belgium. Siemens AG anchors the supply landscape with advanced combined-cycle technology optimized for hydrogen cofiring. Electricité de France SA sustains its nuclear-thermal hybrid positioning while competing in gas peaker markets.
Thermal power denotes electricity and heat generation from combustion or steam-driven turbine systems, typically operating at temperatures between five hundred and six hundred degrees Celsius for steam cycles and up to fourteen hundred degrees Celsius for gas turbines, serving baseload, mid-merit, and peaking roles in European energy systems. Coal technology retains installed capacity dominance but faces accelerated retirement schedules under EU emissions trading, while natural gas technology captures incremental growth as a bridge fuel with lower carbon intensity per megawatt-hour. Biomass applications within district heating represent the fastest-expanding margin pool, particularly in Nordic and Baltic markets where forestry residues supply combined heat and power plants.
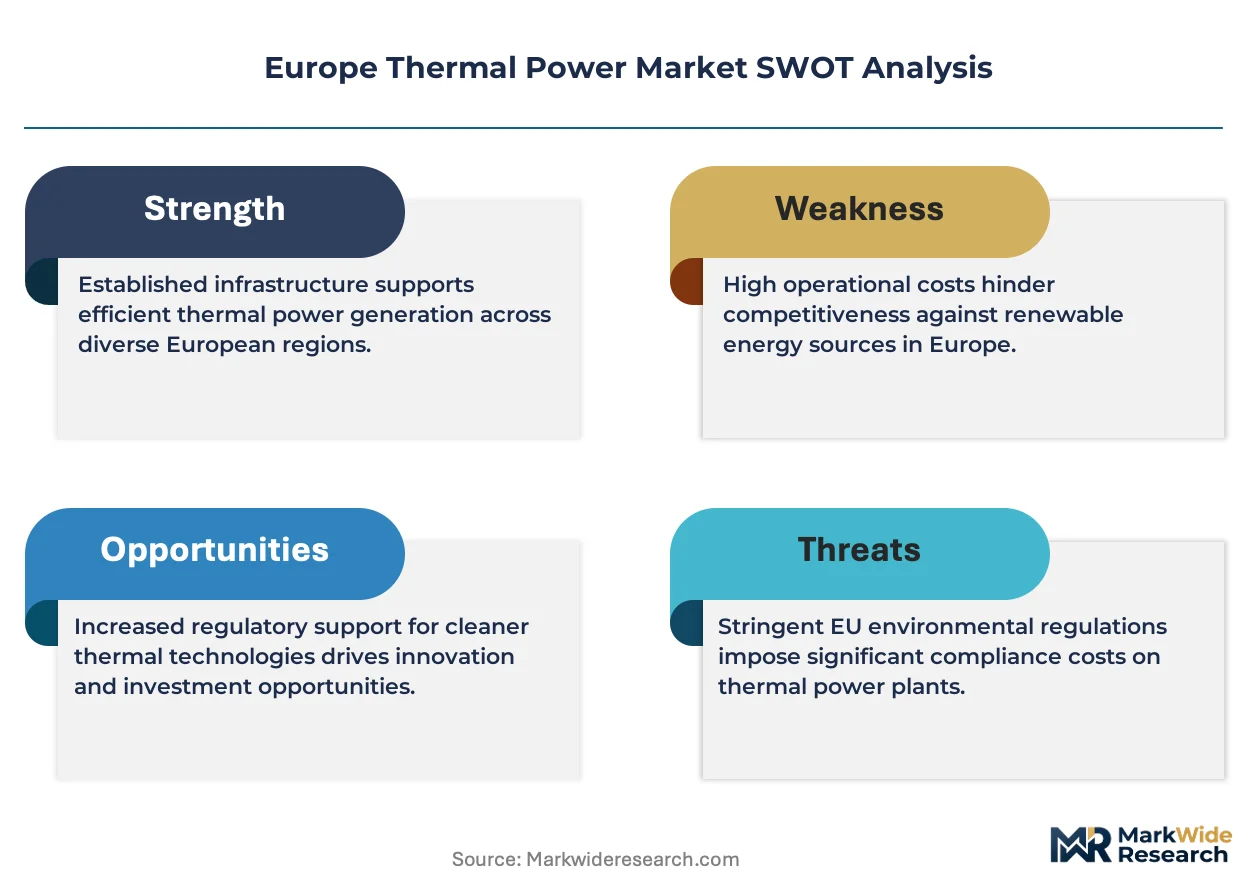
The EU Green Deal, the EU Emissions Trading System, and national carbon floor prices in the United Kingdom and France are reshaping thermal power economics by penalizing unabated coal and rewarding lower-carbon gas and biomass operations. EMA guidelines on industrial emissions and the Industrial Emissions Directive enforce best available techniques for nitrogen oxides and sulfur dioxide controls, raising compliance costs for aging lignite plants in Poland and eastern Germany. Stakeholders must monitor hydrogen readiness certifications and carbon capture readiness mandates as these standards will determine which thermal assets retain long-term viability in Europe's decarbonized power system.
Market Dynamics
The EU Green Deal and the EU Emissions Trading System are forcing a wholesale reconfiguration of thermal power economics across Europe. Asset owners must now choose between costly retrofits for carbon capture readiness or accelerated retirement schedules for legacy coal and lignite plants.
Growth Catalysts
- Industrial Emissions Directive:The directive mandates best available techniques for nitrogen oxides and sulfur dioxide controls, creating replacement demand for modern gas turbine and biomass systems in Poland and eastern Germany.
- District heating networks:Municipal utilities in Nordic and Baltic markets are expanding combined heat and power capacity to serve dense urban heating loads with forestry residue feedstock.
- Hydrogen cofiring readiness:Natural gas turbines with 30 percent hydrogen blending capability are capturing incremental capacity awards as bridge fuel investments ahead of full green hydrogen deployment.
Market Restraints
- Carbon price volatility:EU ETS allowance price swings above 80 euros per tonne are compressing operating margins for unabated gas plants and complicating long-term power purchase agreement pricing.
- Lignite supply concentration:Domestic lignite mining in Germany and Poland faces accelerated phase-out timelines, stranding specialized fuel handling infrastructure and local employment bases.
- Intermittency integration costs:Grid balancing services from thermal plants must absorb rising cycling duty as renewable penetration climbs, accelerating wear on steam turbine components and raising maintenance intensity.
Strategic Opportunities
- Biomass conversion of coal plants:Existing turbine halls in Denmark and the Netherlands are being repowered with wood pellet firing systems, preserving grid connection assets while eliminating coal combustion.
- Waste heat recovery in industrial clusters:Port of Rotterdam and Rhine-Ruhr chemical corridors are deploying thermal power as anchor loads for integrated heat networks serving refineries and process industries.
- Carbon capture readiness certification:The EU Green Deal's net-zero 2050 mandate is creating first-mover advantage for plants engineered with post-combustion capture tie-in points and CO2 transport pipeline access.
Industry Challenges
- Turbomachinery engineering talent:The retirement wave of specialists in steam turbine blade design and high-temperature metallurgy is outpacing university pipeline output across Germany and France.
- Hydrogen embrittlement materials science:Gas turbine hot gas path components require accelerated qualification programs for 100 percent hydrogen combustion temperatures and flame dynamics.
- Legacy control system integration:Digital retrofit of 1980s-era distributed control systems with modern grid code compliance modules is extending outage durations and raising project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Thermal Power Market |
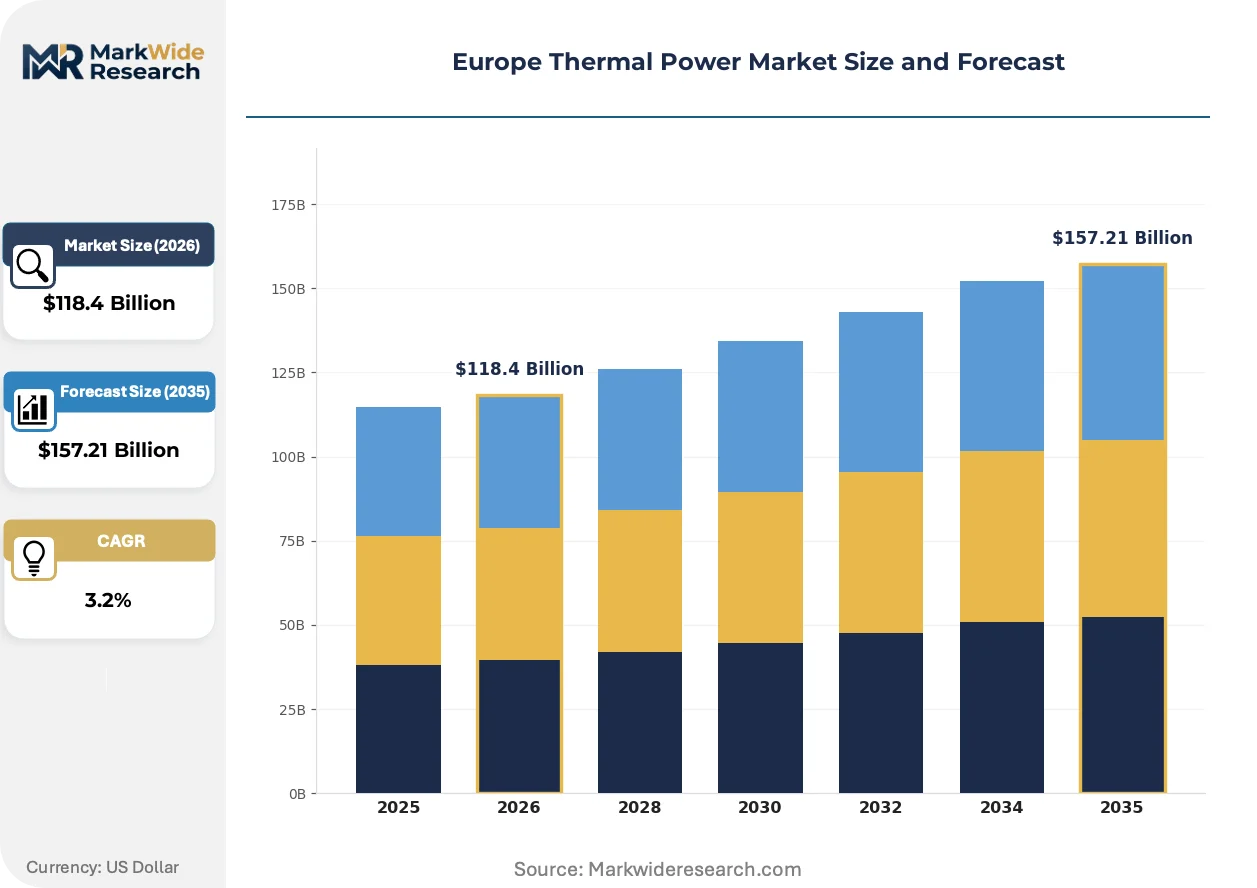
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $157.21 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Coal, Natural Gas, Biomass, Oil Application: Industrial Heating, Power Generation, District Heating, Waste Treatment End User: Manufacturing, Utilities, Residential, Commercial Fuel Type: Renewable, Non-Renewable, Diesel, Others |
| Companies Covered | Engie SA, Enel S.p.A, Electricité de France SA, Rosatom State Atomic Energy Corporation, Siemens AG, General Electric Company, American Electric Power Company, Inc., Chubu Electric Power, TotalEnergies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Thermal Power Market Shifts & Advancements
Modular plant architectures and hydrogen-ready turbine designs are absorbing capital allocation that previously flowed to centralized greenfield developments. Technology roadmaps now prioritize fuel flexibility over single-fuel optimization.
Advanced gas turbines with sequential combustion architecture are absorbing the technical risk of hydrogen cofiring progression. Siemens Energy and Ansaldo Energia are deploying these systems for German and Italian utilities seeking 30 percent hydrogen capability by 2028 and full conversion by 2035. The technology is absorbing market share from aeroderivative turbines in mid-merit applications where fuel flexibility outweighs startup speed.
The F-Gas Regulation and EU Green Deal are compressing investment timelines for coal-to-gas conversions. National carbon floor prices in France and the United Kingdom are rendering unabated coal operation uneconomic regardless of EU ETS price levels. Eastern European utilities are responding with accelerated procurement of combined-cycle blocks to preserve grid stability while meeting Industrial Emissions Directive limits.
Utility procurement is consolidating around long-term service agreements with guaranteed heat rate and availability performance. District heating operators in Sweden and Finland are unbundling equipment supply from twenty-year maintenance contracts, shifting operational risk to OEM service arms. This pattern is most visible in Nordic markets where municipal ownership structures favor fixed-cost predictability over capital ownership.
Europe Thermal Power Market Segmentation
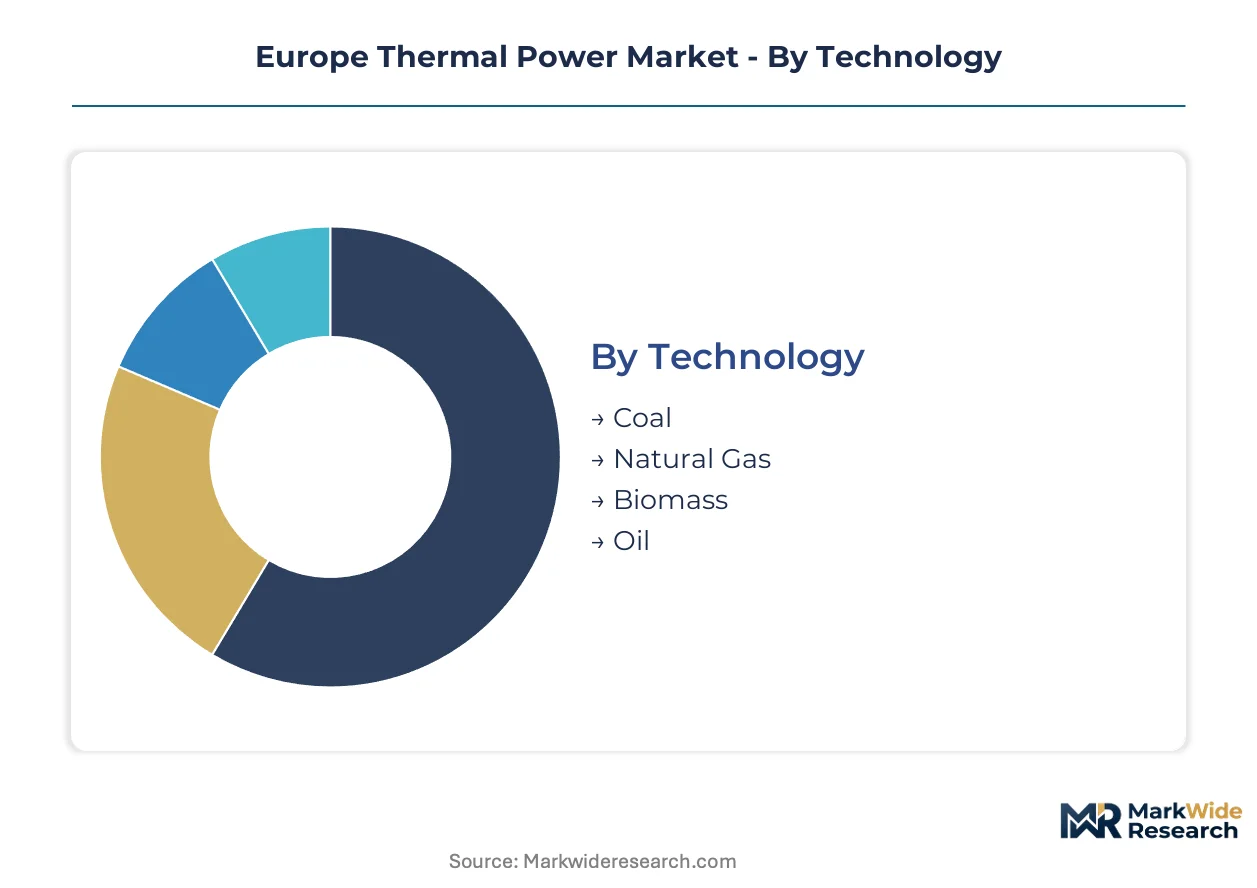
Technology differentiation determines equipment selection cycles and retrofit economics across European thermal portfolios. Fuel flexibility specifications now dominate procurement criteria as asset owners hedge against carbon price volatility and hydrogen infrastructure timelines.
Technology:
Upgrade and replacement cycles vary dramatically by combustion system maturity and emissions compliance deadlines.
- Natural Gas:Combined-cycle blocks with sequential combustion architecture dominate new capacity awards. German and Italian utilities prioritize turbines with 30 percent hydrogen cofiring capability to satisfy EU Green Deal transition pathways while preserving grid stability services.
- Biomass:Forestry residue combustion systems in combined heat and power configuration serve Nordic district heating networks. Denmark and Sweden lead deployment where carbon-neutral heat supply qualifies for national renewable heat incentives under EU Emissions Trading System exemptions.
- Coal:Pulverized fuel and fluidized bed systems face accelerated retirement schedules under Industrial Emissions Directive limits.
- Oil:Distillate-fired peaking plants retain niche roles in Mediterranean island grids and backup power applications.
Volume placements concentrate in Natural Gas; the faster expansion belongs to Biomass.
Application:
Cost tier differentiation separates baseload investments from peaking and balancing services procurement.
- District Heating:Combined heat and power plants supply dense urban heating loads in Poland, Germany, and Nordic markets. Municipal utilities favor biomass and gas cogeneration to decarbonize heat supply while retaining distribution network control.
- Power Generation:Merchant gas turbines and combined-cycle blocks compete for capacity market contracts and grid balancing revenues. French and UK carbon floor prices render unabated coal uneconomic regardless of EU ETS allowance levels.
- Industrial Heating:Process steam and high-temperature heat for refineries, chemicals, and pulp mills.
- Waste Treatment:Energy-from-waste incineration with power recovery serves urban waste management mandates.
Capital deployment tilts toward District Heating in municipal markets; Industrial Heating captures the steepest expansion trajectory as process industries electrify selectively.
End User:
Customer type determines contracting structure, fuel procurement strategy, and regulatory exposure.
- Utilities:Vertically integrated power and heat suppliers operate under EU Emissions Trading System compliance obligations. EDF, Engie, and RWE anchor procurement volumes with long-term service agreements covering availability guarantees and heat rate performance.
- Manufacturing:Energy-intensive industries deploy captive thermal power for process heat and electricity cost hedging. Rhine-Ruhr chemical corridors and Port of Rotterdam refining clusters integrate waste heat recovery with grid export capability.
- Residential:Apartment block and district heating subscriptions.
- Commercial:Hospital, university, and data center campus cogeneration systems.
Contracting activity concentrates in Utilities; Manufacturing is gaining share fastest as industrial clusters pursue carbon capture readiness certification.
Fuel Type:
Supply concentration and carbon intensity differentiate procurement economics across fuel categories.
- Non-Renewable:Natural gas and coal procurement faces EU ETS cost pass-through and carbon border adjustment exposure. German and Polish utilities hedge price volatility through long-term pipeline contracts and LNG portfolio diversification.
- Renewable:Forestry residues, agricultural waste, and biogas qualify for renewable energy certificate schemes. Baltic and Nordic markets exploit domestic feedstock availability to minimize transport emissions and supply security risks.
- Diesel:Emergency backup and remote power applications.
- Others:Industrial waste gases, refinery residues, and emerging hydrogen blends.
Procurement volumes concentrate in Non-Renewable; Renewable is climbing the fastest as national biomass support schemes expand eligible feedstock categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in coal-dependent basins while consumption demand shifts toward gas and biomass in industrial corridors. The EU Green Deal is accelerating this divergence through carbon pricing mechanisms. National regulators are enforcing divergent phase-out timelines that reshape investment geography.
Germany
Rhine-Ruhr chemical clusters and Lusatian lignite fields drive divergent thermal strategies. The Coal Phase-Out Act mandates 2038 termination for lignite operations, forcing RWE and LEAG to accelerate gas turbine procurement. Hamburg and Berlin district heating networks are repowering with hydrogen-ready combined-cycle blocks.
Poland
Upper Silesian coal basins and Baltic Sea LNG terminals anchor competing fuel strategies. The Industrial Emissions Directive is compelling PGE and Tauron to retrofit lignite plants or retire capacity ahead of schedule. Warsaw and Krakow municipal utilities are expanding biomass cogeneration to meet EU ETS compliance deadlines.
Italy
Po Valley industrial demand and Sardinian coal retirement schedules shape procurement priorities. The National Energy and Climate Plan is redirecting ENEL and A2A toward gas peakers with hydrogen cofiring capability. Milan and Turin district heating operators are deploying high-efficiency combined heat and power units.
France
Nuclear-thermal hybrid positioning and carbon floor pricing create distinctive competitive dynamics. EDF is leveraging its fleet for grid balancing while Engie deploys distributed gas generation. Lyon and Marseille industrial clusters are integrating waste heat recovery with thermal power exports.
Sweden
Forestry residue abundance and district heating density enable biomass leadership. The Renewable Energy Directive exemption for sustainable biomass is sustaining Vattenfall and Fortum investment in combined heat and power. Stockholm and Gothenburg municipal networks are unbundling equipment procurement from long-term service contracts.
Europe Thermal Power Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology and geography vectors. The market exhibits tiered concentration where integrated utilities with generation portfolios coexist with equipment OEMs and project developers. Strategic archetypes span vertically integrated energy majors, turbine technology licensors, and district heating operators with captive demand. Competitive intensity manifests through long-term service agreement contests and hydrogen readiness certification races.
Among French-based integrated utilities, Engie SA and Electricité de France SA exemplify divergent strategic postures within the same regulatory environment. Siemens AG occupies a position as a German engineering conglomerate with turbine technology exposure. These three entities anchor distinct competitive vectors: distributed generation deployment, nuclear-thermal hybrid operations, and equipment-manufacturing scale.
| Leading Market Players |
|---|
| Engie SA |
| Enel S.p.A |
| Electricité de France SA |
| Rosatom State Atomic Energy Corporation |
| Siemens AG |
| General Electric Company |
| American Electric Power Company, Inc. |
| Chubu Electric Power |
| TotalEnergies |
| Others |
Supply & Pricing Matrix
TTF natural gas price volatility cascades through European thermal power supply chains, compressing margins for combined-cycle operators while elevating long-term service agreement premiums for hydrogen-ready turbine fleets.
Pricing Analysis
Margin tightening in merchant gas generation reflects EU ETS allowance cost pass-through and carbon border adjustment exposure. Three-tier pricing structure across premium hydrogen-ready, standard combined-cycle, and economy peaker tiers separates equipment procurement by fuel flexibility certification. Price differentiation hinges on guaranteed heat rate performance and twenty-year maintenance bundling. Industrial offtakers in Rhine-Ruhr chemical corridors exhibit lowest price sensitivity; municipal utilities in Poland and Baltic markets face acute budget constraints.
Supply Chain Analysis
Baltic Sea freight rates for LNG cargo and specialized turbine components strain just-in-time delivery schedules for Eastern European project timelines. Manufacturing concentrates in Germany, Italy, and Japan for heavy-duty gas turbine rotors and combustion hardware. Component sourcing draws from nickel superalloy foundries in Germany, precision casting facilities in Italy, and advanced coating specialists in Japan. Single-source vulnerability persists for sequential combustion system intellectual property. Distribution runs through EPC contractor networks anchored by Siemens Energy and Ansaldo Energia service arms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European thermal power equipment supply is tightening around hydrogen-ready turbine manufacturing capacity, sustaining pricing power for OEMs with certified 30 percent cofiring platforms.
For Market Incumbents: Anticipate accelerated retirement schedules for legacy coal and lignite fleets under EU Green Deal enforcement. Defend installed base revenues through long-term service agreement renewals with availability guarantees. Prioritize backward integration into hydrogen combustion testing facilities to capture certification premiums before 2030 compliance deadlines. For New Entrants and Emerging Players: Begin with biomass conversion retrofit opportunities in Denmark and Netherlands where coal plant repowering preserves grid connection assets. Target Nordic district heating networks for combined heat and power deployment under renewable heat incentive schemes. Pursue waste heat recovery integration in Port of Rotterdam and Rhine-Ruhr industrial clusters as anchor load contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor stranded coal assets with carbon capture readiness certification in Poland and eastern Germany. Long-term viability centers on hydrogen pipeline access and CO2 transport infrastructure proximity. Watch EU ETS allowance price sustained above eighty euros per tonne as inflection signal for accelerated coal retirement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Cofiring Certification | Siemens Energy and Ansaldo Energia capture premium pricing for 30 percent hydrogen-ready turbine platforms. |
| Biomass Plant Conversion | Danish and Dutch utilities preserve grid assets while eliminating coal combustion under EU ETS compliance. |
| Long-term Service Agreement | Nordic municipal operators unbundle equipment procurement from twenty-year maintenance contracts with OEMs. |
| Carbon Capture Readiness | Polish and German lignite operators engineer post-combustion tie-in points for net-zero 2050 alignment. |
| District Heating Expansion | Swedish and Finnish forestry residue feedstock supplies combined heat and power under renewable exemptions. |
Research Methodology
Independent corroboration across utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists underwrites the qualitative findings. Primary fieldwork with grid operators and OEM service heads combined with secondary validation from EIA data, IEA reports, FERC filings, and European project development databases. Bottom-up capacity addition tracking and top-down regulatory scenario analysis triangulate market sizing.
Rate-of-change decomposition separates fuel-switching velocity from capacity replacement cycles across the projection horizon. Segmentation dimensions span fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derive from installed base turnover modeling and hydrogen infrastructure deployment curves. Forecast inputs incorporate EU ETS price trajectory assumptions and national carbon floor price enforcement schedules.
Underlying measurement precision varies by segment; natural gas combined-cycle and biomass cogeneration carry tighter precision than emerging hydrogen blending categories. Forecasts reflect documented assumptions about EU Green Deal implementation pace and Industrial Emissions Directive enforcement uniformity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Global Black Start Generator Market
Power Generation
Cogeneration System Market
Power Generation
Gas Fired Power Plant Market
Power Generation
Captive Power Plant Market
Power Generation
Oman Power Market
Power Generation
East Africa Power Market
Power Generation
Japan Combined Heat and Power Market
Power Generation
Malaysia Power Market
Power Generation
Hydrogenerators Market
Power Generation
Venezuela Power Market
Power Generation
India Gensets Market
Power Generation
Asia-Pacific Distributed Power Generation Market
Power Generation
Global Distributed Energy Generation Market
Power Generation
Australia Thermal Power Market
Power Generation
Global Gas Turbines Market
Power Generation
Coal Fired Power Generation Market