
 Industrial Motherboards Market | 2026-2036
Industrial Motherboards Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Motherboards Market Intelligence
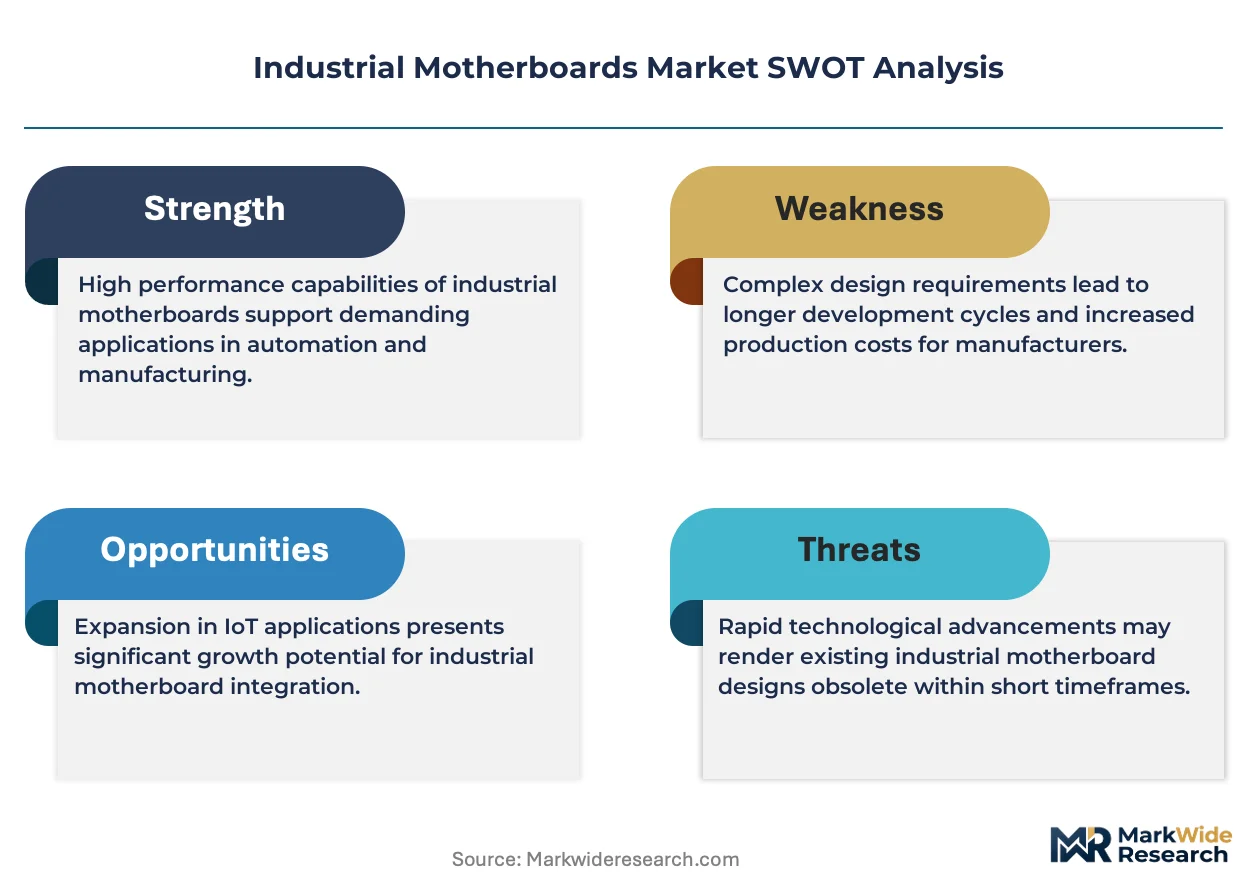
CE marking under the EU's Radio Equipment Directive is collapsing the supplier base for industrial motherboards bound for European automation OEMs. Supermicro sustains a commanding position in high-density server-grade boards for edge data centers. Advantech dominates the embedded IPC motherboard segment through deep channel partnerships with Asian system integrators. Kontron specializes in ruggedized designs for railway and defense applications where shock resistance certifications gate market entry.
An industrial motherboard is a printed circuit board assembly designed for 24/7 operation in factory, transportation, or infrastructure environments, typically supporting extended temperature ranges from -40°C to 85°C and legacy I/O interfaces like RS-232/422/485 alongside modern PCIe lanes. Its primary purpose is to host processors, memory, and expansion slots within fanless or conduction-cooled enclosures where consumer-grade components would fail from thermal cycling or particulate contamination. Mini ITX form factor boards are capturing disproportionate design wins in space-constrained edge nodes where single-board density determines enclosure size. The embedded technology segment anchors long-lifecycle programs in transportation and medical imaging where seven-year availability commitments are standard contractual terms. Ruggedized form factors command premium positioning in outdoor digital signage and agricultural telemetry where conformal coating and MIL-STD shock ratings justify unit price multiples over standard commercial variants.
FCC Part 15 Class A emissions compliance shapes product development timelines for industrial motherboard vendors targeting North American factory automation deployments. The EU Cyber Resilience Act and IEC 62443 security standards are forcing firmware signing and secure boot implementations that smaller PCB houses lack resources to implement. China's GB/T standards for industrial control equipment add a parallel certification track for boards integrated into domestically manufactured CNC and robotic systems. Buyers must weigh single-source long-lifecycle commitments against the operational risk of supplier consolidation driven by proliferating cybersecurity mandates.
Market Dynamics
Edge computing deployments in manufacturing facilities are compressing refresh cycles for embedded compute hardware, forcing vendors to reconcile seven-year availability commitments against accelerating silicon obsolescence.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory firmware signing and secure boot implementations are creating upgrade demand across installed bases of connected industrial systems.
- Stuttgart-Munich automation corridor:Concentrated demand from German automotive OEMs is pulling specialized Mini ITX designs with extended temperature specifications.
- PCIe Gen5 migration:High-bandwidth expansion requirements in machine vision and robotic control applications are displacing legacy PCIe Gen3 motherboard inventories.
Market Restraints
- CE marking collapse under RED:The Radio Equipment Directive's tightened emissions standards are eliminating smaller PCB houses from European supplier lists.
- Substrate supply concentration:High-layer-count PCB fabrication capacity concentrates in Taiwanese and South Korean facilities, exposing buyers to single-source risk.
- ARM architecture substitution:Power-efficient SoC designs are encroaching on x86 sockets in fanless edge nodes below 15W thermal envelopes.
Strategic Opportunities
- India PLI scheme for industrial automation:Domestic manufacturing incentives are opening design-win opportunities for boards integrated into locally produced CNC controllers.
- Railway signaling modernization:EN 50155 certification requirements across European rail networks are creating premium positioning for shock-resistant conformal-coated variants.
- 5G private network convergence:Integration of time-sensitive networking with cellular backhaul is spawning new motherboard categories for mobile robotics.
Industry Challenges
- Firmware security engineering talent:IEC 62443 implementation requires specialized embedded security expertise that legacy hardware teams lack.
- Dual certification timelines:Parallel FCC Part 15 Class A and GB/T compliance tracks for boards serving both North American and Chinese OEMs extend qualification cycles.
- Legacy ISA bus retention:Decades-old industrial equipment still requires arcane interface support that modern silicon increasingly abandons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Motherboards Market |
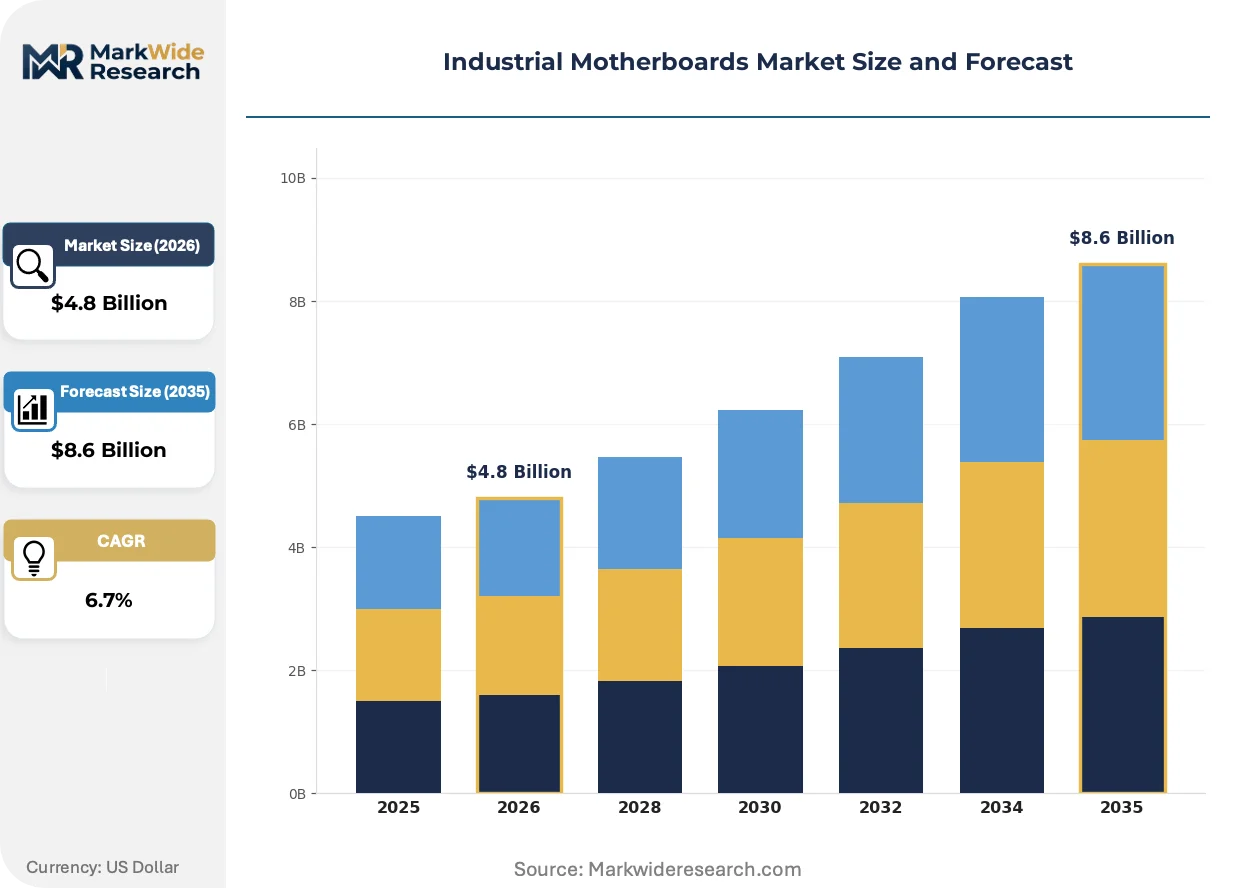
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ATX, Micro ATX, Mini ITX, Pico ITX Technology: Embedded, Open Frame, High Performance, Low Power End User: Manufacturing, Transportation, Healthcare, Retail Form Factor: Standard, Ruggedized, Compact, Rack-Mount |
| Companies Covered | MSI, Jetway, Supermicro, IEI Integration, Advantech, ASRock Rack, Gigabyte, Kontron, ASUS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Motherboards Market Strategic Shifts & Innovations
Silicon-level security mandates and form-factor miniaturization are rewriting design priorities across industrial motherboard portfolios, with thermal management and supply assurance now dominating specification conversations.
Chiplet-based processor packaging is fragmenting traditional monolithic CPU sockets into modular compute tiles with discrete I/O dies. Railway signaling and defense system integrators are piloting these designs for field-upgradable performance without full board replacement. The technology is fragmenting vendor roadmaps into parallel long-lifecycle and leading-edge product streams.
REACH substance restrictions on halogenated flame retardants are forcing laminate suppliers to reformulate PCB substrates for European-bound hardware. Industrial automation OEMs face 18-month requalification cycles for new material stacks. Medical imaging equipment manufacturers are absorbing the steepest cost premiums as they cannot derogate from patient-safety material standards.
Direct procurement from ODMs is displacing traditional distribution for volume automation accounts. System integrators in Germany's automotive sector now negotiate board-level pricing directly with Taiwanese manufacturing partners. This channel compression is most visible in Stuttgart, where enclosure vendors bundle motherboards into subassembly contracts rather than sourcing independently.
Industrial Motherboards Market Segmentation
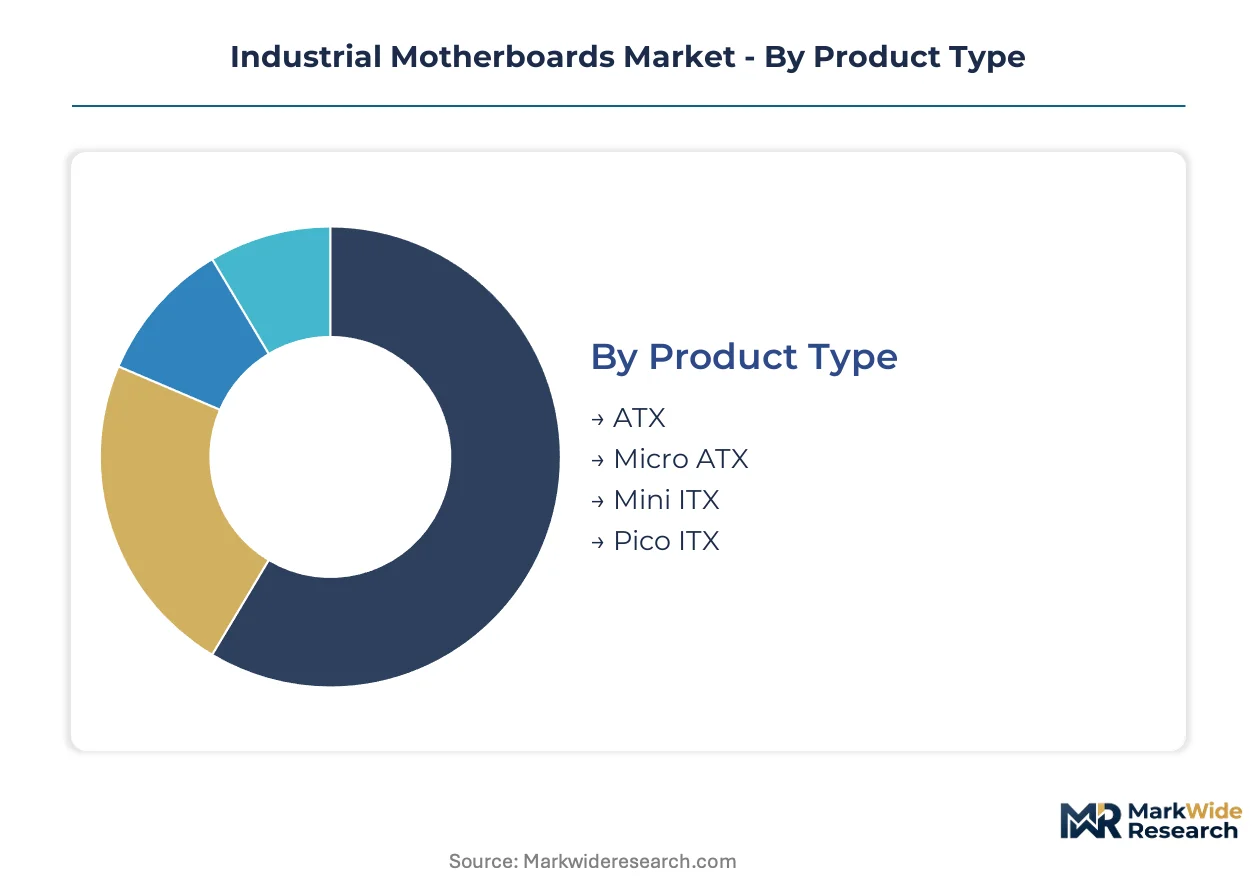
Segmentation in industrial motherboards reveals where ARM SoC substitution and legacy ISA retention create divergent design priorities. Form factor and thermal envelope specifications determine enclosure engineering costs more than raw board pricing. Certification requirements fragment procurement patterns across transportation, healthcare, and factory automation verticals.
Product Type:
ARM-based single-board computers exert substitution pressure most acutely on smaller form factors below Mini ITX, compressing addressable markets for x86 designs in sub-15W applications.
- Mini ITX:170mm x 170mm dimensions balance expansion capability with enclosure compactness. Stuttgart automotive OEMs specify these for edge nodes in paint shop automation where single-board density determines cabinet footprint. PCIe Gen5 lanes support machine vision frame grabbers in robotic welding cells.
- ATX:Full-size 305mm x 244mm boards retain dominance in rack-mounted industrial servers requiring multiple expansion slots. Legacy ISA bridge chips still appear on these platforms for CNC retrofit markets.
- Micro ATX:244mm x 244mm mid-range format serves medical imaging workstations needing GPU acceleration without full ATX depth.
- Pico ITX:100mm x 72mm footprint targets fanless digital signage and agricultural telemetry nodes. Thermal design power constraints below 10W limit processor selection to embedded Atom and ARM SoC options.
ATX retains volume leadership in factory automation retrofits; Pico ITX holds the steepest expansion curve in outdoor edge infrastructure.
Technology:
Cost tier stratification separates long-lifecycle embedded programs from price-sensitive open-frame designs serving Asian system integrators.
- Embedded:Seven-year availability commitments with locked bill-of-materials dominate transportation and medical imaging contracts. Kontron and Advantech maintain dedicated product lines for railway EN 50155 certification tracks. Firmware signing requirements under IEC 62443 add engineering overhead that smaller PCB houses cannot absorb.
- High Performance:Server-grade designs with PCIe Gen5 and DDR5 memory target edge data centers processing machine vision inference. Supermicro's density-optimized boards serve this tier exclusively.
- Open Frame:Unenclosed bare boards for integration into custom housings by Asian ODMs. Direct procurement from Taiwanese manufacturing partners now displaces distribution in volume accounts.
- Low Power:Sub-15W thermal envelopes favor ARM SoC adoption over x86 sockets. Agricultural telemetry and battery-powered mobile robotics drive specification here.
Embedded technology commands premium pricing through availability guarantees; High Performance gains share fastest in semiconductor fab automation.
End User:
Application-driven segmentation shows manufacturing absorbing the majority of edge computing refresh cycles while transportation demands the most stringent certification depth.
- Transportation:Railway signaling modernization across European networks requires EN 50155 shock resistance and conformal coating. Defense applications add MIL-STD-810G vibration ratings that gate vendor qualification.
- Manufacturing:German automotive OEMs in the Stuttgart-Munich corridor specify extended temperature ranges from -40°C to 85°C for paint shop and welding environments. PCIe Gen5 migration displaces legacy Gen3 inventories in machine vision applications.
- Healthcare:Medical imaging equipment demands patient-safety material standards under REACH flame retardant restrictions. Eighteen-month requalification cycles for new laminate stacks concentrate procurement among established vendors.
- Retail:Outdoor digital signage and point-of-sale terminals prioritize cost over longevity, opening opportunities for open-frame designs with shorter availability commitments.
Manufacturing retains volume leadership through automation density; Transportation holds the steepest expansion curve in signaling infrastructure investment.
Form Factor:
Supply concentration in Taiwanese and South Korean high-layer-count fabrication shapes cost structures most acutely for ruggedized variants requiring specialized substrate formulations.
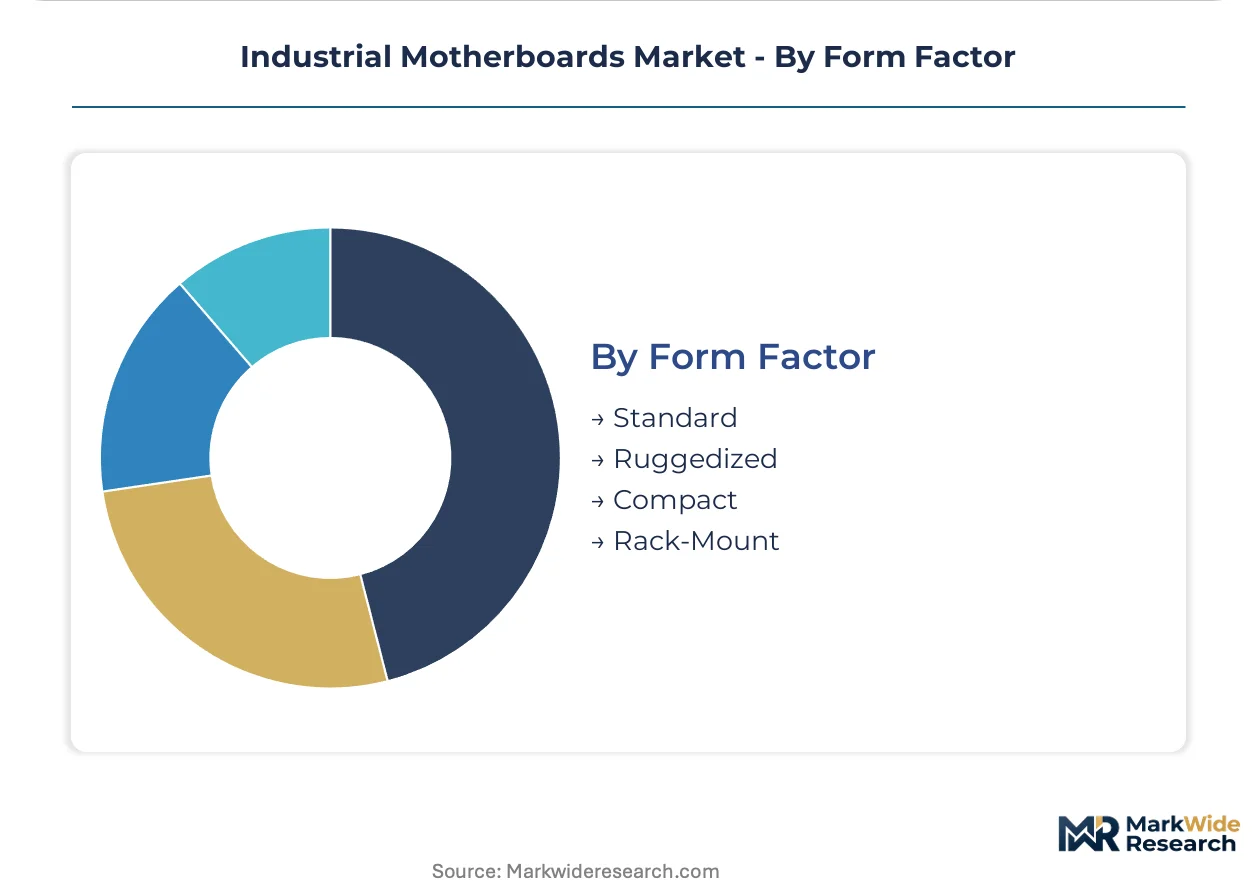
- Ruggedized:Conformal coating, extended temperature silicon, and shock-mounted connectors multiply unit costs over standard variants. Railway and defense applications mandate these specifications regardless of price premium.
- Standard:Unmodified commercial-grade boards serve climate-controlled factory floors where particulate contamination risks remain minimal. FCC Part 15 Class A emissions compliance still shapes development timelines.
- Compact:Space-constrained designs without full ruggedization target indoor edge nodes. Mini ITX dominates this middle tier.
- Rack-Mount:19-inch chassis integration with redundant power and hot-swap capabilities. Edge data center deployments favor this format for maintainability.
Standard form factor retains volume leadership in brownfield automation; Ruggedized gains share fastest in outdoor infrastructure and defense modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for industrial automation is redirecting motherboard procurement toward domestic manufacturing incentives. Germany's Cyber Resilience Act enforcement is compressing supplier qualification timelines for European-bound hardware. China's GB/T certification requirements are creating parallel compliance tracks for CNC and robotic system integrators.
Germany
Stuttgart-Munich automation corridor demand concentrates around Mini ITX designs with extended temperature specifications for paint shop environments. EU Cyber Resilience Act mandates are eliminating smaller PCB houses from automotive OEM supplier lists. Bavaria's automotive engineering clusters are specifying PCIe Gen5 lanes for machine vision frame grabbers in robotic welding cells.
United States
FCC Part 15 Class A emissions compliance shapes development timelines for factory automation deployments. OSHA workplace safety regulations intersect with hardware reliability standards in heavy manufacturing environments. Texas and Michigan industrial corridors are absorbing edge computing refresh cycles for semiconductor fab automation equipment.
China
GB/T standards for industrial control equipment add certification complexity for boards integrated into domestically manufactured CNC systems. MIIT semiconductor localization policies are influencing processor socket selection in state-funded automation projects. Yangtze River Delta manufacturing clusters are piloting chiplet-based designs for field-upgradable railway signaling hardware.
India
PLI scheme incentives for industrial automation are opening design-win opportunities for boards integrated into locally produced CNC controllers. BIS certification requirements are extending qualification cycles for European and Taiwanese vendors. Gujarat and Maharashtra industrial zones are concentrating demand for fanless edge nodes in textile and pharmaceutical manufacturing.
Japan
METI technology roadmaps are accelerating PCIe Gen5 migration in precision manufacturing equipment. JIS standards for industrial electronics maintain strict material traceability requirements that concentrate procurement among established laminate suppliers. Kansai region robotics manufacturers are specifying shock-resistant conformal-coated variants for cleanroom automation deployments.
Industrial Motherboards Market Key Industry Players
Listed leaders compete with private specialists across certification depth and long-lifecycle availability commitments. The vendor base stratifies into three tiers: global platform vendors with full certification portfolios, regional ODMs serving volume automation accounts, and niche specialists targeting defense and railway applications. Two dominant competitive moves are reshaping positioning: direct procurement partnerships between German system integrators and Taiwanese manufacturing partners, and vertical integration into high-layer-count PCB fabrication to secure substrate supply.
Among Taiwan-based platform vendors, Advantech and Supermicro exemplify divergent strategic archetypes. Advantech anchors the embedded IPC motherboard segment through channel partnerships with Asian system integrators. Supermicro occupies a position in high-density server-grade boards for edge data centers. Kontron, a European specialist, represents the ruggedized design tier where EN 50155 and MIL-STD certifications gate market entry in railway and defense verticals.
| Leading Market Players |
|---|
| MSI |
| Jetway |
| Supermicro |
| IEI Integration |
| Advantech |
| ASRock Rack |
| Gigabyte |
| Kontron |
| ASUS |
| Others |
Cost & Logistics Intelligence
High-layer-count PCB fabrication capacity utilization in Taiwanese and South Korean facilities anchors both supply concentration and price floors across ruggedized motherboard tiers. Scale economies at substrate suppliers translate directly into procurement leverage for volume automation accounts while smaller European PCB houses absorb margin compression from certification overhead.
Pricing Analysis
Certification level (IEC 62443/EN 50155/CE marking) creates the primary spread between premium embedded tiers and open-frame commodity boards. Three-tier pricing structure across premium, standard, and economy levels reflects firmware signing investment, availability commitment length, and thermal specification breadth. Cost compression in standard-tier Mini ITX designs is intensifying because German automotive OEMs now negotiate board-level pricing directly with Taiwanese ODMs. System integrators serving railway signaling represent the least price-sensitive segment; Asian volume automation accounts exhibit highest sensitivity to per-unit board costs.
Supply Chain Analysis
Taiwan Strait shipping lanes and South Korean port capacity constrain substrate delivery timelines for European-bound ruggedized variants. High-layer-count PCB fabrication concentrates in Taiwan, South Korea, and select Japanese facilities. Raw material dependencies span halogen-free laminate resins, low-loss copper foils, and embedded security controller silicon. Single-source vulnerability concentrates in ABF substrate supply for fine-pitch BGA packages. Distribution runs through direct procurement partnerships between German system integrators and Taiwanese manufacturing partners, displacing traditional component distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German automotive OEMs and Asian system integrators through direct ODM partnerships, fragmenting incumbent vendor pricing leverage across the supplier base.
For Market Incumbents: Shield long-lifecycle embedded programs through captive supply of high-layer-count PCB substrate capacity. Deepen firmware security engineering teams to absorb IEC 62443 implementation overhead that eliminates smaller competitors. ARM SoC substitution in sub-15W edge nodes threatens x86 socket retention; defend through PCIe Gen5 performance differentiation in machine vision applications. For New Entrants and Emerging Players: Post-sales firmware maintenance and secure boot update services represent underserved white space where incumbents under-serve legacy installed bases. Target India's PLI scheme automation corridors for design-win opportunities in domestically produced CNC controllers. Pursue direct procurement relationships with Maharashtra textile manufacturers seeking fanless edge nodes. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists with EN 50155 certification depth and railway signaling track records over commodity platform vendors. Long-term viability over a five-to-ten-year window rests on secure boot implementation capability and substrate supply assurance. Monitor chiplet-based processor packaging adoption in defense and railway verticals as inflection indicator for modular upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Fabrication | Captive supply of high-layer-count PCB capacity secures ruggedized motherboard cost structures against Taiwanese supplier consolidation. |
| IEC 62443 Certification Investment | Firmware signing capability gates European automotive OEM supplier lists under EU Cyber Resilience Act mandates. |
| Direct ODM Partnership Expansion | Taiwanese manufacturing relationships bypass distribution markup for Stuttgart-Munich automation corridor volume accounts. |
| Chiplet-Based Design Platform Launch | Modular compute tiles enable field-upgradable performance without full board replacement in railway signaling. |
| India PLI Scheme Localization | Domestic manufacturing qualification opens design-win opportunities in Gujarat and Maharashtra industrial zones. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade records, and IEC certification databases. Interviews with embedded hardware procurement managers, industrial automation system integrators, railway signaling engineers, and PCB substrate suppliers informed demand-side validation. Top-down market sizing triangulates against bottom-up bill-of-materials analysis across Mini ITX, ATX, and Pico ITX form factor categories.
Segmentation dimensions modeled span form factor specification, thermal envelope tier, certification depth, and end-use vertical across the projection horizon. CAGRs derive from silicon obsolescence cycle compression, edge computing refresh acceleration, and regulatory mandate implementation timelines. Forecast inputs incorporate PCIe generation migration curves, ARM SoC substitution rates in sub-15W applications, and EN 50155 certification pipeline visibility.
Underlying assumptions cover seven-year availability commitment retention, EU Cyber Resilience Act enforcement timelines, and Taiwanese substrate supply continuity, with deviation risk concentrated in geopolitical trade restrictions and REACH substance restriction reformulation delays. Practitioners should keep alternative scenarios live as semiconductor localization policies and railway infrastructure investment cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IT Hardware
PC Case Market
IT Hardware
India IT Hardware Market
IT Hardware
Europe IT Device Market
IT Hardware
USB 3.0 Market
IT Hardware
Server Chassis Market
IT Hardware
Three-Proof Laptop Market
IT Hardware
Cloud IT Infrastructure Hardware Market
IT Hardware
Global IT Hardware Market
IT Hardware
Tablet PC Market
IT Hardware
Global 4K Set Top Box (STB) Market
IT Hardware
Single Board Computer Market
IT Hardware
Asia Pacific IT Device Market
IT Hardware
Middle East and Africa IT Device Market