
 PC Case Market | 2026-2036
PC Case Market Size, Share, and Industry Trends Forecast 2026-2036
PC Case Market Insights
The gap between consumer and professional chassis requirements is narrowing as GPU power densities and thermal loads converge across segments. Corsair leverages its liquid cooling ecosystem to anchor premium positioning in full-tower configurations. Cooler Master competes through broad SKU coverage spanning entry-level steel to enthusiast tempered glass builds. NZXT differentiates via software-integrated lighting control and clean cable management architectures.
A PC case is an enclosure that houses and protects computer motherboard, power supply, storage drives, and expansion cards, typically constructed from stamped steel, extruded aluminum, or injection-molded ABS with tempered glass side panels for component visibility. Its primary function is to provide structural mounting, electromagnetic shielding, and engineered airflow paths to maintain thermal stability under load. Mid-tower configurations dominate volume shipments due to their compatibility with standard ATX motherboards and balanced footprint for mainstream builds. Full-tower chassis command the strongest margin pools as they accommodate extended ATX boards and custom liquid cooling loops favored by enthusiast segments. Tempered glass panel adoption outpaces opaque steel alternatives as RGB lighting and component showcase aesthetics drive material substitution in the premium tier.
The EPA Energy Star program and EU Ecodesign requirements shape efficiency standards for power supply integration and standby consumption in pre-built systems. China's GB standards and RoHS compliance obligations govern material restrictions and electromagnetic compatibility certification for export-oriented manufacturers. Stakeholders must monitor how right-to-repair legislation and modular upgradeability mandates alter chassis design priorities and tooling investments.
Market Dynamics
GPU thermal envelopes exceeding 450W are forcing chassis manufacturers to redesign airflow architectures around direct-to-chip cooling compatibility, compressing the product development cycle from 18 months to under 12 months.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:The framework mandates modular designs and recycled aluminum content, pushing manufacturers toward circular production models and creating upgradeable chassis as a compliance-driven category.
- Content creator workstation builds:Video editing and 3D rendering professionals now specify full-tower configurations with custom loop support, expanding the addressable market beyond traditional gaming segments.
- China's domestic OEM partnerships:Local brands securing direct supply agreements with motherboard and GPU manufacturers are capturing volume through bundled system sales and pre-installed thermal solutions.
Market Restraints
- Aluminum and tempered glass input volatility:Spot prices for extruded aluminum and chemically-treated glass panels fluctuate with energy costs, compressing margin predictability for mid-tier manufacturers.
- Shenzhen and Dongguan supply concentration:Over 70 percent of stamped steel chassis and injection-molded ABS components originate from Pearl River Delta facilities, creating geographic risk exposure.
- Electromagnetic shielding trade-offs:Tempered glass panel adoption reduces Faraday cage effectiveness, forcing expensive mesh integration or conductive coating applications to maintain FCC and CE certification compliance.
Strategic Opportunities
- India's nascent gaming hardware ecosystem:Import tariff structures on fully assembled systems create localized assembly incentives for chassis manufacturers establishing regional stamping and finishing operations.
- Right-to-repair legislative momentum:France's reparability index requirements and pending EU-wide standards reward tool-free designs and standardized mounting patterns with retail placement advantages.
- Dual-chamber and vertical GPU mounting convergence:Thermal separation architectures and showcase orientations are merging into hybrid layouts that serve both airflow optimization and aesthetic display functions.
Industry Challenges
- Thermal simulation and CFD modeling expertise:The shortage of engineers capable of validating airflow paths against 600W GPU loads extends prototyping cycles and increases reliance on external consulting partnerships.
- RoHS and REACH certification timelines:Material substitutions for recycled aluminum alloys and alternative surface treatments require 6-9 month validation windows that delay product launches.
- Legacy ATX power supply form factor integration:SFX and ATX12VO standards create mounting and cable routing conflicts that complicate backward compatibility in compact chassis designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PC Case Market |
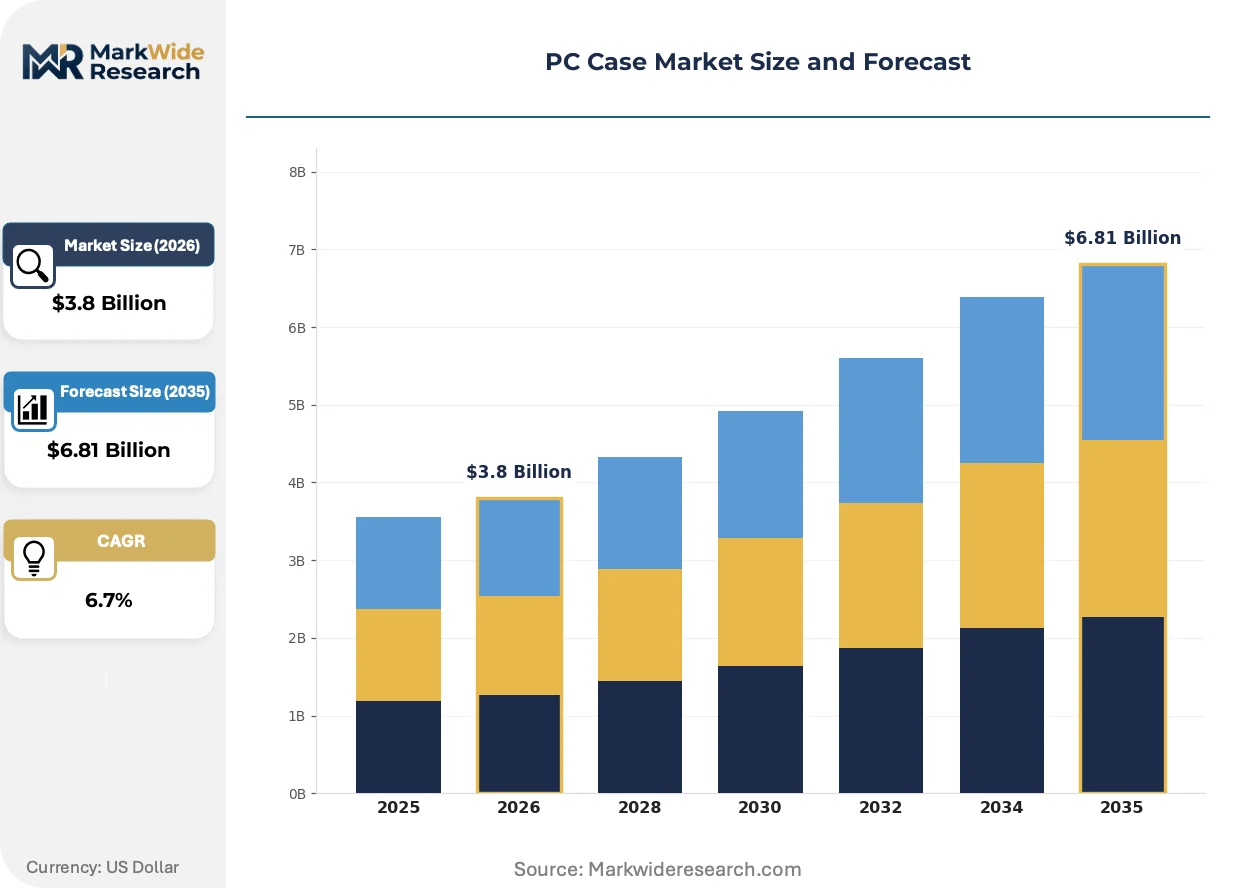
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mid Tower, Full Tower, Mini Tower, Micro ATX Material: Steel, Aluminum, Plastic, Tempered Glass Form Factor: ATX, E-ATX, Mini ITX, Standard Cooling Type: Air Cooling, Liquid Cooling, Passive Cooling, Hybrid Cooling |
| Companies Covered | Lian Li, Antec, Cooler Master, In Win, Aerocool, Corsair, Thermaltake, Silverstone, NZXT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PC Case Market Trends and Innovations
Thermal engineering and material science are converging to redefine chassis architecture as active cooling components rather than passive enclosures, with regulatory pressure accelerating the transition toward serviceable and recyclable designs.
Tool-less mounting systems for storage drives and expansion cards are migrating from premium SKUs to mainstream mid-tower configurations. System integrators and DIY builders now expect snap-fit retention mechanisms as standard equipment. This capability compression is eroding the historical segmentation between enthusiast and consumer price tiers.
REACH substance restrictions and the EU Green Deal's circular economy action plan are compelling manufacturers to document material provenance and design for disassembly. The industrial consequence is a shift toward standardized screw patterns, detachable front panels, and recyclable packaging. Full-tower chassis targeting European distribution channels are most affected, with several manufacturers now publishing repair manuals and spare parts availability commitments.
Direct-to-consumer configuration tools are displacing traditional retail shelf purchases for enthusiast segments. NZXT's BLD platform and comparable services allow component selection with guaranteed thermal and dimensional compatibility, capturing buyers who previously relied on brick-and-mortar advice. This channel rotation is most visible in North American and Western European markets where shipping logistics and return policies support build-to-order fulfillment.
PC Case Market Segmentation
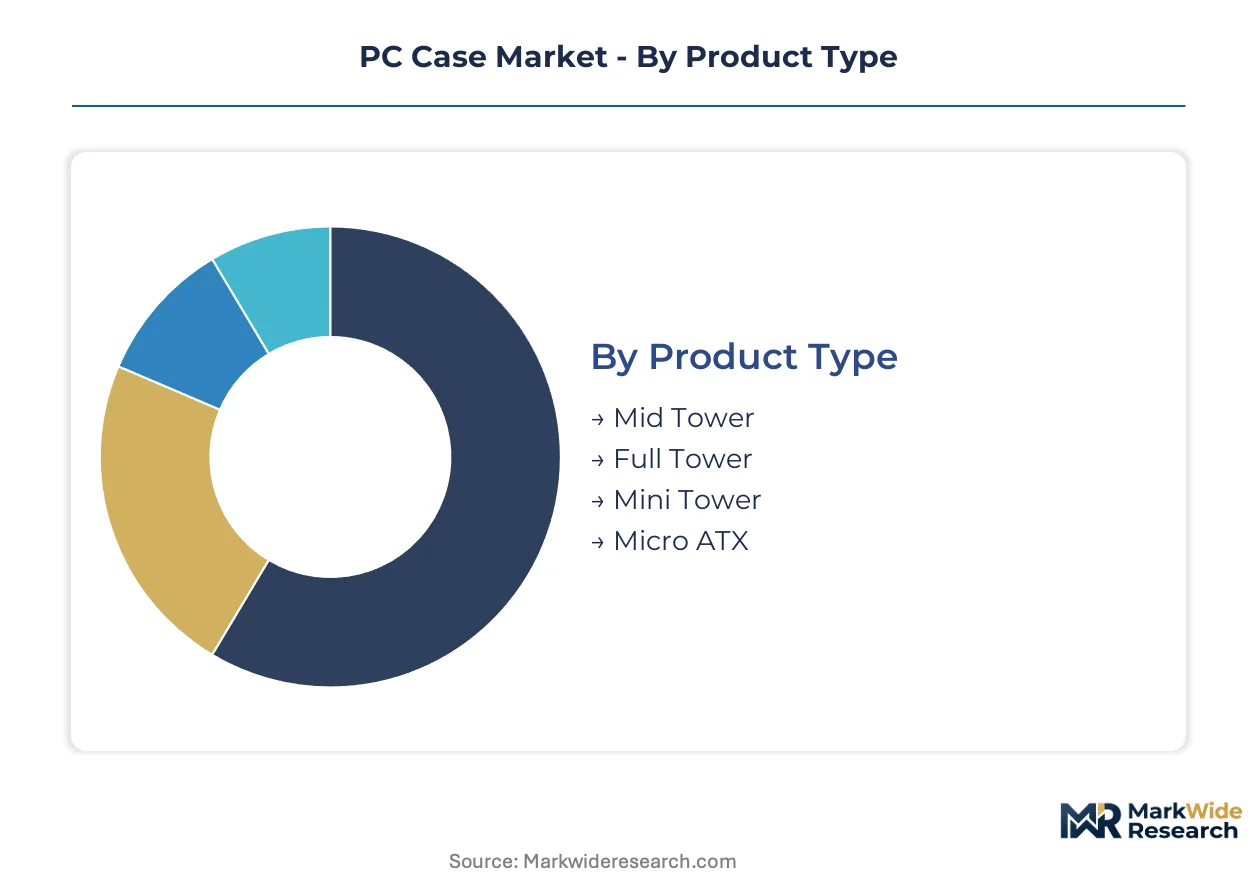
PC case segmentation determines thermal engineering priorities, material sourcing strategies, and regional compliance pathways. Manufacturers align chassis specifications with GPU power envelopes, motherboard form factors, and cooling system integration requirements.
Product Type:
After-sales service intensity varies sharply across tower configurations, with full-tower chassis demanding specialized support for custom loop maintenance and component compatibility verification.
- Mid Tower:ATX-compatible enclosures balance footprint against expansion capacity, serving mainstream gaming builds and professional workstations. Demand concentrates in China and the United States where domestic brands bundle these configurations with pre-installed motherboards and power supplies.
- Full Tower:Extended ATX support and dual-chamber architectures accommodate 600W GPU loads and custom liquid cooling loops. Content creator workstations and enthusiast gaming segments in Germany and France specify these configurations for thermal headroom and showcase aesthetics.
- Mini Tower:Compact footprints prioritize desk space efficiency over expansion slots.
- Micro ATX:Smaller form factors target budget-conscious builders and office deployments.
Mid Tower holds the largest share; momentum sits with Full Tower as GPU thermal envelopes expand.
Material:
Cost tier stratification separates premium aluminum and tempered glass builds from entry-level steel alternatives, with recycled content mandates reshaping supplier qualification criteria.
- Steel:Stamped and extruded variants provide electromagnetic shielding and structural rigidity at lowest unit cost. Volume shipments concentrate in entry-level and mainstream segments across India and Southeast Asia where price sensitivity dominates procurement decisions.
- Aluminum:Extruded and recycled alloys reduce chassis weight while improving thermal conductivity for passive cooling designs. European Union Ecodesign regulations and France's reparability index requirements accelerate adoption in premium tiers distributed through German and Dutch retail channels.
- Plastic:Injection-molded ABS and polycarbonate components reduce manufacturing costs for budget-oriented SKUs.
- Tempered Glass:Chemically-treated panels enable component visibility and RGB lighting showcase.
Steel commands volume leadership; aluminum is expanding most quickly on regulatory pressure.
Form Factor:
Customer type differentiation separates DIY enthusiast builders from system integrators, with mounting pattern standardization affecting inventory complexity and tooling amortization.
- ATX:Standard motherboard mounting dimensions dominate compatibility specifications across mid-tower and full-tower chassis. System integrators in the United States and United Kingdom specify ATX support as baseline requirement for mainstream gaming and productivity system bundles.
- E-ATX:Extended dimensions accommodate workstation-class motherboards with additional memory channels and expansion slots. Professional 3D rendering and video editing deployments in Japan and South Korea specify E-ATX compatibility for threadripper and Xeon-based configurations.
- Mini ITX:Reduced footprint targets compact builds and portable LAN party systems.
- Standard:Legacy mounting patterns serve replacement and upgrade markets.
ATX retains dominant share; E-ATX climbs the fastest on workstation demand.
Cooling Type:
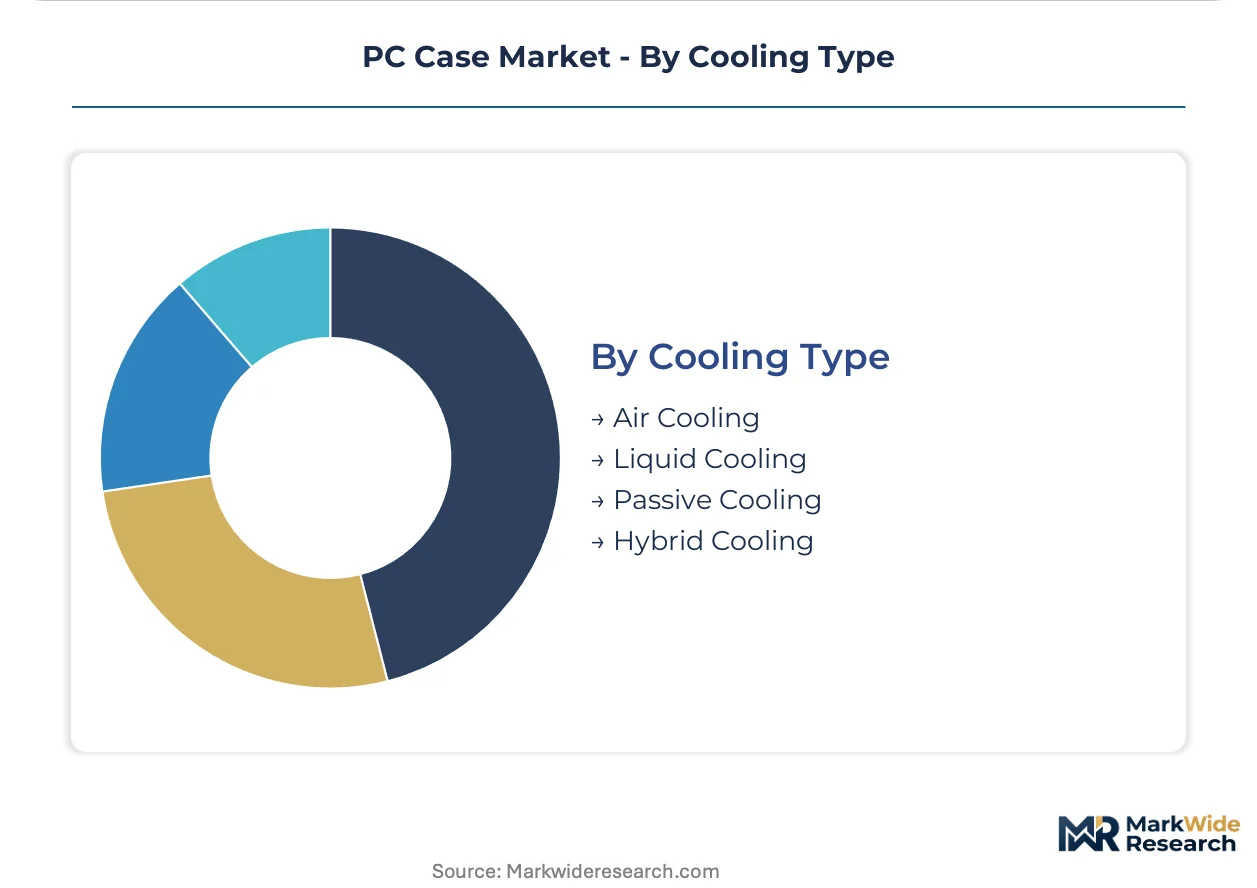
Application-driven segmentation separates passive designs for low-power office systems from active solutions targeting sustained compute loads, with thermal validation requirements affecting warranty terms and support obligations.
- Air Cooling:Fin-stack and heat-pipe configurations leverage chassis airflow paths for cost-effective thermal management. Budget gaming and office productivity builds across Brazil and Mexico prioritize air-cooled designs for reliability and maintenance accessibility.
- Liquid Cooling:AIO and custom loop integration demands radiator mounting points, pump brackets, and leak containment features. Enthusiast segments in Canada and Australia specify liquid cooling support for overclocked CPU and GPU configurations in climate-challenged environments.
- Passive Cooling:Convection-dependent designs eliminate moving parts for silent operation.
- Hybrid Cooling:Combined air and liquid architectures optimize thermal performance across component zones.
Air Cooling maintains volume leadership; Liquid Cooling gains share fastest on GPU power density trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports stamped steel chassis and injection-molded ABS components to system integrators in the United States and Germany, while Taiwan-based manufacturers supply aluminum enclosures to premium distributors across Western Europe.
United States
Content creator workstations and enthusiast gaming builds drive full-tower chassis demand in California and Texas. The EPA Energy Star program shapes efficiency standards for power supply integration in pre-built systems. System integrators in Austin and Los Angeles bundle mid-tower configurations with motherboards and GPUs for domestic retail channels.
Germany
Professional 3D rendering and video editing deployments specify E-ATX full-tower chassis with custom loop support. The EU Ecodesign for Sustainable Products Regulation mandates modular designs and recycled aluminum content. Industrial clusters in Bavaria and North Rhine-Westphalia host distributors prioritizing reparability index compliance for retail placement.
China
Domestic OEM partnerships with motherboard and GPU manufacturers capture volume through bundled system sales. GB standards and RoHS compliance obligations govern material restrictions for export-oriented manufacturers. Stamping and finishing operations concentrate in Shenzhen and Dongguan, supplying over 70 percent of global steel chassis and ABS components.
India
Import tariff structures on fully assembled systems create localized assembly incentives for entry-level steel chassis. The Bureau of Indian Standards (BIS) certification requirements shape electromagnetic compatibility validation. Manufacturing investments in Gujarat and Tamil Nadu target regional stamping operations for gaming hardware ecosystems.
Japan
Workstation-class deployments with threadripper and Xeon-based configurations demand E-ATX thermal headroom. METI efficiency guidelines influence standby consumption standards for pre-built systems. Industrial concentration in Tokyo and Osaka prioritizes compact Mini-ITX builds for space-constrained professional environments.
PC Case Market Competitive Landscape
On the supply side, the industry is moderately consolidated around component ecosystem integrators and specialized chassis fabricators. The vendor base stratifies across three tiers: premium aluminum-and-glass specialists, mid-tier steel-volume producers, and entry-level OEM suppliers. Dominant competitive moves include backward integration into liquid cooling ecosystems and geographic expansion through regional stamping partnerships.
Among Taiwan-based fabricators, Lian Li and In Win exemplify premium-tier aluminum construction archetypes. Cooler Master occupies a position spanning steel-volume and enthusiast-tier coverage. NZXT represents the software-integrated configuration and direct-to-consumer build services segment.
| Leading Market Players |
|---|
| Lian Li |
| Antec |
| Cooler Master |
| In Win |
| Aerocool |
| Corsair |
| Thermaltake |
| Silverstone |
| NZXT |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Shenzhen stamping facilities is compressing supplier margins and forcing extended payment terms downstream, while simultaneously enabling aggressive pricing postures among volume-tier manufacturers competing for OEM contracts.
Pricing Analysis
The technology-generation pricing gap between ATX12VO-ready chassis and legacy ATX power supply configurations is widening as thermal engineering complexity diverges. Three-tier pricing structure across premium aluminum-tempered glass, standard steel-mesh, and economy stamped-steel levels stratifies the market, with certification tier (FCC/CE/GB standards) and volume scale serving as primary differentiation drivers. Pricing pressure stems from aluminum spot volatility and tempered glass energy-cost pass-through, compressing mid-tier margins most severely. System integrators in China exhibit highest price sensitivity, while enthusiast builders in Germany and France accept premiums for reparability-index compliance.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard among Pearl River Delta fabricators, with supply-chain finance facilities increasingly bridging working-capital gaps for tier-two suppliers. Geographic supply concentration centers on China, Taiwan, and Vietnam, with raw material dependencies spanning extruded aluminum from Guangdong, chemically-treated tempered glass from Jiangsu, and ABS resin from Singaporean petrochemical complexes. Single-source vulnerability in electromagnetic shielding mesh creates exposure to RoHS certification delays. Distribution runs through direct OEM supply agreements, regional distributors in North America and Western Europe, and build-to-order configuration platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where thermal validation consulting and custom loop maintenance contracts are expanding faster than hardware unit shipments, particularly for full-tower configurations targeting content creator workstations.
For Market Incumbents: Entrench position through backward integration into liquid cooling ecosystems and captive aluminum extrusion capacity in Vietnam, defending against emerging direct-to-consumer configuration platforms that displace traditional distributor relationships. Prioritize reparability-index certification investment for European retail placement advantages. For New Entrants and Emerging Players: India's nascent gaming hardware ecosystem offers the most penetrable white-space, with import tariff structures on fully assembled systems creating localized assembly incentives for entry-level steel chassis. Target Gujarat and Tamil Nadu manufacturing clusters with tool-free design architectures that satisfy France's reparability requirements, leveraging direct-to-consumer build services as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among chassis manufacturers with integrated software platforms for thermal monitoring and lighting control, as these generate ongoing licensing and subscription attach rates. Long-term viability favors acquisition targets with established OEM partnerships in China and modular design IP aligned with EU Ecodesign mandates. Monitor right-to-repair legislative momentum as the primary inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Design Platform Development | EU Ecodesign compliance creates upgradeable chassis as a regulatory-driven category with retail placement advantages. |
| Regional Stamping Partnership in India | Import tariff structures on fully assembled systems incentivize localized assembly for gaming hardware ecosystems. |
| Direct-to-Consumer Configuration Tool Launch | NZXT's BLD platform demonstrates capture of enthusiast buyers previously reliant on brick-and-mortar advice. |
| Recycled Aluminum Supply Agreement | France's reparability index and EU circular economy mandates reshape supplier qualification criteria for premium tiers. |
| Thermal Simulation Consulting Service | Engineer scarcity for CFD validation against 600W GPU loads extends prototyping cycles and creates service-attach revenue. |
Research Methodology
A standing panel of chassis product managers, thermal engineering consultants, system integrator procurement leads, and European distributor category buyers provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from customs/trade data, SEC filings of publicly traded component suppliers, EPA Energy Star program documentation, and EU Ecodesign regulatory filings. Bottom-up shipment estimates by tower configuration and material tier triangulated against top-down market sizing derived from motherboard and GPU attach-rate assumptions.
Scenario-bracketing around GPU thermal envelope trajectories and right-to-repair legislative adoption timelines anchored the forecast framework across the modeling period. Segmentation dimensions modeled include tower configuration, material composition, motherboard form factor, cooling type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating replacement cycle compression and workstation-class build expansion. Industry-specific forecast inputs encompassed aluminum spot price volatility bands and RoHS certification timeline distributions.
Practitioners should monitor GPU power density announcements, EU circular economy enforcement actions, and China domestic OEM partnership formations for early signals of trajectory revision. Forecasts reflect documented assumptions regarding thermal engineering talent availability and recycled aluminum alloy qualification timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IT Hardware
Global IT Hardware Market
IT Hardware
India IT Hardware Market
IT Hardware
Europe IT Device Market
IT Hardware
Tablet PC Market
IT Hardware
Single Board Computer Market
IT Hardware
Industrial Motherboards Market
IT Hardware
Global 4K Set Top Box (STB) Market
IT Hardware
Middle East and Africa IT Device Market
IT Hardware
Asia Pacific IT Device Market
IT Hardware
Three-Proof Laptop Market
IT Hardware
Server Chassis Market
IT Hardware
USB 3.0 Market
IT Hardware
Cloud IT Infrastructure Hardware Market