
 Global 4K Set Top Box (STB) Market | 2026-2036
Global 4K Set Top Box (STB) Market Size, Share, and Industry Trends Forecast 2026-2036
Global 4K Set Top Box (STB) Market Foresight
Residential consumer demand for OTT streaming is expanding faster than pay-TV subscriptions across major economies. Amazon.com, Inc. leverages its Prime Video ecosystem to anchor device sales in North America and Western Europe. Roku, Inc. competes aggressively through its advertising-supported platform model and content-agnostic operating system. Huawei Technologies dominates infrastructure-linked STB deployments in markets where telecom operators bundle hardware with fiber broadband services.
A 4K Set Top Box is a dedicated hardware decoder that receives compressed video streams via satellite, cable, IP, or terrestrial networks and outputs Ultra HD resolution at 3840 x 2160 pixels with support for advanced codecs such as HEVC or AV1. Its primary commercial purpose is to bridge broadcast and broadband delivery methods while enabling interactive services, digital rights management, and conditional access for content protection. Android TV Box and Amazon Fire TV categories lead volume shipments due to open application ecosystems and aggressive pricing from platform owners. Dolby Vision and AV1 technology segments are gaining structural importance as streaming services mandate higher dynamic range and bandwidth-efficient encoding for premium tier delivery.
The FCC in the United States enforces electromagnetic compatibility and energy consumption standards that shape hardware certification timelines for imported devices. Ecodesign requirements under EU regulations and REACH substance restrictions compel manufacturers to reformulate circuit boards and power supplies for European market access. China's MIIT administers network access licenses and GB standards compliance for devices integrating terrestrial broadcast tuners. Stakeholders must monitor codec royalty structures and regional content carriage mandates as these determine which technology configurations achieve viable unit economics in each geography.
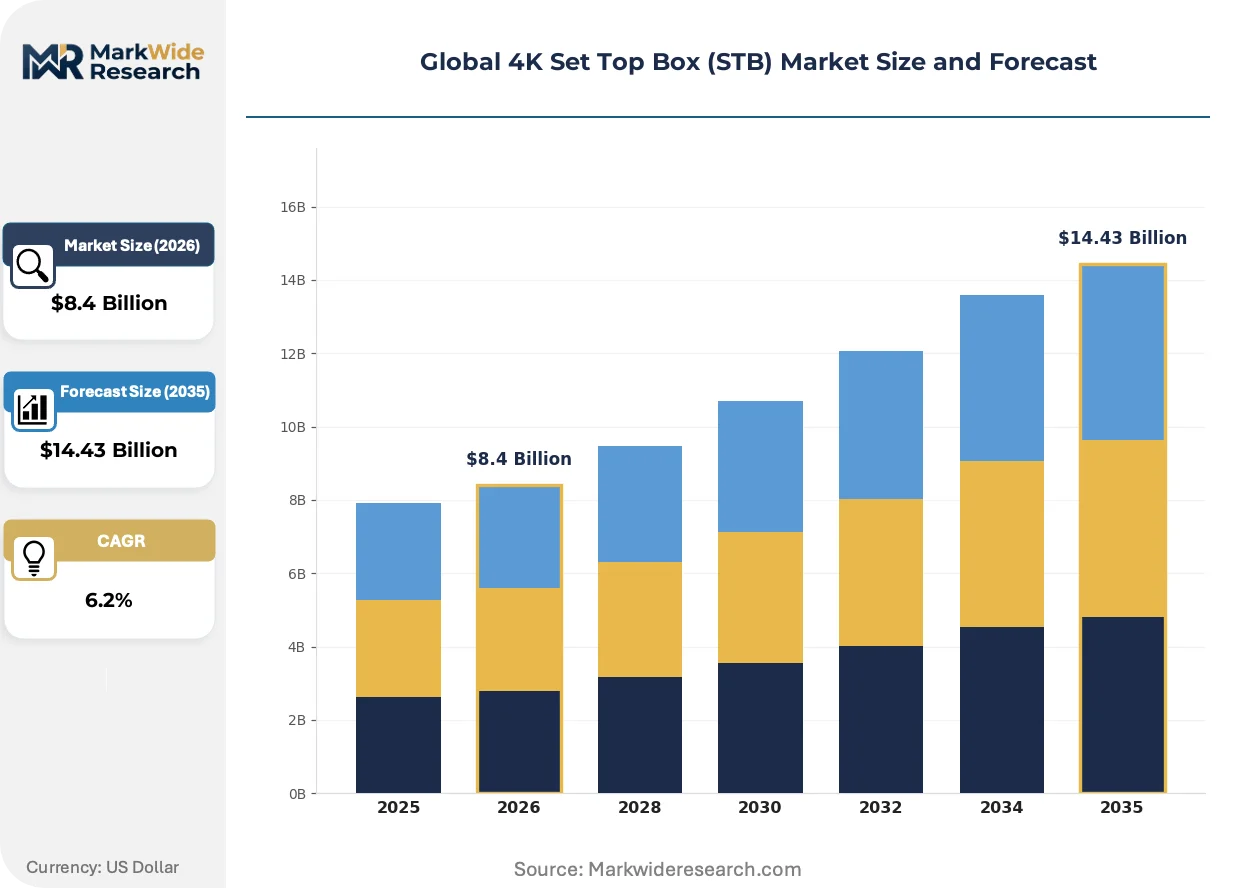
Market Dynamics
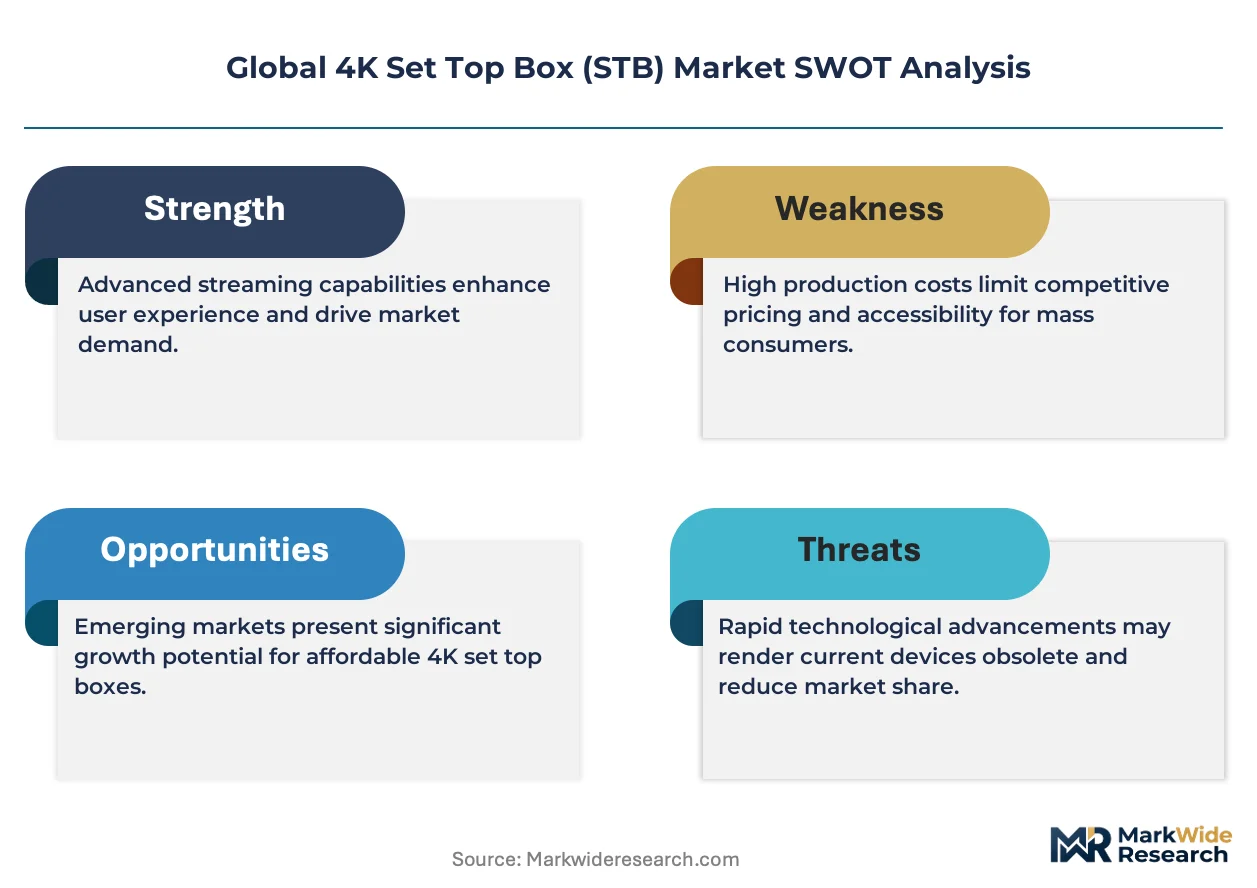
The migration from conditional-access broadcast architectures to open-platform streaming ecosystems is compressing hardware margins while expanding addressable service revenue pools for platform operators.
Growth Catalysts
- EU Green Deal Ecodesign mandates:Energy efficiency directives are forcing semiconductor refreshes that reduce standby power consumption below one watt, creating replacement cycles across installed bases in Germany, France, and Italy.
- India's PLI scheme for electronics manufacturing:Local production incentives are attracting component assembly and final integration capacity to Gujarat and Tamil Nadu, cutting landed costs for Android TV-based devices.
- AV1 codec royalty-free structure:The Alliance for Open Media's encoding standard is expanding into premium tier delivery, enabling bandwidth-efficient 4K streaming without HEVC patent pool obligations.
Market Restraints
- Memory price volatility:DDR4 and NAND flash cost swings from Korean and Taiwanese suppliers compress gross margins on mid-range STB configurations during contract negotiations.
- Conditional access module concentration:Proprietary security chipset supply concentrates among three European vendors, creating single-source risk for pay-TV operators requiring Common Interface Plus certification.
- Terrestrial broadcast tuner mandates:China's MIIT network access licenses require GB-standard demodulators that add BOM cost and extend certification timelines for hybrid IP-broadcast devices.
Strategic Opportunities
- Brazil's analog switch-off completion:The final terrestrial digitization phase is creating replacement demand for DVB-T2 compatible devices in São Paulo and Rio de Janeiro metropolitan zones.
- Voice control integration:Far-field microphone arrays and natural language processing are converging with STB remotes, enabling hands-free content discovery in North American and Western European living rooms.
- TRAI's interoperability framework:India's regulatory push for platform-agnostic hardware is opening white-label manufacturing contracts for regional telecom operators building fiber broadband bundles.
Industry Challenges
- HDCP 2.3 certification backlog:Hollywood studio content protection mandates are extending hardware validation timelines by eight to twelve weeks, delaying retail launches during holiday windows.
- Legacy MPEG-2 depreciation:Operators maintaining hybrid broadcast stacks face integration complexity as chipset vendors sunset standard-definition decoder support, forcing firmware forks across installed bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 4K Set Top Box (STB) Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Android TV Box, Apple TV, Roku Player, Amazon Fire TV, Google Chromecast Technology: HDR10, Dolby Vision, HLG, VP9, AV1, HEVC Application: OTT Streaming, Pay TV, IPTV, Gaming, Video Conferencing, Educational Content End User: Residential Consumers, Hotels & Hospitality, Educational Institutes, Corporate Offices, Public Entertainment Venues |
| Companies Covered | Amazon.com, Inc., Roku, Inc., ZTE Corporation, HUMAX Electronics Co., Ltd, Sagemcom Group, EchoStar Corporation, Huawei Technologies, Infomir Group, Technicolor SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 4K Set Top Box (STB) Market Shifts & Advancements
Codec transitions and regulatory energy mandates are simultaneously compressing hardware refresh cycles and opening service monetization paths through platform-agnostic operating systems.
AV1 hardware decoding is expanding into mass-market silicon designs after initial deployment in flagship streaming sticks. MediaTek and Amlogic are integrating royalty-free decode blocks into sub-fifteen-dollar SoCs for emerging market volume tiers. This compression of encoding cost structures is expanding into premium tier delivery mandates from Netflix and YouTube, forcing HEVC patent pool renegotiations.
REACH substance restrictions are reformulating printed circuit board laminates and solder compositions for European market access. ECHA's candidate list expansions for SVHCs are triggering supply chain audits that extend qualification timelines by four to six months. German retail channels are responding by demanding full material disclosure documentation ahead of seasonal stocking commitments.
Subscription fatigue among residential broadband subscribers is fragmenting content budgets across multiple streaming services rather than consolidating behind single pay-TV bundles. This behavioral pivot is displacing traditional operator-issued STBs with retail-purchased streaming devices in North American and Western European markets. Amazon and Roku are capturing this shift through aggressive hardware subsidy models that recover margin through advertising and transactional video revenue shares.
Global 4K Set Top Box (STB) Market Segmentation
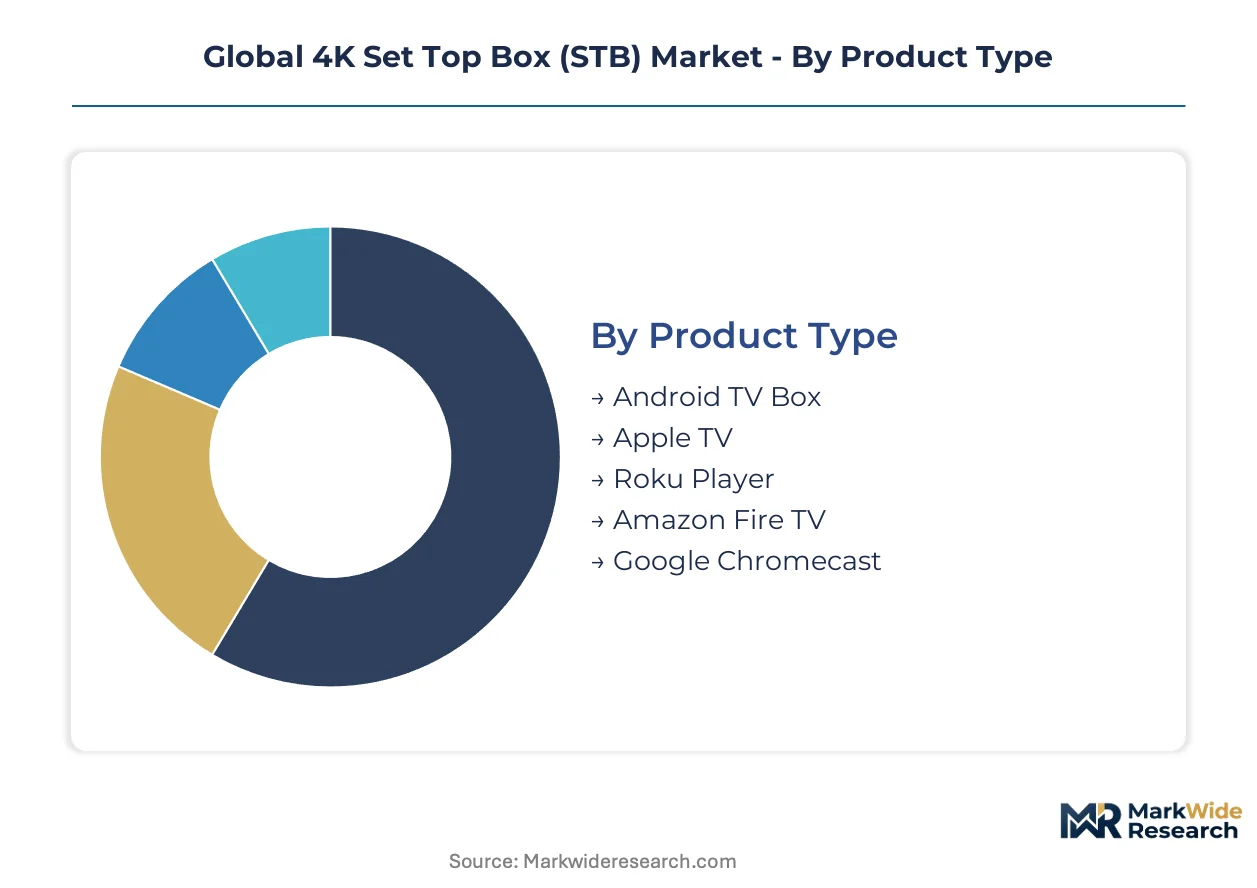
Hardware refresh cycles and codec transitions fragment demand across device categories in the 4K STB market. Upgrade timing varies by installed base age, content service requirements, and regional energy mandate compliance schedules.
Product Type:
Replacement cycles accelerate where open-platform ecosystems displace operator-locked hardware, compressing refresh intervals from seven years toward three-to-four year patterns.
- Android TV Box:Google-certified devices integrate Google Assistant and Play Store access through ARM-based SoCs from Amlogic and MediaTek. Demand concentrates in India where PLI manufacturing incentives and JioFiber bundling are expanding Gujarat assembly capacity for retail and operator channels.
- Amazon Fire TV:Proprietary Fire OS fork runs on subsidized hardware that recovers margin through Prime Video subscription anchoring and advertising revenue shares. North American living rooms dominate placements as cord-cutting households replace legacy cable boxes with retail-purchased streaming sticks.
- Roku Player:Content-agnostic Roku OS aggregates streaming services through neutral search and discovery layers.
- Apple TV:Premium A-series silicon targets iOS ecosystem households with AirPlay mirroring and Arcade gaming integration.
- Google Chromecast:Screen-casting architecture without dedicated remote reduces BOM cost for secondary television locations.
Volume placements concentrate in Android TV Box; the faster expansion belongs to Amazon Fire TV.
Technology:
Codec licensing economics and streaming service mandates determine which decode blocks achieve silicon integration priority.
- AV1:Royalty-free Alliance for Open Media standard eliminates HEVC patent pool obligations while delivering equivalent compression efficiency at 4K resolutions. Netflix and YouTube premium tier mandates are forcing MediaTek and Amlogic to integrate dedicated decode hardware into sub-fifteen-dollar SoCs for emerging market volume tiers.
- Dolby Vision:Dynamic metadata HDR format requires per-frame luminance optimization and licensing fees to Dolby Laboratories. Hollywood studio content protection mandates through HDCP 2.3 are extending hardware validation timelines by eight to twelve weeks for devices targeting premium television integration.
- HDR10:Static metadata baseline format dominates mid-range configurations without per-title licensing overhead.
- HLG:Hybrid Log-Gamma targets broadcast-OTT hybrid deployments in European markets with legacy terrestrial infrastructure.
- VP9:Google-developed codec retains relevance for YouTube delivery at sub-4K resolutions where AV1 hardware decode remains unavailable.
- HEVC:H.265 decode blocks face sunset pressure as patent pool disputes and AV1 migration compress addressable premium tier demand.
Silicon integration priorities favor AV1; Dolby Vision commands the steepest expansion trajectory in premium tier configurations.
Application:
Service revenue models determine hardware subsidy depth and distribution channel selection across use cases.
- OTT Streaming:Subscription video-on-demand and advertising-supported tiers dominate residential consumer demand as broadcast pay-TV subscriptions contract. Roku and Amazon capture this displacement through retail hardware subsidies that recover lifetime value through platform revenue shares.
- Pay TV:Conditional access security requirements concentrate chipset supply among European vendors with Common Interface Plus certification. Legacy MPEG-2 depreciation is forcing firmware complexity as operators maintain hybrid broadcast stacks across installed bases.
- IPTV:IP-based delivery through telecom operator bundles requires TRAI interoperability compliance in India.
- Gaming:Cloud gaming latency requirements drive premium SoC selection with dedicated GPU blocks.
- Video Conferencing:Enterprise room systems integrate far-field microphone arrays and camera peripherals.
- Educational Content:K-12 and higher education deployments prioritize durability and centralized device management.
Shipments concentrate in OTT Streaming; Pay TV maintains replacement-driven stability through security mandate compliance.
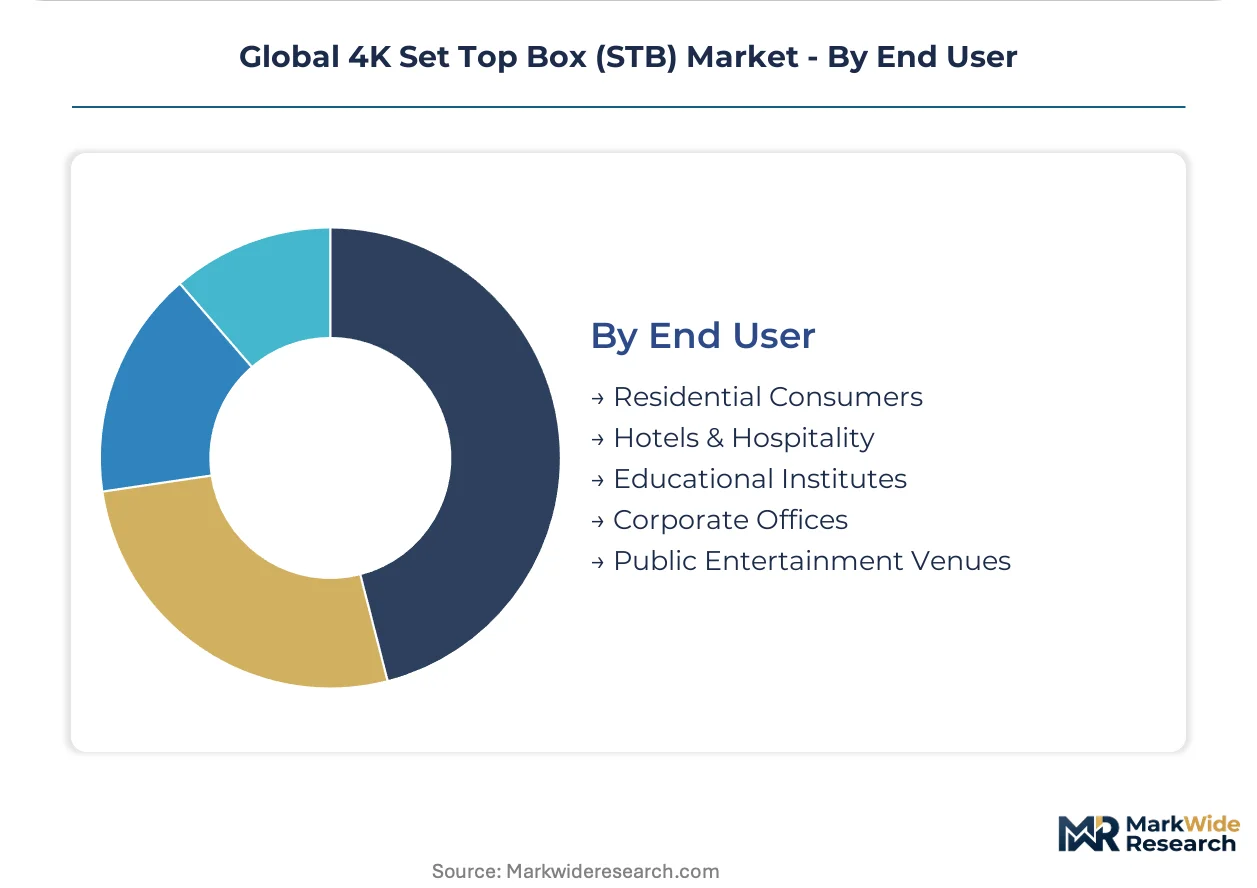
End User:
Procurement authority and budget cycles separate consumer retail purchases from institutional volume contracts.
- Residential Consumers:Individual purchasing decisions respond to streaming service bundling and holiday promotional windows. Subscription fatigue is fragmenting content budgets across multiple services rather than consolidating behind single pay-TV bundles.
- Hotels & Hospitality:Property-wide deployments require centralized content management and guest authentication integration. Provisioning at scale favors platform-agnostic Android TV configurations over brand-locked alternatives.
- Educational Institutes:K-12 and university procurement prioritizes durability specifications and fleet management tools.
- Corporate Offices:Enterprise video conferencing and digital signage applications demand centralized administration portals.
- Public Entertainment Venues:Stadium and cinema deployments require ruggedized enclosures and commercial display synchronization.
Residential Consumers absorb the majority of unit volume; Hotels & Hospitality presents the most concentrated B2B contract opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive scheme for electronics manufacturing has concentrated 4K STB assembly capacity in Gujarat and Tamil Nadu special economic zones, cutting landed costs for Android TV-based devices destined for domestic and export markets.
United States
Cord-cutting households in metropolitan zones are replacing legacy cable boxes with retail-purchased streaming devices at accelerating rates. The FCC enforces electromagnetic compatibility and energy consumption standards that shape hardware certification timelines for imported devices. Silicon Valley and Austin technology corridors host platform operators subsidizing hardware through advertising revenue recovery models.
Germany
EU Green Deal Ecodesign mandates are forcing semiconductor refreshes that reduce standby power consumption below one watt, triggering replacement cycles across aging installed bases. ECHA REACH substance restrictions compel manufacturers to reformulate circuit boards and power supplies for European market access. Bavarian industrial clusters are adapting supply chains to meet full material disclosure documentation demands from retail channels.
India
Broadband infrastructure rollout and JioFiber bundling are accelerating deployment of Android TV-based devices among residential consumers. TRAI's interoperability framework is opening white-label manufacturing contracts for regional telecom operators building fiber broadband bundles. Gujarat and Tamil Nadu assembly plants are expanding capacity under PLI scheme incentives to serve domestic demand and Middle East export corridors.
China
MIIT network access licenses and GB standards compliance requirements regulate devices integrating terrestrial broadcast tuners. Domestic chipset vendors are integrating AV1 decode blocks into mass-market silicon designs to serve local streaming platform mandates. Shenzhen and Dongguan electronics manufacturing clusters are adapting to dual carbon goals through power supply efficiency redesigns.
Brazil
The final phase of analog switch-off is creating replacement demand for DVB-T2 compatible devices in São Paulo and Rio de Janeiro metropolitan zones. ANVISA and national telecommunications regulators are harmonizing certification requirements with Mercosur standards to streamline import procedures. Southeast industrial corridors are attracting final assembly investment to bypass import tariff barriers on finished goods.
Global 4K Set Top Box (STB) Market Competitive Landscape
Top-tier vendors anchor platform ecosystems, while mid-tier hardware specialists serve operator-locked deployments. The vendor base separates into advertising-subsidized streaming platforms, conditional-access security integrators, and white-label contract manufacturers. Three archetypes dominate: ecosystem owners recovering margin through service revenue, telecom-captive suppliers bundling with fiber broadband, and component-agnostic assemblers serving regional operators. Competitive moves concentrate on codec licensing negotiations and energy compliance certification acceleration.
Within the ecosystem-owner archetype, Amazon.com, Inc. and Roku, Inc. represent the advertising-subsidized platform model, while Huawei Technologies occupies a position among infrastructure-linked suppliers serving telecom operator bundles. These three exemplify divergent margin recovery strategies: content-agnostic aggregation, Prime Video subscription anchoring, and fiber broadband hardware integration respectively.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Roku, Inc. |
| ZTE Corporation |
| HUMAX Electronics Co., Ltd |
| Sagemcom Group |
| EchoStar Corporation |
| Huawei Technologies |
| Infomir Group |
| Technicolor SA |
| Others |
Supply & Pricing Matrix
Embedded systems engineering talent concentration in Shenzhen and Dongguan compresses BOM optimization cycles, enabling Chinese contract manufacturers to offer Android TV Box configurations at spreads that undercut European and North American assembly by margins sufficient to fund retail channel subsidies.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent operator deployments from scheduled retail replenishment. Premium-mid-economy pricing differentiation rests on AV1 decode block integration and Dolby Vision certification tier, with volume scale discounts compressing per-unit costs for JioFiber and Reliance Jio bundling contracts. Pricing pressure stems from DDR4 and NAND flash cost swings from Korean and Taiwanese suppliers. Residential consumers in India and Brazil exhibit highest price sensitivity; hospitality procurement in Germany and the United States shows lowest.
Supply Chain Analysis
Certification gating through FCC electromagnetic compatibility, EU Ecodesign standby power mandates, and MIIT network access licenses fragments supplier qualification timelines. Component sourcing concentrates in China, Taiwan, and South Korea for ARM-based SoCs from MediaTek and Amlogic, with memory modules drawing from Samsung and SK Hynix fabs. Single-source vulnerability concentrates in conditional access security chipsets from three European vendors. Distribution runs through operator-locked bundling channels and retail electronics chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where platform owners are pursuing backward integration into silicon design to escape MediaTek and Amlogic dependency.
For Market Incumbents: Acquire far-field microphone array and natural language processing IP to anchor voice control differentiation against Roku and Amazon. Secure captive supply of AV1-capable SoCs through direct foundry relationships or minority stakes in emerging Chinese silicon vendors. Defensive positioning requires accelerating EU Ecodesign certification ahead of German and French retail stocking deadlines.
For New Entrants and Emerging Players: Begin with white-label Android TV Box manufacturing for India's regional telecom operators under TRAI interoperability frameworks. Target Brazil's DVB-T2 replacement cycle in São Paulo metropolitan zones where analog switch-off completion creates hardware procurement windows. Pursue hospitality sector contracts in Germany requiring centralized fleet management and guest authentication integration.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated platform operators given advertising revenue share recovery models and Prime Video subscription anchoring. Long-term viability favors ecosystem owners with direct consumer relationships over component-agnostic assemblers. Watch HDCP 2.3 certification backlog resolution as inflection signal for holiday retail launch timing.
| Strategic Initiative | Industry Significance |
|---|---|
| AV1 Hardware Decode Integration | Enables royalty-free 4K streaming without HEVC patent pool obligations for Netflix and YouTube. |
| EU Ecodesign Certification Acceleration | Reduces standby power below one watt to comply with Green Deal mandates in Germany and France. |
| India PLI Manufacturing Expansion | Captures local assembly incentives in Gujarat and Tamil Nadu for JioFiber bundling contracts. |
| Voice Control Peripheral Integration | Converges far-field microphone arrays with STB remotes for hands-free content discovery. |
| Conditional Access Security Consolidation | Mitigates single-source risk from European Common Interface Plus chipset vendors. |
Research Methodology
Document review covered FCC equipment authorization databases, EU Ecodesign implementing measures, and MIIT network access license filings, complemented by interviews with chipset vendor product managers, pay-TV operator procurement directors, and contract manufacturing executives in Shenzhen and Dongguan. Secondary validation drew from customs trade records, SEC 10-K disclosures from platform operators, and TRAI regulatory circulars. Bottom-up unit shipment estimates triangulated against top-down service revenue allocations across OTT streaming and pay-TV application segments.
Cross-referencing historical codec transition patterns with panel input from Amlogic and MediaTek engineering directors shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology codec tier, application service model, and end-user procurement authority. CAGRs derived from installed base replacement cycle analysis and energy mandate compliance schedules. Industry-specific inputs incorporated PLI scheme capacity buildout timelines and AV1 hardware decode penetration curves.
Underlying measurement precision varies by segment; OTT streaming shipment estimates carry tighter precision than hospitality procurement forecasts given fragmented property-level data. Projections reflect assumptions on broadband infrastructure rollout pace and regulatory energy mandate enforcement intensity. A model refresh is warranted upon material change in DDR4 and NAND flash contract pricing or HDCP certification timeline extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IT Hardware
India IT Hardware Market
IT Hardware
Tablet PC Market
IT Hardware
Middle East and Africa IT Device Market
IT Hardware
Europe IT Device Market
IT Hardware
USB 3.0 Market
IT Hardware
Cloud IT Infrastructure Hardware Market
IT Hardware
Global IT Hardware Market
IT Hardware
Three-Proof Laptop Market
IT Hardware
Asia Pacific IT Device Market
IT Hardware
PC Case Market
IT Hardware
Single Board Computer Market
IT Hardware
Industrial Motherboards Market
IT Hardware
Server Chassis Market