
 Europe IT Device Market | 2026-2036
Europe IT Device Market Size, Share, and Industry Trends Forecast 2026-2036
Europe IT Device Market Foresight
Enterprise distribution through value-added resellers is fragmenting as direct-to-business digital procurement platforms gain traction across the continent. ASML sustains its lithography equipment dominance through captive R&D investments in Veldhoven. Infineon anchors European semiconductor supply security with discrete power and security chip specialization for automotive and industrial clients. Nokia competes aggressively in private 5G network hardware, positioning its radio access portfolio for factory-floor digitization contracts.
Europe IT Devices encompass computing, networking, and peripheral hardware engineered to process, store, or transmit digital information, typically incorporating processors with thermal design power ratings from 15W ultrabook chips to 350W server-class units, solid-state storage subsystems, and wireless connectivity modules certified under ETSI standards. These systems serve commercial automation, data infrastructure, and knowledge-work productivity across regulated European industries. Laptops and tablets capture the largest volume share within product type segments, though servers command superior margin pools driven by AI training cluster deployments. Cloud computing technology underpins the fastest expansion trajectory as hyperscalers expand Frankfurt, Amsterdam, and Dublin data center footprints. Enterprise end users represent the most concentrated buyer segment, with healthcare facilities emerging as a priority vertical due to diagnostic imaging digitization mandates.
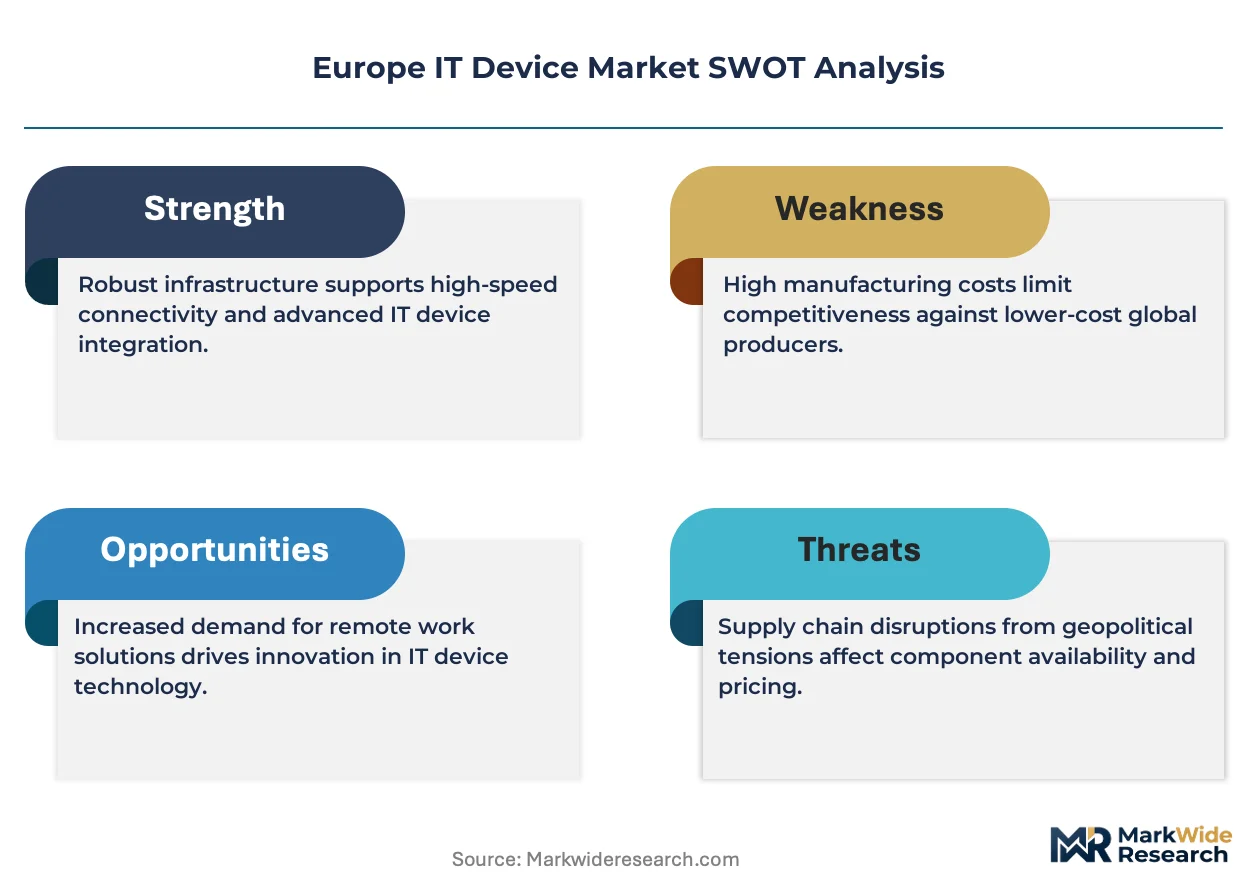
CE marking under the Radio Equipment Directive and Ecodesign framework enforced by national market surveillance authorities dictate electromagnetic compatibility and energy efficiency thresholds for hardware market access. The EU AI Act introduced by the European Parliament imposes risk-classification requirements on AI-embedded IT devices, compelling manufacturers to redesign inference accelerator modules and document training data provenance. REACH compliance managed by ECHA restricts hazardous substance content in printed circuit assemblies, elevating material substitution costs for producers serving European public sector tenders. Stakeholders must monitor evolving conformity assessment timelines and pre-position modular product architectures capable of absorbing regulatory scope expansion without complete platform redesign.
Market Dynamics
Enterprise procurement of AI-enabled workstations is compressing refresh cycles across Germany and France, while the EU AI Act forces hardware redesigns for inference accelerators before devices reach European markets.
Growth Catalysts
- AI Act Compliance Mandate:The EU AI Act's risk-classification framework compels manufacturers to pre-integrate documented training data provenance into embedded inference modules, creating captive demand for compliant chipsets.
- Industrial Automation Corridors:Germany's Ruhr and Baden-Württemberg manufacturing belts are deploying edge computing clusters for real-time quality control, pulling high-TDP workstation shipments.
- Ecodesign Energy Thresholds:Servers exceeding new efficiency benchmarks under the Ecodesign framework gain preferential placement in Nordic hyperscaler tenders, rewarding thermal design investments.
Market Restraints
- Lithography Equipment Concentration:Advanced node semiconductor production depends on single-source extreme ultraviolet tools, creating supply vulnerability for European AI accelerator fabs.
- Neodymium Magnet Supply:Permanent magnets for server cooling motors and hard drive actuators concentrate in Asian refining corridors, exposing assemblers to rare earth price volatility.
- REACH Substitution Costs:ECHA-mandated replacements for flame retardants and solder alloys in printed circuit assemblies elevate material costs for producers serving public sector tenders.
Strategic Opportunities
- Private 5G Network Hardware:Factory-floor digitization contracts in France and Italy are creating openings for radio access equipment optimized for industrial latency requirements.
- Healthcare Imaging Digitization:Diagnostic equipment mandates across EU member states are pulling high-resolution display panels and GPU-accelerated workstations into hospital procurement pipelines.
- Modular Product Architectures:CE marking under the Radio Equipment Directive rewards platform designs capable of absorbing regulatory scope expansion without complete redesign cycles.
Industry Challenges
- Conformity Assessment Timelines:National market surveillance authorities in multiple member states operate asynchronous approval queues, delaying synchronized product launches.
- Inference Accelerator Integration:Legacy enterprise software stacks require extensive revalidation when AI coprocessors replace conventional CPU-only configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe IT Device Market |
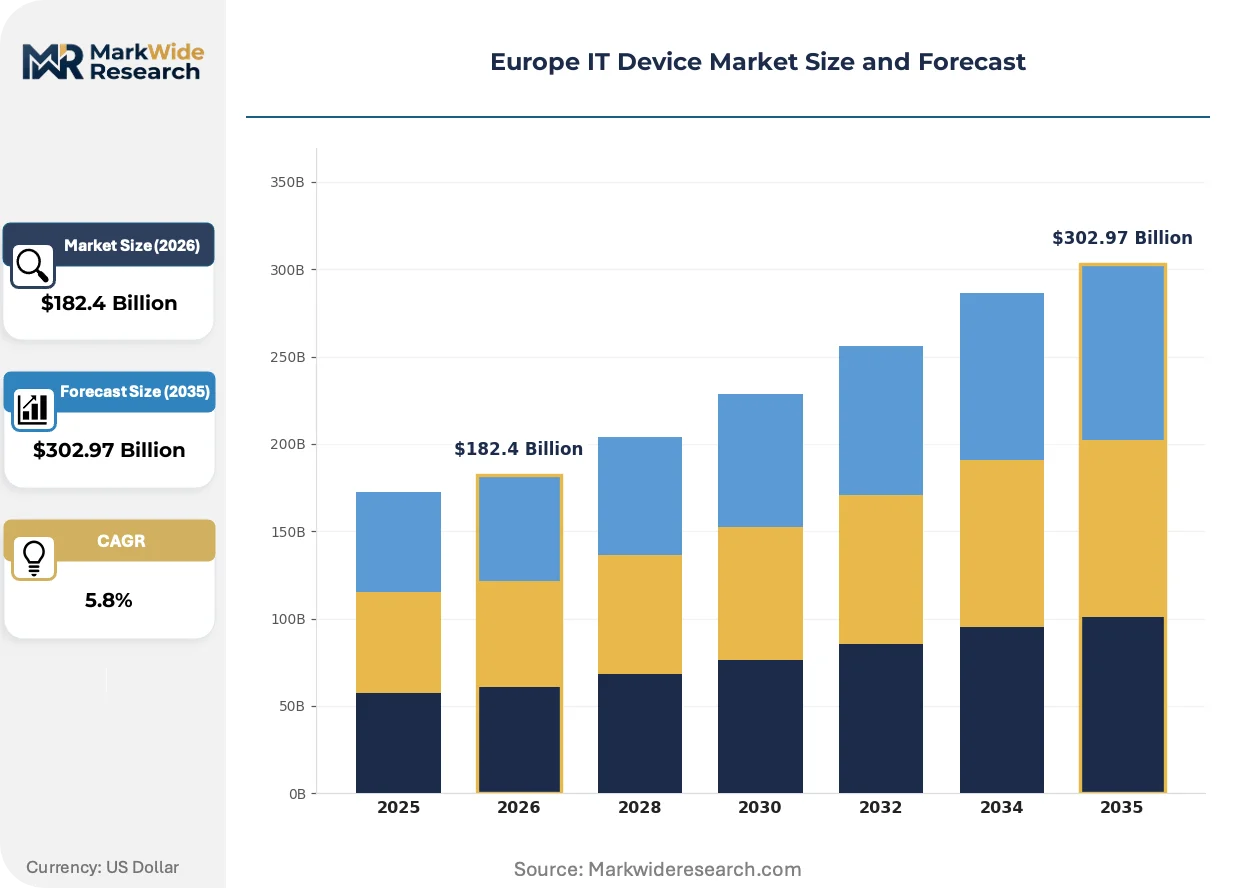
| Market Size in 2026 | $182.4 Billion |
| Market Size in 2035 | $302.97 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laptops, Desktops, Tablets, Servers Technology: AI, IoT, Cloud Computing, Virtual Reality End User: Enterprises, Educational Institutions, Healthcare Facilities, Government Agencies Distribution Channel: Online Retailers, Direct Sales, Value-Added Resellers, Distributors |
| Companies Covered | STMicroelectronics, Nokia, ASML, ASM International, Adyen, Infineon, Arm, Oura Health, NXP Semiconductors, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe IT Device Market Shifts & Advancements
Hardware architectures are fragmenting between cloud-scale training clusters and distributed edge inference nodes, with thermal design power budgets diverging sharply across deployment contexts.
Arm-based server processors are penetrating European data centers through efficiency-optimized cloud instances. Hyperscalers in Frankfurt and Amsterdam are deploying these chips for containerized workloads. The technology is digitizing thermal management tradeoffs previously dominated by x86 performance-per-watt benchmarks.
The EU AI Act's risk-classification framework is reshaping embedded system design rules. Manufacturers must now document training data provenance and implement kill-switch circuitry for high-risk AI applications. Medical device and automotive ECU categories face the steepest compliance gradients, with notified bodies expanding assessment capacity.
Direct-to-business digital procurement platforms are displacing value-added reseller networks for standard server configurations. Enterprise buyers in the Netherlands and Ireland are consolidating purchases through self-service portals with transparent configuration tools. This channel rotation is most visible in mid-market segments where customization requirements remain minimal.
Europe IT Device Market Segmentation
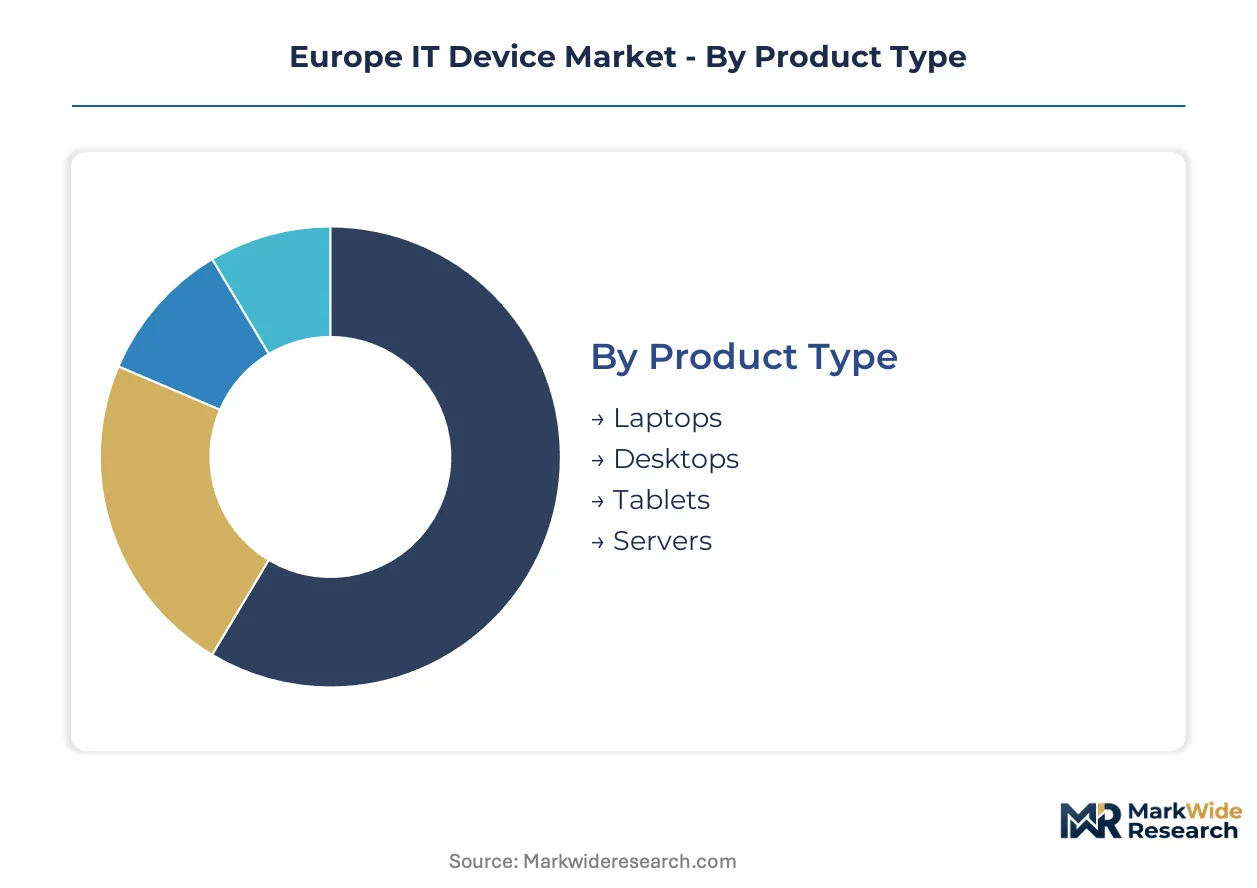
Segmentation in the Europe IT Device Market reveals divergent margin structures and procurement behaviors across hardware categories. Understanding these divides helps manufacturers align thermal design investments with buyer willingness to pay for efficiency and compliance.
Product Type:
Cost tier differentiation separates high-volume consumer hardware from mission-critical infrastructure systems with extended service lifecycles.
- Laptops:Mobile computing platforms with 15W to 45W TDP processors, integrated graphics subsystems, and solid-state storage. Demand concentrates in German knowledge-work corridors where hybrid work mandates sustain fleet refresh programs.
- Servers:Rack-mounted and blade configurations with 150W to 350W processors, redundant power supplies, and hardware-rooted security modules. Nordic hyperscalers in Frankfurt and Amsterdam drive procurement of AI training clusters with liquid cooling requirements.
- Desktops:Fixed workstation platforms for specialized applications requiring discrete GPU expansion. European public sector tenders specify Ecodesign-compliant units with documented energy consumption metrics.
- Tablets:Touch-optimized mobile devices with ARM-based SoCs and cellular connectivity modules. Healthcare facilities in France and Italy deploy ruggedized variants for bedside patient data access.
Laptops command the established base. The steepest expansion runs through servers.
Technology:
Application maturity separates proven infrastructure platforms from emerging workloads requiring specialized silicon.
- Cloud Computing:Distributed infrastructure for elastic compute and storage provisioning. Frankfurt, Amsterdam, and Dublin hyperscaler expansions pull high-density server shipments with advanced thermal management.
- AI:Machine learning inference and training acceleration through dedicated tensor processing units. The EU AI Act forces redesigns of embedded inference modules for risk-classified applications in automotive and medical devices.
- IoT:Networked sensor and actuator systems with constrained power budgets. Industrial automation corridors in Baden-Württemberg deploy edge gateways for real-time quality control feedback loops.
- Virtual Reality:Head-mounted displays with high-refresh panels and spatial tracking subsystems. Enterprise training programs in aviation and energy sectors drive niche procurement of tethered workstation bundles.
Cloud computing anchors current infrastructure spending. AI workloads are climbing the fastest.
End User:
Customer type determines procurement complexity, with regulated verticals imposing documentation and compliance burdens that commodity buyers avoid.
- Enterprises:Corporate IT departments with standardized refresh cycles and volume purchasing agreements. German automotive manufacturers lead workstation deployments for engineering simulation workloads.
- Healthcare Facilities:Hospitals and diagnostic centers with imaging digitization mandates. EU member state requirements pull GPU-accelerated workstations and high-resolution display panels into procurement pipelines.
- Government Agencies:Public sector bodies with tender-based purchasing and REACH compliance requirements. Flame retardant substitutions in printed circuit assemblies elevate material costs for these buyers.
- Educational Institutions:Universities and vocational schools with constrained capital budgets. Bulk purchasing consortia negotiate standard laptop configurations for student device programs.
Enterprises dominate volume commitments. Healthcare facilities are gaining share fastest.
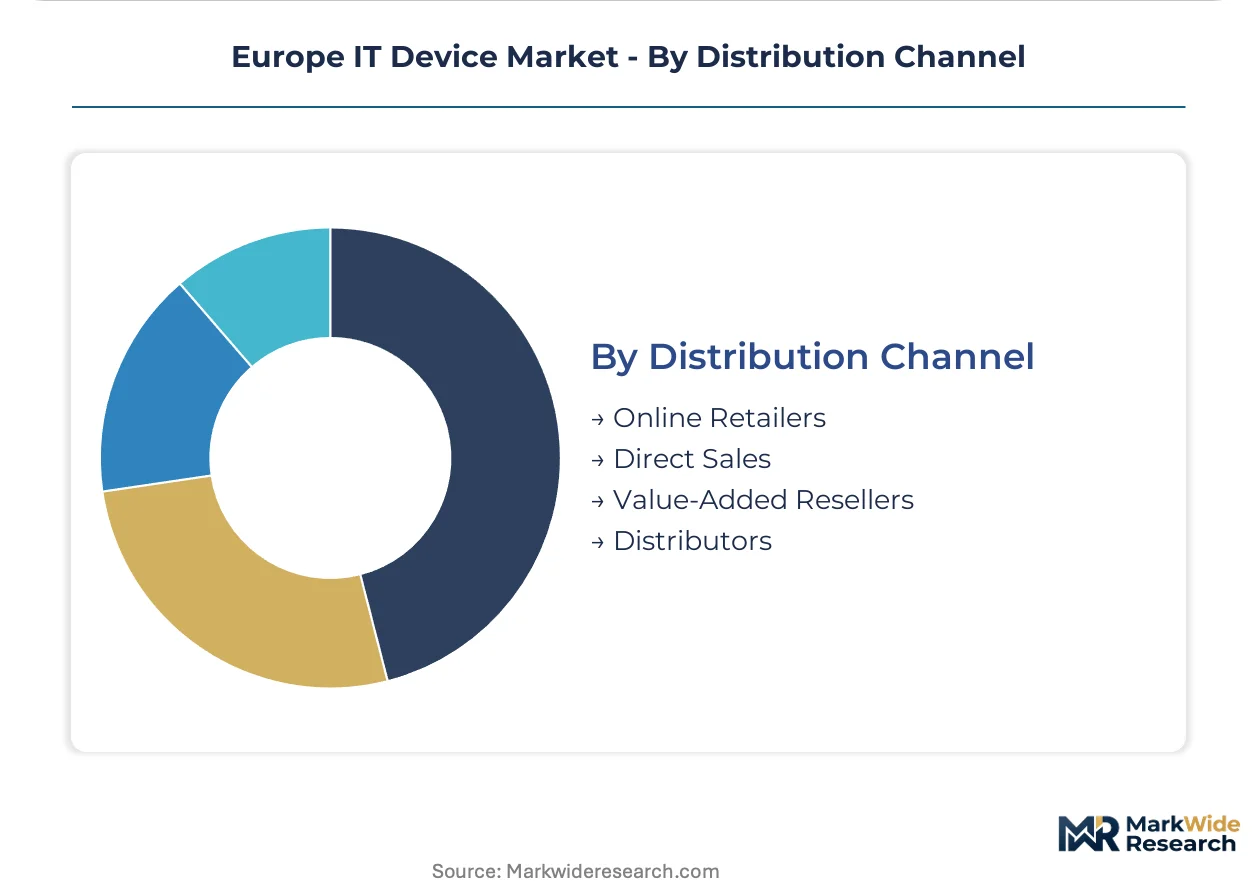
Distribution Channel:
Supply concentration shapes margin capture, with direct relationships displacing intermediary layers in standardized hardware categories.
- Direct Sales:Manufacturer-to-business transactions with configuration tools and transparent pricing. Dutch and Irish mid-market buyers consolidate server purchases through self-service portals.
- Value-Added Resellers:Integration and support specialists serving complex deployment scenarios. Fragmentation accelerates as digital procurement platforms capture standard configuration business.
- Online Retailers:E-commerce platforms with comparison tools and rapid fulfillment. Consumer and small business laptop purchases migrate to these channels for price transparency.
- Distributors:Inventory and logistics intermediaries serving fragmented reseller networks. Geographic coverage requirements sustain their role in peripheral European markets.
Value-added resellers retain the installed base. Direct sales channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Amsterdam-Rhine-Ruhr corridor's dense fiber interconnects and Frankfurt's DE-CIX internet exchange anchor Europe's data infrastructure gravity, pulling hyperscaler investments and enterprise procurement decisions toward these nodes.
Germany
Industrial automation corridors in Baden-Württemberg and North Rhine-Westphalia deploy edge computing clusters for real-time quality control. The EU AI Act's risk-classification requirements compel automotive ECU manufacturers to redesign inference modules. Stuttgart's manufacturing belt concentrates GPU-accelerated workstation procurement for engineering simulation workloads.
Netherlands
Hyperscaler expansions in Amsterdam and Eindhoven drive liquid-cooled server shipments for AI training clusters. REACH compliance managed by ECHA elevates material substitution costs for printed circuit assemblies. The Randstad metro anchors direct-to-business digital procurement platform adoption among mid-market enterprises.
France
Healthcare imaging digitization mandates pull high-resolution display panels and GPU workstations into hospital procurement pipelines. ANSM and CNIL oversight intersects with EU AI Act requirements for medical device embedded systems. Factory-floor digitization contracts in Île-de-France and Auvergne-Rhône-Alpes create demand for private 5G network hardware.
Sweden
Nordic cloud infrastructure hubs prioritize servers exceeding Ecodesign energy efficiency benchmarks for preferential tender placement. The country's national market surveillance authority operates CE marking queues for Radio Equipment Directive compliance. Stockholm's data center cluster concentrates Arm-based processor deployments for containerized cloud workloads.
Ireland
Dublin's hyperscaler footprint expands with AI training cluster investments requiring advanced thermal management. GDPR enforcement by the Data Protection Commission shapes data residency requirements for server procurement. Enterprise buyers consolidate purchases through self-service digital procurement portals with transparent configuration tools.
Europe IT Device Market Competitive Landscape
On the supply side, the industry is consolidating around specialized semiconductor equipment and discrete chip fabrication, with lithography tool dependence creating single-source vulnerabilities. Three archetypes dominate: captive R&D specialists controlling critical process technologies, diversified component suppliers serving automotive and industrial verticals, and intellectual property licensors enabling third-party chip designs. Competitive moves concentrate on strategic partnerships for EU AI Act compliance and modular product architectures absorbing regulatory scope expansion.
Among Netherlands-based equipment specialists, ASML and ASM International exemplify the captive R&D archetype through lithography and deposition tool dominance. STMicroelectronics and Infineon represent diversified European component suppliers anchoring supply security for automotive and industrial clients. Nokia occupies a position in private 5G network hardware, competing for factory-floor digitization contracts across French and Italian industrial corridors.
| Leading Market Players |
|---|
| STMicroelectronics |
| Nokia |
| ASML |
| ASM International |
| Adyen |
| Infineon |
| Arm |
| Oura Health |
| NXP Semiconductors |
| Others |
Supply & Pricing Matrix
Extreme ultraviolet lithography equipment from ASML's Veldhoven facilities anchors margin capture at the most advanced semiconductor nodes, concentrating pricing power with captive R&D specialists while downstream assemblers absorb rare earth magnet volatility in server cooling subsystems.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise server procurement, with hyperscaler direct agreements commanding 15-25 point discounts off list against mid-market VAR-mediated purchases. Price differentiation hinges on Ecodesign certification tiers and thermal management complexity, with liquid-cooled AI training clusters sustaining premium positioning against air-cooled commodity racks. Cost compression in entry-level laptop tiers intensifies as direct-to-business platforms displace distributor markups. Healthcare facilities demonstrate lowest price sensitivity due to diagnostic imaging digitization mandates, while educational consortia negotiate aggressively on standard fleet configurations.
Supply Chain Analysis
Export-control regimes restricting extreme ultraviolet tool flows to Chinese fabs have redirected lithography capacity toward European and Taiwanese foundry expansions, tightening delivery queues for advanced node AI accelerators. Semiconductor manufacturing draws from Netherlands-based equipment, Taiwanese wafer fabrication, and South Korean memory packaging. Neodymium magnet refining concentrates in Chinese and Vietnamese corridors, exposing server motor assemblies to supply disruption. Single-source dependency on ASML's EUV systems creates structural vulnerability for European AI chip self-sufficiency. Distribution runs through direct sales portals for hyperscalers and value-added reseller networks for complex enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe IT Device Market is recovering from cyclical inventory destocking, with enterprise AI workstation refresh programs and hyperscaler capacity expansion providing demand momentum across the analysis window.
For Market Incumbents: Entrench lithography equipment dominance through captive R&D commitments in Veldhoven and Dresden corridor partnerships. Defend against Arm-based server processor encroachment by accelerating x86 efficiency roadmaps for Frankfurt and Amsterdam cloud instances. Prioritize modular product architectures capable of absorbing EU AI Act scope expansion without platform redesign cycles.
For New Entrants and Emerging Players: Private 5G network hardware for French and Italian factory-floor digitization contracts represents the most penetrable entry point among infrastructure categories underserved by incumbent radio access specialists. GPU-accelerated medical imaging workstations for ANSM-regulated hospital procurement pipelines offer second-tier white space. Channel through direct-to-business digital procurement platforms with transparent configuration tools to bypass established VAR relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI training cluster deployments requiring liquid-cooled infrastructure and specialized inference accelerator packaging. Long-term viability over the next decade rests on regulatory compliance capabilities rather than pure performance benchmarks. Target acquisition candidates with established EU AI Act documentation protocols and REACH-certified supply chains. Monitor Ecodesign threshold revisions as the critical inflection signal for server margin compression or expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Product Architecture Investment | Enables rapid EU AI Act compliance absorption without complete platform redesign cycles. |
| Direct-to-Business Digital Procurement Platform Launch | Captures mid-market server volume migrating from value-added reseller networks in Netherlands and Ireland. |
| Private 5G Radio Access Equipment Partnership | Positions hardware portfolios for Île-de-France and Auvergne-Rhône-Alpes factory-floor digitization contracts. |
| Healthcare Imaging Workstation Certification Pathway | Unlocks ANSM-regulated hospital procurement pipelines for GPU-accelerated diagnostic platforms. |
| Ecodesign-Compliant Thermal Management Scale-Up | Secures preferential placement in Nordic hyperscaler tenders exceeding energy efficiency benchmarks. |
Research Methodology
The analysis maps lithography equipment, discrete power semiconductors, server-class processors, and private 5G hardware sub-sectors, each validated through procurement officers at German automotive manufacturers, Dutch hyperscaler infrastructure teams, French hospital biomedical engineers, and Nordic cloud platform architects. Primary interview insights triangulate against secondary sources including SEC filings from equipment vendors, ECHA REACH substance restriction updates, EU AI Act implementation guidance, and hyperscaler capital expenditure disclosures. Bottom-up shipment modeling and top-down market sizing converge through iterative stakeholder feedback.
Assumptions held fixed include current EU AI Act risk-classification thresholds, Ecodesign energy efficiency benchmarks, and REACH substance restriction scopes, while tariff regimes and export control stringency were varied across sensitivity scenarios. Segmentation dimensions span product type, technology deployment model, end-user vertical, and distribution channel structure. CAGRs derive from regression analysis against historical refresh cycle patterns and projected AI infrastructure investment trajectories. Forecast inputs incorporate foundry capacity expansion timelines and enterprise software stack revalidation requirements for inference accelerator integration.
Practitioners should monitor EU AI Act delegated act expansions, Ecodesign threshold revisions, and rare earth magnet supply disruption indicators for early signals of forecast deviation. Material shifts in lithography equipment export control scope or REACH substance restriction acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IT Hardware
Three-Proof Laptop Market
IT Hardware
India IT Hardware Market
IT Hardware
Tablet PC Market
IT Hardware
PC Case Market
IT Hardware
Industrial Motherboards Market
IT Hardware
Cloud IT Infrastructure Hardware Market
IT Hardware
Middle East and Africa IT Device Market
IT Hardware
Server Chassis Market
IT Hardware
Asia Pacific IT Device Market
IT Hardware
Single Board Computer Market
IT Hardware
Global 4K Set Top Box (STB) Market
IT Hardware
Global IT Hardware Market
IT Hardware
USB 3.0 Market