
 Asia Pacific IT Device Market | 2026-2036
Asia Pacific IT Device Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific IT Device Market Outlook
China's dual carbon goals are restructuring supply chain requirements for IT device manufacturers serving the Asia Pacific region. HP Inc. leverages its established enterprise service networks to sustain large-volume contracts across Southeast Asian markets. Lenovo Group Limited anchors regional manufacturing through its in-house production facilities in Hefei and Wuhan. Samsung Electronics differentiates through vertical control over display and memory component supply.
Asia Pacific IT devices encompass computing and communication hardware with specifications ranging from sub-1 kg ultraportable form factors to AI-accelerated processors exceeding 45 TOPS for on-device inference, serving commercial productivity, connectivity, and data processing needs. Laptops and smartphones occupy the largest margin pools as replacement cycles shorten and enterprise refresh programs expand. Cloud Computing and Artificial Intelligence represent the fastest-growing technology segments as edge inference workloads migrate from centralized data centers to local devices.
China's MIIT enforces GB standards for electromagnetic compatibility and energy efficiency that shape product design requirements for devices manufactured or sold in the region. India's BIS mandates compulsory registration for IT equipment imports, while Japan's METI promotes JIS-aligned sustainability criteria for corporate procurement. Stakeholders must monitor divergence between national certification regimes when configuring regional product portfolios.
Market Dynamics
Enterprise procurement of cloud-ready laptops is restructuring demand patterns across Asia Pacific as organizations prioritize AI-accelerated edge inference capabilities and unified endpoint management.
Growth Catalysts
- India's BIS certification mandates:Compulsory registration schemes for IT equipment imports are elevating product quality benchmarks and filtering non-compliant suppliers from the regional market.
- China's Yangtze River Delta cluster:Concentrated manufacturing infrastructure enables rapid scaling of high-volume laptop and smartphone production for regional distribution.
- On-device AI inference workloads:Migration of computational tasks from centralized data centers to local processors is accelerating replacement cycles for enterprise device fleets.
Market Restraints
- Memory component supply concentration:Vertical control over DRAM and NAND flash by Korean and Chinese suppliers creates vulnerability to geopolitical trade restrictions and export controls.
- China's dual carbon goals:Energy efficiency mandates under MIIT enforcement are raising compliance costs for manufacturing facilities and limiting expansion permits.
- Display panel input volatility:OLED substrate and driver IC supply bottlenecks from concentrated Taiwanese and Korean sources generate price instability for premium device segments.
Strategic Opportunities
- Vietnam and Indonesia manufacturing:Underpenetrated assembly capacity in Southeast Asian economies offers tariff-advantaged export positioning for China-origin component flows.
- Japan's METI sustainability criteria:JIS-aligned corporate procurement guidelines create preferential market access for devices meeting circular economy and carbon disclosure standards.
- 5G-integrated edge AI convergence:Combining millimeter-wave connectivity with neural processing units opens industrial IoT and smart manufacturing application verticals previously served by separate device categories.
Industry Challenges
- GB standard electromagnetic compatibility testing:China's MIIT certification timelines extend product launch windows and require redundant testing protocols for devices serving multiple national markets.
- Legacy enterprise fleet integration:Hybrid cloud management platforms must bridge on-premises Active Directory infrastructure with modern zero-trust architectures, complicating deployment at scale.
- Specialized NPU firmware engineering:Scarce talent pools for optimizing on-device inference workloads across heterogeneous silicon architectures constrain product differentiation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific IT Device Market |
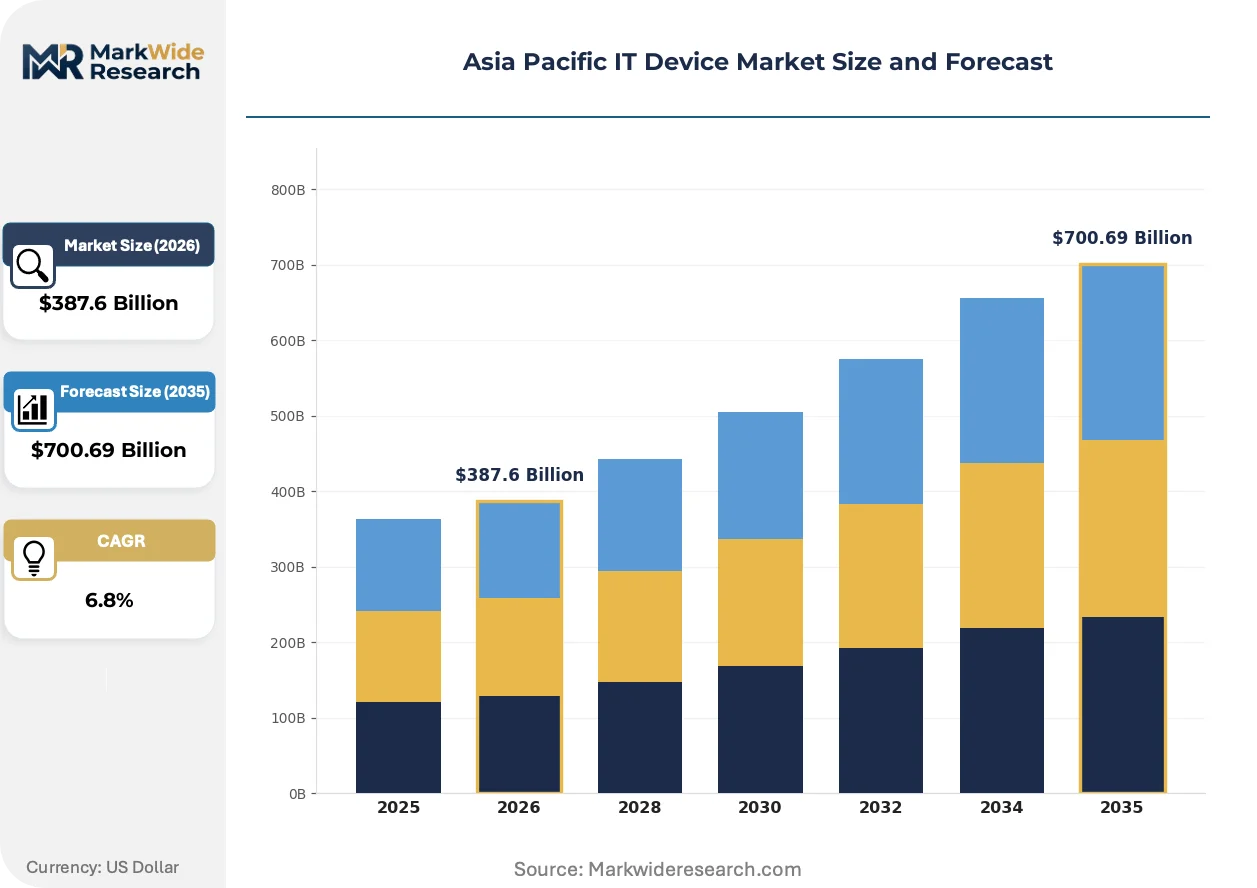
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laptops, Desktops, Tablets, Smartphones Technology: Cloud Computing, Artificial Intelligence, IoT, Edge Computing End User: Enterprises, Educational Institutions, Government, Individual Consumers Distribution Channel: Online Retail, Direct Sales, Retail Stores, Value-Added Resellers |
| Companies Covered | HP Inc., ASUSTek Computer Inc., Lenovo Group Limited, Huawei Technologies, Xiaomi Corporation, Samsung Electronics, Dell Technologies, Acer Inc., Apple Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific IT Device Market Strategic Shifts
Neural processing unit integration is compressing the boundary between consumer and enterprise device categories as inference capabilities become baseline specifications rather than premium differentiators.
Coprocessor architectures are unifying CPU, GPU, and NPU silicon onto single-package designs. Enterprise buyers in financial services and healthcare verticals are adopting these configurations within eighteen-month refresh cycles. This unification is collapsing the historical segmentation between productivity laptops and workstation-class mobile devices.
Japan's METI has issued JIS-aligned sustainability disclosure requirements for corporate IT procurement. Manufacturers must now document full lifecycle carbon footprints and modular repairability scores. Premium enterprise contracts in Tokyo and Osaka metropolitan markets increasingly specify compliance with these criteria as mandatory bidding prerequisites.
Device-as-a-service contracting is displacing capital purchase models among mid-market enterprises. Managed service providers are capturing procurement decisions previously controlled by internal IT departments. Australia and Singapore exhibit the fastest transition velocity, with banking and professional services verticals leading adoption.
Asia Pacific IT Device Market Segmentation
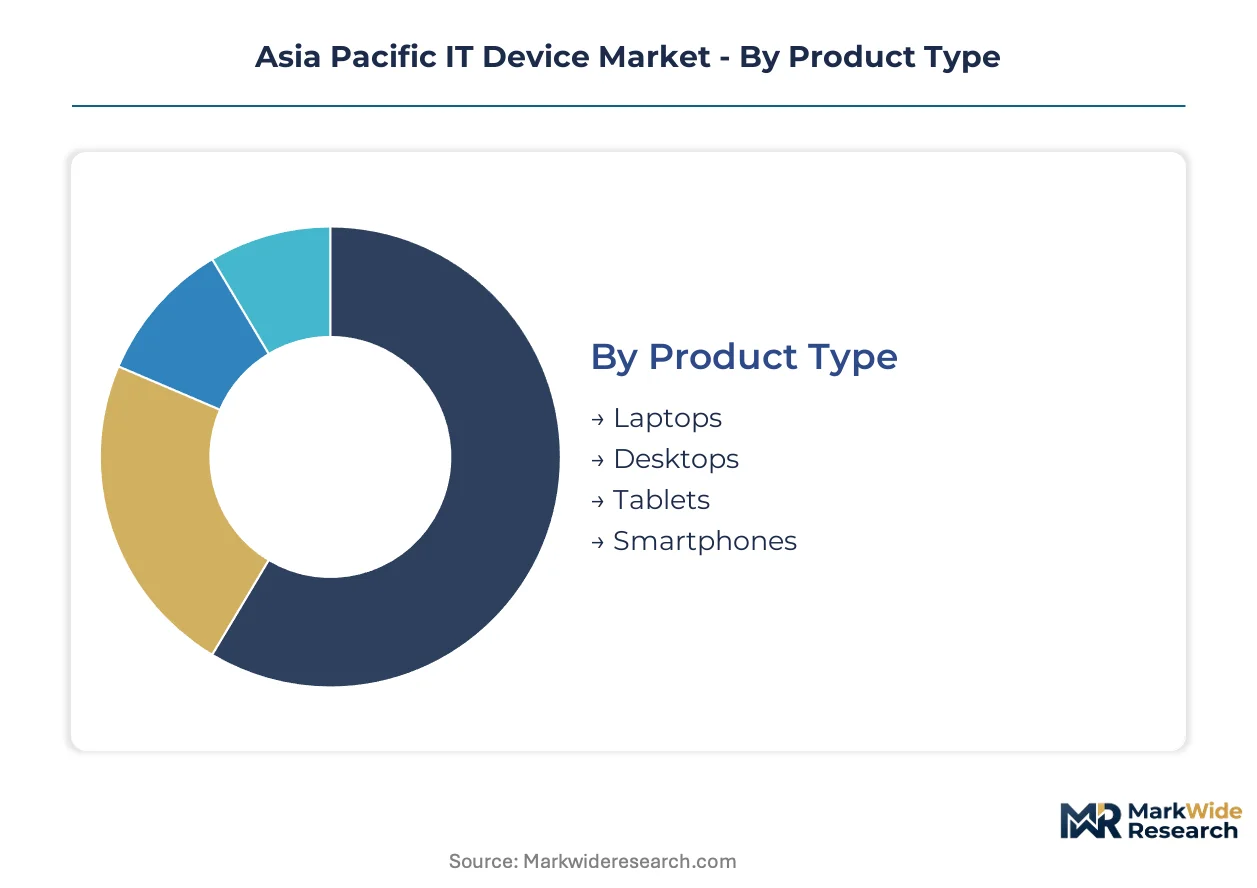
IT device procurement in Asia Pacific follows distinct configuration logics across product, technology, and customer dimensions. Segment boundaries are blurring as AI inference capabilities and cloud management platforms become baseline requirements rather than premium tiers.
Product Type:
Standardization dominates at the component level while customization concentrates in form factor and thermal design across this category.
- Laptops:Cloud-ready configurations with neural processing units exceeding 45 TOPS now anchor enterprise refresh programs. Procurement concentrates in China's Yangtze River Delta manufacturing cluster as organizations prioritize unified endpoint management and AI-accelerated edge inference.
- Smartphones:5G-integrated devices with on-device inference capabilities are compressing replacement cycles across enterprise fleets. India's BIS certification mandates are filtering non-compliant suppliers while elevating quality benchmarks for regional distribution.
- Desktops:Tower and small-form-factor units serve legacy workstation applications in manufacturing and engineering verticals.
- Tablets:Ruggedized and stylus-enabled variants address field service and healthcare mobility requirements.
Leading the category by volume: Laptops. Growing fastest: Smartphones.
Technology:
Deployment maturity separates established infrastructure plays from emerging workload categories in this segmentation.
- Artificial Intelligence:Neural processing unit integration is collapsing historical boundaries between consumer and enterprise device tiers. Migration of inference workloads from centralized data centers to local processors is accelerating hardware refresh cycles across financial services and healthcare verticals in Japan and Australia.
- Cloud Computing:Unified endpoint management and zero-trust architecture compliance now drive procurement specifications. Device-as-a-service contracting is displacing capital purchase models among mid-market enterprises in Singapore and Australian banking sectors.
- Edge Computing:Industrial IoT gateways and smart manufacturing controllers are opening application verticals previously served by separate device categories.
- IoT:Sensor-integrated endpoints serve predictive maintenance and asset tracking in logistics and warehousing operations.
Expanding most quickly: Artificial Intelligence. Largest installed base: Cloud Computing.
End User:
Budget authority and refresh frequency create distinct purchasing patterns across this customer segmentation.
- Enterprises:Device-as-a-service adoption is shifting procurement decisions from internal IT departments to managed service providers. Financial services and professional services verticals in Australia and Singapore exhibit the fastest transition velocity.
- Educational Institutions:Bulk purchasing programs and extended warranty requirements dominate procurement logic across K-12 and higher education segments.
- Government:India's BIS mandates and China's GB standards for electromagnetic compatibility create compliance-intensive procurement workflows with extended certification timelines.
- Individual Consumers:Replacement cycle compression in premium segments contrasts with extended holding periods in mass-market tiers.
Maximum contract value: Enterprises. Steepest expansion trajectory: Educational Institutions.
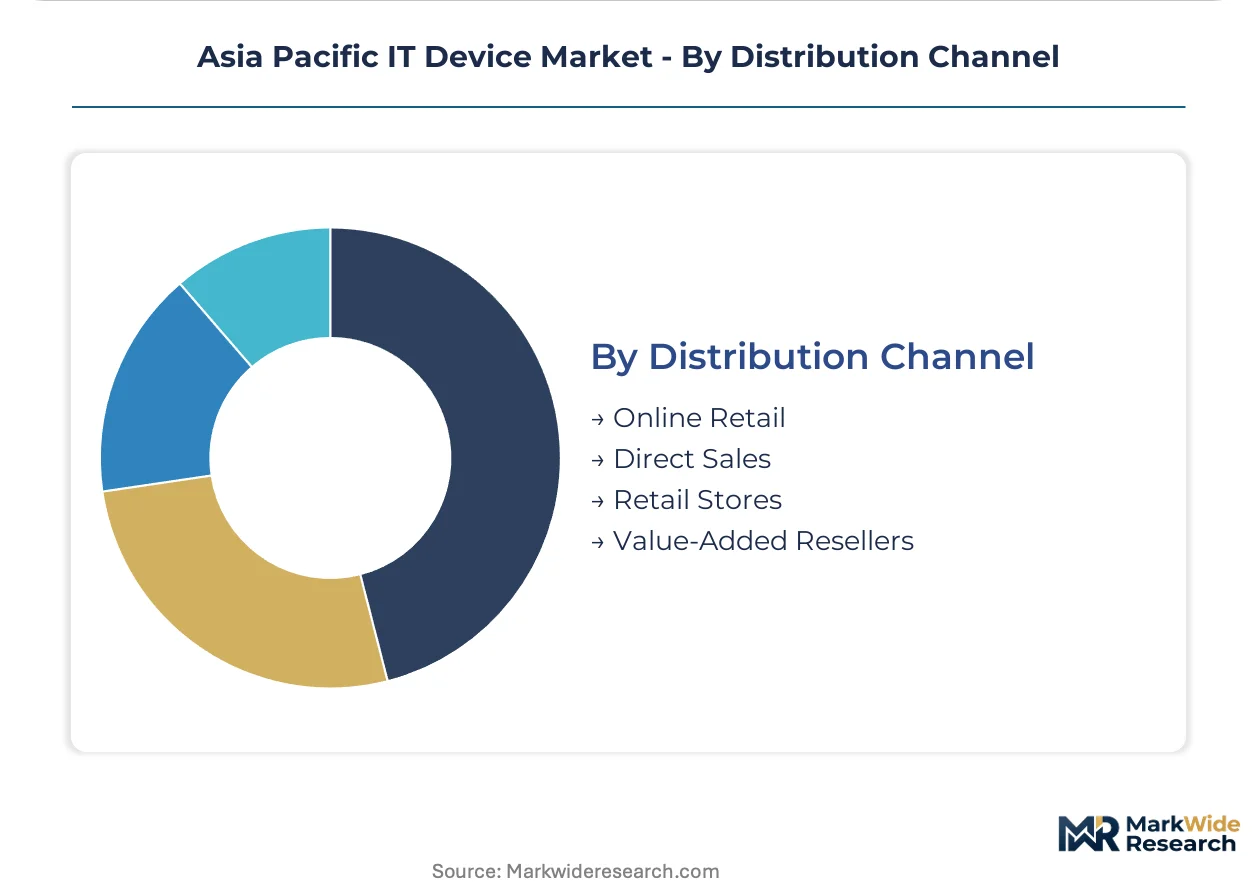
Distribution Channel:
Control over configuration and support services determines channel selection across customer segments.
- Direct Sales:Large-volume enterprise contracts with customized imaging and fleet management services anchor this channel. HP Inc. and Lenovo Group Limited leverage established service networks to sustain regional contract wins.
- Value-Added Resellers:Hybrid cloud integration and legacy Active Directory bridging services create differentiation for mid-market enterprise accounts.
- Online Retail:Consumer and small business transactions concentrate in marketplace platforms with standardized configurations.
- Retail Stores:Tactile evaluation and immediate fulfillment support consumer preference in premium smartphone and laptop segments.
Highest margin capture: Direct Sales. Gaining share fastest: Value-Added Resellers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta manufacturing cluster anchors regional production capacity for cloud-ready laptops and AI-accelerated devices. Shanghai, Suzhou, and Hangzhou form a contiguous production corridor where component suppliers, assembly facilities, and logistics hubs operate within two-hour transit windows. This concentration enables rapid scaling of high-volume orders for enterprise procurement programs across Southeast Asia.
China
MIIT enforcement of GB standards for electromagnetic compatibility and energy efficiency is extending product launch timelines for devices targeting domestic and export markets. The dual carbon goals are restricting expansion permits for manufacturing facilities in coastal provinces. Hefei and Wuhan house in-house production facilities that serve as alternative assembly nodes when Yangtze River Delta capacity saturates.
India
BIS compulsory registration schemes for IT equipment imports are filtering non-compliant suppliers from the regional market while elevating quality benchmarks for enterprise and government procurement. The PLI scheme for electronics manufacturing is attracting assembly investments into Gujarat and Tamil Nadu. Noida and Sri City emerging as alternative production corridors for smartphone and laptop assembly serving domestic demand.
Japan
METI JIS-aligned sustainability disclosure requirements for corporate IT procurement are creating preferential market access for devices with documented lifecycle carbon footprints. Financial services and healthcare verticals in Tokyo and Osaka metropolitan markets specify circular economy compliance as mandatory bidding prerequisites. Nagoya manufacturing belt maintains specialized capacity for industrial IoT gateway production.
Australia
Banking and professional services verticals exhibit the fastest transition velocity toward device-as-a-service contracting models. Sydney and Melbourne enterprise markets are shifting procurement decisions from internal IT departments to managed service providers. This shift is compressing replacement cycles for AI-accelerated laptop fleets.
Vietnam
Tariff-advantaged export positioning is attracting China-origin component flows for final assembly of smartphones and laptops. Bac Ninh and Bac Giang provinces house expanding electronics manufacturing zones. Underpenetrated assembly capacity offers alternative sourcing for enterprises diversifying supply chain exposure.
Asia Pacific IT Device Market Competitive Environment
The competitive structure tilts toward diversified electronics conglomerates with captive component supply and established enterprise service networks. Market concentration is moderate, with five to eight players capturing significant share in laptops and smartphones while remaining segments fragment across regional specialists. Two archetypes dominate: vertically integrated manufacturers controlling display and memory supply, and brand-asset companies leveraging outsourced production with premium positioning. Capacity expansion and strategic partnerships represent the primary competitive moves, with players securing assembly capacity in Vietnam and Indonesia to navigate tariff and carbon compliance pressures.
Within the diversified conglomerate tier, Samsung Electronics and Huawei Technologies exemplify archetypes built on component control and integrated production ecosystems. HP Inc. and Lenovo Group Limited occupy positions anchored by enterprise service networks and large-volume contract sustainment across Southeast Asian markets. Dell Technologies sits within the direct-sales enterprise specialist tier. Among these, HP Inc. and Lenovo Group Limited represent the scale-driven end of procurement-focused competition.
| Leading Market Players |
|---|
| HP Inc. |
| ASUSTek Computer Inc. |
| Lenovo Group Limited |
| Huawei Technologies |
| Xiaomi Corporation |
| Samsung Electronics |
| Dell Technologies |
| Acer Inc. |
| Apple Inc. |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals gate qualified supply and premium-tier pricing access for IT device manufacturers serving Asia Pacific enterprise buyers. MIIT enforcement of GB standards for energy efficiency and electromagnetic compatibility restricts manufacturing expansion permits in coastal provinces, concentrating compliant capacity within the Yangtze River Delta cluster. This environmental mandate elevates compliance costs that feed into pricing premiums for certified devices while filtering non-compliant suppliers from procurement shortlists.
Pricing Analysis
Per-unit transactional pricing anchored to TOPS performance benchmarks dominates enterprise laptop procurement across Asia Pacific. Three-tier pricing structure across premium, standard, and economy levels separates AI-accelerated configurations exceeding 45 TOPS from baseline productivity units and entry-level education devices. Cost compression in the standard tier is intensifying because memory component supply concentration limits negotiation leverage with Korean and Chinese DRAM suppliers. Government and educational institutions exhibit highest price sensitivity due to bulk purchasing mandates, while financial services verticals in Tokyo and Singapore demonstrate lowest sensitivity when sustainability disclosure compliance is bundled.
Supply Chain Analysis
Regional distribution centers in Shanghai, Singapore, and Sydney operate hub-and-spoke patterns that consolidate component flows from China, South Korea, and Taiwan before last-mile deployment. The supply chain draws from concentrated DRAM and NAND flash fabrication in South Korea, display panel production in Taiwan and South Korea, and final assembly capacity in China's Yangtze River Delta and emerging Vietnam electronics zones. Single-source vulnerability in OLED substrate and driver IC supply generates price instability for premium device segments. Distribution runs through direct sales channels for large-volume enterprise contracts and value-added resellers for mid-market hybrid cloud integration requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific IT device procurement operates as a supply-constrained market where Yangtze River Delta manufacturing saturation props pricing for compliant capacity. OLED substrate bottlenecks and MIIT expansion permit restrictions limit qualified supply growth below demand acceleration from AI inference workload migration.
For Market Incumbents: Cement enterprise service network density across Southeast Asian markets to sustain large-volume contract renewals against emerging Vietnam-based assemblers. Prioritize backward integration into neural processing unit firmware engineering to offset scarce talent pools constraining product differentiation velocity. Expand Hefei and Wuhan production nodes when Yangtze River Delta capacity saturates.
For New Entrants and Emerging Players: The price-point gap between premium AI-accelerated enterprise laptops and economy-tier education devices offers white-space targeting for mid-market managed service providers in Australia and Singapore. Device-as-a-service contracting penetration remains underdeveloped among professional services verticals outside banking, creating segment entry opportunity. Pursue JIS-aligned sustainability certification to unlock Tokyo and Osaka metropolitan procurement specifications.
For Investors and Strategic Acquirers: BIS registration scheme compliance acceleration in India is the leading indicator that quality-filtered supply consolidation will concentrate procurement decisions among certified manufacturers. Long-term viability favors diversified electronics conglomerates with captive component supply and established enterprise service networks. Monitor Vietnam electronics manufacturing zone expansion rates as signal for tariff-advantaged assembly capacity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Neural Processing Unit Integration | Compresses consumer-enterprise device boundaries as inference becomes baseline specification across financial services verticals. |
| Device-as-a-Service Platform Launch | Captures procurement decisions from internal IT departments in Australian banking and Singapore professional services. |
| JIS-Aligned Sustainability Certification | Unlocks mandatory bidding prerequisites in Tokyo and Osaka metropolitan enterprise markets under METI disclosure requirements. |
| Vietnam Manufacturing Footprint Expansion | Secures tariff-advantaged export positioning for China-origin component flows amid dual carbon permit restrictions. |
| Unified Endpoint Management Partnership | Bridges legacy Active Directory infrastructure with zero-trrust architectures for hybrid cloud enterprise deployments. |
Study Parameters
Multi-period observation of BIS registration timelines, MIIT GB standard enforcement patterns, and enterprise refresh cycle velocities anchored the trend analysis, supplemented by interviews with procurement officers at financial services firms, IT directors at educational institutions, channel managers at value-added resellers, and supply chain planners at electronics manufacturers. Secondary validation drew from MIIT regulatory filings, BIS compulsory registration databases, METI sustainability disclosure guidelines, customs trade data for component flows, and SEC filings of listed device manufacturers. Bottom-up assembly capacity estimates triangulated against top-down enterprise spending surveys across the analysis window.
Segment-weighting approaches modeled product type, technology deployment maturity, end-user budget authority, and distribution channel control dimensions throughout the forecast period. CAGRs derived from installed base turnover rates, replacement cycle compression patterns, and AI inference workload migration trajectories. Forecast inputs incorporated NPU integration adoption curves, device-as-a-service contracting velocity in Australian and Singapore markets, and BIS certification compliance rates for import suppliers.
Inputs from regulatory filings and enterprise procurement surveys were available through the study window; gaps in real-time component inventory data and unannounced capacity expansion permits introduce uncertainty bands around supply-side assumptions. Forecasts reflect documented assumptions regarding enforcement consistency of China's dual carbon goals and India's PLI scheme implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IT Hardware
Tablet PC Market
IT Hardware
Middle East and Africa IT Device Market
IT Hardware
Single Board Computer Market
IT Hardware
Global IT Hardware Market
IT Hardware
Industrial Motherboards Market
IT Hardware
India IT Hardware Market
IT Hardware
Europe IT Device Market
IT Hardware
USB 3.0 Market
IT Hardware
Server Chassis Market
IT Hardware
Three-Proof Laptop Market
IT Hardware
Global 4K Set Top Box (STB) Market
IT Hardware
Cloud IT Infrastructure Hardware Market
IT Hardware
PC Case Market