
 Server Chassis Market | 2026-2036
Server Chassis Market Size, Share, and Industry Trends Forecast 2026-2036
Server Chassis Market Intelligence
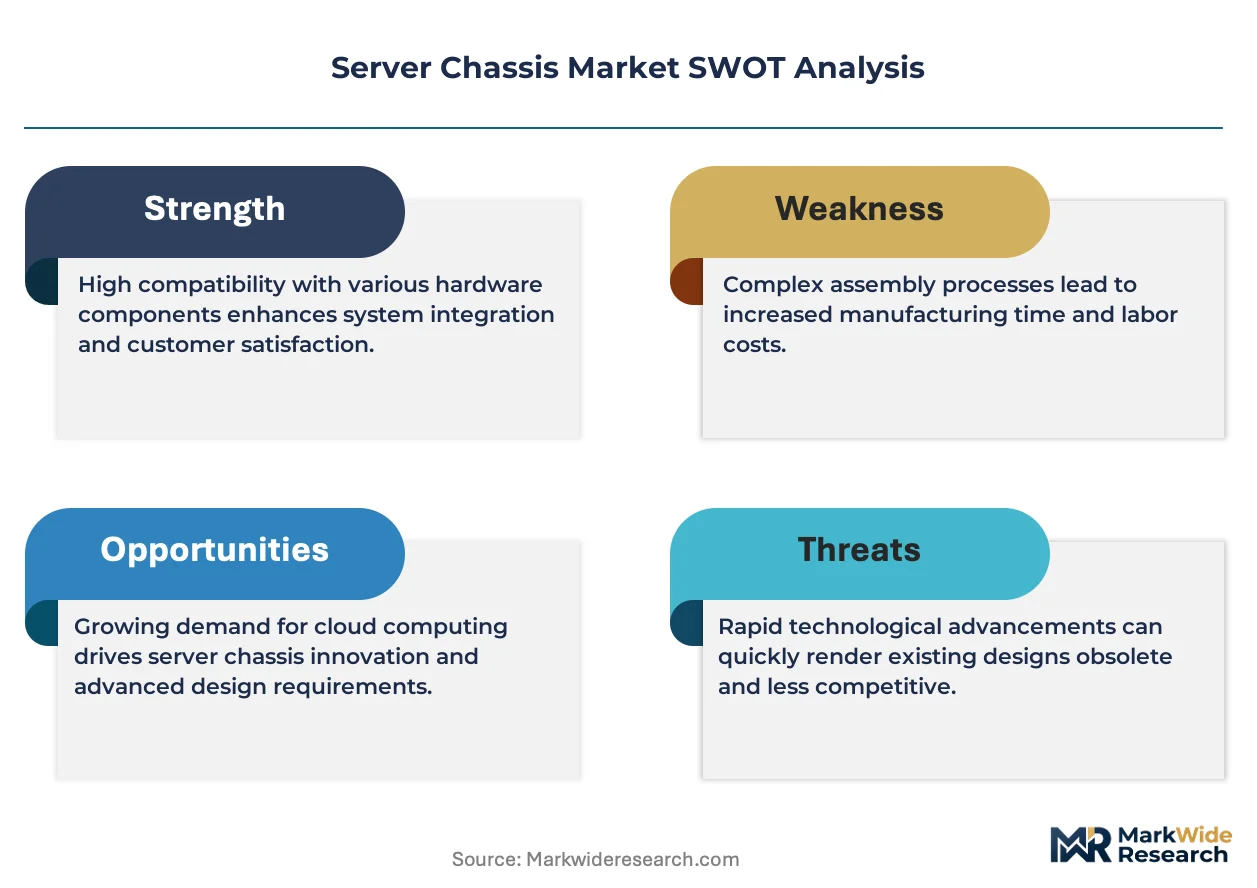
Custom chassis design for specialized workloads is tilting the margin pool away from standardized, high-volume manufacturing. Supermicro differentiates through its extensive portfolio of application-optimized server solutions. Hewlett-Packard Enterprise leverages its global supply chain and enterprise service contracts to secure large-scale deployments. Chenbro Micom competes on specialized manufacturing capabilities for original design manufacturer (ODM) clients.
A server chassis is a specialized metal enclosure designed to house and protect a server's internal components, including the motherboard, storage drives, and power supply units. These structures provide critical airflow for cooling, electromagnetic shielding, and structural support for mounting within data center racks. Rackmount chassis constitute the largest product segment, driven by density requirements in enterprise and cloud data centers. Within this category, 1U and 2U sizes represent the highest volume, while steel remains the dominant material due to its cost-to-strength ratio.
Regulatory compliance significantly influences material selection and design, with frameworks like the EU's RoHS directive restricting hazardous substances in electronics. In the United States, FCC Part 15 regulations impose strict limits on electromagnetic emissions, while China's GB standards govern product safety and performance. Suppliers must now navigate the engineering challenge of accommodating higher thermal design power within existing form factors while meeting stricter energy efficiency targets.
Market Dynamics
The central structural force shaping the server chassis market is the engineering imperative to manage escalating thermal loads from next-generation processors within standardized rackmount form factors. This challenge dictates material science, internal layout, and cooling system integration.
Growth Catalysts
- Hyperscale Data Center Construction:Sustained development of large-scale data centers, particularly in hubs like Northern Virginia and Texas, creates continuous, high-volume demand for rackmount server chassis to populate new server racks.
- AI Workload Proliferation:The expansion of artificial intelligence and machine learning applications requires specialized chassis capable of housing multiple high-power GPUs, driving demand for custom thermal and power-dense designs.
- Direct Liquid Cooling Adoption:The transition to direct liquid cooling (DLC) technologies to manage processor heat necessitates entirely new chassis designs with integrated manifolds, tubing, and quick-disconnect fittings.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the cost of steel and aluminum, the primary structural materials, directly impact manufacturing costs and compress supplier margins, especially on high-volume, standardized products.
- Legacy Infrastructure Inertia:The vast installed base of 19-inch rack infrastructure limits radical form factor innovation, forcing designers to engineer solutions within strict dimensional and power-connectivity constraints.
- ODM Manufacturing Concentration:Heavy reliance on a few original design manufacturers based in Taiwan and China for high-volume production creates significant supply chain vulnerability and geopolitical risk for global buyers.
Strategic Opportunities
- Modular and Composable Designs:Developing chassis based on modular principles allows for greater flexibility and scalability, appealing to enterprise customers seeking to future-proof their infrastructure and simplify component upgrades.
- Edge Computing Deployments:Growth in edge computing creates a new market for ruggedized, compact, and non-standard chassis designed for deployment in harsh or space-constrained environments outside traditional data centers.
- Circular Economy Initiatives:Designing chassis for disassembly and material reuse presents an opportunity to meet corporate sustainability goals and comply with upcoming regulations like the EU's CSRD, attracting environmentally conscious enterprise buyers.
Industry Challenges
- Fragmented Regulatory Compliance:Manufacturers face significant overhead in ensuring a single product line complies with disparate international standards, including the EU's RoHS directive, US FCC Part 15 emissions limits, and China's GB safety standards.
- Thermal and Power Density Limits:Engineers face the immense challenge of designing adequate airflow and power distribution to support components with rising thermal design power (TDP) within the fixed volume of 1U and 2U chassis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Server Chassis Market |
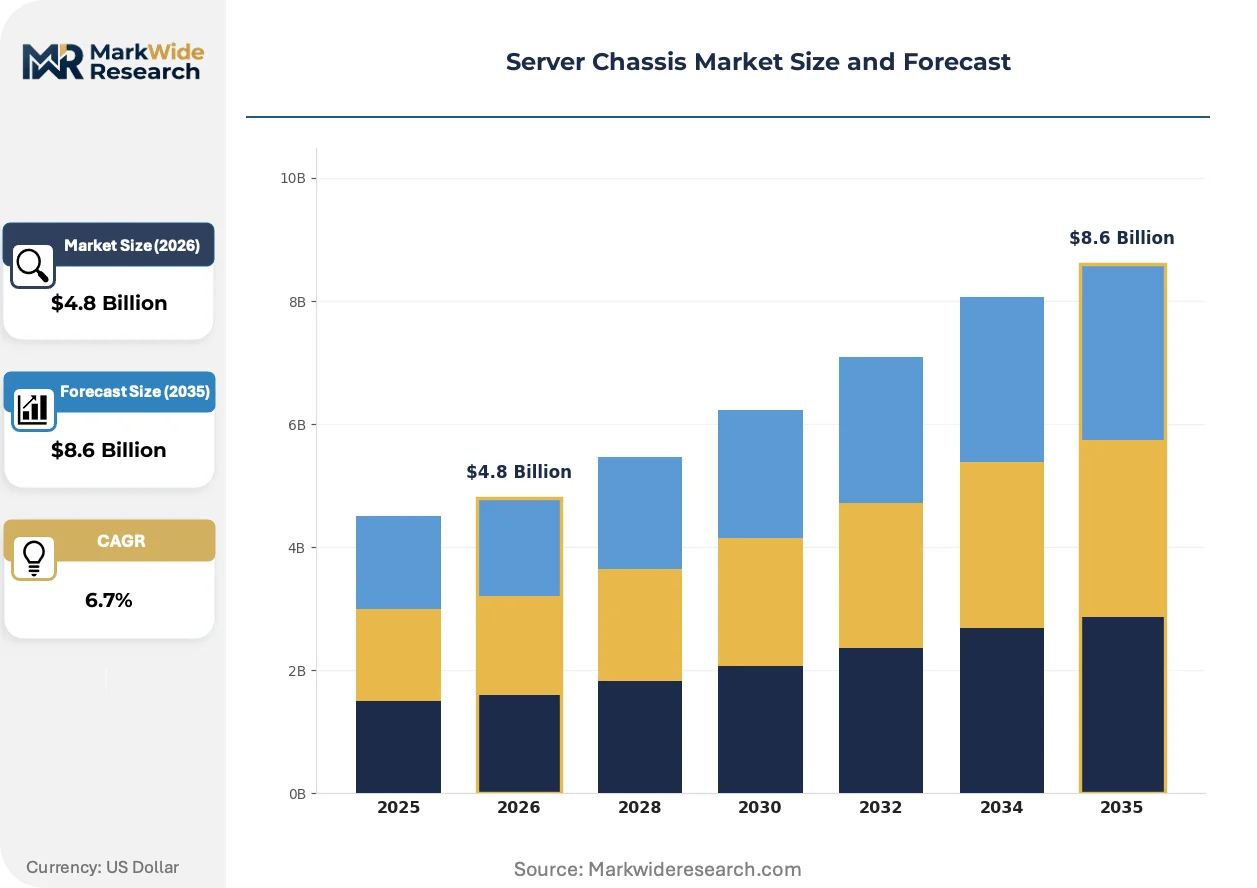
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rackmount Chassis, Tower Chassis, Blade Chassis, Modular Chassis Size: 1U, 2U, 3U, 4U Material: Aluminum, Steel, Plastic, Composite Power Rating: 500W, 750W, 1000W, 1200W |
| Companies Covered | Dell, Lenovo, Supermicro, In Win Development, Cisco Systems, Chenbro Micom, Hewlett-Packard Enterprise, iStarUSA, Advantech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Server Chassis Market Strategic Shifts & Innovations
The server chassis is evolving from a passive sheet metal enclosure into an active, engineered system integral to server performance and data center efficiency. This shift is driven by thermal necessity and the demand for greater operational intelligence at the hardware level.
Onboard sensing technology is a primary innovation area. Smart sensors and microcontrollers are now embedded directly into the chassis backplane and internal structure to monitor real-time thermal conditions, fan speeds, and power consumption. Hyperscale and large enterprise operators are the principal adopters, using the data for fleet-wide optimization. The integration of this onboard intelligence is digitizing the chassis from a static asset into a dynamic node within the data center infrastructure management fabric.
Regulatory frameworks focused on sustainability are reshaping design priorities. The European Union's Ecodesign for Sustainable Products Regulation (ESPR) is forcing manufacturers to consider the entire product lifecycle, including material sourcing, energy efficiency in use, and end-of-life recyclability. This directly impacts chassis sold into the EU market, promoting designs that utilize more recycled aluminum and steel and are engineered for easier disassembly and component separation.
Buyer behavior is moving away from standardized catalog purchases toward direct co-development, particularly at the hyperscale level. This model involves deep collaboration between cloud service providers and original design manufacturers (ODMs) to create custom chassis optimized for specific workloads and operational environments. This trend is most visible in the United States and China, where it effectively disintermediates traditional OEM channels for the market's largest-volume orders.
Server Chassis Market Segmentation
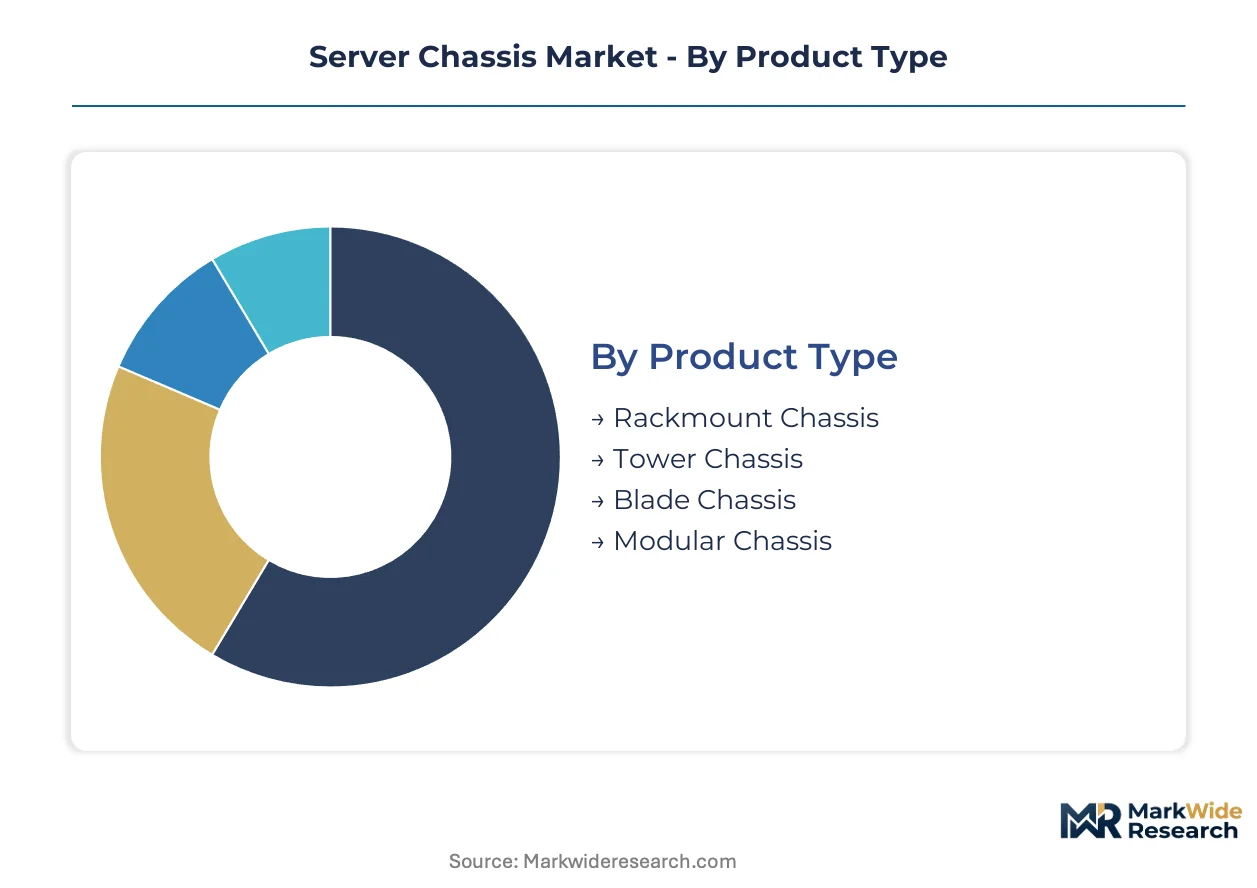
The server chassis market segments across several critical dimensions, each reflecting distinct operational demands and technological capabilities. Understanding these classifications is essential for manufacturers to tailor offerings and for data center operators to optimize infrastructure investments.
Product Type:
The product type segmentation reveals a market balancing mature, high-volume solutions with emerging, specialized designs.
- Rackmount Chassis:These standardized 19-inch form factors provide structural support and optimized airflow for servers within data center racks. Hyperscale data centers in the United States drive continuous demand for high-density rackmount solutions.
- Blade Chassis:These high-density modular systems integrate multiple server blades, power, and networking into a single shared enclosure. Enterprise customers seeking converged infrastructure solutions for virtualized environments increasingly adopt blade systems.
- Tower Chassis:Traditional freestanding enclosures house single servers, primarily used in small offices or for specialized workstation applications.
- Modular Chassis:These flexible designs allow for interchangeable components and hot-swappable modules, supporting diverse configurations for evolving compute requirements.
Rackmount Chassis handles the majority of throughput; Modular Chassis is the fastest mover on share.
Size:
Size categories reflect critical density requirements influencing server deployment volumes across various data center environments.
- 1U:These ultra-dense chassis occupy one rack unit, maximizing compute power within limited rack space for high-density deployments. Hyperscale cloud providers frequently deploy 1U servers to optimize data center footprint.
- 2U:Offering a balance of density and expandability, 2U chassis provide more internal space for cooling and additional components like GPUs or storage. Enterprise data centers in Europe prioritize 2U solutions for versatile workloads.
- 3U:These larger chassis accommodate more complex configurations, often used for storage servers or specialized compute nodes requiring greater volume.
- 4U:The largest standard rackmount size, 4U chassis support high-performance computing, multiple GPUs, or extensive internal storage capacity.
The 1U and 2U segments dominate deployment volumes, while the 4U category exhibits the steepest expansion trajectory for specialized applications.
Material:
Material selection for server chassis primarily differentiates across cost tiers and specific performance requirements.
- Steel:This material remains dominant due to its high strength-to-cost ratio and excellent inherent electromagnetic shielding properties. Large-scale data center builds in China rely heavily on steel chassis for cost-effective deployments.
- Aluminum:Lighter than steel, aluminum chassis offer superior thermal conductivity and corrosion resistance, suitable for specialized or higher-performance applications. Edge computing deployments often utilize aluminum for weight reduction and thermal management.
- Plastic:Limited to specific non-structural components or smaller, less demanding server applications, plastic offers cost savings and design flexibility.
- Composite:Advanced composite materials provide a balance of strength, weight, and thermal properties for high-end or custom chassis designs.
Steel chassis account for the largest proportion of shipments, with composite materials seeing increased uptake for niche, performance-driven solutions.
Power Rating:
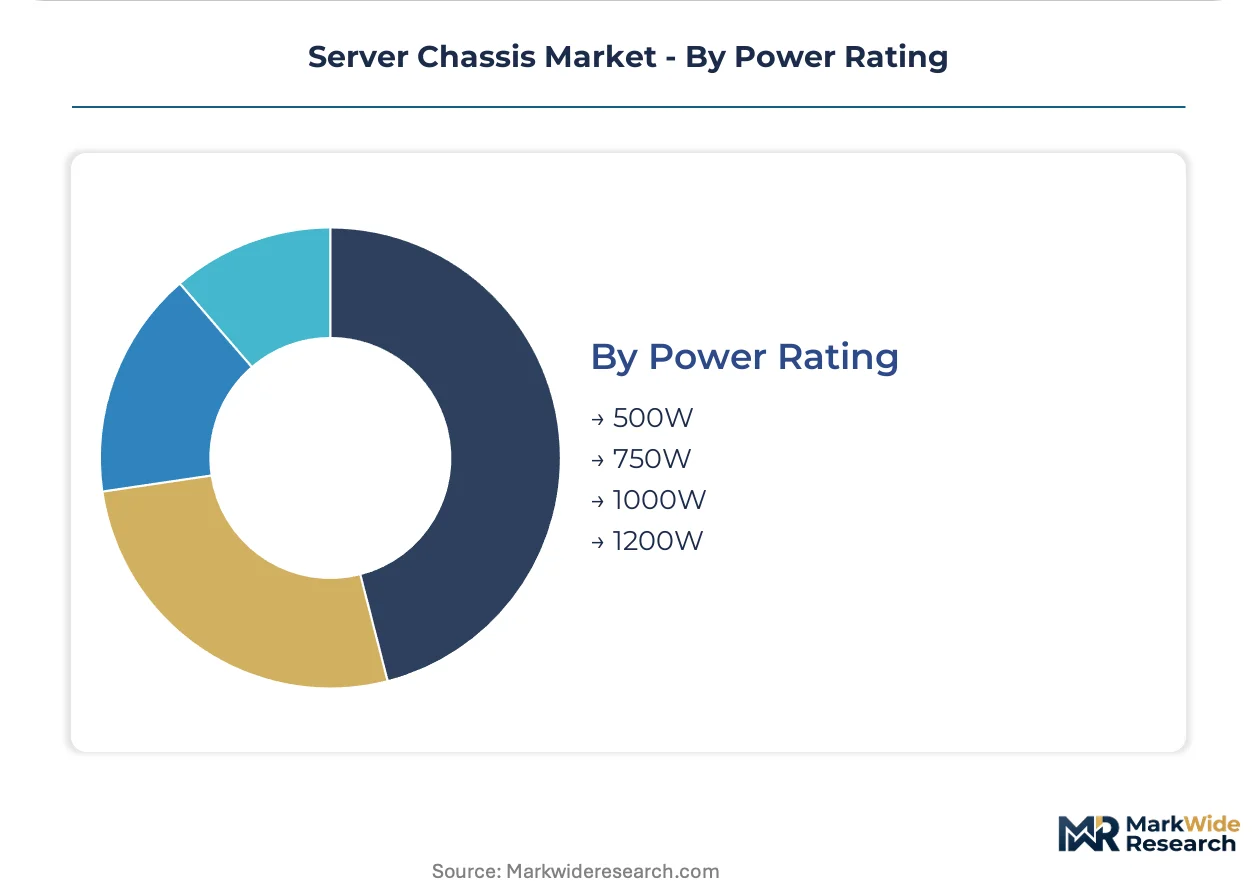
Power rating classifications directly correspond to the thermal design power of housed components and the intended application workload.
- 1000W:Chassis rated for 1000W support robust single-processor servers or configurations with moderate GPU acceleration requirements. General-purpose enterprise workloads frequently require this power level.
- 1200W:Designed for high-performance computing and AI workloads, 1200W chassis accommodate multiple powerful GPUs and advanced processors. Hyperscale AI clusters in the US mandate 1200W or higher power ratings.
- 500W:Lower power ratings are suitable for entry-level servers or network appliances with minimal computational demands.
- 750W:These chassis support mid-range server configurations, balancing performance with energy efficiency for various business applications.
Higher power ratings like 1200W are increasingly critical for advanced AI applications, while 500W and 750W remain foundational for standard server infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The server chassis market exhibits a significant concentration of manufacturing and procurement activities in specific geographies. This supply-side dynamic influences global pricing and product availability for data center infrastructure. Hyperscale data center growth and specialized workload demands drive regional market evolution across continents.
United States
Hyperscale data center construction and AI workload proliferation drive substantial demand for server chassis. FCC Part 15 regulations strictly govern electromagnetic emissions for electronic devices, impacting design. Northern Virginia and Texas remain primary hubs for new data center builds, driving continuous high-volume demand.
China
Large-scale domestic data center builds and cost-effective deployments for a vast market characterize the Chinese demand. China's GB standards stringently govern product safety and performance for server components. Major manufacturing and data center expansion occurs extensively in the Yangtze River Delta region.
Germany
Enterprise data centers prioritizing 2U solutions and stringent energy efficiency targets shape demand in Germany. The EU's Ecodesign for Sustainable Products Regulation (ESPR) significantly influences material sourcing and recyclability. Frankfurt continues as a major internet exchange point and a growing data center cluster in Europe.
Taiwan
High-volume original design manufacturer (ODM) manufacturing for global brands and specialized component production define Taiwan's role. Local industrial policies actively support the electronics manufacturing and export sector. Hsinchu Science Park serves as a key hub for advanced electronics and ODM operations, fostering innovation.
Server Chassis Market Key Industry Players
Value-added solution providers and high-volume original design manufacturers split the market for server chassis. The industry shows a tiered structure, with specialized players catering to custom needs and large-scale manufacturers dominating standardized products. Strategic partnerships and technology licensing represent dominant competitive moves among these diverse entities. Companies often pursue portfolio diversification to address evolving thermal management challenges.
Among the established players, Supermicro exemplifies a focus on extensive application-optimized server solutions, catering to specialized performance needs. Hewlett-Packard Enterprise leverages its robust global supply chain and established enterprise service contracts, anchoring the large-scale deployment segment. Chenbro Micom, a Taiwan-based company, sits within the specialized manufacturing archetype, competing on capabilities for original design manufacturer clients. These entities collectively represent diverse strategic approaches to serving the varied demands within the global server chassis market.
| Leading Market Players |
|---|
| Dell |
| Lenovo |
| Supermicro |
| In Win Development |
| Cisco Systems |
| Chenbro Micom |
| Hewlett-Packard Enterprise |
| iStarUSA |
| Advantech |
| Others |
Cost & Logistics Intelligence
Northern Virginia's data center capacity utilization drives supplier behavior, influencing pricing postures for high-volume rackmount chassis. This regional concentration of demand creates specific dynamics in procurement and manufacturing.
Pricing Analysis
After-sales service contracts for server chassis solutions drive significant lifetime value for enterprise customers. The dominant pricing model is transactional per-unit, often bundled with long-term service agreements for large deployments. Customization levels and volume scale differentiate prices. Pricing softness stems from intense competition among high-volume manufacturers, making hyperscale operators highly price-sensitive.
Supply Chain Analysis
Upstream feedstock availability for steel and aluminum directly impacts server chassis manufacturing costs. Supply concentration for high-volume production centers in China and Taiwan. Raw material price volatility presents a structural risk for suppliers. The distribution model primarily runs through direct sales channels to large data centers and through OEM partners to smaller enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The server chassis market presents a defensive-moat story for established players, largely due to high switching costs associated with integrating new chassis designs into existing data center infrastructure. This structural advantage protects incumbent market positions.
For Market Incumbents: Harden existing relationships with hyperscale clients through co-development initiatives. Invest in R&D for advanced thermal management to counter escalating processor thermal design power. Strategic partnerships with direct liquid cooling technology providers expand portfolio capabilities. Optimize global supply chains to mitigate raw material price volatility.
For New Entrants and Emerging Players: Geographic underpenetration in emerging edge computing markets offers significant white-space opportunities. Target ruggedized, compact chassis designs for harsh environments outside traditional data centers. Focus on modular and composable designs to appeal to enterprises. A go-to-market angle emphasizing rapid customization can differentiate offerings.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the specialized server chassis segment, driven by advanced material science. Long-term viability rests on companies delivering high-performance, application-optimized solutions for AI workloads. Acquisition targets should include vertically integrated mid-cap specialists with strong intellectual property in thermal management. The signal to watch is direct liquid cooling adoption in new data center builds.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Modular Chassis | This initiative offers greater flexibility and scalability, attracting enterprise customers seeking adaptable infrastructure solutions. |
| Strategic Partnership: Direct Liquid Cooling Integration | Collaborating on DLC technologies addresses escalating thermal loads from next-generation processors, enhancing product performance. |
| Capacity Expansion: US Manufacturing | Expanding production in the United States mitigates geopolitical supply chain risks and serves growing regional demand. |
| Certification Investment: EU Ecodesign Compliance | Achieving compliance with ESPR regulations opens access to the European market and meets corporate sustainability goals. |
| Supply Chain Optimization: Raw Material Sourcing | Improving sourcing strategies for steel and aluminum reduces cost volatility and strengthens margin stability. |
Research Approach
Operator-level perspectives from data center architects, IT procurement officers, ODM engineers, and enterprise infrastructure managers anchored the qualitative base. This analysis combined primary interviews with rigorous secondary validation. Secondary data sources included regulatory filings (FCC, EU ESPR), industry association reports, and technical specifications. Bottom-up and top-down triangulation ensured data integrity and market sizing accuracy.
Scenario-bracketing frameworks were employed to account for varying technology adoption rates and data center investment cycles. The analytical framework projected market evolution across the analysis window. Segmentation dimensions modeled included product type, size, material, power rating, and regional deployment patterns. Hyperscale data center expansion and AI workload growth served as key forecast inputs.
Practitioners should monitor geopolitical shifts impacting raw material supply and rapid advancements in processor architecture for early signals. Forecasts reflect assumptions regarding current technological trajectories and regulatory environments. Material shifts in global economic conditions or major regulatory changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IT Hardware
Global IT Hardware Market
IT Hardware
Single Board Computer Market
IT Hardware
Tablet PC Market
IT Hardware
India IT Hardware Market
IT Hardware
Middle East and Africa IT Device Market
IT Hardware
USB 3.0 Market
IT Hardware
Industrial Motherboards Market
IT Hardware
Global 4K Set Top Box (STB) Market
IT Hardware
PC Case Market
IT Hardware
Asia Pacific IT Device Market
IT Hardware
Three-Proof Laptop Market
IT Hardware
Europe IT Device Market
IT Hardware
Cloud IT Infrastructure Hardware Market