
 Tablet PC Market | 2026-2036
Tablet PC Market Size, Share, and Industry Trends Forecast 2026-2036
Tablet PC Market Analysis
Market Dynamics
Direct-to-enterprise distribution is fragmenting as original equipment manufacturers bypass traditional retail channels to serve vertical buyers directly. Lenovo Group Limited leverages its ThinkPad heritage to dominate commercial procurement pipelines for field-service deployments. Samsung Electronics Co Ltd anchors consumer mindshare through retail partnerships while extending Galaxy Tab portfolios into education tenders. Getac Technology Corporation specializes in MIL-STD-810G-certified rugged units for military and industrial applications where durability commands premium positioning.
Product Architecture and Segment Structure
A tablet PC is a portable computing device featuring a touchscreen interface as the primary input mechanism, typically incorporating ARM or x86 processors, solid-state storage between 64 GB and 1 TB, and lithium-polymer batteries engineered for 8-14 hour active use cycles. The device serves commercial, educational, and consumer markets requiring mobile access to cloud-native applications, digital content creation, and field data capture. Slate form factors lead unit shipments due to lower bill-of-materials costs and thinner profiles that appeal to mass-market buyers. Rugged tablets represent the fastest-growing product category as construction, logistics, and public safety agencies replace aging notebook fleets with drop-resistant, weather-sealed alternatives. Windows operating system deployments concentrate in enterprise and healthcare segments where legacy application compatibility and Active Directory integration justify higher per-unit expenditure.
Regulatory Environment and Strategic Outlook
The EU Ecodesign for Sustainable Products Regulation and REACH chemical restrictions are reshaping supply chain compliance costs for display assemblies and battery chemistries sold across European member states. The US FCC equipment authorization process and California's SB 244 right-to-repair legislation are extending product lifecycle obligations and influencing modular design priorities among original design manufacturers. India's BIS certification mandates and PLI scheme incentives for electronics manufacturing are redirecting assembly capacity toward domestic production hubs. Stakeholders must monitor how divergent repairability, recyclability, and energy efficiency standards across the US, Europe, and India fragment compliance architectures and reshape total cost of ownership calculations for fleet buyers.
Market Dynamics
Enterprise digitization of clinical workflows and field-service operations is fragmenting distribution channels, as OEMs bypass retail to serve vertical buyers directly through certified partner networks and direct sales organizations.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Electronics manufacturers face tightening material disclosure mandates for display assemblies and battery chemistries, accelerating modular design investments that extend product lifecycles and create aftermarket service revenue streams.
- Healthcare digitization:Hospital systems and ambulatory clinics deploy tablet fleets for bedside documentation, medication administration verification, and telehealth endpoints, replacing clipboard-and-paper workflows with HIPAA-compliant mobile infrastructure.
- India's PLI scheme:Production-linked incentives for electronics manufacturing redirect assembly capacity toward domestic hubs, lowering landed costs for education and SMB segments through localized supply chains.
Market Restraints
- Lithium-polymer supply concentration:Battery cell production clusters in East Asian manufacturing centers expose OEMs to shipping disruptions and raw material price volatility that compress gross margins on thin-profile consumer slates.
- REACH chemical restrictions:European substance limitations on flame retardants and plasticizers force reformulation of enclosure materials, extending qualification timelines and raising compliance costs for products sold across member states.
- Smartphone substitution:Large-format handsets with stylus support capture casual content consumption and light annotation tasks, narrowing the addressable market for entry-level tablets below ten-inch diagonal displays.
Strategic Opportunities
- Ruggedized application expansion:Construction, logistics, and public safety agencies replace aging notebook fleets with MIL-STD-810G-certified tablets, creating premium positioning for drop-resistant, weather-sealed alternatives with hot-swappable batteries.
- India ed-tech infrastructure:Government digital classroom initiatives and state-level tablet distribution programs expand addressable volume in K-12 segments, favoring OEMs with localized assembly and Hindi-language software partnerships.
- Windows-Android convergence:Dual-boot and virtualization architectures enable enterprise IT departments to consolidate device fleets, serving legacy Active Directory-dependent applications alongside modern cloud-native tools on single hardware platforms.
Industry Challenges
- Right-to-repair compliance fragmentation:California's SB 244 mandates modular component access and repair documentation, while EU battery passport requirements impose divergent serialization and traceability obligations that complicate global SKU strategies.
- Active Directory integration complexity:Enterprise buyers demand seamless certificate-based authentication and Group Policy enforcement, requiring OEMs to maintain specialized engineering teams for Windows firmware validation and security patch certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tablet PC Market |
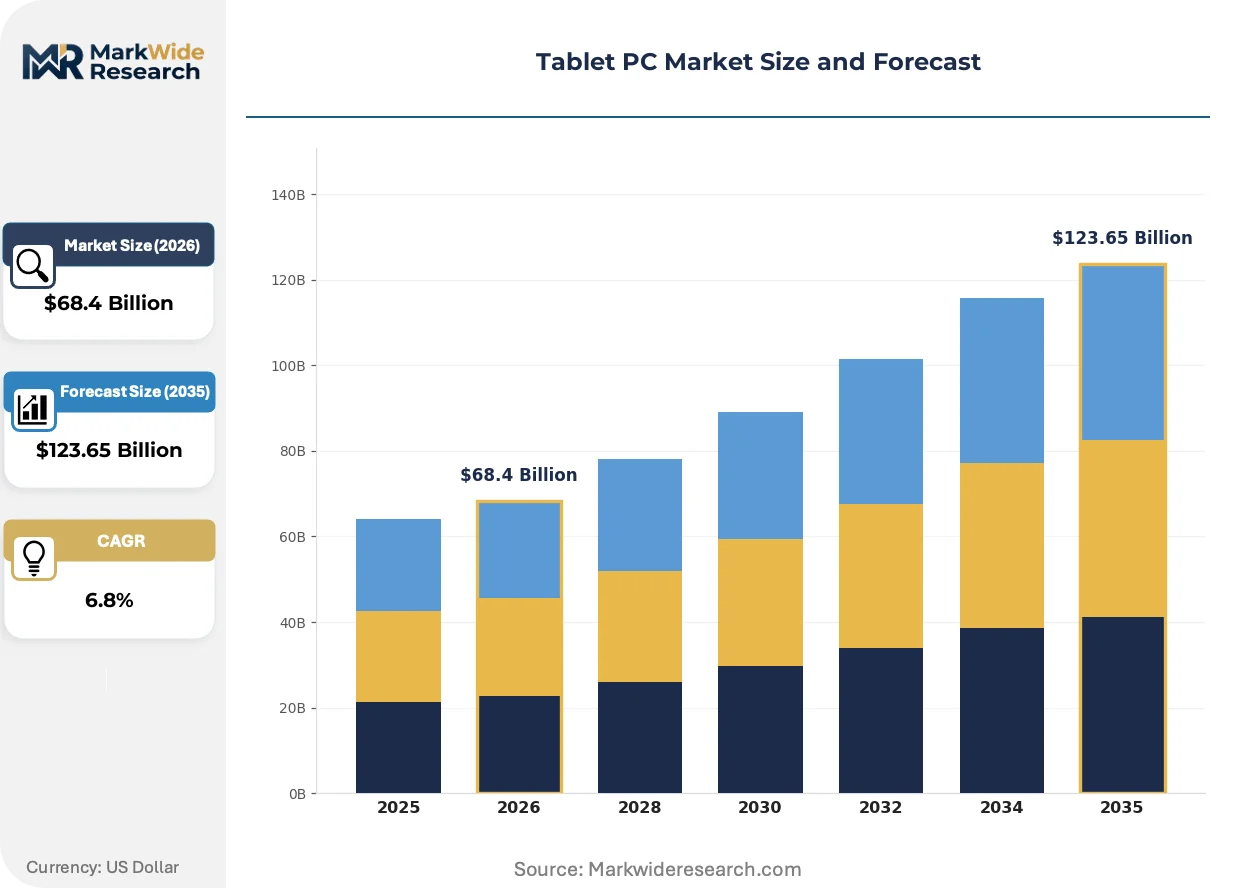
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convertible, Slate, Rugged, Hybrid Operating System: Android, iOS, Windows, Chrome OS Display Technology: LCD, OLED, IPS, AMOLED Market Segment: Education, Business, Entertainment, Healthcare |
| Companies Covered | Lenovo Group Limited, Getac Technology Corporation, Samsung Electronics Co Ltd, General Dynamics Corporation, Zebra Technologies Corporation, Dell Technologies, Panasonic Corporation, Honeywell International Inc, Advantech Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tablet PC Market Emerging Trajectories
Touchscreen interface architectures and compute form factors are converging toward virtualization-ready endpoints that decouple local processing from cloud-dependent workflows, reshaping hardware specification priorities across commercial buyer segments.
ARM-based system-on-chip designs with integrated neural processing units are virtualizing legacy x86 application workloads through emulation layers and containerized delivery. Healthcare IT departments pilot these configurations for clinical documentation terminals, compressing per-unit hardware expenditure while maintaining compatibility with electronic health record systems. The technology is virtualizing the traditional tradeoff between battery endurance and software ecosystem breadth.
REACH chemical restrictions and the EU Ecodesign for Sustainable Products Regulation mandate granular material disclosure and recyclability quotas for electronics sold across European member states. OEMs reconfigure supply chains to source halogen-free substrates and establish reverse-logistics partnerships for end-of-life collection. Display assembly suppliers face the steepest compliance cost escalation, accelerating consolidation among panel manufacturers with in-house recycling capabilities.
Enterprise procurement teams unbundle hardware acquisition from lifecycle management services, negotiating multi-year device-as-a-service contracts that include warranty extensions, accidental damage coverage, and certified data destruction. Field-service and logistics verticals in North America and Western Europe lead this transition, replacing capital expenditure approvals with predictable operational budgets. Channel partners respond by building managed deployment capabilities and helpdesk integrations that displace traditional reseller markups.
Tablet PC Market Segmentation
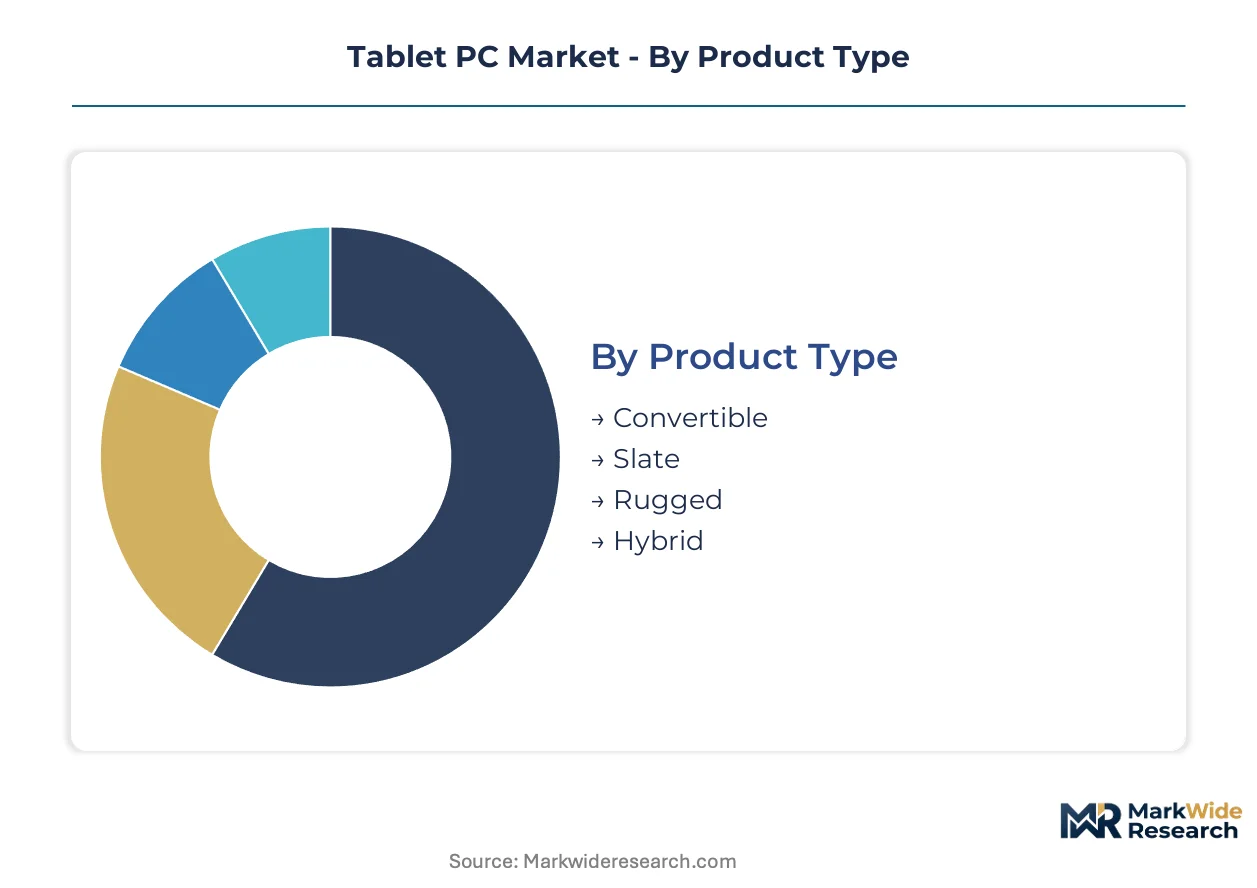
Tablet PC segmentation reveals how hardware architecture, software ecosystems, and end-use requirements fragment procurement patterns across enterprise and consumer buyers. Understanding these dimensions clarifies why slate form factors dominate unit economics while rugged variants capture premium margins in vertical deployments.
Product Type:
Use-case spectrum spans casual content consumption through mission-critical field operations, with form factor durability and input flexibility determining addressable application scope.
- Slate:Thin-profile touchscreen devices without integrated keyboards utilize ARM-based chipsets and sealed lithium-polymer cells to achieve sub-7mm chassis depths. Mass-market buyers in education and entertainment segments prioritize these units for their lower bill-of-materials costs and portability.
- Rugged:MIL-STD-810G-certified enclosures incorporate shock-mounted displays, chemically strengthened glass, and ingress protection sealing for exposure to dust, moisture, and temperature extremes. Construction firms and public safety agencies in Germany and Australia are replacing aging notebook fleets with these drop-resistant alternatives featuring hot-swappable batteries.
- Convertible:Hinge-attached keyboards enable laptop-mode productivity while maintaining tablet portability for annotation tasks.
- Hybrid:Detachable keyboard docks separate compute modules from input accessories, allowing pure slate use when weight minimization matters.
Established volume favors Slate; emerging adoption favors Rugged.
Operating System:
Software licensing economics and legacy application compatibility create distinct procurement tiers that reshape hardware specification priorities across buyer categories.
- Windows:Enterprise and healthcare segments concentrate procurement here, where Active Directory integration, Group Policy enforcement, and x86 legacy application support justify per-unit premiums. Hospital systems deploying bedside documentation terminals require certificate-based authentication that Android and iOS cannot replicate.
- Android:Open-source licensing and ARM-optimized performance drive adoption in education tenders and emerging-market consumer segments where cost minimization dominates.
- iOS:Apple's vertical integration of silicon, software, and services captures creative professionals and premium consumer buyers seeking stylus precision and ecosystem continuity.
- Chrome OS:Cloud-native architecture and centralized fleet management appeal to K-12 institutions with limited IT staffing and browser-dependent curricula.
Enterprise compliance requirements elevate Windows; price-sensitive volume flows to Android.
Display Technology:
Panel chemistry and subpixel architecture determine color accuracy, power consumption, and outdoor readability—specifications that diverge sharply between entertainment and industrial use cases.
- LCD:Mature thin-film transistor manufacturing achieves lowest unit costs for education and entry-level consumer shipments. India's state-level tablet distribution programs specify LCD panels to maximize device counts within fixed procurement budgets.
- OLED:Self-emitting organic compounds eliminate backlight layers, enabling flexible form factors and perfect black levels for premium entertainment and design applications.
- IPS:In-plane switching maintains color fidelity at wide viewing angles, suiting collaborative workflows in conference rooms and clinical settings.
- AMOLED:Active-matrix addressing enables faster refresh rates and always-on display features for stylus-intensive creative workloads.
Cost-optimized tenders default to LCD; premium positioning requires OLED or AMOLED.
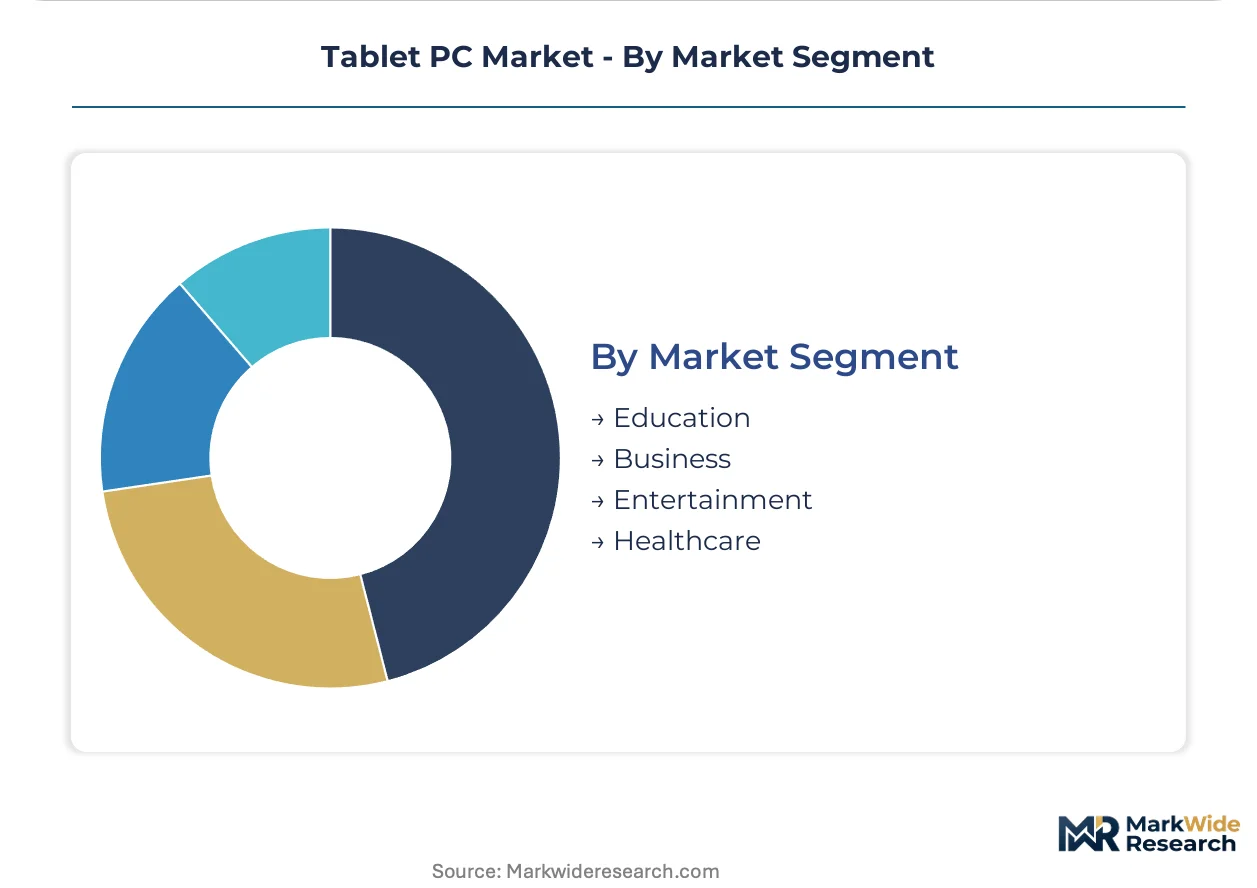
Market Segment:
End-use environment dictates durability specifications, security certifications, and software integration depth, fragmenting vendor go-to-market strategies across verticals.
- Healthcare:HIPAA-compliant mobile infrastructure for bedside documentation, medication administration verification, and telehealth endpoints requires antimicrobial enclosures and IEC 60601-1-2 electromagnetic compatibility certification. Hospital systems in the United States and Germany are replacing clipboard-and-paper workflows with sealed, disinfectable tablet fleets.
- Business:Field-service digitization and logistics fleet management drive demand for ruggedized units with barcode scanning integration and cellular connectivity.
- Education:Government digital classroom initiatives in India expand addressable volume through localized assembly requirements and Hindi-language software partnerships.
- Entertainment:Streaming-optimized specifications prioritize display quality and audio output over durability or enterprise manageability.
Procurement scale concentrates in Education; margin capture concentrates in Healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in Germany command 40-50% premiums over Indian education tenders for comparable hardware specifications, reflecting divergent compliance burdens and service bundling expectations across procurement contexts.
United States
Hospital systems in Texas and California deploy HIPAA-compliant tablet fleets for bedside documentation and telehealth endpoints, replacing clipboard workflows with sealed, disinfectable devices. FCC equipment authorization processes and California SB 244 right-to-repair mandates extend product lifecycle obligations and modular design priorities. Austin and San Diego clusters host field-service digitization pilots where logistics agencies test MIL-STD-certified units with barcode scanning integration.
Germany
Construction firms and public safety agencies in Bavaria and North Rhine-Westphalia replace aging notebook fleets with rugged tablets featuring hot-swappable batteries and ingress protection sealing. REACH chemical restrictions and EU Ecodesign for Sustainable Products Regulation impose granular material disclosure mandates for display assemblies and battery chemistries. Stuttgart's industrial automation corridor anchors demand for Windows-based fleet management terminals with Active Directory integration.
India
State-level tablet distribution programs in Maharashtra and Karnataka expand K-12 addressable volume through government digital classroom initiatives and Hindi-language software partnerships. BIS certification mandates and PLI scheme incentives for electronics manufacturing redirect assembly capacity toward domestic production hubs in Tamil Nadu and Telangana. SMB digitization in Gujarat accelerates demand for cost-optimized Android slates with localized supply chains.
China
Yangtze River Delta manufacturing centers concentrate lithium-polymer battery cell production, exposing OEMs to shipping disruptions and raw material price volatility that compress margins on thin-profile consumer slates. MIIT equipment certification and dual carbon goals reshape enclosure material sourcing toward halogen-free substrates. Shenzhen's display assembly suppliers face consolidation pressure as recyclability quotas accelerate vertical integration among panel manufacturers with in-house recovery capabilities.
Japan
Tokyo and Osaka healthcare networks pilot ARM-based clinical documentation terminals with integrated neural processing units, virtualizing legacy x86 workloads through emulation layers. METI standards and JIS certification requirements maintain stringent electromagnetic compatibility thresholds for medical device deployments. Kansai manufacturing clusters specialize in high-durability components for enterprise fleet refresh cycles.
Tablet PC Market Vendor Landscape
Enterprise-focused OEMs and consumer electronics conglomerates split the market along software ecosystem and distribution channel lines. Consolidation concentrates around five to seven vertically integrated players with captive silicon or display supply. Three archetypes dominate: heritage PC manufacturers leveraging ThinkPad-era commercial relationships, Korean conglomerates anchoring retail mindshare through Galaxy portfolios, and Taiwanese rugged specialists certifying MIL-STD units for military procurement. Competitive moves center on direct-to-enterprise distribution bypasses and modular design investments that satisfy divergent right-to-repair mandates.
Within the enterprise-tier, Lenovo Group Limited and Dell Technologies occupy positions anchored by decades of commercial procurement relationships and Active Directory integration capabilities. Samsung Electronics Co Ltd exemplifies the consumer-to-commercial crossover archetype, bridging retail partnerships with education tender participation. Getac Technology Corporation and Zebra Technologies Corporation sit within the rugged specialization tier, where MIL-STD-810G certification and hot-swappable battery architectures command premium positioning in construction and logistics verticals. Panasonic Corporation and Honeywell International Inc represent diversified industrial conglomerates with embedded computing divisions serving field-service digitization requirements.
| Leading Market Players |
|---|
| Lenovo Group Limited |
| Getac Technology Corporation |
| Samsung Electronics Co Ltd |
| General Dynamics Corporation |
| Zebra Technologies Corporation |
| Dell Technologies |
| Panasonic Corporation |
| Honeywell International Inc |
| Advantech Co Ltd |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta display assembly clusters anchor global panel capacity, concentrating procurement leverage among vertically integrated manufacturers and compressing margins for downstream OEMs sourcing thin-film transistor substrates. This geographic concentration amplifies pricing power for panel suppliers while exposing tablet assemblers to lithium-polymer cell volatility and REACH-compliant substrate qualification delays.
Pricing Analysis
Configured-to-order enterprise tablets command 35-60% premiums over standard consumer slates, with Windows-Active Directory integration and MIL-STD-810G certification driving the spread. Three-tier pricing structure across premium rugged, standard commercial, and economy education levels reflects durability grade and software ecosystem bundling. Cost compression in entry-level ARM-based slates intensifies because India's PLI scheme incentivizes localized assembly, while healthcare buyers exhibit lowest price sensitivity due to HIPAA compliance requirements and lifecycle service dependencies.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations, prompting OEMs to diversify final assembly toward Vietnam and India. Lithium-polymer cell production draws from China, South Korea, and Japan, with display substrates and ARM-based system-on-chip designs resting on East Asian semiconductor fabrication. Single-source vulnerability in OLED panel supply concentrates procurement leverage among Korean and Chinese panel manufacturers. Distribution runs through direct-to-enterprise channels for vertical buyers and retail partnerships for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tablet PC procurement is shifting toward platform-economics logic as Windows-Android virtualization architectures enable single-device consolidation of legacy and cloud-native workflows. This interoperability inflection rewards OEMs with software ecosystem breadth and modular hardware roadmaps.
For Market Incumbents: Entrench enterprise relationships through device-as-a-service contract structures that bundle hardware, warranty extensions, and certified data destruction. Deepen Active Directory integration capabilities to defend against ARM-based virtualization entrants. Prioritize modular design investments that satisfy California SB 244 and EU battery passport requirements simultaneously.
For New Entrants and Emerging Players: Pursue ruggedized field-service deployments in Germany and Australia where aging notebook replacement cycles create white-space opportunity. Target India's state-level education tenders through Hindi-language software partnerships and Tamil Nadu assembly partnerships. Lead with barcode scanning integration and hot-swappable battery architectures as differentiated entry angles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors rugged-specialist OEMs with MIL-STD certification capabilities and enterprise service infrastructure. Long-term viability hinges on compliance architecture scalability across divergent right-to-repair mandates. Watch ARM-based emulation performance benchmarks as the signal indicating virtualization adoption inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Design Investment | California SB 244 and EU battery passport requirements force component accessibility redesigns. |
| Device-as-a-Service Launch | Enterprise procurement teams in North America unbundle hardware from lifecycle management services. |
| ARM Emulation Development | Healthcare IT pilots in Japan validate neural processing unit virtualization of legacy x86 workloads. |
| Localized Assembly Expansion | India's PLI scheme redirects capacity toward Tamil Nadu and Telangana production hubs. |
| Rugged Certification Pipeline | MIL-STD-810G certification unlocks premium positioning in German construction and logistics verticals. |
Methodological Framework
Operator-level perspectives from OEM product managers, enterprise IT procurement officers, healthcare biomedical engineers, and education technology coordinators anchored the qualitative base. Primary interviews triangulated against secondary validation from FCC equipment authorization databases, BIS certification registries, EU Ecodesign implementation guidance, and hyperscaler education tender disclosures. Bottom-up shipment modeling and top-down value estimation converged across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling segmentation dimensions including form factor durability tier, operating system ecosystem, display technology chemistry, and end-use vertical compliance requirements. CAGRs derived from shipment elasticity analysis against ed-tech infrastructure spend and enterprise digitization budgets. Forecast inputs incorporated PLI scheme capacity buildout timelines and REACH chemical restriction phase-in schedules.
Macroeconomic conditions sit as an overlay; deviation in lithium raw material prices, East Asian shipping rates, or electronics consumer confidence indices would shift the trajectory. Forecasts reflect documented assumptions about virtualization adoption curves and regulatory compliance cost pass-through. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IT Hardware
Middle East and Africa IT Device Market
IT Hardware
Europe IT Device Market
IT Hardware
India IT Hardware Market
IT Hardware
Industrial Motherboards Market
IT Hardware
Global IT Hardware Market
IT Hardware
PC Case Market
IT Hardware
Asia Pacific IT Device Market
IT Hardware
USB 3.0 Market
IT Hardware
Single Board Computer Market
IT Hardware
Cloud IT Infrastructure Hardware Market
IT Hardware
Server Chassis Market
IT Hardware
Three-Proof Laptop Market
IT Hardware
Global 4K Set Top Box (STB) Market