
 Global IT Hardware Market | 2026-2036
Global IT Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Global IT Hardware Market Outlook
Modular server configurations is shifting buyer choice toward disaggregated compute, memory, and storage units that enterprises can upgrade independently. Dell Technologies Inc. leverages its supply chain scale to dominate enterprise rack deployments across North America and Europe. Lenovo Group anchors its competitive stance through in-house manufacturing of high-density server platforms for cloud providers.
Global IT hardware encompasses physical computing equipment including servers, workstations, desktops, and laptops, typically specified by processor architecture, thermal design power, memory bandwidth, and form factor standards, manufactured through precision SMT assembly and burn-in testing to deliver reliable data processing and enterprise productivity. Servers command the largest revenue pool as hyperscalers prioritize AI training clusters with accelerator-rich configurations, while edge computing infrastructure represents the fastest expansion trajectory as latency-sensitive applications migrate processing closer to data sources. Laptops maintain mature volume scale across corporate refresh cycles, though margin compression persists in entry-level consumer tiers.
The U.S. Environmental Protection Agency Energy Star program and the EU Ecodesign Directive impose escalating efficiency thresholds on server power supplies and standby consumption, forcing OEMs to redesign thermal architectures and component selection. China's MIIT issues mandatory GB standards for data center power usage effectiveness that shape domestic procurement specifications. India's BIS certification requirements for IT equipment create compliance gates for imported hardware. Stakeholders must monitor divergence between regional efficiency mandates and the energy intensity of next-generation AI accelerators to avoid stranded inventory or certification gaps.
Market Dynamics
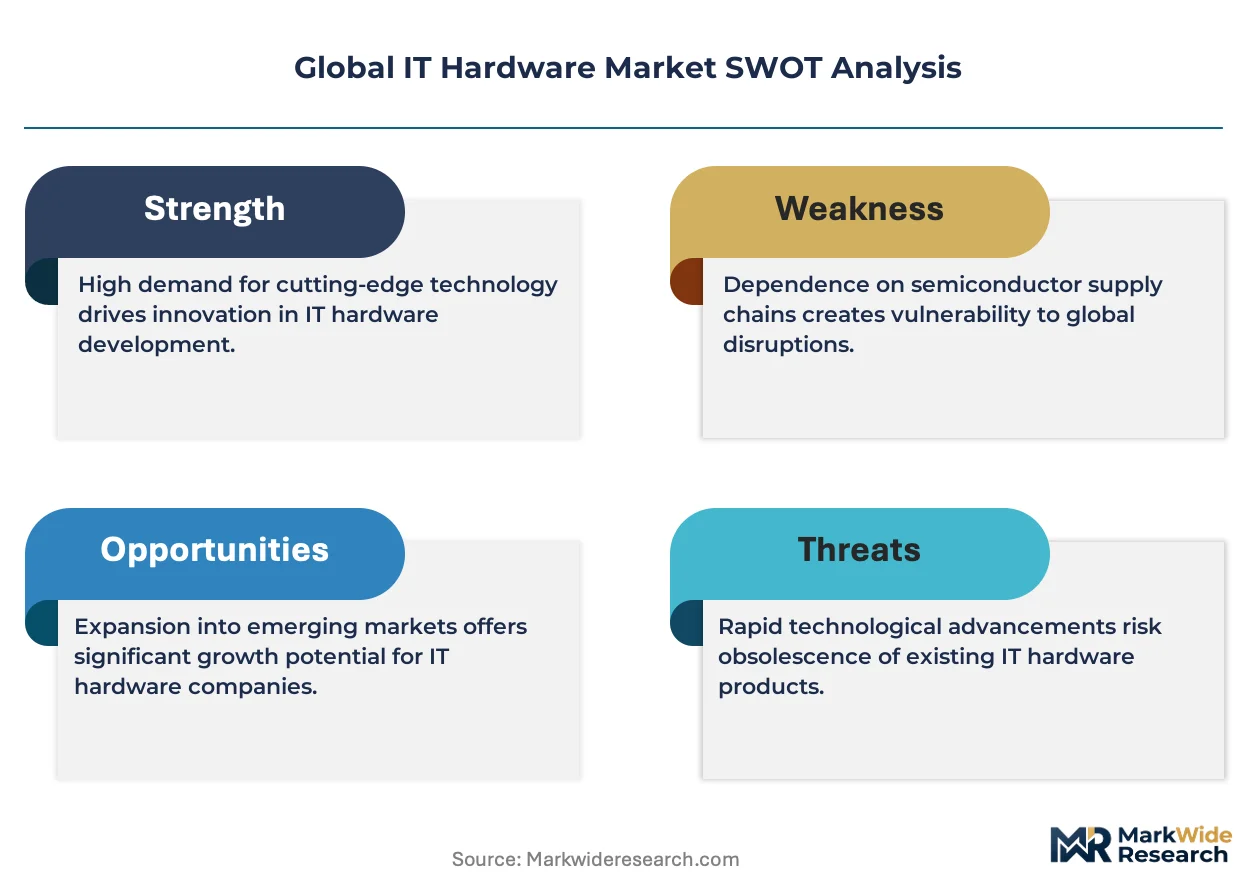
Hyperscaler procurement concentration is compressing server OEM margins while forcing rapid thermal architecture redesigns to accommodate accelerator power densities exceeding 700W per socket.
Growth Catalysts
- EU AI Act compliance mandates:European data center operators must retrofit infrastructure for algorithmic transparency and energy reporting, triggering replacement cycles for legacy server fleets.
- Generative AI training clusters:Cloud providers in the United States are commissioning GPU-dense configurations that prioritize memory bandwidth and liquid cooling over traditional air-cooled rack designs.
- India's PLI scheme for IT hardware:Domestic manufacturing incentives are attracting component assembly operations to Tamil Nadu and Karnataka, reducing import dependency for enterprise laptops and servers.
Market Restraints
- High-bandwidth memory supply concentration:Three Korean and Taiwanese suppliers control advanced HBM3E output, creating allocation bottlenecks for AI server builds.
- China's GB 40879 efficiency standards:Domestic data center PUE ceilings below 1.3 disqualify air-cooled designs from state-owned enterprise procurement lists.
- Silicon carbide substrate scarcity:Power supply manufacturers face 40-week lead times for high-efficiency MOSFET substrates essential to 80 PLUS Titanium certification.
Strategic Opportunities
- Saudi Arabia's NEOM giga-project:The linear city's data center zone requires modular, renewable-powered server infrastructure with liquid cooling integration from ground-up construction.
- Edge AI inference appliances:Manufacturing floors in Germany are deploying compact GPU servers for real-time defect detection, bypassing cloud latency for sub-10ms response requirements.
- Japan's METI Green Transformation bonds:Subsidized financing for energy-efficient IT equipment is accelerating corporate refresh cycles beyond typical five-year depreciation schedules.
Industry Challenges
- Liquid cooling plumbing certification:Immersion and direct-to-chip systems lack unified IEC safety standards, forcing OEMs to pursue redundant country-specific approvals.
- Firmware supply chain integrity:Baseboard management controller vulnerabilities require cryptographic signing infrastructure that most contract manufacturers have not yet deployed.
- Accelerator-to-server form factor mismatch:NVIDIA's proprietary SXM sockets and AMD's OAM modules demand incompatible motherboard layouts, fragmenting inventory pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IT Hardware Market |
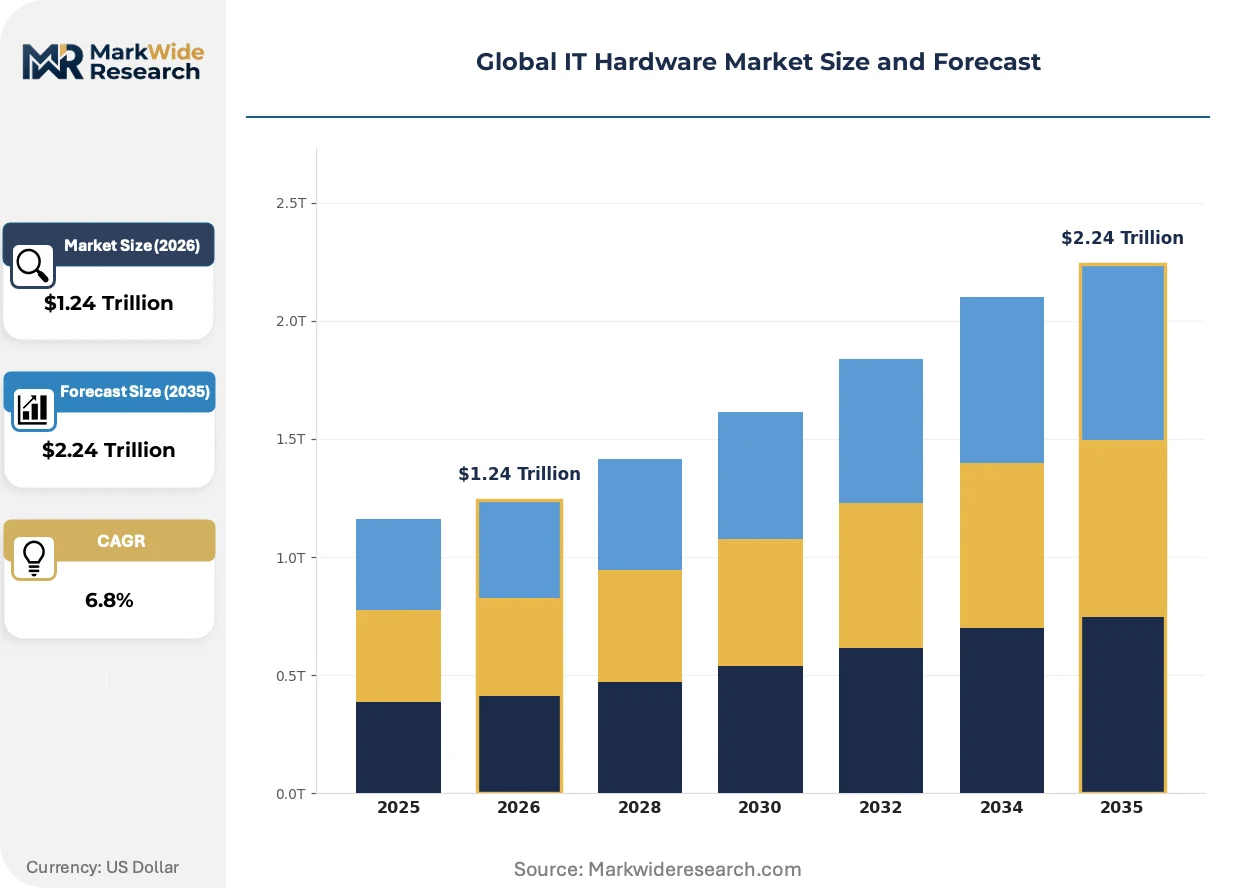
| Market Size in 2026 | $1.24 Trillion |
| Market Size in 2035 | $2.24 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Servers, Workstations, Desktops, Laptops Technology: Cloud Computing, Edge Computing, Virtualization, Networking End User: Small Enterprises, Medium Enterprises, Large Corporations, Government Sales Channel: Direct Sales, Retail Sales, Online Sales, Distribution Partners |
| Companies Covered | HP Inc., Dell Technologies Inc., Lenovo Group, Samsung Electronics Co. Ltd., Intel Corporation, NVIDIA Corporation, Apple Inc., Quanta Computer Inc., Acer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IT Hardware Market Strategic Shifts
Compute infrastructure is fragmenting into disaggregated resource pools that buyers compose dynamically rather than purchasing fixed-configuration servers. This architectural shift is compressing traditional server SKU counts while expanding the addressable market for specialized accelerators and memory expansion modules.
Chiplet-based processor packaging is unifying memory and logic die integration through advanced 2.5D interposers. Cloud providers in the United States are qualifying these designs for production workloads this year. The technology is unifying previously separate procurement streams for CPUs, memory DIMMs, and accelerator cards into single-socket decisions.
The EU Ecodesign Directive's 2026 standby power limits are forcing power supply redesigns across server and workstation categories. OEMs must eliminate vampire draw below 0.5W or forfeit CE marking eligibility. Enterprise rack deployments in France and Germany are already specifying 80 PLUS Titanium supplies to preempt compliance gaps.
Leasing models are displacing capital purchases for AI training infrastructure. Hyperscalers in the United States now offer bare-metal GPU clusters on 12-month contracts with refresh guarantees. Financial services firms in New York and Chicago are the earliest adopters, trading depreciation complexity for operational expense predictability.
Global IT Hardware Market Segmentation
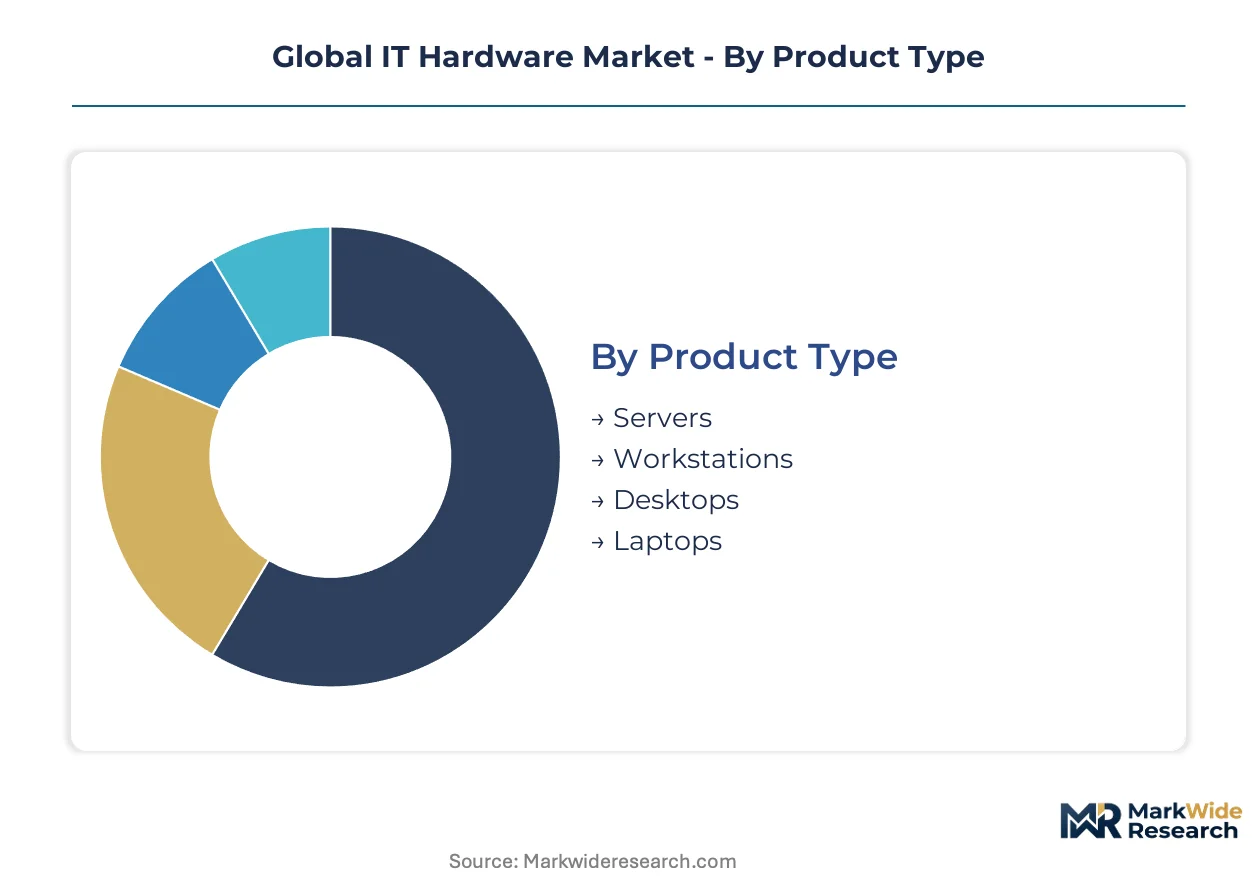
IT hardware procurement patterns diverge sharply across deployment scales and thermal architectures. Understanding these segment boundaries reveals where upgrade cycles compress and where refresh decisions stall.
Product Type:
Replacement cycles vary dramatically by thermal density and socket modularity.
- Servers:Accelerator-rich configurations now dominate hyperscaler procurement, with liquid-cooled rack designs displacing air-cooled legacy fleets. Demand concentrates in United States cloud regions where GPU-dense training clusters command allocation priority from Korean HBM suppliers.
- Laptops:Corporate refresh cycles sustain volume scale despite margin compression in entry-level consumer tiers. Procurement in Germany and France prioritizes Energy Star compliance and 80 PLUS Titanium power supplies ahead of EU Ecodesign Directive deadlines.
- Workstations:Engineering and media production workflows drive specification toward high-core-count processors and professional GPU accelerators.
- Desktops:Persistent in cost-sensitive education and back-office deployments where peripheral compatibility outweighs mobility requirements.
Servers sit at the top of the volume ranking, with laptops climbing the fastest as hybrid work policies extend corporate fleet refreshes.
Technology:
Cost tier stratification separates capital-intensive infrastructure from operational expenditure models.
- Cloud Computing:Hyperscaler bare-metal leasing now offers 12-month GPU cluster contracts with refresh guarantees. Financial services firms in New York and Chicago are the earliest adoptees, trading depreciation complexity for predictable operational expenses.
- Edge Computing:Latency-sensitive manufacturing applications in Germany deploy compact GPU servers for sub-10ms defect detection, bypassing cloud round-trip delays. This architecture gains share fastest as industrial automation intensifies.
- Virtualization:Software-defined resource pooling extends hardware lifecycles through workload abstraction and dynamic allocation.
- Networking:High-speed interconnects between disaggregated compute and memory pools require specialized switch silicon and cabling infrastructure.
Cloud Computing commands the largest addressable spend, while Edge Computing exhibits the steepest expansion trajectory.
End User:
Customer type dictates procurement sophistication and vendor relationship depth.
- Large Corporations:Direct OEM relationships enable custom thermal architectures and liquid cooling integration. Saudi Arabia's NEOM giga-project exemplifies this tier, specifying modular renewable-powered server infrastructure from ground-up construction.
- Government:India's PLI scheme for IT hardware attracts domestic assembly to Tamil Nadu and Karnataka, reducing import dependency for state procurement lists. BIS certification requirements create compliance gates that favor local manufacturing.
- Medium Enterprises:Standardized rack configurations with distribution partner support balance capability against IT staffing constraints.
- Small Enterprises:Volume purchasing through retail and online channels prioritizes upfront cost over lifecycle service agreements.
Large Corporations anchor procurement value, with Government expanding most quickly through localization mandates.
Sales Channel:
Supply concentration shapes channel access and margin distribution.
- Direct Sales:Hyperscaler and enterprise accounts negotiate thermal architecture customization and firmware signing requirements directly with OEM engineering teams.
- Distribution Partners:Regional integrators in India and Europe manage BIS and CE marking compliance for mid-market deployments.
- Online Sales:Standardized SKUs with transparent specification sheets serve cost-optimized procurement in small enterprise and consumer tiers.
- Retail Sales:Physical channel presence persists in education and public sector segments where purchase order workflows require local vendor registration.
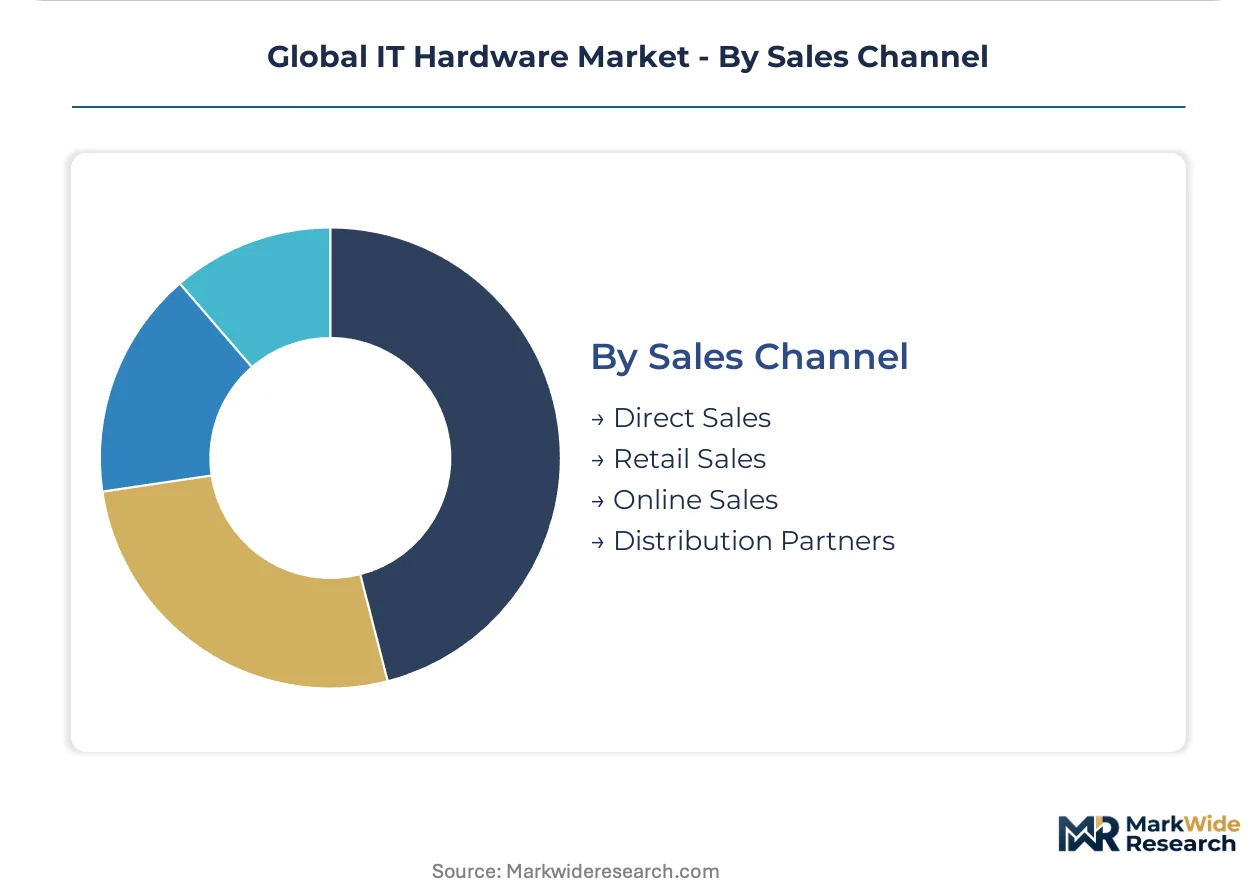
Direct Sales captures the highest transaction values, with Distribution Partners gaining share fastest as compliance complexity fragments procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IT hardware industry traces its modern scale to Silicon Valley's semiconductor fabrication expansion during the 1970s, with subsequent manufacturing gravity shifting toward East Asian electronics clusters and now redistributing across energy-abundant and policy-incentivized zones worldwide.
United States
Hyperscaler capex from Microsoft, Amazon, and Google drives GPU-dense server procurement for generative AI training clusters. The EPA Energy Star program imposes escalating efficiency thresholds on data center power supplies. Northern Virginia's Loudoun County hosts the world's densest concentration of cloud infrastructure, with liquid-cooled rack deployments now exceeding traditional air-cooled capacity.
China
Domestic cloud providers Alibaba and Tencent expand AI training infrastructure despite export control constraints on advanced accelerators. MIIT's GB 40879 standard mandates PUE ceilings below 1.3 for state-owned enterprise data centers. The Yangtze River Delta around Shanghai anchors server assembly operations, with Jiangsu Province concentrating precision SMT manufacturing for motherboard production.
Germany
Industrial automation demand from automotive and precision engineering sectors accelerates edge GPU server deployment for real-time quality control. The EU Ecodesign Directive's 2026 standby power limits force power supply redesigns across enterprise categories. Bavaria's Munich-Stuttgart corridor concentrates R&D engineering for thermal architecture solutions serving European hyperscaler facilities.
India
Corporate laptop refresh cycles and data center localization requirements expand procurement from domestic assembly operations. The PLI scheme for IT hardware attracts component manufacturing to Tamil Nadu and Karnataka, with BIS certification requirements creating compliance gates for imported equipment. Bengaluru's Electronics City hosts expanding server and workstation assembly lines serving enterprise and government accounts.
Saudi Arabia
NEOM giga-project specifications require modular, renewable-powered server infrastructure from ground-up construction. The country's national investment fund mandates technology localization commitments for major cloud contracts. The Tabuk Province development zone is attracting liquid cooling specialists for data center builds designed around solar and wind generation capacity.
Global IT Hardware Market Competitive Environment
The competitive structure tilts toward diversified technology conglomerates with captive semiconductor and systems integration capabilities. Server OEM margins compress under hyperscaler procurement concentration while thermal architecture specialization creates defensible positioning for liquid cooling engineering firms. Three strategic archetypes dominate: scale-driven rack OEMs, fabless semiconductor designers, and contract manufacturing specialists. Competitive moves center on strategic partnerships for accelerator supply security and geographic expansion into policy-incentivized manufacturing zones.
Within the diversified technology conglomerate tier, Dell Technologies Inc. and Lenovo Group occupy positions reflecting supply chain scale advantages, while HP Inc. anchors the corporate laptop refresh segment. NVIDIA Corporation exemplifies the fabless semiconductor archetype through accelerator architecture control. Samsung Electronics Co. Ltd. represents vertical integration spanning memory fabrication through finished system assembly. These company structures illustrate how competitive positioning fragments between silicon-level design control, manufacturing scale, and brand-channel access rather than consolidating around any single capability vector.
| Leading Market Players |
|---|
| HP Inc. |
| Dell Technologies Inc. |
| Lenovo Group |
| Samsung Electronics Co. Ltd. |
| Intel Corporation |
| NVIDIA Corporation |
| Apple Inc. |
| Quanta Computer Inc. |
| Acer Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive manufacturing of high-density server platforms anchors supply position and pricing power for OEMs serving hyperscaler procurement. Lenovo Group's in-house production facilities in China and Mexico insulate margin structures from contract manufacturer volatility while Dell Technologies Inc. leverages direct-to-cloud relationships to bypass distribution markups on accelerator-rich configurations. This integration choice separates premium thermal architecture providers from commodity rack assemblers competing on spot component costs.
Pricing Analysis
Three-tier pricing structure across premium liquid-cooled, standard air-cooled, and economy refurbished tiers stratifies the server market by thermal density and certification grade. Premium tiers command substantial markups for 80 PLUS Titanium power supplies and direct-to-chip cooling compatibility demanded by EU Ecodesign Directive compliance. Cost compression in entry-level laptop tiers intensifies as Indian PLI scheme manufacturing expands domestic assembly capacity. Small enterprises exhibit highest price sensitivity, prioritizing upfront hardware cost over lifecycle service agreements, while hyperscalers accept premium positioning for guaranteed accelerator allocation from Korean HBM suppliers.
Supply Chain Analysis
Workforce availability in precision SMT manufacturing clusters across Taiwan, China, and Vietnam shapes component assembly capacity for motherboard and memory module production. Advanced packaging operations draw from specialized engineering talent pools concentrated in Hsinchu and Shanghai. Raw material dependencies span silicon carbide substrates for power supplies, high-bandwidth memory stacks from Korean fabs, and rare earth elements for magnet-based cooling pumps. Single-source vulnerability in HBM3E output creates allocation bottlenecks for AI server builds. Distribution runs through direct OEM-hyperscaler contracts for enterprise infrastructure, with regional integrators managing compliance certification for mid-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by enterprise procurement shifting toward liquid-cooled, energy-certified server configurations that command durable margin premiums over commodity air-cooled alternatives.
For Market Incumbents: Acquire liquid cooling engineering capabilities to defend positioning against thermal architecture specialists eroding rack OEM margins. Pursue backward integration into power supply manufacturing to secure 80 PLUS Titanium certification capacity ahead of EU Ecodesign Directive deadlines. Expand captive HBM allocation agreements with Korean suppliers to guarantee accelerator-rich build slots for cloud provider customers. For New Entrants and Emerging Players: Begin with edge AI inference appliances serving German automotive manufacturing floors where sub-10ms latency requirements bypass hyperscaler cloud competition. Target India's domestic laptop assembly market where PLI scheme incentives and BIS certification requirements create procurement preference for local manufacturing. Establish channel partnerships with regional systems integrators managing CE marking and Energy Star compliance complexity for European mid-market accounts. For Investors and Strategic Acquirers: Roll-up economics work for thermal architecture engineering boutiques because hyperscaler procurement concentration fragments liquid cooling expertise across country-specific certification requirements. Long-term viability centers on five-to-ten year infrastructure refresh cycles as EU AI Act mandates and energy efficiency directives force legacy fleet replacement. Watch accelerator-to-server form factor standardization efforts as the inflection signal determining whether proprietary socket designs consolidate or fragment inventory pools.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Engineering Acquisition | Secures thermal architecture expertise for 700W+ accelerator socket deployments in United States cloud regions. |
| HBM Supply Agreement Expansion | Guarantees memory allocation priority from Korean suppliers for GPU-dense training cluster builds. |
| Edge Computing Appliance Launch | Captures German manufacturing automation demand for sub-10ms defect detection workloads. |
| India PLI Manufacturing Footprint | Positions for government procurement preference under BIS certification and localization mandates. |
| 80 PLUS Titanium Certification Investment | Ensures CE marking eligibility ahead of EU Ecodesign Directive standby power limits. |
Study Parameters
Multiple input streams — hyperscaler capex disclosures, OEM procurement manager interviews, and regulatory filing analysis — were reconciled to construct market sizing and segmentation. Primary fieldwork captured perspectives from data center infrastructure directors, thermal engineering specialists, cloud provider procurement leads, and channel distribution managers across North America, Europe, and Asia-Pacific. Secondary validation drew from SEC 10-K filings, EPA Energy Star certification databases, EU Ecodesign Directive implementation guidance, and MIIT GB standard publications. Bottom-up build from server shipment and configuration data triangulated against top-down IT hardware spending estimates from enterprise technology budget surveys.
Data-stream reconciliation across the projection horizon applied segment-specific growth assumptions to derive volume and value trajectories. Modeling dimensions encompassed product type, thermal architecture, deployment scale, end-user sophistication tier, and regional regulatory cluster. CAGRs emerged from fitted growth curves applied to historical shipment patterns and forward procurement pipeline visibility. Forecast inputs incorporated hyperscaler accelerator procurement schedules, corporate laptop refresh cycle timing, and data center PUE compliance deadline impacts across European and Chinese jurisdictions.
Several conditions sit outside the modeled scope, including unannounced export control expansions on advanced accelerators, breakthrough chiplet packaging yield improvements, and geopolitical disruption to Taiwan Strait semiconductor logistics. Forecasts reflect assumptions about sustained hyperscaler AI training investment, stable HBM supply allocation mechanisms, and gradual liquid cooling cost curve reduction. Material deviation in accelerator availability, memory pricing volatility, or regulatory timeline acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IT Hardware
India IT Hardware Market
IT Hardware
Industrial Motherboards Market
IT Hardware
PC Case Market
IT Hardware
USB 3.0 Market
IT Hardware
Tablet PC Market
IT Hardware
Europe IT Device Market
IT Hardware
Single Board Computer Market
IT Hardware
Server Chassis Market
IT Hardware
Cloud IT Infrastructure Hardware Market
IT Hardware
Middle East and Africa IT Device Market
IT Hardware
Global 4K Set Top Box (STB) Market
IT Hardware
Three-Proof Laptop Market
IT Hardware
Asia Pacific IT Device Market