
 USB 3.0 Market | 2026-2036
USB 3.0 Market Size, Share, and Industry Trends Forecast 2026-2036
USB 3.0 Market Analytics
Project finance and equipment-leasing structures for semiconductor fabrication lines is rewriting competitive entry barriers across the USB 3.0 supply base. Intel Corporation leverages captive foundry investments to sustain process-node leadership in controller silicon. Texas Instruments anchors its position through analog integration that competitors struggle to replicate at comparable die sizes.
USB 3.0 denotes a Universal Serial Bus protocol revision delivering 5 Gbps SuperSpeed data transfer with full-duplex signaling and enhanced power delivery up to 900 mA per port, engineered for synchronous high-bandwidth peripheral communication in computing and embedded systems. The protocol serves industrial and commercial purposes by enabling real-time video streaming, rapid mass-storage access, and concurrent device charging across single-cable topologies. Cable and connector segments dominate volume shipments as infrastructure refresh cycles accelerate, while adapter products capture disproportionate margin pools through protocol-translation complexity. Peripheral connectivity applications lead deployment breadth, though video output implementations are expanding fastest as DisplayPort-over-USB-C architectures proliferate.
FCC equipment authorization requirements govern electromagnetic compatibility for USB 3.0 devices distributed in the United States, while CE marking under EU RoHS and REACH frameworks restricts substance composition and mandates conformity assessment for European market access. China's GB standards and MIIT certification protocols impose additional testing burdens on imported controllers and cable assemblies. Stakeholders must monitor evolving USB4 and Thunderbolt convergence timelines that threaten to compress the standalone USB 3.0 upgrade cycle.
Market Dynamics
Protocol convergence between USB4 and Thunderbolt is compressing the standalone USB 3.0 upgrade cycle, forcing suppliers to recalibrate controller roadmaps and cable certification pipelines around backward-compatible architectures.
Growth Catalysts
- EU RoHS Directive:Hazardous substance restrictions in electronics manufacturing accelerate compliance-driven component replacements across European supply chains, refreshing installed bases.
- Data Center Peripheral Connectivity:Cloud infrastructure providers expand high-speed external storage and device management deployments, sustaining demand for 5 Gbps SuperSpeed interfaces.
- China Server Production:Domestic manufacturing of enterprise servers and consumer electronics concentrates demand for certified USB 3.0 controllers and cable assemblies.
Market Restraints
- Silicon Foundry Concentration:Advanced controller fabrication depends on Taiwan and South Korea foundry capacity, creating geographic supply vulnerability.
- USB4 Substitution:Unified 40 Gbps protocol with native Thunderbolt compatibility threatens to bypass standalone USB 3.0 procurement in premium device segments.
- Copper Alloy Volatility:Connector and cable manufacturing faces input cost pressure from fluctuating copper and rare earth magnet prices.
Strategic Opportunities
- Industrial Embedded Systems:Factory automation and medical equipment sectors in Germany and Japan underutilize USB 3.0 for machine vision and diagnostic connectivity.
- DisplayPort-over-USB-C Convergence:Video output implementations expand as single-cable docking architectures proliferate in corporate workstation refresh cycles.
- India PLI Scheme:Production-linked incentives for electronics manufacturing attract cable and connector assembly investments serving domestic and export markets.
Industry Challenges
- MIIT Certification Timelines:China's type-approval protocols for imported controllers and cable assemblies extend time-to-market for foreign suppliers.
- Legacy USB 2.0 Integration:Maintaining backward compatibility with billions of existing peripherals complicates firmware and physical layer design.
- High-Speed Signal Integrity Expertise:Scarce engineering talent for 5 Gbps PCB layout and EMI suppression constrains product development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USB 3.0 Market |
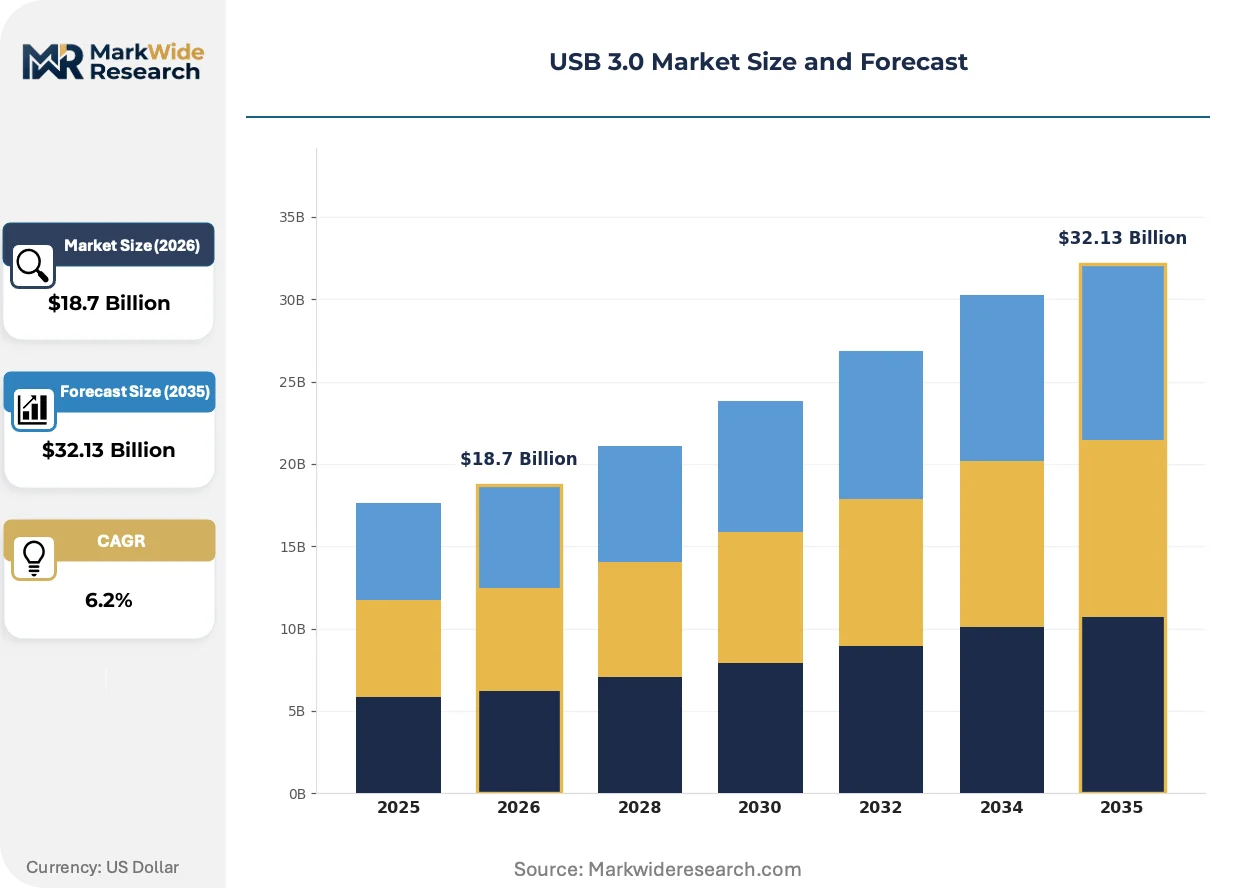
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.13 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cable, Connector, Hub, Adapter Application: Data Transfer, Charging, Peripheral Connectivity, Video Output End User: Consumer Electronics, IT & Telecom, Automotive, Healthcare Installation Type: Internal, External, Integrated, Modular |
| Companies Covered | NXP Semiconductors, Renesas Electronics Corporation, Intel Corporation, STMicroelectronics, Broadcom Inc., Texas Instruments, ASMedia Technology Inc., Kingston Technology Corporation, Microchip Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USB 3.0 Market Evolving Landscape
Active cable architectures and intelligent power negotiation are redefining physical layer economics, while regulatory pressure on material composition and electromagnetic compliance intensifies design complexity.
Redriver and retimer semiconductor integration is virtualizing signal conditioning functions that previously required bulky external amplifiers. Server motherboard designers adopt these active components to extend trace lengths without sacrificing eye diagram margins. This silicon migration is virtualizing the traditional discrete analog front-end, compressing bill-of-materials counts and enabling thinner form factors in high-density rack configurations.
EU REACH substance restrictions now govern phthalate content in cable jacketing and halogen-free flame retardant formulations. Manufacturers reformulate compound recipes to maintain flexibility and durability ratings under stricter SVHC thresholds. German automotive suppliers face the most acute compliance burden, as in-cabin USB charging ports must simultaneously satisfy REACH, RoHS, and OEM-specific material declaration protocols.
Enterprise procurement teams now mandate USB-IF certification logos as a non-negotiable vendor qualification gate, displacing informal interoperability testing. This behavioral shift concentrates volume with suppliers maintaining active certification programs and accredited test lab relationships. North American IT distributors report certification status has become the primary sorting criterion in RFP evaluations, ahead of unit pricing for multi-thousand unit orders.
USB 3.0 Market Segmentation
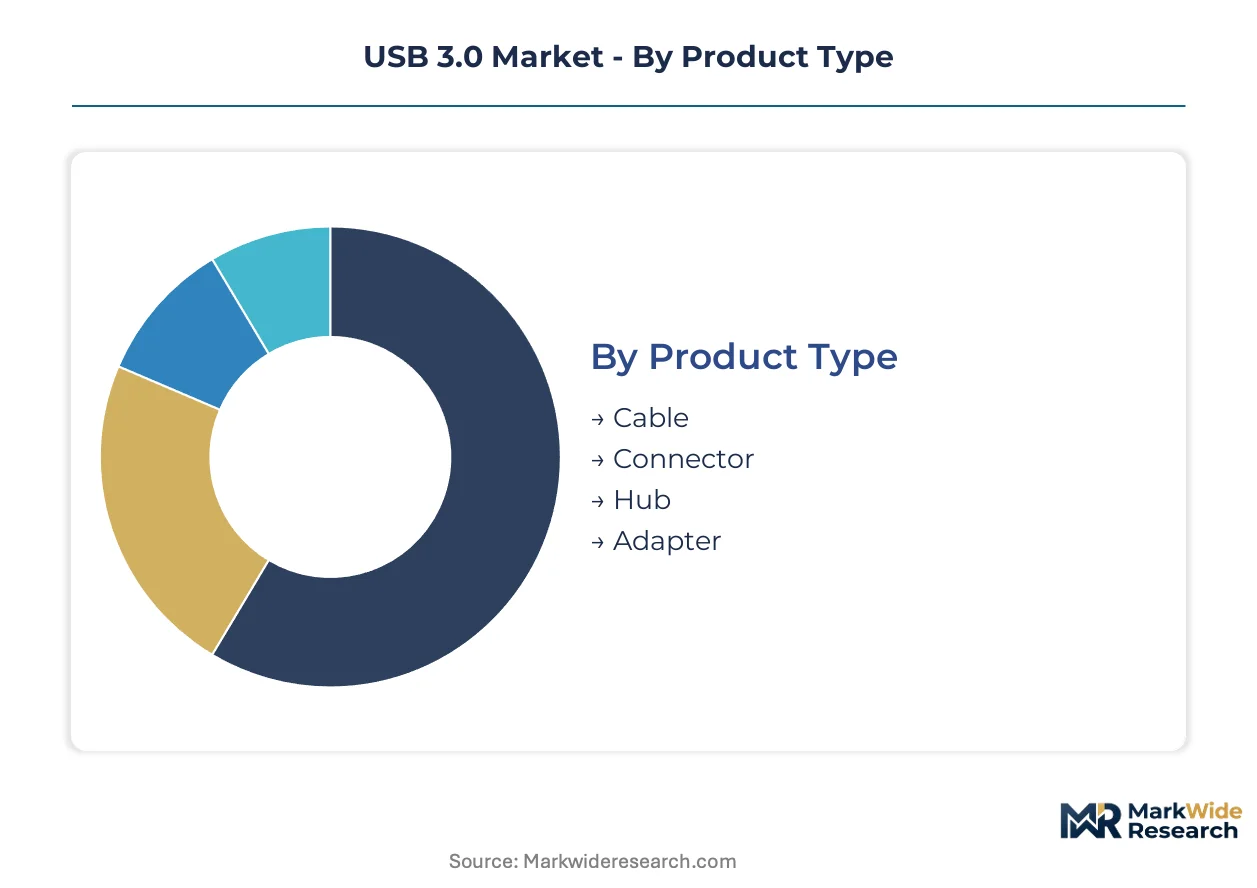
USB 3.0 market segmentation reveals distinct competitive dynamics across physical components, functional applications, and deployment contexts. Each dimension carries specific margin profiles and regulatory exposure that reshape supplier positioning.
Product Type:
Mature connector and cable segments coexist with emerging hub and adapter architectures that integrate protocol translation intelligence.
- Cable:Copper-alloy conductor assemblies with shielded twisted-pair construction dominate volume shipments as infrastructure refresh cycles accelerate across data centers and enterprise workstation deployments. Chinese cable manufacturers concentrate capacity for certified SuperSpeed assemblies serving domestic server production and export markets.
- Connector:Precision-molded receptacles and plug housings with contact plating specifications determine signal integrity margins; USB-C form factor adoption in German automotive in-cabin charging ports drives REACH-compliant material reformulation requirements.
- Hub:Multi-port expansion controllers with integrated power management serve corporate docking station procurement.
- Adapter:Protocol-translation devices enabling legacy peripheral compatibility capture disproportionate margin pools through firmware complexity.
Cable retains volume leadership; adapter holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity data functions from premium video and power-delivery implementations.
- Data Transfer:Mass-storage and peripheral synchronization at 5 Gbps SuperSpeed represents the foundational use case; cloud infrastructure providers in the United States sustain procurement for high-speed external storage arrays under FCC electromagnetic compliance frameworks.
- Charging:Enhanced power delivery up to 900 mA per port enables concurrent device charging; Japanese medical equipment manufacturers underutilize this capability for diagnostic cart connectivity.
- Peripheral Connectivity:Keyboard, mouse, and printer interface deployment leads deployment breadth across consumer and enterprise segments.
- Video Output:DisplayPort-over-USB-C architectures proliferate fastest in corporate workstation refresh cycles as single-cable docking simplifies IT asset management.
Peripheral connectivity retains volume leadership; video output gains share fastest.
End User:
Customer type segmentation exposes divergent certification requirements and procurement decision structures.
- Consumer Electronics:Smartphone, laptop, and tablet integration drives highest unit volumes; China's domestic manufacturing scales concentrate demand for MIIT-certified controllers.
- IT & Telecom:Enterprise server and networking equipment procurement mandates USB-IF certification as non-negotiable vendor qualification; North American distributors report certification status dominates RFP evaluation criteria.
- Automotive:In-cabin charging and infotainment connectivity face stringent OEM material declaration protocols, particularly among German tier-1 suppliers.
- Healthcare:Diagnostic equipment and patient monitoring systems require isolation-rated implementations with FDA device-level compliance.
Consumer electronics retains volume leadership; automotive climbs the fastest.
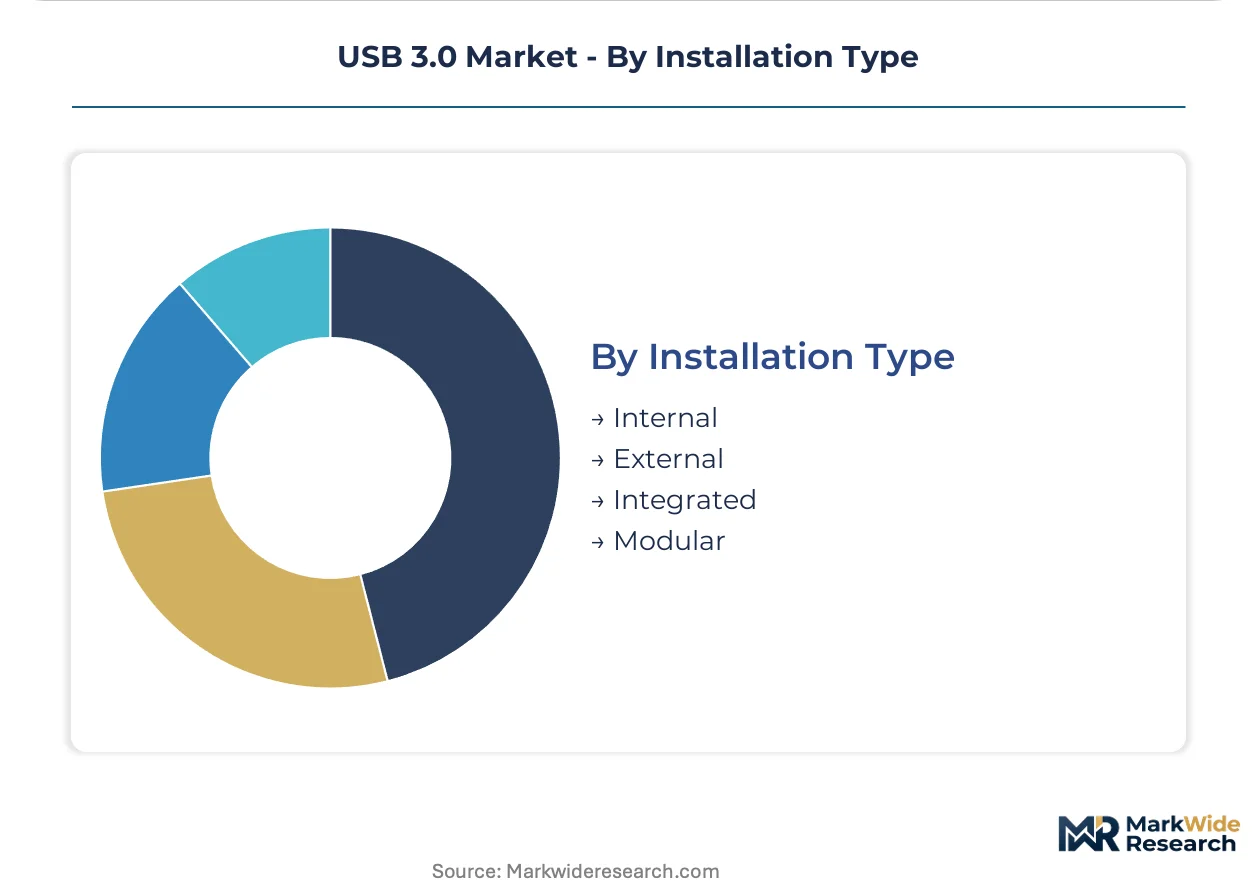
Installation Type:
Supply concentration varies sharply between captive integrated implementations and modular aftermarket configurations.
- Internal:Motherboard-integrated controllers and embedded trace routing serve OEM device manufacturing with captive silicon procurement.
- External:Cabled peripheral and standalone hub deployments face highest replacement frequency and price elasticity.
- Integrated:System-on-chip USB 3.0 PHY integration in application processors reduces discrete component counts.
- Modular:Field-replaceable controller cards and expansion modules sustain aftermarket upgrade demand in industrial embedded systems.
Internal retains volume leadership; modular shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USB 3.0 component trade flows reveal stark asymmetries. China runs substantial controller and cable assembly surpluses while the United States and Germany remain net importers of certified SuperSpeed silicon. These imbalances shape regional investment patterns and regulatory enforcement intensity.
United States
Cloud infrastructure providers in Virginia and Oregon sustain procurement of high-speed external storage arrays. FCC equipment authorization governs electromagnetic compatibility for all distributed devices. Silicon Valley controller design houses concentrate firmware development while Texas instruments fabricators manage analog integration.
China
Domestic server production in Shenzhen and Dongguan concentrates demand for MIIT-certified controllers. GB standards and MIIT certification protocols impose testing burdens on imported cable assemblies. Yangtze River Delta cable manufacturers scale certified SuperSpeed assembly capacity for export markets.
Germany
Automotive tier-1 suppliers in Stuttgart and Munich face REACH, RoHS, and OEM-specific material declaration protocols for in-cabin USB charging ports. EU RoHS directive accelerates compliance-driven component replacements. Bavarian industrial automation sectors underutilize USB 3.0 for machine vision connectivity.
Japan
Medical equipment manufacturers in Tokyo and Osaka underutilize enhanced power delivery for diagnostic cart connectivity. METI oversees industrial standards alignment with international USB-IF specifications. Nagoya-area automotive suppliers integrate charging ports under stringent material compliance frameworks.
India
Production-linked incentives under the PLI scheme attract cable and connector assembly investments in Tamil Nadu and Karnataka. Domestic electronics manufacturing scales rapidly for smartphone and laptop integration. BIS certification requirements govern quality standards for locally produced controller imports.
USB 3.0 Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The USB 3.0 supply base consolidates around captive foundry investments and analog integration capabilities that resist replication. Three archetypes dominate: semiconductor fabricators with process-node leadership, analog specialists with die-size advantages, and fabless controller designers with certification pipeline depth. Competitive moves center on backward integration into foundry capacity and strategic partnerships for MIIT certification acceleration.
Among semiconductor fabricators, Intel Corporation and Texas Instruments occupy positions at the integrated extreme, while NXP Semiconductors sits within the European analog-specialist tier. These entities exemplify divergent approaches to controller silicon—captive foundry investments versus analog integration complexity. ASMedia Technology Inc. represents the fabless archetype dependent on external fabrication partnerships. Each anchors a distinct competitive vector without overlapping strategic territory.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Renesas Electronics Corporation |
| Intel Corporation |
| STMicroelectronics |
| Broadcom Inc. |
| Texas Instruments |
| ASMedia Technology Inc. |
| Kingston Technology Corporation |
| Microchip Technology Inc. |
| Others |
Value Network & Pricing Analysis
Taiwanese foundry concentration for advanced controller silicon concentrates margin capture at the wafer-fabrication tier, forcing downstream cable and connector assemblers to compete on volume efficiency rather than technology premiums. USB-IF certification investments now function as a price floor mechanism, segmenting suppliers between accredited premium tiers and uncertified commodity players.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scale and certification-grade price differentiation. Three-tier pricing structure across USB-IF certified premium, standard compliance, and uncertified economy levels separates procurement pools. Cost compression in Chinese cable assembly is intensifying because Yangtze River Delta capacity expansion outpaces demand growth. Automotive tier-1 suppliers in Germany show least price sensitivity due to REACH-compliant material premiums, while Indian PLI-scheme beneficiaries compete most aggressively on unit economics.
Supply Chain Analysis
Foxconn and Pegatron electronics manufacturing services hold dominant cable and connector assembly capacity across Shenzhen, Dongguan, and Tamil Nadu facilities. Controller silicon draws from Taiwan and South Korea foundry output, with copper-alloy conductor and rare earth magnet inputs feeding connector plating operations. Single-source vulnerability concentrates at the 5nm controller fabrication node where TSMC capacity allocation determines shipment priority. Distribution runs through North American IT distributors and Chinese domestic server OEM direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The USB 3.0 market sits in a cyclical recovery phase as data center infrastructure refresh cycles accelerate replacement demand for SuperSpeed peripheral connectivity. Cloud provider capex normalization provides the cyclical justification for near-term volume expansion.
For Market Incumbents: Harden analog integration capabilities at die-size parity to resist fabless competitor replication. Prioritize captive foundry investments in Taiwan to secure controller silicon allocation against USB4 substitution threats. Deepen USB-IF certification pipeline relationships to maintain RFP qualification dominance in North American enterprise procurement.
For New Entrants and Emerging Players: Build out industrial embedded system penetration in German factory automation and Japanese medical equipment where USB 3.0 remains underutilized for machine vision connectivity. Target India's PLI-scheme cable assembly investments as the most penetrable geography with export market access. Lead with MIIT certification acceleration partnerships to compress China time-to-market versus established foreign suppliers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed analog-specialist semiconductor portfolios seeking controller IP bolt-ons. Long-term viability hinges on backward compatibility maintenance through the USB4 convergence transition. Monitor USB-IF certification withdrawal rates as the inflection signal for supplier consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| USB-IF Certification Pipeline Expansion | Enterprise procurement teams at North American IT distributors mandate certification logos as non-negotiable vendor qualification gates. |
| Active Cable Architecture Migration | Redriver and retimer semiconductor integration virtualizes signal conditioning functions for server motherboard eye diagram margin extension. |
| REACH-Compliant Material Reformulation | German automotive tier-1 suppliers reformulate cable jacketing compounds under stricter EU SVHC thresholds for in-cabin charging ports. |
| MIIT Certification Acceleration Partnership | Foreign suppliers compress China time-to-market by aligning with domestic testing laboratories for GB standards compliance. |
| DisplayPort-over-USB-C Convergence Investment | Corporate workstation refresh cycles drive single-cable docking architectures that expand video output implementation share fastest. |
Research Methodology
A standing panel of controller firmware engineers, cable assembly procurement managers, data center infrastructure planners, and USB-IF certification test lab directors provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against SEC semiconductor filings, MIIT certification databases, EU REACH substance restriction updates, and hyperscaler capex disclosures. Bottom-up shipment modeling and top-down value chain triangulation anchored segment-level outputs.
Scenario-bracketing around USB4 substitution velocity and data center refresh cycle timing bounded projection uncertainty across the analysis window. Segmentation dimensions modeled include product type, application function, end-user industry, and installation configuration. CAGRs derived from unit shipment trajectory analysis weighted by average selling price evolution. Controller silicon node migration and copper alloy input cost volatility served as industry-specific forecast sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive foundry capacity expansion by fabless controller designers would shift outcomes beyond modeled ranges. Quarterly review of USB-IF certification withdrawal rates, MIIT approval timeline extensions, and cloud provider storage array procurement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IT Hardware
Server Chassis Market
IT Hardware
Middle East and Africa IT Device Market
IT Hardware
Cloud IT Infrastructure Hardware Market
IT Hardware
Global 4K Set Top Box (STB) Market
IT Hardware
Global IT Hardware Market
IT Hardware
Europe IT Device Market
IT Hardware
PC Case Market
IT Hardware
Tablet PC Market
IT Hardware
Three-Proof Laptop Market
IT Hardware
India IT Hardware Market
IT Hardware
Single Board Computer Market
IT Hardware
Industrial Motherboards Market
IT Hardware
Asia Pacific IT Device Market