
 India IT Hardware Market | 2026-2036
India IT Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
India IT Hardware Market Insights
The PLI scheme for IT hardware is recalibrating competitive priorities across India's electronics manufacturing landscape. Dell Technologies leverages its direct sales infrastructure to sustain enterprise relationships in banking and government verticals. Tata Consultancy Services anchors large-scale server deployments through its systems integration practice. Lenovo India dominates the commercial laptop segment with channel depth that extends into tier-two cities.
India IT Hardware encompasses computing devices, peripheral equipment, and infrastructure components assembled or manufactured for data processing, storage, and network transmission, typically specified by processor architecture, memory bandwidth, and thermal design power ratings. The primary purpose spans enterprise workload execution, cloud service delivery, and endpoint productivity across organizational scales. Laptops and servers occupy the largest revenue pools, while edge computing configurations represent the fastest-growing technology segment as latency-sensitive applications proliferate. Government and BFSI end users concentrate procurement volumes through formal tender processes that favor vendors with domestic assembly certifications.
BIS certification requirements and the PLI scheme administered by MeitY shape product compliance thresholds and local manufacturing incentives for market participants. CDSCO regulates medical-grade hardware deployed in healthcare settings, adding a parallel compliance layer for specialized devices. Stakeholders must monitor evolving domestic value-addition mandates and tariff structures that determine cost competitiveness against fully imported alternatives.
Market Dynamics
The PLI scheme administered by MeitY is forcing a wholesale reconfiguration of component sourcing toward domestic value addition, compressing margins for import-dependent assemblers while rewarding captive manufacturing investments.
Growth Catalysts
- MeitY's PLI scheme:Tiered incentives for local assembly are pulling motherboard and power supply manufacturing into Tamil Nadu and Uttar Pradesh electronics clusters.
- Banking sector server refresh:RBI-mandated data localization requirements are accelerating enterprise storage and compute procurement from domestic assembly-certified vendors.
- Edge computing deployments:Latency-sensitive video analytics for smart city projects in Surat and Pune are creating dedicated hardware demand outside traditional data center channels.
Market Restraints
- Memory chip import concentration:DRAM and NAND flash supply routes through Singapore and South Korea expose assemblers to freight cost volatility and currency fluctuation.
- BIS certification timelines:Mandatory safety testing for power adapters and lithium battery packs extends product launch cycles by 8-14 weeks against unregulated imports.
- Chromebook substitution in education:Low-cost cloud-dependent devices are capturing tender volumes in state government school laptop programs, compressing Windows laptop addressable market.
Strategic Opportunities
- Northeast India connectivity projects:BharatNet Phase 3 fiber rollout is creating first-time demand for ruggedized edge routers and outdoor-rated server enclosures in Assam and Meghalaya.
- Medical device hardware convergence:CDSCO's streamlined approval pathway for diagnostic imaging workstations is opening specialized compute configurations for radiology equipment manufacturers.
- AI inferencing accelerators:Domestic assembly of GPU-based inference cards for computer vision applications is qualifying for enhanced PLI rates above standard server incentives.
Industry Challenges
- PCB design engineering scarcity:High-speed signal integrity expertise for server motherboard development concentrates in Bengaluru and Hyderabad, constraining expansion timelines for second-tier manufacturers.
- Legacy government tender protocols:L1 price-based selection criteria in state procurement portals favor lowest-spec configurations, complicating premium feature differentiation for enterprise-grade hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India IT Hardware Market |
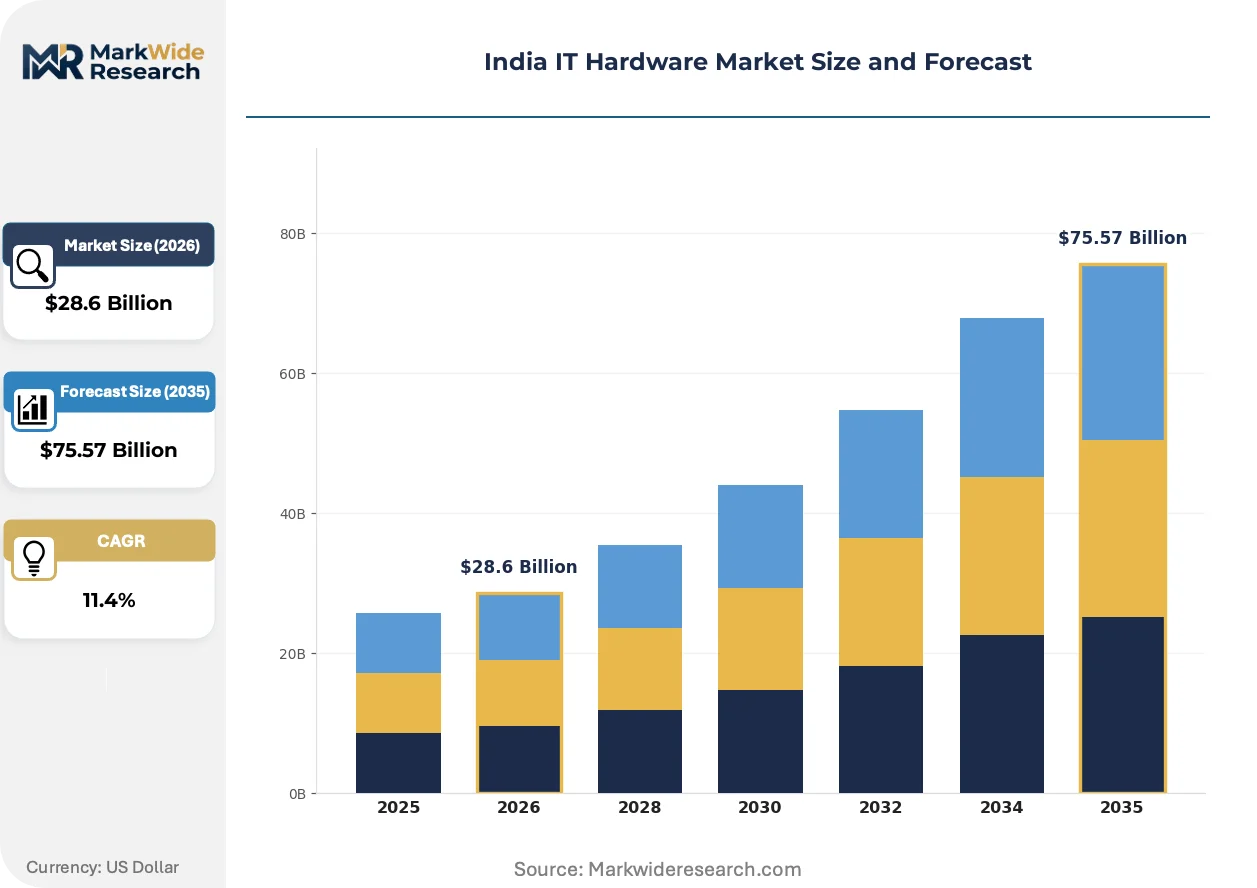
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laptops, Desktops, Servers, Workstations Technology: Cloud Computing, Edge Computing, Virtualization, Artificial Intelligence End User: Education, Healthcare, BFSI, Government Distribution Channel: Retail Stores, E-commerce, Direct Sales, Resellers |
| Companies Covered | Wipro, Dell Technologies, Tata Consultancy Services, ASUS Technology India, Intel Technology India, Infosys, Lenovo India, Hitachi High-Technologies India, HCL Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India IT Hardware Market Trends and Innovations
Arm-based processor architectures are overtaking x86 dominance in power-constrained deployment scenarios, while regulatory pressure on domestic value addition and procurement digitization are simultaneously rewiring competitive access.
Arm server processors are overtaking Intel Xeon installations in cloud provider edge nodes and telco central offices where thermal constraints and per-watt performance dominate selection criteria. Bharti Airtel and Jio are piloting Ampere-based racks for 5G core functions, compressing Intel's historical share in infrastructure compute. This shift is enabling domestic assemblers to bypass legacy x86 supply allocation queues controlled by multinational distributors.
MeitY's phased manufacturing program is mandating progressive domestic content thresholds for laptops and servers, with 2025-26 requirements targeting display panel and keyboard module localization. Hardware vendors are responding by qualifying Chennai and Noida-based component suppliers ahead of tariff escalation on fully built units. The BFSI vertical faces the steepest compliance burden due to pre-existing RBI localization mandates that now intersect with PLI participation requirements.
State government e-procurement portals are consolidating laptop and desktop demand into annual rate contracts, displacing fragmented purchase orders through authorized distributors. Tamil Nadu and Gujarat electronics corporations are aggregating tender volumes that previously fragmented across individual departments and municipal bodies. This concentration favors vendors with dedicated government vertical sales teams and MeitY-certified domestic assembly facilities, compressing channel margins for traditional distributor networks.
India IT Hardware Market Segmentation
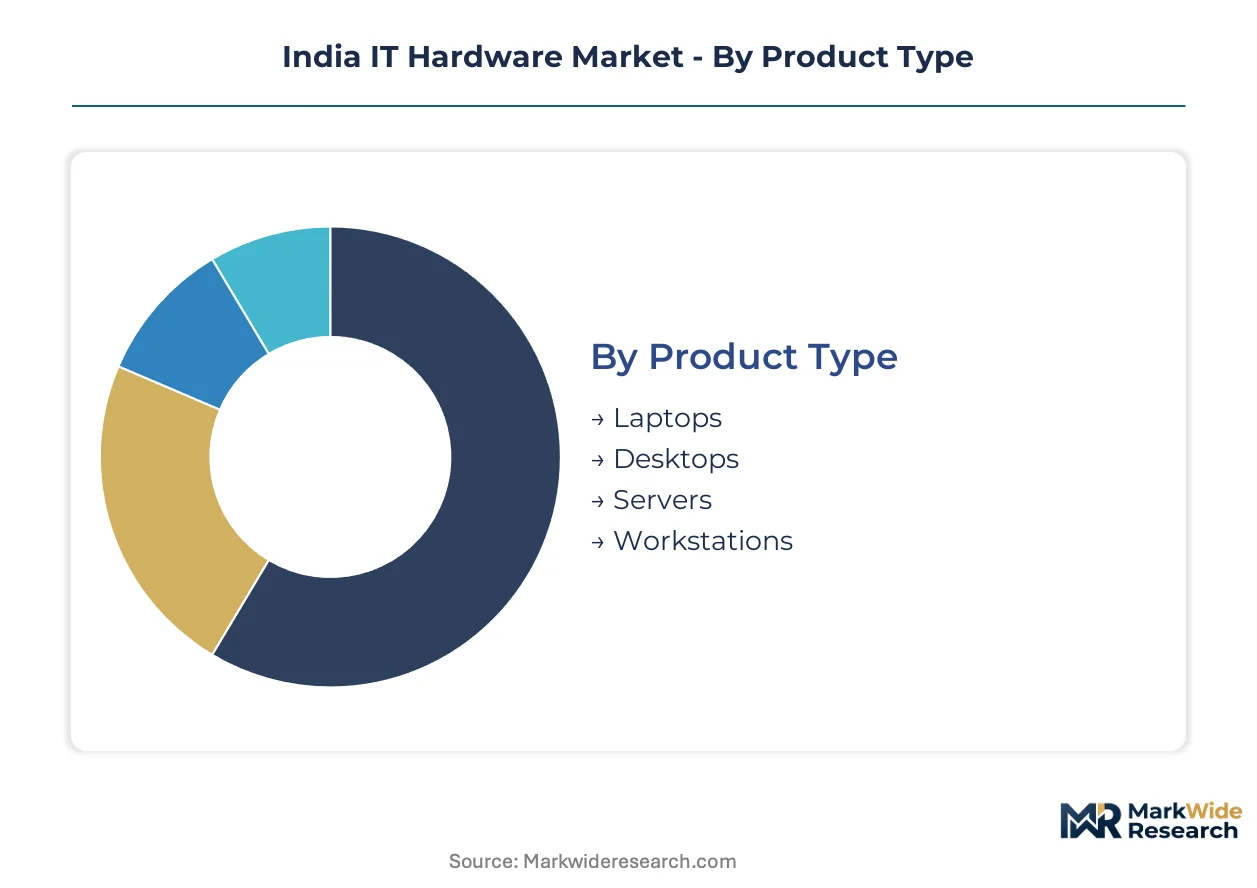
Segmentation in India's IT hardware market exposes divergent procurement rhythms across institutional buyers versus individual consumers. Product specifications, compliance requirements, and channel economics vary sharply between government tenders and enterprise direct sales.
Product Type:
Standardization dominates at the component level while finished configurations fragment across customer tiers.
- Laptops:Commercial-grade units with Intel vPro or AMD PRO manageability chipsets dominate enterprise fleets. Maharashtra's banking sector concentrates procurement through annual rate contracts that specify minimum domestic assembly thresholds.
- Servers:Rack-mounted x86 and emerging Arm-based configurations handle enterprise workload execution and cloud service delivery. RBI-mandated data localization is pulling hyperscale storage deployments toward domestic assembly-certified vendors in Tamil Nadu electronics clusters.
- Desktops:Tower and small-form-factor units serve cost-sensitive educational institutions and back-office operations.
- Workstations:GPU-accelerated configurations for CAD, media production, and scientific computing carry specialized thermal and power supply requirements.
Most installed capacity flows through Laptops. Expansion is steepest in Servers.
Technology:
Deployment architecture determines hardware specification intensity and refresh cadence across customer segments.
- Cloud Computing:Hyperscale data center infrastructure demands high-density server configurations with liquid cooling compatibility. Telco central offices in Mumbai and Chennai are expanding compute capacity to host sovereign cloud instances.
- Edge Computing:Ruggedized micro-servers and gateway devices process latency-sensitive workloads outside centralized facilities. Smart city video analytics projects in Surat and Pune are deploying outdoor-rated enclosures with dust and humidity protection.
- Virtualization:Software-defined infrastructure reduces hardware unit volumes while increasing per-server memory and core density requirements.
- Artificial Intelligence:GPU and specialized inference accelerators for computer vision and natural language processing carry enhanced PLI qualification rates.
Cloud Computing absorbs the largest capital deployment. Edge Computing is climbing the fastest.
End User:
Procurement formalization and compliance burden vary dramatically across institutional buyer categories.
- Government:Central and state administrative bodies purchase through MeitY-mandated e-procurement portals with domestic content verification. Annual rate contracts in Tamil Nadu and Gujarat aggregate previously fragmented departmental purchases.
- BFSI:Banks and insurers face intersecting RBI data localization and PLI participation requirements. Server refresh cycles are accelerating to meet storage sovereignty mandates.
- Education:State government laptop programs for schools are fragmenting between Windows notebooks and lower-cost Chromebook alternatives.
- Healthcare:Diagnostic imaging and hospital information systems require CDSCO-regulated hardware configurations with specialized compliance documentation.
Government channels process the highest unit volumes. BFSI is gaining share fastest.
Distribution Channel:
Channel economics and customer touch intensity determine margin structure and vendor selection criteria.
- Direct Sales:Enterprise account teams manage large-scale server deployments and government tender responses. Dell Technologies and Lenovo India maintain dedicated vertical sales organizations for banking and public sector procurement.
- Resellers:Systems integrators and value-added distributors provide configuration, installation, and maintenance services. TCS anchors complex server deployments through its integration practice.
- E-commerce:Consumer and small business laptop purchases migrate toward platform aggregators with instant credit and exchange programs.
- Retail Stores:Tier-two and tier-three city consumers rely on authorized brand outlets for demonstration and after-sales support.
Direct Sales captures the largest enterprise transaction value. Resellers are expanding most quickly.
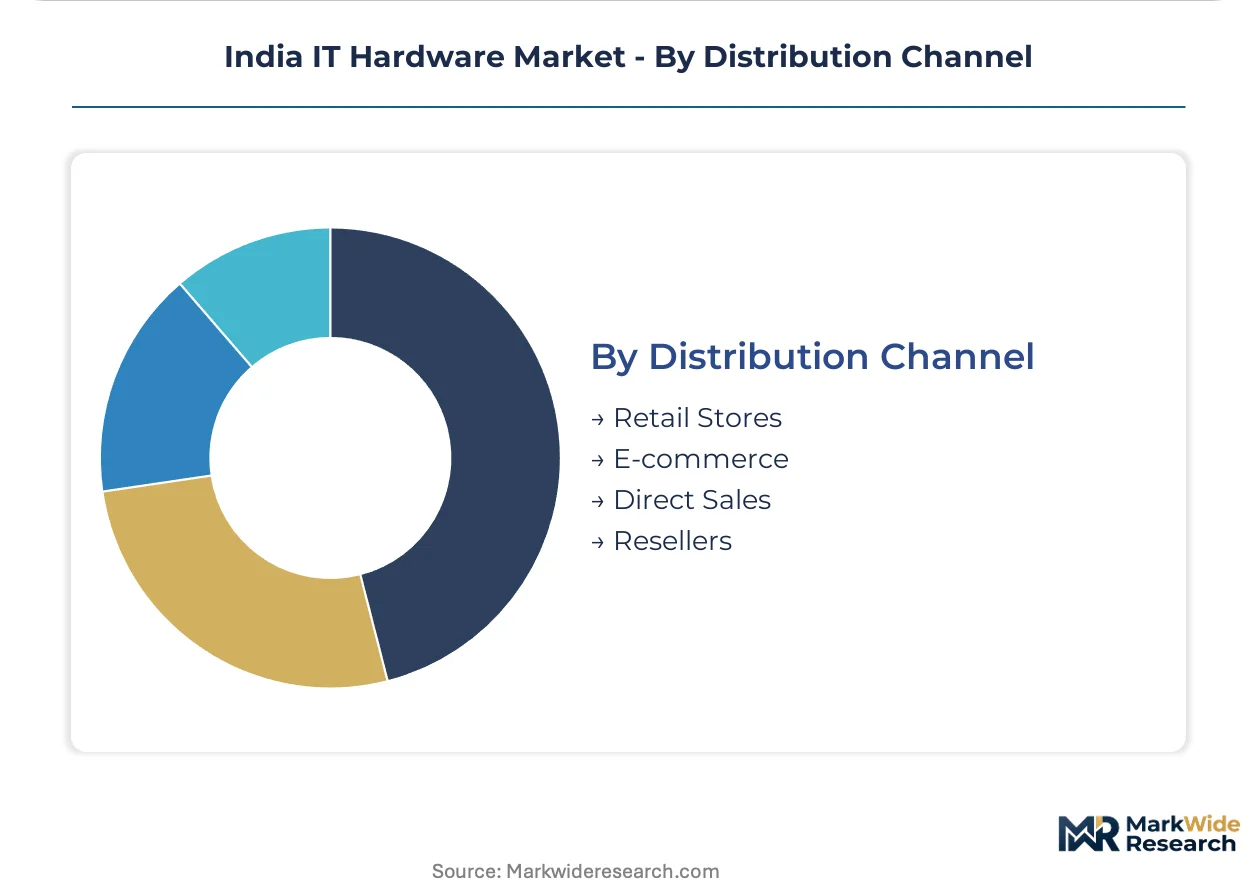
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's IT hardware industry traces its manufacturing lineage to the 1980s software export boom, which seeded demand for domestic assembly capabilities. Electronics manufacturing clusters now concentrate across five industrial states that anchor procurement, production, and policy implementation.
Maharashtra
Mumbai-Pune corridor hosts enterprise data centers and banking sector procurement headquarters. RBI-mandated data localization drives server refresh cycles through domestic assembly-certified vendors. Thane and Pimpri-Chinchwad electronics clusters are expanding motherboard and power supply manufacturing capacity.
Tamil Nadu
State electronics corporations aggregate annual rate contracts for government laptop and desktop procurement. MeitY's PLI scheme pulls display panel and keyboard module suppliers into Sriperumbudur and Oragadam industrial zones. Chennai's port infrastructure supports component import routes for DRAM and NAND flash supply chains.
Karnataka
Bengaluru anchors PCB design engineering expertise for server motherboard development. BIS certification timelines for power adapters and lithium battery packs extend product launch cycles for hardware vendors. Electronics City and Whitefield host systems integration practices for hyperscale storage deployments.
Gujarat
Gandhinagar and Ahmedabad electronics corporations consolidate tender volumes from previously fragmented departmental purchases. State government e-procurement portals specify minimum domestic assembly thresholds for commercial-grade units. Sanand and Vadodara industrial corridors qualify for tiered PLI incentives.
Telangana
Hyderabad concentrates high-speed signal integrity engineering talent for server development. CDSCO-regulated diagnostic imaging workstations require specialized compute configurations for healthcare hardware. Genome Valley and Hardware Park are attracting medical device hardware convergence investments.
India IT Hardware Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across India's IT hardware landscape. The market structure fragments between multinational assemblers with captive manufacturing, domestic systems integrators, and component specialists. Three archetypes dominate: direct-sales enterprise vendors, channel-deep commercial distributors, and government-vertical specialists. Competitive moves center on PLI scheme qualification and state tender aggregation capabilities.
Within the direct-sales enterprise tier, Dell Technologies and Lenovo India occupy positions serving banking and government verticals through dedicated sales organizations. Tata Consultancy Services anchors complex server deployments through its systems integration practice, exemplifying the services-led hardware procurement model. These three represent distinct approaches to navigating MeitY certification requirements and RBI localization mandates.
| Leading Market Players |
|---|
| Wipro |
| Dell Technologies |
| Tata Consultancy Services |
| ASUS Technology India |
| Intel Technology India |
| Infosys |
| Lenovo India |
| Hitachi High-Technologies India |
| HCL Technologies |
| Others |
Pricing and Supply Chain Analysis
Government tender aggregation through MeitY-mandated e-procurement portals anchors pricing power for domestic assembly-certified vendors, compressing margins for import-dependent assemblers while rewarding captive manufacturing investments with preferential rate contract access.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by domestic content certification grade and volume scale. Premium tiers command markups for BIS-certified configurations with localized motherboard and power supply assemblies. Cost compression in the economy tier is intensifying because Chromebook alternatives capture state education tenders. State government procurement bodies exhibit highest price sensitivity, while BFSI enterprises prioritize compliance-grade specifications over unit cost.
Supply Chain Analysis
DRAM and NAND flash supply rests on South Korean and Singaporean semiconductor producers, with display panel sourcing concentrated in Chinese and Taiwanese manufacturing bases. Server motherboard fabrication draws from Bengaluru and Hyderabad engineering clusters, while power adapter components feed from Shenzhen and Dongguan electronics corridors. Single-source vulnerability in memory chip allocation exposes assemblers to freight cost volatility. Distribution runs through authorized distributor networks for tier-two city penetration, with direct sales teams managing enterprise and government account execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India IT Hardware represents a late-cycle quality story as RBI data localization mandates and MeitY PLI participation requirements shift procurement toward premium domestic assembly-certified configurations with enhanced compliance documentation.
For Market Incumbents: Anchor enterprise relationships through dedicated government vertical sales teams with MeitY-certified assembly facilities. Invest in Chennai and Noida component supplier qualification ahead of tariff escalation on fully built units. Defend against Arm-based processor substitution by securing x86 supply allocation commitments from multinational distributors. For New Entrants and Emerging Players: Northeast India connectivity projects present underserved buyer archetype opportunities in Assam and Meghalaya for ruggedized edge routers and outdoor-rated server enclosures. Target BharatNet Phase 3 fiber rollout deployments with dust and humidity-protected micro-server configurations. Pursue systems integration partnerships with state electronics corporations to bypass fragmented departmental procurement channels. For Investors and Strategic Acquirers: Domestic systems integrators with captive manufacturing assets are the most active acquirer category in this space. Long-term viability hinges on PLI scheme qualification depth and state tender aggregation capabilities. Monitor BIS certification timeline compression as an inflection indicator for product launch cycle competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Component Supplier Qualification | Chennai and Noida-based suppliers gain preferential access to MeitY PLI tiered incentives. |
| Arm-Based Server Platform Development | Ampere processor deployments at Bharti Airtel and Jio compress Intel infrastructure compute share. |
| Government Vertical Sales Organization Buildout | Dedicated teams capture Tamil Nadu and Gujarat annual rate contract aggregations. |
| Edge Computing Ruggedization Investment | Outdoor-rated enclosures address Surat and Pune smart city video analytics latency requirements. |
| BIS Certification Process Optimization | Compressed 8-14 week timelines for power adapters and lithium battery packs accelerate product launches. |
Research Methodology
Multiple input streams — primary interviews with hardware vendor sales directors, component procurement leads, and state electronics corporation officials; secondary validation through MeitY PLI scheme disclosures, RBI circulars on data localization, and BIS certification registries; plus customs import data for DRAM and NAND flash — were reconciled through bottom-up and top-down triangulation.
Historical shipment patterns were cross-referenced against panel input from systems integration practitioners to construct analytical frameworks across the analysis window. Segmentation dimensions modeled include product type, deployment architecture, end-user vertical, and distribution channel. CAGRs were derived from installed base refresh cycles intersecting with regulatory compliance deadlines, with Arm-based processor adoption curves and PLI participation rates serving as industry-specific forecast inputs.
Inputs from state government e-procurement portals and CDSCO medical device registries were available through the study window; gaps in real-time component inventory data and tender award pricing introduce uncertainty bands around volume assumptions. A small set of triggers — BIS certification timeline shifts, PLI scheme rate adjustments, and RBI localization mandate expansion — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IT Hardware
Server Chassis Market
IT Hardware
Global 4K Set Top Box (STB) Market
IT Hardware
USB 3.0 Market
IT Hardware
Tablet PC Market
IT Hardware
Cloud IT Infrastructure Hardware Market
IT Hardware
Industrial Motherboards Market
IT Hardware
Single Board Computer Market
IT Hardware
Three-Proof Laptop Market
IT Hardware
Asia Pacific IT Device Market
IT Hardware
Middle East and Africa IT Device Market
IT Hardware
Global IT Hardware Market
IT Hardware
Europe IT Device Market
IT Hardware
PC Case Market