
 Stacker Market | 2026-2036
Stacker Market Size, Share, and Industry Trends Forecast 2026-2036
Stacker Market Intelligence
Aftermarket service revenue is fragmenting across OEM-affiliated networks and independent service providers. Liebherr Group leverages its crane and port equipment heritage to anchor premium service contracts in European heavy-lift terminals. Toyota Material Handling sustains channel control through dense dealer networks in North American warehousing. SANY Group competes on manufacturing scale, extending cost-advantaged electric stacker lines into Southeast Asian distribution centers.
A stacker is a pedestrian-operated or rider-operated material handling machine designed to lift, transport, and stack palletized loads vertically using a mast assembly and fork carriage, with lift heights typically ranging from 2.5 meters to over 6 meters and load capacities from 1 to 4 tons. Its primary industrial purpose centers on vertical storage density optimization in warehouses, retail backrooms, and manufacturing floors where counterbalance forklifts prove excessive. Electric stackers now dominate procurement in warehouse end-use settings, as lithium-ion battery chemistry displaces lead-acid across battery-powered operation mode fleets. Manual and semi-electric variants retain niche positions in retail and small-footprint manufacturing, though margin pools have migrated toward fully electric walkie stackers with integrated lithium platforms.
OSHA workplace safety standards and EPA Tier 4 emissions regulations in the United States compel fleet operators to retire internal-combustion units and document operator certification for powered industrial trucks. ISO 3691 and CE marking requirements in Europe enforce stability testing and electromagnetic compatibility for battery-powered stackers sold across EU member states. Stakeholders must monitor lithium supply chain concentration and emerging solid-state battery timelines to time fleet transition investments.
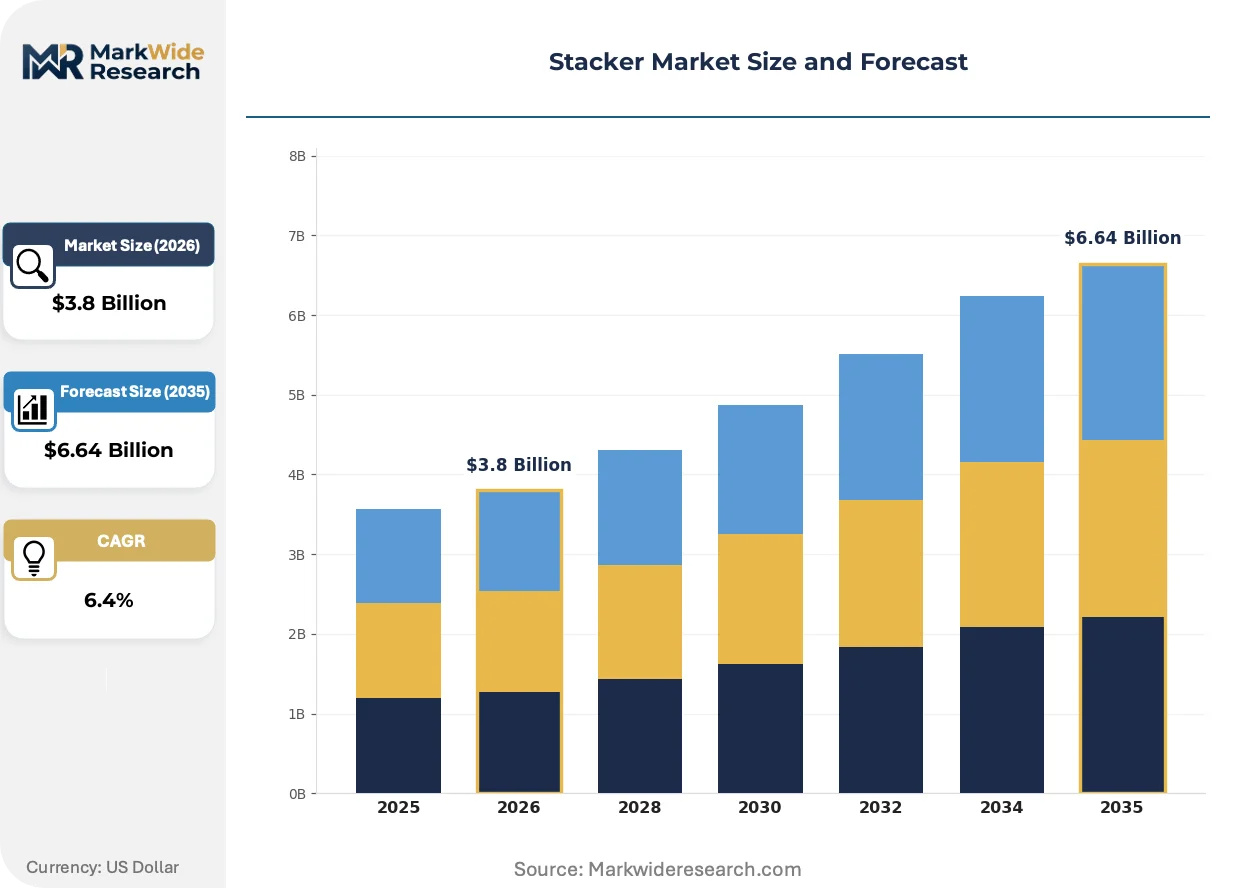
Market Dynamics
Lithium-ion battery chemistry is compressing fleet replacement cycles across warehouse operations, forcing capital allocation toward electrified equipment before residual value of lead-acid fleets fully depreciates.
Growth Catalysts
- EPA Tier 4 emissions standards:US warehouse operators face accelerated retirement deadlines for internal-combustion units, redirecting procurement toward battery-powered alternatives.
- E-commerce fulfillment density:Last-mile distribution centers in Germany's Ruhr corridor are expanding vertical storage to maximize cubic meter utilization.
- ISO 3691 stability mandates:European certification requirements are filtering non-compliant equipment from secondary markets, supporting OEM replacement demand.
Market Restraints
- Lithium supply concentration:Cathode material processing clusters in China's Hunan and Sichuan provinces create input price volatility for battery pack manufacturers.
- Lead-acid residual infrastructure:Existing charging stations and maintenance protocols lock smaller warehousing operations into legacy chemistry despite performance gaps.
- Manual stacker substitution floor:Retail backrooms and micro-fulfillment sites below 500 square meters favor semi-electric units where vertical lift requirements stay below 2.5 meters.
Strategic Opportunities
- Southeast Asian distribution expansion:Vietnam and Indonesia are greenfielding logistics parks without legacy equipment bases, permitting pure electric fleet deployment.
- Solid-state battery timelines:Energy density improvements from emerging cell architectures could extend single-shift operational range beyond current lithium-ion limits.
- Independent service networks:Third-party maintenance providers are capturing aftermarket revenue from OEM-affiliated channels in North American secondary markets.
Industry Challenges
- Operator certification backlogs:OSHA-powered industrial truck licensing delays in US metropolitan markets are extending equipment commissioning timelines.
- Electromagnetic compatibility testing:CE marking requirements for battery-powered stackers are lengthening product launch cycles for manufacturers serving EU member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stacker Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Stacker, Manual Stacker, Semi-Electric Stacker, Walkie Stacker End User: Warehouse, Retail, Manufacturing, Construction Operation Mode: Hand-Powered, Battery-Powered, LPG-Powered, Diesel-Powered Capacity: 1 Ton, 2 Ton, 3 Ton, 4 Ton |
| Companies Covered | Liebherr Group, Terex Corporation, Kalmar, Toyota Material Handling, Hyster-Yale Group Inc., SANY Group, Cargotec Corporation, Crown Equipment Corporation, Konecranes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stacker Market Strategic Shifts & Innovations
Telematics integration is reconfiguring how fleet managers monitor utilization, maintenance intervals, and operator behavior across distributed warehousing networks.
Lithium-iron-phosphate (LFP) cell chemistry is virtualizing the traditional battery room infrastructure. Third-party logistics operators in California and Texas are adopting opportunity-charging protocols that eliminate dedicated battery swap stations. This convergence is compressing facility layout requirements and enabling denser racking configurations in existing square footage.
EU Green Deal industrial decarbonization targets are accelerating diesel equipment phase-outs in European logistics corridors. Germany's KBA is tightening type-approval scrutiny for imported equipment, favoring regional OEMs with established conformity assessment pathways. Warehouse operators in the Netherlands and Belgium are front-loading electric stacker procurement to secure carbon accounting advantages under CSRD reporting mandates.
Equipment-as-a-service contracting is displacing capital purchase models in mid-scale warehousing. Third-party logistics providers in the US Southeast are unbundling maintenance from acquisition, transferring residual value risk to OEM financing arms. This shift concentrates purchasing influence among fleet management platforms rather than individual facility managers.
Stacker Market Segmentation
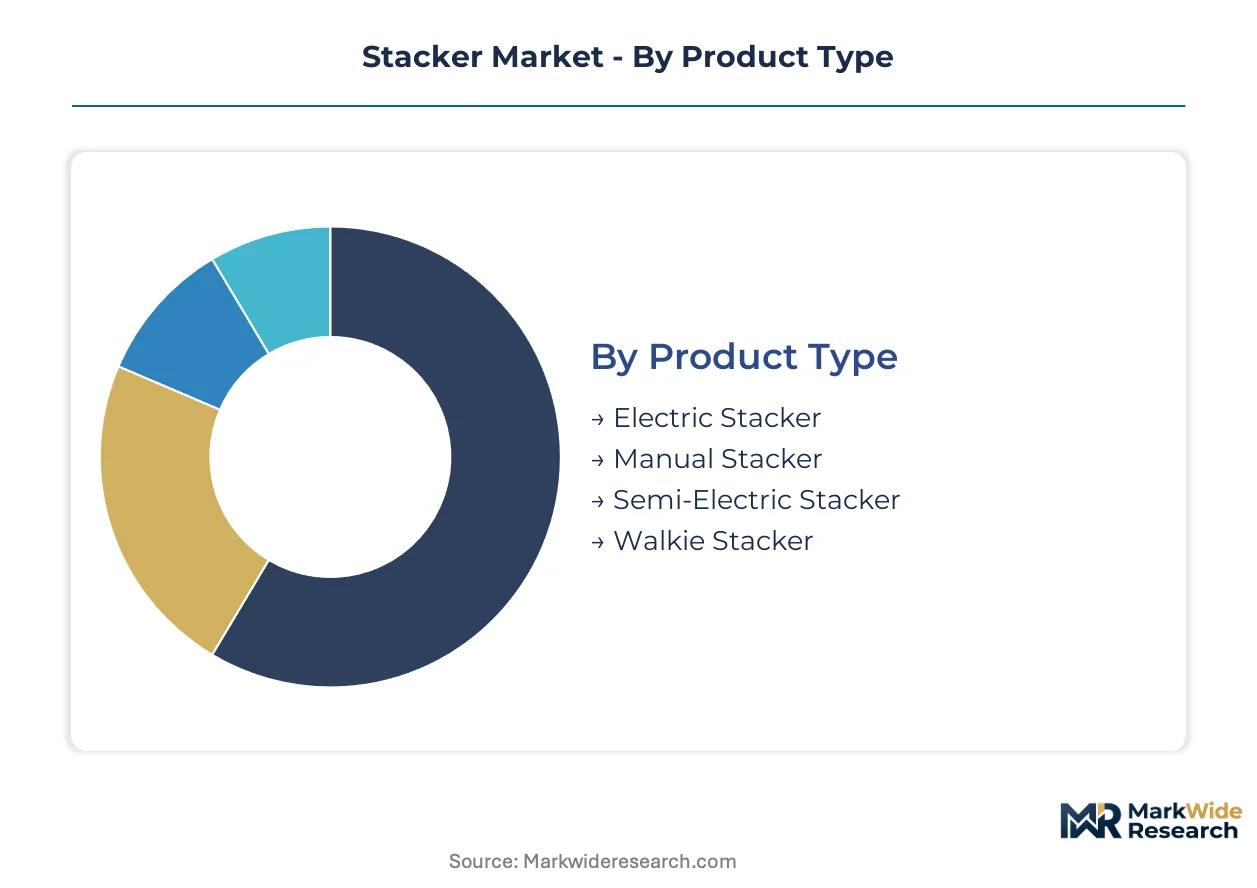
Stacker procurement patterns diverge sharply across facility scale, energy infrastructure, and vertical storage requirements. Segment boundaries are blurring as lithium-ion platforms absorb share from legacy powertrains and manual alternatives.
Product Type:
Mature electric configurations now anchor fleet procurement, while emerging walkie variants capture micro-fulfillment growth pockets.
- Electric Stacker:Fully motorized lift and drive systems utilizing lithium-ion or lead-acid battery packs, with integrated controllers managing hydraulic mast functions. Demand concentrates in German logistics corridors around Düsseldorf and Hamburg, driven by EU Green Deal decarbonization deadlines forcing diesel equipment retirement.
- Walkie Stacker:Pedestrian-operated units with standing operator platforms or walk-behind configurations, optimized for narrow aisle navigation in high-density racking. Southeast Asian distribution centers in Vietnam and Indonesia are greenfielding pure electric fleets without legacy infrastructure constraints.
- Manual Stacker:Hand-pumped hydraulic lift mechanisms requiring no electrical infrastructure, suited to retail backrooms below 500 square meters where vertical lift stays under 2.5 meters.
- Semi-Electric Stacker:Hybrid designs pairing electric lift with manual propulsion, occupying a narrowing price band between fully manual and battery-powered alternatives.
Electric Stacker retains volume leadership; Walkie Stacker holds the steepest expansion curve.
End User:
Cost tier separation runs from capital-intensive warehousing through asset-light retail operations.
- Warehouse:Third-party logistics operators and dedicated distribution facilities deploying fleet-scale electrification with telematics integration for utilization monitoring.
- Retail:Backroom and stock floor applications favoring compact footprints, with semi-electric units dominating where shift intensity remains intermittent.
- Manufacturing:Production floor material flow requiring integration with conveyor systems and automated storage, with 2-ton and 3-ton capacities standard for work-in-process handling.
- Construction:Rough-terrain and outdoor applications retaining diesel and LPG powertrains where emissions regulations permit, though California and Texas operators are piloting electric alternatives for enclosed site work.
Warehouse commands procurement volume; Retail presents the most price-sensitive contracting environment.
Operation Mode:
Supply concentration in battery cell manufacturing is compressing chemistry transition timelines.
- Battery-Powered:Lithium-ion chemistry now dominates warehouse end-use, with LFP cells eliminating dedicated battery swap infrastructure through opportunity-charging protocols.
- Hand-Powered:Zero-energy manual operation for low-throughput environments, retaining niche positioning where electrical infrastructure is unavailable or capital constraints prevail.
- Diesel-Powered:Internal combustion units facing accelerated retirement under EPA Tier 4 emissions standards, with residual demand concentrating in construction and outdoor yard applications.
- LPG-Powered:Liquid petroleum gas alternatives occupying a narrowing middle ground as battery energy density improves and emissions scrutiny intensifies.
Battery-Powered absorbs replacement demand fastest; Hand-Powered defends the lowest installed-base erosion rate.
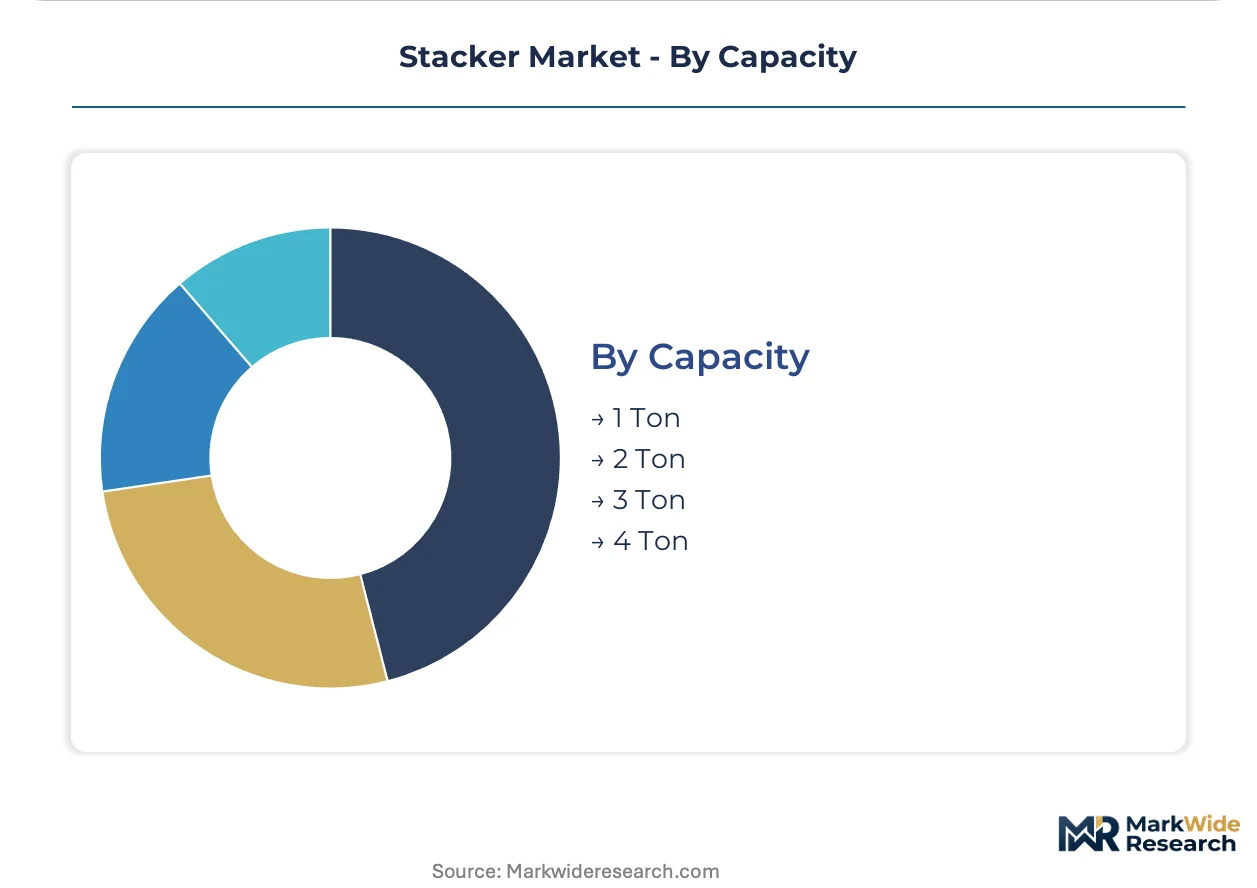
Capacity:
Application-driven loading requirements stratify across vertical storage density and pallet weight specifications.
- 2 Ton:The standard specification for general warehousing and manufacturing floors, balancing mast stability with aisle maneuverability in racking configurations up to 6 meters.
- 1 Ton:Compact units for retail backrooms and light manufacturing, where single-pallet handling and narrow turning radii outweigh lift capacity requirements.
- 3 Ton:Heavy-duty configurations for inbound receiving and outbound shipping docks, where consolidated pallet loads approach maximum rated capacity.
- 4 Ton:Specialized industrial applications including port-adjacent logistics and heavy manufacturing, requiring reinforced mast assemblies and counterweight distribution.
2 Ton retains the broadest installed base; 1 Ton is climbing fastest in micro-fulfillment penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German logistics corridors deploy electric stackers for vertical density optimization, while Southeast Asian greenfield sites adopt battery-powered fleets without legacy infrastructure constraints. US warehouse operators face compressed replacement cycles under emissions deadlines. Chinese manufacturing clusters supply cathode materials that dictate battery pack economics worldwide.
United States
EPA Tier 4 emissions standards are accelerating internal-combustion retirements across third-party logistics fleets. OSHA workplace safety mandates require documented operator certification for powered industrial trucks, extending commissioning timelines in metropolitan markets. California and Texas distribution centers are adopting opportunity-charging protocols that eliminate dedicated battery swap infrastructure.
Germany
EU Green Deal decarbonization targets are forcing diesel equipment phase-outs in logistics corridors around Düsseldorf and Hamburg. KBA type-approval scrutiny favors regional OEMs with established conformity assessment pathways. Warehouse operators in the Ruhr corridor are expanding vertical storage to maximize cubic meter utilization under CSRD reporting mandates.
China
Cathode material processing clusters in Hunan and Sichuan provinces are creating input price volatility for battery pack manufacturers. MIIT industrial policy is channeling investment toward lithium-ion cell capacity expansion. Manufacturing hubs in the Yangtze River Delta are exporting cost-advantaged electric stacker lines to Southeast Asian distribution centers.
Vietnam
Greenfield logistics parks are deploying pure electric fleets without legacy equipment bases or charging infrastructure constraints. National industrial zones are attracting foreign direct investment in automated storage and retrieval systems. Ho Chi Minh City and Hanoi logistics corridors are standardizing on walkie stacker configurations for narrow aisle navigation.
Netherlands
CSRD corporate sustainability reporting mandates are front-loading electric stacker procurement for carbon accounting advantages. Port-adjacent logistics operators in Rotterdam are integrating telematics for fleet utilization monitoring. National distribution networks are optimizing facility layouts around lithium-iron-phosphate opportunity-charging protocols.
Stacker Market Key Industry Players
Capability concentration sits with European and Japanese OEMs anchored in premium service ecosystems; scale advantage sits with Chinese manufacturers leveraging integrated battery supply chains. The vendor base stratifies across three tiers: diversified industrial conglomerates with port equipment heritage, dedicated material handling specialists with dense dealer networks, and emerging Asian fabricators competing on manufacturing scale. Two dominant competitive moves are reshaping positioning: telematics integration for fleet management platform control, and equipment-as-a-service contracting that transfers residual value risk to OEM financing arms.
Within the diversified industrial tier, Liebherr Group and Cargotec Corporation exemplify players leveraging crane and port equipment heritage to anchor premium service contracts in heavy-lift terminals. Toyota Material Handling occupies a position representing dedicated material handling specialists with established channel control through dense dealer networks. SANY Group sits within the scale-driven archetype, extending manufacturing volume advantages into cost-sensitive Southeast Asian markets. These three anchors illustrate how geographic origin and corporate structure map to divergent competitive vectors without requiring identical strategic postures.
| Leading Market Players |
|---|
| Liebherr Group |
| Terex Corporation |
| Kalmar |
| Toyota Material Handling |
| Hyster-Yale Group Inc. |
| SANY Group |
| Cargotec Corporation |
| Crown Equipment Corporation |
| Konecranes |
| Others |
Cost & Logistics Intelligence
Hunan and Sichuan cathode processing clusters dictate battery pack economics for electric stacker OEMs, with capacity utilization swings translating directly into downstream procurement leverage for fleet operators. Lithium-iron-phosphate cell chemistry standardization is compressing price dispersion across premium and economy tiers as manufacturing scale effects override brand premiums.
Pricing Analysis
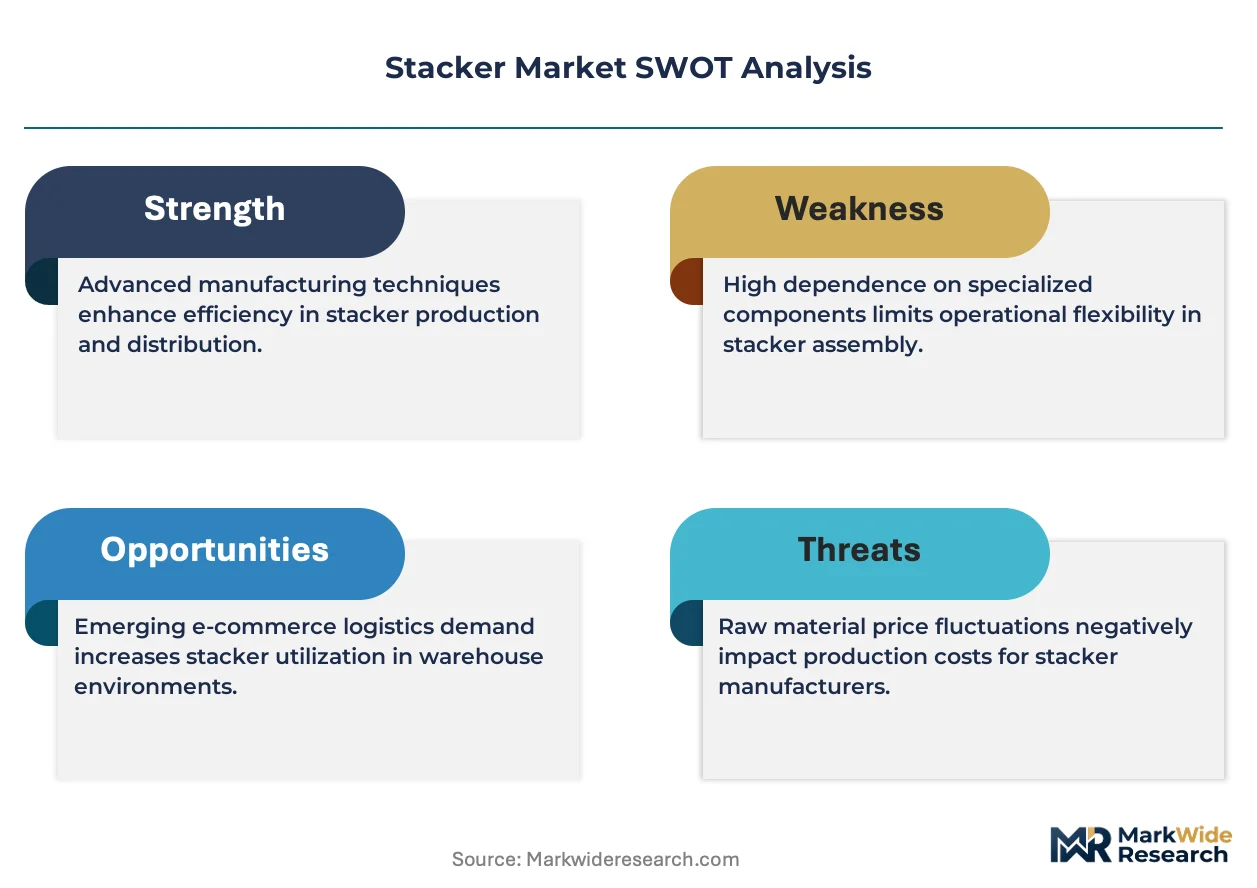
Long-term offtake contracts dominate fleet-scale procurement, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and after-sales service bundling. Price differentiation stems from ISO 3691 compliance tier and telematics integration depth. Cost compression in economy-tier walkie stackers is intensifying because Chinese manufacturing scale feeds Southeast Asian greenfield demand. Retail backroom operators exhibit highest price sensitivity; heavy-lift terminal operators in European ports show lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for battery-powered equipment manufacturers. Cathode material processing concentrates in China, South Korea, and Japan; hydraulic mast assemblies source from Germany and Italy. Raw material dependencies span lithium carbonate, rare-earth magnets, and high-grade steel. Single-source vulnerability in solid-state electrolyte precursors threatens next-generation product timelines. Distribution runs through OEM-affiliated dealer networks in North America and independent service providers in European secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified lithium-ion battery integration expertise sits in short supply relative to fleet electrification timelines, constraining OEM capacity to capture replacement demand from lead-acid legacy bases. This capability gap favors incumbents with captive cell partnerships and punishes assemblers dependent on spot market battery procurement.
For Market Incumbents: Pre-empt emerging Asian fabricators by anchoring backward integration into LFP cell supply through joint ventures in Yangtze River Delta manufacturing hubs. Defend channel control against independent service network encroachment by unbundling maintenance contracts from equipment sales. Threat vector: SANY Group manufacturing scale feeding cost-advantaged electric lines into Vietnamese logistics parks. For New Entrants and Emerging Players: Indonesian greenfield logistics corridors offer the most penetrable geography for pure electric fleet deployment without legacy infrastructure displacement costs. Target 1-ton walkie stacker specifications for micro-fulfillment sites below 500 square meters where incumbent coverage remains thin. Go-to-market angle: equipment-as-a-service contracting transferring residual value risk to balance-sheet-light operators. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming material handling divisions lacking telematics integration capabilities. Long-term viability hinges on lithium chemistry transition execution rather than hydraulic engineering heritage. Signal to watch: solid-state battery pilot announcements from tier-one cell manufacturers as inflection indicator for next-generation range extension.| Strategic Initiative | Industry Significance |
|---|---|
| Lithium-Ion Cell Backward Integration | Yangtze River Delta joint ventures secure cathode supply for OEM cost parity. |
| Telematics Platform Integration | Fleet management software anchors recurring revenue against hardware commoditization. |
| Equipment-as-a-Service Contracting | OEM financing arms capture residual value risk from capital-constrained logistics operators. |
| Southeast Asian Manufacturing Footprint | Vietnam and Indonesia greenfield sites bypass legacy lead-acid infrastructure lock-in. |
| ISO 3691 Certification Investment | CE marking pathways filter non-compliant imports from EU secondary markets. |
Research Approach
The analysis maps electric stacker, walkie stacker, manual stacker, and semi-electric sub-sectors, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interviews with fleet operators and dealer network managers combined with secondary validation from SEC 10-K filings, customs and trade data, and EU type-approval databases. Bottom-up unit shipment estimates triangulate against top-down OEM revenue disclosures.
Assumptions held fixed include EPA Tier 4 enforcement timelines and EU Green Deal decarbonization deadlines, while lithium carbonate price trajectories and solid-state battery commercialization curves were varied across sensitivity scenarios. Segmentation dimensions modeled span product type, operation mode, capacity tier, and end-use vertical across the analysis window. CAGRs derive from logistic curve fitting to replacement cycle compression patterns and fleet electrification penetration rates. Industry-specific inputs include OSHA operator certification backlogs and KBA type-approval processing durations.
Practitioners should monitor lithium supply concentration shifts and solid-state battery pilot scale-ups for early signals of chemistry transition timing. Forecasts reflect documented assumptions about regulatory enforcement intensity and cathode material processing capacity expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Vapor Blasting Equipment Market
Material Handling Equipment
Industrial Hose Assemblies Market
Material Handling Equipment
Reach Stacker Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Global Screw Conveyors Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Drum Dumper Market
Material Handling Equipment
Firewood Processors Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Automated Material Handling Systems Market
Material Handling Equipment
Carry Deck Crane Market