
 Trash Chute Market | 2026-2036
Trash Chute Market Size, Share, and Industry Trends Forecast 2026-2036
Trash Chute Market Intelligence
China's manufacturing base for stainless steel fabrication is tilting toward specialized waste infrastructure components. ChuteMaster Manufacturing leverages vertical integration across sheet metal forming and door assembly to control lead times. Kapella anchors its position in European high-rise residential projects through localized fabrication. CHUTES International differentiates via fire-rated intake door engineering that meets stringent building codes.
Trash chutes are enclosed vertical duct systems, typically fabricated from 16-gauge minimum stainless steel or galvanized steel with 24-inch minimum diameter, designed to convey waste from multiple floors to a central collection point. The primary commercial purpose is to reduce labor costs, fire risk, and pest exposure in multi-story buildings. Stainless steel dominates material type selection due to corrosion resistance and NFPA 82 compliance requirements, while plastic segments face margin compression from commodity resin volatility. Recessed installation types command premium positioning in luxury residential towers, whereas surface-mounted systems occupy volume-driven commercial retrofit demand. Airports represent the fastest-growing application segment as terminal expansions prioritize automated waste handling.
NFPA 82, OSHA workplace safety standards, and the International Building Code collectively govern fire dampering, access door specifications, and maintenance protocols across the United States market. EPA hazardous waste handling guidelines further shape product design for hospital and laboratory installations where contaminated material separation is mandatory. Stakeholders must monitor evolving municipal zero-waste mandates that increasingly require chute-integrated sorting mechanisms for recyclables and organics.
Market Dynamics
High-rise residential construction across Southeast Asia and India's urban corridor is compressing specification cycles and forcing stainless steel fabricators to accelerate NFPA 82-compliant fire-rated door engineering.
Growth Catalysts
- NFPA 82 fire safety standards:Tightening material specifications in the United States are mandating 16-gauge minimum stainless steel construction and automated fire dampering systems in new high-rise developments.
- India's Mumbai-Delhi urban corridor:Concentrated high-rise residential tower construction is generating sustained demand for centralized waste infrastructure with integrated sorting capabilities.
- Terminal automation:Airport expansion projects are prioritizing enclosed vertical waste conveyance systems to reduce labor exposure and optimize janitorial workflows in 24-hour operations.
Market Restraints
- Commodity resin volatility:Plastic segment manufacturers face persistent margin compression from unpredictable polypropylene and polyethylene feedstock pricing.
- China stainless steel concentration:Fabrication capacity clusters in Shandong and Jiangsu provinces create geographic supply risk and extended lead time exposure for distant markets.
- Fire dampering complexity:NFPA 82's evolving fusible link temperature requirements and interconnection protocols with building management systems extend engineering validation timelines.
Strategic Opportunities
- Vietnam and Indonesia high-rise pipeline:Underpenetrated Southeast Asian markets with accelerating residential tower permits represent whitespace for chute-integrated recycling separation systems.
- Municipal zero-waste mandates:Jurisdictions in California, New York, and the European Union are requiring source-separated organics and recyclables collection, creating demand for multi-stream chute configurations.
- IoT sensor convergence:Integration of fill-level monitoring and predictive maintenance algorithms with stainless steel intake doors enables outcome-based service contracts for facility managers.
Industry Challenges
- Welding certification scarcity:Qualified pressure-vessel and sanitary-grade stainless steel welders remain concentrated in legacy manufacturing regions, constraining capacity expansion.
- Retrofit integration friction:Surface-mounted chute installations in existing commercial buildings require structural reinforcement and fire-rated shaft enclosure modifications that compress project margins.
- Multi-jurisdiction code alignment:Reconciling NFPA 82, International Building Code, and local amendments across municipal permitting offices extends specification approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trash Chute Market |
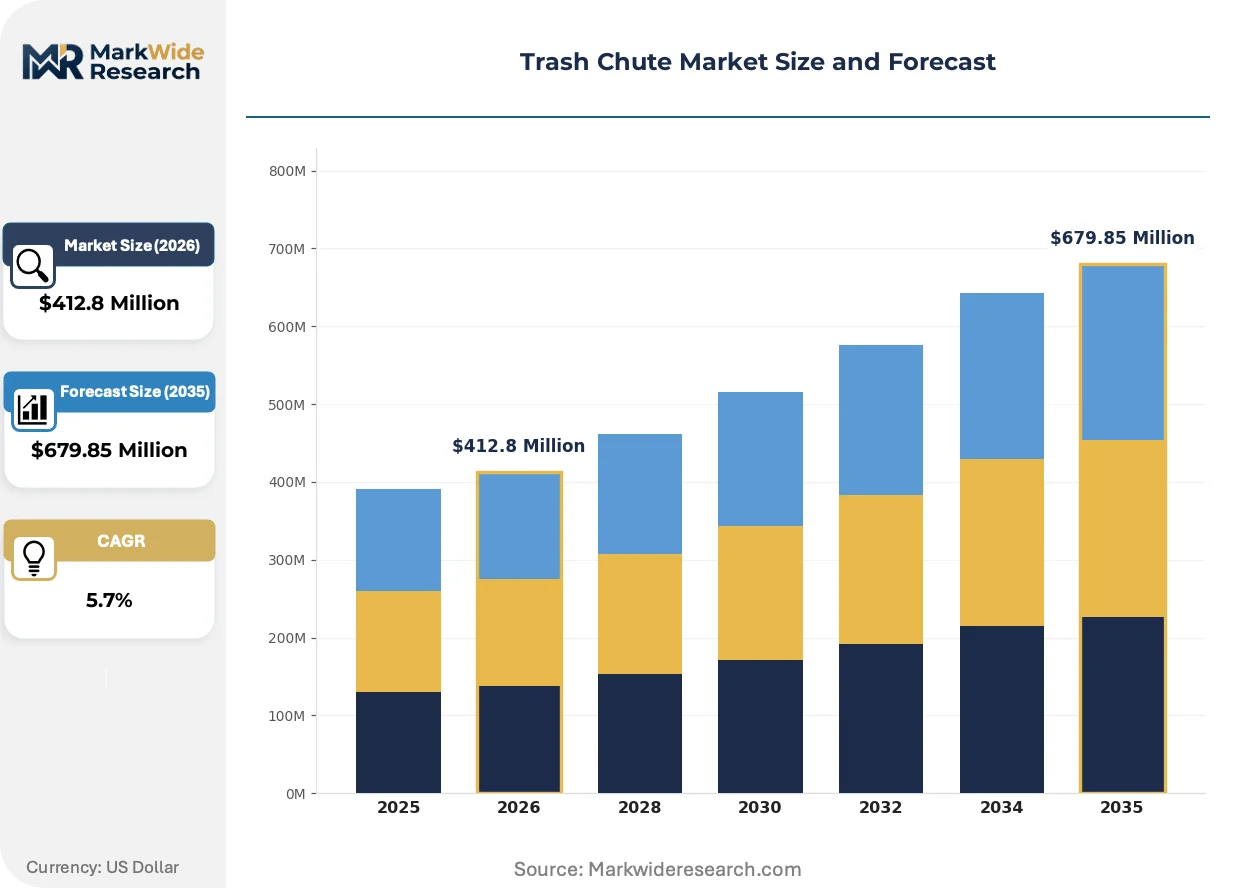
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $679.85 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
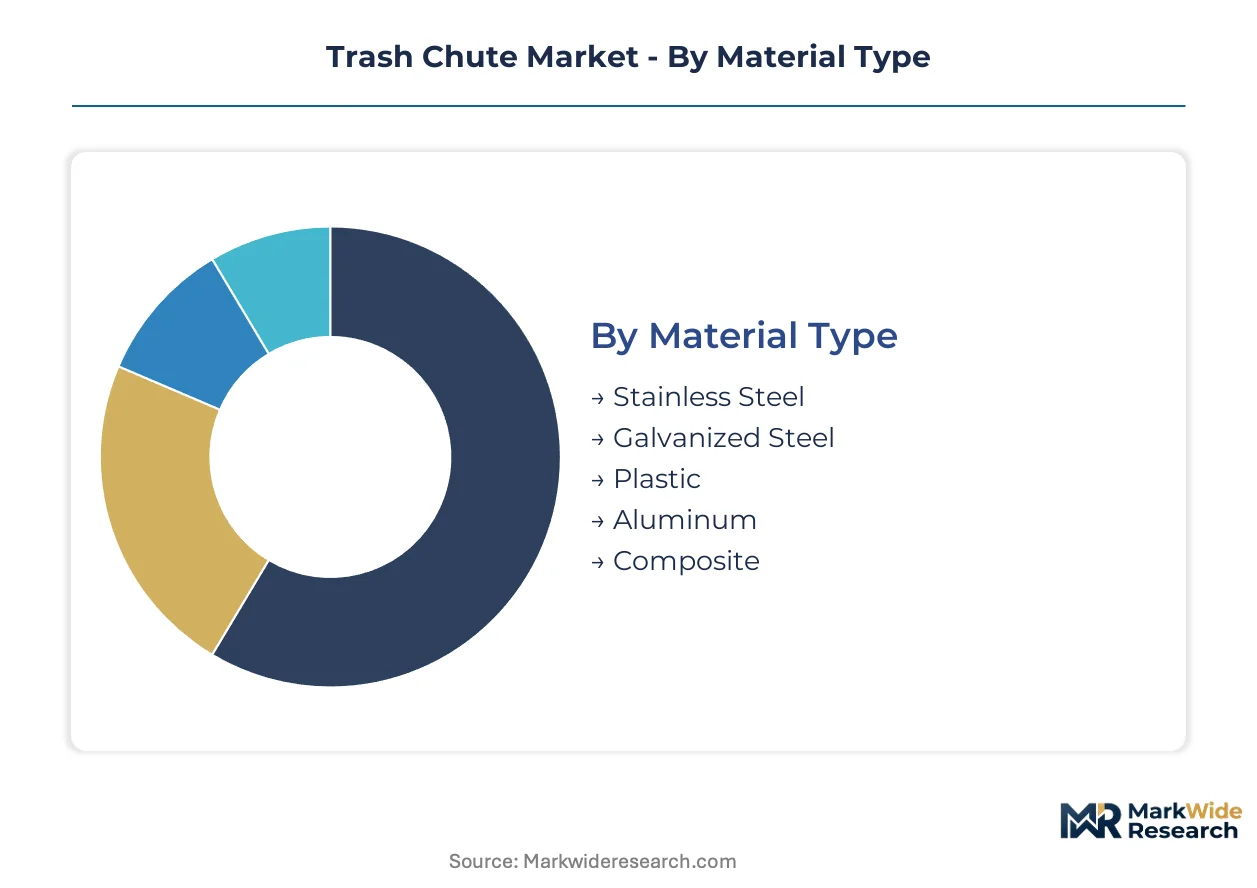
| Segmentation | Material Type: Stainless Steel, Galvanized Steel, Plastic, Aluminum, Composite Installation Type: Surface Mounted, Recessed, Modular, Integrated, Freestanding Application: Commercial Buildings, Residential Complexes, Hospitals, Educational Institutions, Airports End User: Property Management Firms, Facility Operators, Waste Collection Services, Maintenance Contractors |
| Companies Covered | ChuteMaster Manufacturing, Kapella, CHUTES International, American Chute, Midland Chutes, Wilkinson Hi-Rise, Rockwell Chute, Qingdao Chute Equipment, Century Chutes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trash Chute Market Strategic Shifts & Innovations
Automation and sensor integration are compressing the traditional specification playbook, while regulatory fragmentation across fire safety and waste diversion mandates forces manufacturers to engineer modular, code-adaptable platform architectures.
Electro-polished 316L stainless steel chute liners with integrated antimicrobial surface treatments are rendering obsolete traditional galvanized steel installations in healthcare and food-service verticals. Hospital facility managers in the United States are specifying these upgraded materials to satisfy Joint Commission infection control protocols. The shift is compressing price-competitive bidding for standard-grade systems in institutional segments.
REACH chemical substance restrictions and the EU Green Deal's embodied carbon reporting requirements are reshaping material sourcing decisions for European project developers. Stainless steel suppliers must now document recycled content percentages and Scope 3 emissions across melting and finishing operations. German and French high-rise residential developers are prioritizing suppliers with Environmental Product Declarations certified by third-party verifiers.
Facility management procurement teams are unbundling after-sales service from initial equipment purchase, forcing chute manufacturers to compete on lifecycle maintenance contracts rather than upfront capital cost alone. Third-party technical service providers in Singapore and Dubai are capturing recurring revenue streams that historically anchored manufacturer profitability. This shift is most pronounced in airport and hospitality verticals where uptime guarantees carry operational penalties.
Trash Chute Market Segmentation
Trash chute procurement patterns diverge sharply across material grades and installation architectures. Facility managers segment suppliers by lifecycle service intensity rather than capital cost alone.
Material Type:
After-sales service intensity varies dramatically by material grade, with stainless steel demanding specialized welding recertification and plastic requiring resin-sourcing contingency planning.
- Stainless Steel:Fabricated from 16-gauge minimum 304 or 316L grade with NFPA 82 fire dampering compatibility. Hospital and airport terminal specifications in the United States concentrate demand here due to Joint Commission infection control mandates and FAA fire safety protocols.
- Galvanized Steel:Zinc-coated carbon steel offers intermediate corrosion resistance at lower capital cost. Commercial retrofit projects across India's Mumbai-Delhi urban corridor specify this grade where budget constraints override lifecycle durability calculations.
- Plastic:Polypropylene and polyethylene constructions face margin pressure from commodity resin volatility.
- Aluminum:Lightweight extrusions suit freestanding and modular configurations where structural load limits constrain design.
- Composite:Fiber-reinforced polymer blends target specialized acoustic dampening and chemical resistance applications.
Stainless steel holds the largest share; momentum sits with composite materials gaining specification in noise-sensitive healthcare environments.
Installation Type:
Cost tier stratification separates premium recessed systems from volume-driven surface-mounted alternatives, with modular architectures capturing mid-market flexibility demand.
- Surface Mounted:Exposed duct configurations attach directly to structural elements without shaft enclosure modifications. Facility operators in Southeast Asian high-rise retrofits favor this approach where core drilling and fire-rated shaft construction would trigger permitting delays.
- Recessed:Flush-mounted intake doors integrate with finished wall assemblies in luxury residential towers. Developers across Singapore and Dubai specify these for aesthetic cohesion with premium interior design schemes.
- Modular:Prefabricated sectional assemblies compress on-site installation timelines.
- Integrated:Chute systems bundled with building management system connectivity and automated sorting mechanisms.
- Freestanding:Self-supporting structures for atrium and lobby placements where vertical shaft routing is impractical.
Surface mounted dominates volume; integrated configurations are climbing the fastest as municipal zero-waste mandates proliferate.
Application:
Customer type segmentation reveals divergent procurement authority structures, with property management firms prioritizing capital efficiency and facility operators optimizing for uptime guarantees.
- Commercial Buildings:Office and retail multi-tenant properties specify standardized intake door configurations with centralized compaction equipment. Property management firms across Germany and France increasingly require Environmental Product Declaration documentation to satisfy EU Green Deal procurement guidelines.
- Airports:24-hour terminal operations demand automated waste handling with minimal janitorial labor exposure. Expansion projects at hub facilities in the United States, UAE, and Singapore are expanding most quickly as aviation traffic recovers.
- Residential Complexes:High-rise towers with centralized collection infrastructure.
- Hospitals:Infection control protocols mandate electro-polished 316L liners with antimicrobial surface treatments.
- Educational Institutions:Campus housing and administrative buildings with seasonal occupancy variation.
Commercial buildings hold the largest share; airports represent the steepest expansion trajectory.
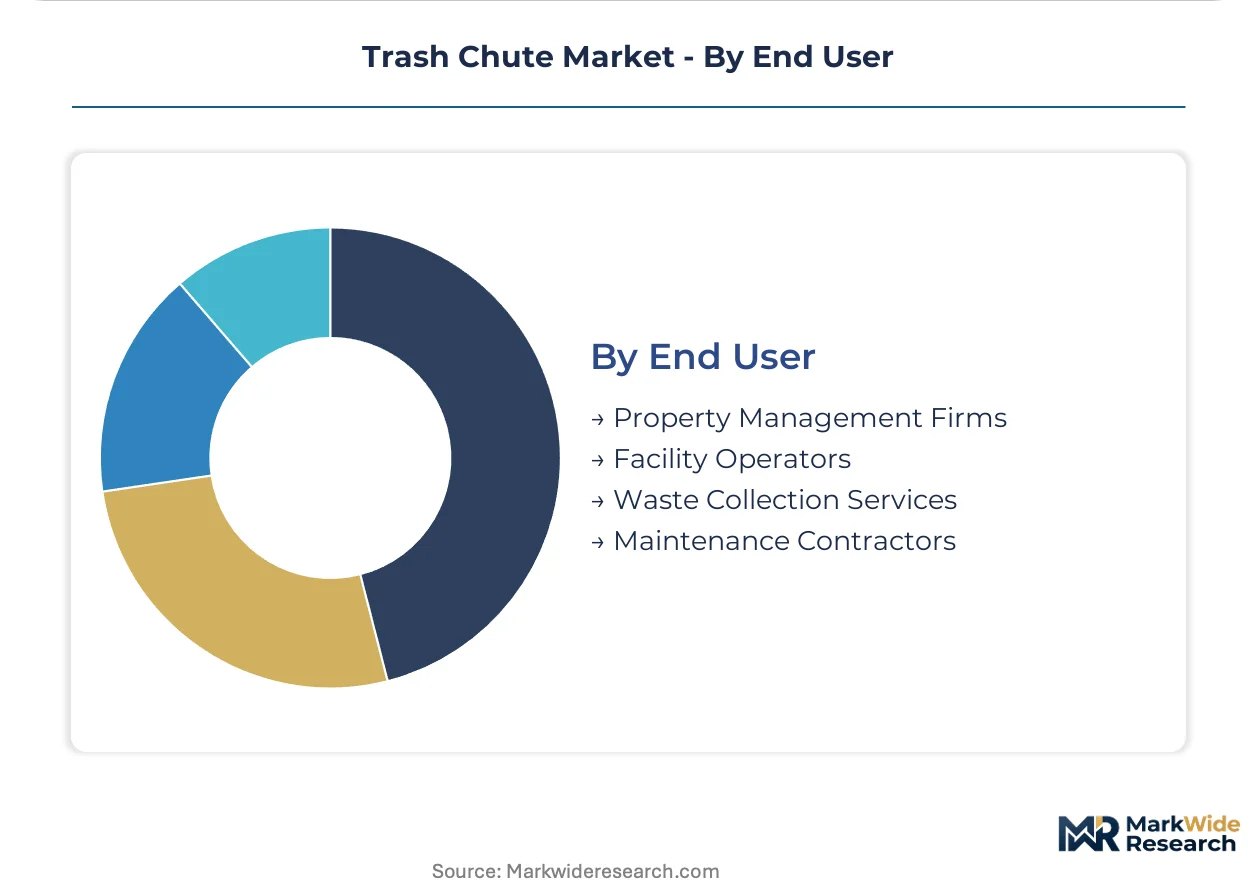
End User:
Supply concentration shapes vendor selection criteria, with waste collection services driving standardization and maintenance contractors capturing recurring revenue streams.
- Property Management Firms:Multi-tenant building operators prioritize capital expenditure control and vendor consolidation across portfolios. Large-scale operators in the United States unbundle equipment purchase from service contracts, compressing manufacturer margins on initial sales.
- Facility Operators:Airport and hospitality verticals demand outcome-based uptime guarantees with operational penalty clauses. Technical service providers in Singapore and Dubai have captured this recurring revenue, displacing traditional manufacturer service attachments.
- Waste Collection Services:Haulage companies specify chute-compactor compatibility with their vehicle fleets and container standards.
- Maintenance Contractors:Independent service providers performing NFPA 82-mandated annual inspections and fire damper testing.
Property management firms hold the largest share; facility operators are gaining procurement authority fastest as service unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NFPA 82 fire safety standards in the United States anchor regulatory development across high-rise waste infrastructure. Stainless steel fabrication clusters in Shandong and Jiangsu provinces supply distant markets with extended lead times. India's urban corridor from Mumbai to Delhi concentrates residential tower construction with integrated sorting requirements.
United States
High-rise residential development in Miami and New York City drives specification cycles for fire-rated intake door systems. NFPA 82 mandates 16-gauge minimum stainless steel construction with automated fire dampering in new developments. ChuteMaster Manufacturing and CHUTES International anchor fabrication capacity across the Northeast and Southeast corridors.
China
Shandong and Jiangsu provinces host concentrated stainless steel sheet metal forming capacity for waste infrastructure components. GB standards and MIIT industrial guidelines shape material certification requirements for export-bound fabrication. Qingdao Chute Equipment exemplifies coastal manufacturing positioning serving Southeast Asian project pipelines.
India
The Mumbai-Delhi urban corridor generates sustained demand for centralized waste collection systems in residential towers exceeding 30 stories. BIS certification requirements and municipal zero-waste mandates in Maharashtra and Delhi NCR shape multi-stream chute specifications. Local fabricators compete with Chinese imports on galvanized steel retrofits for budget-constrained developments.
Germany
REACH chemical substance restrictions and the EU Green Deal's embodied carbon reporting requirements reshape material sourcing for high-rise residential developers. Environmental Product Declarations certified by third-party verifiers dominate procurement criteria in Berlin and Frankfurt tower projects. Kapella anchors localized fabrication serving premium European specifications.
Singapore
Luxury residential towers in the Marina Bay and Orchard Road districts specify recessed intake door configurations for aesthetic cohesion with premium interiors. Third-party technical service providers capture recurring maintenance revenue streams historically attached to manufacturer sales. Airport terminal expansions at Changi prioritize automated waste handling for 24-hour operational continuity.
Trash Chute Market Key Industry Players
Vertically integrated fabricators and specialized regional suppliers split the market across material grades and service intensity tiers. The vendor base concentrates around stainless steel sheet metal forming expertise with in-house door assembly capabilities. Two archetypes dominate: scale-driven manufacturers controlling lead times through captive supply chains, and premium-tier specialists engineering fire-rated configurations for stringent building codes. Competitive moves center on geographic expansion into underpenetrated Southeast Asian markets and unbundling of after-sales service from initial equipment purchase.
Among United States-based fabricators, ChuteMaster Manufacturing and CHUTES International exemplify the vertically integrated archetype with control over sheet metal forming and door assembly operations. Kapella occupies a position within the European premium-tier segment serving high-rise residential projects through localized fabrication. Qingdao Chute Equipment represents Chinese manufacturing scale positioned to supply distant markets with standardized configurations.
| Leading Market Players |
|---|
| ChuteMaster Manufacturing |
| Kapella |
| CHUTES International |
| American Chute |
| Midland Chutes |
| Wilkinson Hi-Rise |
| Rockwell Chute |
| Qingdao Chute Equipment |
| Century Chutes |
| Others |
Cost & Logistics Intelligence
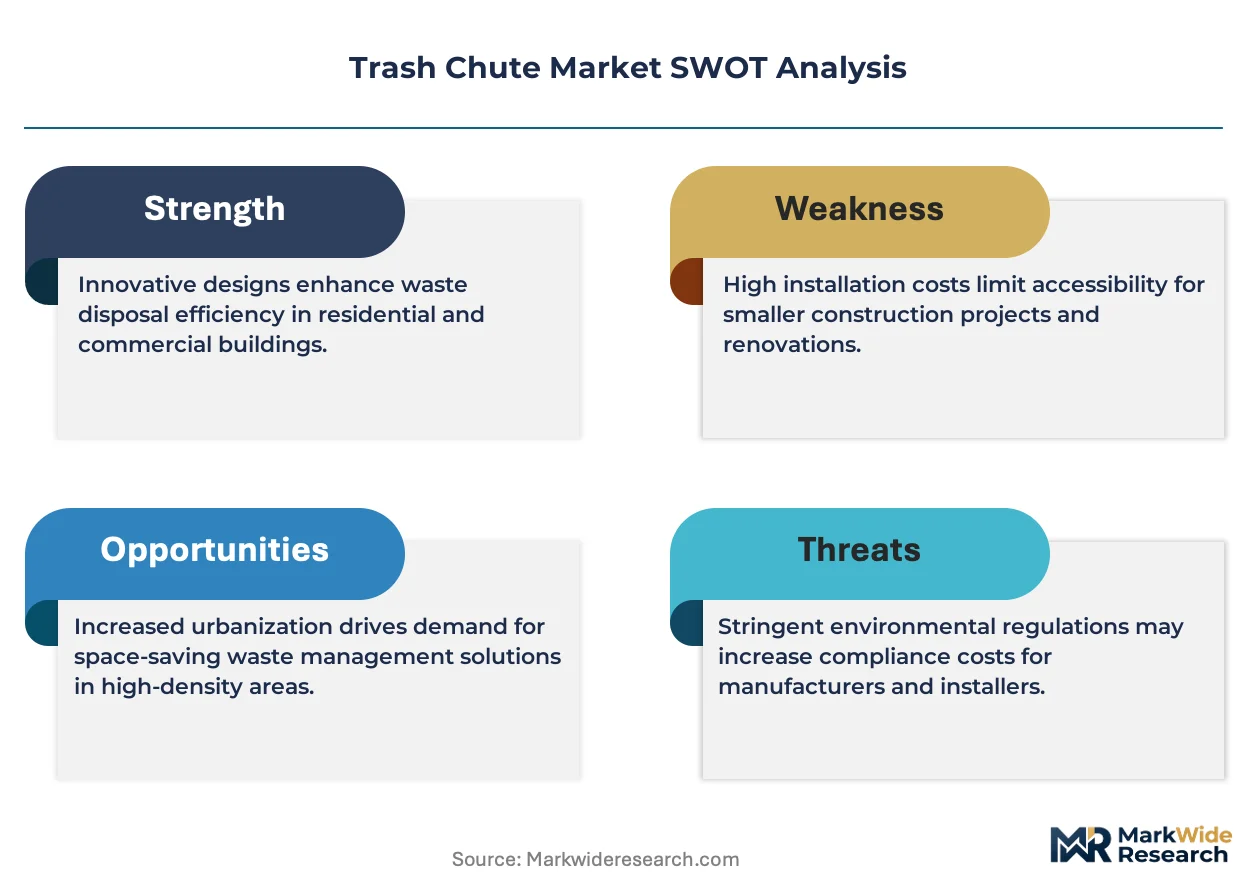
Shanghai-to-Singapore freight corridors transmit cost volatility from Chinese stainless steel mills directly into Southeast Asian project bids, compressing margins for distributors while enabling sharp price differentiation between NFPA 82-certified systems and commodity-grade alternatives. This logistics tension concentrates pricing power with fabricators possessing captive sheet metal forming capacity, leaving import-dependent intermediaries exposed to both freight surges and downstream buyer consolidation.
Pricing Analysis
Price spreads between Chinese-origin galvanized steel chutes and European-fabricated 316L stainless steel systems exceed three-to-one on a per-linear-foot basis across Mumbai-Delhi corridor projects. Three-tier pricing structure across premium electro-polished hospital-grade, standard fire-rated residential, and economy galvanized retrofit levels dominates procurement frameworks. Cost compression in the plastic segment stems from polypropylene resin volatility, eroding manufacturer margins regardless of volume scale. Property management firms in India's urban corridor exhibit highest price sensitivity, while airport facility operators prioritize lifecycle service guarantees over capital expenditure minimization.
Supply Chain Analysis
Hot-rolled stainless steel coil from Shandong and Jiangsu provinces feeds fabrication clusters serving export markets across Southeast Asia, India, and the Middle East. Raw material dependencies center on nickel-ore sourcing from Indonesia and the Philippines, chrome from South Africa, and specialized fire-rated damper components from German and Italian suppliers. Single-source vulnerability concentrates in qualified pressure-vessel welders certified for NFPA 82-compliant intake door assembly, constraining capacity expansion regardless of steel availability. Distribution runs through manufacturer-direct project sales for large developments, with regional distributors capturing retrofit and maintenance contract flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trash chute market sits in early-cycle expansion as municipal zero-waste mandates across California, New York, and the European Union force retrofits of legacy single-stream buildings toward multi-stream configurations with integrated sorting. This regulatory tailwind compounds underlying high-rise residential construction velocity in underpenetrated Southeast Asian markets.
For Market Incumbents: Harden fire-rated engineering capabilities against emerging Chinese competitors by deepening backward integration into stainless steel coil slitting and automated door assembly. Invest in IoT sensor integration partnerships to capture facility management service contracts that third-party technical providers in Singapore and Dubai currently displace. Certification investment in EU Environmental Product Declarations represents the critical lever for defending premium positioning against galvanized steel alternatives in European high-rise residential specifications. For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Indonesia high-rise residential pipelines where localized fabrication capacity remains scarce and Chinese import lead times create service gaps. Target the modular installation segment for budget-constrained commercial retrofits across India's Mumbai-Delhi corridor, where surface-mounted systems bypass structural reinforcement permitting delays. A go-to-market angle anchored in rapid-deployment prefabricated assemblies with bundled maintenance contracts bypasses incumbent advantages in captive steel supply. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building products conglomerates with underperforming waste infrastructure divisions lacking vertical integration into sheet metal forming. Long-term viability favors specialists with in-house 16-gauge stainless steel fabrication and certified fire dampering engineering, as regulatory complexity rises across NFPA 82, REACH, and municipal zero-waste mandates. The signal to watch is consolidation of third-party technical service providers in Dubai and Singapore, which would indicate manufacturer attempts to recapture recurring revenue streams currently lost to unbundling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Coil Processing | Captive slitting capacity insulates margin from Shandong-Jiangsu supply volatility and freight surges. |
| IoT Sensor Platform Development | Fill-level monitoring enables outcome-based service contracts with airport facility operators demanding uptime guarantees. |
| Multi-Stream Chute Configuration Engineering | Integrated sorting mechanisms satisfy California and EU municipal zero-waste mandates driving retrofit demand. |
| Environmental Product Declaration Certification | Third-party verified embodied carbon documentation unlocks Berlin and Frankfurt premium residential specifications. |
| Southeast Asian Fabrication Footprint Expansion | Localized production in Vietnam or Indonesia compresses lead times against Chinese import dependence. |
Research Approach
Operator-level perspectives from facility managers at airport and hospitality verticals, procurement directors at property management firms, stainless steel fabrication plant engineers, and fire safety code consultants anchored the qualitative base. These primary interviews combined with secondary validation from NFPA 82 technical committee documentation, EPA hazardous waste handling guidelines, BIS certification records, and EU Green Deal procurement directives. Customs data from Indian and Southeast Asian import registries, SEC filings from diversified building products manufacturers, and project pipeline databases for high-rise residential construction across the Mumbai-Delhi corridor provided quantitative anchors. Bottom-up project-level demand estimation triangulated against top-down steel consumption forecasts for waste infrastructure applications.
Scenario-bracketing around resin price volatility, freight rate fluctuations, and regulatory adoption timelines for zero-waste mandates bounded the projection envelope across the analysis window. Segmentation dimensions modeled include material grade tier, installation architecture, application vertical, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to project pipeline data, cross-referenced against stainless steel consumption trends in building construction and airport capital expenditure cycles. Industry-specific forecast inputs incorporated NFPA 82 amendment trajectories and municipal waste diversion policy adoption curves.
Stress conditions across nickel-ore supply disruptions, qualified welder availability constraints, and fire damper interconnection protocol changes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding continued high-rise residential construction velocity in Southeast Asia and sustained enforcement of municipal zero-waste mandates. Cross-checking against IEA embodied carbon tracking for building materials and airport authority capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Counterweights Market
Material Handling Equipment
Lifting Machinery Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Vapor Blasting Equipment Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Global Metal Shredder Machine Market
Material Handling Equipment
Rotating Fork Clamp Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Global Metal Expansion Joints Market
Material Handling Equipment
Global Industrial Weighing Equipment Market
Material Handling Equipment
Lever Hoist Market