
 North America Screw Conveyor Market | 2026-2036
North America Screw Conveyor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Screw Conveyor Market Analytics
Carbon steel auger flights in standard-duty applications is broadening the addressable market for cost-sensitive buyers in agriculture and construction. KWS Manufacturing leverages its vertically integrated foundry operations to control raw material costs across the Great Plains. Flexicon Corporation sustains a defensible position in flexible screw systems for powder transfer through proprietary drive-head engineering. Industrial Screw Conveyors Inc. anchors its revenue in custom-fabricated stainless steel units for dairy and meat processors requiring USDA-compliant finishes.
A screw conveyor is a helical flighting mechanism rotating within a stationary trough or tube, engineered to move bulk solids along an inclined, vertical, or horizontal path at controlled rates typically measured in cubic feet per hour. The device serves as a sealed, dust-contained method for transporting powders, granules, flakes, and semi-solids across continuous-process industries. Standard horizontal units retain the largest installed base but generate thinner margins due to commoditized fabrication; flexible configurations capture premium pricing in powder transfer where layout constraints prohibit rigid ducting. Stainless steel material grades dominate food processing and pharmaceutical installations where surface roughness and corrosion resistance carry regulatory weight, while carbon steel persists in mining and construction applications where abrasion tolerance outweighs sanitary requirements.
USDA sanitary equipment design standards and FDA food contact surface regulations shape procurement specifications for processors handling meat, dairy, and ready-to-eat products across the United States. OSHA machine guarding directives and EPA dust emission thresholds further constrain conveyor enclosure and ventilation designs in grain handling and mineral processing facilities. Stakeholders must weigh total cost of ownership against compliance exposure when specifying material grades and seal configurations for multi-decade equipment lifecycles.
Market Dynamics
USDA sanitary equipment design standards and FDA food contact surface regulations are compressing replacement cycles across meat and dairy processing facilities, forcing capital allocation toward stainless steel configurations that satisfy surface roughness and cleanability mandates.
Growth Catalysts
- USDA Sanitary Equipment Standards:Meat processors across the Midwest are retrofitting aging carbon steel lines with 304 and 316-grade stainless units to satisfy surface finish requirements and avoid inspection penalties.
- Grain Handling Modernization:Elevator operators in Kansas, Nebraska, and Iowa are replacing worn auger systems with enclosed dust-tight designs to meet EPA particulate emission thresholds.
- Powder Transfer Automation:Pharmaceutical compounders in New Jersey and North Carolina are specifying flexible screw configurations for contained material movement between process suites.
Market Restraints
- Stainless Steel Input Volatility:Nickel and chromium price swings from Indonesian and South African supply nodes compress margin predictability for fabricators quoting multi-month projects.
- Specialized Welding Labor Scarcity:Certified sanitary welders capable of orbital TIG passes on 20Ra finishes command wage premiums that extend lead times for custom dairy units.
- Pneumatic Conveying Substitution:Dense-phase and dilute-phase pneumatic systems capture powder transfer applications where layout flexibility outweighs mechanical simplicity.
Strategic Opportunities
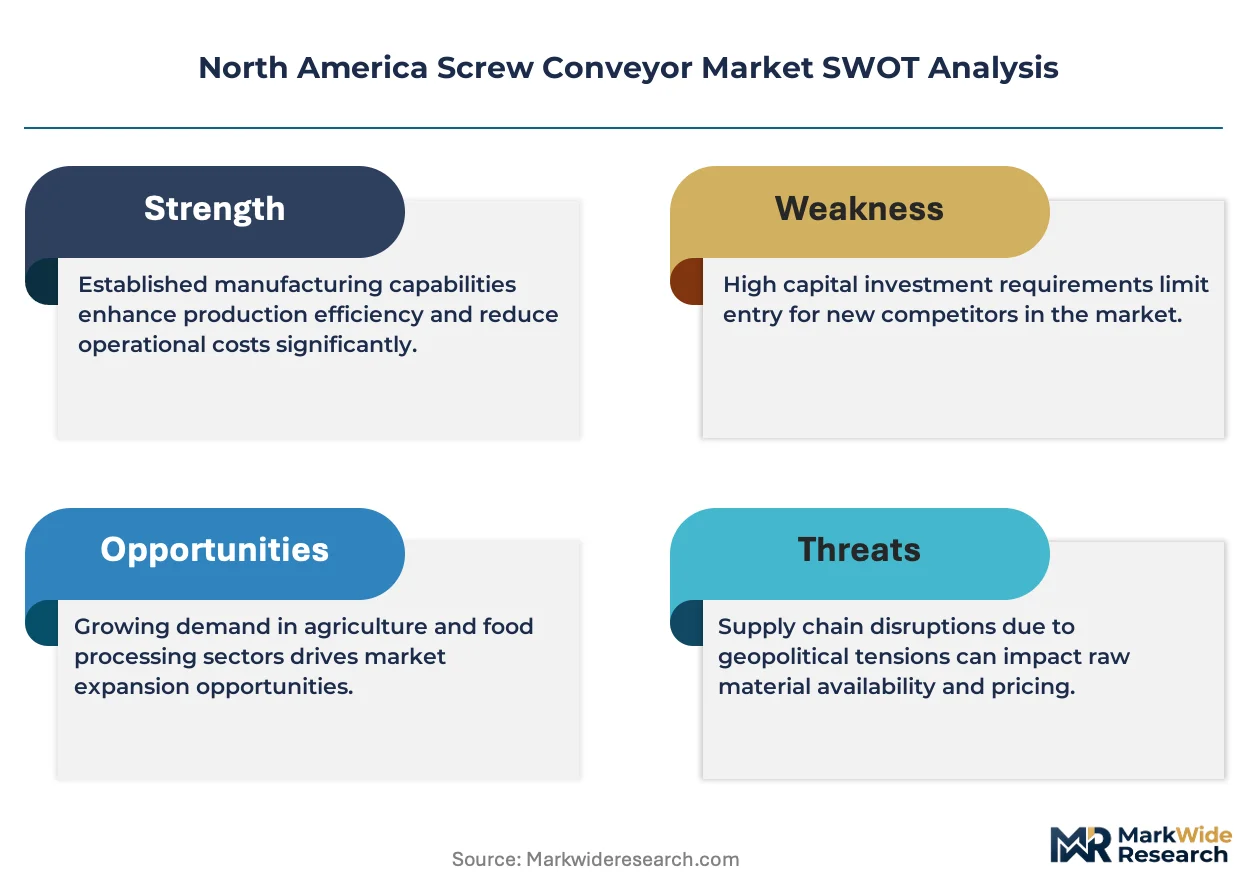
- Canadian Prairie Expansion:Saskatchewan and Alberta grain handlers are importing U.S.-fabricated enclosed screw systems to replace open belt conveyors and reduce dust exposure liability.
- Bioplastics Compounding:Corn starch and PLA pellet producers in the U.S. Southeast are specifying heat-jacketed auger troughs for temperature-controlled resin transfer to extrusion lines.
- OSHA Silica Rule Enforcement:Frac sand and mineral processors in Texas and Wisconsin are retrofitting with sealed screw configurations to satisfy respirable crystalline silica exposure limits.
Industry Challenges
- Sanitary Welding Certification Bottlenecks:Third-party validation of 3A and USDA-compliant surface finishes adds 4-6 weeks to project timelines, straining just-in-line capital deployment schedules.
- Legacy DCS Integration Complexity:Brownfield food plants running Allen-Bradley PLC-5 architectures face protocol translation costs when connecting modern VFD-driven screw systems to existing control networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Screw Conveyor Market |
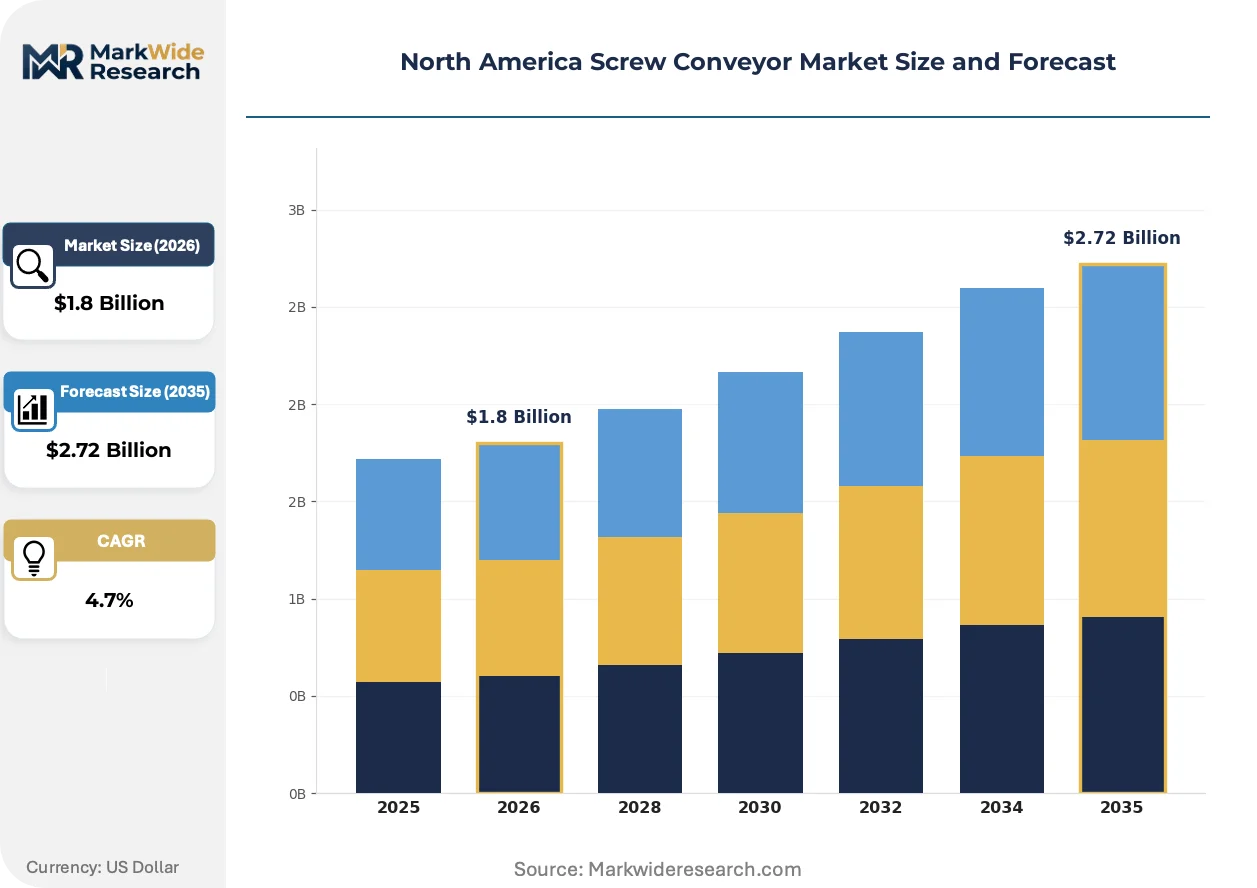
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Flexible, Vertical, Horizontal End User: Agriculture, Food Processing, Mining, Construction Material: Stainless Steel, Plastic, Carbon Steel, Alloy Application: Bulk Handling, Powder Transfer, Waste Management, Granular Transport |
| Companies Covered | Screw Conveyor Corporation, Industrial Screw Conveyors Inc., KWS Manufacturing, Astro Metal Craft, Cyclonaire Corporation, Flexicon Corporation, Conveyor Engineering & Manufacturing, Metzgar Conveyor Co., Continental Screw Conveyor, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Screw Conveyor Market Evolving Landscape
Automation architectures and material science advances are reconfiguring how bulk solids move through continuous-process environments. Equipment specifiers now prioritize data connectivity and regulatory traceability alongside mechanical reliability.
Modular stainless steel flighting with quick-release shaft couplings is integrating into pharmaceutical and nutraceutical facilities where batch changeover frequency demands tool-free disassembly for cleaning validation. Contract manufacturers in Pennsylvania and California are specifying these configurations to reduce downtime between product campaigns. The technology is integrating with isolator and containment suite designs, compressing the traditional trade-off between throughput and cross-contamination risk.
FDA's Food Safety Modernization Act preventive controls rules are mandating documented cleanability validation for equipment contacting ready-to-eat products. Processors must now maintain written procedures for disassembly, cleaning, and inspection of all material contact surfaces. Dairy and meat facilities in Wisconsin, California, and New York are responding by specifying 3A Sanitary Standards-compliant designs with polished welds and radiused corners that eliminate harborage points.
Maintenance departments are unbundling OEM service contracts and sourcing aftermarket flighting and bearing assemblies from independent fabricators. Large grain cooperatives in the Midwest are building in-house rebuild capabilities for standard-duty carbon steel units, reducing reliance on factory-authorized technicians. This pattern is most visible in Illinois and Ohio, where elevator networks operate sufficient screw conveyor populations to justify captive repair shops and spare parts inventories.
North America Screw Conveyor Market Segmentation
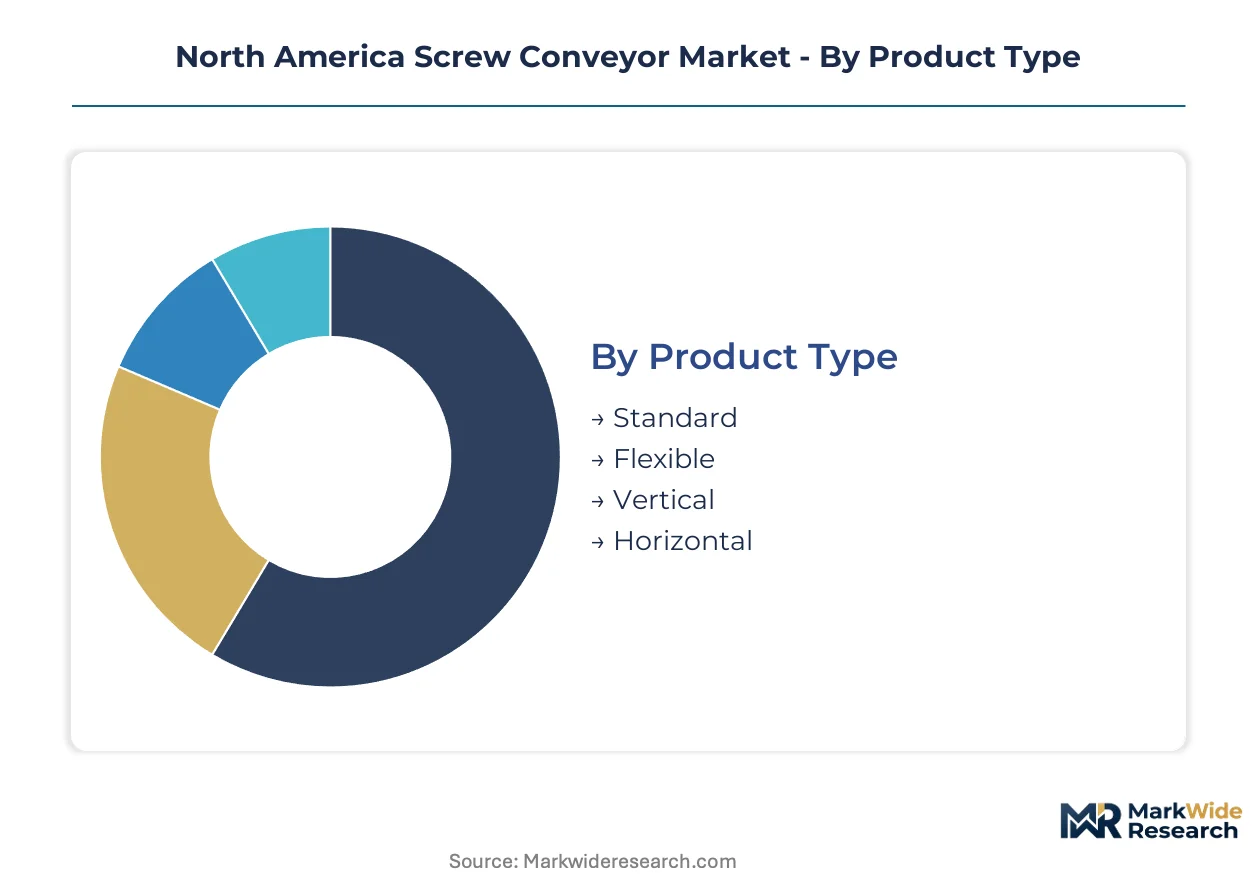
Screw conveyor procurement in North America splits sharply between commodity carbon steel units for grain elevators and precision-fabricated stainless systems for USDA-inspected meat plants. Specification engineers weigh surface finish requirements against abrasion tolerance when mapping segments to facility type.
Product Type:
Volume concentrates in horizontal configurations for grain handling, while premium pricing accrues to flexible systems solving layout constraints in pharmaceutical suites.
- Standard:Rigid U-trough designs with fixed pitch flighting dominate grain elevator retrofits across Kansas and Nebraska. USDA food safety audits are accelerating replacement of open-frame standard units with sealed sanitary alternatives in Midwest meat processing corridors.
- Flexible:Helix-driven conveying within polymer tubes enables powder transfer around structural obstacles without rigid ducting. New Jersey and North Carolina pharmaceutical compounders specify these configurations for contained movement between process isolators.
- Vertical:High-torque drive heads lift bulk materials against gravity in limited-footprint mineral processing facilities.
- Horizontal:Zero-incline transport paths retain the largest installed base but generate compressed margins due to commoditized fabrication.
Today's leader: Standard. Tomorrow's challenger: Flexible.
End User:
Cost tier separation runs deepest between price-sensitive agricultural buyers and compliance-driven food processors.
- Agriculture:Grain cooperatives in Illinois and Ohio operate captive repair shops for carbon steel flighting rebuilds. EPA dust emission enforcement is forcing elevator operators toward enclosed designs despite capital budget constraints.
- Food Processing:Wisconsin dairy facilities and California meat plants specify 3A Sanitary Standards-compliant units with 20Ra surface finishes. FDA preventive controls rules mandate documented cleanability validation for all material contact surfaces.
- Mining:Abrasion-resistant alloy flighting withstands silica sand and mineral aggregate transport in Texas and Wisconsin frac sand operations.
- Construction:Portable auger systems move cement and aggregate at job sites where equipment mobility outweighs durability requirements.
Agriculture commands unit volume. Food Processing captures margin premiums.
Material:
Supply concentration for nickel and chromium inputs in Indonesian and South African nodes compresses margin predictability for stainless fabricators.
- Stainless Steel:304 and 316 grades with polished welds satisfy USDA surface roughness mandates for meat and dairy contact surfaces. Certified sanitary welders capable of orbital TIG passes command wage premiums extending lead times for custom dairy units.
- Carbon Steel:Standard-duty flighting persists in grain handling where abrasion tolerance outweighs corrosion resistance. Midwest elevator networks justify in-house rebuild capabilities for captive repair of worn auger assemblies.
- Plastic:UHMW and nylon flighting reduces product adhesion in sticky agricultural commodities and certain food applications.
- Alloy:Hardened steel compositions withstand extreme abrasion in mining and heavy construction material transport.
Carbon Steel anchors volume. Stainless Steel claims value.
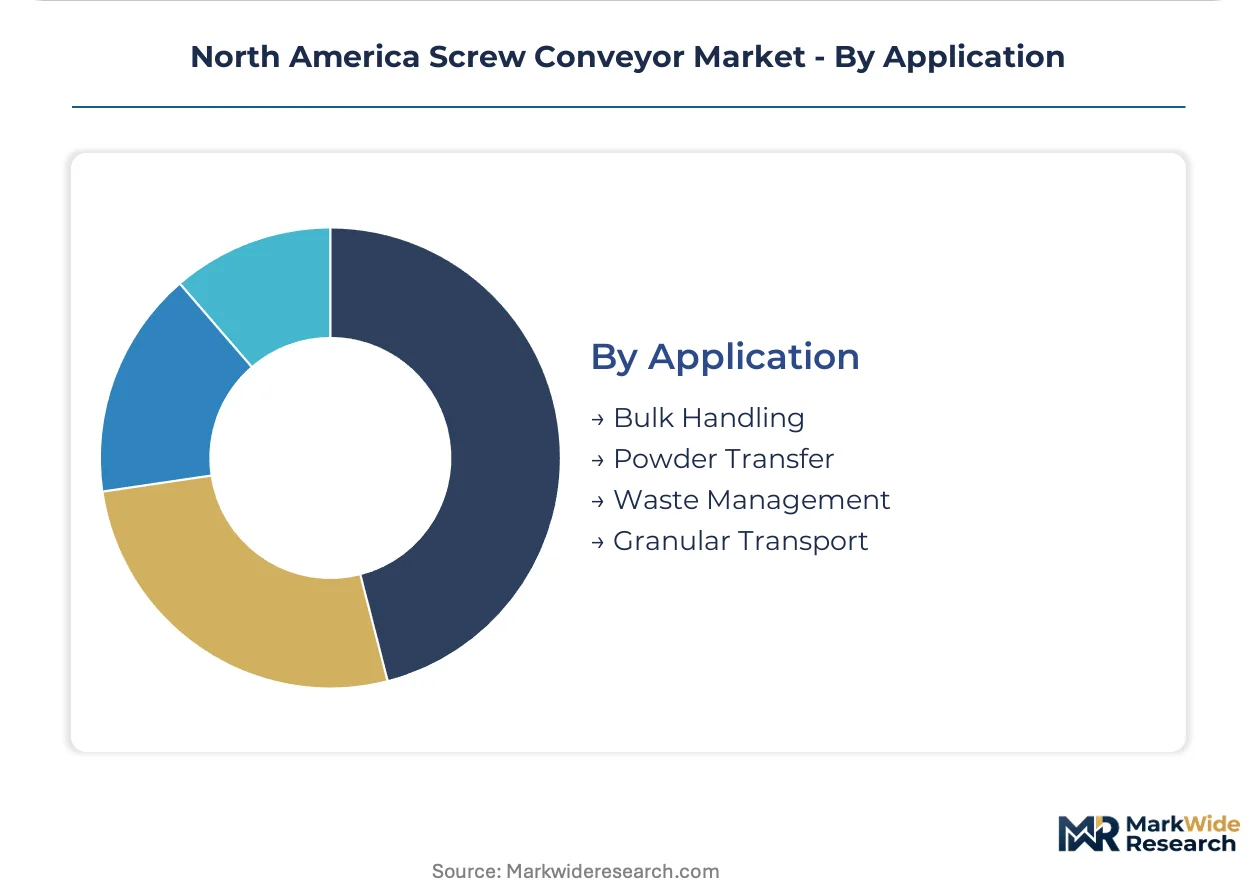
Application:
Customer type separation distinguishes between continuous-flow bulk operations and batch-oriented powder handling.
- Bulk Handling:High-capacity grain movement through enclosed U-troughs defines the core installed base across Prairie provinces and U.S. Midwest states. Canadian Saskatchewan and Alberta handlers are importing U.S.-fabricated enclosed systems to replace open belt conveyors.
- Powder Transfer:Contained pharmaceutical and food ingredient movement demands flexible configurations with dust-tight seals. Pneumatic conveying substitution threatens mechanical screw systems where layout flexibility outweighs capital cost sensitivity.
- Waste Management:Municipal sludge and industrial byproduct transport requires corrosion-resistant materials and specialized flight geometries.
- Granular Transport:Controlled-rate feeding of pellets and granules into extrusion and compounding lines in Southeast bioplastics facilities.
Bulk Handling dominates installed base. Powder Transfer expands fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Midwest grain belt generates the densest concentration of screw conveyor demand across North America, driven by elevator modernization cycles and meat processing facility retrofits.
United States
USDA sanitary equipment standards and FDA food contact surface regulations compress replacement cycles across Wisconsin dairy facilities and Midwest meat processing corridors. EPA dust emission thresholds force Kansas and Nebraska elevator operators toward enclosed auger designs. Chicago and Minneapolis-St. Paul anchor fabrication capacity for custom stainless steel units.
Canada
Saskatchewan and Alberta grain handlers import U.S.-fabricated enclosed screw systems to replace open belt conveyors and reduce dust exposure liability. Health Canada food safety codes align procurement specifications with USDA sanitary design standards. Prairie province elevator cooperatives justify captive repair shops for carbon steel flighting rebuilds.
Mexico
Nuevo León automotive suppliers and Bajío Region food processors specify stainless steel configurations for export-oriented production lines. Mexican federal food safety regulations tighten equipment surface requirements for facilities supplying U.S. markets. Guadalajara industrial corridors concentrate demand for flexible powder transfer systems in pharmaceutical ingredient handling.
North America Screw Conveyor Market Competitive Landscape
Global majors compete with regional champions across fabrication specialization and regulatory compliance depth. The vendor base stratifies between vertically integrated foundry operators and boutique sanitary fabricators. Three archetypes dominate: scale-driven commodity producers, compliance-focused stainless specialists, and flexible-system technology holders. Capacity expansion in Great Plains fabrication clusters and strategic partnerships for distribution reach constitute the dominant competitive moves.
Among U.S.-based fabricators, KWS Manufacturing exemplifies the vertically integrated archetype through captive foundry operations controlling raw material costs. Flexicon Corporation occupies a defensible position in flexible screw technology for contained powder movement. Industrial Screw Conveyors Inc. anchors the premium sanitary tier serving USDA-inspected meat and dairy facilities.
| Leading Market Players |
|---|
| Screw Conveyor Corporation |
| Industrial Screw Conveyors Inc. |
| KWS Manufacturing |
| Astro Metal Craft |
| Cyclonaire Corporation |
| Flexicon Corporation |
| Conveyor Engineering & Manufacturing |
| Metzgar Conveyor Co. |
| Continental Screw Conveyor |
| Others |
Value Network & Pricing Analysis
Modular stainless steel flighting with quick-release shaft couplings is compressing cost economics for pharmaceutical compounders while simultaneously concentrating fabrication capacity among Great Plains foundry operators capable of precision orbital TIG welding. This technology transition rewards vertically integrated producers with captive heat-treatment capabilities and marginalizes regional job shops lacking sanitary certification depth.
Pricing Analysis
Input-cost pass-through from nickel and chromium volatility directly shapes quoting behavior for multi-month stainless steel projects across U.S. fabricators. Three-tier pricing structure across USDA-certified premium, industrial-grade standard, and carbon steel economy levels separates dairy processors from grain elevators from construction contractors. Price differentiation hinges on surface finish certification and geographic delivery radius. Cost compression in standard horizontal configurations is intensifying because Midwest elevator networks now operate captive rebuild shops. Grain cooperatives exhibit highest price sensitivity; pharmaceutical compounders demonstrate lowest.
Supply Chain Analysis
Domestic-content preferences in Canadian Prairie province procurement are reshaping sourcing patterns for Saskatchewan and Alberta grain handlers importing U.S.-fabricated enclosed systems. Raw material supply draws from Indonesian nickel nodes, South African chromium sources, and domestic Great Plains steel mills. Component fabrication rests on specialized orbital welding equipment and 3A-certified surface finishing capacity. Single-source vulnerability concentrates in certified sanitary welder labor pools. Distribution runs through regional fabrication clusters serving elevator cooperatives and meat processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America screw conveyor market functions as a stable compounder anchored by regulatory-mandated replacement cycles across USDA-inspected food facilities. Compliance-driven capital allocation sustains predictable demand visibility regardless of macroeconomic volatility.
For Market Incumbents: Anticipate pneumatic conveying substitution threats in powder transfer applications by deepening captive foundry integration and expanding heat-jacketed auger offerings for bioplastics compounders. Prioritize orbital TIG welding certification pipelines to offset specialized labor scarcity. Defensive consolidation through regional fabrication capacity additions in Kansas and Nebraska secures grain belt customer lock-in. For New Entrants and Emerging Players: Canadian Prairie grain handlers represent an underserved buyer archetype seeking dust-tight enclosed systems with reduced lead times versus incumbent U.S. suppliers. Bioplastics pellet producers in the U.S. Southeast offer secondary white-space targeting for temperature-controlled resin transfer configurations. Go-to-market execution through regional elevator cooperative purchasing consortiums bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among carbon steel commodity fabricators lacking stainless steel certification depth but possessing transferable Great Plains customer relationships. Five-to-ten-year viability framing favors USDA-compliant sanitary specialists with demonstrated 3A validation track records. Monitor EPA dust emission enforcement intensity across Midwest elevator networks as inflection indicator for enclosed system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | KWS Manufacturing's captive raw material cost control anchors margin defense against nickel volatility. |
| Sanitary Certification Investment | 3A and USDA-compliant surface finish validation opens dairy and meat processor procurement channels. |
| Flexible Screw Technology Licensing | Proprietary drive-head engineering captures pharmaceutical powder transfer premium pricing. |
| Geographic Expansion into Canadian Prairies | Saskatchewan and Alberta grain handlers import U.S. systems to replace open belt conveyors. |
| Aftermarket Service Unbundling | Independent flighting and bearing assembly sourcing builds Midwest elevator cooperative loyalty. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation through USDA equipment certification databases and EPA emission compliance filings, and customs records tracking Canadian Prairie import flows — were reconciled through bottom-up and top-down triangulation. Conversations with maintenance directors at Illinois grain cooperatives, sanitary welding certification bodies, and pharmaceutical compounders in New Jersey informed operational reality checks. SEC 10-K disclosures from publicly traded fabrication parent companies and regional trade association shipment data provided secondary anchor points.
Historical shipment trajectories were cross-referenced against panel input from fabrication executives to establish baseline momentum across the analysis window. Segmentation modeling incorporated product type, material grade, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from fitted trend extrapolation moderated by replacement cycle visibility and enforcement intensity assumptions. Industry-specific forecast inputs included EPA dust rule implementation timelines and FDA Food Safety Modernization Act preventive controls adoption curves.
Underlying measurement precision varies by segment; flexible screw configurations and stainless steel sanitary units carry tighter precision than commoditized carbon steel grain handling equipment due to concentrated vendor populations and visible certification backlogs. Forecasts reflect assumptions regarding regulatory enforcement continuity and raw material supply stability. Nickel export policy shifts from Indonesian mining jurisdictions or South African logistics disruptions could materially revise stainless steel fabrication outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Dump Tubs Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Rail Mounted Gantry Crane Market
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Asia-Pacific Forklift Rental Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Global Pipe and Tube Bending Machine Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Compaction Machines Market
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Global Precision Gearboxes Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
North America Utility Locator Market
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
Vertical Lift Module (VLM) Market