
 Middle East Programmable Logic Controller (PLC) Market | 2026-2036
Middle East Programmable Logic Controller (PLC) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Programmable Logic Controller (PLC) Market Insights
Aftermarket service revenue is fragmenting across the Middle East PLC landscape as hardware margins compress and vendors compete on lifecycle contracts. Siemens AG leverages its TIA Portal ecosystem to anchor long-term service relationships with Saudi Aramco and ADNOC affiliates. Schneider Electric SE sustains competitive positioning through its EcoStruxure architecture, which dominates energy management integrations in UAE smart building projects. ABB Ltd specializes in safety PLC configurations for high-risk hydrocarbon environments, occupying a defensible niche in Qatar's North Field expansion and Kuwait's Al-Zour refinery.
A programmable logic controller is an industrial digital computer engineered for electromechanical process automation, typically operating across temperature ranges from minus 20 to 60 degrees Celsius with scan cycles measured in milliseconds; its core function executes programmed logic to control machinery, assembly lines, and robotic devices in continuous or batch manufacturing environments. Modular PLC architectures command the dominant share of regional capital expenditure, as Gulf operators prioritize scalability in brownfield petrochemical upgrades over compact units suited to discrete manufacturing. Cloud-based technology represents the fastest-expanding dimension, with Saudi and Emirati state enterprises piloting edge-to-cloud architectures for predictive maintenance in remote desert production facilities.
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations and UAE's Emirates Authority for Standardization and Metrology (ESMA) conformity schemes shape PLC import requirements, mandating electromagnetic compatibility and environmental resilience certifications that filter out lower-tier suppliers. The Saudi Communications and Information Technology Commission (CITC) and UAE's Telecommunications and Digital Government Regulatory Authority (TDRA) govern wireless industrial networking protocols, directly influencing technology roadmaps for vendors seeking deployment permits. Stakeholders must weigh the accelerating shift toward indigenous manufacturing incentives against the persistent dependency on European and East Asian hardware supply chains.
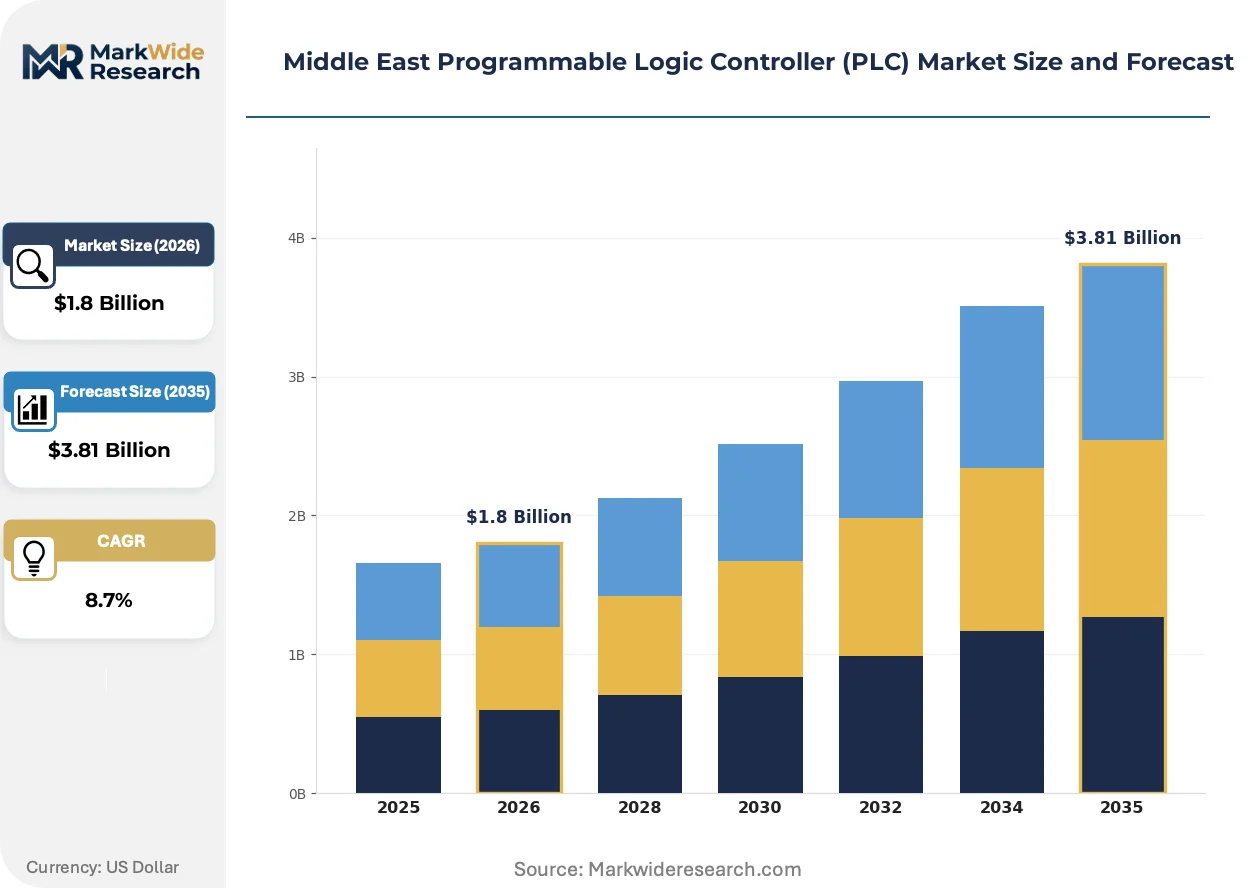
Market Dynamics
The Middle East PLC market is undergoing a structural transformation driven by the collision between hydrocarbon legacy infrastructure and state-mandated industrial diversification programs. Saudi Vision 2030 and UAE Operation 300bn are redirecting capital flows from upstream oil automation toward advanced manufacturing control systems, forcing vendors to reconfigure product portfolios and service architectures.
Growth Catalysts
- Saudi Vision 2030:The national transformation program mandates localization of industrial control systems, creating procurement preferences for PLC vendors establishing in-Kingdom manufacturing or joint ventures with Saudi entities.
- Edge-to-cloud architectures:State energy enterprises in the UAE and Saudi Arabia are piloting distributed control systems that integrate on-premise PLCs with cloud analytics for predictive maintenance in remote desert production facilities.
- Jubail Industrial City concentration:Petrochemical complex expansions in this Saudi hub generate concentrated demand for integrated safety and process control systems requiring modular PLC configurations.
Market Restraints
- Semiconductor supply concentration:PLC processor and I/O module production concentrates in East Asian foundries, exposing Middle East operators to extended lead times and allocation constraints during global chip shortages.
- SASO technical barriers:Saudi electromagnetic compatibility and environmental resilience certifications filter out lower-tier suppliers, reducing price competition and extending vendor qualification timelines.
- Legacy system lock-in:Brownfield hydrocarbon facilities operate proprietary communication protocols that create switching costs and compatibility barriers for new PLC installations.
Strategic Opportunities
- Kuwait Al-Zour refinery greenfield:This megaproject represents underpenetrated demand for integrated safety PLC systems in a market historically dominated by Saudi Arabia and UAE procurement.
- EcoStruxure-type platform convergence:Vendors combining energy management software with industrial automation hardware capture cross-selling opportunities in UAE smart building and district cooling projects.
- Qatar North Field expansion:LNG infrastructure investments create demand for SIL-rated safety PLCs in high-risk cryogenic processing environments.
Industry Challenges
- Automation engineering talent scarcity:Shortages of certified PLC programmers and SCADA integration specialists delay commissioning timelines across Gulf petrochemical projects.
- Multi-vendor system integration:Operators mixing Siemens, Schneider, and ABB architectures face protocol translation complexity and cybersecurity vulnerability management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Programmable Logic Controller (PLC) Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact PLC, Modular PLC, Rack-Mounted PLC, Safety PLC End User: Manufacturing, Oil & Gas, Automotive, Water & Wastewater Technology: Wired, Wireless, Integrated, Cloud-Based Application: Process Control, Assembly Line Automation, Packaging, HVAC |
| Companies Covered | Siemens AG, ABB Ltd, Schneider Electric SE, Rockwell Automation Inc., Mitsubishi Electric Corporation, Honeywell International Inc., Omron Corporation, Panasonic Corporation, Emerson Electric Co., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Programmable Logic Controller (PLC) Market Trends and Innovations
Control system architectures across the Middle East are fragmenting as operators balance cybersecurity hardening against cloud connectivity demands. Vendors are repositioning around software-defined automation platforms that decouple hardware from control logic execution.
Modular PLC hardware is hybridizing with edge computing nodes to enable localized data preprocessing before cloud transmission. Saudi Aramco and ADNOC affiliates are deploying these hybrid configurations in remote wellhead monitoring applications. This convergence is compressing the traditional boundary between distributed control systems and discrete PLCs.
SASO technical regulations and ESMA conformity schemes are tightening electromagnetic compatibility mandates for industrial networking equipment. These certification requirements are filtering out uncertified wireless protocol suppliers from Saudi and UAE project bids. System integrators are responding by pre-qualifying hardware against dual-jurisdiction standards before procurement submission.
Service contract unbundling is disrupting traditional PLC vendor revenue models across Gulf state enterprises. Aramco and ADNOC operating companies are separating hardware procurement from lifecycle maintenance, awarding multi-year service agreements to specialized third-party integrators. This shift is most visible in Saudi Arabia's Jubail and Yanbu industrial cities where petrochemical operators optimize vendor management overhead.
Middle East Programmable Logic Controller (PLC) Market Segmentation
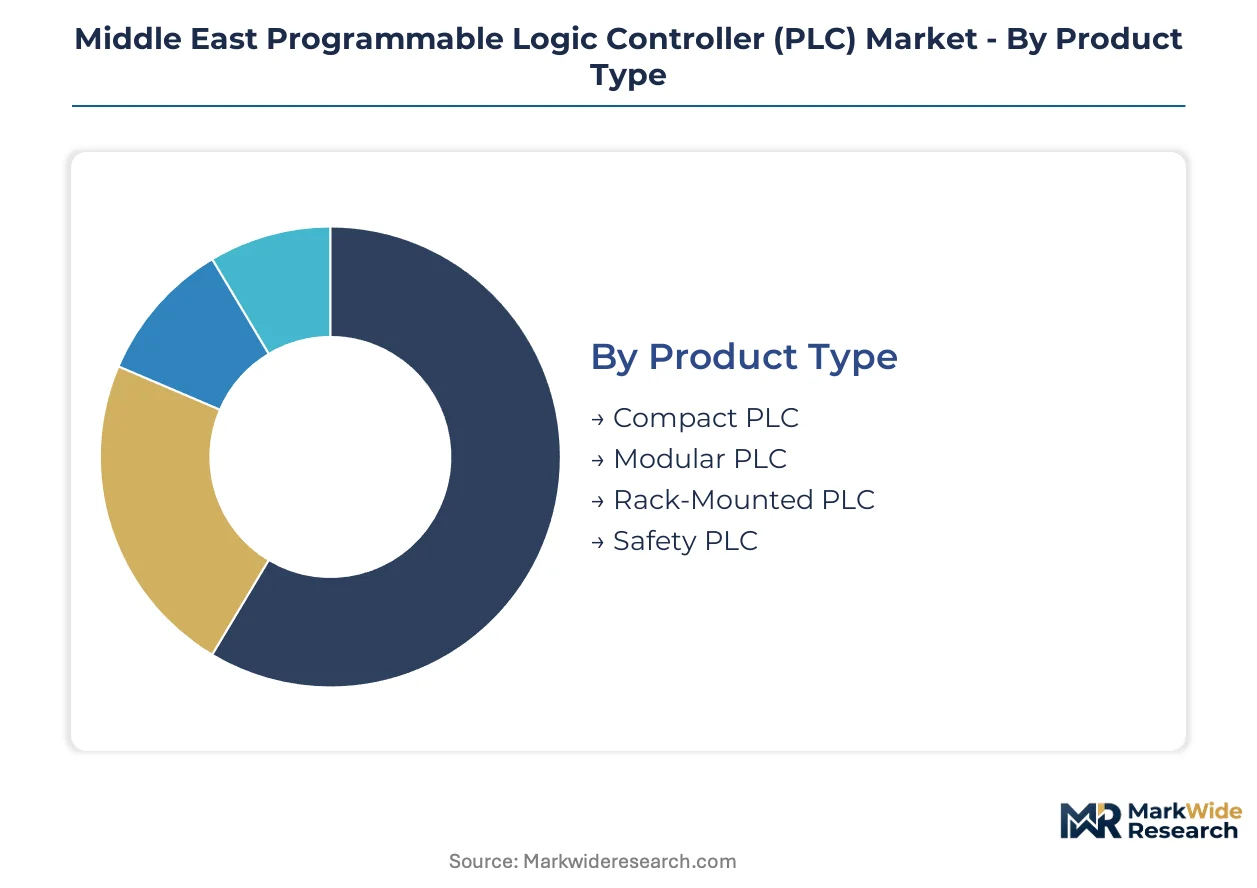
PLC purchasing patterns across the Middle East diverge sharply between hydrocarbon operators seeking safety-certified configurations and industrial diversification projects favoring modular scalability. Understanding these segment boundaries clarifies why vendors maintain parallel product portfolios rather than unified platforms for the region.
Product Type:
Use-case spectrum spans compact units for discrete manufacturing to rack-mounted systems for distributed petrochemical control.
- Modular PLC:Scalable I/O architectures allow Gulf operators to expand control points without full system replacement. Petrochemical complexes in Saudi Arabia's Jubail Industrial City and UAE's KIZAD free zone specify these configurations for brownfield upgrade flexibility.
- Safety PLC:SIL-rated hardware executes safety instrumented functions in high-risk hydrocarbon processing. Qatar's North Field LNG expansion and Kuwait's Al-Zour refinery mandate these systems for cryogenic and high-pressure environments.
- Compact PLC:Fixed I/O units serve discrete manufacturing and building automation where space constraints dominate.
- Rack-Mounted PLC:Centralized chassis configurations persist in legacy refinery distributed control system architectures.
The dominant share belongs to Modular PLC, while Safety PLC is closing the gap fastest.
End User:
Customer concentration reflects state capital allocation priorities across hydrocarbon extraction and industrial diversification agendas.
- Oil & Gas:Upstream automation and downstream refinery digitization consume the majority of regional PLC capital expenditure. Saudi Aramco and ADNOC affiliates drive specifications for hazardous area certifications and extreme temperature resilience.
- Manufacturing:Advanced manufacturing initiatives under Saudi Vision 2030 and UAE Operation 300bn redirect procurement toward flexible automation systems. Specialty chemical plants and automotive component facilities in industrial free zones generate concentrated demand.
- Water & Wastewater:Desalination and district cooling infrastructure in UAE coastal cities deploy PLCs for process optimization.
- Automotive:Limited vehicle assembly presence in the region constrains this segment to parts manufacturing and logistics automation.
Oil & Gas retains the largest installed base, though Manufacturing is expanding most quickly.
Technology:
Connectivity architecture choices balance cybersecurity hardening against cloud analytics integration for predictive maintenance.
- Cloud-Based:Edge-to-cloud configurations enable remote monitoring of desert production facilities with centralized analytics platforms. Saudi and Emirati state enterprises pilot these architectures for wellhead automation and pipeline integrity management.
- Wired:Proprietary fieldbus and industrial Ethernet protocols dominate safety-critical process control where electromagnetic interference resistance is mandatory.
- Wireless:ISA100 and WirelessHART deployments face regulatory scrutiny from Saudi CITC and UAE TDRA for spectrum allocation and cybersecurity compliance.
- Integrated:Hybrid architectures combining PLC logic with PC-based HMI and SCADA functions serve mid-scale facilities seeking unified control platforms.
Wired technology holds the dominant position, yet Cloud-Based systems are gaining share fastest.
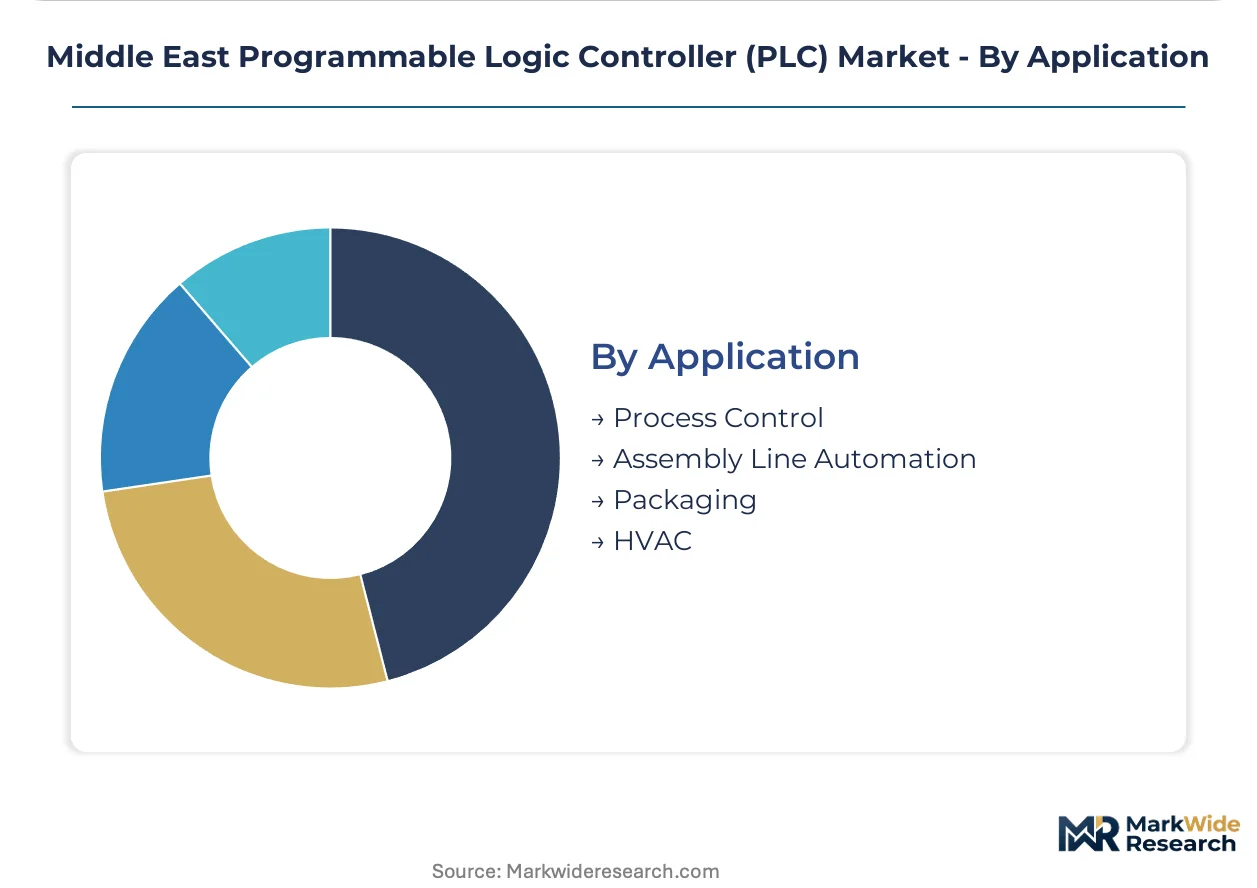
Application:
Functional deployment patterns separate continuous process industries from discrete manufacturing and building automation.
- Process Control:Continuous manufacturing environments in petrochemicals and refining require PID loop control, batch sequencing, and safety interlocking. These applications demand ruggedized hardware certified for SASO electromagnetic compatibility standards.
- Assembly Line Automation:Discrete manufacturing for industrial diversification projects employs PLCs for conveyor coordination, robotic cell control, and quality inspection integration.
- HVAC:District cooling plants and smart building projects in UAE commercial developments specify PLCs for energy optimization and demand response.
- Packaging:Food and consumer goods manufacturing in Saudi industrial cities uses compact PLCs for filling, labeling, and palletizing operations.
Process Control commands the dominant share, while Assembly Line Automation is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across the Middle East PLC landscape. Saudi buyers exhibit the greatest price sensitivity due to localization mandates, while UAE operators prioritize integration speed over unit cost. Qatar and Kuwait represent intermediate positions where safety certification premiums override pure price competition.
Saudi Arabia
Jubail Industrial City and Yanbu petrochemical complexes drive concentrated demand for modular PLC architectures. SASO electromagnetic compatibility regulations filter supplier pools, extending vendor qualification timelines. NEOM Northwest development is piloting edge-to-cloud automation configurations for smart city infrastructure.
United Arab Emirates
KIZAD free zone specialty chemical plants and Dubai smart building projects generate dual demand streams. ESMA conformity schemes govern industrial networking equipment imports, shaping procurement specifications. Abu Dhabi National Oil Company affiliates are unbundling hardware procurement from lifecycle service contracts.
Qatar
North Field LNG expansion mandates SIL-rated safety PLC systems for cryogenic processing environments. The country's national standardization body enforces hazardous area certification requirements that limit supplier participation. Ras Laffan Industrial City concentrates demand for integrated process control and safety instrumented systems.
Kuwait
Al-Zour refinery greenfield construction represents the region's largest underpenetrated PLC opportunity outside Saudi Arabia and UAE. The national petroleum corporation's procurement frameworks emphasize European vendor pre-qualification. Shuaiba industrial area retrofits are replacing legacy relay systems with modern programmable controllers.
Middle East Programmable Logic Controller (PLC) Market Competitive Landscape
Capability concentration sits with European automation conglomerates; scale advantage sits with diversified industrial technology groups. The Middle East PLC market structures around three tiers: full-line automation vendors, safety-system specialists, and building-technology integrators. Consolidation pressure is minimal given the project-based nature of hydrocarbon sector procurement. Dominant competitive moves include ecosystem lock-in through software platforms and lifecycle service contract unbundling.
Among European-headquartered industrial technology groups, Siemens AG, ABB Ltd, and Schneider Electric SE exemplify the capability-tier archetype. These entities anchor competitive positioning through integrated software-hardware architectures rather than discrete component sales. Siemens AG represents the ecosystem-lock-in model through its TIA Portal platform. ABB Ltd occupies the safety-system specialist position for high-risk hydrocarbon applications. Schneider Electric SE exemplifies building-technology convergence through energy management integration.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Schneider Electric SE |
| Rockwell Automation Inc. |
| Mitsubishi Electric Corporation |
| Honeywell International Inc. |
| Omron Corporation |
| Panasonic Corporation |
| Emerson Electric Co. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in East Asian semiconductor foundries is compressing PLC processor margins while extending supplier payment terms for Middle East system integrators. This utilization dynamic forces Gulf procurement teams to balance spot-market component savings against long-term vendor qualification costs under SASO electromagnetic compatibility mandates.
Pricing Analysis
Project-based contracting dominates PLC procurement across Saudi Aramco and ADNOC affiliates, with hardware procurement increasingly unbundled from multi-year lifecycle service agreements. Price differentiation centers on SIL certification tier and after-sales service bundling rather than base hardware specifications. Pricing pressure stems from state enterprise procurement frameworks favoring in-Kingdom manufacturing joint ventures. Saudi buyers exhibit the greatest price sensitivity due to localization mandates, while Qatar's North Field expansion prioritizes safety certification premiums over unit cost.
Supply Chain Analysis
Upstream semiconductor fabrication concentrates in Taiwan, South Korea, and China, with PLC processors and I/O modules drawing from these concentrated foundry capacities. Raw material dependencies span silicon wafers, copper interconnects, and rare-earth magnet components for motor control applications. Single-source vulnerability in advanced node semiconductor production exposes Middle East operators to allocation constraints during global chip shortages. Distribution runs through Dubai-based regional logistics hubs serving Jubail Industrial City and KIZAD free zone deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial edge computing platforms represent the most credible substitution threat to traditional PLC architectures, forcing incumbents to defend their installed base through software-defined automation transitions.
For Market Incumbents: Pre-empt displacement by embedding PLC logic execution within virtualized edge computing nodes deployed at Saudi Aramco remote wellhead facilities. Deepen backward integration into safety-certified firmware development to capture SIL-rated project specifications in Qatar's LNG expansion. Anchor ecosystem lock-in through TIA Portal-type platform stickiness before third-party integrators unbundle service contracts entirely. For New Entrants and Emerging Players: Kuwait's Al-Zour refinery greenfield construction represents the most penetrable entry point outside Saudi-UAE procurement concentration, with European vendor pre-qualification requirements creating qualification gaps for agile specialists. Cloud-native PLC architectures with integrated cybersecurity hardening offer differentiation against legacy hardware incumbents in UAE smart building projects. Target mid-scale specialty chemical plants in Saudi industrial cities seeking modular upgrade flexibility without full system replacement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based automation software layers as hardware commoditization accelerates. Acquire regional system integrators with established SASO certification pathways and Aramco-approved vendor status to capture unbundled service contract flows. Monitor edge-to-cloud pilot deployment timelines at NEOM and ADNOC facilities as inflection indicators for architecture transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Localization Joint Venture | SASO procurement preferences favor in-Kingdom manufacturing partnerships with Saudi entities. |
| Safety Certification Investment | SIL-rated hardware qualifications unlock Qatar North Field and Kuwait Al-Zour project participation. |
| Edge-to-Cloud Platform Development | Virtualized control logic execution addresses Saudi Aramco predictive maintenance requirements. |
| Service Contract Unbundling | Third-party integrator partnerships capture separated lifecycle maintenance awards from hardware sales. |
| Cybersecurity Hardening | CITC and TDRA wireless protocol compliance enables deployment permits for industrial networking equipment. |
Research Methodology
Cross-validation between primary interviews with automation engineering directors and secondary validation through customs trade data anchors the qualitative findings. Stakeholder consultations span plant engineers at Jubail petrochemical complexes, procurement leads at ADNOC operating companies, system integrators in Dubai's industrial technology corridor, and aftermarket service heads managing brownfield upgrades. Secondary sources include SASO technical regulation filings, ESMA conformity scheme documentation, SEC 10-K disclosures from listed automation vendors, and project development databases tracking refinery and LNG infrastructure investments. Bottom-up project pipeline aggregation triangulates against top-down industrial capital expenditure forecasts.
Calibration against historical deployment patterns across oil and gas, manufacturing, and water infrastructure segments shapes the analytical framework. Segmentation dimensions span product architecture type, end-use industry vertical, connectivity technology, and application function. CAGRs derive from weighted average of deployment velocity assumptions across the projection horizon, with specific inputs including Saudi Vision 2030 industrial diversification spend trajectories and UAE Operation 300bn manufacturing automation commitments.
Macroeconomic conditions sit as an overlay; deviation in hydrocarbon capital expenditure cycles or semiconductor supply availability would shift the trajectory. Forecasts reflect documented assumptions regarding state enterprise procurement framework continuity and certification regime stability. Quarterly review of project commissioning timelines at Jubail Industrial City and KIZAD free zone is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Smart Sorting Line Market
Industrial Automation
Europe Retail Automation Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
Industrial Networking Solutions Market
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
Predictive Maintenance for Manufacturing Market
Industrial Automation
Europe Smart Manufacturing Market
Industrial Automation
Smart Elevator Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
South East Asia Warehouse Automation Market
Industrial Automation
Mining Automation Solutions Market