
 North America Factory Automation and Industrial Controls Market | 2026-2036
North America Factory Automation and Industrial Controls Market Size, Share, and Industry Trends Forecast 2026-2036
North America Factory Automation and Industrial Controls Market Analytics
The US Inflation Reduction Act is realigning capital deployment thresholds for automation vendors serving domestic manufacturing. Rockwell Automation leverages its Milwaukee headquarters to anchor PLC and HMI supply chains for Midwest automotive clients. Siemens AG competes through its Texas-based digital industries hub, specializing in integrated DCS platforms for Gulf Coast chemical processors.
Factory automation and industrial controls encompass electromechanical systems, programmable logic controllers, distributed control architectures, and human-machine interfaces operating at millisecond cycle times to govern production throughput, safety interlocks, and energy efficiency in continuous and discrete manufacturing. Control Systems and Software capture widening margin pools as edge-computing architectures displace legacy centralized SCADA deployments. Industrial Robots lead volume contribution from automotive assembly lines across Ohio and Ontario, while Sensors experience accelerated replacement cycles driven by predictive maintenance mandates in Food & Beverage cold chain operations.
FDA equipment validation requirements, OSHA machine guarding standards, and NHTSA traceability protocols collectively elevate compliance costs for control system vendors accessing US industrial end users. Canada's PMRA and Mexico's national metrology authority impose parallel certification burdens that fragment cross-border deployment timelines. Stakeholders must monitor evolving EPA emissions monitoring rules for Oil & Gas automation contracts, as retrofit obligations will reshape upgrade prioritization across Permian Basin and Alberta oil sands facilities.
Market Dynamics
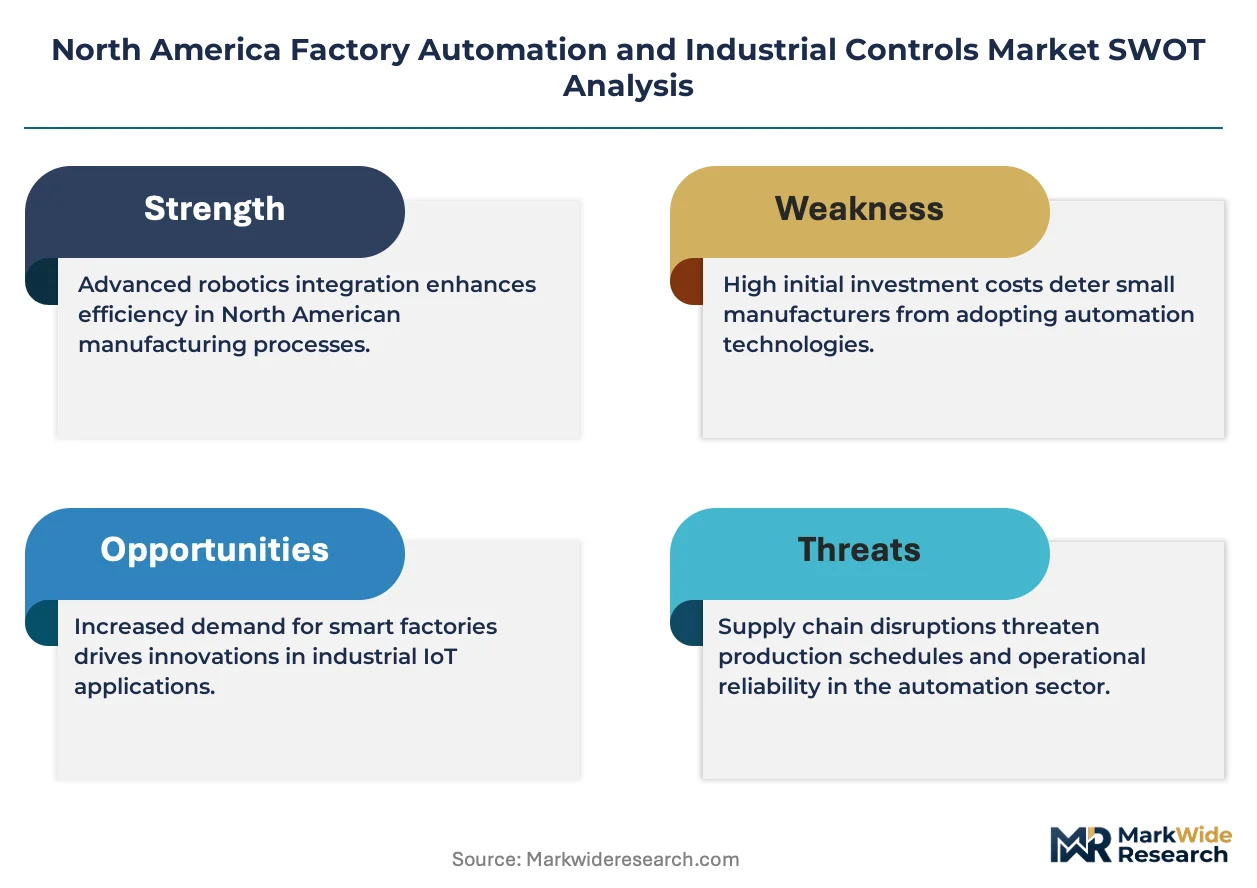
The US Inflation Reduction Act's domestic content incentives are compressing procurement timelines for control system vendors while reshoring mandates accelerate capital redeployment toward Milwaukee and Detroit industrial corridors.
Growth Catalysts
- IRA Domestic Content Thresholds:Automotive OEMs in Ohio and Michigan now prioritize US-sourced PLCs and HMIs to qualify for federal EV tax credits, tightening supplier qualification windows.
- Edge Computing Architectures:Food & Beverage cold chain operators across Ontario deploy predictive maintenance sensors with millisecond latency requirements, displacing legacy centralized SCADA.
- Permian Basin Emissions Monitoring:EPA retrofit obligations for Oil & Gas automation contracts in Texas and Alberta oil sands facilities trigger control system upgrade cycles.
Market Restraints
- Semiconductor Input Volatility:Industrial-grade chip shortages from Asian foundries extend PLC lead times for Midwest automotive clients beyond 26 weeks.
- Cross-Border Certification Fragmentation:Canada's PMRA and Mexico's national metrology authority impose parallel validation burdens that stall unified North American deployments.
- Legacy Protocol Lock-In:Proprietary fieldbus standards from incumbent vendors create switching costs that inhibit open-architecture adoption.
Strategic Opportunities
- Mexico Nearshoring Corridor:Nuevo León and Baja California manufacturing clusters lack mature system integrator networks, creating first-mover openings for US-based automation service providers.
- Digital Twin Convergence:Integration of physics-based simulation with real-time DCS data streams enables virtual commissioning for Gulf Coast chemical processors.
- OSHA Machine Guarding Modernization:Updated safety interlock mandates drive replacement demand for aging relay-based systems in Great Lakes metal fabrication.
Industry Challenges
- Control Systems Engineering Talent Gap:Shortages of PLC programmers and safety-certified technicians in Michigan and Ohio extend project implementation timelines.
- Multi-Protocol Integration Complexity:Brownfield facilities struggle to synchronize EtherCAT, Profinet, and legacy DeviceNet networks without production downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Factory Automation and Industrial Controls Market |
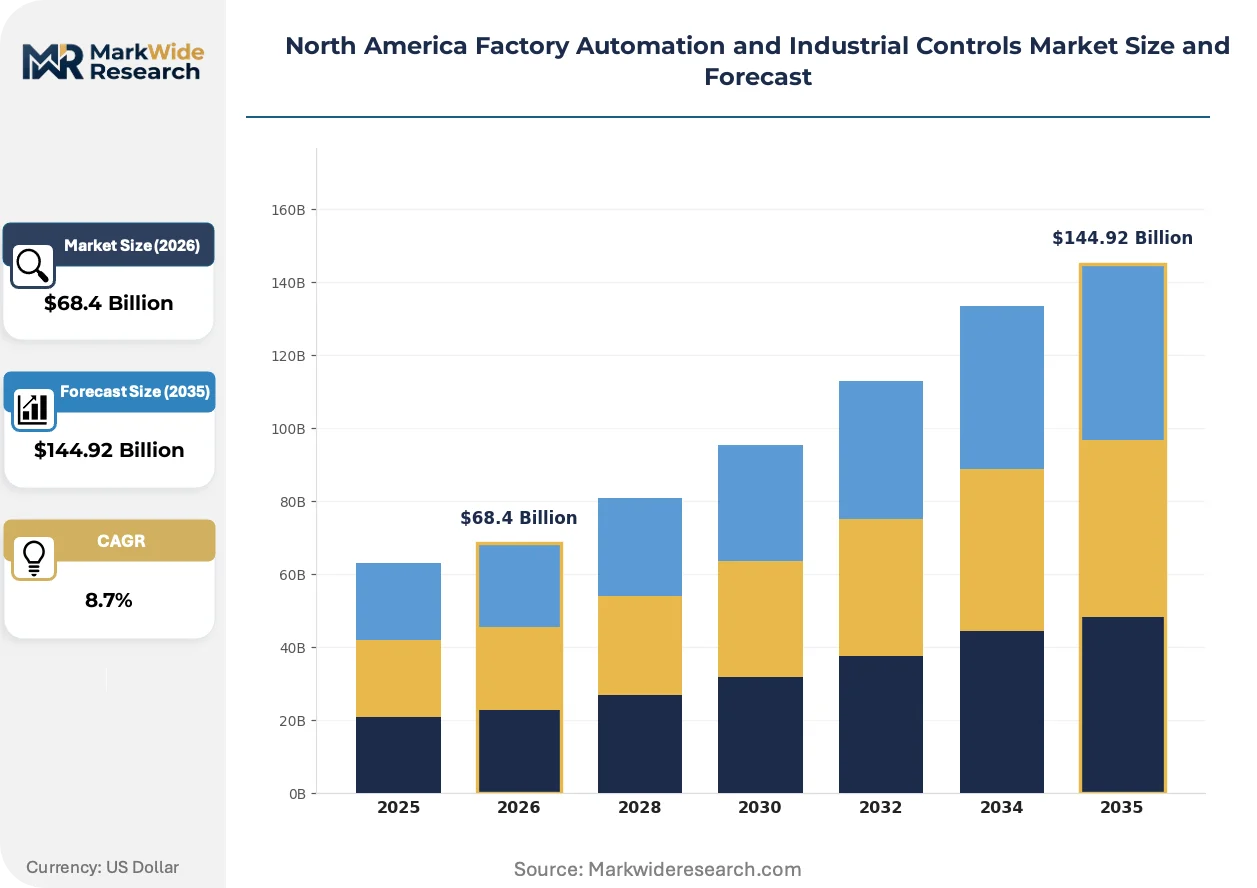
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Sensors, Control Systems, Software End User: Manufacturing, Oil & Gas, Chemicals, Food & Beverage Technology: PLC, SCADA, DCS, HMI Application: Assembly Line, Quality Control, Packaging, Material Handling |
| Companies Covered | Rockwell Automation Inc., Siemens AG, ABB Ltd., Schneider Electric SE, Emerson Electric Co., Mitsubishi Electric Corporation, Honeywell International Inc., Omron Corporation, Fanuc Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Factory Automation and Industrial Controls Market Evolving Landscape
Software-defined automation architectures are dissolving the boundary between operational technology and enterprise IT, forcing vendors to restructure service delivery models around continuous deployment rather than capital equipment sales.
Time-sensitive networking over standard Ethernet is unifying deterministic control traffic with information technology data flows on single cable infrastructure. Automotive assembly plants in Ontario and Ohio deploy TSN-enabled drives and I/O modules to eliminate separate fieldbus wiring. This convergence is unifying hardware procurement budgets under chief information officers rather than plant engineering departments.
EPA emissions monitoring rules for Oil & Gas automation contracts are mandating continuous methane detection and automated valve shutdown capabilities. Permian Basin operators must retrofit existing wellpad control systems with certified optical gas imaging integration. Gulf Coast chemical processors face parallel obligations under Texas Commission on Environmental Quality protocols, compressing vendor certification timelines.
Subscription-based control software licensing is displacing perpetual ownership models among mid-sized discrete manufacturers. Michigan automotive tier suppliers now prefer annual SaaS fees for HMI visualization and analytics over upfront capital expenditure. This preference shift concentrates vendor revenue predictability while transferring upgrade responsibility to automation providers.
North America Factory Automation and Industrial Controls Market Segmentation
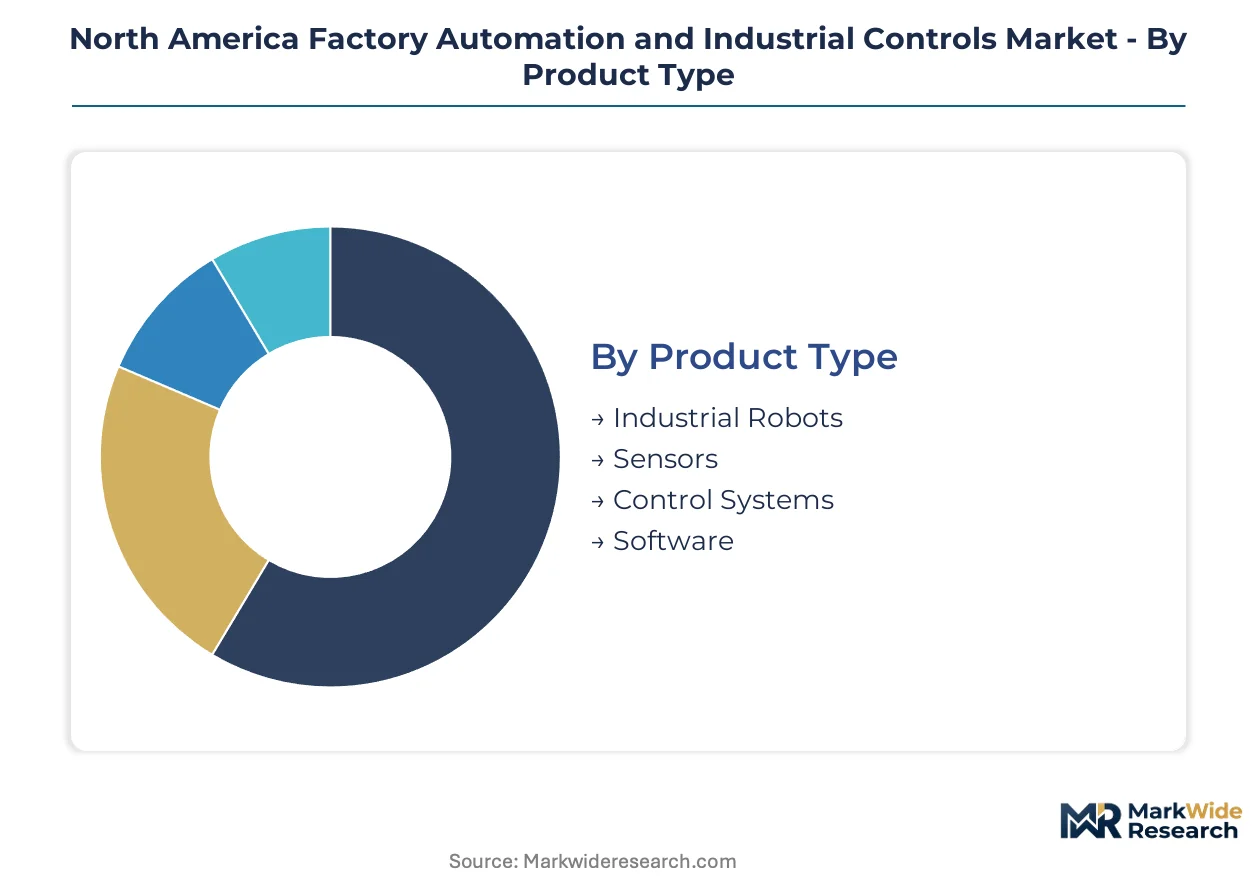
Factory automation vendors structure pricing and service models around four intersecting dimensions: capital-intensive hardware, vertical-specific compliance burdens, protocol architecture choices, and discrete operational functions. Procurement patterns diverge sharply between continuous process industries and discrete manufacturing, forcing suppliers to maintain parallel competency centers.
Product Type:
Industrial Robots and Sensors capture volume-driven procurement cycles, while Control Systems and Software command premium margins through recurring licensing and integration services.
- Industrial Robots:Six-axis articulated arms and collaborative cobots execute welding, painting, and material transfer operations at millisecond repeatability tolerances. Demand concentrates across Ohio and Ontario automotive assembly plants where OEMs retool for electric vehicle platforms under IRA domestic content mandates.
- Sensors:Temperature, pressure, vibration, and optical detection devices feed real-time data streams into predictive maintenance algorithms. Food & Beverage cold chain operators across the Great Lakes corridor drive replacement cycles as FDA traceability rules mandate continuous environmental monitoring.
- Control Systems:Encompass PLCs, PACs, and embedded motion controllers governing electromechanical actuation.
- Software:Includes HMI visualization, MES integration layers, and edge analytics platforms.
Mature deployment sits with Control Systems. Newer deployment is concentrated in Software.
End User:
Application complexity and regulatory burden separate high-touch process industries from standardized discrete manufacturing procurement.
- Manufacturing:Automotive, electronics, and metal fabrication facilities deploy discrete automation for throughput optimization and labor substitution. Michigan and Ohio tier suppliers prioritize US-sourced PLCs to qualify for federal EV tax credit domestic content thresholds.
- Oil & Gas:Upstream wellpad automation and midstream pipeline control demand explosion-proof enclosures and SIL-rated safety systems. Permian Basin operators face EPA methane monitoring retrofit obligations that compress vendor certification timelines.
- Chemicals:Continuous process control with batch reactor sequencing and hazardous area classifications.
- Food & Beverage:Cold chain integrity and washdown-rated hardware for sanitary processing environments.
Procurement sophistication peaks in Oil & Gas. Fastest expansion trajectory belongs to Food & Beverage.
Technology:
Architecture choices determine interoperability boundaries and long-term vendor lock-in exposure for brownfield facilities.
- PLC:Programmable logic controllers execute ladder logic and structured text for discrete manufacturing sequences. Midwest automotive clients face 26-week lead time extensions due to industrial-grade semiconductor shortages from Asian foundries.
- SCADA:Supervisory control and data acquisition systems aggregate field-level telemetry into centralized historian databases. Gulf Coast chemical processors migrate toward edge-computing architectures that displace legacy centralized deployments.
- DCS:Distributed control systems dominate continuous process industries with redundant controller architectures.
- HMI:Human-machine interfaces bridge operator interaction with underlying control logic.
Legacy dominance persists in DCS. Technology transition is accelerating fastest in SCADA.
Application:
Functional automation requirements map directly to capital allocation priorities and ROI measurement frameworks.
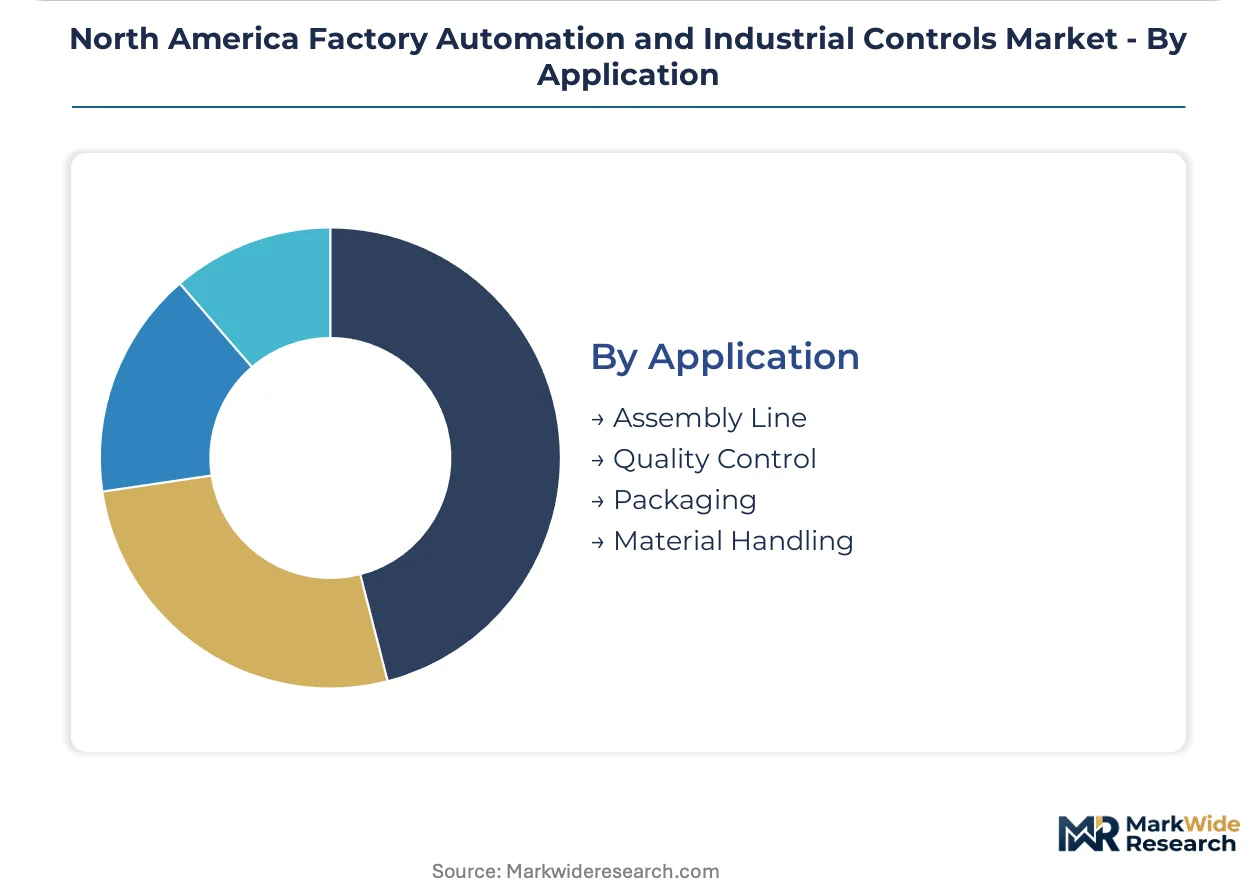
- Assembly Line:Robotic workcells synchronize multiple axes for welding, fastening, and component placement. Ontario and Ohio automotive plants deploy time-sensitive networking over standard Ethernet to unify deterministic control with IT data flows on single cable infrastructure.
- Quality Control:Machine vision systems and automated gauging enforce dimensional tolerances and defect rejection. Medical device manufacturers in Minnesota and Massachusetts integrate FDA equipment validation protocols into automated inspection sequences.
- Packaging:High-speed cartoning, palletizing, and labeling automation for consumer goods throughput.
- Material Handling:Automated guided vehicles and conveyor routing systems for warehouse and production logistics.
Capital intensity peaks in Assembly Line. Efficiency gains concentrate most rapidly in Quality Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act's domestic content bonus credits have concentrated automation procurement decisions around qualifying manufacturing zones in the Great Lakes and Gulf Coast corridors.
United States
Automotive OEMs in Michigan and Ohio retool assembly lines for electric vehicle platforms under IRA domestic content thresholds. OSHA machine guarding modernization mandates accelerate replacement of aging relay-based safety systems in Great Lakes metal fabrication clusters. Milwaukee anchors PLC and HMI supply chains serving Midwest automotive tier suppliers facing compressed qualification windows.
Canada
Food and Beverage cold chain operators across Ontario deploy predictive maintenance sensors to meet FDA-aligned PMRA traceability protocols. The province's automotive plants in Windsor and Oshawa integrate time-sensitive networking infrastructure for unified control and IT data flows. Alberta oil sands facilities face parallel EPA emissions monitoring retrofit obligations that compress vendor certification timelines.
Mexico
Nuevo León manufacturing clusters near Monterrey attract reshoring investments lacking mature system integrator networks. The national metrology authority imposes certification burdens that fragment cross-border deployment timelines with US and Canadian facilities. Baja California electronics assembly plants drive demand for collaborative robotics in precision component handling operations.
North America Factory Automation and Industrial Controls Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and integration service layers. The vendor base organizes into three strategic archetypes: diversified industrial conglomerates with broad automation portfolios, pure-play control system specialists, and robotics-centric manufacturers. Competitive intensity concentrates around M&A activity targeting software-defined automation capabilities and strategic partnerships bridging operational technology with enterprise IT infrastructure.
Among diversified industrial conglomerates, Rockwell Automation Inc. and Siemens AG occupy anchor positions representing contrasting geographic headquarters strategies. Rockwell Automation exemplifies the Midwest-anchored pure-play model with concentrated automotive sector exposure. Siemens AG represents the European-headquartered multinational with integrated digital industries positioning across process and discrete manufacturing verticals. ABB Ltd. sits within the robotics-heavy archetype with motion control and power electronics heritage.
| Leading Market Players |
|---|
| Rockwell Automation Inc. |
| Siemens AG |
| ABB Ltd. |
| Schneider Electric SE |
| Emerson Electric Co. |
| Mitsubishi Electric Corporation |
| Honeywell International Inc. |
| Omron Corporation |
| Fanuc Corporation |
| Others |
Value Network & Pricing Analysis
Performance-grade certification tiers for safety-rated PLCs and SIL-certified DCS hardware create a three-rung ladder that separates automotive OEM procurement from commodity discrete manufacturing, with each rung demanding distinct supplier qualification investments and geographic sourcing footprints that compress or extend delivery timelines.
Pricing Analysis
Lead-time premiums now dominate contract negotiations, with automotive clients in Michigan and Ohio paying surcharges for sub-12-week PLC delivery while spot inventory from distributors trades at discounts for non-certified legacy models. Three-tier pricing structure across premium, standard, and economy levels reflects UL/CE certification grades and after-sales service bundling. Price erosion runs through economy-tier HMIs as Asian contract manufacturers expand capacity. Tier suppliers facing IRA domestic content mandates show least price sensitivity; mid-sized metal fabricators exhibit highest elasticity.
Supply Chain Analysis
US Inflation Reduction Act domestic content thresholds are forcing control system vendors to reshore final assembly to Milwaukee and Detroit corridors, displacing previous reliance on Mexican maquiladora integration. Industrial-grade semiconductors draw from Taiwan, South Korea, and Japan; precision motion components feed from Germany and Switzerland. Single-source vulnerability concentrates in advanced FPGA supply for safety controllers. Distribution runs through authorized system integrator networks rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory automation vendors are racing to capture in-house semiconductor sourcing and captive safety-certification testing capabilities as vertical-integration levers that lock in margin pools and accelerate qualification timelines for IRA-compliant deployments.
For Market Incumbents: Anticipate margin compression from subscription-based SaaS competitors by accelerating edge-computing platform R&D and acquiring regional system integrators in Nuevo León to defend installation-service revenue. Reinforce certification laboratory capacity to shorten UL/FDA validation cycles that emerging players cannot match.
For New Entrants and Emerging Players: The price-point gap between Rockwell/Siemens premium tiers and economy-grade Asian imports creates white-space for mid-market cobot vendors targeting Ontario food processing and Baja California electronics assembly. Prioritize TSN-enabled hardware to bypass legacy fieldbus switching costs. Pursue channel partnerships with Great Lakes distributors lacking predictive maintenance software capabilities.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified industrial conglomerates seeking software-defined automation capabilities. Long-term viability favors vendors with integrated safety-certification labs and IRA-compliant domestic assembly footprints. Watch EPA methane monitoring rule enforcement velocity as inflection indicator for Permian Basin upgrade cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Captive FPGA supply insulates vendors from Taiwan foundry lead time volatility for automotive safety controllers. |
| Edge Computing Platform Launch | Millisecond-latency architectures displace centralized SCADA in Ontario cold chain operations and Gulf Coast chemical processing. |
| System Integrator Network Expansion | First-mover presence in Nuevo León manufacturing clusters captures reshoring capital flows lacking mature service infrastructure. |
| Subscription-Based Software Licensing | Annual SaaS fees for HMI analytics transfer upgrade responsibility to vendors while concentrating revenue predictability from Michigan tier suppliers. |
| Safety Certification Laboratory Investment | In-house UL and SIL testing accelerates qualification timelines that fragmented third-party validation cannot match for IRA-compliant deployments. |
Research Methodology
SEC 10-K filings, EIA industrial power consumption data, and customs import records formed the secondary backbone, cross-referenced with primary interviews spanning control system engineering directors, automotive OEM procurement leads, and system integrator principals across the Great Lakes and Gulf Coast corridors. Bottom-up and top-down triangulation validated segment-level assumptions against macroeconomic industrial production indices.
Bottom-up modeling aggregated unit economics across PLC, HMI, sensor, and robot product categories while top-down cross-checks calibrated against national manufacturing capital expenditure surveys. Segmentation dimensions included technology architecture, end-use vertical, and regional regulatory cluster. CAGRs derived from historical shipment correlations with industrial production indices and automotive platform transition timelines. Forecast inputs incorporated IRA domestic content threshold compliance rates and EPA emissions monitoring retrofit obligation schedules.
Inputs from OSHA machine guarding standard drafts and PMRA equipment validation protocols were available through the study window; gaps in real-time semiconductor foundry capacity utilization introduce uncertainty bands around PLC lead time assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Modular Automation and Services Market
Industrial Automation
Latin America Process Automation Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
Agricultural Automation Market
Industrial Automation
China Factory Automation and Industrial Controls Market
Industrial Automation
Electric Linear Actuator Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Middle East and Africa Industrial Automation Market
Industrial Automation
Global Intelligent Process Automation Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market
Industrial Automation
AI-driven Predictive Maintenance Market
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
Global Healthcare Automation Market
Industrial Automation
Asia-Pacific Automation Components Market