
 Asia Pacific Warehouse Automation Market | 2026-2036
Asia Pacific Warehouse Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Warehouse Automation Market Outlook
Autonomous mobile robotics is tilting the technology stack away from fixed conveyor infrastructure toward flexible, software-orchestrated fulfillment. Daifuku Co., Ltd. anchors high-throughput automated storage and retrieval systems across Japanese automotive parts distribution. Geek+ Inc. competes aggressively on AI-driven fleet management for Chinese e-commerce fulfillment centers. HAI Robotics specializes in cube-based robotic storage that maximizes vertical density in constrained urban warehouse footprints.
Asia Pacific warehouse automation encompasses electromechanical systems, control software, and sensor networks that execute material transport, storage, retrieval, and sortation with minimal human intervention; these installations typically integrate programmable logic controllers, machine vision, and wireless communication protocols to achieve throughput rates exceeding manual operations by an order of magnitude. Robotic Arms command substantial investment in manufacturing end-user environments where precision assembly feed lines require sub-millimeter repeatability. Sortation Systems capture expanding margin pools in e-commerce application settings as parcel volumes fragment into single-item orders. Cloud Computing as a technology layer enables real-time warehouse digital twins that optimize labor deployment across Third-Party Logistics operations.
Japan's METI enforces industrial robot safety standards through JIS certification requirements that shape product design for domestic suppliers and import eligibility. China's SAMR coordinates GB standards for automated guided vehicle interoperability with existing facility infrastructure. India's BIS mandatory certification for electrical control equipment creates compliance thresholds for equipment deployment in Mumbai and Hyderabad pharmaceutical hubs. Stakeholders must weigh national standard divergence against platform standardization economics when configuring multi-country fulfillment networks.
Market Dynamics
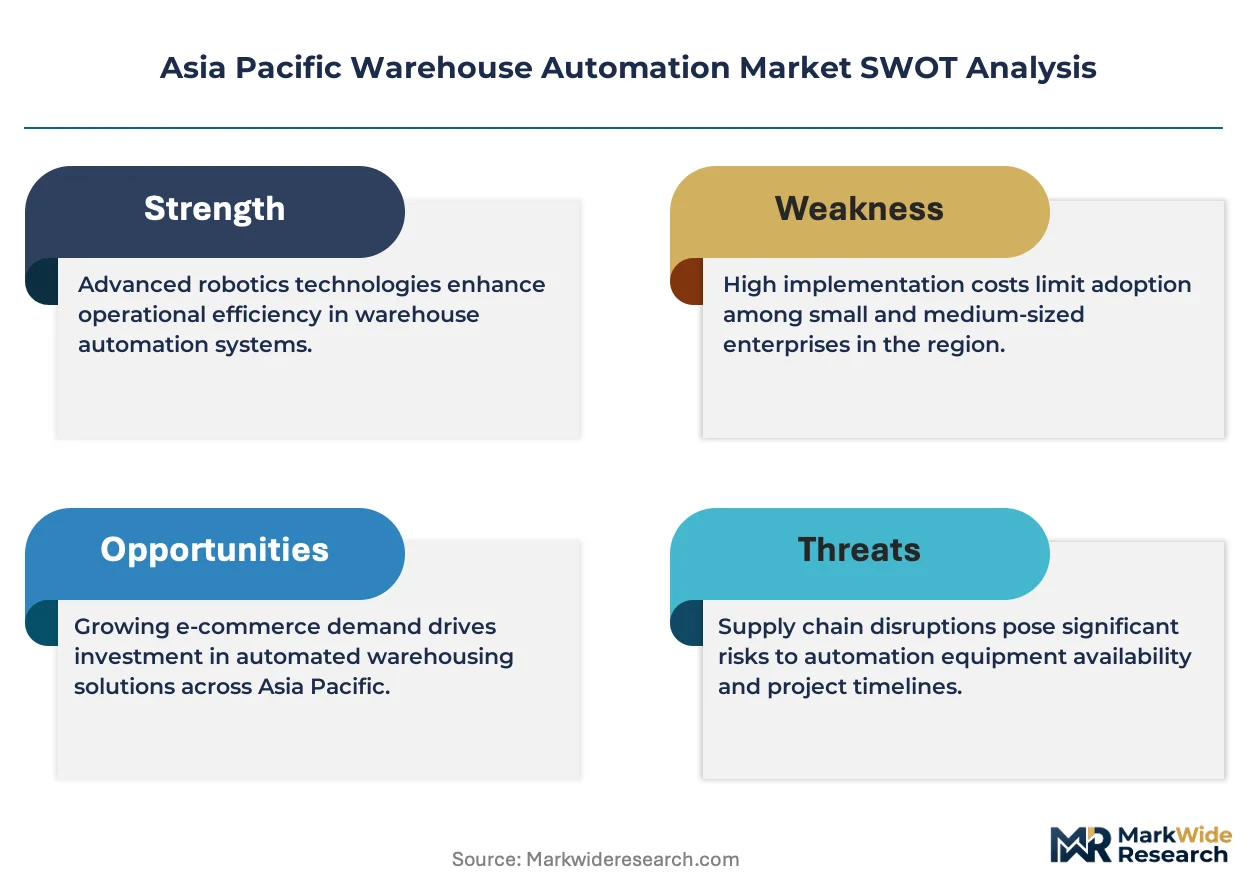
Autonomous mobile robotics is compressing fulfillment timelines across Asia Pacific e-commerce networks, forcing warehouse operators to reconfigure fixed infrastructure investments toward software-defined orchestration platforms that adapt to volatile SKU profiles.
Growth Catalysts
- China's MIIT smart logistics guidelines:National standardization mandates for automated storage density are accelerating retrofit cycles in tier-one fulfillment hubs around Shanghai and Shenzhen.
- Pharmaceutical cold-chain expansion:Temperature-controlled automation deployment in Hyderabad and Mumbai is creating specialized demand for robotic handling systems certified to CDSCO pharmaceutical storage protocols.
- Japan's METI robotics roadmaps:JIS certification requirements for collaborative robots are streamlining import eligibility and domestic procurement specifications for automotive parts distributors.
Market Restraints
- Indium and rare-earth magnet cost volatility:Permanent magnet supply concentration in Chinese processing facilities is squeezing margins for robotic motor manufacturers serving Southeast Asian integrators.
- Legacy PLC interoperability gaps:Proprietary communication protocols from established Japanese and European automation vendors create technical friction for cloud-native fleet management deployments.
- India's BIS electrical certification timelines:Mandatory testing for control equipment in Mumbai pharmaceutical hubs extends deployment lead times by 8-14 weeks against project schedules.
Strategic Opportunities
- Vietnam's underpenetrated northern industrial corridor:Samsung and Foxconn supplier parks around Bac Ninh lack automated material handling density comparable to Chinese tier-two cities.
- 5G-private network convergence with edge AI:Real-time robotic coordination without fixed infrastructure is enabling greenfield warehouse designs in Australian mining logistics.
- Thailand's Board of Investment automation incentives:Tax holidays for smart factory investments are pulling Japanese automotive suppliers toward Bangkok-region fulfillment automation.
Industry Challenges
- Scarce mechatronics integration specialists:Deployment of multi-vendor robotic fleets requires cross-trained engineers fluent in both Japanese PLC architectures and Chinese AI middleware.
- Fragmented GB-SAMR standard evolution:China's automated guided vehicle interoperability mandates are shifting faster than vendor firmware update cycles, forcing premature obsolescence risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Warehouse Automation Market |
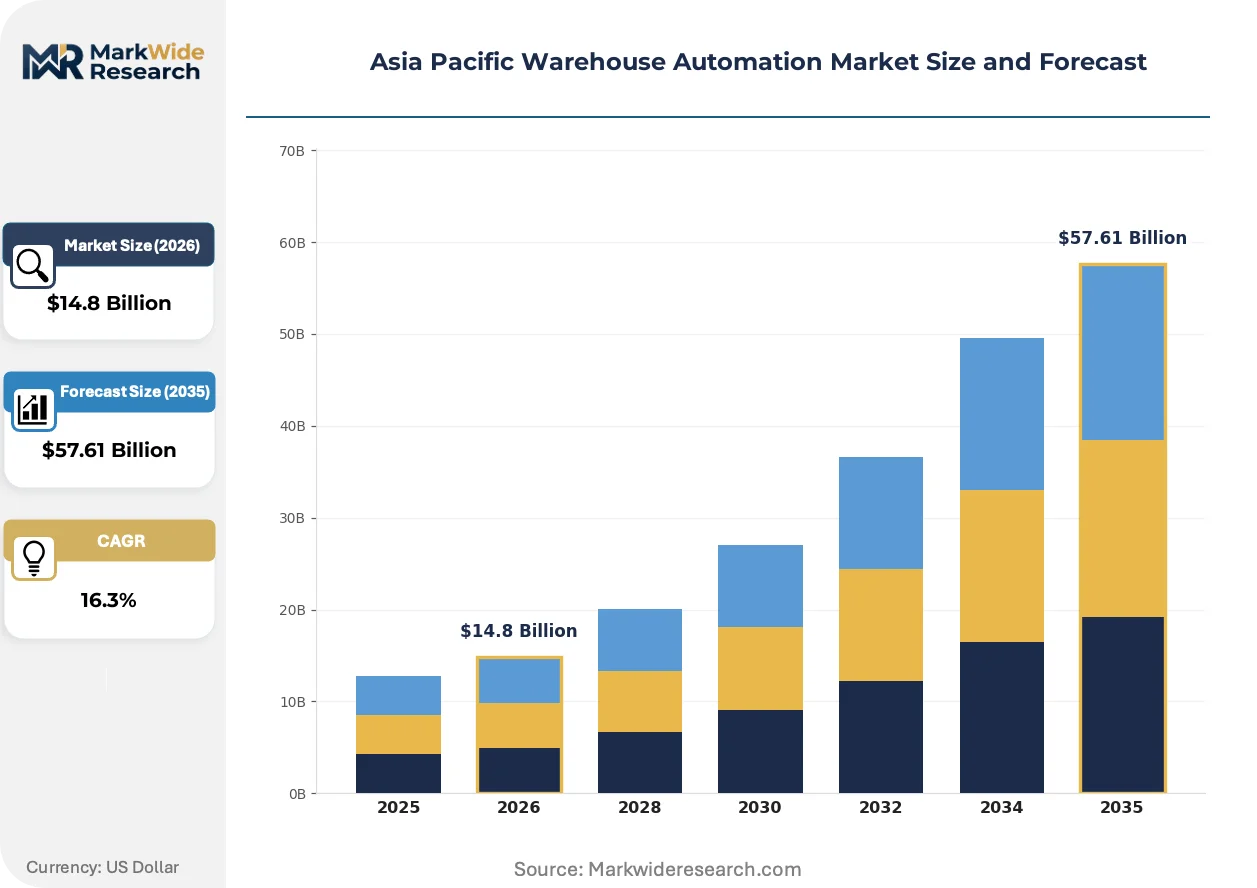
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $57.61 Billion |
| CAGR (2026 – 2036) | 16.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Robotic Arms, Conveyor Systems, Sortation Systems Application: Food & Beverage, Retail, Pharmaceuticals, E-commerce End User: Third-Party Logistics, Manufacturing, Wholesale Distribution, E-commerce Retailers Technology: Artificial Intelligence, Internet of Things, Machine Learning, Cloud Computing |
| Companies Covered | Daifuku Co., Ltd., Murata Machinery, Ltd., Swisslog Holding AG, Geek+ Inc., GreyOrange Pte. Ltd., HAI Robotics, Toyota Material Handling, Yaskawa Electric Corporation, ABB Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Warehouse Automation Market Strategic Shifts
Software-defined fulfillment architectures are displacing electromechanical fixed-path systems across Asia Pacific distribution networks, compressing the traditional 10-year infrastructure depreciation cycles toward 4-6 year technology refresh timelines.
Cube-based robotic storage is migrating from Chinese e-commerce fulfillment centers into Japanese pharmaceutical distribution networks. PMDA-certified cold-chain operators in Osaka and Tokyo are piloting vertical density systems that recover 40% floor space against traditional racking. The technology is migrating from high-SKU apparel sortation toward temperature-validated pharmaceutical buffer storage where space constraints in urban logistics hubs command premium lease rates.
China's SAMR GB standards for automated guided vehicle interoperability are forcing facility retrofit investments across existing warehouse footprints. The regulations mandate wireless communication protocols that conflict with legacy 2.4 GHz industrial Wi-Fi installations in facilities built before 2019. Third-party logistics operators in Guangdong and Jiangsu provinces are most affected, responding with phased infrastructure replacement rather than greenfield construction.
Same-day delivery promises from Southeast Asian e-commerce platforms are compressing buyer tolerance for capital expenditure recovery periods. Procurement committees at Indonesian and Vietnamese retail conglomerates now evaluate automation vendors on 24-month payback thresholds rather than traditional 5-year ROI models. The behavioral shift is most visible in Jakarta and Ho Chi Minh City, where fulfillment network density is becoming a competitive moat against cross-border marketplace entrants.
Asia Pacific Warehouse Automation Market Segmentation
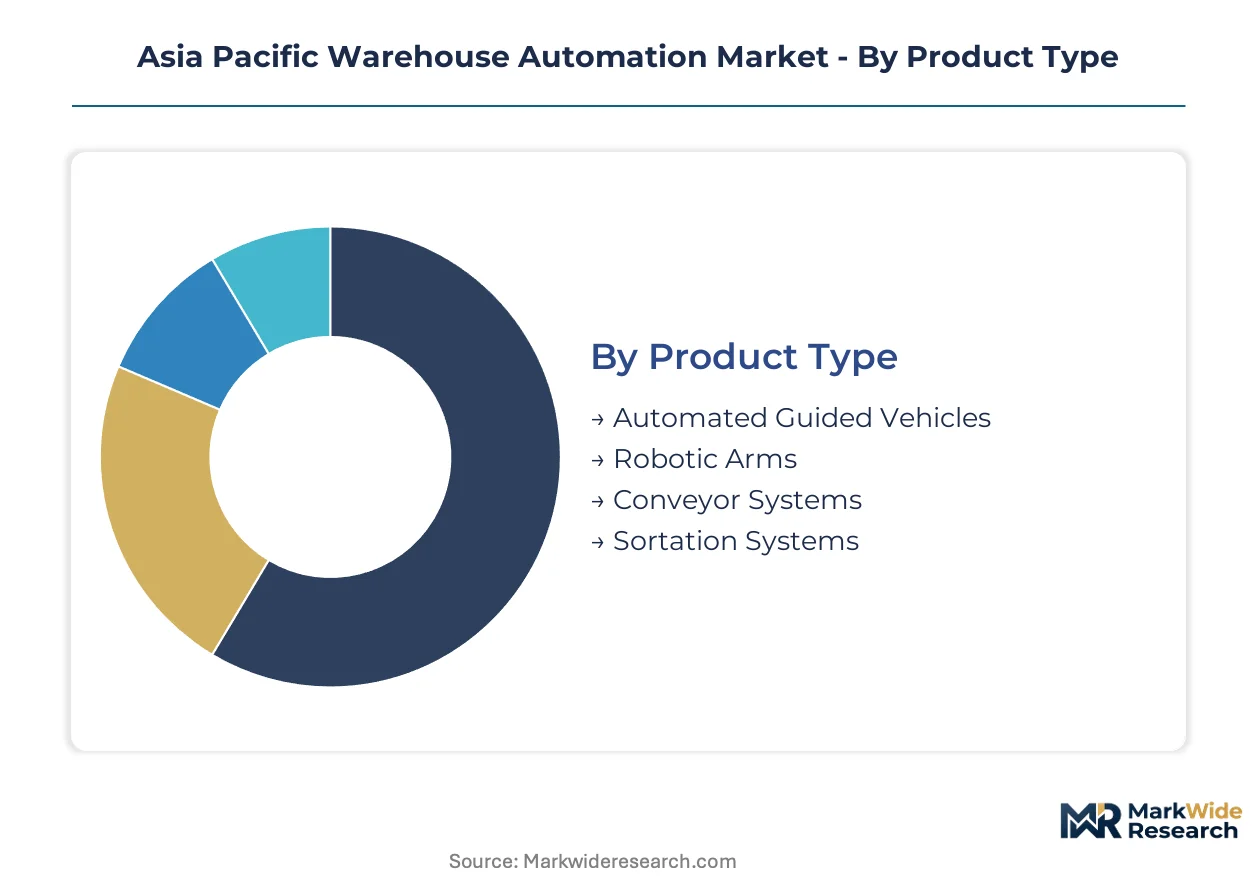
Segmentation reveals how warehouse automation value pools concentrate across hardware platforms, software layers, and customer archetypes. Each dimension carries distinct margin profiles and deployment complexity that shape vendor strategy across the Asia Pacific region.
Product Type:
After-sales service intensity varies dramatically across hardware categories, with mobile robotics demanding continuous fleet management while fixed infrastructure requires periodic component replacement.
- Automated Guided Vehicles:Battery-powered mobile platforms navigate via magnetic tape, laser guidance, or vision systems to transport pallets and totes through facility corridors. Demand concentrates in Chinese e-commerce fulfillment centers around Shanghai and Shenzhen where MIIT standardization mandates accelerate retrofit timelines. Fleet management software subscriptions now generate recurring revenue streams that rival initial hardware margins.
- Robotic Arms:Articulated manipulators deliver sub-millimeter repeatability for pick-and-place, palletizing, and depalletizing operations in high-throughput environments. Japanese automotive parts distributors in Nagoya and Osaka deploy collaborative variants certified to METI JIS standards for human-robot workcell integration. Precision gearbox maintenance contracts extend vendor relationships across 10-year operational lifecycles.
- Conveyor Systems:Belt and roller configurations form the backbone of fixed-path material flow in established distribution facilities.
- Sortation Systems:Cross-belt, tilt-tray, and sliding-shoe technologies direct parcels to outbound shipping lanes based on destination routing.
Conveyor Systems hold the largest share; momentum sits with Automated Guided Vehicles.
Application:
Application-driven procurement patterns separate temperature-validated deployments from ambient operations, with pharmaceutical and food segments commanding premium pricing for compliance-certified installations.
- Pharmaceuticals:Cold-chain automation in Hyderabad and Mumbai requires robotic systems certified to CDSCO temperature-mapping protocols for vaccine and biologics storage. India's BIS electrical certification creates 8-14 week deployment lead times that favor established integrators with regulatory navigation expertise. PMDA-certified operators in Osaka and Tokyo are piloting cube-based vertical storage to recover premium urban floor space.
- E-commerce:Same-day delivery promises from Southeast Asian platforms compress capital recovery thresholds to 24-month payback models in Jakarta and Ho Chi Minh City. Procurement committees evaluate vendors on software-defined orchestration capabilities rather than fixed infrastructure durability. Cloud-native fleet management enables rapid reconfiguration for volatile SKU profiles during promotional surge periods.
- Food & Beverage:Temperature-controlled automation handles perishable inventory with FIFO rotation compliance and traceability documentation.
- Retail:Store replenishment and omnichannel fulfillment drive demand for flexible automation in urban distribution hubs.
Pharmaceuticals commands premium pricing; E-commerce is expanding most quickly.
End User:
End-user sophistication determines whether deployments prioritize operational control or capital efficiency, separating asset-heavy manufacturers from logistics outsourcing specialists.
- Third-Party Logistics:Multi-tenant operators in Guangdong and Jiangsu provinces face SAMR GB standard retrofit mandates conflicting with legacy 2.4 GHz industrial Wi-Fi infrastructure. Cloud Computing layers enable real-time digital twins that optimize labor deployment across fragmented customer portfolios. Phased infrastructure replacement dominates over greenfield construction given lease term constraints.
- Manufacturing:Automotive and electronics producers in Thailand's Board of Investment zones leverage tax holidays to justify smart factory investments around Bangkok. Japanese suppliers require JIS-certified collaborative robots for assembly feed lines with human-robot interaction safety protocols. Precision repeatability specifications favor established PLC architectures over cloud-native alternatives.
- E-commerce Retailers:Vertical integration of fulfillment networks creates competitive moats against cross-border marketplace entrants in Indonesia and Vietnam.
- Wholesale Distribution:Bulk handling operations prioritize throughput density over SKU flexibility in regional distribution centers.
Third-Party Logistics holds the largest share; momentum sits with E-commerce Retailers.
Technology:
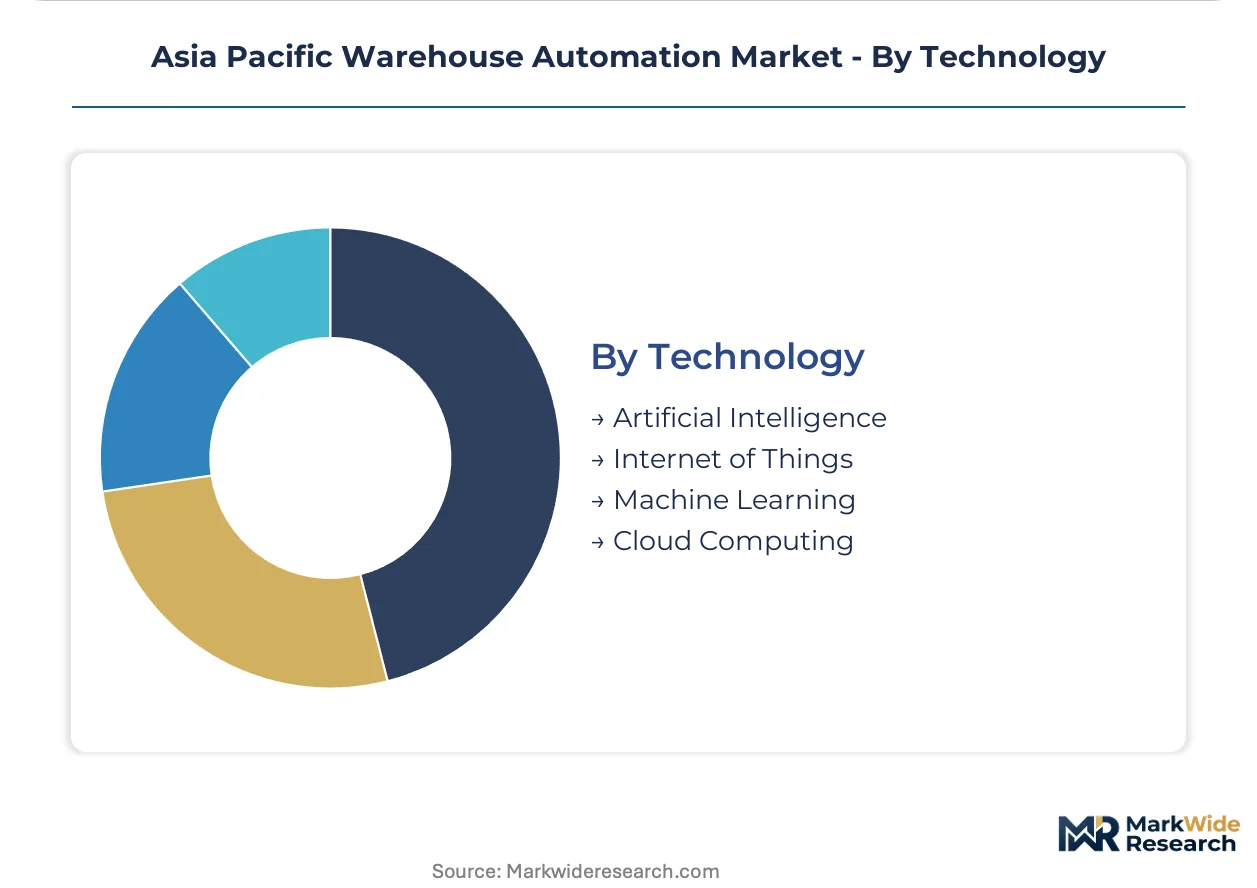
Technology layering determines system adaptability, with edge-AI deployments enabling real-time coordination without fixed infrastructure dependency.
- Cloud Computing:Centralized data architectures support warehouse digital twins that simulate labor deployment scenarios and predict maintenance windows. Australian mining logistics operators leverage 5G-private network convergence for real-time robotic coordination in remote greenfield designs. Subscription pricing models shift vendor economics from capital equipment toward recurring platform revenue.
- Artificial Intelligence:Computer vision and path optimization algorithms enable autonomous navigation in dynamic environments with human pedestrian traffic. Fleet management platforms from Chinese vendors compete on AI-driven orchestration for high-SKU apparel sortation. Algorithm update cycles create ongoing vendor dependency beyond initial hardware deployment.
- Machine Learning:Demand forecasting models optimize inventory positioning and labor scheduling based on historical throughput patterns.
- Internet of Things:Sensor networks provide equipment health monitoring and environmental condition tracking across distributed facility footprints.
Cloud Computing holds the largest share; Artificial Intelligence shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement committees across the Asia Pacific region concentrate in three distinct buyer archetypes: Japanese automotive distributors prioritizing JIS-certified collaborative robotics, Chinese e-commerce operators demanding cloud-native fleet orchestration, and Indian pharmaceutical logistics specialists requiring CDSCO-validated cold-chain automation.
China
Shanghai and Shenzhen fulfillment hubs drive retrofit demand as MIIT smart logistics guidelines mandate automated storage density standards. SAMR coordinates GB standards for automated guided vehicle interoperability that conflict with legacy 2.4 GHz industrial Wi-Fi infrastructure in pre-2019 facilities. Guangdong and Jiangsu province operators respond with phased infrastructure replacement rather than greenfield construction.
Japan
Nagoya and Osaka automotive parts distributors deploy collaborative robots certified to METI JIS standards for human-robot workcell integration. METI robotics roadmaps streamline import eligibility and domestic procurement specifications for precision assembly feed lines. PMDA-certified cold-chain operators in Tokyo pilot cube-based vertical storage systems to recover premium urban floor space.
India
Hyderabad and Mumbai pharmaceutical cold-chain hubs require robotic handling systems certified to CDSCO temperature-mapping protocols for vaccine and biologics storage. BIS mandatory certification for electrical control equipment extends deployment lead times by 8-14 weeks against project schedules. Established integrators with regulatory navigation expertise capture preference over new market entrants.
Vietnam
Samsung and Foxconn supplier parks around Bac Ninh lack automated material handling density comparable to Chinese tier-two cities. Thailand's Board of Investment automation incentives pull Japanese automotive suppliers toward Bangkok-region fulfillment automation as regional alternatives. Northern industrial corridor underpenetration creates first-mover positioning for vendors with proven Southeast Asian deployment experience.
Australia
Mining logistics operators leverage 5G-private network convergence with edge AI for real-time robotic coordination in remote greenfield warehouse designs. Cloud-native fleet management enables rapid reconfiguration without fixed infrastructure dependency in distributed operational footprints. Subscription pricing models shift vendor economics from capital equipment toward recurring platform revenue streams.
Asia Pacific Warehouse Automation Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered market structure where Japanese industrial conglomerates anchor high-throughput fixed infrastructure while Chinese AI-native vendors capture flexible orchestration contracts. The vendor base separates into three strategic archetypes: diversified industrial automation conglomerates with century-long manufacturing heritage, venture-backed robotics pure-plays competing on software-defined fulfillment, and regional system integrators with regulatory navigation expertise. Dominant competitive moves include strategic partnerships between hardware fabricators and cloud platform providers, plus geographic expansion through local joint ventures to circumvent certification timeline penalties.
Within the diversified conglomerate tier, Daifuku Co., Ltd. and Murata Machinery, Ltd. represent Japanese industrial automation heritage with established positions in automotive parts distribution. Among venture-backed robotics specialists, Geek+ Inc. and HAI Robotics occupy positions exemplifying the shift toward AI-driven fleet management and cube-based vertical storage density. Yaskawa Electric Corporation anchors the precision motion control segment where collaborative robot safety certification creates vendor stickiness across decade-long operational lifecycles.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Murata Machinery, Ltd. |
| Swisslog Holding AG |
| Geek+ Inc. |
| GreyOrange Pte. Ltd. |
| HAI Robotics |
| Toyota Material Handling |
| Yaskawa Electric Corporation |
| ABB Ltd. |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Shenzhen freight corridors transmit cost volatility from rare-earth processing concentration directly into robotic motor pricing tiers, while downstream buyers in Japanese automotive distribution and Indian pharmaceutical cold-chain hubs face divergent price elasticity based on certification requirements and lease-term constraints.
Pricing Analysis
Cost-plus contracts with rare-earth magnet indexation dominate procurement agreements for autonomous mobile robotics fleets serving Southeast Asian e-commerce fulfillment networks. Pricing stratifies across JIS-certified premium tiers for Japanese automotive distributors, CDSCO-validated mid-tiers for Indian pharmaceutical operators, and standard economy tiers for ambient warehouse retrofits in Vietnam and Indonesia. Cost compression in economy-tier AGV motors is intensifying because Chinese processing facility concentration for neodymium and dysprosium feeds through to bill-of-materials pressure. Third-party logistics operators in Guangdong and Jiangsu provinces exhibit highest price sensitivity due to SAMR-mandated infrastructure replacement cycles, while PMDA-certified pharmaceutical distributors in Osaka and Tokyo absorb premium pricing for temperature-validated cube storage systems.
Supply Chain Analysis
Upstream feedstock for permanent magnet motors draws from Chinese rare-earth separation facilities, Japanese precision gearbox foundries, and South Korean battery cell manufacturers serving mobile robotics platforms. Critical component dependencies include neodymium-iron-boron magnets, harmonic drive reducers, and lithium-nickel-manganese-cobalt cathode materials. Single-source vulnerability concentrates in Chinese rare-earth oxide processing, where export license volatility creates 8-14 week component availability gaps. Distribution runs through regional system integrators with BIS and JIS certification navigation expertise, who capture margin pools between hardware fabricators and end-user deployment committees in Mumbai, Hyderabad, Nagoya, and Bangkok.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as SAMR GB standard interoperability mandates force vendor selection around software-defined orchestration ecosystems rather than discrete hardware specifications.
For Market Incumbents: Pre-empt cloud-native fleet management displacement by acquiring AI middleware capabilities or forming exclusive platform partnerships with Chinese robotics pure-plays. Daifuku and Murata Machinery must accelerate firmware update cycles to match SAMR's shifting AGV interoperability mandates, or risk premature obsolescence in Guangdong retrofit contracts. JIS certification maintenance and precision gearbox service contracts provide defensive moats against price erosion in Japanese automotive distribution.
For New Entrants and Emerging Players: Build out regulatory navigation capabilities for India's BIS electrical certification timelines, where 8-14 week deployment lead times create preference for established integrators. Vietnam's Bac Ninh industrial corridor offers the most penetrable geography, with Samsung and Foxconn supplier parks lacking automated material handling density comparable to Chinese tier-two cities. Position around 5G-private network convergence with edge AI for Australian mining logistics greenfield designs, where subscription pricing models shift procurement criteria toward recurring platform value.
For Investors and Strategic Acquirers: Regional system integrators with multi-country certification expertise represent the most defensible acquisition archetype, as divergence between Japan's JIS, China's GB, and India's BIS standards forces specialized regulatory navigation. Long-term viability hinges on software-defined fulfillment platform economics displacing fixed infrastructure depreciation cycles. Watch for SAMR issuing updated AGV wireless protocol mandates that outpace incumbent firmware refresh capabilities, signaling accelerated market share transfer toward AI-native vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cloud-native fleet management from Geek+ and HAI Robotics enables rapid reconfiguration for volatile SKU profiles during promotional surges. |
| Regulatory Certification Investment | JIS collaborative robot safety standards and CDSCO cold-chain protocols create vendor stickiness across decade-long operational lifecycles. |
| Backward Integration into Rare-Earth Magnet Supply | Vertical control over neodymium processing mitigates cost volatility from Chinese export license uncertainty. |
| Geographic Expansion via Joint Ventures | Local partnerships in Vietnam and Thailand circumvent BIS certification timeline penalties and accelerate deployment schedules. |
| 5G-Private Network Infrastructure Partnership | Edge-AI robotic coordination without fixed infrastructure dependency enables greenfield warehouse designs in Australian mining logistics. |
Study Parameters
A standing panel of warehouse operations directors, robotics procurement leads, system integration engineers, and pharmaceutical cold-chain compliance officers provided ongoing calibration against secondary validation from MIIT smart logistics guideline releases, SAMR GB standard documentation, METI robotics roadmap publications, and BIS electrical certification procedural records. Bottom-up installation data from tier-one fulfillment hubs in Shanghai, Shenzhen, and Jakarta triangulated against top-down vendor revenue disclosures across the analysis window.
Scenario-bracketing framed projections across hardware platform, software layer, application, and end-user segmentation dimensions, with CAGRs derived from elasticity modeling against e-commerce delivery promise compression and pharmaceutical cold-chain regulatory expansion. Forecast inputs incorporated SAMR interoperability mandate implementation timelines, METI JIS certification update cycles, and 5G-private network deployment curves in Australian mining regions.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native platform investments by diversified industrial conglomerates or accelerated SAMR standard evolution would shift outcomes beyond modeled ranges. Cross-checking against MIIT smart logistics infrastructure disclosure timelines and METI robotics roadmap revision frequency is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Computer-Aided Manufacturing (CAM) Market
Industrial Automation
Industrial Automation Spares Market
Industrial Automation
Global Industrial Wireless Automation Market
Industrial Automation
Port Equipment Automation Market
Industrial Automation
Middle East and Africa Process Automation Market
Industrial Automation
Industrial Automation Motion Control System Software Market
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Refining Industry Automation and Software Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Programmable Automation Controller (PAC) Market
Industrial Automation
Forklift-Mounted Computers Market
Industrial Automation
Industrial Internet Connectivity Tracker Market