
 Global Smart Manufacturing Platform Market | 2026-2036
Global Smart Manufacturing Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Manufacturing Platform Market Foresight
Southeast Asia's manufacturing base is tilting toward digital infrastructure as Vietnam, Thailand, and Indonesia expand electronics and automotive output. Siemens AG leverages its digital twin portfolio to anchor European factory modernization. Microsoft Corporation competes through Azure IoT integration with existing enterprise software stacks. Schneider Electric specializes in edge-to-cloud architectures for energy-intensive process industries.
A smart manufacturing platform is an integrated software environment that collects, processes, and analyzes operational data from production assets using IoT connectivity, digital twin modeling, and AI-driven analytics to optimize throughput and quality. These platforms typically process sub-second machine telemetry through edge nodes before cloud aggregation, enabling real-time decision loops that reduce unplanned downtime. Cloud-based deployments now capture the largest revenue pool as manufacturers prioritize scalable infrastructure over capital-heavy on-premise installations. Predictive maintenance applications are expanding fastest among aerospace and pharmaceutical end users where asset failure carries regulatory and safety consequences.
The U.S. FDA's 21 CFR Part 11 framework shapes data integrity requirements for pharmaceutical platform deployments, while China's MIIT mandates GB standards for industrial data security in smart factory certifications. The EU AI Act imposes risk-classification obligations on automated quality control systems, creating compliance complexity for exporters. Stakeholders must weigh regulatory divergence against platform standardization when architecting multi-country deployments.
Market Dynamics
Automotive OEMs are forcing platform vendors to compress deployment timelines as connected factory mandates from Volkswagen, BMW, and Toyota reshape procurement specifications. Edge-to-cloud latency requirements now dictate architecture decisions more than capital cost.
Growth Catalysts
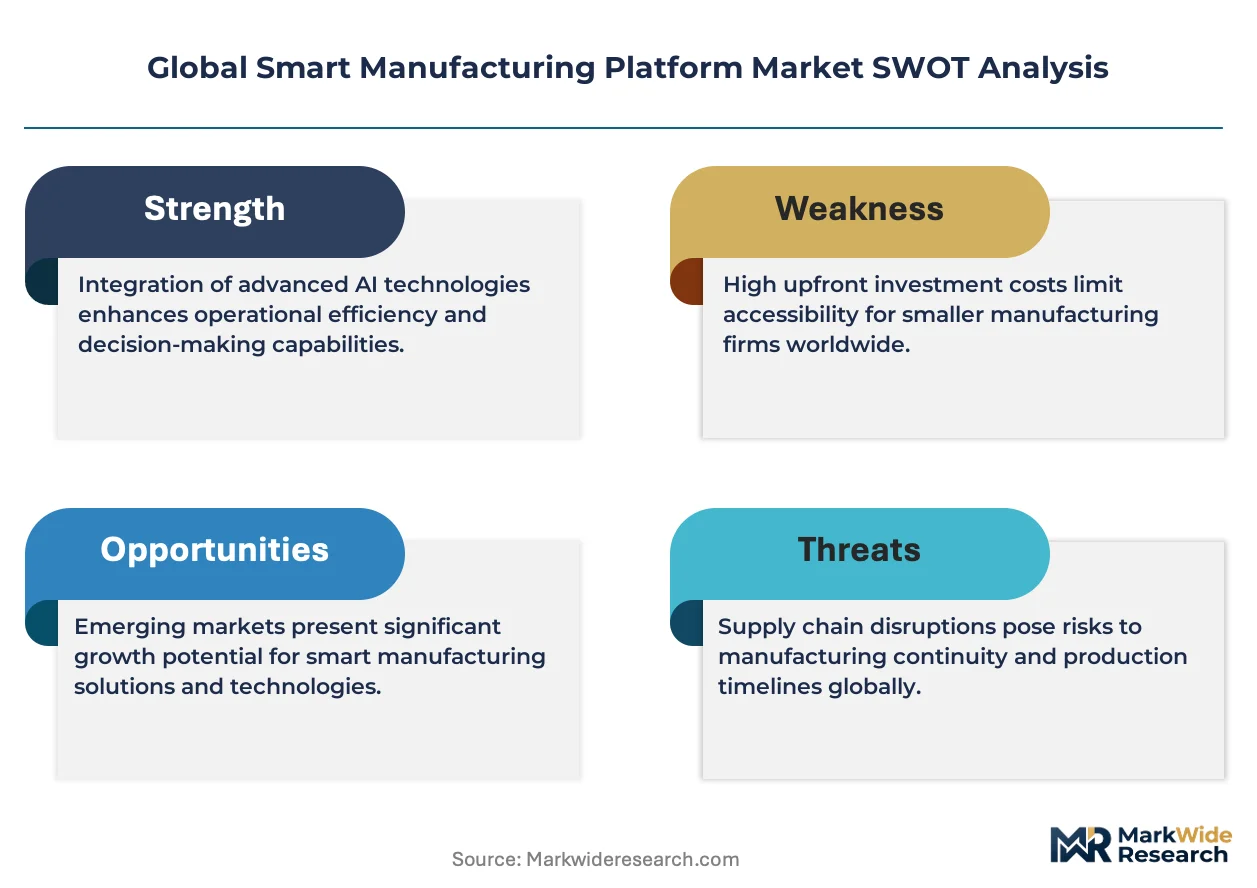
- EU AI Act risk classification:Automated quality control systems in German automotive plants must now embed explainable AI, creating replacement demand for legacy black-box analytics.
- Pharmaceutical serialization mandates:FDA 21 CFR Part 11 enforcement on electronic batch records drives platform upgrades at Merck and Pfizer facilities.
- Industrial data security:China's MIIT GB standards for smart factory certification block non-compliant foreign platforms from state-backed tenders.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundry capacity constraints throttle edge device production for predictive maintenance nodes.
- Interoperability fragmentation:Proprietary OT protocols from Siemens, Rockwell, and Schneider prevent seamless multi-vendor platform integration.
- Energy cost volatility:German industrial electricity prices above 25 euro cents per kilowatt-hour compress margins for energy-intensive AI training workloads.
Strategic Opportunities
- Vietnam electronics corridor:Samsung and Foxconn contract manufacturers lack mature platform vendors, creating first-mover whitespace for cloud-native entrants.
- Digital twin convergence with generative AI:Physics-informed neural networks reduce simulation calibration time from weeks to hours for aerospace tooling design.
- India PLI scheme incentives:Production-linked subsidies for advanced manufacturing cover 25% of platform software costs for domestic electronics and automotive suppliers.
Industry Challenges
- OT-IT skill synthesis:Combined expertise in programmable logic controllers and Kubernetes orchestration remains scarce in Midwest US and Ruhr Valley labor pools.
- Legacy asset retrofit complexity:Brownfield installations require custom protocol gateways for 1990s-era CNC machines, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Manufacturing Platform Market |
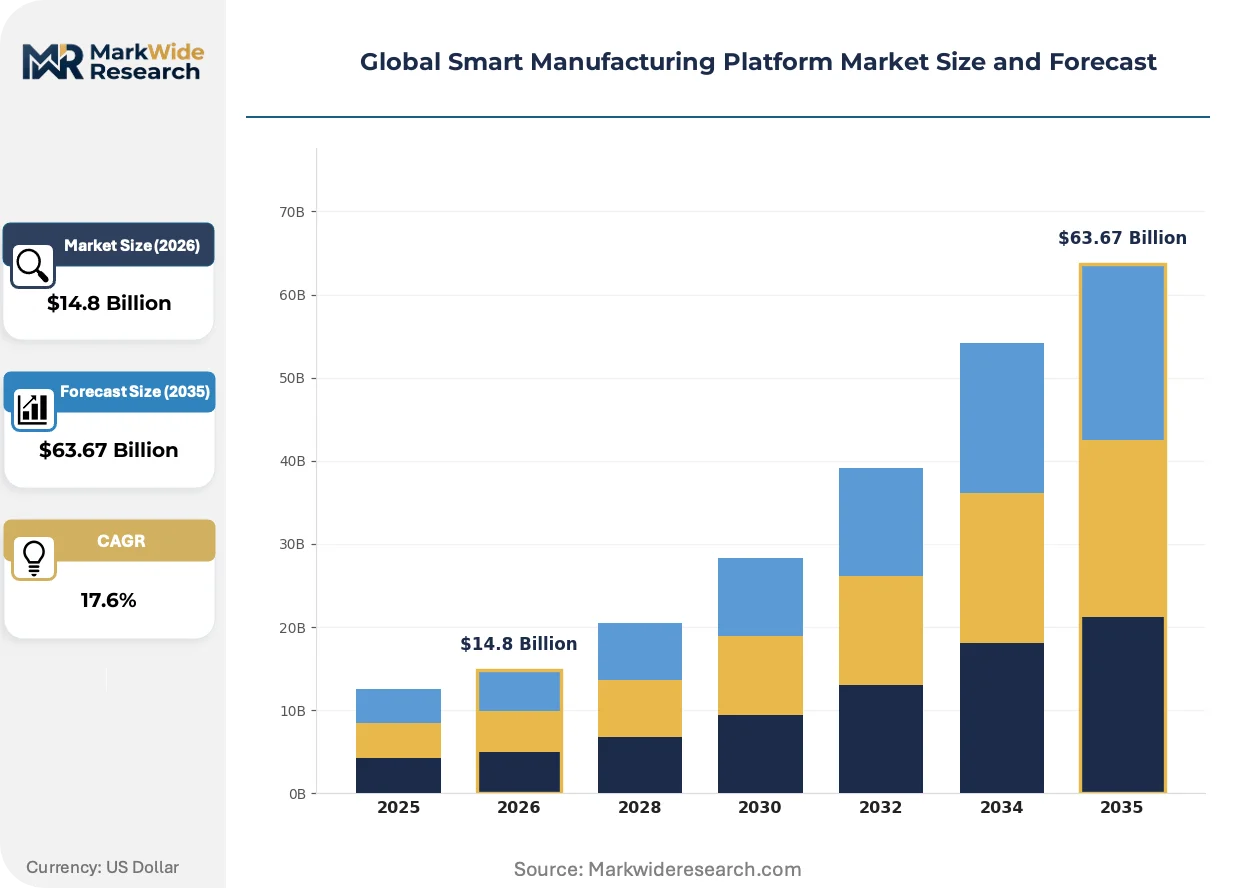
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $63.67 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Cloud-Based, On-Premise, Hybrid, Edge Computing Technology: AI & Machine Learning, Digital Twin, IoT Connectivity, Big Data Analytics, Cybersecurity Application: Predictive Maintenance, Quality Control, Production Optimization, Supply Chain Management, Asset Tracking End User Industry: Electronics, Aerospace, Consumer Goods, Pharmaceuticals, Food Processing |
| Companies Covered | Microsoft Corporation, IBM Corporation, Siemens AG, ABB Group, SAP SE, Rockwell Automation, General Electric, Honeywell International, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Manufacturing Platform Market Shifts & Advancements
Platform architectures are bifurcating between hyperscale cloud stacks and sovereign edge deployments as data residency requirements harden. Vendors must now engineer for jurisdictional fragmentation rather than uniform global rollout.
Digital twin technology is hybridizing physics-based simulation with real-time machine learning inference. Aerospace manufacturers at Airbus and Lockheed Martin deploy these fused models for predictive structural fatigue analysis. The convergence collapses separate CAE and MLOps budgets into unified platform contracts.
EU AI Act enforcement is mandating human-in-the-loop overrides for high-risk automated decisions. German automotive suppliers must redesign quality inspection pipelines to enable operator intervention within 500 milliseconds. This regulatory friction favors European platform vendors with pre-certified compliance modules over US cloud entrants.
Service contracting is fragmenting from perpetual licenses toward consumption-based runtime pricing. Pharmaceutical buyers at GSK and AstraZeneca now negotiate platform fees tied to validated batch throughput rather than seat counts. The shift concentrates vendor risk in manufacturing uptime guarantees and compresses upfront implementation revenue.
Global Smart Manufacturing Platform Market Segmentation
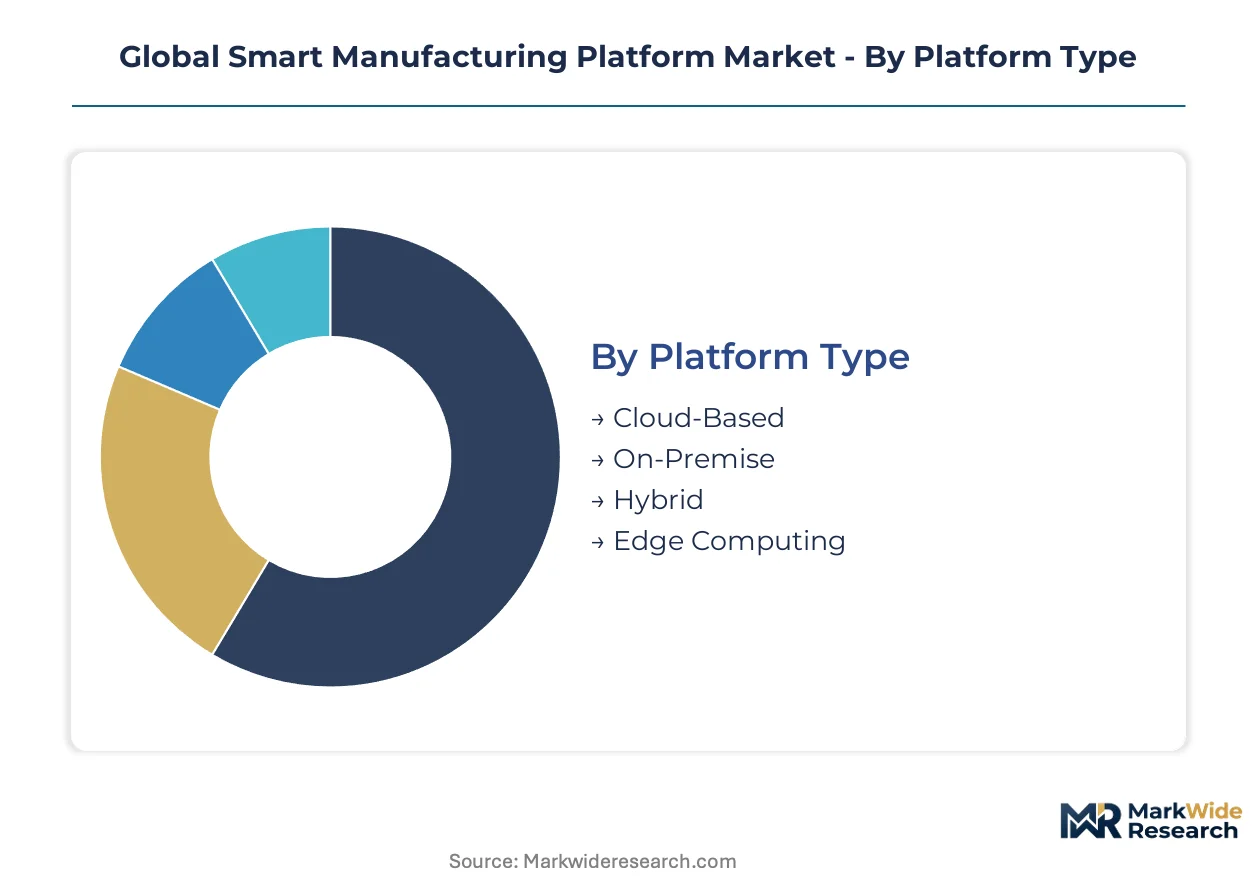
Smart manufacturing platforms segment across deployment architectures, analytical engines, operational use cases, and vertical compliance requirements. Each dimension carries distinct procurement cycles, with cloud infrastructure refreshing annually while pharmaceutical validation processes extend platform lifecycles to seven years. Procurement committees weigh these temporal mismatches when consolidating vendor relationships.
Platform Type:
Cloud-based deployments turn over fastest as manufacturers chase scalable compute for AI training workloads, while on-premise installations persist longest in defense and pharmaceutical facilities with data sovereignty mandates.
- Cloud-Based:Hyperscale infrastructure enables elastic scaling for seasonal production surges without capital expenditure. Automotive OEMs in Germany's industrial corridor prioritize these deployments for connected factory rollouts where Volkswagen and BMW mandate sub-100ms latency for quality inspection pipelines. The EU AI Act's risk classification requirements accelerate replacement of legacy black-box systems with explainable cloud-native alternatives.
- Hybrid:Split architectures process sensitive OT data locally while aggregating analytics in sovereign cloud regions. Aerospace manufacturers at Airbus deploy hybrid models to satisfy both ITAR compliance and cross-facility benchmarking needs. Procurement cycles average three to four years as edge hardware refresh desynchronizes from cloud subscription renewals.
- On-Premise:Air-gapped installations dominate pharmaceutical facilities subject to FDA 21 CFR Part 11 validation requirements. Merck and Pfizer facilities maintain these deployments for electronic batch record integrity despite higher total cost of ownership.
- Edge Computing:Distributed nodes process sub-second machine telemetry before cloud aggregation. Predictive maintenance applications in semiconductor fabs drive fastest growth here as Taiwan-based foundry constraints throttle device availability.
Cloud-based platforms anchor the volume base while edge computing deployments gain share at the steepest rate.
Technology:
Technology layers stratify by margin structure, with cybersecurity modules commanding premium pricing against commoditized IoT connectivity stacks.
- AI & Machine Learning:Physics-informed neural networks collapse aerospace tooling simulation calibration from weeks to hours. German automotive suppliers embed explainable AI to satisfy EU AI Act human-in-the-loop mandates within 500-millisecond intervention windows.
- Digital Twin:Fused physics-based and machine learning models enable predictive structural fatigue analysis at Lockheed Martin. These implementations consolidate separate CAE and MLOps budgets into unified platform contracts with five-year lifecycles.
- IoT Connectivity:Protocol translation gateways bridge proprietary OT systems from Siemens, Rockwell, and Schneider. Brownfield retrofits of 1990s-era CNC machines extend deployment timelines by eight to fourteen months.
- Big Data Analytics:Historian functions aggregate multi-year operational datasets for trend analysis. Pharmaceutical buyers at GSK negotiate consumption-based pricing tied to validated batch throughput rather than seat counts.
- Cybersecurity:ISO 27001 certification modules address EU AI Act and China MIIT GB standards simultaneously. Multi-jurisdictional compliance complexity favors European vendors with pre-certified architectures over US cloud entrants.
IoT connectivity generates the highest transaction volume while digital twin technology climbs the fastest as aerospace and automotive procurement concentrates.
Application:
Application modules diverge by customer sophistication, with predictive maintenance requiring deepest OT integration while asset tracking deploys through standardized APIs.
- Predictive Maintenance:Real-time vibration and thermal analysis prevents unplanned downtime in energy-intensive process industries. Aerospace and pharmaceutical end users prioritize these applications where asset failure carries regulatory and safety consequences.
- Quality Control:Automated visual inspection pipelines must enable operator override within regulatory-mandated windows. EU AI Act enforcement redesigns these systems for explainability, displacing legacy black-box analytics.
- Production Optimization:Throughput balancing algorithms coordinate multi-site manufacturing networks. Vietnam's electronics corridor lacks mature platform vendors, creating whitespace for cloud-native entrants targeting Samsung and Foxconn contract manufacturers.
- Supply Chain Management:Serialization tracking satisfies pharmaceutical mandates for end-to-end batch provenance. FDA 21 CFR Part 11 enforcement drives platform upgrades at Merck and Pfizer facilities.
- Asset Tracking:RFID and BLE beacon deployments monitor work-in-progress inventory without deep ERP integration. Consumer goods manufacturers deploy these modules fastest due to lower change management requirements.
Quality control applications anchor installed base value while predictive maintenance expands most quickly among regulated industries.
End User Industry:
Industry verticals separate by compliance burden and capital intensity, with pharmaceuticals tolerating longest validation cycles and consumer goods demanding fastest time-to-value.
- Electronics:High-mix, low-volume production environments require rapid reconfiguration of digital twin parameters. India's PLI scheme subsidies cover twenty-five percent of platform software costs for domestic suppliers.
- Aerospace:AS9100 quality standards and ITAR regulations mandate air-gapped or sovereign cloud deployments. Physics-informed neural networks reduce tooling design iteration cycles dramatically.
- Consumer Goods:Seasonal demand volatility drives preference for consumption-based runtime pricing over perpetual licenses. Procurement teams prioritize rapid deployment over deep customization.
- Pharmaceuticals:FDA validation requirements and EU GMP Annex 11 compliance extend platform procurement to eighteen-month cycles. Electronic batch record integrity mandates dominate vendor selection criteria.
- Food Processing:HACCP traceability requirements intersect with sustainability reporting under CSRD for European exporters. Smaller facilities lag in platform adoption due to OT-IT skill scarcity.
Electronics manufacturing anchors platform revenue volume while pharmaceutical applications demonstrate steepest expansion trajectory as serialization mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Edge device supply chains concentrate in Taiwanese foundry capacity, while platform deployment demand spreads across German automotive corridors, Vietnamese electronics zones, and American pharmaceutical clusters. Regulatory divergence between the EU AI Act, China's MIIT standards, and FDA validation requirements fragments vendor standardization efforts.
Germany
Automotive OEMs at Volkswagen and BMW mandate sub-100ms latency for quality inspection pipelines. The EU AI Act's risk classification framework forces explainable AI retrofits in Stuttgart and Munich manufacturing zones. Siemens anchors Industry 4.0 integration across the Baden-Württemberg industrial corridor.
United States
Pharmaceutical serialization mandates drive platform upgrades at Merck and Pfizer facilities. FDA 21 CFR Part 11 enforcement shapes data integrity requirements for electronic batch records. Aerospace manufacturers in Seattle and Dallas deploy hybrid architectures to satisfy ITAR compliance alongside cross-facility benchmarking.
China
MIIT-mandated GB standards for industrial data security block non-compliant foreign platforms from state-backed tenders. Smart factory certification requirements concentrate procurement decisions in Shenzhen and Suzhou electronics clusters. Domestic suppliers capture preference in Yangtze River Delta manufacturing investments.
Vietnam
Samsung and Foxconn contract manufacturers lack mature platform vendors, creating first-mover whitespace for cloud-native entrants. Electronics output expansion in Bac Ninh and Hai Phong industrial zones outpaces local digital infrastructure maturity. Foreign platform vendors face localization requirements for government-linked tenders.
India
Production-linked incentive schemes subsidize twenty-five percent of platform software costs for domestic electronics and automotive suppliers. Karnataka and Tamil Nadu manufacturing clusters attract contract manufacturers migrating from China. BIS standards for industrial automation create compliance entry barriers for uncertified foreign vendors.
Global Smart Manufacturing Platform Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in protocol translation and edge hardware. The vendor base stratifies between hyperscale cloud stacks, industrial automation incumbents, and emerging sovereign-edge specialists. Three archetypes dominate: cloud-native entrants targeting mid-market electronics manufacturers, legacy automation vendors retrofitting brownfield installations, and cybersecurity-focused compliance module providers. Consolidation pressure intensifies through strategic partnerships between cloud providers and industrial hardware manufacturers, while geographic expansion into Southeast Asian electronics corridors accelerates.
Within the industrial automation tier, Siemens AG and Rockwell Automation exemplify legacy vendors extending proprietary OT protocol dominance into platform layers. Microsoft Corporation occupies a distinct position bridging enterprise software stacks with Azure IoT integration. These three anchors represent divergent strategic postures: Siemens leverages digital twin portfolios for European factory modernization, Rockwell defends installed base relationships in North American automotive supply chains, and Microsoft competes through consumption-based runtime pricing models that align with pharmaceutical buyer preferences.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Siemens AG |
| ABB Group |
| SAP SE |
| Rockwell Automation |
| General Electric |
| Honeywell International |
| Schneider Electric |
| Others |
Supply & Pricing Matrix
Taiwanese foundry capacity dynamics in Hsinchu and Tainan Science Parks directly shape downstream pricing power for edge computing nodes, with semiconductor supply constraints allowing device manufacturers to command premium placement fees against platform vendors desperate for predictive maintenance hardware.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European deployments, mandating explainable AI modules that separate premium-certified architectures from standard cloud-native alternatives. Certification grade and geographic delivery cost drive price differentiation, with German automotive OEMs paying substantial premiums for sub-100ms latency guarantees. Cost compression in mid-market electronics tiers is intensifying because cloud-native entrants from Vietnam lack legacy compliance overhead. Pharmaceutical buyers at Merck and Pfizer demonstrate least price sensitivity due to FDA validation lock-in, while Vietnamese contract manufacturers show acute sensitivity to upfront licensing costs.
Supply Chain Analysis
Foxconn, Pegatron, and Wistron hold concentrated contract-manufacturing capacity for industrial edge devices across their Shenzhen, Zhengzhou, and Bac Ninh facilities. Component sourcing draws from Taiwan for semiconductors, Germany for precision sensors, and Japan for industrial networking hardware. Single-source vulnerability around Taiwanese foundry capacity presents acute supply chain risk, with any disruption cascading through predictive maintenance node availability. Distribution runs through direct OEM relationships for large automotive and pharmaceutical accounts, while regional system integrators serve mid-market electronics manufacturers in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German automotive OEMs and American pharmaceutical giants, with procurement committees at Volkswagen, BMW, and Pfizer consolidating vendor relationships around fewer platform providers capable of multi-jurisdictional compliance.
For Market Incumbents: Pre-empt cloud-native displacement by embedding sovereign-edge compliance modules directly into core offerings, addressing EU AI Act and China MIIT GB standards simultaneously. Fortify position through backward integration into protocol translation hardware, capturing margin currently leaked to gateway specialists serving brownfield retrofit demand. Certification investment in FDA 21 CFR Part 11 and AS9100 aerospace standards creates switching costs that emerging entrants cannot rapidly replicate. For New Entrants and Emerging Players: Pursue whitespace in Vietnam's Bac Ninh and Hai Phong electronics corridors, where Samsung and Foxconn contract manufacturers lack mature platform vendor relationships and procurement sophistication remains nascent. Target India's PLI-subsidized domestic suppliers in Karnataka and Tamil Nadu, where twenty-five percent software cost coverage accelerates payback periods for pilot deployments. Lead with consumption-based runtime pricing that mirrors pharmaceutical buyer preferences and minimizes upfront capital barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because jurisdictional fragmentation between EU AI Act, China MIIT standards, and FDA validation requirements favors vendors with pre-certified multi-market architectures over pure-play cloud entrants. Acquisition targets should demonstrate established compliance modules across at least two major regulatory regimes. Watch for inflection when German automotive OEMs begin mandating human-in-the-loop override specifications in procurement RFPs, signaling explainable AI transition from premium feature to table stakes.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Combines Azure IoT with Siemens digital twin portfolios for unified European factory modernization contracts. |
| Sovereign Edge Deployment | Satisfies EU AI Act data residency requirements while enabling sub-100ms quality inspection latency for BMW. |
| Regulatory Certification Investment | Pre-clears FDA 21 CFR Part 11 and AS9100 pathways, compressing pharmaceutical and aerospace sales cycles. |
| Geographic Expansion | Captures first-mover position in Vietnam's Bac Ninh corridor before local platform vendors mature. |
| Acquisition of Specialist Firm | Absorbs protocol translation expertise for 1990s-era CNC retrofits, accelerating brownfield deployment timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, IT/OT integration specialists, pharmaceutical validation officers, and automotive platform procurement leads. Secondary validation drew from SEC filings of industrial automation vendors, FDA 21 CFR Part 11 guidance documents, EU AI Act regulatory texts, and MIIT GB standard publications. Bottom-up deployment estimates across German automotive facilities, Vietnamese electronics zones, and American pharmaceutical clusters were triangulated against top-down market sizing from hyperscaler IoT revenue disclosures and industrial software vendor segment reporting.
Calibration against historical platform adoption curves in automotive and pharmaceutical verticals anchored growth assumptions across the analysis window. Segmentation dimensions modeled include deployment architecture, analytical engine technology, operational use case, and vertical compliance requirements, with additional granularity on jurisdictional certification status. CAGRs were derived from elasticity-adjusted penetration rates and replacement cycle analysis. Forecast inputs incorporated foundry capacity constraints from Taiwanese semiconductor supply chains and PLI scheme subsidy trajectories in Indian manufacturing clusters.
Sensitivities concentrate around foundry capacity expansion timelines, EU AI Act enforcement stringency evolution, and China MIIT standard reciprocity negotiations. Forecasts reflect documented assumptions regarding edge device availability and regulatory harmonization progress. Cross-checking against hyperscaler IoT revenue disclosures and industrial automation vendor order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
Refining Industry Automation and Software Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
Machine Automation Controllers Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
Industrial Automation Spares Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
North America Automated Rotary Indexing Table Market
Industrial Automation
Latin America Laboratory Automation Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Utility Automation Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Smart Manufacturing Devices Market