
 Linear Motion System Market | 2026-2036
Linear Motion System Market Size, Share, and Industry Trends Forecast 2026-2036
Linear Motion System Market Intelligence
The gap between precision-grade linear motion components and standard commodity units is realigning procurement patterns across industrial automation. THK Co., Ltd. leverages its captive manufacturing of ball screws and linear guides to sustain premium positioning in semiconductor equipment supply chains. Bosch Rexroth AG anchors European demand through integrated drive-and-motion platforms that combine electric linear actuators with control software. HIWIN Corporation competes aggressively on cost-adjusted precision, dominating volume supply to Asian machine tool builders.
Linear motion systems translate rotational energy into controlled straight-line displacement using recirculating ball or roller elements within hardened raceways, achieving positioning repeatability below five micrometers in premium configurations. These systems enable the precise axis control essential to CNC machinery, robotic arms, and automated conveying systems across discrete manufacturing. Ball screws command the largest value share among product types due to their load-bearing capacity and stiffness in machine tool applications. Electric technology leads the technology dimension as servo-driven linear actuators displace pneumatic and hydraulic alternatives in cleanroom and food-grade environments where oil-free operation matters.
The EU Machinery Directive and ISO 13849 safety standards shape product certification requirements for linear motion systems deployed in collaborative robotics and automated packaging lines. In the United States, OSHA machine guarding regulations and FDA food contact material standards constrain design choices for linear actuators in food and beverage processing environments. Stakeholders must monitor how regional carbon border adjustments and energy efficiency codes reshape the total cost of ownership calculus for electromechanical versus fluid-power linear drive technologies.
Market Dynamics
Electromechanical actuation is displacing fluid-power systems across precision manufacturing, forcing suppliers to reconfigure product portfolios around servo-motor integration and oil-free operation protocols demanded by semiconductor and food-grade end-users.
Growth Catalysts
- Semiconductor capital expenditure:Wafer fabrication facilities in Taiwan and South Korea are scaling automated handling systems that depend on sub-micron positioning repeatability. This equipment category specifies hardened linear guides and preloaded ball screws as non-negotiable components.
- EU Machinery Directive tightening:The 2023 amendments to safety requirements for electromechanical positioning equipment mandate redundant position monitoring and force-limited operation in collaborative robotics. Certification to ISO 13849 PLd is becoming a baseline procurement filter.
- Cleanroom operational mandates:FDA food contact material standards and USDA sanitary design requirements are eliminating hydraulic alternatives in dairy processing and ready-to-eat packaging lines. Electric linear actuators with IP69K sealing are capturing specification share.
Market Restraints
- Specialized alloy input volatility:Chrome steel and ceramic ball element costs fluctuate with energy-intensive smelting operations in China. THK and NSK maintain captive heat-treatment facilities to buffer margin compression.
- Precision-grade supply concentration:Ultra-high-accuracy ground ball screw production concentrates in Japan and Germany. Equipment builders outside these geographies face extended lead times for C5-grade and tighter tolerance classes.
- Technical stiffness limitations:Long-stroke linear motor stages exhibit reduced rigidity compared to ball screw equivalents. Machine tool builders above two-meter travel lengths must accept positioning trade-offs or absorb cost premiums for dual-drive compensation.
Strategic Opportunities
- Indian industrial automation buildout:The PLI scheme for manufacturing and textile machinery is stimulating demand for cost-adjusted precision linear components. Domestic system integrators are specifying Taiwanese and Korean guide suppliers to meet price-performance thresholds.
- Regenerative energy harvesting:The EU Green Deal and national carbon border adjustments are elevating total cost of ownership calculations for electromechanical versus pneumatic alternatives. Servo systems with regenerative drives capture operating cost advantages in high-cycle packaging applications.
- Linear motor-ceramic guide convergence:Direct-drive linear motors paired with silicon nitride roller elements eliminate mechanical transmission losses and lubrication requirements. Semiconductor inspection equipment manufacturers in the Netherlands and Germany are piloting this architecture for next-generation metrology platforms.
Industry Challenges
- Mechatronics engineering scarcity:System integrators struggle to source engineers capable of tuning servo-loop gains for high-dynamic linear stages. Training programs at vocational institutes in Germany and Switzerland are expanding to address this pipeline constraint.
- Multi-axis certification complexity:Functional safety validation for coordinated linear motion systems requires SIL-rated encoders, safety torque-off modules, and documented failure mode analysis. The documentation burden extends project timelines by four to eight months for collaborative robot deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linear Motion System Market |
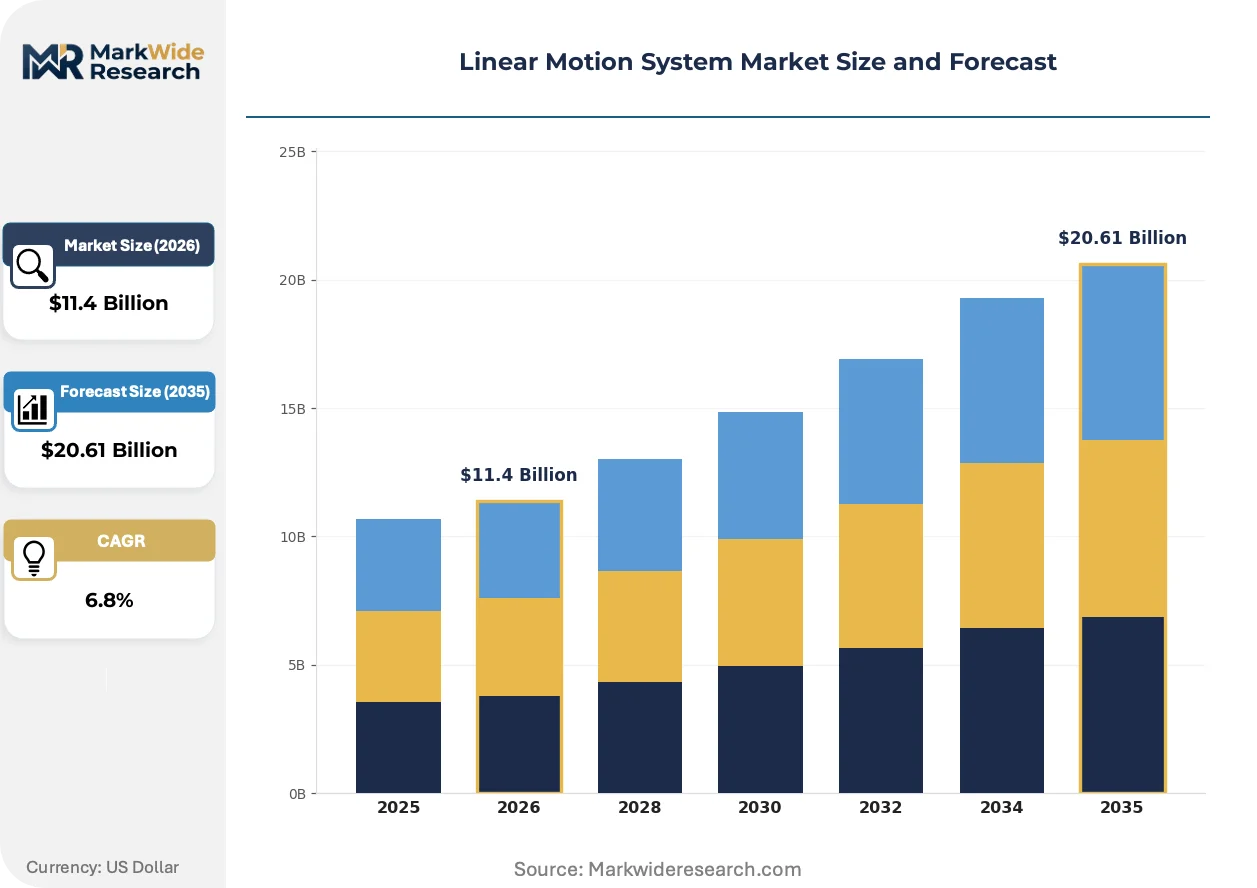
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Guides, Ball Screws, Belt Drives, Linear Actuators Technology: Electric, Hydraulic, Pneumatic, Mechanical End User: Aerospace, Automotive, Food & Beverage, Packaging Application: Robotics, CNC Machinery, Conveying Systems, 3D Printing |
| Companies Covered | THK Co., Ltd., NSK Ltd., HIWIN Corporation, Bosch Rexroth AG, SCHNEEBERGER Group, Ewellix AB, Rockwell Automation Inc., Schaeffler AG, Thomson Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linear Motion System Market Strategic Shifts & Innovations
Intelligent edge computing is embedding predictive maintenance algorithms directly into linear motion controllers, transforming component-level hardware into data-generating nodes that feed factory-wide digital twin architectures.
Integrated linear motor modules with embedded position sensing and thermal compensation are electrifying high-throughput pick-and-place operations in electronics assembly. SMT equipment manufacturers specify these systems for cycle rates exceeding two hundred placements per minute. The elimination of mechanical transmission elements compresses maintenance intervals and enables continuous duty profiles previously impractical with ball screw alternatives.
The EU F-Gas Regulation and REACH restrictions on perfluorinated lubricants are compelling lubricant reformulation across precision bearing supply chains. Equipment builders must validate alternative greases against accelerated life test protocols without established field correlation data. German machine tool OEMs are responding by qualifying ionic liquid lubricants for high-load linear guide applications, accepting extended break-in periods in exchange for regulatory compliance.
Specification authority is migrating from maintenance departments to corporate procurement functions with centralized vendor rationalization mandates. Multi-site manufacturers in the United States are consolidating linear motion suppliers to three preferred partners, trading application-specific optimization for volume pricing and unified service level agreements. This concentration is most visible in automotive stamping press retrofits, where standardization across fifteen-plus facilities overrides individual plant engineering preferences.
Linear Motion System Market Segmentation
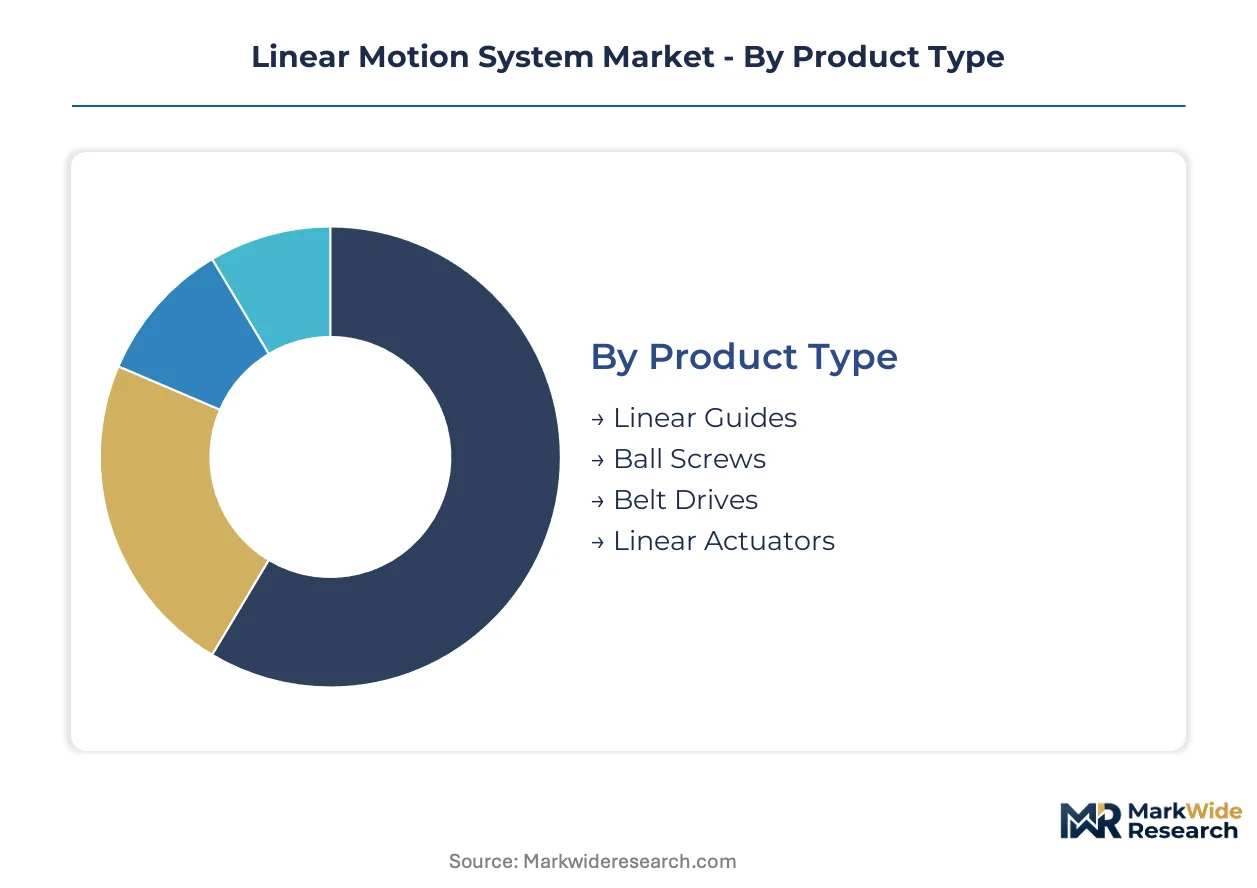
Linear motion system procurement hinges on load-bearing requirements, precision tolerances, and environmental constraints that vary sharply across manufacturing verticals. Equipment builders select component architectures based on duty cycle intensity, positioning repeatability demands, and total cost of ownership calculations over equipment lifespan.
Product Type:
Load capacity and stiffness requirements drive buyer selection between recirculating element technologies and transmission mechanisms.
- Ball Screws:Ground ball screws with preloaded nut assemblies convert rotary servo input into sub-five-micrometer positioning repeatability. Machine tool builders in Germany and Japan specify C5-grade and tighter tolerance classes for five-axis machining centers where thermal expansion compensation is critical.
- Linear Guides:Hardened raceway systems with recirculating ball or roller carriages support radial and moment loads across multi-axis gantries. Semiconductor wafer handling equipment in Taiwan and South Korea depends on sealed linear guide configurations with stainless steel construction for cleanroom compatibility.
- Linear Actuators:Integrated screw-driven or belt-driven units with housed motors simplify procurement for system integrators.
- Belt Drives:Reinforced polyurethane timing belts with steel cord tension members enable long-stroke positioning at velocities exceeding ball screw limits.
Volume sits with ball screws; growth tilts toward linear actuators.
Technology:
Energy efficiency mandates and contamination sensitivity are accelerating displacement of fluid-power alternatives across precision manufacturing environments.
- Electric:Servo motor-driven ball screws and linear motors deliver programmable positioning with regenerative energy recovery. FDA food contact material standards and USDA sanitary design requirements in US dairy processing are eliminating hydraulic alternatives in favor of IP69K-sealed electric actuators.
- Pneumatic:Compressed air cylinders remain cost-effective for simple pick-and-place operations with limited positioning precision.
- Hydraulic:Fluid-power actuators retain niche applications in metal forming and heavy pressing operations.
- Mechanical:Cam-driven and linkage-based systems persist in high-speed packaging machinery where fixed motion profiles suffice.
Electric technology commands specification share in new equipment; pneumatic systems defend installed base in legacy automation.
End User:
Industry-specific certification requirements and operational environments reshape component selection criteria across vertical markets.
- Automotive:Stamping press transfer systems and battery assembly lines demand high-cycle durability with force monitoring integration. OSHA machine guarding regulations constrain linear actuator selection for collaborative robot deployments in Michigan and Tennessee assembly plants.
- Food & Beverage:Washdown-compatible materials and lubricant compliance dominate procurement filters.
- Aerospace:Traceability documentation and material certification requirements extend procurement timelines.
- Packaging:Throughput velocity and changeover flexibility drive specification priorities.
Automotive absorbs the highest absolute unit volume; food and beverage is climbing the fastest on regulatory displacement of fluid-power systems.
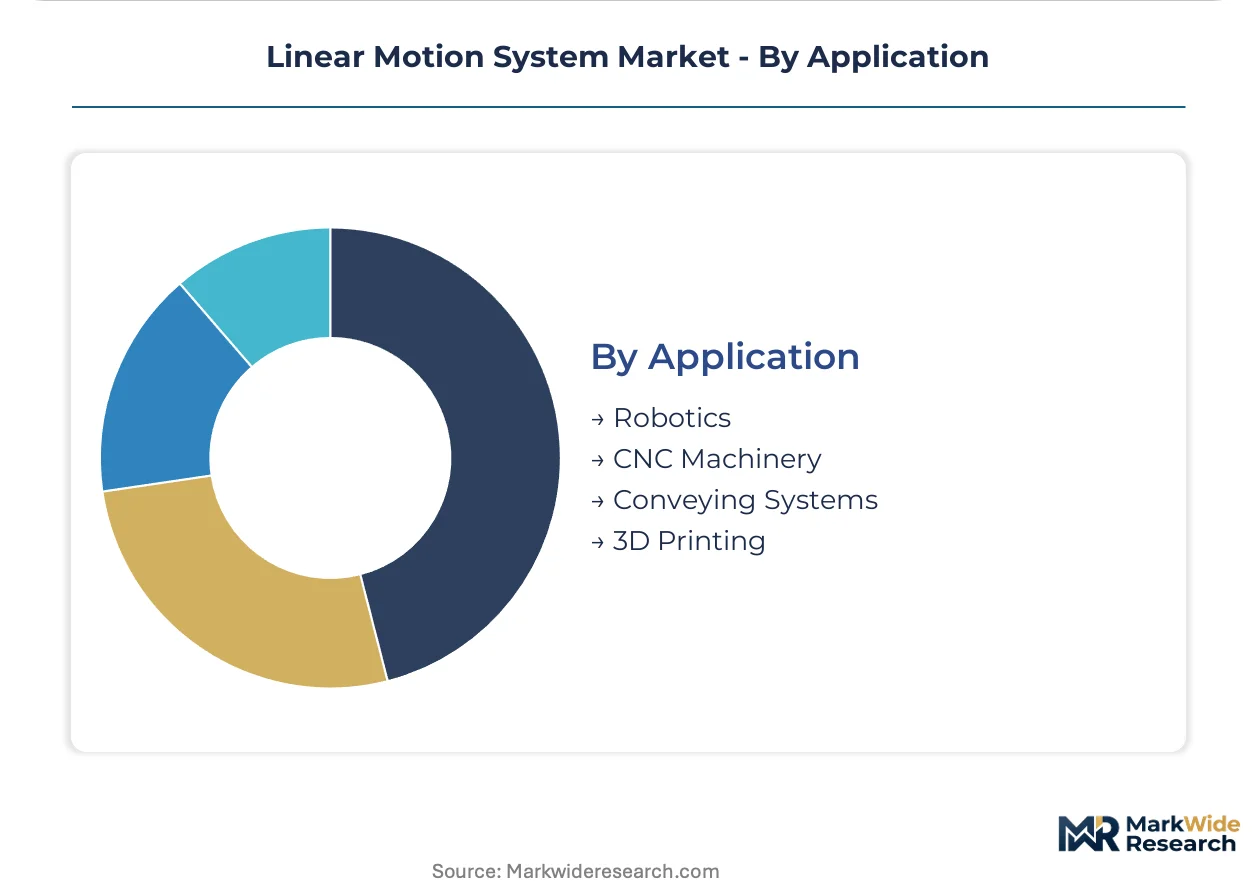
Application:
Axis count, travel length, and dynamic response requirements differentiate component architectures across equipment categories.
- CNC Machinery:Five-axis machining centers and precision grinding equipment specify ground ball screws with double-nut preload and thermal compensation. Germany's machine tool builders source THK and Bosch Rexroth components for next-generation platforms requiring sustained positioning accuracy under cutting loads.
- Robotics:Collaborative and industrial robot arms integrate compact linear modules for joint actuation and end-effector positioning.
- Conveying Systems:Pallet-based and continuous-flow material handling equipment employs belt drives and roller guides.
- 3D Printing:Fused deposition and powder bed fusion systems utilize lead screw or ball screw Z-axis mechanisms.
CNC machinery maintains the largest installed base; robotics is gaining share fastest on collaborative automation deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European linear motion system procurement through its concentration of machine tool builders and automotive automation engineering. Germany's industrial automation corridor generates sustained specification pull for precision-grade ball screws and linear guides across CNC platform development.
United States
Automotive battery assembly investments in Michigan and Tennessee drive demand for high-cycle linear actuators with force monitoring integration. OSHA machine guarding regulations constrain collaborative robot deployments, extending certification timelines by four to eight months. The Pacific Northwest semiconductor equipment cluster specifies cleanroom-compatible linear guides for wafer handling automation.
Germany
Five-axis machining center builders in Baden-Württemberg source ground ball screws with thermal compensation for sustained positioning accuracy under cutting loads. The EU Machinery Directive and ISO 13849 safety standards mandate redundant position monitoring for electromechanical positioning equipment. Bavaria's industrial automation corridor concentrates specification authority for THK and Bosch Rexroth components in next-generation CNC platforms.
Japan
Ultra-high-accuracy ground ball screw production concentrates in precision manufacturing clusters serving semiconductor capital equipment. METI industrial policy supports domestic supply chain resilience for critical motion control components. Nagoya's machine tool engineering base maintains captive heat-treatment facilities to buffer specialized alloy input volatility.
South Korea
Wafer fabrication facilities scale automated handling systems requiring sub-micron positioning repeatability from hardened linear guides and preloaded ball screws. The country's national industrial regulator enforces cleanroom operational mandates for semiconductor capital expenditure projects. Seoul Capital Area equipment builders face extended lead times for C5-grade tolerance classes sourced from Japanese and German suppliers.
India
The PLI scheme for manufacturing and textile machinery stimulates demand for cost-adjusted precision linear components. Domestic system integrators specify Taiwanese and Korean guide suppliers to meet price-performance thresholds. Maharashtra and Gujarat industrial corridors concentrate textile automation retrofits specifying belt-driven linear actuators for long-stroke positioning applications.
Linear Motion System Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the linear motion system supply base. The market structure concentrates premium-grade manufacturing among Japanese and German firms with captive heat-treatment and grinding capabilities, while volume supply fragments across Taiwanese and Korean competitors competing on cost-adjusted precision. Three strategic archetypes dominate: integrated drive-and-motion platform providers, captive component specialists, and modular actuator assemblers. Competitive moves center on M&A for safety certification capabilities and geographic expansion into Indian industrial automation buildout.
Among Japanese precision component specialists, THK Co., Ltd. and NSK Ltd. exemplify the captive manufacturing archetype with in-house ball screw and linear guide production. Bosch Rexroth AG represents the integrated platform approach combining electric linear actuators with control software for European machine tool builders. HIWIN Corporation occupies the cost-adjusted precision position, supplying volume linear motion components to Asian equipment manufacturers.
| Leading Market Players |
|---|
| THK Co., Ltd. |
| NSK Ltd. |
| HIWIN Corporation |
| Bosch Rexroth AG |
| SCHNEEBERGER Group |
| Ewellix AB |
| Rockwell Automation Inc. |
| Schaeffler AG |
| Thomson Industries Inc. |
| Others |
Cost & Logistics Intelligence
Electromechanical actuation's displacement of fluid-power systems across precision manufacturing simultaneously compresses cost structures and concentrates supply authority among captive heat-treatment specialists. This technological transition rewards Japanese and German producers with in-house grinding capabilities while squeezing margin buffers for volume assemblers dependent on outsourced ball screw and linear guide sourcing.
Pricing Analysis
Positioning repeatability guarantees anchor value-based pricing tiers across the linear motion system market. Three-tier pricing structure across premium, standard, and economy levels separates C5-grade ground ball screws with thermal compensation from rolled screw alternatives and belt-driven actuators. Pricing pressure stems from Taiwanese and Korean competitors aggressively qualifying cost-adjusted precision components for Indian PLI scheme machinery tenders. Automotive battery assembly integrators exhibit highest price sensitivity due to consolidated procurement mandates, while semiconductor capital equipment builders prioritize sub-micron accuracy over unit economics.
Supply Chain Analysis
Containerized freight volatility from East Asian precision manufacturing hubs to European machine tool corridors elevates landed cost uncertainty for C-grade tolerance components. Ultra-high-accuracy ground ball screw production concentrates in Japan and Germany, with volume linear guide assembly spreading across Taiwan and South Korea. Chrome steel and ceramic ball element sourcing draws from energy-intensive Chinese smelting operations exposed to carbon border adjustment mechanisms. Single-source vulnerability persists for C3-grade and tighter preloaded nut assemblies. Distribution runs through authorized distributor networks with technical specification support rather than commodity wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The linear motion system market functions as a vertical-integration race where control over heat-treatment and precision grinding operations determines margin capture. Players are pursuing backward integration into specialized alloy supply and captive ball element production to buffer input cost volatility.
For Market Incumbents: To counter Taiwanese and Korean cost-adjusted precision competitors, THK and NSK should expand captive ceramic ball manufacturing capacity while Bosch Rexroth consolidates safety certification capabilities through targeted acquisition of ISO 13849 validation specialists. Channel control represents a critical defensive lever as procurement authority migrates to corporate vendor rationalization functions.
For New Entrants and Emerging Players: Direct-to-OEM digital specification platforms offer the most penetrable route for modular actuator assemblers seeking to bypass incumbent distributor networks. India's PLI scheme for manufacturing machinery presents the most penetrable geography, with Maharashtra and Gujarat textile automation retrofits demanding belt-driven linear actuators at price-performance thresholds below Japanese premium positioning. A technical content marketing strategy targeting mechatronics engineering scarcity through online servo-loop tuning certification programs addresses the pipeline constraint directly.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing ISO 13849 PLd safety certification and established semiconductor equipment supply relationships given EU Machinery Directive tightening and collaborative robotics deployment acceleration. Long-term viability over the coming decade hinges on regenerative drive integration capabilities and cleanroom-compatible sealing expertise. The signal to watch as inflection indicator is Indian domestic system integrator specification shifts from Taiwanese guide suppliers toward vertically integrated European-Japanese partnerships.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Heat-Treatment Facility Expansion | Buffers margin compression from chrome steel alloy input volatility for Japanese precision specialists. |
| ISO 13849 Safety Certification Investment | Unlocks specification access for collaborative robotics deployments under EU Machinery Directive mandates. |
| Regenerative Drive Integration | Captures operating cost advantages in high-cycle packaging applications subject to EU Green Deal carbon accounting. |
| Ceramic Ball Element Manufacturing Scale-Up | Eliminates lubrication requirements for semiconductor metrology platforms facing REACH restrictions. |
| Digital Specification Platform Launch | Bypasses traditional distributor networks as corporate procurement centralizes vendor rationalization authority. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this linear motion system market analysis. Primary interviews with machine tool procurement directors, semiconductor capital equipment engineers, and industrial automation system integrators validated component-level demand assumptions. Technical interviews with THK, NSK, Bosch Rexroth, and HIWIN field application engineers informed precision-grade versus standard-grade substitution elasticity. Secondary sources included METI industrial policy documents, EU Machinery Directive amendment filings, FDA food contact material standards, and Indian PLI scheme machinery tender databases. Bottom-up bill-of-materials analysis across CNC machining center, robotic arm, and automated conveying equipment categories triangulated against top-down regional industrial automation expenditure estimates.
Product type granularity modeled ball screws, linear guides, linear actuators, and belt drives separately with precision tolerance class distinctions. Technology dimension segmentation captured electric, pneumatic, hydraulic, and mechanical actuation with servo-motor integration depth variations. End-use verticals included automotive, food and beverage, aerospace, and packaging with industry-specific certification requirements. Application segmentation distinguished CNC machinery, robotics, conveying systems, and additive manufacturing platforms by axis count and travel length parameters. CAGRs derived from equipment replacement cycle analysis, capital expenditure pipeline tracking, and regulatory displacement rate assumptions for fluid-power alternatives. Semiconductor fabrication facility buildout schedules and automotive battery assembly investment announcements provided forward demand calibration.
The model holds under stable alloy input pricing and sustained EU Machinery Directive enforcement; deviation in carbon border adjustment implementation timelines or Chinese smelting capacity restrictions would shift cost-competitive positioning between electromechanical and remaining fluid-power alternatives. Stakeholders should weight assumptions against their own operating context and regional regulatory compliance obligations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Asia Pacific Warehouse Automation Market
Industrial Automation
Smart Elevator Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Smart Manufacturing Devices Market
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Port Equipment Automation Market
Industrial Automation
Digital Rotator Market
Industrial Automation
Europe ICS Market
Industrial Automation
Smart Handwriting Machine Market
Industrial Automation
Pick and Place Machines Market
Industrial Automation
Global Healthcare Automation Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
North America Smart Factory Market
Industrial Automation
Material Handling Robotics Market
Industrial Automation
Assembly Automation Systems Market