
 India Industrial Automation Market | 2026-2036
India Industrial Automation Market Size, Share, and Industry Trends Forecast 2026-2036
India Industrial Automation Market Outlook
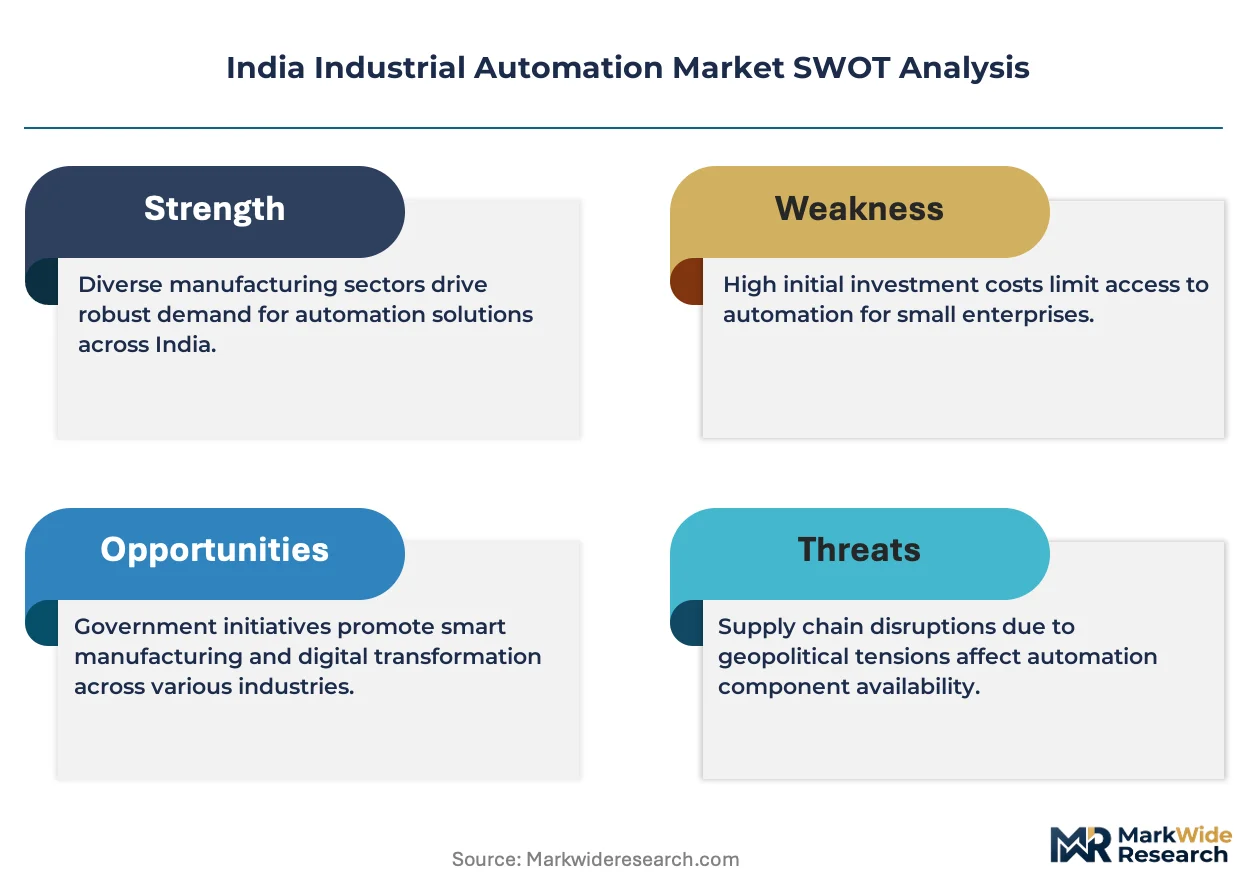
Asset-light leasing and pay-per-output financing is fragmenting competitive dynamics across India's industrial automation sector. Siemens Ltd leverages its captive finance arm to place programmable logic controllers on operational-expense contracts with mid-tier metalworking shops. Honeywell Automation India Limited anchors premium process control deployments through long-term service agreements with Reliance Industries' Jamnagar refinery complex. ABB India Ltd competes by extending robotics-as-a-service models to Gujarat's ceramic tile manufacturers, lowering capital barriers for first-time adopters.
Industrial automation encompasses the integration of control systems, instrumentation, and information technologies to operate industrial processes with minimal human intervention, typically employing IEC 61131-3 compliant programmable controllers and real-time Ethernet protocols achieving sub-millisecond response cycles. Its primary purpose is to enhance throughput consistency, reduce defect rates, and enable continuous operation in hazardous or precision-critical environments. PLC and DCS architectures dominate installed value across process industries, with DCS retaining margin concentration in petrochemical and power generation applications where redundancy requirements sustain premium pricing. Factory automation applications within the automotive end-user segment represent the fastest-expanding demand pool, driven by electric vehicle assembly line retrofits requiring synchronized robotic welding and vision-guided quality inspection.
BIS mandates IEC 61508 functional safety certification for safety instrumented systems deployed in oil and gas facilities, compelling vendors to redesign channel partner qualification programs. The PLI scheme for specialty steel and automotive components indirectly stimulates automation procurement by tying incentive eligibility to minimum capacity utilization thresholds that mechanized lines can reliably satisfy. CDSCO's evolving good manufacturing practice requirements for pharmaceutical batch records are pushing Mumbai-Pune corridor formulators toward validated distributed control architectures with electronic signature capabilities. Stakeholders must monitor how RBI's projected digital lending guidelines for equipment finance reshape availability of automation capital for tier-two manufacturing clusters.
Market Dynamics
Asset-light financing models are fragmenting competitive dynamics across India's industrial automation sector, compelling vendors to restructure revenue recognition around operational-expense contracts rather than capital-equipment sales.
Growth Catalysts
- PLI scheme thresholds:The production-linked incentive scheme for specialty steel and automotive components ties incentive eligibility to minimum capacity utilization, compelling manufacturers to deploy mechanized lines that reliably satisfy volume benchmarks.
- BIS functional safety mandates:Bureau of Indian Standards certification requirements for IEC 61508-compliant safety instrumented systems in oil and gas facilities are accelerating compliance investments among domestic system integrators.
- Electric vehicle assembly retrofits:Automotive manufacturers in Tamil Nadu and Gujarat are scaling robotic welding and vision-guided quality inspection systems to support synchronized EV production lines.
Market Restraints
- Imported component dependency:Servo motors and precision encoders concentrate in German and Japanese supplier networks, exposing domestic integrators to currency volatility and extended lead times.
- Skill scarcity in safety engineering:TÜV-certified functional safety engineers remain concentrated in Mumbai-Pune and Bengaluru corridors, constraining deployment velocity for process industry projects.
- Legacy DCS lock-in:Petrochemical facilities operating Honeywell TDC3000 and Yokogawa CENTUM systems face prohibitively expensive migration paths to open-architecture alternatives.
Strategic Opportunities
- Robotics-as-a-service penetration:Pay-per-output financing models are lowering capital barriers for first-time adopters among Gujarat's ceramic tile manufacturers.
- Pharmaceutical electronic batch records:CDSCO's evolving good manufacturing practice requirements are pushing Mumbai-Pune corridor formulators toward validated distributed control architectures with electronic signature capabilities.
- Tier-two cluster financing:RBI's projected digital lending guidelines for equipment finance could reshape automation capital availability in Aurangabad and Coimbatore manufacturing belts.
Industry Challenges
- Multi-protocol integration complexity:Facilities deploying PROFINET, EtherCAT, and EtherNet/IP simultaneously require specialized systems integrators capable of deterministic clock synchronization across heterogeneous networks.
- BIS certification timelines:Industrial control equipment testing at BIS-recognized laboratories routinely extends beyond six months, delaying project commissioning for time-sensitive automotive capacity expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Industrial Automation Market |
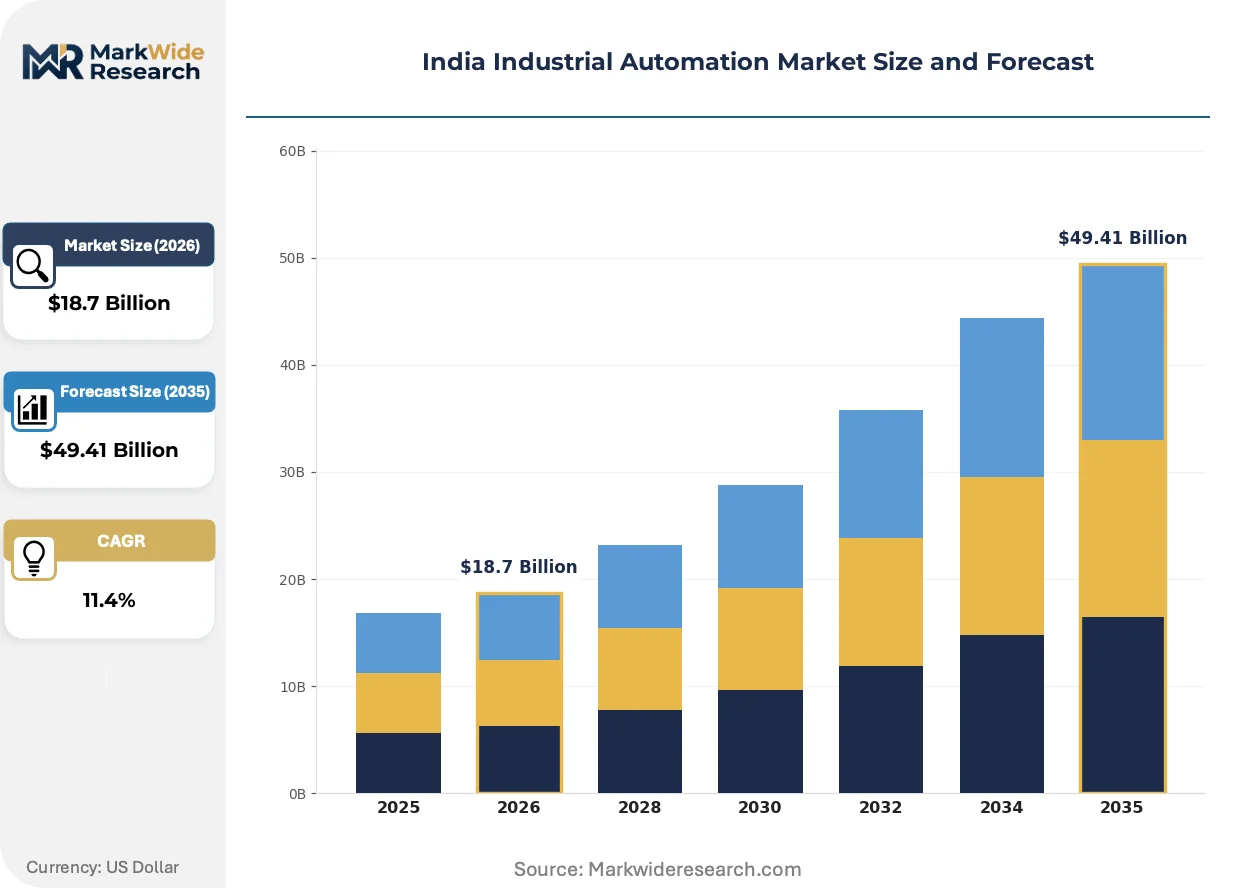
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SCADA, PLC, HMI, DCS End User: Manufacturing, Oil & Gas, Pharmaceuticals, Food & Beverage Technology: IoT, AI, Robotics, Machine Learning Application: Process Automation, Factory Automation, Building Automation, Energy Management |
| Companies Covered | Rockwell Automation India Pvt Ltd, Honeywell Automation India Limited, ABB India Ltd, KPIT Technologies, Tata Elxsi, Siemens Ltd, Mitsubishi Electric India Pvt Ltd, Endress+Hauser India Pvt. Ltd., Schneider Electric India Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Industrial Automation Market Strategic Shifts
Digital twin architectures are compressing commissioning cycles and enabling predictive maintenance contracts that restructure vendor-customer relationships around uptime guarantees rather than hardware shipments.
Digital twin software is virtualizing physical production lines before physical deployment, allowing automotive manufacturers in Tamil Nadu to simulate robotic cell interactions and optimize cycle times without halting existing operations. Mahindra and Mahindra's Chakan facility has reduced commissioning timelines by running virtual commissioning protocols on Siemens Tecnomatix platforms. This virtualization is compressing the traditional gap between engineering design and production ramp-up.
BIS mandates IEC 61508 functional safety certification for safety instrumented systems deployed in oil and gas facilities, compelling vendors to redesign channel partner qualification programs around TÜV Rheinland and exida credentials. Reliance Industries' Jamnagar refinery complex has accelerated vendor audits to ensure SIL-rated architectures meet third-party validation requirements. Process control suppliers are responding by embedding certified safety modules into standard DCS offerings.
Mid-tier metalworking shops in Maharashtra are unbundling after-sales service from hardware procurement, demanding outcome-based contracts that tie vendor payments to spindle uptime metrics rather than preventive maintenance schedules. Siemens Financial Services has structured operational-expense agreements with Pune-based precision engineering vendors that shift balance sheet classification from capex to opex. This behavioral shift is most visible in the automotive component supply chain, where tier-two suppliers face working capital constraints.
India Industrial Automation Market Segmentation
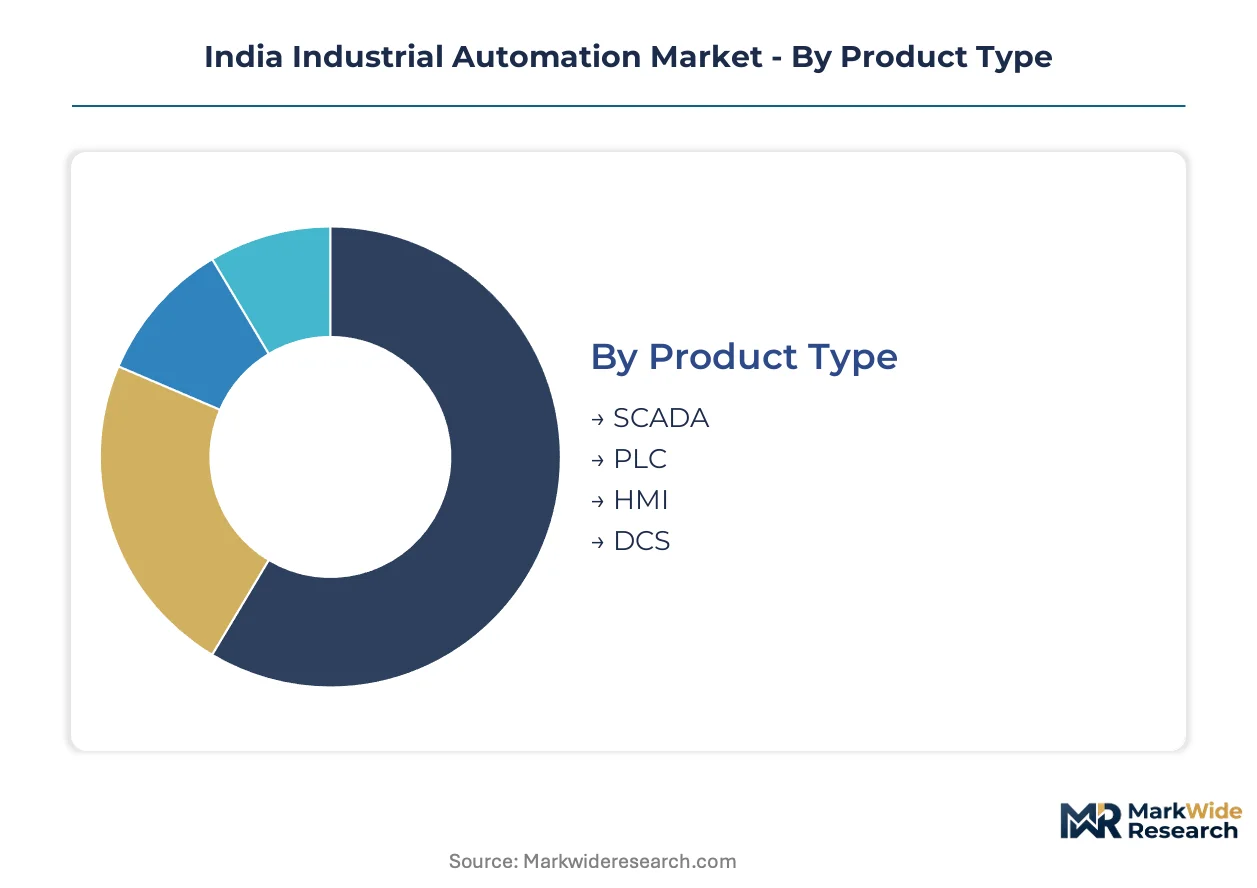
Segmentation in India's industrial automation sector reveals distinct service intensity profiles across product architectures. After-sales engineering support and long-term maintenance contracts vary dramatically by control system complexity, reshaping vendor profitability and customer lifetime value calculations.
Product Type:
After-sales-service intensity escalates with system redundancy requirements and safety certification burdens, creating divergent margin profiles across hardware categories.
- SCADA:Supervisory control and data acquisition systems aggregate distributed sensor networks into centralized visualization layers for grid-scale utilities and pipeline operators. Maharashtra's power distribution utilities concentrate procurement here, driven by CEA mandates for remote monitoring of substation assets.
- PLC:Programmable logic controllers execute deterministic control sequences in discrete manufacturing cells, typically IEC 61131-3 compliant with ladder logic programming environments. Gujarat's automotive component suppliers anchor demand, compelled by PLI scheme utilization thresholds that mechanized lines reliably satisfy.
- HMI:Human-machine interfaces bridge operator cognition with machine states through industrial-grade touch panels and visualization software.
- DCS:Distributed control systems orchestrate continuous process loops across petrochemical and refinery complexes with redundant controller architectures.
PLC holds the largest share; momentum sits with SCADA as grid modernization accelerates.
End User:
Cost tier stratification separates premium process control deployments from standardized factory automation, with certification requirements and safety integrity levels driving pricing spreads.
- Manufacturing:Discrete production environments employ robotic cells and conveyor synchronization systems for automotive and consumer durable assembly. Tamil Nadu's EV manufacturing corridor concentrates investment, scaling robotic welding lines under the PLI scheme for advanced automotive components.
- Oil & Gas:Hydrocarbon processing facilities demand SIL-rated safety instrumented systems and explosion-proof instrumentation for hazardous area classification. Reliance Industries' Jamnagar complex anchors premium DCS deployments, compelled by BIS IEC 61508 mandates for functional safety certification.
- Pharmaceuticals:Batch processing operations require validated distributed architectures with electronic signature capabilities and audit trail integrity.
- Food & Beverage:Hygienic design standards and clean-in-place automation dominate capital allocation in this price-sensitive segment.
Oil & Gas commands premium pricing; Pharmaceuticals is climbing the fastest on CDSCO compliance investments.
Technology:
Application maturity separates proven industrial protocols from emerging analytics layers, with integration complexity dictating deployment timelines and systems integrator qualification requirements.
- IoT:Industrial internet-of-things platforms retrofit legacy assets with edge connectivity and cloud telemetry for predictive maintenance contracts. Pune-Aurangabad metalworking clusters concentrate adoption, drawn by asset-light financing models that shift automation expenditure from capex to opex.
- AI:Machine vision and anomaly detection algorithms optimize quality inspection throughput in high-volume discrete manufacturing. Gujarat's ceramic tile manufacturers deploy vision-guided systems for defect classification, lowering capital barriers through robotics-as-a-service arrangements.
- Robotics:Articulated and collaborative robot arms execute material handling, welding, and assembly operations with sub-millimeter repeatability.
- Machine Learning:Predictive models trained on operational data forecast equipment degradation and optimize process parameters.
Robotics holds the largest installed base; AI is gaining share fastest on vision system retrofits.
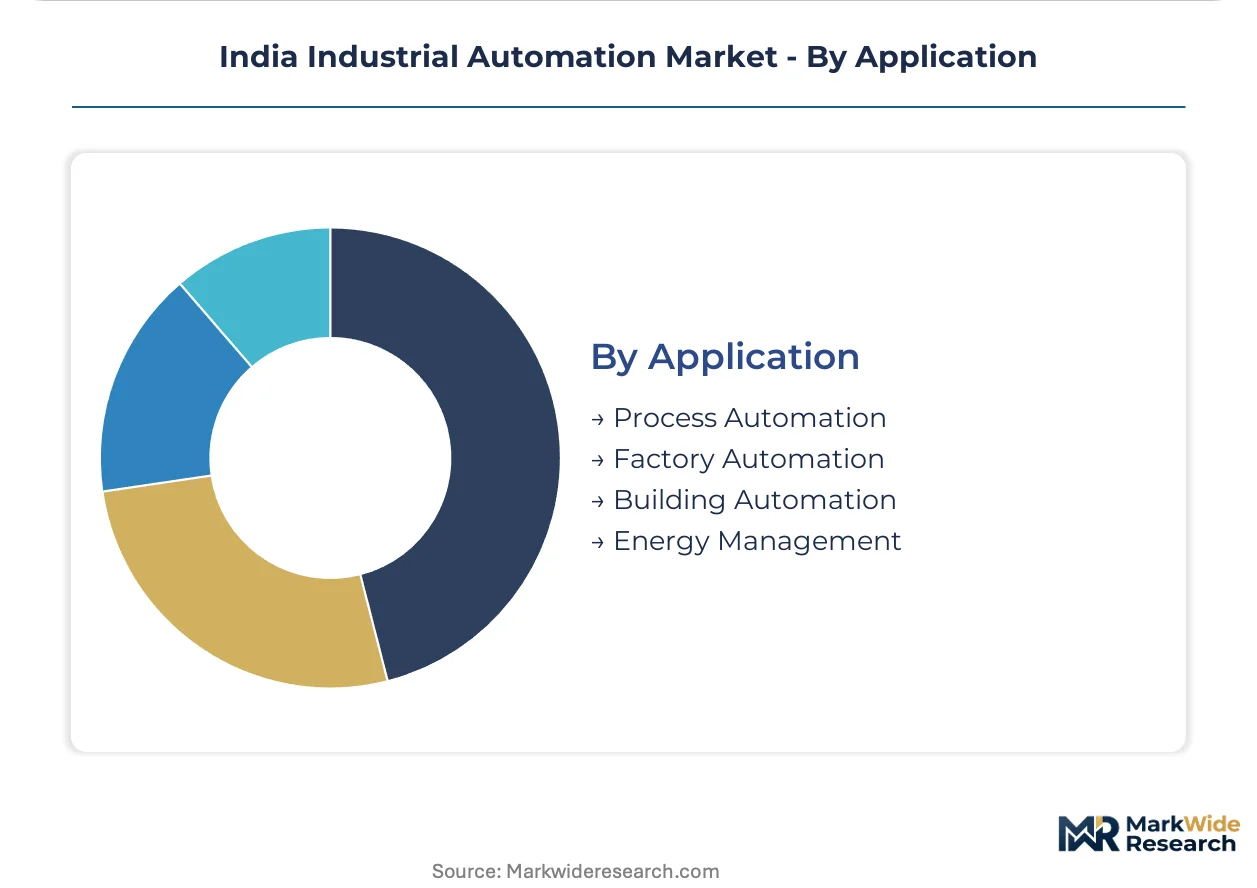
Application:
Customer type differentiation separates process industry incumbents with legacy lock-in from greenfield factory automation adopters seeking modular, open-architecture solutions.
- Process Automation:Continuous manufacturing control for chemicals, petrochemicals, and power generation emphasizes high-availability architectures and redundant safety systems. Mumbai-Pune corridor refineries anchor demand, constrained by TÜV-certified functional safety engineer scarcity that extends project commissioning timelines.
- Factory Automation:Discrete manufacturing synchronization employs robotic cells, AGV fleets, and machine-to-machine communication protocols. Coimbatore's precision engineering vendors concentrate procurement, pressured by tier-one automotive supplier quality audits that mechanized lines satisfy.
- Building Automation:HVAC, lighting, and access control integration for commercial and industrial facilities.
- Energy Management:Load balancing, demand response, and renewable integration for industrial microgrids.
Process Automation commands the highest service attach rates; Factory Automation shows steepest expansion trajectory on EV line retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's industrial automation trade remains import-dependent for precision motion control components, though domestic system integration capabilities are expanding in western and southern manufacturing belts. The export-import imbalance concentrates procurement leverage with German and Japanese component suppliers, while PLI-linked capacity expansions drive localized assembly investments.
Maharashtra
Pune-Aurangabad metalworking clusters anchor factory automation demand, pressured by tier-one automotive supplier quality audits. CEA mandates for remote substation monitoring accelerate SCADA procurement by state power distribution utilities. Mumbai-Pune pharmaceutical formulators invest in validated distributed control architectures to satisfy CDSCO electronic batch record requirements.
Gujarat
Specialty steel and automotive component manufacturers scale robotic welding lines to meet PLI scheme utilization thresholds. Ceramic tile manufacturers adopt robotics-as-a-service models that shift capital expenditure to operational contracts. BIS certification timelines for industrial control equipment routinely extend commissioning schedules for time-sensitive capacity expansions.
Tamil Nadu
Electric vehicle assembly retrofits concentrate investment in synchronized robotic welding and vision-guided quality inspection systems. Automotive OEMs leverage Siemens Tecnomatix platforms for virtual commissioning that compresses production ramp-up timelines. Hosur-Sriperumbudur corridor suppliers face working capital constraints that favor asset-light financing structures.
Karnataka
Bengaluru's precision engineering vendors concentrate TÜV-certified functional safety engineering talent, constraining deployment velocity for pan-Indian process industry projects. Machine vision and AI-driven anomaly detection adoption accelerates among aerospace component manufacturers. RBI's projected digital lending guidelines for equipment finance could reshape automation capital availability for mid-tier fabricators.
Telangana
Hyderabad's pharmaceutical and life sciences manufacturing base drives demand for electronic signature-capable batch processing systems. Process control suppliers embed certified safety modules into standard DCS offerings to satisfy evolving CDSCO good manufacturing practice requirements. Medchal-Jeedimetla industrial estates concentrate domestic system integrator capabilities for pharmaceutical validation protocols.
India Industrial Automation Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in precision motion and sensing technologies. Market structure fragments across captive finance arms of multinational industrials, domestic system integration houses, and emerging robotics-as-a-service operators. Three archetypes dominate: full-stack automation platforms with captive financing, safety-certified process control specialists, and asset-light robotics service providers. Competitive moves center on operational-expense contract restructuring and channel partner qualification programs around TÜV Rheinland credentials.
Within the multinational platform tier, Siemens Ltd and ABB India Ltd occupy positions that exemplify integrated hardware-financing combinations. Honeywell Automation India Limited anchors premium process control deployments through long-term service agreements. Among domestic specialists, KPIT Technologies and Tata Elxsi represent engineering service archetypes that bridge software integration gaps for automotive and industrial clients. Rockwell Automation India Pvt Ltd, Mitsubishi Electric India Pvt Ltd, and Schneider Electric India Pvt Ltd sit within the factory automation component supply tier, competing on protocol compatibility and deterministic control performance.
| Leading Market Players |
|---|
| Rockwell Automation India Pvt Ltd |
| Honeywell Automation India Limited |
| ABB India Ltd |
| KPIT Technologies |
| Tata Elxsi |
| Siemens Ltd |
| Mitsubishi Electric India Pvt Ltd |
| Endress+Hauser India Pvt. Ltd. |
| Schneider Electric India Pvt Ltd |
| Others |
Value Chain & Pricing Dynamics
Jawaharlal Nehru Port Trust freight corridors expose domestic system integrators to currency-adjusted component costs that compress margins on standardized PLC deployments while sustaining premium pricing for SIL-certified DCS architectures serving Reliance Industries' Jamnagar complex.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates TÜV-certified safety systems from uncertified alternatives and bundles after-sales engineering attach rates. Cost compression in mid-tier metalworking clusters is intensifying because asset-light financing models shift procurement evaluation toward total cost of ownership. Tier-two automotive suppliers exhibit highest price sensitivity; oil and gas operators show lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Precision servo motors and optical encoders draw from concentrated manufacturing bases in Germany, Japan, and South Korea. Raw material dependencies span rare-earth magnets, high-purity silicon for sensors, and specialty steel for robotic arm castings. Single-source vulnerability in field-programmable gate arrays creates exposure to export control restrictions. Distribution runs through authorized channel partners with BIS-recognized laboratory certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from predictive maintenance contracts and TÜV recertification programs is expanding faster than hardware shipments, reframing vendor profitability around customer lifetime value rather than upfront equipment margins.
For Market Incumbents: Build captive financing moats by extending operational-expense contracts to tier-two precision engineering vendors in Aurangabad and Coimbatore. Deepen channel control through exclusive BIS certification fast-track arrangements for partner system integrators. Counter robotics-as-a-service entrants by embedding uptime guarantees into standard DCS maintenance agreements.
For New Entrants and Emerging Players: Tier-two pharmaceutical formulators in Hyderabad's Medchal-Jeedimetla estates present underpenetrated demand for validated batch processing systems with electronic signature capabilities. Deploy pay-per-output financing models that shift balance sheet classification from capex to opex, mirroring ABB's Gujarat ceramic tile approach. Target CDSCO compliance consulting as a differentiated entry wedge.
For Investors and Strategic Acquirers: Domestic system integrators with TÜV Rheinland-certified safety engineering benches represent the most defensible acquisition archetype. Long-term viability rests on recurring revenue attach rates exceeding forty percent of total contract value. Monitor RBI digital lending guideline finalization as an inflection signal for equipment finance availability in tier-two manufacturing belts.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Finance Arm Expansion | Siemens Ltd structures opex contracts with Pune metalworking shops, displacing traditional capex procurement. |
| TÜV Certification Investment | BIS IEC 61508 mandates force channel partner redesign around exida and Rheinland credentials. |
| Robotics-as-a-Service Launch | ABB India lowers capital barriers for Gujarat ceramic manufacturers through pay-per-output arrangements. |
| Virtual Commissioning Platform | Siemens Tecnomatix deployments at Mahindra Chakan compress EV line ramp-up timelines. |
| Pharmaceutical Validation Protocol | CDSCO electronic batch record requirements drive DCS upgrades with electronic signature capabilities. |
Study Parameters
Desk research of BIS certification registries, CEA grid modernization directives, and PLI scheme utilization filings preceded structured interviews with plant engineers at Reliance Jamnagar, procurement leads at Tamil Nadu automotive OEMs, and aftermarket service heads at Siemens and ABB India. Secondary validation drew from RBI equipment finance circulars, CDSCO good manufacturing practice amendments, and customs import data for servo motors and precision encoders. Bottom-up demand aggregation across Maharashtra, Gujarat, Tamil Nadu, Karnataka, and Telangana manufacturing clusters was cross-checked against top-down vendor shipment estimates.
Assumptions held fixed include BIS IEC 61508 enforcement timelines, PLI scheme continuation through the analysis window, and current RBI digital lending draft provisions. Variables modeled encompass PLI threshold adjustments, currency volatility in yen-euro-rupee crosses, and TÜV-certified engineer supply expansion. Segmentation dimensions covered product architecture, end-user industry, technology layer, and application type. CAGRs were derived from logistic adoption curves fitted to disclosed capacity expansion timelines and vendor contract values.
Practitioners should monitor PLI scheme renewal negotiations, BIS laboratory accreditation backlogs, and RBI equipment finance final guidelines for early signals of forecast revision. Cross-checking against disclosed vendor order books and CEA substation automation procurement dashboards is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Europe SCADA Market
Industrial Automation
Asia Pacific Retail Automation Market
Industrial Automation
Refining Industry Automation and Software Market
Industrial Automation
Middle East and Africa Automated Storage and Retrieval System Market
Industrial Automation
Global Motion Controller Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Model Based Manufacturing Technologies Market
Industrial Automation
Global Mining Automation Consumption Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Grippers Market
Industrial Automation
Industrial Automation Device Manager Software Market