
 Automotive Vacuum Brake Booster Market | 2026-2036
Automotive Vacuum Brake Booster Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Vacuum Brake Booster Market Outlook
Premium-grade vacuum brake booster specifications is unwinding legacy cost structures across the supply base. Robert Bosch GmbH leverages in-house vacuum pump integration to sustain margin control in European passenger vehicle programs. Denso Corporation anchors Asian OEM supply through dedicated engine-mounted booster architectures. ZF Friedrichshafen AG competes on chassis-integrated module designs that reduce assembly complexity for vehicle assemblers.
An automotive vacuum brake booster is a vacuum-actuated force-multiplying device mounted between the brake pedal and master cylinder, typically utilizing a single or dual elastomer diaphragm within a sealed housing to amplify driver input through differential pressure from the engine intake manifold or dedicated vacuum pump. Its primary industrial purpose is to reduce pedal effort while maintaining hydraulic brake system responsiveness across passenger and commercial vehicle platforms. Double diaphragm configurations lead volume in heavy-duty applications where larger master cylinder displacements require greater assist ratios, while electronic vacuum-assisted variants represent the fastest-growing technology segment as mild-hybrid architectures proliferate. OEM direct supply channels concentrate margin pools through long-term platform contracts, whereas aftermarket providers face pricing pressure from remanufactured single diaphragm units.
NHTSA Federal Motor Vehicle Safety Standards govern minimum stopping distances and booster failure modes in the United States, while ECE R13-H regulations in Europe mandate specific performance envelopes for vacuum-assisted braking across vehicle weight classes. China's MIIT enforces GB standards for brake system durability that directly influence local booster material specifications and diaphragm compound selection. Stakeholders must monitor divergence between vacuum-dependent internal combustion platforms and electric vehicle brake-by-wire architectures that eliminate conventional vacuum sources entirely.
Market Dynamics
The transition from internal combustion engines to electrified powertrains is systematically eliminating the intake manifold vacuum source that conventional brake boosters require, forcing a fundamental re-architecture of braking assist systems across vehicle platforms.
Growth Catalysts
- Commercial fleet renewal:Brazilian logistics operators are expanding vacuum-assisted braking purchases for medium-duty trucks under updated federal transport safety mandates.
- Dual diaphragm specifications:Heavy-duty master cylinder displacement requirements in North American commercial vehicles drive adoption of larger assist-ratio configurations.
- MIIT durability standards:China's GB brake system regulations enforce specific diaphragm compound selections that elevate local manufacturing quality thresholds.
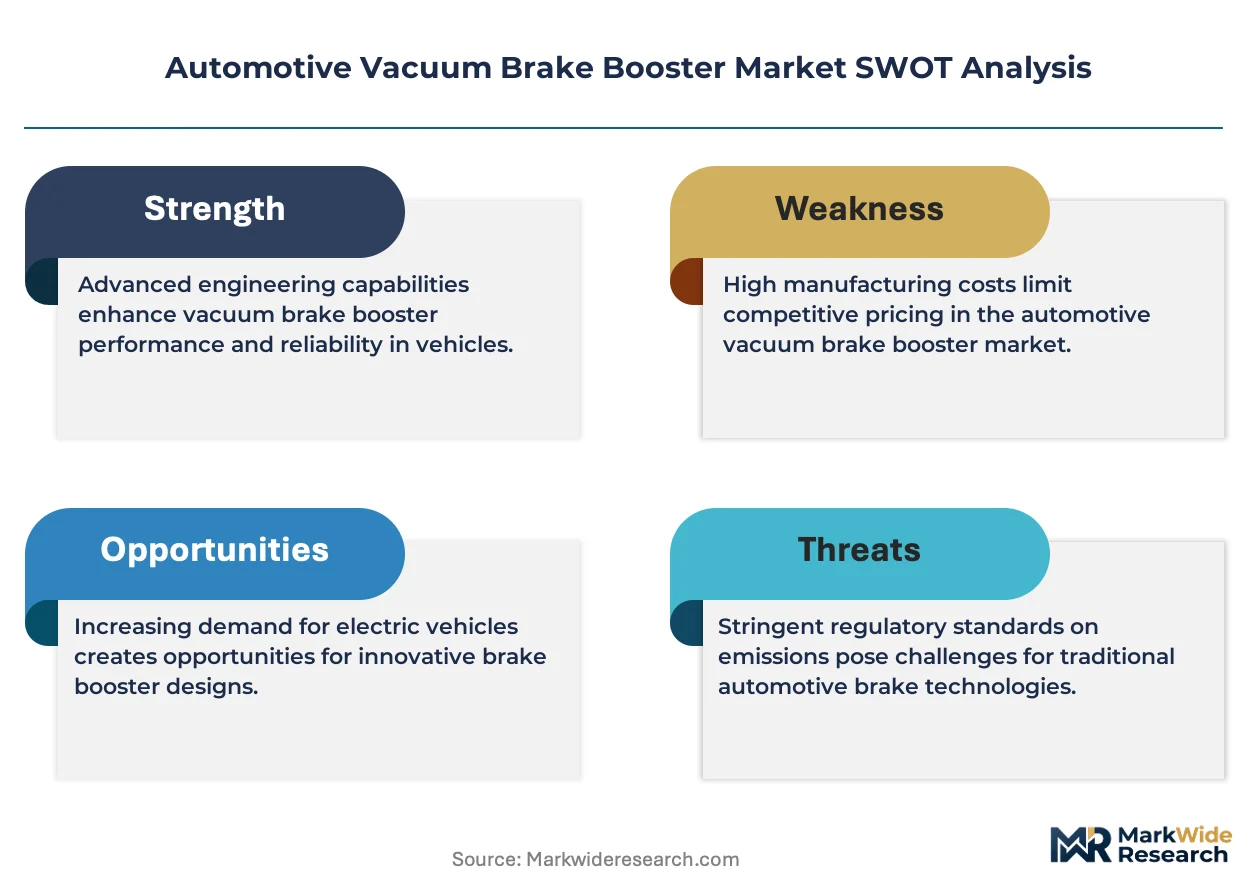
Market Restraints
- Raw material volatility:EPDM rubber and reinforced steel shell costs fluctuate with petrochemical feedstock pricing, compressing tier-two supplier margins.
- Supplier concentration:European vacuum pump integration capabilities cluster within a narrow band of Tier 1 chassis specialists, limiting second-source options.
- Technical obsolescence pathway:Brake-by-wire architectures in battery electric vehicles eliminate vacuum dependency entirely, capping long-term addressable market for conventional boosters.
Strategic Opportunities
- Mild-hybrid vacuum demand:48V architectures in Germany and Japan retain engine-coupled vacuum pumps while adding electric assist, creating hybrid-specific booster specifications.
- Remanufactured aftermarket channels:North American independent service networks are developing certified rebuild programs for single diaphragm units at price points below OEM replacement.
- CSRD supply chain disclosure:European sustainability reporting requirements favor suppliers with documented circular material flows in diaphragm production.
Industry Challenges
- Cross-platform engineering talent:Vacuum system expertise concentrated in legacy internal combustion programs must retrain for electromechanical brake assist integration.
- Homologation timeline compression:ECE R13-H amendment cycles are accelerating, requiring faster validation of new booster designs across multiple vehicle weight classes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Vacuum Brake Booster Market |
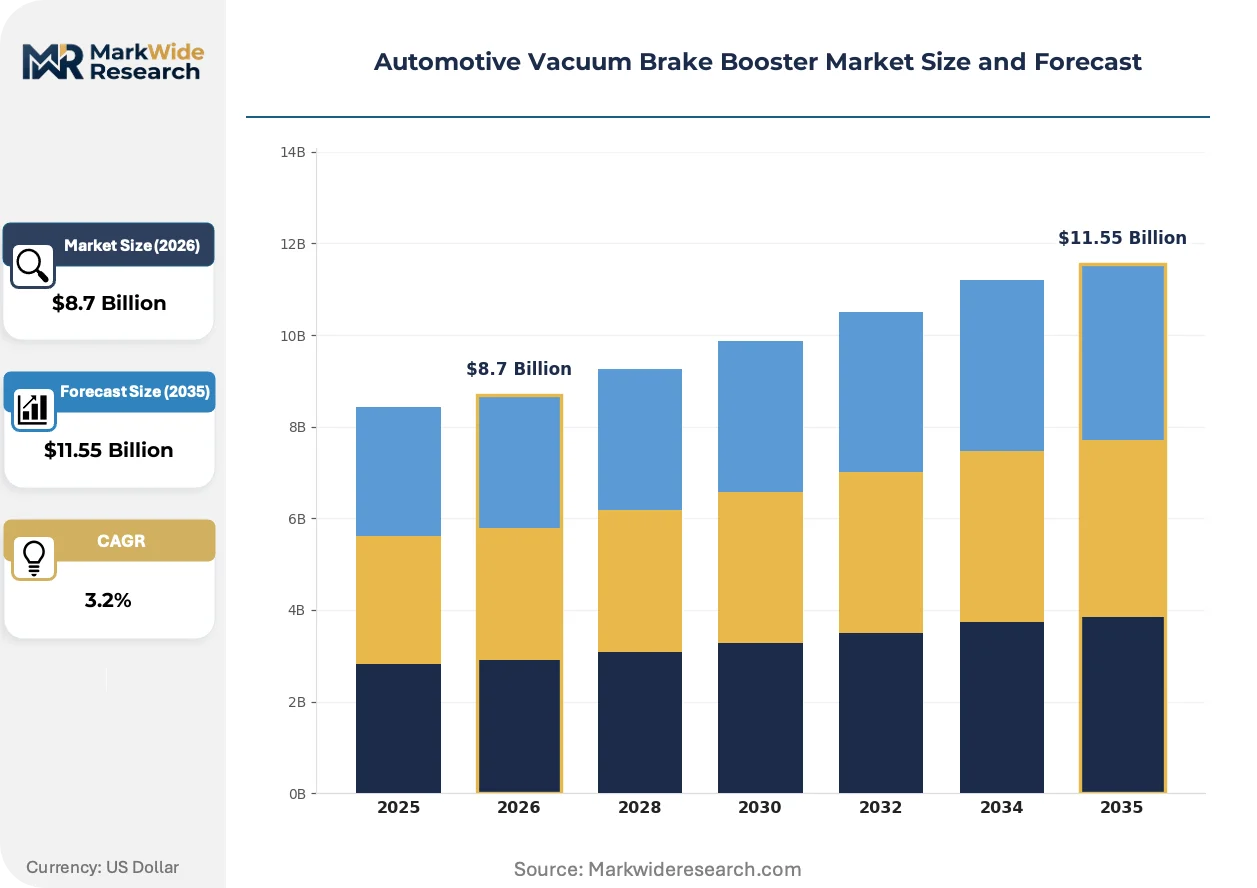
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.55 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Diaphragm, Double Diaphragm, Remote Booster, Integral Booster End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Hydraulic, Pneumatic, Electronic, Vacuum Assisted Installation: Frame Mounted, Chassis Mounted, Engine Mounted, Others |
| Companies Covered | HELLA, Denso Corporation, Robert Bosch GmbH, ZF Friedrichshafen AG, Hyundai Mobis, Aisin Seiki, Delphi Technologies, Brembo, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Vacuum Brake Booster Market Strategic Shifts
Electrification is fragmenting the traditional vacuum brake booster value chain into parallel technology tracks serving divergent powertrain architectures. Three developments are restructuring competitive positioning.
Electronic vacuum-assisted variants are decomposing the conventional single-source vacuum supply model. These systems integrate dedicated electric pumps with diaphragm housings, enabling consistent assist pressure regardless of engine load state. European mild-hybrid programs are adopting this architecture fastest, compressing the addressable market for manifold-dependent designs while opening new component sourcing patterns for pump motor suppliers.
REACH substance restrictions are tightening allowable compounds in elastomer diaphragm formulations. The industrial consequence is accelerated material qualification cycles for EPDM alternatives with reduced plasticizer content. Asian OEM supply chains are responding fastest, shifting compound specifications ahead of European implementation timelines to maintain export eligibility.
Fleet procurement departments are consolidating brake system sourcing under platform-level contracts rather than component-level negotiations. This behavior concentrates purchasing power with vehicle assemblers and displaces independent booster distributors from original equipment channels. The shift is most visible in Chinese passenger vehicle manufacturing corridors, where Shanghai-based OEMs are enforcing direct Tier 1 relationships for integrated brake modules.
Automotive Vacuum Brake Booster Market Segmentation
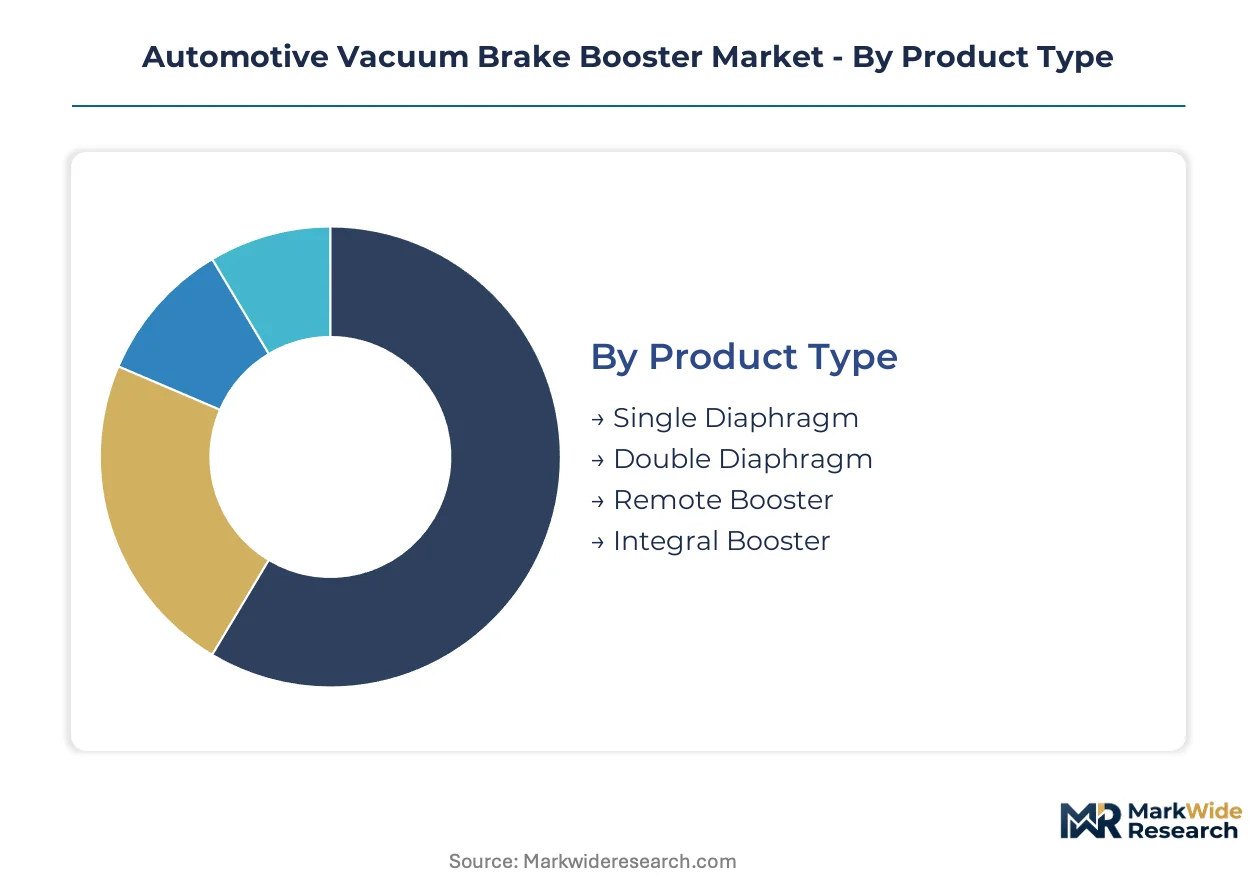
Vacuum brake booster procurement channels diverge sharply between long-term OEM platform contracts and fragmented aftermarket rebuild networks. Understanding segment-specific margin structures and technical specifications enables suppliers to align production capacity with the most defensible revenue pools.
Product Type:
Single diaphragm units flow primarily through aftermarket remanufacturing channels, while double diaphragm and electronic variants concentrate in OEM direct supply with multi-year platform commitments.
- Single Diaphragm:Compact elastomer diaphragm housed in stamped steel shells delivers moderate assist ratios for passenger vehicle hydraulic systems. Brazilian commercial fleet operators under ANVISA-aligned federal transport mandates are expanding purchases of remanufactured units to manage brake system renewal costs.
- Double Diaphragm:Tandem diaphragm architecture doubles effective surface area to generate higher assist forces for heavy-duty master cylinder displacements. North American commercial vehicle specifications for stopping-distance compliance are concentrating demand among medium-duty truck platforms requiring larger assist ratios.
- Remote Booster:Separated vacuum chamber linked to master cylinder via hydraulic lines enables flexible packaging in confined engine bays. Japanese compact commercial vehicle programs specify remote mounting to accommodate crowded powertrain compartments.
- Integral Booster:Master cylinder and booster share a common housing casting to reduce assembly steps and leak paths. German premium passenger vehicle platforms favor integrated modules for chassis weight reduction targets.
By volume, single diaphragm leads. By growth pace, electronic vacuum-assisted configurations are climbing the fastest.
End User:
Margin capture varies dramatically across the value chain, with OEM direct contracts locking in specification control while aftermarket channels compete on price for replacement volume.
- OEMs:Vehicle manufacturers specify booster architectures at platform conception, embedding multi-year supply agreements with brake system integrators. Chinese passenger vehicle corridors around Shanghai and Wuhan concentrate procurement authority with domestic OEM engineering centers.
- Tier-1 Suppliers:Chassis module specialists aggregate booster, master cylinder, and ABS valve block sourcing under integrated brake system contracts. European CSRD disclosure requirements favor Tier-1s with documented circular material flows in diaphragm production.
- Aftermarket Providers:Independent distributors and rebuild specialists compete on price for single diaphragm replacement volume. North American service networks are developing certified rebuild programs at price points below OEM replacement units.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations procure boosters as part of complete knock-down brake system kits. Brazilian logistics fleet expansion is driving assembler-level demand for vacuum-assisted braking in medium-duty truck platforms.
OEMs and Tier-1s dominate value capture. Aftermarket channels expand most quickly in emerging market fleet renewal cycles.
Technology:
Powertrain electrification is fragmenting technology adoption, with vacuum-dependent architectures declining while electromechanical assist systems gain specification share in hybrid platforms.
- Hydraulic:Direct mechanical amplification without vacuum dependency, historically limited to performance and racing applications. Niche specification persists in track-focused vehicle programs requiring consistent pedal feel regardless of engine state.
- Pneumatic:Compressed air assist systems dominant in heavy commercial vehicles with onboard air compression for braking and suspension. Air brake jurisdictions in Brazil and select North American heavy-duty segments sustain specification demand.
- Electronic:Sensor-actuated brake-by-wire architectures eliminate vacuum and hydraulic lines entirely, representing the terminal technology pathway for battery electric vehicles. European and Japanese OEMs are accelerating specification for dedicated EV platforms.
- Vacuum Assisted:Conventional manifold-dependent or pump-supplied differential pressure systems retain dominant share in internal combustion and mild-hybrid architectures. ECE R13-H performance envelope mandates sustain European specification requirements across passenger and light commercial weight classes.
Vacuum assisted retains volume leadership. Electronic configurations show steepest expansion trajectory as brake-by-wire platforms proliferate.
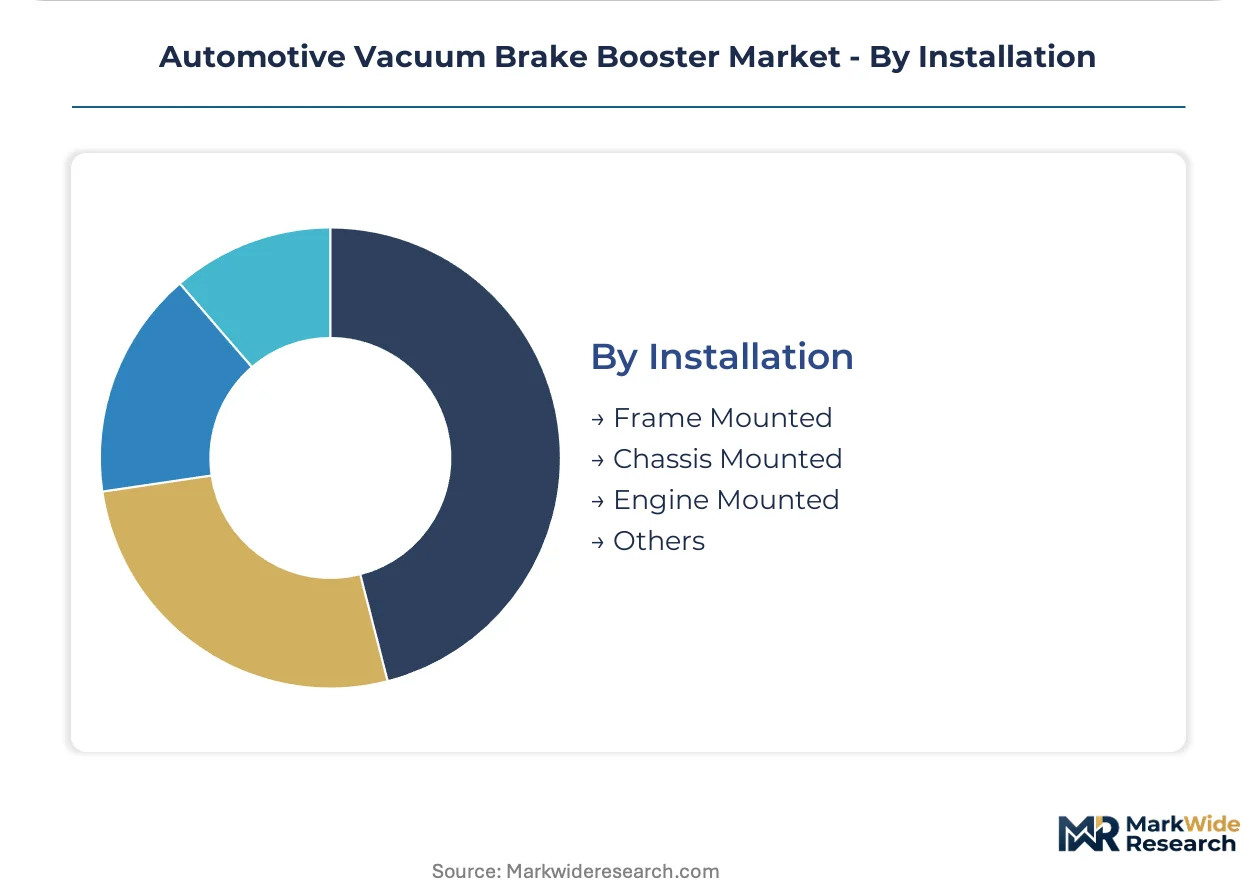
Installation:
Mounting location determines vacuum source routing, structural load paths, and service accessibility, with engine-mounted configurations facing displacement pressure from chassis-integrated module designs.
- Frame Mounted:Booster assembly attaches to vehicle frame rails, common in heavy commercial vehicles with remote master cylinder placement. North American heavy-duty truck specifications favor frame mounting for service accessibility in severe-duty applications.
- Chassis Mounted:Integration with suspension cross-members or subframe structures enables modular brake system pre-assembly. ZF Friedrichshafen AG competes on chassis-integrated module designs that reduce final assembly complexity for vehicle assemblers.
- Engine Mounted:Direct attachment to intake manifold or engine block minimizes vacuum line length and response lag. Denso Corporation anchors Asian OEM supply through dedicated engine-mounted booster architectures optimized for compact powertrain packaging.
- Others:Firewall-mounted and bulkhead-integrated configurations for specialized vehicle architectures including cab-over commercial designs and low-floor bus platforms. Japanese urban bus specifications require compact bulkhead mounting to preserve passenger cabin space.
Engine mounted leads by installed base. Chassis mounted is gaining specification fastest as modular assembly practices spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supplier consolidation around dedicated vacuum pump integration capabilities has concentrated manufacturing expertise among German and Japanese Tier 1 chassis specialists. This geographic clustering shapes regional procurement patterns and regulatory compliance pathways across major automotive production corridors.
United States
Commercial fleet operators in Michigan and Ohio are expanding vacuum-assisted braking purchases for medium-duty trucks under NHTSA's tightened stopping-distance mandates. The federal regulator's Federal Motor Vehicle Safety Standards govern minimum booster performance envelopes and failure mode requirements. Detroit-area engineering centers concentrate specification authority for North American truck platforms.
Germany
Mild-hybrid 48V architectures in Bavaria and Baden-Württemberg retain engine-coupled vacuum pumps while adding electric assist, creating hybrid-specific booster demand. ECE R13-H regulations mandate specific performance envelopes for vacuum-assisted braking across vehicle weight classes. Stuttgart-based OEMs enforce direct Tier 1 relationships for integrated brake modules.
China
Passenger vehicle manufacturing corridors around Shanghai and Wuhan concentrate procurement authority with domestic OEM engineering centers requiring MIIT-enforced GB brake system durability standards. The ministry's regulations directly influence local booster material specifications and diaphragm compound selection. Yangtze River Delta clusters anchor volume production for both domestic consumption and export markets.
Japan
Compact commercial vehicle programs in Aichi and Shizuoka prefectures specify remote booster mounting to accommodate crowded powertrain compartments. METI oversees industrial standards coordination for brake system component interoperability. Nagoya-area suppliers anchor Asian OEM supply through dedicated engine-mounted booster architectures.
Brazil
Logistics operators in São Paulo and Minas Gerais are expanding vacuum-assisted braking purchases for medium-duty trucks under ANVISA-aligned federal transport safety mandates. The national health regulator's vehicle safety alignment drives commercial fleet renewal cycles. Southeast industrial zones concentrate assembler-level demand for vacuum-assisted braking in truck platforms.
Automotive Vacuum Brake Booster Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated brake system specialists commanding specification control while component fabricators compete on unit economics. The supplier base organizes around three strategic archetypes: chassis-integrated module designers, engine-mounted architecture specialists, and dedicated vacuum pump integrators. Competitive dynamics center on long-term platform contract capture and backward integration into vacuum pump production.
Among Germany-based fabricators, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify the integrated systems archetype, occupying positions that span booster housing production through vacuum source integration. Denso Corporation anchors the Japanese specialist tier, representing engine-mounted architecture optimization for compact powertrain packaging. These three entities collectively illustrate how geographic clustering around OEM engineering centers reinforces supply relationships.
| Leading Market Players |
|---|
| HELLA |
| Denso Corporation |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Hyundai Mobis |
| Aisin Seiki |
| Delphi Technologies |
| Brembo |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
EPDM rubber compound substitution for REACH-compliant elastomer formulations simultaneously shifts diaphragm sourcing toward Asian compounders and compresses margin pools for European legacy suppliers. This material transition reconfigures procurement geography as Chinese manufacturers accelerate qualification cycles ahead of European implementation timelines.
Pricing Analysis
ECE R13-H performance envelope mandates dictate the pricing tier structure across European vacuum-assisted braking procurement. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated modules from aftermarket rebuilds and independent distributor channels. Cost compression in remanufactured single diaphragm units is intensifying because Brazilian fleet operators prioritize brake system renewal economics over specification grade. Aftermarket channels exhibit highest price sensitivity, while German premium OEMs accept premium positioning for chassis-integrated module designs.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes amplify inbound logistics costs for EPDM rubber feedstocks and stamped steel shell components. Manufacturing gravity centers on Germany, China, and Japan for vacuum pump integration and booster housing fabrication. Raw material dependencies draw from petrochemical-derived elastomer compounds, cold-rolled steel grades, and precision-machined aluminum valve bodies. Single-source vulnerability concentrates in European vacuum pump motor suppliers. Distribution runs through Tier 1 chassis module integrators to OEM assembly plants, with aftermarket channels feeding independent service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brake-by-wire proliferation in battery electric vehicle platforms constitutes a high-growth disruption, with NHTSA stopping-distance mandates simultaneously tightening performance thresholds for remaining vacuum-dependent architectures.
For Market Incumbents: Secure captive supply of vacuum pump motor production to defend against emerging electromechanical brake assist specialists. Lock long-term platform contracts with Chinese OEMs around Shanghai and Wuhan manufacturing corridors before local suppliers achieve ECE R13-H certification equivalence. Prioritize backward integration into EPDM compound formulation to offset REACH-driven material cost inflation. For New Entrants and Emerging Players: Anchor in Brazilian medium-duty truck fleet renewal cycles under ANVISA-aligned federal transport mandates, where specification authority fragments across logistics operators rather than concentrating with OEM engineering centers. Target remanufactured single diaphragm certification programs for North American independent service networks. Pursue direct Tier 2 supply relationships with chassis module integrators lacking in-house vacuum pump capabilities. For Investors and Strategic Acquirers: CSRD supply chain disclosure requirements reshape the acquisition landscape toward European Tier 1s with documented circular material flows in diaphragm production. Long-term viability favors targets with hybrid-specific electronic vacuum-assisted architectures serving 48V mild-hybrid programs in Germany and Japan. Monitor brake-by-wire specification rates in dedicated EV platforms as terminal demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Pump Production | Robert Bosch GmbH sustains margin control through in-house pump integration for European passenger programs. |
| Platform Standardization Across Mild-Hybrid Architectures | German OEMs consolidate booster specifications to reduce validation burden under accelerating ECE R13-H amendment cycles. |
| Geographic Manufacturing Footprint Expansion | Denso Corporation anchors Asian supply through engine-mounted architectures optimized for compact powertrain packaging. |
| Remanufactured Aftermarket Certification Program | North American service networks develop certified rebuild programs at price points below OEM replacement units. |
| Software-Defined Brake Module Investment | Electronic vacuum-assisted variants integrate sensor-actuated architectures for consistent assist pressure regardless of engine load state. |
Study Parameters
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier production schedules anchors the qualitative findings across this analysis. Primary interviews with brake system procurement managers, chassis module integration specialists, aftermarket distribution heads, and regulatory compliance officers combined with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA FMVSS filings, and ECE regulatory amendment records. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates.
Sensitivity analysis across propulsion architecture adoption scenarios, raw material cost bands, and regulatory implementation timelines frames the projection methodology. Segmentation dimensions span vehicle class, propulsion architecture, diaphragm configuration, and regional production cluster throughout the forecast period. CAGRs derive from unit shipment trajectories weighted by content-per-vehicle economics and platform lifecycle phasing. Forecast inputs incorporate MIIT durability standard enforcement intensity and Brazilian fleet renewal cycle timing.
Underlying assumptions cover internal combustion platform persistence rates, EPDM compound qualification timelines, and vacuum pump motor supply elasticity, with deviation risk concentrated in brake-by-wire adoption acceleration and REACH substance restriction scope expansion. Recalibration cycles align with material shifts in powertrain electrification penetration and regulatory amendment publication schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Torque Converter Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Power Liftgate for Automotive Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
Global Automotive Electric Drivetrain System Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Automotive Camshaft Market
Powertrain
Racing Clutches Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Small Gas Engine Market
Powertrain
Engines Market
Powertrain
Automotive Water Pump Market
Powertrain
Automotive Slipper Clutch Market
Powertrain
Global Automotive Engine Pulley Market