
 Global Automotive Torque Vectoring Market | 2026-2036
Global Automotive Torque Vectoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Torque Vectoring Market Intelligence
The shift toward active, electronically controlled systems is redrawing supplier hierarchies. GKN Automotive leverages its specialization in eDrive systems to capture demand from electric vehicle platforms. ZF Friedrichshafen AG competes across a wide portfolio of drivetrain solutions, while BorgWarner Inc. sustains its position through deep expertise in powertrain components and control modules.
Automotive torque vectoring is a drivetrain technology that dynamically distributes engine or motor torque between wheels on the same axle or between front and rear axles. By precisely managing torque delivery based on inputs like wheel speed and steering angle, it improves vehicle handling and stability. Electronic torque vectoring systems are displacing older mechanical variants due to superior response times. Adoption is highest in high-performance vehicles and electric vehicles, which benefit most from precise traction control.
Regulatory frameworks, including the US National Highway Traffic Safety Administration (NHTSA) stability control mandates, set a baseline for active safety. In Europe, the General Safety Regulation (GSR) further encourages the integration of advanced driver-assistance systems. These rules create a favorable environment for torque vectoring adoption as a safety and performance feature. The key decision for automakers now involves managing the system cost for integration into mass-market passenger cars.
Market Dynamics
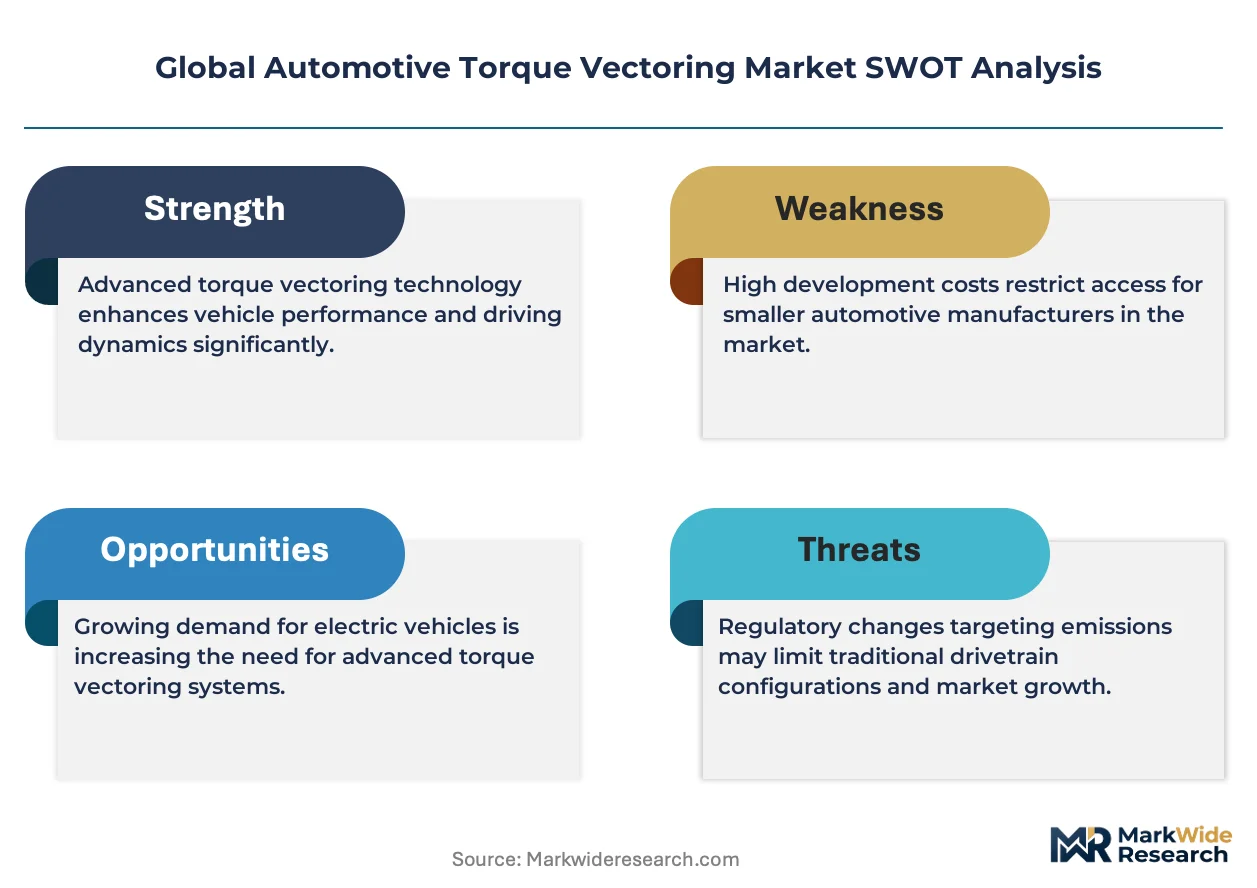
The transition from mechanical to active, electronically controlled systems represents the central structural force in the automotive torque vectoring market. This shift is driven by the demands of electric vehicle platforms and stricter global safety regulations requiring more responsive vehicle dynamics.
Growth Catalysts
- EV Performance Optimization:The adoption of torque vectoring in electric vehicles enhances performance and battery efficiency by enabling precise torque distribution to each wheel, minimizing wheel slip and optimizing regenerative braking.
- High-Performance Segment Demand:In geographies like Germany, automakers in the high-performance and luxury segments integrate torque vectoring to deliver superior handling, cornering stability, and a more engaging driving experience, setting a benchmark for vehicle dynamics.
- Regulatory Safety Mandates:Frameworks such as Europe's General Safety Regulation (GSR) promote the integration of advanced active safety systems, creating a favorable regulatory environment for torque vectoring as a tool to enhance vehicle stability and prevent loss of control.
Market Restraints
- High System Cost:The significant cost associated with the sensors, actuators, and control units for electronic torque vectoring systems currently limits their widespread adoption in mass-market, budget-oriented passenger cars.
- Integration Complexity:Integrating sophisticated torque vectoring software with a vehicle's existing electronic control unit (ECU) architecture presents a substantial engineering challenge, requiring extensive validation and calibration.
- Competition from Simpler Systems:Advanced electronic stability control (ESC) and traction control systems offer a subset of the benefits at a lower cost, posing a substitution threat in cost-sensitive vehicle segments.
Strategic Opportunities
- Mass-Market Vehicle Penetration:Developing more cost-effective and modular torque vectoring systems presents a significant opportunity to penetrate the high-volume compact and mid-size passenger car segments currently underserved by this technology.
- Autonomous Driving Synergy:The convergence of torque vectoring with advanced driver-assistance systems (ADAS) and autonomous driving platforms creates an opportunity, as precise wheel-level torque control is essential for safe and stable automated maneuvering.
- Expansion into Commercial Vehicles:Applying torque vectoring technology to light commercial vehicles and heavy-duty trucks offers an opportunity to improve stability, traction, and safety, particularly for vehicles operating with heavy or shifting loads.
Industry Challenges
- Software Development and Validation:The operational challenge lies in developing and rigorously testing the complex control algorithms that govern torque distribution in real-time, ensuring flawless performance across all driving conditions and failure modes.
- Specialized Component Supply:Automakers face the challenge of securing a stable supply of specialized components, such as high-speed electric motors and planetary gear sets, from a concentrated base of Tier-1 suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Torque Vectoring Market |
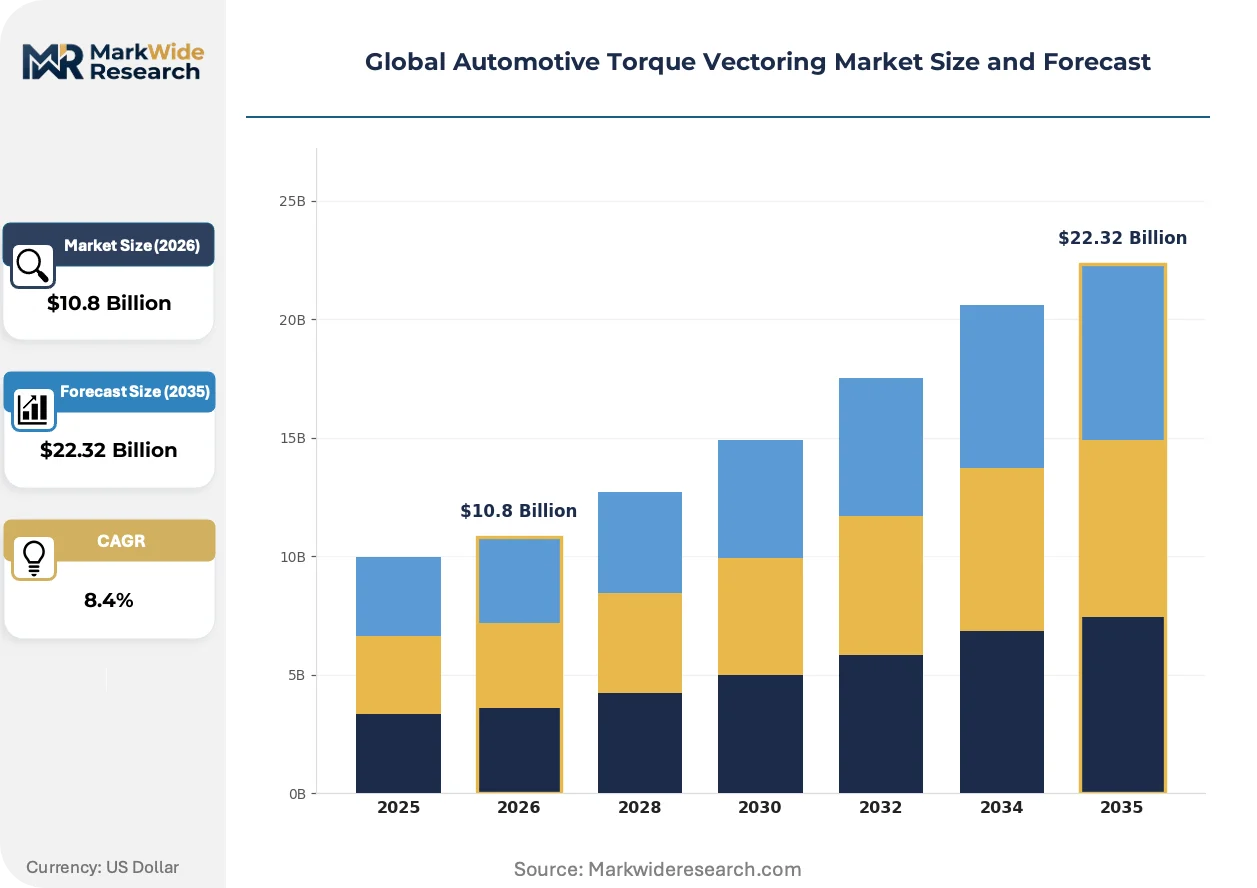
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $22.32 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Electric Vehicles, Heavy-Duty Trucks Technology: Mechanical Torque Vectoring, Electronic Torque Vectoring, Hydraulic Torque Vectoring, Electro-Hydraulic Torque Vectoring Application: High-Performance Vehicles, Off-Road Vehicles, Luxury Vehicles, Compact Cars, Safety Systems Component: Torque Vectoring Control Unit, Sensors, Actuators, Drive Shafts, Differential Gears |
| Companies Covered | GKN Automotive, BorgWarner Inc., ZF Friedrichshafen AG, Dana Incorporated, American Axle & Manufacturing, Continental AG, Bosch Group, Aisin Seiki Co., Ltd., JTEKT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Torque Vectoring Market Strategic Shifts & Innovations
Innovation in the torque vectoring market is defined by the move toward software-defined vehicle dynamics. The focus is shifting from mechanical hardware to the sophistication of control algorithms and their ability to integrate with other vehicle systems for a holistic performance outcome.
Advanced electronic torque vectoring systems provide instantaneous, software-driven management of torque to individual wheels. Automakers in the electric vehicle and performance segments are rapidly adopting these systems to gain a competitive edge in handling and efficiency. This software-centric approach is displacing older, purely mechanical or hydraulic limited-slip differentials, which cannot offer the same level of dynamic adjustment or integration with vehicle electronics.
Regulatory frameworks establish a clear pathway for advanced safety technology adoption. The US National Highway Traffic Safety Administration (NHTSA) mandates for electronic stability control create a baseline for active vehicle safety. This encourages automakers to differentiate by offering superior systems like torque vectoring. The sport utility vehicle (SUV) segment is most affected, with manufacturers increasingly using advanced traction management as a key safety and performance feature.
A notable shift in consumer behavior is the growing preference for customizable vehicle performance through selectable drive modes. This demand for software-defined handling characteristics is altering how vehicles are marketed, moving beyond just mechanical specifications. This trend is most prominent in the North American and German automotive markets, where brand identity is deeply connected to the perceived quality of the driving experience.
Global Automotive Torque Vectoring Market Segmentation
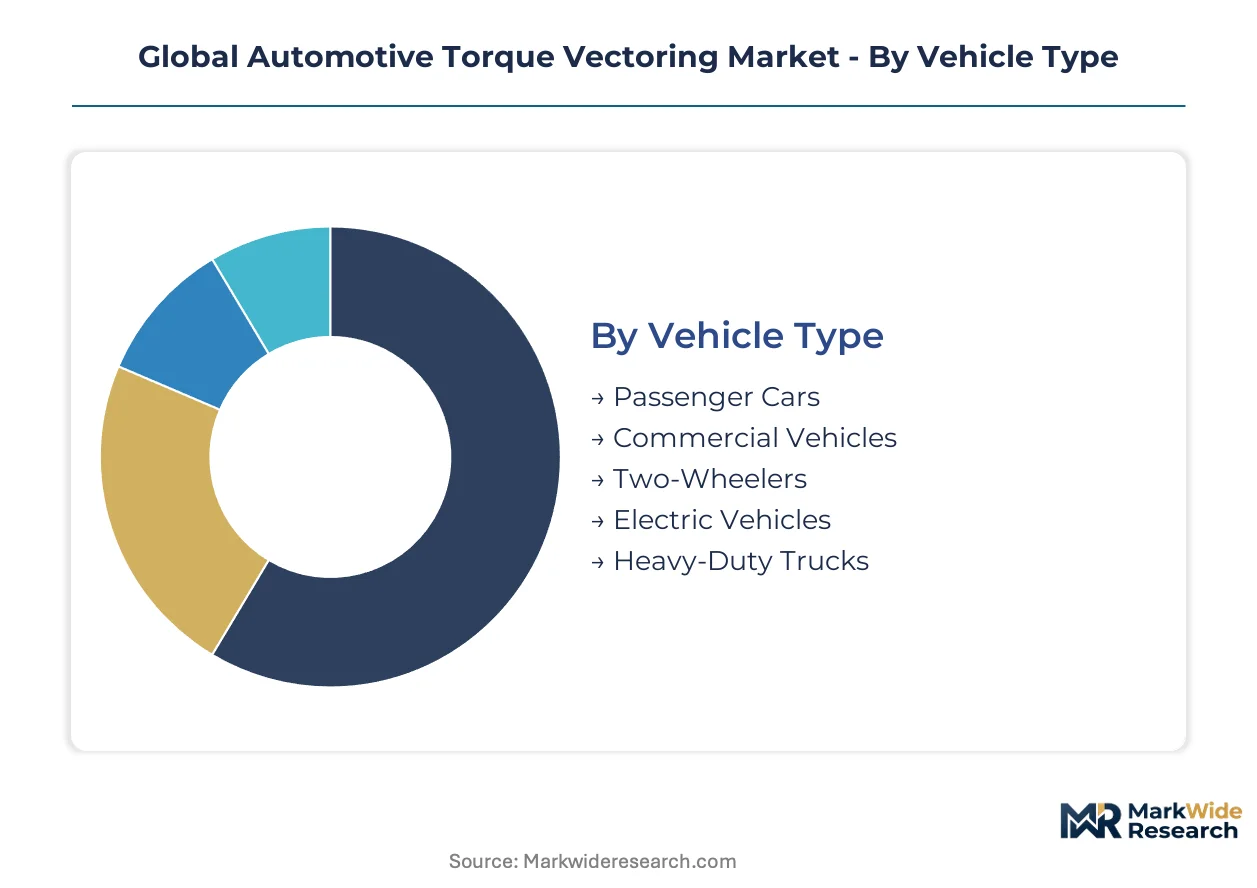
The global automotive torque vectoring market segments across various dimensions, reflecting the diverse requirements of vehicle manufacturers and end-users. Understanding these distinct segments reveals where innovation concentrates and where new opportunities emerge for technology providers.
Vehicle Type:
Regulatory frameworks across the US and Europe directly influence the vehicle types that integrate advanced torque vectoring systems.
- Electric Vehicles:Electric vehicles utilize precise motor control for instantaneous torque distribution to individual wheels, enhancing both traction and battery regeneration efficiency. Demand from Germany's high-performance electric vehicle sector drives innovation in these systems.
- Passenger Cars:Passenger cars integrate torque vectoring for improved stability and handling, particularly in higher-trim models and performance variants. The US National Highway Traffic Administration (NHTSA) mandates for stability control create a baseline for active safety features in this segment.
- Commercial Vehicles:Commercial vehicles employ torque vectoring to improve traction and stability, especially when operating with heavy or shifting loads.
- Two-Wheelers:Two-wheelers incorporate basic torque vectoring principles for enhanced cornering stability and rider safety, particularly in advanced motorcycle designs.
- Heavy-Duty Trucks:Heavy-duty trucks benefit from torque vectoring by improving off-road capability and load distribution management.
Passenger Cars handle the majority of throughput; Electric Vehicles are the fastest mover on share.
Technology:
The maturity and complexity of torque vectoring technologies dictate their adoption rates across various vehicle platforms.
- Electronic Torque Vectoring:Electronic systems offer superior response times and precise, software-driven torque management to individual wheels, displacing older mechanical variants. Automakers in Germany's high-performance sector prioritize these advanced systems for dynamic handling.
- Mechanical Torque Vectoring:Mechanical systems use physical differentials to distribute torque, providing a cost-effective solution with less dynamic control than electronic counterparts. This technology remains prevalent in cost-sensitive vehicle segments.
- Hydraulic Torque Vectoring:Hydraulic systems utilize fluid pressure to manage torque distribution, offering a balance between cost and responsiveness for specific applications.
- Electro-Hydraulic Torque Vectoring:Electro-hydraulic systems combine electric control with hydraulic actuation, providing a refined level of torque management for specialized vehicle designs.
Electronic Torque Vectoring is rapidly displacing older solutions; Mechanical Torque Vectoring maintains a significant installed base.
Application:
Customer demand for enhanced driving dynamics and safety features shapes the application of torque vectoring solutions.
- High-Performance Vehicles:High-performance vehicles integrate torque vectoring to maximize cornering grip, acceleration, and overall dynamic handling, delivering a superior driving experience. Germany's automotive industry heavily relies on this application for brand differentiation.
- Safety Systems:Torque vectoring enhances active safety systems by preventing wheel slip and maintaining vehicle stability during emergency maneuvers or adverse road conditions. The European General Safety Regulation (GSR) encourages such integrations.
- Luxury Vehicles:Luxury vehicles employ torque vectoring to provide refined handling, improved ride comfort, and advanced traction control, elevating the premium driving experience.
- Off-Road Vehicles:Off-road vehicles utilize torque vectoring to optimize traction and control across challenging terrains, improving capability and driver confidence.
- Compact Cars:Compact cars are beginning to adopt simplified torque vectoring solutions to improve stability and handling, particularly in higher-trim variants.
High-Performance Vehicles continue to represent the premium application; Safety Systems show the steepest expansion trajectory.
Component:
Supply concentration among specialized Tier-1 manufacturers influences the availability and integration of core torque vectoring components.
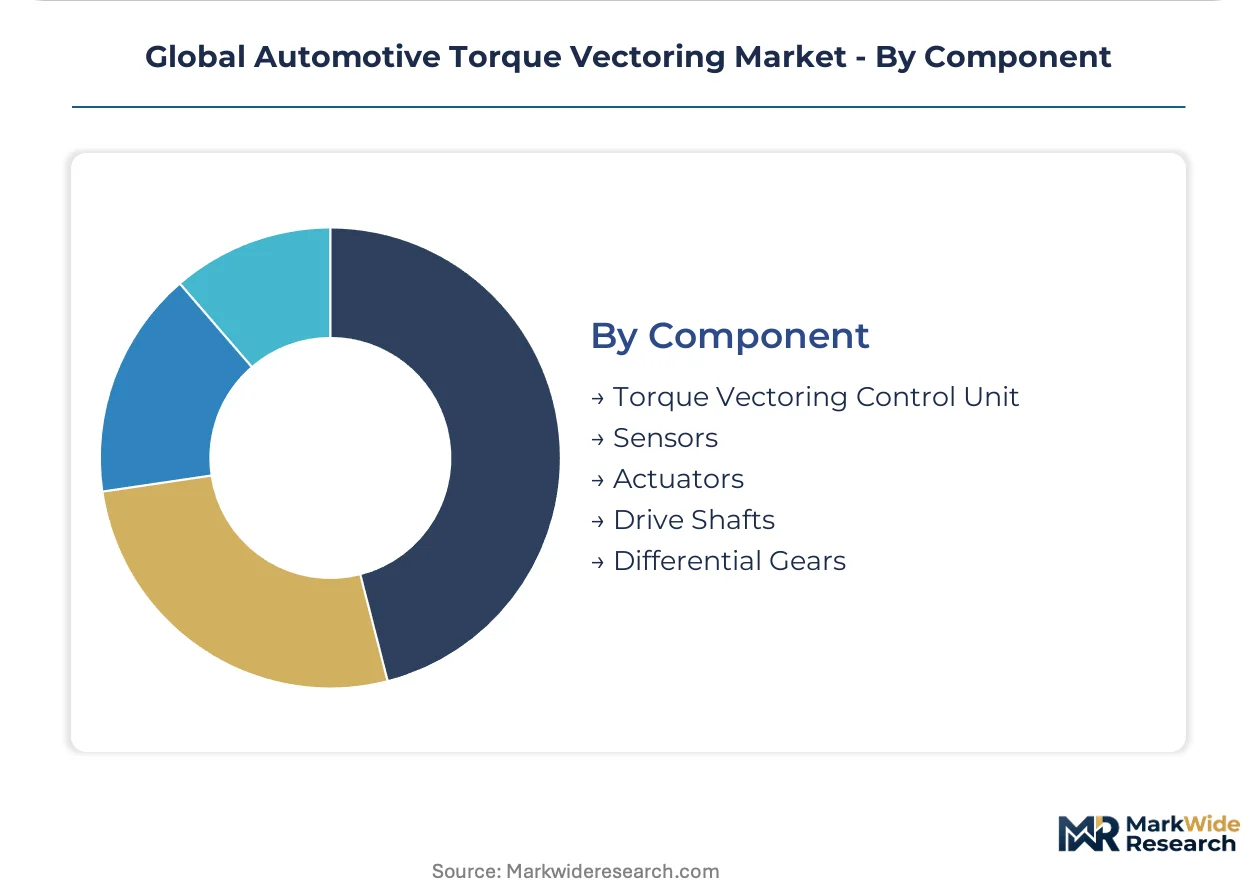
- Torque Vectoring Control Unit:These electronic control units house the complex algorithms that process sensor data and command actuators for precise torque distribution. ZF Friedrichshafen AG specializes in these sophisticated control modules.
- Actuators:Actuators convert electrical signals from the control unit into mechanical action, dynamically adjusting torque delivery to individual wheels or axles. GKN Automotive leverages its expertise in eDrive systems for specialized actuator development.
- Sensors:Various sensors, including wheel speed, steering angle, and yaw rate sensors, provide real-time data inputs crucial for the torque vectoring system's operation.
- Drive Shafts:Drive shafts transmit power from the transmission to the differential, forming a fundamental part of the drivetrain architecture for torque vectoring.
- Differential Gears:Differential gears enable wheels on the same axle to rotate at different speeds, a foundational mechanism for torque distribution in both mechanical and electronic systems.
Torque Vectoring Control Units command the highest value per unit; Differential Gears remain foundational for torque transfer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive torque vectoring market exhibits a balanced trade dynamic, with technology-exporting nations driving innovation and large automotive manufacturing hubs absorbing advanced systems. High-value components often originate from specialized European and Asian suppliers, while vehicle assembly and integration occur across major production centers. This interplay shapes regional demand and supply configurations for sophisticated drivetrain technologies.
Germany
Germany's high-performance automotive sector drives significant demand for torque vectoring, enhancing vehicle dynamics and safety. The KBA (Federal Motor Transport Authority) mandates stringent safety standards for vehicle stability, encouraging advanced system integration. Automotive clusters in Bavaria and Baden-Württemberg lead development and adoption of electronic torque vectoring for luxury and sports car brands.
United States
The United States market prioritizes active safety and performance in passenger cars and SUVs, fostering strong adoption of torque vectoring. The National Highway Traffic Safety Administration (NHTSA) stability control mandates establish a baseline for active safety features. Detroit's automotive hub and Silicon Valley tech firms collaborate on advanced control algorithms for next-generation vehicle platforms.
Japan
Japan's automotive industry integrates torque vectoring for enhanced vehicle stability and fuel efficiency, particularly in hybrid and electric models. METI (Ministry of Economy, Trade and Industry) policies support research and development in advanced automotive technologies. Manufacturing centers like Nagoya and Yokohama host key Tier-1 suppliers and automakers advancing torque vectoring solutions.
China
China represents a critical market for electric vehicle torque vectoring, where precise control optimizes battery performance and range. The MIIT (Ministry of Industry and Information Technology) promotes new energy vehicle technologies and safety standards. Automotive production bases in Shanghai and Guangzhou are rapidly deploying advanced torque vectoring systems in domestic EV brands.
South Korea
South Korea's robust automotive sector demands torque vectoring for premium vehicle segments and electric mobility solutions. The country's national automotive safety standards encourage the integration of sophisticated stability control systems. Manufacturing facilities in Ulsan and Gyeonggi Province are central to the development and production of advanced torque vectoring components.
Global Automotive Torque Vectoring Market Key Industry Players
Concentration sits with established Tier-1 automotive suppliers, who leverage extensive R&D capabilities and deep integration with global automakers. The market structure is characterized by a tiered ecosystem, where a few dominant players control core technologies and specialized components. Strategic archetypes include diversified drivetrain solution providers and focused eDrive system specialists. Key competitive moves involve technology licensing to broaden market reach and strategic partnerships to co-develop next-generation systems.
Diversified drivetrain solution providers, such as ZF Friedrichshafen AG, offer a wide portfolio of components spanning mechanical and electronic systems, serving a broad customer base. GKN Automotive exemplifies specialization in eDrive systems, catering to the growing electric vehicle segment with advanced torque management solutions. BorgWarner Inc. represents a global player with deep expertise across powertrain components and control modules, sustaining its position through continuous innovation in torque management technologies. These companies anchor the supply of critical torque vectoring units and actuators to major vehicle manufacturers worldwide, influencing system architecture.
| Leading Market Players |
|---|
| GKN Automotive |
| BorgWarner Inc. |
| ZF Friedrichshafen AG |
| Dana Incorporated |
| American Axle & Manufacturing |
| Continental AG |
| Bosch Group |
| Aisin Seiki Co., Ltd. |
| JTEKT Corporation |
| Others |
Cost & Logistics Intelligence
Specialized component lead times, often exceeding 12 months for critical actuators, grant significant pricing power to concentrated Tier-1 suppliers and shape strategic inventory decisions across the automotive torque vectoring supply chain.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing for torque vectoring systems. Price differentiation stems from the high customization level required for specific vehicle platforms and the established brand premium of Tier-1 suppliers. Cost compression in the mass-market segment intensifies as automakers seek to integrate torque vectoring into more affordable vehicles. High-performance and luxury segments exhibit lower price sensitivity, prioritizing advanced features and integration.
Supply Chain Analysis
Extended lead times for specialized components from Europe and Asia define the torque vectoring supply chain. Geographic supply concentration centers on Germany, Japan, and South Korea for advanced components like high-speed electric motors and planetary gear sets. Single-source vulnerability from a concentrated base of Tier-1 suppliers presents a structural risk. Distribution runs through direct long-term contracts with vehicle manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive torque vectoring market is experiencing a cyclical recovery, driven by renewed vehicle production cycles and increased investment in advanced electric vehicle platforms. This rebound reflects broader automotive industry health and innovation priorities.
For Market Incumbents: Shield existing market share by accelerating investment in software-defined vehicle dynamics and advanced control algorithms. Strategic partnerships with automakers for deep integration of torque vectoring systems will counter the threat from simpler, lower-cost stability systems. Deepen vertical integration into specialized control module development to maintain technological leadership. Emphasize robust certification and validation processes to differentiate offerings.
For New Entrants and Emerging Players: Differentiate on cost-effective, modular torque vectoring solutions designed for high-volume segments. Target underpenetrated mass-market compact cars and commercial vehicles, where existing systems are less sophisticated. Focus on light commercial vehicles as a penetrable segment, offering improved stability for heavy loads. A go-to-market angle emphasizing ease of integration and lower total cost of ownership will be crucial.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified Tier-1 automotive suppliers seeking to divest non-core drivetrain assets. The market's long-term viability is strong, given torque vectoring's essential role in advanced driver-assistance systems and electric vehicle performance. Acquisition archetypes include specialized software firms focused on control algorithms and niche component manufacturers. The signal to watch is a sustained increase in OEM internal R&D spending on next-generation torque vectoring integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Control Investment | Enhances dynamic response and customization for software-centric vehicle architectures. |
| EV Platform Integration Partnerships | Captures demand from electric vehicles, optimizing battery efficiency and performance. |
| Cost-Effective Modular System Development | Unlocks penetration into high-volume mass-market passenger car segments. |
| Commercial Vehicle Segment Expansion | Improves stability and traction for heavy loads in light and heavy-duty trucks. |
| Advanced Sensor Fusion R&D | Enables more precise torque distribution through real-time environmental awareness. |
Research Approach
Operator-level perspectives from OEM platform engineers, Tier-1 procurement leads, automotive software developers, and vehicle safety regulators anchored the qualitative base. Primary interviews were combined with extensive secondary research, validating insights across multiple data points. Secondary sources included vehicle production databases, regulatory filings from NHTSA and KBA, technical journals, and company financial reports. This approach facilitated both bottom-up and top-down triangulation of market dynamics.
Sensitivity analysis was performed to account for varying market conditions across the analysis window. The analytical framework modeled segmentation dimensions including vehicle type, technology, application, component, and regional production cluster. Compound annual growth rates were derived from historical data and projected growth drivers. Key forecast inputs included electric vehicle adoption rates and the evolution of global safety regulations.
The analysis sits within stated boundaries; outcomes outside of anticipated technological advancements or regulatory shifts would require recalibration. Forecasts reflect assumptions regarding economic stability and automotive industry investment, with unforeseen geopolitical events or significant shifts in consumer vehicle preferences as key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Internal Combustion Engine Market
Powertrain
EGR and Emissions Control Actuator Systems Market
Powertrain
Tachometer Market
Powertrain
Automatic Transmission Torque Converter Market
Powertrain
Clutch Market
Powertrain
Automotive Torque Vectoring System Market
Powertrain
North America Automotive Engine Oils Market
Powertrain
Global Automotive Electric Drivetrain System Market
Powertrain
Global Powertrain Market
Powertrain
Crankshaft Oil Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
Automotive Carburetor Market
Powertrain
LNG Engine Market
Powertrain
Automotive Oil Sump Market
Powertrain
Automotive TCU Market
Powertrain
Advanced Gear Shifter System Market