
 Global Industrial Turbocharger Market | 2026-2036
Global Industrial Turbocharger Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Turbocharger Market Intelligence
The expansion of data centers and distributed power systems is rebalancing the industrial turbocharger market away from a sole reliance on traditional marine and construction applications. Cummins Inc. leverages its integrated engine and aftertreatment expertise to serve this diverse application base. Mitsubishi Heavy Industries Ltd. specializes in large-frame turbochargers for the marine and power generation sectors, sustaining a strong position in high-output segments. BorgWarner Inc. competes with advanced technologies like electric turbochargers for commercial vehicles.
An industrial turbocharger is a turbine-driven forced induction device that increases an internal combustion engine's efficiency and power output. It utilizes hot exhaust gas to spin a turbine, which in turn drives a compressor wheel to force more dense, oxygen-rich air into the combustion chamber. Variable Geometry Turbochargers represent a high-growth product segment due to their efficiency benefits under varied load conditions. The commercial vehicles application remains the largest volume segment, driven by global logistics and freight transport.
Emissions standards are the primary regulatory force, with frameworks like the US EPA's Tier 4 Final and the EU Green Deal shaping engine design and aftertreatment requirements. China's dual carbon goals also mandate higher efficiency and lower emissions from industrial machinery and power systems, influencing OEM choices. OEM decisions on adopting electric turbochargers versus optimizing existing variable geometry designs will determine future technology roadmaps and investment priorities.
Market Dynamics
The industrial turbocharger market is defined by the persistent tension between the demand for greater power density in industrial engines and the global mandate for stricter emissions control, a dynamic that elevates advanced air management technologies as a critical design component.
Growth Catalysts
- Regulatory Mandates:Frameworks like the US EPA's Tier 4 Final and the EU Green Deal directly compel the adoption of more efficient turbochargers to meet nitrogen oxide and particulate matter reduction targets in industrial and commercial vehicle engines.
- Power Generation Demand:The expansion of data centers and the need for reliable backup power systems in commercial infrastructure create consistent demand for turbocharged generator sets that offer high power output and rapid load response.
- Infrastructure Development:Major infrastructure and construction projects, particularly in China, sustain demand for high-output engines in heavy machinery, requiring advanced turbocharging to meet both performance and local emissions standards like China VI.
Market Restraints
- Material and Manufacturing Costs:The high cost of nickel-based superalloys and titanium aluminides, necessary for the turbine wheels in high-efficiency Variable Geometry Turbochargers, presents a significant barrier to wider adoption in cost-sensitive segments.
- Technical Durability:Electric turbochargers face durability and thermal management challenges, especially in harsh industrial environments with high vibration and temperature cycles, limiting their deployment in certain off-highway applications.
- Supply Chain Bottlenecks:The manufacturing of precision-cast turbine and compressor wheels is concentrated among a few specialized suppliers, creating potential bottlenecks and price volatility for engine OEMs.
Strategic Opportunities
- Hydrogen Combustion Engines:The development of hydrogen internal combustion engines (H2-ICE) for heavy-duty transport creates a new application for specialized turbochargers designed to handle different air-to-fuel ratios and higher combustion temperatures.
- Remanufacturing and Aftermarket:Offering certified remanufactured turbochargers provides a cost-effective solution for second and third-life engines, opening a significant service revenue stream in regions with aging commercial vehicle fleets like Europe.
- Hybrid System Integration:Combining turbochargers with 48V mild-hybrid systems in commercial vehicles allows for energy recuperation and electric boosting, improving overall powertrain efficiency beyond what a turbocharger alone can achieve.
Industry Challenges
- ECU Integration Complexity:Integrating the advanced controls for electric and variable geometry turbochargers with existing engine control unit (ECU) software is a complex task requiring significant software development and validation resources from OEMs.
- Specialized Engineering Talent:A scarcity of engineers with cross-disciplinary expertise in high-speed rotating machinery, power electronics, and control systems engineering hinders rapid innovation and product development cycles for next-generation turbochargers.
- Certification and Validation Cycles:The long and capital-intensive process of validating new turbocharger designs to meet OEM standards for durability, reliability, and performance over hundreds of thousands of miles or thousands of operating hours slows market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Turbocharger Market |
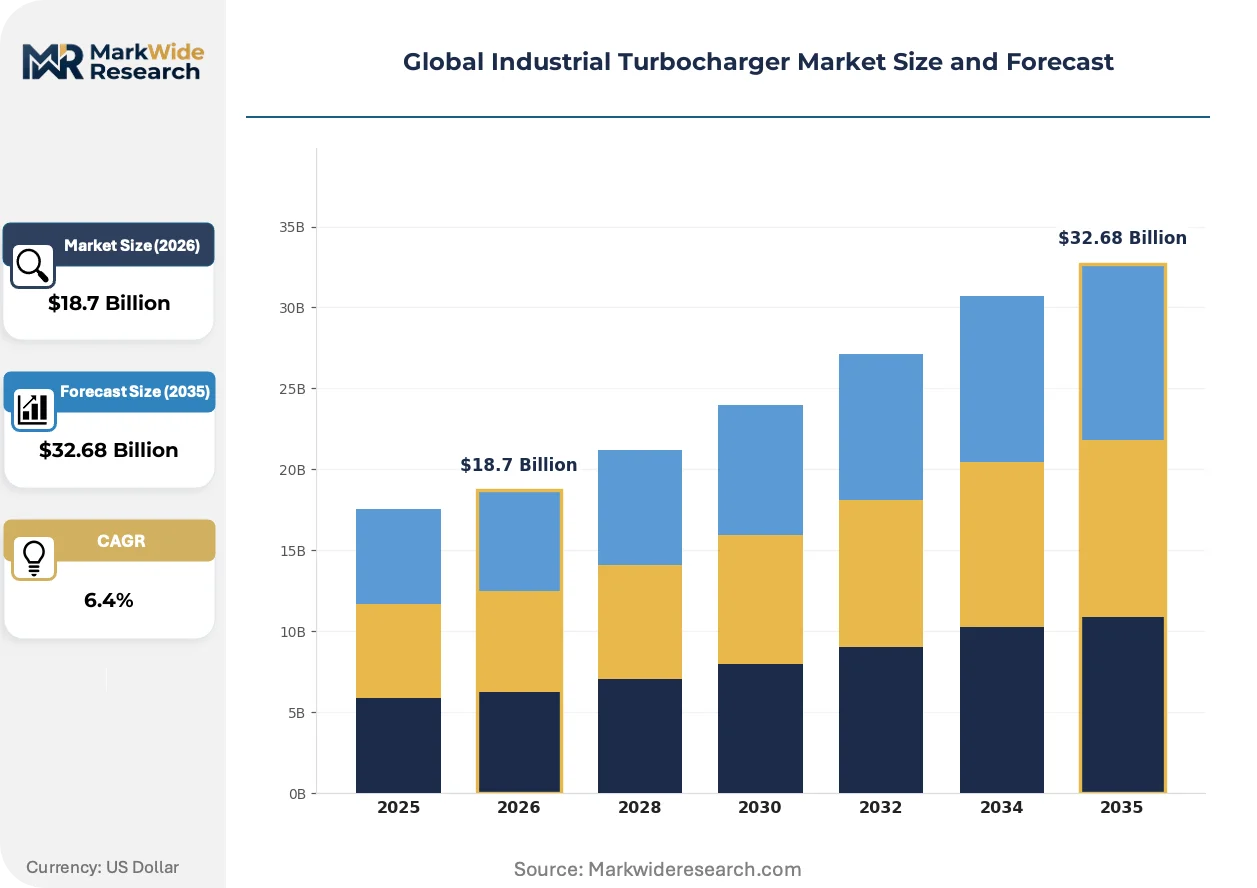
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Turbocharger, Twin Turbocharger, Variable Geometry Turbocharger, Electric Turbocharger Technology: Wastegate, Ball Bearing, Variable Nozzle, Fixed Geometry Turbo, Electric Assisted Application: Commercial Vehicles, Marine Engines, Power Generation, Construction Equipment, Agricultural Machinery End User: OEMs, Aftermarket Suppliers, Fleet Operators, Shipyards |
| Companies Covered | IHI Corporation, Honeywell International Inc., BorgWarner Inc., Fengcheng Xindongli Turbocharger Co. Ltd., Continental AG, Garrett Motion Inc., Cummins Inc., Bosch Mahle, Mitsubishi Heavy Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Turbocharger Market Strategic Shifts & Innovations
The market is shifting from a focus on purely mechanical efficiency gains toward integrated, electronically controlled air management systems. These systems are essential for simultaneously meeting demands for improved engine performance and compliance with increasingly stringent global emissions regulations.
Electric turbochargers, or e-turbos, utilize an integrated high-speed electric motor to spin the compressor wheel, effectively eliminating turbo lag at low engine speeds. Commercial vehicle and specialized industrial engine segments are adopting this technology to achieve superior transient response and low-end torque. This technology is rewriting the performance expectations for engine responsiveness and a vehicle's ability to accelerate under load.
China's dual carbon goals are a significant regulatory driver, mandating higher efficiency and lower emissions from industrial machinery and power systems. This policy is forcing engine manufacturers to accelerate the adoption of high-efficiency technologies, including Variable Geometry Turbochargers and waste heat recovery systems. The off-highway equipment segment, in particular, is rapidly moving away from older, less efficient fixed-geometry designs to comply.
Fleet operators are increasingly making purchasing decisions based on a turbocharger's contribution to total cost of ownership, prioritizing fuel efficiency and extended service intervals over the initial component price. This behavioral change disrupts the traditional aftermarket channel, which often competed on price, and favors premium components with documented performance and reliability benefits. This trend is most visible within the long-haul freight and continuous-duty power generation sectors in North America and Europe.
Global Industrial Turbocharger Market Segmentation
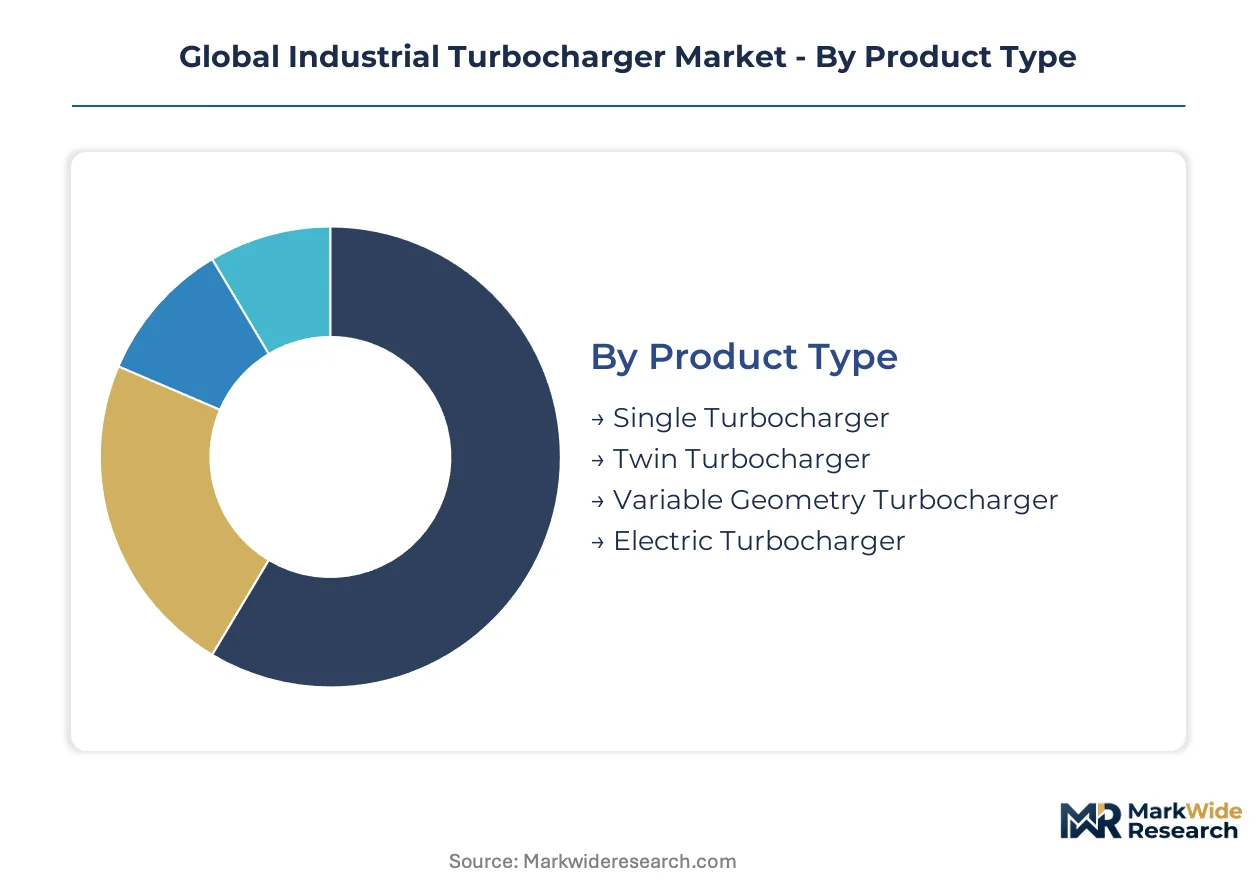
The global industrial turbocharger market segmentation provides a granular view of product evolution and demand drivers. This detailed analysis helps stakeholders understand the diverse technological requirements and application-specific needs shaping market dynamics. It also highlights the different regulatory and performance standards influencing component selection.
Product Type:
The product type segmentation highlights varying regulatory approval pathways, with advanced designs facing more rigorous validation processes.
- Variable Geometry Turbocharger:This advanced design dynamically alters exhaust gas flow to the turbine, optimizing boost pressure across a wide engine speed range for improved fuel efficiency and reduced emissions. Demand is concentrating in Europe and China, driven by stringent emissions standards like the EU Green Deal and China's dual carbon goals.
- Electric Turbocharger:Featuring an integrated electric motor, this turbocharger eliminates turbo lag by spinning the compressor independently of exhaust gas flow, providing instant boost. Commercial vehicle manufacturers in North America are increasingly adopting this technology to meet demanding transient response requirements and enhance low-end torque.
- Single Turbocharger:This is the most common and cost-effective turbocharger configuration, utilizing a single turbine and compressor wheel for basic boost.
- Twin Turbocharger:Employing two turbochargers, often in parallel or sequential setups, this configuration enhances power output and reduces turbo lag in larger industrial engines.
Leading the category by volume: Single Turbocharger. Growing fastest: Electric Turbocharger.
Technology:
Technology segmentation reflects distinct cost tiers, ranging from established, cost-effective solutions to premium, high-performance innovations.
- Variable Nozzle:This technology uses movable vanes to control exhaust gas velocity entering the turbine, optimizing performance across engine loads and improving fuel economy. Its adoption is accelerating in commercial vehicles and power generation to meet efficiency targets.
- Electric Assisted:Integrating an electric motor with the turbocharger shaft, this technology provides supplementary power to the compressor, particularly at low engine speeds, enhancing responsiveness. This is gaining traction in heavy-duty commercial transport for improved transient performance.
- Wastegate:A bypass valve that controls the amount of exhaust gas reaching the turbine, regulating boost pressure to prevent overspeeding in industrial engines.
- Ball Bearing:Incorporating ball bearings reduces friction and improves turbocharger responsiveness compared to traditional journal bearings, enhancing durability.
- Fixed Geometry Turbo:A basic turbocharger design with static turbine housing and compressor wheel geometry, offering simplicity and cost-effectiveness for various applications.
Variable Nozzle technology is expanding most quickly, while Wastegate designs maintain significant market presence.
Application:
Application segmentation reveals where the highest volumes of industrial turbochargers are deployed, influencing manufacturing scale and design priorities.
- Commercial Vehicles:This segment includes heavy-duty trucks, buses, and vans, where turbochargers are essential for power, fuel efficiency, and emissions compliance. Global logistics expansion drives consistent demand for robust and efficient turbocharging solutions in this sector.
- Power Generation:Turbochargers in this application enhance the output and efficiency of diesel and gas generator sets for prime and backup power. The expansion of data centers and distributed power systems in the US creates strong demand for high-performance turbochargers.
- Marine Engines:Turbochargers increase the power and efficiency of propulsion and auxiliary engines in ships and offshore vessels, meeting demanding operational profiles.
- Construction Equipment:Heavy machinery like excavators, loaders, and bulldozers rely on turbochargers for high torque and power in demanding operating conditions.
- Agricultural Machinery:Tractors, harvesters, and other farm equipment utilize turbochargers to improve engine performance and fuel economy in varied field operations.
Commercial Vehicles command the largest share of applications, with Power Generation exhibiting the steepest expansion trajectory.
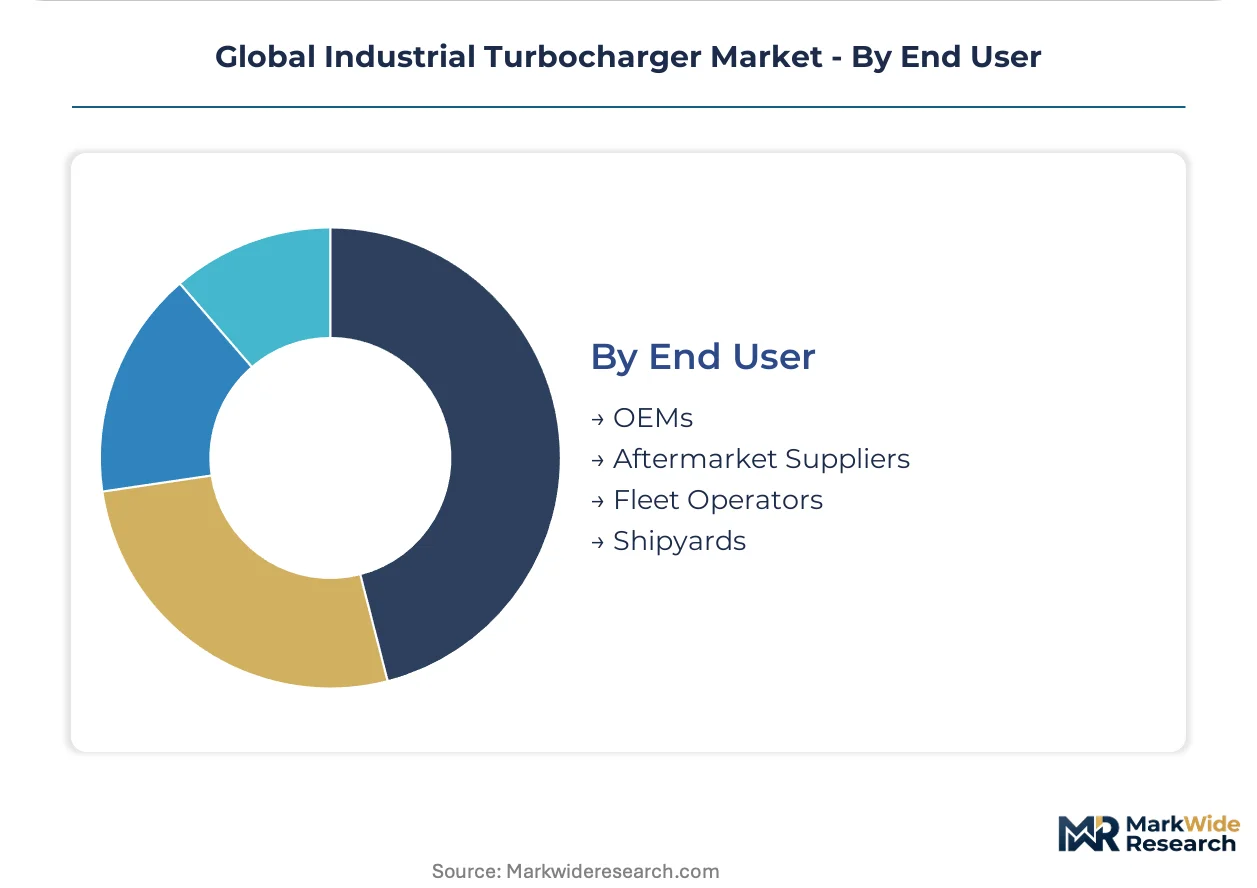
End User:
The end-user segmentation differentiates the distinct procurement and service requirements across various customer types in the industrial turbocharger market.
- OEMs:Original Equipment Manufacturers integrate turbochargers directly into new engines and vehicles during the manufacturing process, demanding specific design and validation support. These customers prioritize long-term supply agreements and stringent quality control.
- Aftermarket Suppliers:These entities provide replacement turbochargers and components for existing engines, catering to maintenance and repair needs. Aftermarket demand is strong in Europe due to aging commercial vehicle fleets requiring cost-effective service solutions.
- Fleet Operators:Companies managing large numbers of commercial vehicles or industrial equipment purchase turbochargers for maintenance and upgrades, focusing on total cost of ownership.
- Shipyards:These facilities procure turbochargers for new marine engine installations and for the repair and overhaul of existing vessels, requiring specialized marine-grade components.
OEMs represent the primary channel for new installations, as Aftermarket Suppliers increasingly gain share through service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones across China drive significant industrial turbocharger demand, particularly for infrastructure and manufacturing projects. This concentration of industrial activity influences global supply chains for high-output engines and components. Specific regional policies and environmental regulations further shape technology adoption and investment patterns.
China
Infrastructure development and heavy machinery manufacturing propel industrial turbocharger demand in China. The nation's dual carbon goals mandate higher efficiency and lower emissions from industrial equipment and power systems. Manufacturing hubs in the Yangtze River Delta actively integrate advanced turbocharging solutions for export and domestic markets.
United States
The expansion of data centers and distributed power systems generates consistent demand for turbocharged generator sets in the United States. US EPA's Tier 4 Final regulations compel engine manufacturers to adopt more efficient turbochargers for off-highway equipment. Major engine assembly plants in the Midwest integrate advanced air management systems into their product lines.
Germany
Commercial vehicle manufacturers and advanced engine developers in Germany seek high-performance turbochargers for efficiency and emissions compliance. The EU Green Deal framework directly influences the design and adoption of low-emission engine technologies. Automotive R&D centers in Bavaria focus on integrating electric and variable geometry turbochargers into future powertrain architectures.
India
Robust infrastructure development and a growing agricultural sector sustain demand for industrial turbochargers in India. The country's national emission standards for vehicles and industrial equipment drive the need for more efficient engine components. The Pune-Chennai automotive corridor sees significant activity in engine and component manufacturing for domestic and export markets.
Japan
Japan's marine engine and industrial equipment sectors require specialized turbochargers for high reliability and performance. METI industrial efficiency targets encourage the adoption of advanced technologies to reduce energy consumption across industries. Precision engineering firms in the Nagoya region develop cutting-edge turbocharger components for global applications.
Global Industrial Turbocharger Market Key Industry Players
Top-tier vendors anchor the premium segment, offering integrated engine and aftertreatment solutions, while specialized component manufacturers and aftermarket suppliers compete in cost-sensitive segments. The market structure features integrated engine solution providers, pure-play turbocharger specialists, and advanced technology innovators. Strategic partnerships for technology integration and continuous investment in electric turbocharger development are common competitive moves.
Among the integrated engine solution providers, Cummins Inc. exemplifies a strategy of leveraging in-house engine and aftertreatment expertise to serve diverse application bases. Mitsubishi Heavy Industries Ltd. occupies a strong position in high-output segments, specializing in large-frame turbochargers for marine and power generation. BorgWarner Inc. represents a key technology innovator, focusing on advanced solutions like electric turbochargers for commercial vehicles.
| Leading Market Players |
|---|
| IHI Corporation |
| Honeywell International Inc. |
| BorgWarner Inc. |
| Fengcheng Xindongli Turbocharger Co. Ltd. |
| Continental AG |
| Garrett Motion Inc. |
| Cummins Inc. |
| Bosch Mahle |
| Mitsubishi Heavy Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Specialized engineering talent in high-speed rotating machinery across Germany and Japan contributes to premium pricing for advanced turbochargers. This expertise creates clear pricing tiers for highly customized, performance-driven components versus mass-produced units.
Pricing Analysis
Premium pricing for short lead times characterizes the high-performance segment, while longer delivery schedules allow for cost-optimized solutions. Contract-based long-term offtake agreements dominate OEM procurement, ensuring stable pricing for large volumes. Quality grade and after-sales service differentiate pricing across tiers, particularly for complex Variable Geometry Turbochargers. Pricing softness reflects cost-sensitive aftermarket segments in regions like Europe, contrasting with OEMs prioritizing performance over initial component price.
Supply Chain Analysis
Single-source vulnerability sits with specialized foundries in China and Japan producing precision-cast turbine and compressor wheels. The market draws heavily from nickel-based superalloys and titanium aluminides, materials with concentrated global extraction and processing. Commodity price volatility for these critical inputs presents a significant structural supply chain risk. Distribution runs through direct channels to OEMs for new installations, complemented by specialized distributors serving the global aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial turbocharger market presents a consolidation play, as the technical complexity of electric turbochargers and stringent emissions regulations force out smaller, less capitalized component manufacturers.
For Market Incumbents:
Anticipate further investments in electric turbocharger development to maintain technological leadership against specialized innovators. Deepen vertical integration into advanced material production, such as titanium aluminides, to secure supply and manage costs. This mitigates the threat of supply chain bottlenecks and enhances control over critical component quality. Prioritize partnerships with engine OEMs for early design-in and validation of next-generation air management systems.
For New Entrants and Emerging Players:
Specialized component distributors offer a viable entry point for new entrants focusing on niche applications like hydrogen combustion engines. Target the aftermarket segment in Europe with cost-effective, certified remanufactured turbochargers for aging commercial vehicle fleets. A strong go-to-market angle involves offering robust, easy-to-integrate solutions for smaller industrial engine manufacturers. Focus on specific regional emission compliance gaps where established players are slower to adapt.
For Investors and Strategic Acquirers:
Re-rating potential sits with pure-play technology innovators specializing in electric turbochargers given the accelerating transition towards advanced air management systems. Long-term viability rests on companies with strong intellectual property in variable geometry and electric-assisted designs. Acquisition targets should include firms with proven expertise in ECU integration and power electronics for commercial vehicles. The signal to watch is OEM commitments to specific electric turbocharger platforms for future engine programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Advanced Electric Turbochargers | BorgWarner Inc. seeks to capture the commercial vehicle segment's demand for superior transient response and low-end torque. |
| Expand Remanufacturing Operations in Europe | Aftermarket suppliers can leverage aging European commercial vehicle fleets for sustainable service revenue streams. |
| Invest in Hydrogen Combustion Engine Turbocharging | Mitsubishi Heavy Industries Ltd. can adapt large-frame turbochargers for new H2-ICE applications with different air-to-fuel ratios. |
| Strengthen ECU Integration Capabilities | OEMs like Cummins Inc. require seamless integration of advanced turbochargers with existing engine control systems. |
| Secure Critical Material Supply Agreements | Manufacturers mitigate volatility in nickel-based superalloy prices, ensuring stability for high-efficiency Variable Geometry Turbochargers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with industry stakeholders. Primary research encompassed discussions with OEM procurement leads, aftermarket service managers, engine design engineers, and fleet operators. Secondary sources included US EPA reports, EU Green Deal policy documents, China's MEE publications, and company annual reports. This approach facilitated a robust bottom-up and top-down triangulation of market size and growth drivers.
Data-stream reconciliation involved cross-referencing demand-side indicators with supply-side capacity additions over the projection horizon. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional demand patterns. Compound Annual Growth Rates were derived from historical trends, projected technology adoption curves, and regulatory impact assessments. Key forecast inputs included infrastructure development spending in China and data center expansion rates in the United States.
Caveats apply where unforeseen shifts in global emissions standards or raw material supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding technological advancements and economic stability across key industrial sectors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Tappet Market
Powertrain
Europe Electro Hydraulic Power Steering Market
Powertrain
Automotive Engine Market
Powertrain
Drive Mode-Linked Powertrain Actuator Systems Market
Powertrain
Global Powertrain Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Automatic Transmission Solenoid Pack Market
Powertrain
Diesel Engine Catalyst Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Iridium Spark Plug Market
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Torque Converter Market
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Reciprocating Engine Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Exhaust Flexible Couplings Market