
 Racing Clutches Market | 2026-2036
Racing Clutches Market Size, Share, and Industry Trends Forecast 2026-2036
Racing Clutches Market Insights
Aftermarket service revenue is reshaping margin distribution across the racing clutches value chain, pulling profitability from unit sales toward rebuild kits and trackside support contracts. Tilton Engineering leverages its California manufacturing base to dominate professional motorsport supply relationships. Spec Clutch anchors the enthusiast tier through direct-to-consumer distribution channels. Schaeffler North America (LuK) competes on OE-derived technology transfer into racing-spec friction materials.
Racing clutches are torque-transfer devices engineered to withstand repeated high-load engagements at rotational speeds exceeding 10,000 RPM, utilizing sintered metallic or carbon-ceramic friction surfaces bolted to lightweight aluminum or titanium cover assemblies for competition vehicles. The primary purpose is to deliver instantaneous power transfer with minimal rotational inertia while tolerating thermal cycling that would degrade standard automotive clutch components. Multi-disc configurations command the premium tier due to their torque density advantage in drag and circuit applications, while organic friction materials retain volume leadership in the enthusiast segment where cost sensitivity constrains specification. Carbon friction surfaces represent the fastest-growing material category as professional teams prioritize thermal stability and reduced rotating mass.
FIA technical regulations and SFI Foundation certification standards govern friction-material specifications and safety testing protocols for competition clutches in sanctioned events. EPA emissions frameworks indirectly shape aftermarket demand as street-driven track cars require compliant materials that bridge road-legal and racing performance thresholds. Stakeholders must monitor evolving sanctioning-body technical bulletins and material-certification timelines to align R&D investment with specification windows.
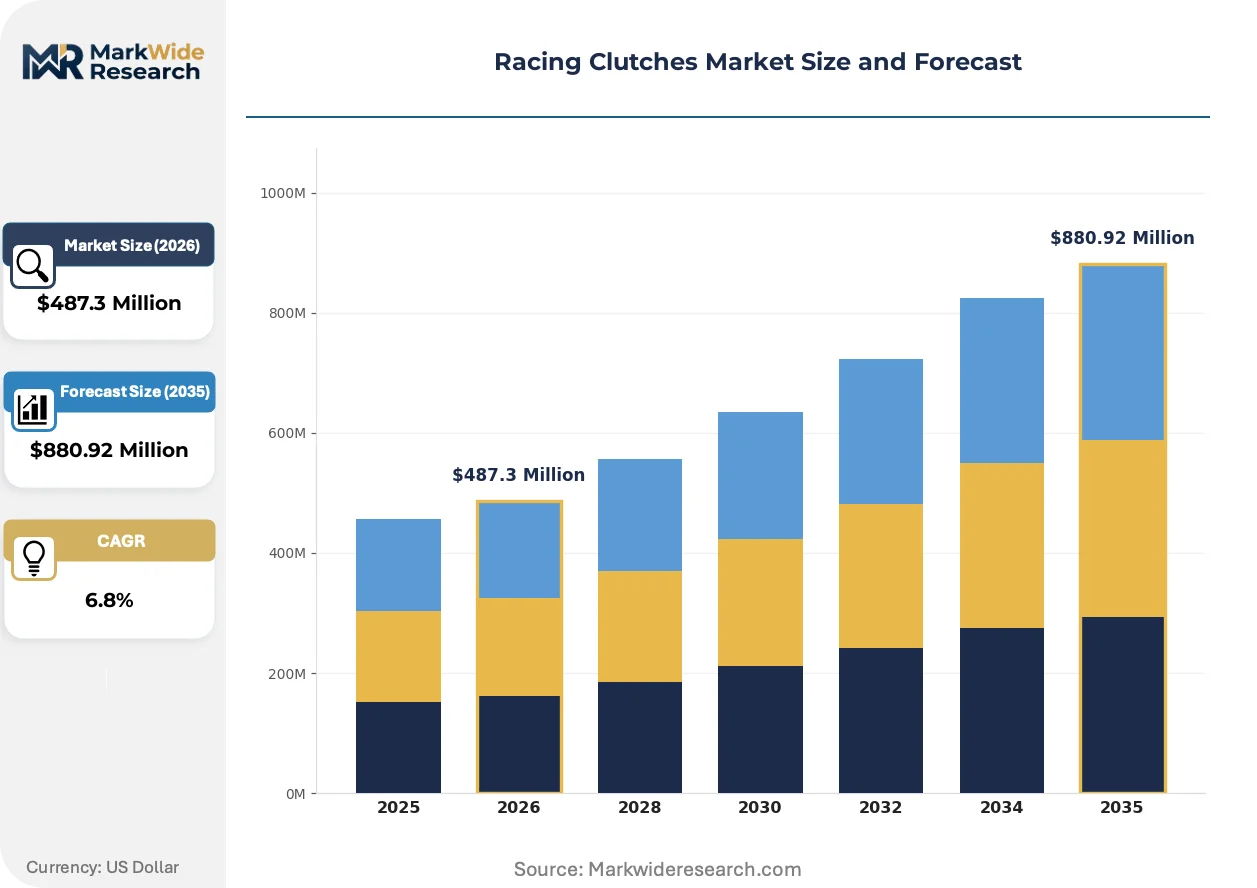
Market Dynamics
FIA technical regulations tightening friction-material specifications are compressing specification cycles and forcing teams toward carbon-ceramic multi-disc architectures that thermal-cycle more efficiently than organic alternatives.
Growth Catalysts
- SFI Foundation certification standards:Mandatory safety testing protocols for professional drag and circuit racing create recurring demand for certified friction-material replacements across North American sanctioning bodies.
- Carbon-ceramic friction surfaces:Professional motorsport teams prioritize thermal stability and reduced rotating mass, accelerating procurement of multi-disc configurations that tolerate repeated high-load engagements.
- NHRA specification cycles:The sanctioning body's technical bulletins drive synchronized replacement demand for professional-grade clutch assemblies among top-tier drag racing teams.
Market Restraints
- Raw material cost volatility:Titanium cover assemblies and sintered metallic friction substrates face price pressure from aerospace and defense procurement competition.
- Supplier concentration risk:Specialized carbon-weave manufacturing for racing friction materials concentrates among a limited number of California and Ohio-based producers.
- Technical limitation:Carbon-ceramic surfaces require precise bedding protocols that amateur installers frequently mishandle, elevating warranty exposure for direct-to-consumer channels.
Strategic Opportunities
- Enthusiast segment underpenetration:Weekend track-day drivers in Germany and the United Kingdom represent an addressable cohort seeking road-legal friction materials that bridge compliant street use and circuit performance.
- Rebuild kit channel innovation:Trackside support contracts and subscription-based maintenance programs capture margin from unit sales while locking in recurring revenue from professional teams.
- EPA emissions frameworks:Street-driven track cars require compliant materials, creating specification demand for friction products certified under dual-use road-legal and racing performance thresholds.
Industry Challenges
- Specialized technician scarcity:Multi-disc carbon system installation and bedding requires expertise that traditional automotive service bays rarely possess, constraining aftermarket expansion.
- Certification timeline compression:FIA technical bulletins and SFI recertification windows demand R&D cycles that outpace smaller friction-material suppliers' laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Racing Clutches Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single Disc, Multi Disc, Carbon, Organic Application: Drag Racing, Circuit Racing, Rally Racing, Off-Road Racing Material: Aluminum, Steel, Composite, Titanium End User: Professional Racers, Enthusiasts, Racing Teams, Aftermarket Providers |
| Companies Covered | Spec Clutch, Tilton Engineering, Advanced Clutch Technology (ACT), Competition Clutch, Quarter Master, Clutch Masters, Ogura Racing Clutch (ORC), Schaeffler North America (LuK), McLeod Racing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Racing Clutches Market Trends and Innovations
Friction-material engineering is migrating toward thermal-management architectures that prioritize heat dissipation over raw torque capacity, reshaping how professional teams evaluate clutch system lifecycle costs.
Carbon-ceramic friction surfaces are migrating from aerospace-derived formulations toward motorsport-optimized weave densities that reduce rotating mass while maintaining engagement consistency across temperature bands. Top-tier circuit and drag teams in the United States and Germany have adopted these configurations for the 2024-2025 specification window. The technology is migrating from premium professional tiers into upper enthusiast segments as rebuild kit economics improve.
EPA emissions frameworks are indirectly governing aftermarket friction-material composition by requiring street-driven track cars to maintain compliant formulations. California Air Resources Board enforcement actions against non-compliant street conversions have elevated demand for dual-certified organic-ceramic hybrid materials. Enthusiast distributors in the United States now stock these formulations as default recommendations for dual-use vehicles.
Trackside support contracts are displacing traditional unit-sales relationships among professional motorsport teams seeking to outsource clutch system lifecycle management. California-based manufacturers dominate this channel through captive service crews at major North American circuits. The model concentrates profitability in recurring maintenance revenue rather than initial hardware procurement.
Racing Clutches Market Segmentation
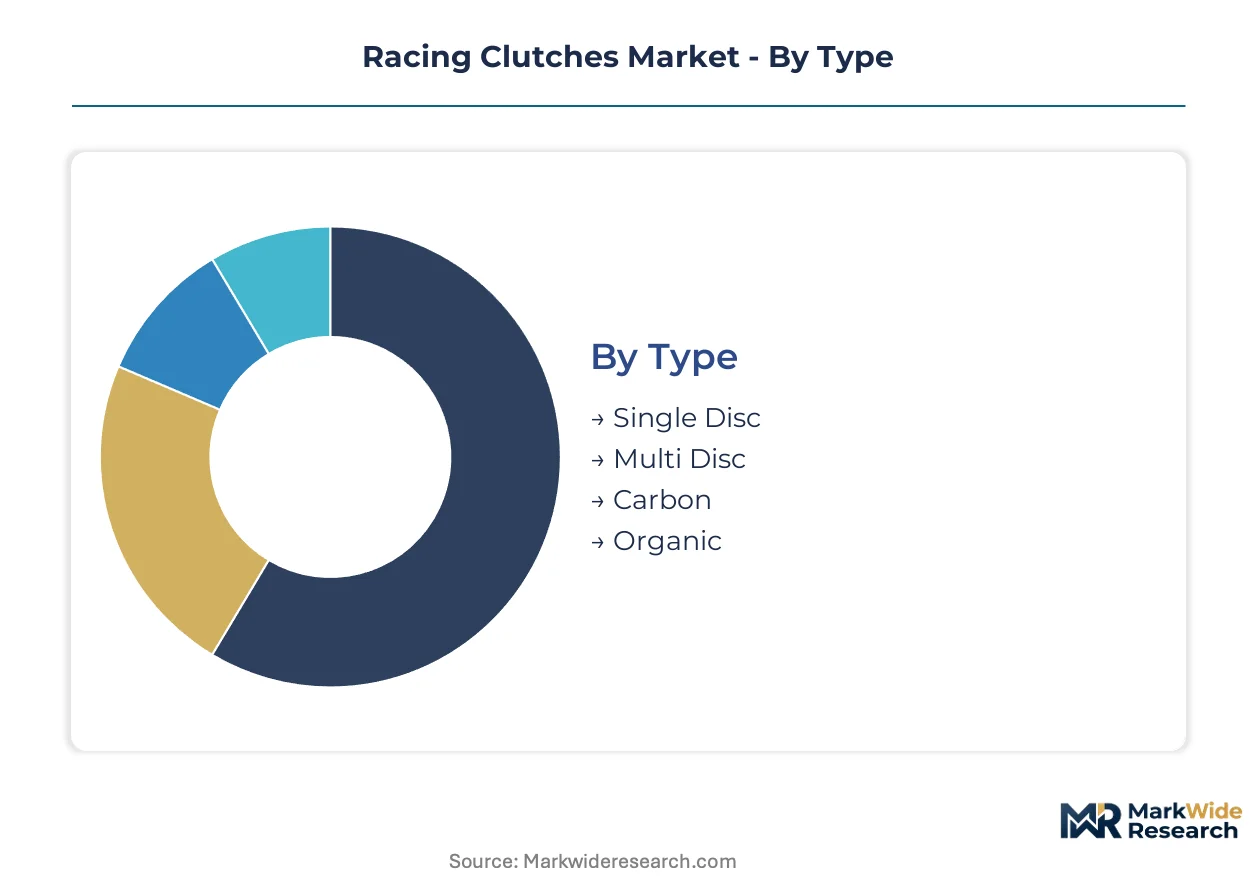
Racing clutch procurement splits sharply between sanctioned competition and enthusiast channels, with specification requirements diverging on thermal tolerance, bedding protocols, and rebuild economics. Understanding these fracture lines clarifies where margin pools concentrate and which technology migrations reshape supplier positioning.
Type:
Cost tier determines specification depth across amateur and professional deployment, separating weekend track-day budgets from top-tier motorsport procurement cycles.
- Multi Disc:Stacked friction plate architectures deliver torque density advantages for repeated high-load engagements in drag and circuit applications. Professional teams in the United States specify these configurations under NHRA and NASCAR technical bulletins that prioritize thermal cycling efficiency.
- Carbon:Carbon-ceramic friction surfaces reduce rotating mass while maintaining engagement consistency across temperature bands. Demand concentrates among FIA-sanctioned circuit teams in Germany and the United Kingdom where technical regulations tighten friction-material specifications.
- Single Disc:Simpler architectures serve cost-constrained enthusiast segments with organic friction materials and aluminum cover assemblies.
- Organic:Conventional friction compounds retain volume leadership in street-legal track-day applications where EPA emissions frameworks govern material composition.
Single Disc and Organic variants command the established base. The steepest expansion runs through Carbon configurations as professional teams prioritize thermal stability.
Application:
Discipline-specific load profiles dictate clutch architecture selection, with sanctioning-body technical regulations creating synchronized replacement demand cycles.
- Drag Racing:Repeated launch engagements at maximum torque demand multi-disc carbon systems with rapid heat dissipation. NHRA specification cycles in the United States drive concentrated procurement among professional teams.
- Circuit Racing:Sustained high-RPM operation with frequent gear changes requires thermal-management architectures that prioritize heat dissipation over raw torque capacity. FIA technical regulations in Europe compress specification windows for friction-material compliance.
- Rally Racing:Variable terrain engagement patterns favor robust cover assemblies that tolerate shock loading across gravel and tarmac surfaces.
- Off-Road Racing:Contaminated operating environments and irregular traction profiles shape friction-material selection toward sealed bearing designs and debris-tolerant configurations.
Drag Racing anchors professional procurement volumes. Circuit Racing climbs the fastest as thermal-management engineering migrates from aerospace-derived formulations toward motorsport-optimized weave densities.
Material:
Cover assembly composition directly determines rotating mass, thermal conductivity, and unit economics across specification tiers.
- Titanium:Premium cover assemblies deliver maximum mass reduction for professional motorsport applications where rotational inertia constrains acceleration performance. Aerospace and defense procurement competition in the United States creates raw material cost volatility.
- Aluminum:Mid-tier specifications balance weight reduction with fabrication cost for enthusiast and semi-professional deployment.
- Composite:Emerging carbon-fiber reinforced formulations target niche applications seeking mass reduction without titanium price exposure.
- Steel:Conventional ferrous covers retain position in budget-conscious segments and heavy-duty off-road configurations where durability outweighs mass considerations.
Steel covers retain the volume base. Titanium gains share fastest as professional teams outsource clutch system lifecycle management through trackside support contracts.
End User:
Customer type fractures the value chain between direct procurement by professional organizations and distributed aftermarket channels serving amateur participants.
- Professional Racers:Individual competitors operating under sanctioning-body licenses demand SFI Foundation-certified configurations with documented thermal cycling performance. California-based manufacturers dominate supply relationships through captive service crews at major North American circuits.
- Racing Teams:Organized motorsport organizations with dedicated technical staff procure multi-disc carbon systems through specification cycles synchronized to FIA technical bulletins.
- Enthusiasts:Weekend track-day participants in Germany and the United Kingdom seek road-legal friction materials bridging compliant street use and circuit performance.
- Aftermarket Providers:Distributors and rebuild specialists capture margin from unit sales through subscription-based maintenance programs and trackside support contracts.
Aftermarket Providers command the established service revenue base. Racing Teams drive the steepest specification upgrade trajectory as rebuild kit economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Professional motorsport procurement concentrates in sanctioning-body jurisdictions with intensive specification cycles, while enthusiast demand clusters in countries with dense track-day infrastructure and road-legal compliance frameworks.
United States
NHRA and NASCAR technical bulletins drive synchronized replacement demand for multi-disc carbon systems among professional drag and circuit teams. EPA emissions frameworks and California Air Resources Board enforcement actions shape friction-material composition requirements for street-driven track cars. California-based manufacturers cluster around Los Angeles and San Diego metro areas, supplying captive service crews at major North American circuits.
Germany
FIA-sanctioned circuit teams prioritize thermal-management architectures that tolerate sustained high-RPM operation with frequent gear changes. REACH regulations and EU technical standards govern friction-material composition and safety certification protocols. Industrial concentration centers on Baden-Württemberg and Bavaria, where motorsport engineering clusters support professional racing organizations.
United Kingdom
Weekend track-day participants seek road-legal friction materials bridging compliant street use and circuit performance. DVSA and Motorsport UK regulations coordinate technical compliance for dual-use vehicles. Motorsport Valley clusters in Oxfordshire and Northamptonshire host engineering operations serving both professional teams and aftermarket distributors.
Japan
Domestic circuit racing and time-attack culture sustains demand for lightweight clutch configurations with reduced rotational inertia. JIS standards and Japan Automobile Federation technical regulations specify friction-material certification requirements. Industrial activity concentrates in Aichi Prefecture and the Kanto region, where automotive component suppliers maintain proximity to motorsport engineering centers.
Australia
Off-road racing and rally disciplines favor robust cover assemblies tolerating shock loading across variable terrain. Department of Infrastructure and Regional Development frameworks govern vehicle modification compliance for competition use. Manufacturing and distribution activity clusters in Victoria and New South Wales, serving both domestic sanctioning bodies and Asia-Pacific export channels.
Racing Clutches Market Competitive Landscape
Capability concentration sits with specialized carbon-weave manufacturers; scale advantage sits with diversified automotive component suppliers. The market structures around three tiers: premium professional motorsport specialists, mid-tier enthusiast-focused fabricators, and diversified industrial conglomerates with racing divisions. Dominant competitive moves include backward integration into friction-material substrate production and geographic expansion through trackside service network establishment.
Within the premium professional tier, Tilton Engineering and Spec Clutch occupy positions exemplifying divergent channel strategies—direct motorsport supply relationships versus enthusiast direct-to-consumer distribution. Schaeffler North America represents the diversified industrial archetype, leveraging OE-derived technology transfer into racing-spec applications. These three anchors illustrate how supplier positioning fractures across procurement channel specialization rather than product differentiation alone.
| Leading Market Players |
|---|
| Spec Clutch |
| Tilton Engineering |
| Advanced Clutch Technology (ACT) |
| Competition Clutch |
| Quarter Master |
| Clutch Masters |
| Ogura Racing Clutch (ORC) |
| Schaeffler North America (LuK) |
| McLeod Racing |
| Others |
Pricing and Supply Chain Analysis
California carbon-weave manufacturers concentrate specialized friction-material substrate production, anchoring margin pools in trackside service contracts and rebuild kit channels rather than unit sales. Aerospace and defense procurement competition for titanium cover assemblies compresses mid-tier supplier margins while premium professional tiers absorb cost pass-through via subscription-based maintenance programs.
Pricing Analysis
Long-term offtake agreements dominate professional motorsport procurement, with NHRA and NASCAR teams locking multi-season supply contracts that synchronize to technical bulletin cycles. Three-tier pricing structure across premium carbon-ceramic, mid-grade sintered metallic, and economy organic formulations differentiates by SFI Foundation certification grade and thermal cycling performance. Pricing pressure stems from raw material cost volatility in titanium and carbon fiber, with amateur enthusiasts exhibiting highest price sensitivity and professional racing teams showing inelastic demand for certified configurations.
Supply Chain Analysis
Extended payment terms from California and Ohio-based carbon-weave producers to motorsport fabricators concentrate working capital risk in specialized substrate manufacturing. Supply draws from United States, Germany, and Japan for titanium cover assemblies, carbon-ceramic friction surfaces, and precision-machined aluminum components. Single-source vulnerability in California carbon-weave manufacturing creates geographic concentration exposure. Distribution runs through captive service crews at major North American circuits for professional tiers, while enthusiast channels rely on direct-to-consumer e-commerce and specialty automotive retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as EPA emissions frameworks and FIA technical regulations split demand between road-legal dual-use vehicles and pure competition specifications, creating distinct procurement channels with diverging margin structures.
For Market Incumbents: Pre-empt specialist technician scarcity by embedding certified installation crews within trackside support contracts, locking professional teams into recurring rebuild kit revenue. Backward integration into carbon-weave substrate production defends margin position against California supplier concentration risk. Prioritize SFI Foundation certification investment to compress specification windows for emerging competitors lacking laboratory capacity. For New Entrants and Emerging Players: Germany and the United Kingdom weekend track-day participants represent underpenetrated white-space for road-legal organic-ceramic hybrid materials bridging EPA compliance and circuit performance. Target enthusiast direct-to-consumer channels with subscription-based bedding protocol guidance and warranty-backed installation partnerships. Pursue dual-certification under REACH and California Air Resources Board frameworks to unlock cross-border distribution economies. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated carbon-weave specialists with captive trackside service networks, capturing recurring maintenance revenue rather than transactional hardware sales. Five-to-ten year viability favors suppliers controlling both friction-material substrate production and professional motorsport relationships. Monitor FIA technical bulletin cadence as inflection signal for specification-driven replacement demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon-Weave Manufacturing | Captive supply of friction-material substrates insulates margin from aerospace titanium competition. |
| Trackside Service Network Expansion | California-based captive crews at NHRA and NASCAR circuits lock professional teams into recurring revenue. |
| Dual-Certification Investment | SFI Foundation and FIA compliance opens synchronized specification windows across North America and Europe. |
| Subscription-Based Rebuild Programs | Maintenance contracts displace unit sales, concentrating profitability in enthusiast and professional channels. |
| Specialized Technician Training Partnerships | Certified installation networks address bedding protocol mishandling that elevates warranty exposure. |
Research Methodology
Initial hypotheses were tested against primary input from motorsport engineering directors, sanctioning-body technical officials, aftermarket distribution managers, and carbon-weave manufacturing specialists and refined through secondary validation. Triangulation combined SEC filings from diversified automotive suppliers, SFI Foundation certification databases, FIA technical bulletin archives, and customs trade records for titanium and carbon fiber imports. Bottom-up segment sizing across clutch type, material, and end-user categories was cross-checked against top-down market aggregation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling procurement cycles synchronized to NHRA and FIA technical bulletins alongside enthusiast replacement patterns. Segmentation dimensions included clutch architecture, friction-material composition, cover assembly material, racing discipline, and customer type. CAGRs were derived from fitted growth curves applied to professional motorsport specification cycles and aftermarket penetration trajectories in Germany and the United Kingdom. Industry-specific inputs incorporated SFI recertification timelines and EPA emissions framework enforcement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated carbon-weave specialists or diversified automotive conglomerates would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
EGR and Emissions Control Actuator Systems Market
Powertrain
Power Liftgate for Automotive Market
Powertrain
Automotive Variable Discharge Oil Pump Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Automotive Clutch Rotor Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
Global Industrial Turbocharger Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Reciprocating Engine Market
Powertrain
Automotive Slipper Clutch Market
Powertrain
Clutch Hub Puller Market
Powertrain
Global Industrial Engine Market
Powertrain
Global Automotive Powertrain Systems Market
Powertrain
Automotive Fuel Injector Market