
 Automotive Crank Trigger Market | 2026-2036
Automotive Crank Trigger Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Crank Trigger Market Outlook
Multi-source procurement among Tier-1 ignition suppliers is consolidating as OEMs reduce vendor counts to secure electromagnetic compatibility guarantees. Denso Corporation leverages its captive semiconductor fabrication to control sensor calibration consistency across crank trigger lines. Holley Performance Products anchors the North American aftermarket through dedicated racing and street-performance distribution channels. COMP Performance Group differentiates via specialized reluctor wheel geometries for small-block and LS engine architectures.
An automotive crank trigger is a position-sensing device that detects crankshaft angular velocity and top-dead-center reference points, typically employing variable reluctance, Hall-effect, or optical detection principles with air gaps specified between 0.25 mm and 1.5 mm depending on target wheel geometry. Its primary function is to deliver phase-accurate timing signals to engine control modules, enabling precise fuel injection sequencing, ignition coil firing, and misfire diagnostics across internal combustion architectures. Magnetic sensors dominate OEM volume programs due to thermal resilience beyond 150°C operating environments, while optical variants retain niche placement in racing applications where absolute positional accuracy outweighs contamination vulnerability. Digital signal conditioning technology is displacing analog front-end designs as automakers mandate SENT protocol outputs for improved noise immunity and diagnostic depth.
EPA emissions certification requirements and NHTSA onboard diagnostic mandates compel crank trigger manufacturers to validate sensor accuracy across full temperature and vibration envelopes before platform approval. EMA and EU Green Deal carbon intensity benchmarks are extending sensor lifecycle durability requirements, forcing material upgrades in magnet wire insulation and connector sealing. China's MIIT fuel consumption regulations similarly tighten crank position measurement tolerances for domestic gasoline engine production. Stakeholders must monitor how hybrid powertrain integration reshapes sensor count per vehicle and whether 48V mild-hybrid architectures sustain dedicated crank trigger demand or consolidate position sensing into integrated starter-generator modules.
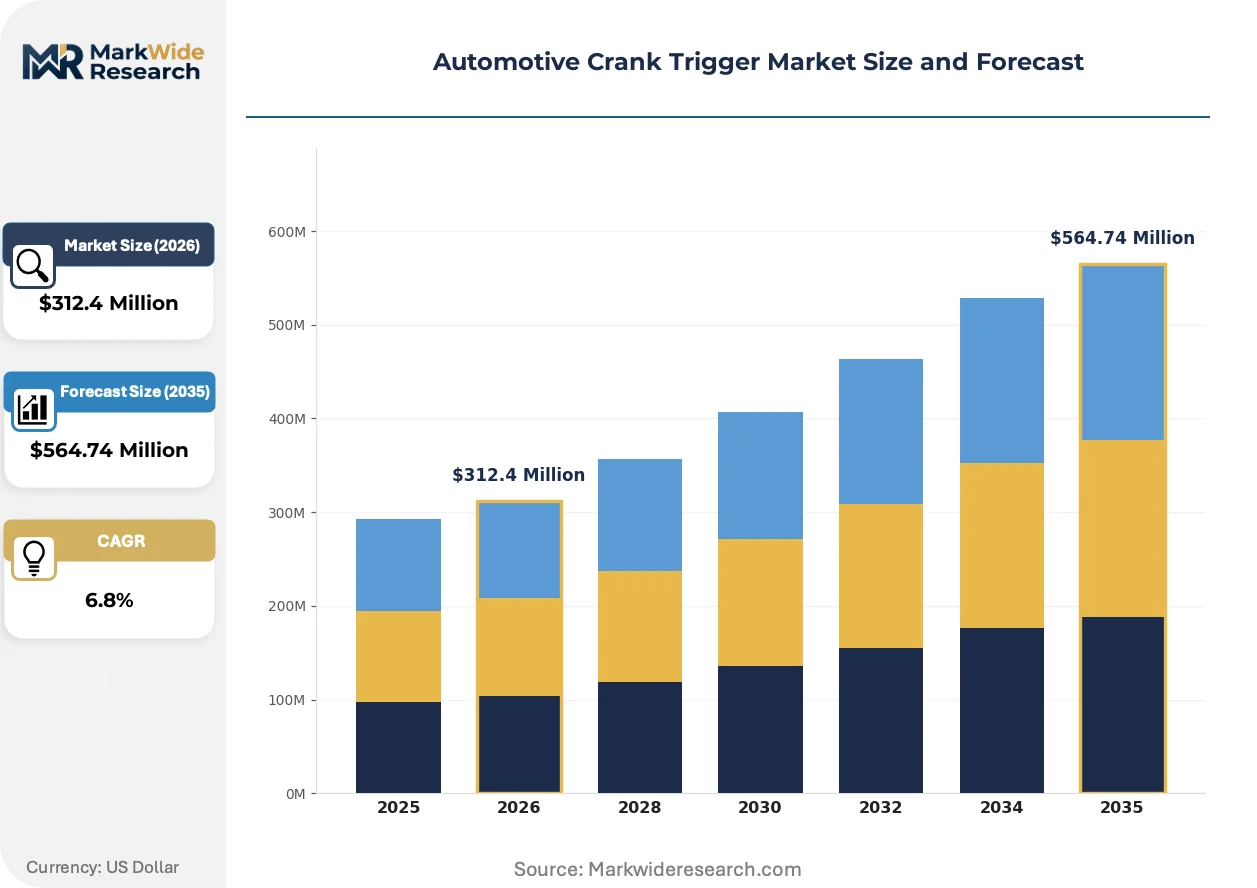
Market Dynamics
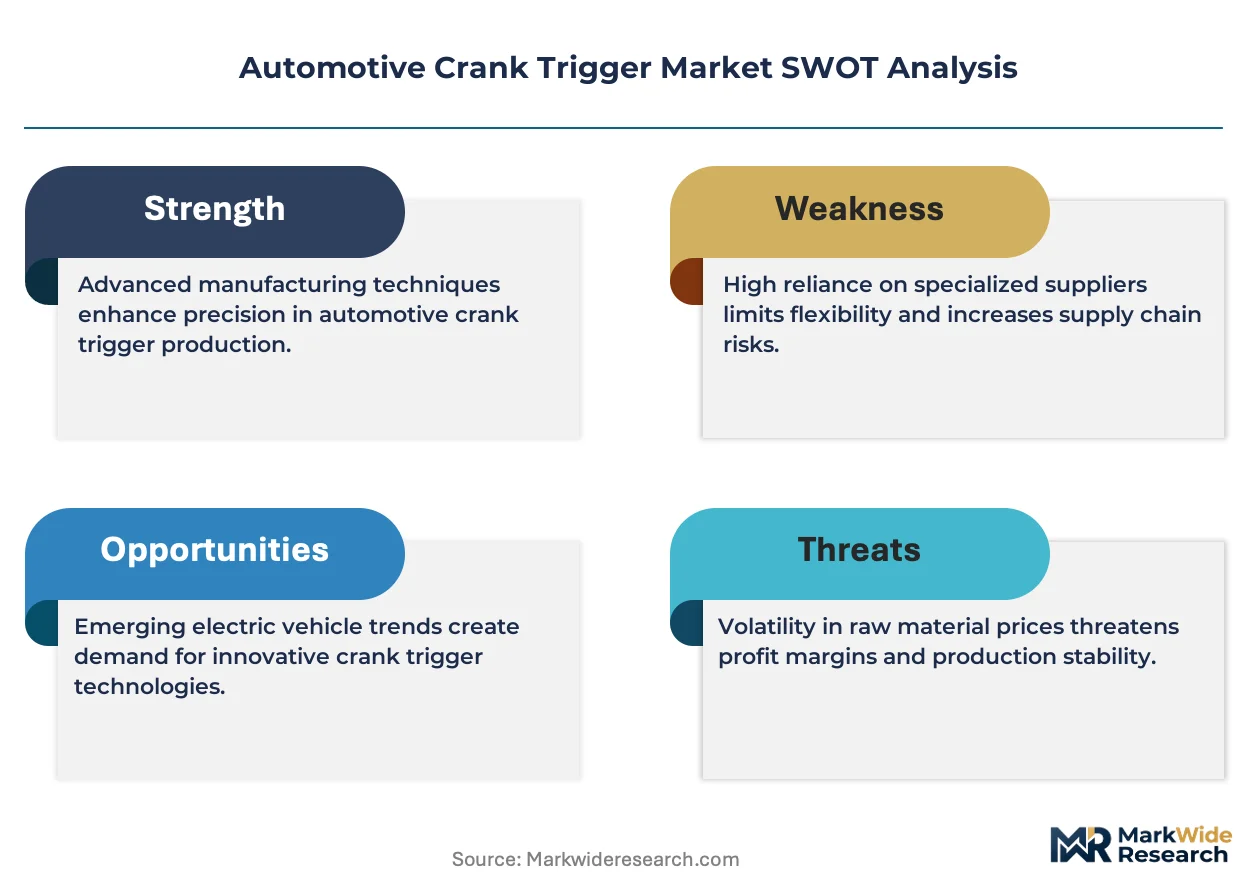
Sensor calibration protocols are tightening across gasoline powertrains as EPA tailpipe standards and Euro 7 precursor discussions force OEMs to validate crank position accuracy within tighter angular tolerances, compressing supplier qualification timelines and consolidating procurement toward vertically integrated semiconductor fabricators.
Growth Catalysts
- Emissions stringency:EPA certification requirements and NHTSA onboard diagnostic mandates compel automakers to replace aging magnetic sensors with digital SENT-protocol variants capable of sub-degree positional accuracy across full thermal envelopes.
- Aftermarket performance tuning:Motorsport builders in the United States and Germany are retrofitting street vehicles with optical crank triggers for absolute positional precision, expanding addressable sensor demand beyond factory-installed volumes.
- Hybrid powertrain proliferation:48V mild-hybrid architectures sustain dedicated crank trigger demand for internal combustion synchronization even as integrated starter-generator modules absorb some position-sensing functions.
Market Restraints
- Semiconductor supply concentration:Captive silicon fabrication at Denso Corporation and Bosch limits second-source availability for Hall-effect sensor dies, exposing Tier-1 suppliers to allocation risk during foundry capacity crunches.
- Rare earth magnet cost volatility:Neodymium and samarium cobalt pricing swings directly impact variable reluctance sensor manufacturing economics, compressing margins on high-temperature magnetic variants specified above 150°C.
- Optical sensor contamination vulnerability:Dust intrusion and oil mist degradation limit optical crank trigger deployment to enclosed racing environments, excluding this high-accuracy technology from mass-market OEM programs.
Strategic Opportunities
- China domestic OEM sensor programs:MIIT fuel consumption regulations are tightening crank position measurement tolerances for domestic gasoline engine production, creating localized sourcing requirements that favor regional suppliers with GB-standard certification.
- Digital signal conditioning convergence:The displacement of analog front-end designs by SENT protocol outputs enables diagnostic depth improvements that differentiate premium sensor tiers from commodity magnetic alternatives.
- Reluctor wheel geometry specialization:Small-block and LS engine architectures in North American performance segments reward suppliers offering application-specific target wheel designs with reduced air gap sensitivity.
Industry Challenges
- Electromagnetic compatibility validation:OEM consolidation of vendor counts demands guaranteed EMC performance across crank trigger lines, requiring capital-intensive anechoic chamber testing and shielding redesign cycles.
- Material durability upgrades:EU Green Deal carbon intensity benchmarks extend sensor lifecycle requirements, forcing magnet wire insulation and connector sealing material transitions that disrupt established supply contracts.
- Hybrid architecture sensor count uncertainty:Powertrain electrification trajectories vary by OEM, complicating volume forecasting for dedicated crank triggers versus integrated position-sensing modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Crank Trigger Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibration Sensors, Optical Sensors, Magnetic Sensors, Infrared Sensors End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: Onboard, Offboard, Modular, Integrated Technology: Analog, Digital, Hybrid, Others |
| Companies Covered | Holley Performance Products, Chevrolet Performance, Mopar Performance, COMP Performance Group, Moroso Performance Products, MSD Ignition, Chongqing Guanglian Qingling Auto Parts, Wenzhou Baian Auto Parts, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Crank Trigger Market Strategic Shifts
Digital signal processing architectures are displacing analog conditioning circuits across crank trigger designs, enabling SENT protocol adoption that improves noise immunity while adding diagnostic telemetry for predictive maintenance algorithms.
Modular sensor packaging is modularizing crank trigger assemblies into separable magnetic sensing elements, connector housings, and conditioning electronics. Performance engine builders in Germany and the United States are adopting these configurations for rapid field serviceability. This modularity is compressing aftermarket replacement cycles while allowing OEMs to standardize electronic subassemblies across multiple engine architectures.
REACH substance restrictions and RoHS recast directives in Europe are accelerating magnet wire insulation material transitions away from traditional enamel coatings. Suppliers must validate alternative polymer formulations for thermal resilience beyond 150°C operating environments. The racing and street-performance aftermarket segments face the steepest reformulation timelines due to smaller batch qualification resources.
Direct sourcing from semiconductor fabricators is reshaping procurement patterns among Tier-1 ignition suppliers previously reliant on distributor channels. OEM electromagnetic compatibility guarantees now require traceable calibration consistency that only captive or closely audited foundry relationships can document. This pattern concentrates most visibly in Germany and Japan where automakers specify supplier audit depth in platform approval contracts.
Automotive Crank Trigger Market Segmentation
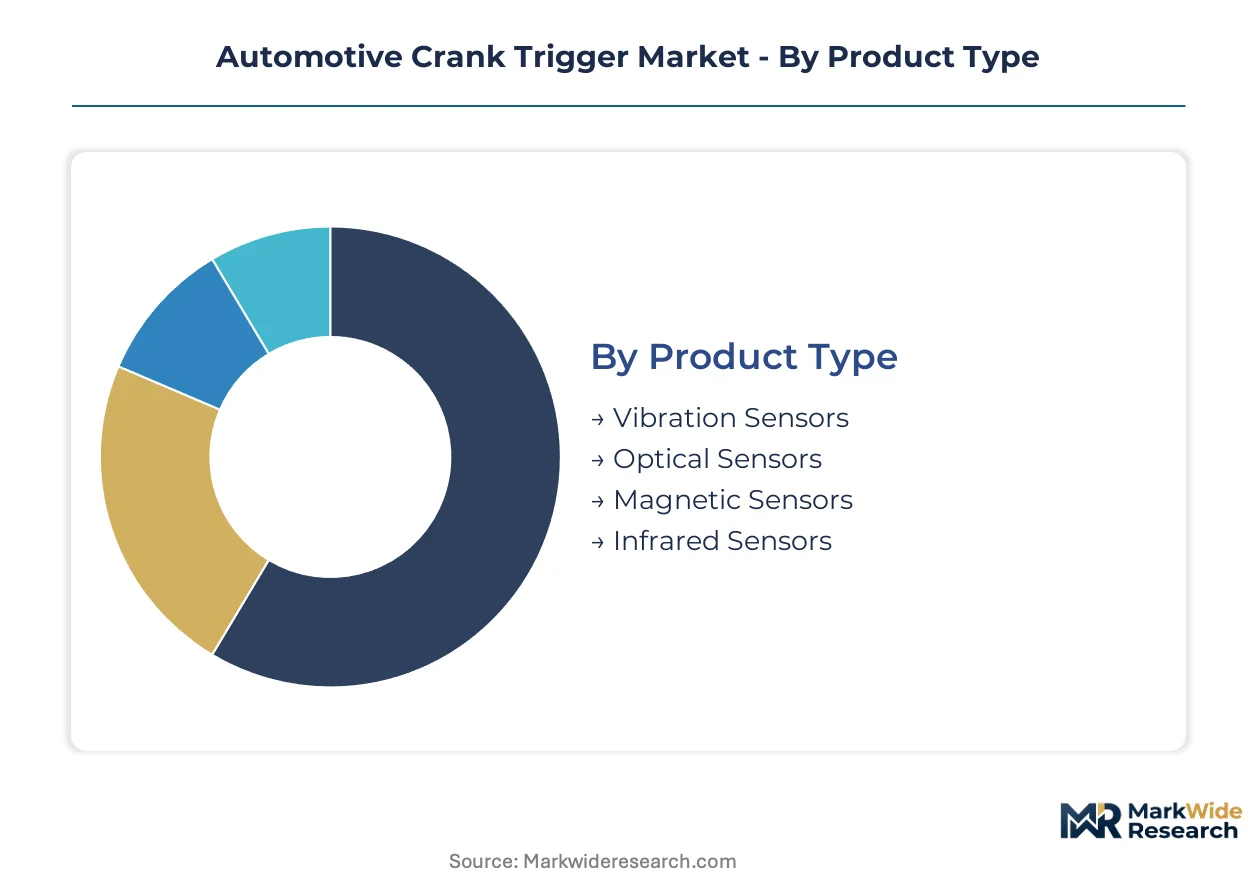
Crank trigger procurement patterns diverge sharply across product architectures and customer types. Supply concentration in magnetic sensing and digital signal conditioning creates tiered competitive dynamics that reshape how vendors prioritize R&D investment and qualification resources.
Product Type:
Magnetic and optical variants concentrate supplier capacity and technical differentiation, while vibration and infrared alternatives occupy specialized niches with fragmented sourcing.
- Magnetic Sensors:Variable reluctance and Hall-effect architectures dominate OEM volume programs with thermal resilience beyond 150°C. Denso Corporation and Bosch anchor supply through captive silicon fabrication, locking in calibration consistency for EPA-certified gasoline powertrains.
- Optical Sensors:Absolute positional accuracy drives demand among German and United States motorsport tuners retrofitting street vehicles, though contamination vulnerability from dust and oil mist restricts deployment to enclosed racing environments and excludes mass-market factory installation.
- Vibration Sensors:Piezoelectric elements detect crankshaft torsional oscillations for misfire diagnostics in heavy-duty commercial applications.
- Infrared Sensors:Non-contact thermal measurement variants serve prototype engine dyno installations requiring non-intrusive angular velocity tracking.
Today's leader: Magnetic Sensors. Tomorrow's challenger: Optical Sensors.
End User:
Customer type determines specification rigor, with OEMs and Tier-1 suppliers enforcing electromagnetic compatibility guarantees that aftermarket channels rarely replicate.
- OEMs:Platform approval contracts mandate SENT protocol outputs, full temperature envelope validation, and traceable semiconductor foundry audits. NHTSA onboard diagnostic mandates compress qualification timelines for domestic United States production.
- Tier-1 Suppliers:Ignition system integrators consolidate vendor counts to secure EMC performance guarantees, favoring vertically integrated sensor manufacturers with in-house calibration laboratories.
- Aftermarket Providers:Performance distributors like Holley Performance Products anchor North American racing and street-performance channels with rapid-turn inventory.
- Vehicle Assemblers:Contract manufacturing partners in China source GB-standard certified sensors under MIIT fuel consumption regulation compliance.
OEMs command specification authority. Aftermarket Providers expand most quickly.
Installation:
Packaging architecture determines serviceability economics and architectural flexibility across production and retrofit applications.
- Onboard:Fixed-mount sensors integrated into engine block castings dominate high-volume OEM programs with minimized air gap tolerance stack-up.
- Offboard:Remote-mounted configurations with extended wiring harnesses serve aftermarket retrofit applications requiring non-standard reluctor wheel placements.
- Modular:Separable magnetic sensing elements, connector housings, and conditioning electronics compress replacement cycles for German and United States performance builders prioritizing field serviceability.
- Integrated:Consolidated position-sensing modules within starter-generator units challenge dedicated crank trigger demand in 48V mild-hybrid architectures.
Modular formats gain share in aftermarket channels. Integrated solutions threaten standalone sensor counts.
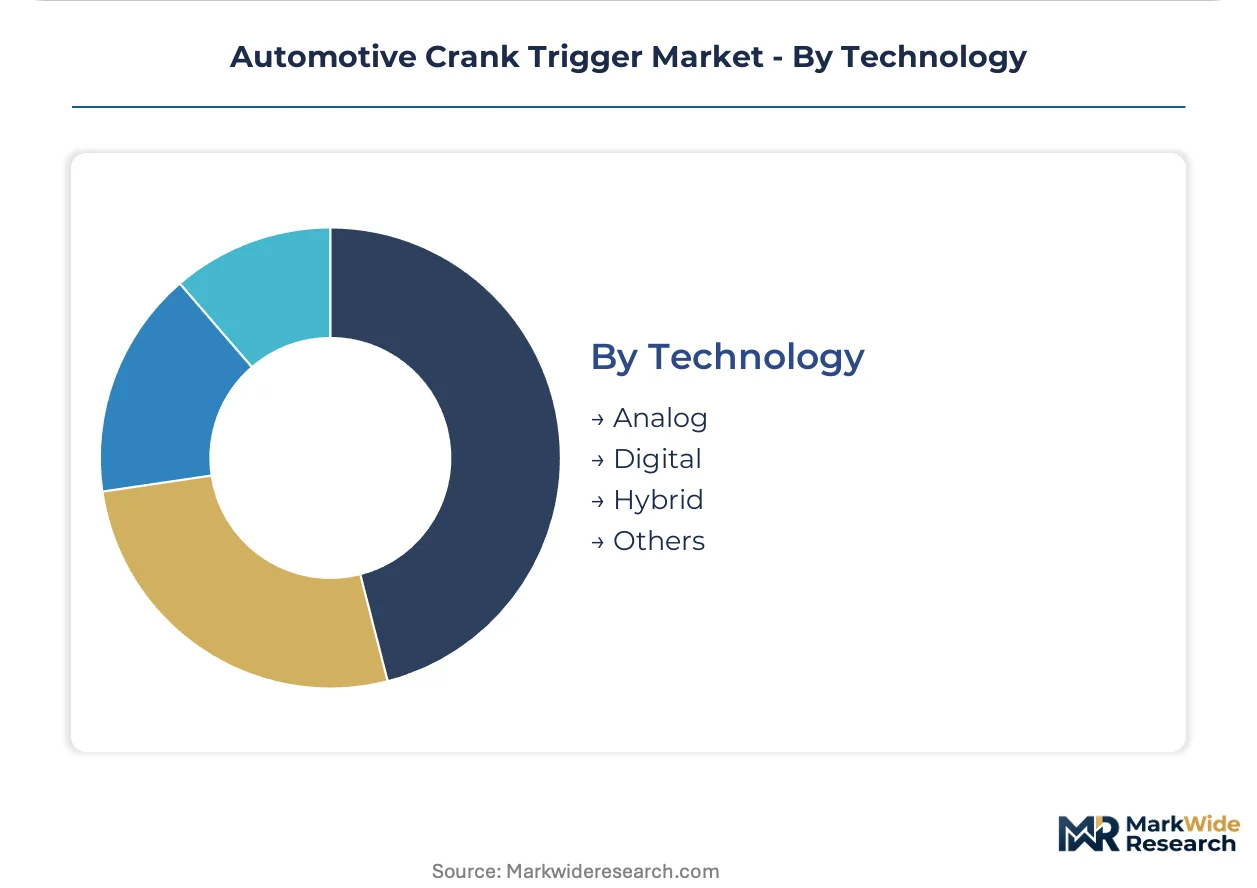
Technology:
Signal conditioning architecture separates premium tiers from commodity alternatives, with protocol migration reshaping component sourcing.
- Analog:Legacy voltage-output designs face displacement as automakers mandate improved noise immunity and diagnostic depth.
- Digital:SENT protocol outputs with embedded diagnostic telemetry differentiate premium sensor tiers and enable predictive maintenance algorithms across EPA-certified powertrains.
- Hybrid:Mixed-signal front-ends bridge analog sensor elements with digital conditioning for cost-optimized mid-market applications.
- Others:Emerging capacitive and magnetoresistive principles occupy research-phase evaluation at specialized automotive research institutes.
Digital dominates new platform approvals. Hybrid captures cost-sensitive transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Detroit-Windsor automotive corridor anchors sensor demand through concentrated OEM powertrain engineering and Tier-1 supplier clustering. Domestic OEM sensor programs in Michigan and Ontario overlap with high-performance aftermarket ecosystems across the Great Lakes basin. Regulatory divergence across major markets is fragmentating qualification protocols and compressing supplier consolidation timelines.
United States
EPA tailpipe standards and NHTSA onboard diagnostic mandates compel automakers to validate crank position accuracy within tighter angular tolerances. Domestic OEM sensor programs in Michigan concentrate procurement authority for gasoline powertrain certification. Holley Performance Products anchors the North American aftermarket through dedicated racing and street-performance distribution channels in Bowling Green and Nashville.
Germany
Euro 7 precursor discussions and EMA carbon intensity benchmarks are extending sensor lifecycle durability requirements. KBA type-approval protocols demand electromagnetic compatibility guarantees that consolidate vendor counts toward vertically integrated fabricators. Stuttgart and Munich host concentrated powertrain engineering centers where Denso Corporation leverages captive semiconductor fabrication for calibration consistency.
China
MIIT fuel consumption regulations tighten crank position measurement tolerances for domestic gasoline engine production. GB-standard certification creates localized sourcing requirements favoring regional suppliers. Chongqing and Wenzhou industrial clusters host domestic auto parts manufacturers serving both OEM sensor programs and export-oriented aftermarket channels.
Japan
METI fuel efficiency standards and JIS certification protocols drive precision ignition timing requirements across hybrid powertrain architectures. Nagoya and Tokyo metropolitan areas concentrate semiconductor fabrication capacity for Hall-effect sensor die production. Captive foundry relationships enable traceable calibration documentation required by platform approval contracts.
Automotive Crank Trigger Market Competitive Environment
Global majors compete with regional champions across semiconductor fabrication and electromagnetic compatibility validation capabilities. The supplier base concentrates around vertically integrated sensor manufacturers with in-house calibration laboratories and captive silicon production. Three archetypes dominate: captive semiconductor fabricators controlling die supply and calibration consistency; performance aftermarket specialists leveraging racing distribution channels; and domestic Chinese suppliers capturing GB-standard certification requirements. Competitive dynamics center on vendor count consolidation for EMC guarantees and direct foundry relationships to secure allocation during capacity crunches.
Among Japanese captive fabricators, Denso Corporation occupies a position exemplifying vertical integration into semiconductor die production. Within the North American performance aftermarket, Holley Performance Products and COMP Performance Group represent archetypes of specialized distribution and application-specific reluctor wheel geometries. Chinese domestic suppliers including Chongqing Guanglian Qingling Auto Parts and Wenzhou Baian Auto Parts sit within the regional certification tier serving MIIT-compliant gasoline engine production.
| Leading Market Players |
|---|
| Holley Performance Products |
| Chevrolet Performance |
| Mopar Performance |
| COMP Performance Group |
| Moroso Performance Products |
| MSD Ignition |
| Chongqing Guanglian Qingling Auto Parts |
| Wenzhou Baian Auto Parts |
| Denso Corporation |
| Others |
Value Chain & Pricing Dynamics
OEM vendor-count consolidation for electromagnetic compatibility guarantees is compressing supplier margins and forcing Tier-1 ignition manufacturers toward direct semiconductor foundry relationships that alter procurement economics across magnetic and optical sensor lines.
Pricing Analysis
Neodymium and samarium cobalt magnet pricing volatility passes directly through variable reluctance sensor manufacturing costs, compressing margins on high-temperature variants specified above 150°C. Pricing stratifies across premium digital SENT-protocol tiers, mid-market hybrid signal conditioning, and economy analog outputs, with EPA-certified gasoline powertrain programs commanding certification premiums. Cost compression in commodity magnetic segments is intensifying because rare earth supply concentration limits second-source alternatives. Aftermarket performance tuners exhibit lowest price sensitivity due to absolute positional accuracy requirements, while domestic Chinese OEMs sourcing GB-standard sensors face tightest procurement constraints.
Supply Chain Analysis
Cross-border freight costs for precision-machined reluctor wheel castings and semiconductor die shipments from Japan and Germany are amplifying landed cost differentials for North American sensor assemblers. Captive silicon fabrication concentrates in Japan and Germany, while magnetic core winding and final sensor packaging clusters in China and Mexico. The supply chain draws from neodymium magnet processors, Hall-effect sensor die foundries, and polymer sealant formulators. Single-source vulnerability in semiconductor allocation during foundry capacity crunches poses structural risk. Distribution runs through Tier-1 ignition system integrators consolidating toward vertically integrated manufacturers with in-house calibration laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value as Euro 7 precursor discussions and EPA tailpipe standards force sensor replacement cycles across gasoline powertrains, embedding crank trigger demand in emissions compliance infrastructure.
For Market Incumbents: Acquire captive semiconductor fabrication capacity or closely audited foundry relationships to secure die allocation during capacity crunches. Lock in long-term rare earth magnet supply contracts before neodymium pricing volatility accelerates. Denso Corporation's backward integration into silicon production exemplifies the defensive moat against Hall-effect sensor die shortages that threaten Tier-1 supplier margins. For New Entrants and Emerging Players: Enter via modular sensor packaging configurations targeting German and United States performance engine builders prioritizing field serviceability. The aftermarket optical sensor segment for enclosed racing environments offers lowest competitive density and highest specification flexibility. Pursue GB-standard certification for MIIT-compliant Chinese domestic OEM programs as the fastest qualification pathway outside captive semiconductor tiers. For Investors and Strategic Acquirers: Asymmetric upside sits with regional Chinese suppliers capturing domestic OEM sensor programs under tightening fuel consumption regulations. Five-to-ten year viability hinges on hybrid powertrain sensor count stabilization versus integrated starter-generator module displacement. Monitor 48V mild-hybrid architecture penetration rates as the critical inflection signal for dedicated crank trigger demand sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Fabrication | Denso Corporation's in-house silicon production locks in calibration consistency for EPA-certified gasoline powertrain programs. |
| Modular Sensor Packaging | Separable magnetic sensing elements compress replacement cycles for German performance builders demanding rapid field serviceability. |
| GB-Standard Certification Investment | Chongqing and Wenzhou suppliers capture MIIT-compliant domestic OEM procurement under tightening crank position tolerances. |
| Rare Earth Magnet Supply Contracting | Long-term neodymium and samarium cobalt agreements insulate margins against commodity volatility in high-temperature sensor variants. |
| SENT Protocol Digital Transition | Automakers mandating improved noise immunity displace analog front-end designs with diagnostic telemetry-enabled outputs. |
Study Parameters
Bottom-up OEM and aftermarket demand modeling reconciled against top-down semiconductor fabrication and magnetic component supply tracking forms the analytical core of this study. Primary interviews with Tier-1 ignition supplier procurement officers, OEM platform engineers, aftermarket distributor operations managers, and performance engine builder technical directors combined with secondary validation from EPA certification filings, NHTSA onboard diagnostic mandates, MIIT fuel consumption regulations, vehicle production databases, and IHS Markit registration data. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of sensor replacement cycles, powertrain electrification trajectories, and regulatory milestone timing informed projection frameworks across the analysis window. Segmentation dimensions modeled include product architecture, end-user type, installation format, and signal conditioning technology, with additional stratification by propulsion architecture and regional regulatory cluster. CAGRs derive from regression analysis of platform approval timelines and aftermarket retrofit penetration patterns, incorporating hybrid powertrain sensor count assumptions and rare earth magnet cost elasticity.
Inputs from OEM platform engineers and Tier-1 supplier procurement officers were available through the study window; gaps in 48V mild-hybrid architecture rollout schedules and integrated starter-generator module specification finalization introduce uncertainty bands around sensor-per-vehicle forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Power Liftgate for Automotive Market
Powertrain
Steering Damper Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Variable Displacement Compressor Market
Powertrain
Yaw Damper Market
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
Europe Hill-Start Assist System Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Gas Engine Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
Crankshaft Oil Market
Powertrain
Engine Rocker Arm Market
Powertrain
Europe Turbocharger Market
Powertrain
Italy Electro Hydraulic Power Steering Market