
 Mobile Messaging Market | 2026-2036
Mobile Messaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Messaging Market Outlook
Multi-source API procurement is consolidating as enterprises reduce vendor fragmentation in their communications stacks. Twilio leverages its developer-first platform to sustain integration density across enterprise workflows. Infobip anchors global reach through direct carrier relationships in emerging markets. Sinch competes on voice and video convergence alongside its messaging core.
Mobile messaging encompasses protocols and platforms enabling real-time text, multimedia, and interactive communication between users and systems, typically operating over IP networks or cellular signaling infrastructure with latency thresholds under 300 milliseconds for conversational interfaces. Its primary commercial purpose centers on customer engagement, authentication, and transactional notifications at scale. SMS retains the largest volume footprint within messaging solutions, though RCS and chatbots capture expanding margin pools as enterprises migrate from plain-text to rich, actionable interfaces. Android dominates platform-type volume in developing markets, while iOS commands premium monetization in North American and European enterprise segments.
FCC rules on robotext mitigation and TCPA consent requirements shape US market access and compliance costs for messaging providers. EMA data-integrity guidelines and EU GDPR cross-border transfer rules impose additional architectural constraints on healthcare and finance deployments in Europe. Stakeholders must monitor evolving RCS interoperability standards and carrier settlement frameworks to anticipate which platform investments will yield sustainable routing economics.
Market Dynamics
Enterprise migration from SMS to RCS and conversational AI interfaces is compressing legacy messaging economics while redistributing margin pools toward rich-media platforms and API consolidation.
Growth Catalysts
- GDPR and EU AI Act compliance mandates:European enterprises are upgrading messaging infrastructure to satisfy cross-border data transfer rules and automated decision-making transparency requirements, forcing platform refreshes.
- Digital payment integration in India:UPI-linked transactional messaging and vernacular-language chatbot deployment are expanding addressable user bases beyond English-centric urban centers.
- RCS protocol standardization:Universal Profile 2.4 interoperability specifications are reducing carrier fragmentation and enabling consistent rich-media delivery across Android devices.
Market Restraints
- Carrier settlement concentration:Direct operator relationships in emerging markets concentrate routing economics among three to four regional aggregators, limiting price competition.
- TCPA consent architecture costs:FCC robotext mitigation rules require express written consent frameworks that add per-message compliance overhead for US-bound traffic.
- Apple iMessage platform exclusivity:iOS's refusal to adopt RCS until late 2024 locked premium North American enterprise segments into siloed, non-interoperable messaging stacks.
Strategic Opportunities
- Brazilian open banking messaging:PIX payment system integration with conversational interfaces creates first-mover advantage for localized Portuguese-language chatbot deployment.
- Healthcare appointment automation:HIPAA-compliant two-way messaging for prescription adherence and scheduling represents underpenetrated vertical with measurable ROI metrics.
- Voice-video-messaging convergence:WebRTC integration with existing SMS/RCS APIs enables unified communication stacks that reduce enterprise vendor fragmentation.
Industry Challenges
- Conversational AI talent scarcity:Natural language processing engineers with vernacular-language expertise command premium compensation, constraining platform localization velocity.
- Legacy SMS gateway deprecation:Enterprises maintaining hybrid SMPP and HTTP API architectures face integration complexity during phased migration to rich-media protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Messaging Market |
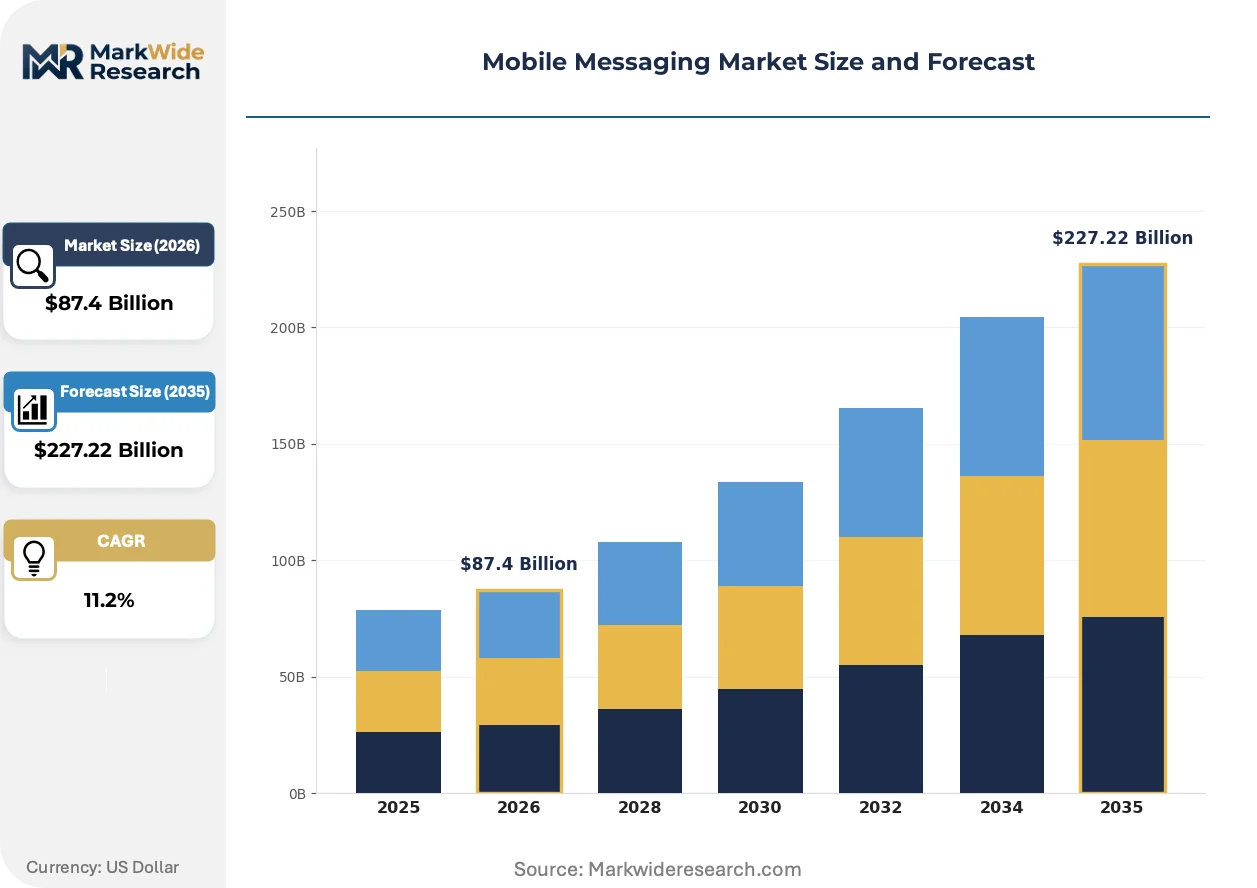
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $227.22 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: iOS, Android, Windows, Web Messaging Solution: SMS, MMS, RCS, Chatbots User Type: Consumers, Businesses, Enterprises, Developers Industry Vertical: Retail, Healthcare, Education, Finance |
| Companies Covered | Infobip, Sinch, Twilio, CM.com, Vonage, Tata Communications, Syniverse, Tanla, Route Mobile, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Messaging Market Strategic Shifts
Protocol-layer convergence between messaging, payments, and identity verification is collapsing traditional boundaries between communication infrastructure and financial services platforms.
Rich Communication Services is electrifying enterprise customer engagement by embedding carousels, suggested replies, and verified sender branding directly into native messaging apps. Retail and banking sectors in Germany and Spain are deploying RCS for appointment scheduling and fraud alerts at scale. The technology is electrifying margin compression against legacy SMS by shifting unit economics from per-message fees to session-based engagement metrics.
EU AI Act algorithmic transparency requirements are mandating disclosure when chatbots initiate conversations or process personal data for automated decisions. Messaging platforms must now maintain audit trails for consent capture and logic explanations in European deployments. Financial services and healthcare verticals face the steepest compliance timelines, with some institutions pausing AI-enabled outbound messaging until technical architectures satisfy national regulator interpretations.
API-first procurement patterns are displacing bundled telecom contracts as enterprises seek granular control over channel routing and failover logic. Mid-market retailers and fintech startups in Southeast Asia now evaluate messaging vendors on latency SLAs and vernacular NLP support rather than geographic coverage breadth alone. This behavior is most pronounced in India and Indonesia, where domestic payment system integration has become a primary selection criterion alongside message delivery rates.
Mobile Messaging Market Segmentation
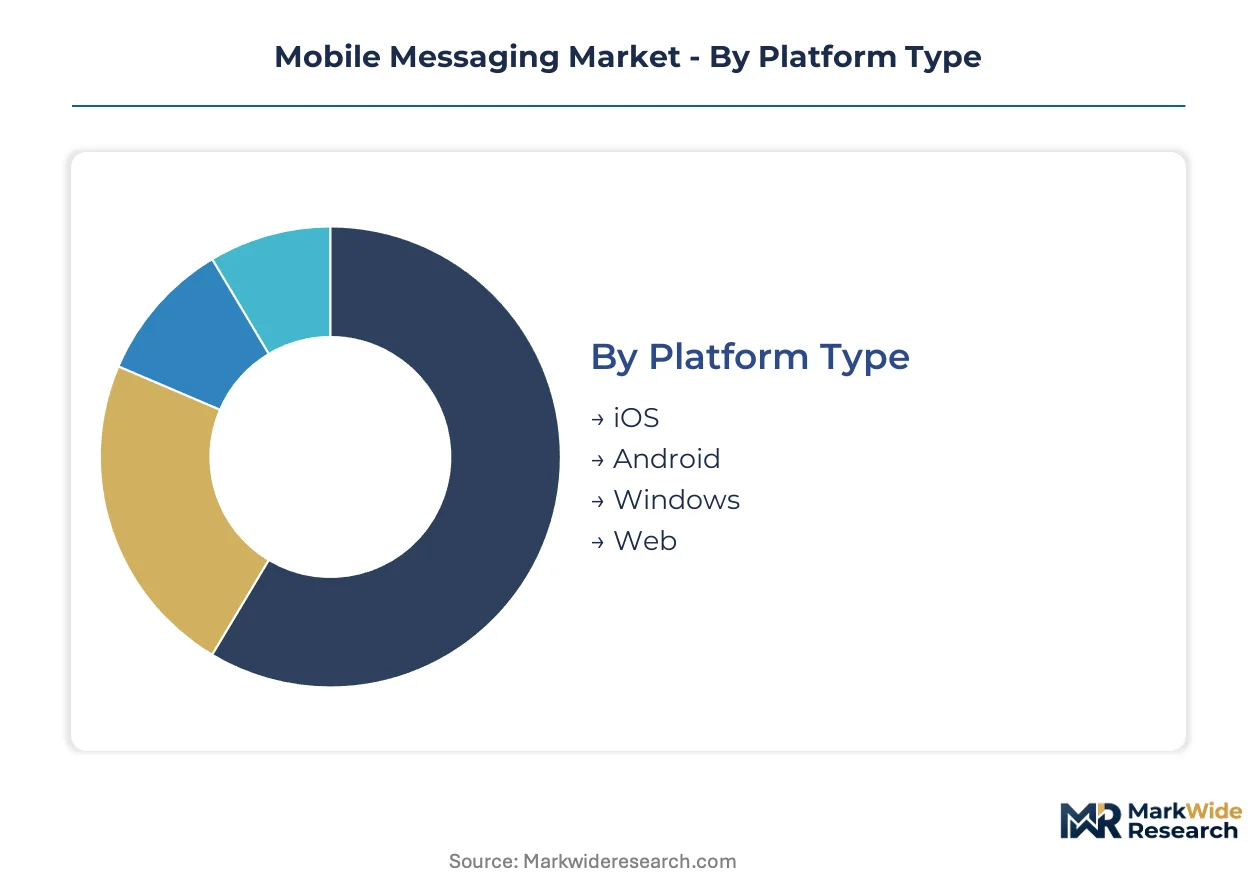
Segmentation in mobile messaging reveals how protocol choices, platform economics, and user sophistication create distinct commercial zones. Each axis governs pricing power, integration complexity, and regulatory exposure differently.
Platform Type:
Device operating systems determine carrier settlement structures, API accessibility, and rich-media rendering capabilities across deployment scenarios.
- iOS:Apple's closed ecosystem commands premium enterprise pricing through iMessage Business Chat and verified sender programs. North American financial institutions concentrate deployment here, drawn by affluent user demographics and Apple's privacy positioning.
- Android:Google's open architecture enables deeper carrier integration and RCS Universal Profile adoption at scale. Indian and Brazilian enterprises prioritize this platform for UPI and PIX payment-linked messaging due to dominant market share in emerging economies.
- Windows:Enterprise desktop messaging persists in regulated industries requiring on-premise infrastructure and legacy Active Directory integration.
- Web:Browser-based messaging delivers cross-platform consistency for customer support portals and Progressive Web App deployments.
Mature deployment sits with Android. Newer deployment is concentrated in Web-based progressive applications.
Messaging Solution:
Protocol selection directly shapes unit economics, with plain-text carriers yielding to rich-media platforms that capture session-based revenue.
- SMS:The 160-character protocol retains universal reach through SS7 signaling infrastructure. Healthcare appointment reminders and two-factor authentication drive residual volume in markets with fragmented smartphone penetration.
- MMS:Multimedia messaging enables image and video transmission over cellular networks. Retail promotional campaigns in Spain and Germany leverage this capability where RCS penetration remains incomplete.
- RCS:Rich Communication Services embeds carousels, suggested replies, and verified branding within native messaging apps. German banking and Spanish retail sectors deploy this for fraud alerts and appointment scheduling.
- Chatbots:Conversational AI interfaces process natural language queries through API integrations. Indian fintech deploys vernacular-language variants alongside UPI payment flows.
Legacy volume concentrates in SMS. Steepest expansion trajectory belongs to RCS as carrier interoperability solidifies.
User Type:
Organizational sophistication dictates integration depth, with developers and enterprises driving API-first procurement patterns.
- Consumers:Individual users generate network effects through peer-to-peer messaging volume. Their platform preferences constrain enterprise channel selection.
- Businesses:Small and medium enterprises adopt templated messaging solutions through self-service portals. Cost sensitivity dominates vendor selection.
- Enterprises:Large organizations demand SLA-backed latency guarantees, failover routing, and compliance audit trails. GDPR and EU AI Act mandates reshape their infrastructure requirements.
- Developers:Technical users embed messaging APIs directly into application workflows. Southeast Asian fintech startups evaluate vendors on vernacular NLP support and latency metrics.
Established procurement patterns sit with Enterprises. Newer deployment is concentrated in Developer-led API integrations.
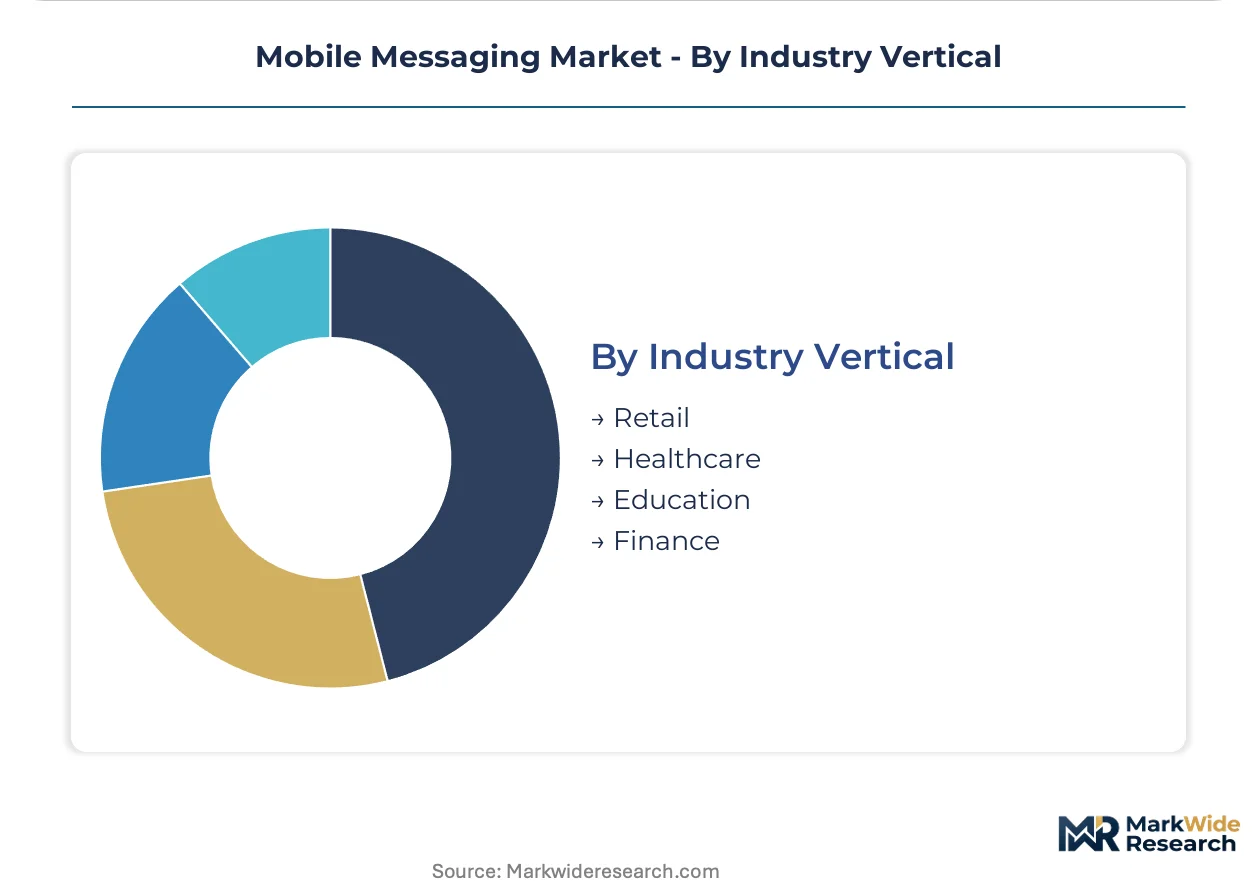
Industry Vertical:
Sector-specific compliance requirements and customer interaction patterns create divergent messaging architectures.
- Retail:Promotional campaigns and order notifications drive high-volume, low-margin traffic. Appointment scheduling through RCS carousels gains traction in German and Spanish markets.
- Healthcare:HIPAA-compliant two-way messaging for prescription adherence and scheduling represents underpenetrated deployment. EMA data-integrity guidelines impose additional architectural constraints in Europe.
- Education:Administrative notifications and emergency alert systems dominate institutional adoption. Budget constraints favor SMS over rich-media alternatives.
- Finance:Fraud alerts, transaction confirmations, and authentication flows demand highest reliability tiers. Brazilian open banking integration with PIX payment messaging creates localized opportunity.
Mature deployment sits with Finance. Newer deployment is concentrated in Healthcare automation systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates enterprise messaging demand through UPI-linked transactional flows and vernacular-language chatbot deployment. The United States shapes compliance architecture through FCC robotext mitigation rules. Germany anchors European RCS adoption for banking fraud alerts.
United States
Financial institutions drive enterprise messaging volume through fraud alert and authentication workflows. FCC TCPA consent requirements and robotext mitigation rules impose per-message compliance overhead on outbound traffic. New York and San Francisco host dense clusters of fintech startups evaluating API vendors on latency SLAs.
Germany
Retail banking and automotive sectors deploy RCS for appointment scheduling and service notifications. GDPR cross-border transfer rules and EU AI Act algorithmic transparency mandates force platform infrastructure refreshes. Frankfurt and Munich concentrate enterprise procurement decisions for rich-media messaging stacks.
India
UPI payment integration and vernacular-language NLP expand addressable user bases beyond urban English-speaking segments. TRAI regulations on commercial communications and data localization shape vendor selection criteria. Bengaluru and Mumbai anchor domestic messaging platform development and enterprise sales operations.
Brazil
PIX open banking integration creates demand for Portuguese-language conversational interfaces in transactional messaging. Central Bank of Brazil regulations on payment system messaging govern data handling requirements. São Paulo concentrates fintech adoption of chatbot-enabled customer engagement platforms.
United Kingdom
Financial services and retail verticals migrate from SMS to RCS for verified sender branding and rich-media campaigns. FCA conduct rules and GDPR compliance requirements shape audit trail specifications. London dominates enterprise procurement for API-first messaging infrastructure.
Mobile Messaging Market Competitive Environment
API consolidation dominates the current landscape as enterprises reduce vendor fragmentation across communication channels. The market structures around three tiers: global aggregators with direct carrier relationships, developer-first platform providers, and regional specialists with local regulatory expertise. Strategic archetypes include carrier-connected infrastructure players, API-native developer platforms, and vertical-focused solution providers. M&A activity and direct carrier partnership expansion represent the primary competitive vectors.
Among global aggregator archetypes, Infobip anchors carrier-connected infrastructure through emerging market direct relationships. Twilio exemplifies the developer-first platform model with integration density across enterprise workflows. Sinch occupies a position spanning voice and video convergence alongside core messaging capabilities.
| Leading Market Players |
|---|
| Infobip |
| Sinch |
| Twilio |
| CM.com |
| Vonage |
| Tata Communications |
| Syniverse |
| Tanla |
| Route Mobile |
| Others |
Value Chain & Pricing Dynamics
GDPR cross-border data transfer compliance gates both qualified supply and premium-tier pricing access for European enterprise deployments, forcing carriers and aggregators to invest in regional infrastructure or exit high-margin contracts entirely. EU AI Act algorithmic transparency requirements further stratify vendor tiers by mandating audit-capable architectures that smaller regional players cannot fund.
Pricing Analysis
Volume concentrates in legacy SMS while margins migrate to RCS and conversational AI platforms. Three-tier pricing structure across premium, standard, and economy levels separates SLA-backed enterprise contracts from self-serve developer tiers and commodity bulk routing. Price differentiation hinges on latency guarantees and vernacular NLP support. Pricing pressure stems from carrier settlement concentration in India and Brazil, where direct operator relationships limit aggregator competition. Small and medium enterprises exhibit highest price sensitivity; North American financial institutions show lowest, prioritizing compliance architecture over per-message cost.
Supply Chain Analysis
Cross-border IP transit and submarine cable capacity costs shape margin structures for global messaging traffic. Supply concentrates in India, Germany, and the United States for carrier-grade infrastructure and enterprise sales operations. Raw material dependencies include SS7 signaling equipment, cloud compute capacity, and vernacular-language training data. Single-source vulnerability in direct carrier relationships across emerging markets creates routing risk. Distribution runs through API-first platforms for developer segments and direct enterprise sales for SLA-backed contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FCC TCPA consent requirements and EU AI Act mandates create barrier-to-entry moats that favor incumbent platforms with dedicated regulatory engineering teams.
For Market Incumbents: Anticipate margin compression in plain-text SMS as RCS interoperability standardizes and new entrants undercut on routing fees. Defensive moves center on deepening direct carrier relationships in India and Brazil to lock in settlement economics, and investing in HIPAA-compliant healthcare messaging infrastructure ahead of vertical specialization. Threat vectors include hyperscaler cloud providers bundling messaging APIs with compute contracts. For New Entrants and Emerging Players: Capture underpenetrated healthcare appointment automation in the United States and German mid-market retail RCS deployment where incumbent coverage gaps persist. Most penetrable entry point lies in vernacular-language chatbot localization for Indian UPI-linked transactional flows. Go-to-market angle emphasizes WebRTC-enabled voice-video-messaging convergence to reduce enterprise vendor fragmentation. For Investors and Strategic Acquirers: Apple's late-2024 RCS adoption announcement is the leading indicator that carrier-interoperable rich messaging will consolidate platform economics around Android-dominated emerging markets. Long-term viability favors aggregators with direct operator relationships in high-growth geographies over pure API-layer plays. Acquisition target archetype: regional specialists with TRAI or Central Bank of Brazil regulatory certifications and established PIX or UPI integrations. Signal to monitor: carrier settlement framework renegotiations in India and Brazil.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Partnership Expansion | Direct operator relationships in India and Brazil lock in settlement economics against aggregator competition. |
| Healthcare Compliance Certification | HIPAA and EMA data-integrity architectures open prescription adherence and scheduling automation revenue pools. |
| Vernacular NLP Development | Portuguese and Hindi language models enable PIX and UPI-linked conversational interfaces at scale. |
| RCS Interoperability Investment | Universal Profile 2.4 compliance ensures consistent rich-media delivery across Android device fragmentation. |
| Voice-Video Convergence Integration | WebRTC embedding reduces enterprise vendor fragmentation and captures unified communications budgets. |
Study Parameters
Multi-period observation of carrier settlement rate disclosures, API pricing transparency reports, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with messaging platform engineering leads, carrier wholesale managers, enterprise IT procurement officers, and fintech integration specialists. Secondary validation drew from FCC robotext mitigation orders, TRAI commercial communication guidelines, EMA data-integrity guidance documents, and Central Bank of Brazil PIX messaging regulations. Bottom-up segmentation modeling triangulated against top-down market sizing from disclosed vendor volumes and carrier traffic reports.
Segment-weighting across platform type, messaging solution protocol, user sophistication tier, and industry vertical governed value allocation throughout the forecast period. Deployment maturity curves by geography and compliance timeline differentials shaped growth trajectory assumptions. CAGRs derived from carrier capacity expansion announcements, enterprise API consumption patterns, and protocol migration velocity indicators. Industry-specific inputs included RCS Universal Profile adoption rates and vernacular chatbot deployment metrics from Indian and Brazilian payment system integrations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Apple iMessage platform strategy shifts and EU AI Act national regulator interpretation variance. Forecasts reflect documented assumptions regarding carrier interoperability timelines and enterprise procurement cycle durations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Meeting Solutions Market
Communication Services
Green Communication Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
Broadcasting Solutions Market
Communication Services
Outbound Telemarketing Market
Communication Services
Global Call Center Platform Market
Communication Services
Global Critical Communication Market
Communication Services
High Performance Message Infrastructure Market
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Voice Commerce Market
Communication Services
Contact Center As a Service (Ccaas) Market
Communication Services
Pcaas Market
Communication Services
Postal Services Market
Communication Services
Web Conferencing Market
Communication Services
Consumer Communication Services Market