
 Hardware OTP Token Authentication Market | 2026-2036
Hardware OTP Token Authentication Market Size, Share, and Industry Trends Forecast 2026-2036
Hardware OTP Token Authentication Market Outlook
East Asian manufacturing clusters for secure semiconductor components is expanding output capacity to serve authentication hardware demand. Thales Group leverages vertically integrated chip-to-token production lines across France and Singapore. RSA Security LLC anchors enterprise sales through deep channel partnerships with North American banking infrastructure providers. Feitian Technologies Co., Ltd. competes aggressively on cost-engineered USB token variants for price-sensitive institutional buyers.
Hardware OTP token authentication employs dedicated physical devices generating time-synchronized or event-based one-time passcodes through embedded secure elements, typically operating on battery-powered microcontrollers with tamper-resistant housings designed to resist side-channel extraction. These devices serve as possession factors in multi-factor authentication frameworks, replacing software-based generators with air-gapped cryptographic modules. USB tokens and smart cards capture the dominant share of product type revenue, with USB formats leading in enterprise deployments while smart cards sustain entrenched government and banking credential systems. Key fobs represent the fastest-growing product configuration as healthcare and education sectors prioritize low-friction user experiences.
FDA cybersecurity guidance for connected medical devices, HIPAA administrative safeguards, and the EU AI Act's risk-classification framework collectively elevate hardware-based authentication above software alternatives in regulated environments. NIS2 implementation across EU member states mandates stronger access controls for critical entities, directly expanding addressable demand. Stakeholders must monitor evolving FERC standards for energy sector critical infrastructure as grid operators face escalating mandate timelines for operator authentication hardening.
Market Dynamics
Regulatory mandates across financial services and critical infrastructure are compressing procurement timelines for hardware-based authentication, forcing buyers to accelerate replacement of software-dependent systems with tamper-resistant physical tokens before compliance deadlines arrive.
Growth Catalysts
- NIS2 Directive:The European Union's cybersecurity framework mandates stronger access controls for critical entities, directly expanding procurement volumes across energy, transport, and healthcare operators in Germany, France, and the Netherlands.
- FDA cybersecurity guidance:Connected medical device manufacturers must implement hardware-backed authentication for operator access, elevating USB token and smart card deployments in hospital networks and diagnostic equipment supply chains.
- Banking corridor concentration:Germany's dense cluster of financial institutions faces accelerated compliance timelines, concentrating demand for key fob and display card formats among cooperative banks and savings institutions.
Market Restraints
- Secure element supply concentration:Foundry capacity for tamper-resistant microcontrollers concentrates among East Asian semiconductor fabricators, creating vulnerability to geopolitical friction or export control tightening.
- Battery chemistry cost volatility:Lithium primary cell prices fluctuate with raw material markets, squeezing margins on compact key fob designs where form factor constraints prevent alternative power architectures.
- Mobile authenticator substitution:Smartphone-based soft tokens erode addressable demand among cost-sensitive small enterprises, particularly in retail and professional services segments with lower regulatory exposure.
Strategic Opportunities
- Healthcare credential convergence:HIPAA administrative safeguards and FDA device rules create dual-mandate environments where hardware tokens satisfy both patient data access and medical equipment operator authentication requirements.
- Education sector friction reduction:Universities and research institutions prioritize low-friction key fob deployments for faculty and student access to sensitive research data, opening volume channels outside traditional financial services buyers.
- FERC energy infrastructure rules:Evolving standards for grid operator authentication hardening present procurement expansion potential as North American utilities face escalating mandate timelines for critical infrastructure protection.
Industry Challenges
- Secure firmware engineering talent scarcity:Embedded cryptographic development requires specialized expertise in side-channel resistance and tamper detection, constraining product pipeline velocity for mid-tier vendors.
- Common Criteria certification timelines:EAL4+ evaluation processes for banking-grade tokens extend 12-18 months, compressing revenue recognition windows and demanding advance R&D investment before procurement commitments materialize.
- Legacy IAM system integration complexity:Enterprise buyers operate heterogeneous identity management platforms requiring custom token middleware development, elongating sales cycles and inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hardware OTP Token Authentication Market |
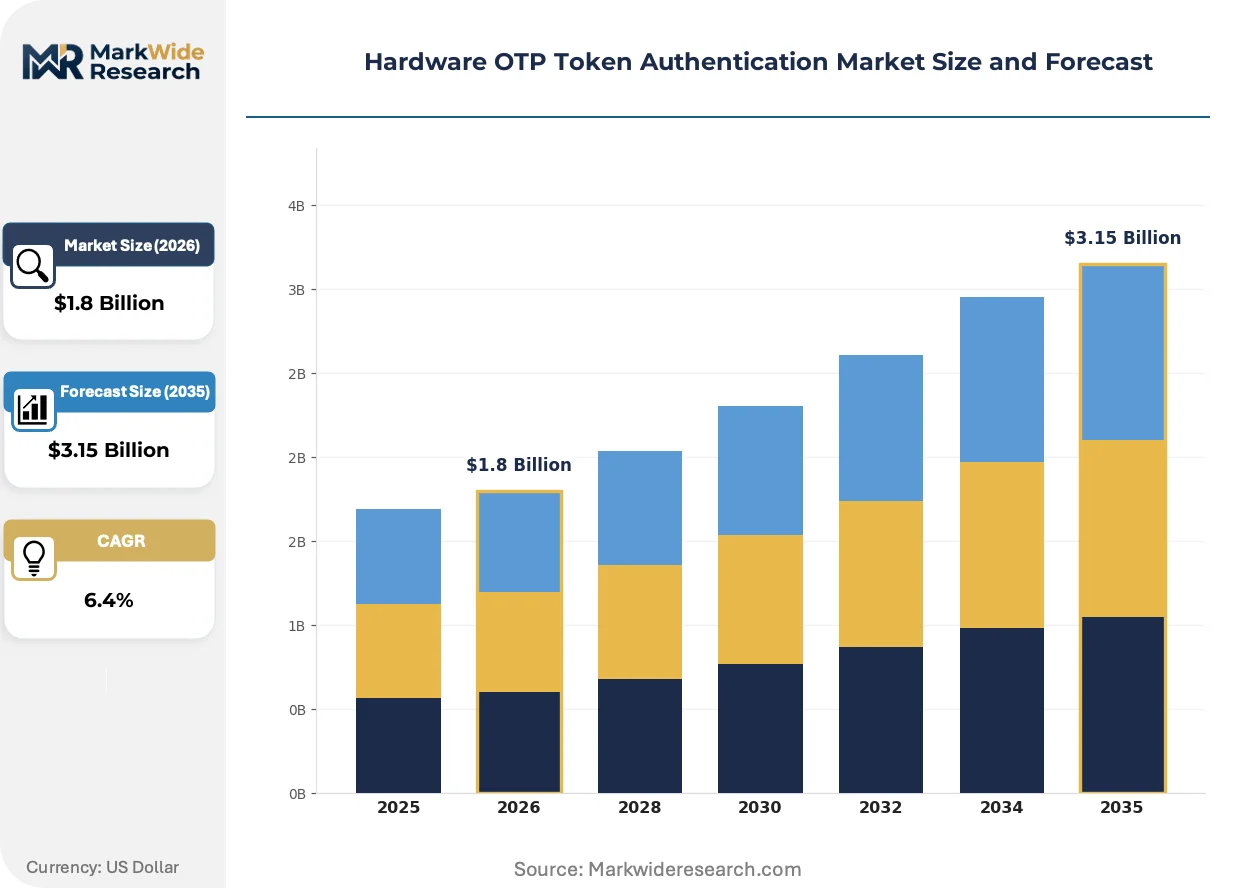
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB Tokens, Smart Cards, Mobile Tokens, Key Fobs End User: BFSI, Healthcare, Government, Education Deployment: On-Premise, Cloud, Hybrid, Remote Technology: RFID, Biometrics, QR Code, PIN Protected |
| Companies Covered | Thales Group, RSA Security LLC, Entrust Datacard Corporation, OneSpan Inc., Yubico, HID Global Corporation, VASCO Data Security International Inc., Feitian Technologies Co., Ltd., IDEMIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hardware OTP Token Authentication Market Strategic Shifts
Hardware token architectures are fragmenting across form factor and connectivity specifications as buyers demand purpose-built devices for distinct risk environments rather than universal platforms.
Secure element technology is decentralizing cryptographic processing from centralized authentication servers to edge devices. Banking networks in Germany and the Netherlands deploy tokens with localized transaction signing capabilities. This architecture compresses attack surfaces by eliminating credential transmission over compromised networks.
The EU AI Act's risk-classification framework elevates hardware-backed identity verification for high-risk automated decision systems. Critical infrastructure operators must implement possession-factor authentication for AI system access controls. Healthcare and energy sectors face the steepest compliance ramps under these provisions.
Subscription-based token lifecycle management displaces perpetual ownership models among enterprise buyers. Managed service providers now bundle hardware provisioning, certificate renewal, and device retirement into recurring contracts. This shift concentrates most visibly in North American financial services and healthcare networks seeking operational expenditure predictability.
Hardware OTP Token Authentication Market Segmentation
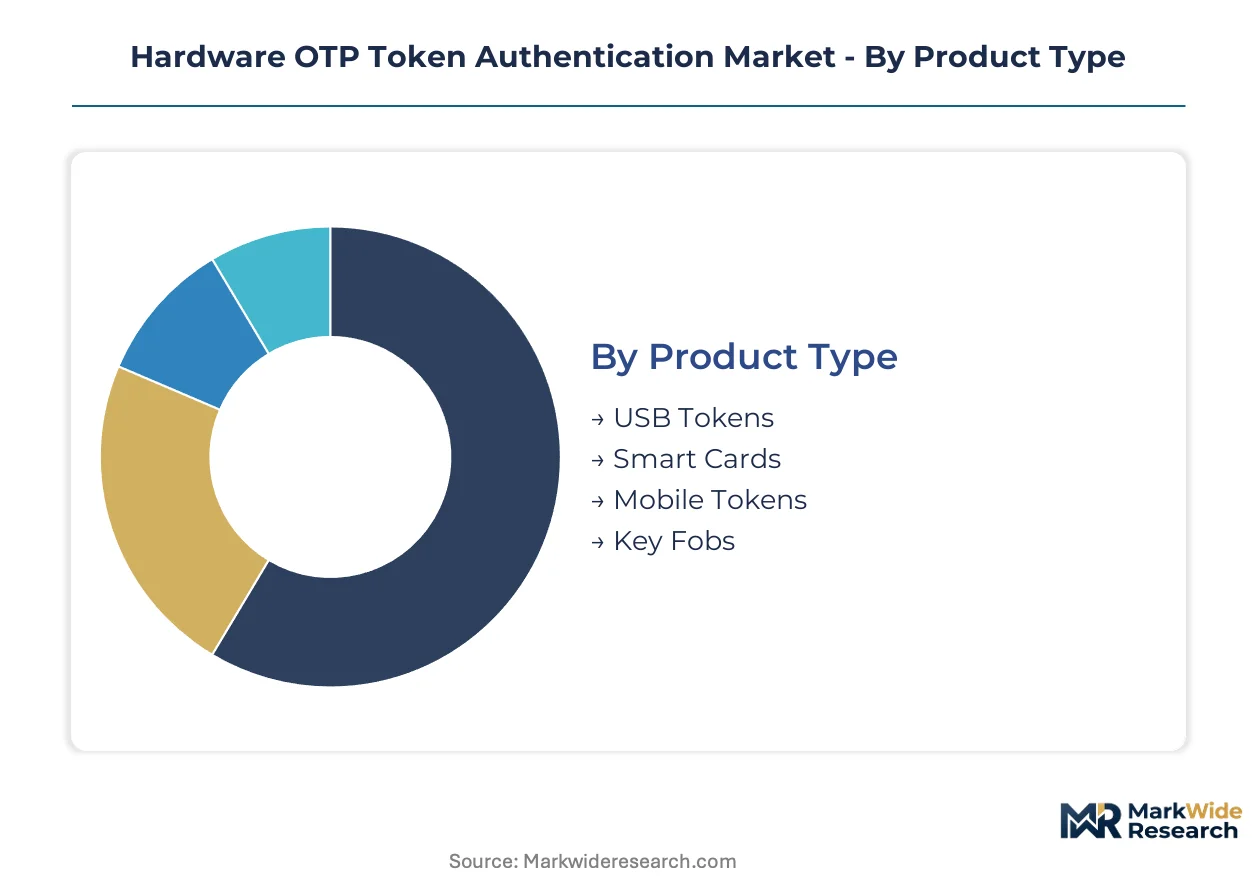
Hardware OTP token architectures fragment across form factor and connectivity specifications as buyers demand purpose-built devices for distinct risk environments. Supply chain configuration for secure semiconductor components directly shapes which product categories capture procurement volume across regulated industries.
Product Type:
Secure element foundry capacity concentrates among East Asian semiconductor fabricators, creating tiered availability that favors form factors with standardized chip footprints over custom designs.
- USB Tokens:These devices embed tamper-resistant secure elements within standard USB-A or USB-C housings, enabling direct host connectivity without additional readers. Enterprise deployments in Germany's banking corridor favor USB formats for workstation-based transaction signing, driven by NIS2 compliance timelines that demand rapid hardware rollout. Supply chain scale advantages from consumer electronics component reuse keep procurement lead times shortest among hardware categories.
- Smart Cards:ISO 7816-compliant contact cards and contactless variants carry embedded microcontrollers in credit-card form factors, sustaining entrenched credential systems. Government identity programs and European banking networks concentrate demand here, constrained by dual-interface chip supply bottlenecks that extend delivery schedules versus simpler USB alternatives.
- Key Fobs:Battery-powered compact devices with push-button or display-based code generation target low-friction user experiences. Healthcare networks and university campuses drive adoption.
- Mobile Tokens:Hardware modules integrated into smartphones or tablets bridge physical and software authentication, though regulatory preference for air-gapped security limits penetration in critical infrastructure.
Today's leader: USB Tokens. Tomorrow's challenger: Key Fobs.
End User:
Regulatory mandate density varies sharply across buyer categories, concentrating procurement urgency where compliance deadlines are binding and penalties severe.
- BFSI:Cooperative banks and savings institutions in Germany's dense financial cluster face accelerated NIS2 implementation timelines. Hardware token procurement here operates on compressed cycles with limited vendor flexibility due to Common Criteria certification requirements.
- Healthcare:FDA cybersecurity guidance for connected medical devices and HIPAA administrative safeguards create dual-mandate environments. Hospital networks deploy USB tokens and smart cards for both patient data access and diagnostic equipment operator authentication.
- Government:National identity programs and classified system access sustain demand for high-assurance smart card formats with extended EAL certification.
- Education:Universities prioritize key fob deployments for faculty and student access to sensitive research data, opening volume channels with lower certification burdens than financial or government buyers.
Procurement urgency peaks in BFSI. Volume expansion potential concentrates in Healthcare.
Deployment:
Enterprise identity management architecture heterogeneity forces token vendors to maintain parallel middleware development tracks, inflating R&D allocation across deployment modes.
- On-Premise:Hardware tokens integrate with locally hosted identity management platforms, dominating banking and government sectors where data sovereignty requirements prohibit cloud credential storage. Germany's financial institutions anchor this segment through regulatory preference for air-gapped authentication infrastructure.
- Cloud:Token-as-a-service models bundle hardware provisioning with managed certificate lifecycle operations. North American healthcare networks drive adoption here, seeking operational expenditure predictability over capital ownership.
- Hybrid:Mixed environments split credential storage between on-premise directories and cloud identity providers, requiring complex synchronization middleware that elongates deployment timelines.
- Remote:Distributed workforce authentication without VPN dependency demands tokens with offline code generation capability, expanding addressable demand beyond traditional perimeter-based security models.
Architecture lock-in sustains On-Premise dominance. Cloud delivery models gain fastest among compliance-flexible buyers.
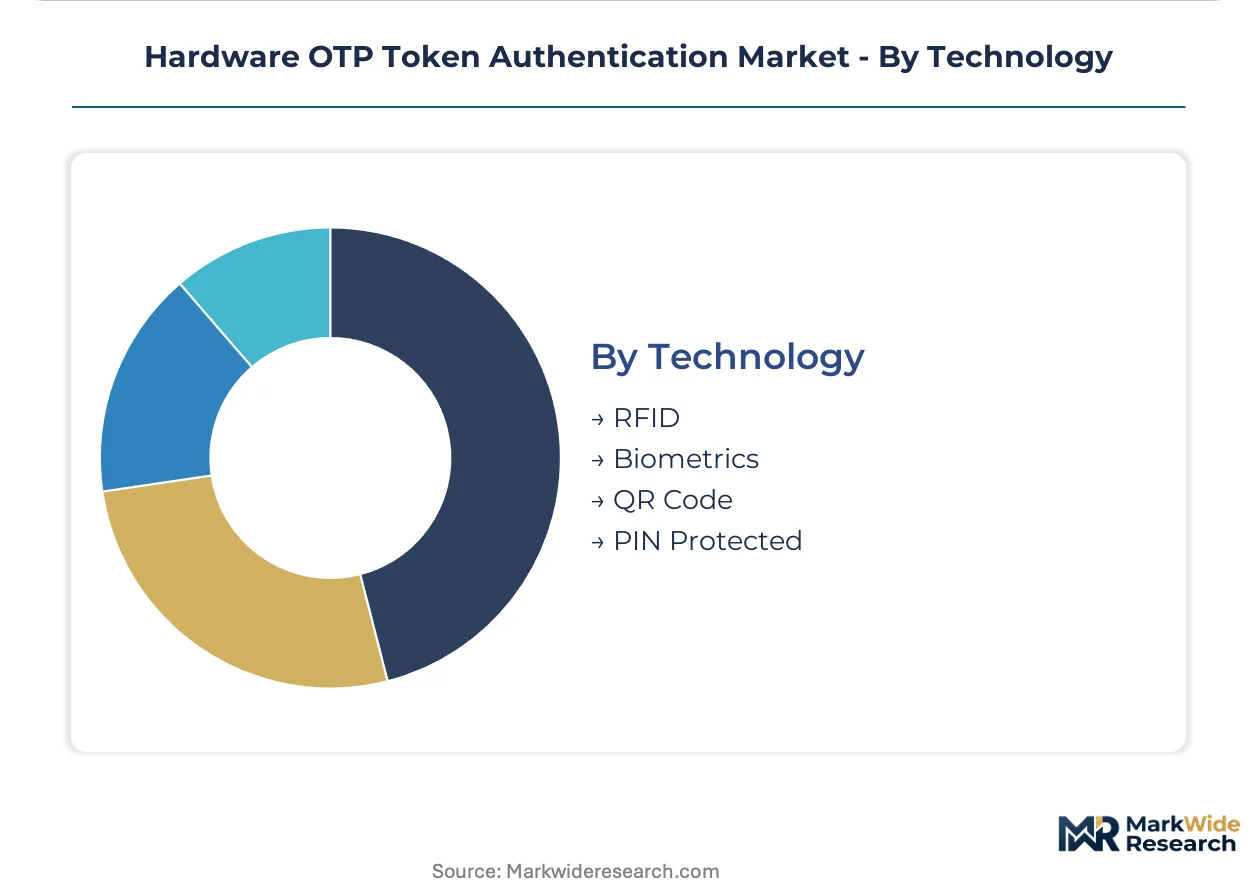
Technology:
Authentication mechanism selection trades security assurance against user friction, with regulated environments accepting higher operational burden for tamper-evident verification.
- PIN Protected:Time-synchronized or event-based code generation requires user entry of memorized credentials alongside hardware possession, creating two-factor verification without secondary devices. Banking networks deploy these most heavily, accepting friction for regulatory demonstrability of possession-plus-knowledge authentication.
- Biometrics:Fingerprint or iris sensors integrated into token housings bind possession to inherence factors, eliminating memorization burden. Healthcare operator authentication for medical devices drives niche adoption where glove removal or hygiene protocols permit sensor contact.
- RFID:Contactless proximity activation enables tap-to-authenticate workflows in physical access control converged with logical system entry.
- QR Code:Optical code display or scanning bridges hardware tokens with mobile or web-based authentication flows, though optical channels introduce network exposure that air-gapped designs avoid.
PIN Protected maintains regulatory preference. Biometrics climbs fastest where user experience pressure overrides pure security optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting production toward jurisdictions with lower compliance-cost burdens. East Asian semiconductor fabricators capture secure element foundry work as European and North American vendors face steeper certification timelines.
United States
FERC standards for energy sector critical infrastructure are tightening authentication requirements for grid operators. The FDA cybersecurity guidance for connected medical devices mandates hardware-backed operator access controls. Hospital networks in the Greater Boston and Pacific Northwest corridors are deploying USB tokens and smart cards for dual patient-data and equipment-authentication use cases.
Germany
NIS2 Directive implementation is compressing procurement timelines across cooperative banks and savings institutions. The country's national cybersecurity regulator is enforcing accelerated compliance deadlines for critical financial infrastructure. Frankfurt and Munich banking clusters are concentrating demand for key fob and display card formats ahead of binding mandate dates.
France
ANSM and CNIL are elevating hardware-based authentication requirements for healthcare data access and medical device operation. The EU AI Act's risk-classification framework binds high-risk automated decision systems to possession-factor controls. Thales Group's vertically integrated chip-to-token production lines in domestic facilities serve both domestic and export demand.
China
National standards for critical information infrastructure protection are mandating stronger access controls for financial and energy operators. MIIT guidelines favor domestic secure element sourcing for government and state-owned enterprise procurement. Shanghai and Shenzhen manufacturing clusters are expanding output capacity for tamper-resistant microcontroller components serving authentication hardware demand.
Singapore
The city-state's financial regulator is aligning commercial bank authentication requirements with EU NIS2-equivalent standards ahead of regional harmonization. Thales Group operates integrated production facilities serving Asia-Pacific demand from this manufacturing hub. The local semiconductor packaging ecosystem supports final-stage token assembly for regional banking and government identity programs.
Hardware OTP Token Authentication Market Competitive Environment
European producers anchor premium-tier certification-heavy supply; East Asian specialists hold cost-engineered volume positions. The vendor base stratifies across three tiers: vertically integrated secure element-to-token manufacturers, middleware-focused platform integrators, and component-assembly contract producers. Two competitive moves dominate: foundry partnerships to secure microcontroller supply, and managed service packaging to capture recurring revenue streams.
Within the integrated-manufacturer tier, Thales Group exemplifies geographic diversification across European and Asia-Pacific production footprints. RSA Security LLC occupies a position emphasizing enterprise channel depth over captive component supply. Feitian Technologies Co., Ltd. represents the cost-optimized archetype, competing on price-engineered USB token variants for institutional buyers with lower certification burdens.
| Leading Market Players |
|---|
| Thales Group |
| RSA Security LLC |
| Entrust Datacard Corporation |
| OneSpan Inc. |
| Yubico |
| HID Global Corporation |
| VASCO Data Security International Inc. |
| Feitian Technologies Co., Ltd. |
| IDEMIA |
| Others |
Value Chain & Pricing Dynamics
Lithium primary cell chemistry costs cascade from East Asian battery foundries through three distinct hardware token pricing tiers, with German banking procurement absorbing premium markups for NIS2-compliant certification while Southeast Asian institutional buyers capture economies from standardized USB housings.
Pricing Analysis
Distributor margins compress most severely on compact key fob formats where battery chemistry cost volatility intersects with form-factor constraints. Pricing stratifies across premium, standard, and economy tiers keyed to Common Criteria certification grade and secure element sourcing geography. Cost compression in the economy tier is intensifying because Feitian Technologies and comparable cost-engineered competitors are flooding USB token channels with reused consumer-electronics component architectures. Healthcare networks exhibit highest price sensitivity due to constrained capital budgets, while German cooperative banks demonstrate lowest sensitivity given binding regulatory deadlines.
Supply Chain Analysis
China's MIIT domestic-content mandates are reshaping sourcing patterns for government and state-owned enterprise procurement, forcing foreign vendors to establish local secure element partnerships or forfeit public-sector contracts. Foundry capacity for tamper-resistant microcontrollers concentrates in Taiwan, South Korea, and mainland China, drawing from silicon wafers, lithium primary cells, and injection-molded ABS housings. Single-source vulnerability runs through Taiwan Semiconductor's advanced-node secure element production. Distribution runs through specialized cybersecurity VARs and direct enterprise sales teams serving banking and healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between East Asian manufacturing cost bases and European regulatory premium capture, with NIS2 compliance timelines in Germany creating 40-60% pricing umbrellas over comparable hardware sourced from Singapore production.
For Market Incumbents: Acquire secure element foundry capacity or binding offtake agreements to insulate margin structures from Taiwan supply concentration. Thales Group's dual-footprint model across France and Singapore exemplifies this defensive posture. RSA Security LLC should deepen channel control through exclusive managed service partnerships with North American healthcare networks facing FDA authentication mandates. Battery chemistry cost volatility represents the most pressing margin threat. For New Entrants and Emerging Players: Begin with education sector key fob deployments where certification burdens remain lowest and volume channels are underdeveloped. Universities in the Netherlands and Nordic markets present penetrable white space outside German banking saturation. A subscription-based token lifecycle management go-to-market angle bypasses capital-constrained procurement committees. For Investors and Strategic Acquirers: Consolidation pressure builds where Common Criteria certification timelines extend 12-18 months and mid-tier vendors lack capital to bridge revenue recognition gaps. Target acquisition archetype: middleware-focused platform integrators with entrenched healthcare IAM system relationships. Watch for FERC authentication rule finalization as the signal indicating North American energy sector procurement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Foundry Partnership | Taiwan Semiconductor binding offtake secures microcontroller supply for NIS2-compliant token volumes. |
| Managed Service Packaging | North American healthcare networks shift from capital ownership to operational expenditure predictability models. |
| Key Fob Form Factor Expansion | Education sector procurement prioritizes low-friction user experience over banking-grade certification tiers. |
| Dual-Geography Production Footprint | Thales Group's France-Singapore integration mitigates tariff exposure and local-content mandate risk. |
| Healthcare Credential Convergence | FDA device rules and HIPAA safeguards create dual-mandate demand for USB token and smart card formats. |
Study Parameters
Direct dialogue with hardware token procurement officers at German cooperative banks, FDA regulatory affairs leads, hospital biomedical engineering directors, and cybersecurity VAR channel managers grounded qualitative findings. Secondary validation drew from NIS2 implementation guidance documents, FDA cybersecurity guidance filings, FERC infrastructure protection dockets, and Common Criteria certification registries. Bottom-up unit shipment estimates triangulated against top-down addressable market calculations across the analysis window.
Segmented outputs by product type, end-user vertical, deployment architecture, and authentication technology mechanism populated the analytical framework throughout the projection horizon. CAGRs emerged from regression against regulatory mandate density, secure element foundry capacity expansion rates, and battery chemistry cost indices. Modeled inputs included NIS2 compliance deadline schedules, FDA guidance implementation timelines, and education sector IT security budget growth patterns.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor supply, breakthrough mobile authenticator technologies achieving regulatory equivalence, and lithium primary cell chemistry substitution. Forecasts reflect documented assumptions regarding mandate enforcement rigor and certification timeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
BYOD Security Market
Security Software
IAM Security Services Market
Security Software
Global Privileged Access Management (PAM) Solutions Market
Security Software
Quantum Key Distribution System Market
Security Software
Anomaly Detection Tools Market
Security Software
Home Webcam Market
Security Software
Bot Mitigation Market
Security Software
Global Data Loss Prevention Software Market
Security Software
Video Intercom Devices and Equipment Market
Security Software
Passport Reader Market
Security Software
Global Runtime Application Self-Protection Market
Security Software
Cloud Encryption Software Market
Security Software
Global Digital Vehicle Forensics Market
Security Software
United States Lawful Interception Market
Security Software
Cloud File Security Software Market
Security Software
Application Control Software Market