
 Asia-Pacific Postal Services Market | 2026-2036
Asia-Pacific Postal Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Postal Services Market Outlook
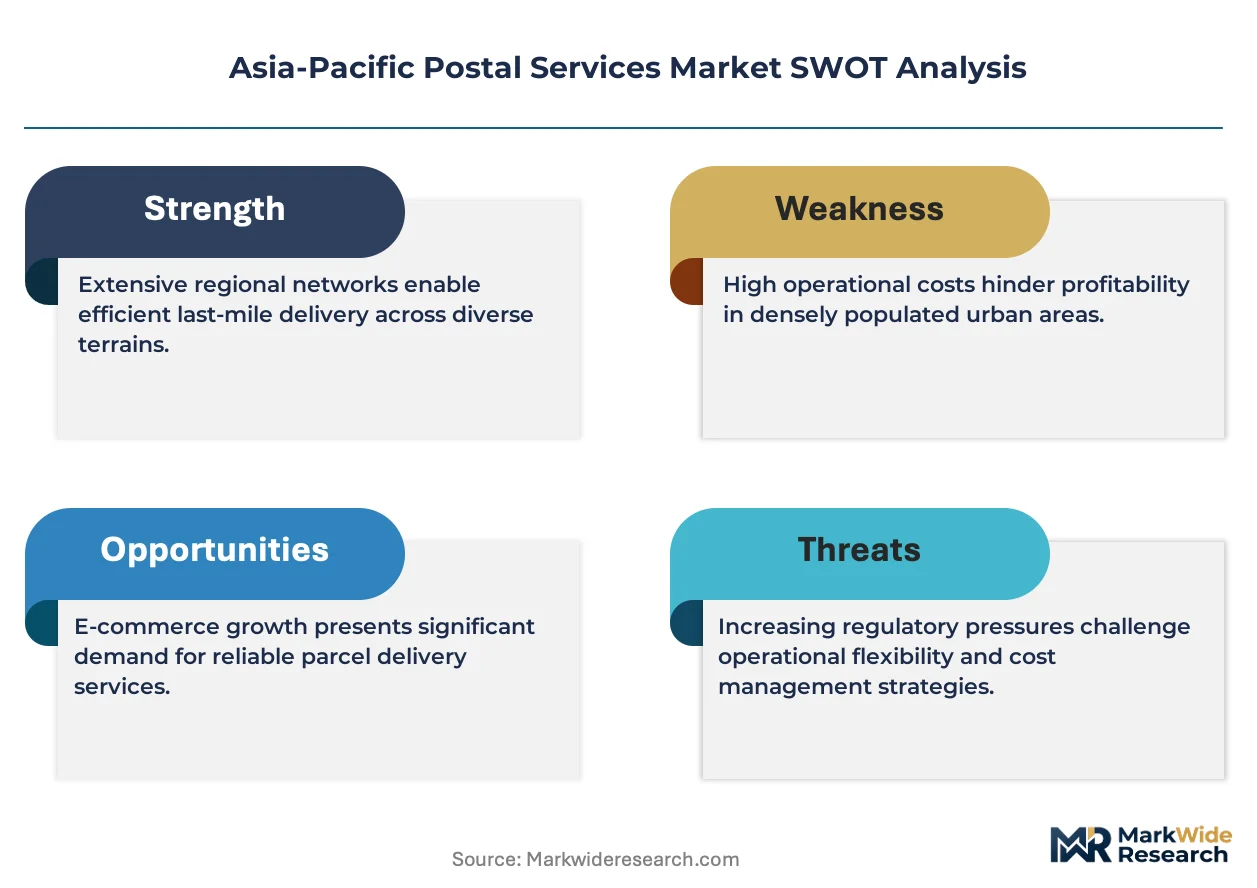
China's automated sorting hub expansion is reconfiguring parcel throughput capacity across the Asia-Pacific corridor. China Post Group Corporation leverages its rural network density to sustain last-mile coverage advantages. Japan Post Co., Ltd. anchors premium financial-services-integrated delivery in aging demographics. Singapore Post Limited competes on cross-border e-commerce gateway positioning between ASEAN and China.
Asia-Pacific postal services encompass state-affiliated and commercial mail, parcel, and logistics operations involving physical document exchange, merchandise transport, and supply-chain intermediation with processing standards ranging from same-day express to economy surface mail. These services facilitate trade documentation, consumer goods distribution, and government benefit disbursement across diverse terrain and regulatory environments. Express Delivery commands premium pricing from time-sensitive manufacturing supply chains, while E-commerce Solutions absorbs the fastest volume growth from platform sellers. Logistics Services captures concentrated margin pools from pharmaceutical cold chain and high-value electronics segments requiring specialized handling protocols.
India's Postal Act amendments under the Department of Posts, Japan's Ministry of Internal Affairs and Communications delivery standards, and China's State Post Bureau parcel tracking mandates collectively determine market access thresholds and service-level benchmarks. EMA-equivalent pharmacovigilance documentation requirements in several jurisdictions shape healthcare logistics certification demands. Stakeholders must weigh infrastructure automation commitments against regulatory labor protections as parcel volumes scale.
Market Dynamics
E-commerce parcel volumes are compressing delivery windows across the Asia-Pacific corridor, forcing state-affiliated operators to automate sorting infrastructure at unprecedented speed while preserving universal service obligations in remote territories.
Growth Catalysts
- China's State Post Bureau parcel tracking mandates:Real-time visibility requirements accelerate carrier technology upgrades and create competitive differentiation for compliant operators.
- Cross-border e-commerce platform expansion:Marketplace sellers in ASEAN manufacturing clusters generate concentrated demand for integrated customs-clearance-and-delivery solutions.
- India's Digital India initiative:Rural network digitization enables financial services integration, transforming post offices into banking access points for unbanked populations.
Market Restraints
- Labor cost inflation in tier-one Chinese cities:Wage pressures in Shanghai and Shenzhen erode margin buffers for labor-intensive last-mile operations.
- Fuel price volatility:Diesel and aviation kerosene exposure compresses earnings for surface and air freight segments without fuel surcharge pass-through mechanisms.
- Japan's Ministry of Internal Affairs delivery standards:Strict service-level benchmarks limit operational flexibility and capex recovery timelines for premium service tiers.
Strategic Opportunities
- Pharmaceutical cold chain certification:EMA-equivalent pharmacovigilance documentation requirements in multiple jurisdictions create specialized logistics margin pools.
- Vietnam-Indonesia manufacturing corridor:Factory relocation from China generates new origin-destination flows requiring integrated warehousing and customs brokerage.
- 5G-enabled predictive routing:Convergence of IoT sensors and edge computing enables dynamic delivery sequencing that cuts fuel consumption and failed delivery attempts.
Industry Challenges
- Automation technician scarcity:Sorting hub robotics deployment outpaces vocational training pipeline capacity in India and Southeast Asia.
- Legacy financial services integration:Japan Post's banking-delivery hybrid model creates system architecture complexity that slows digital platform unification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Postal Services Market |
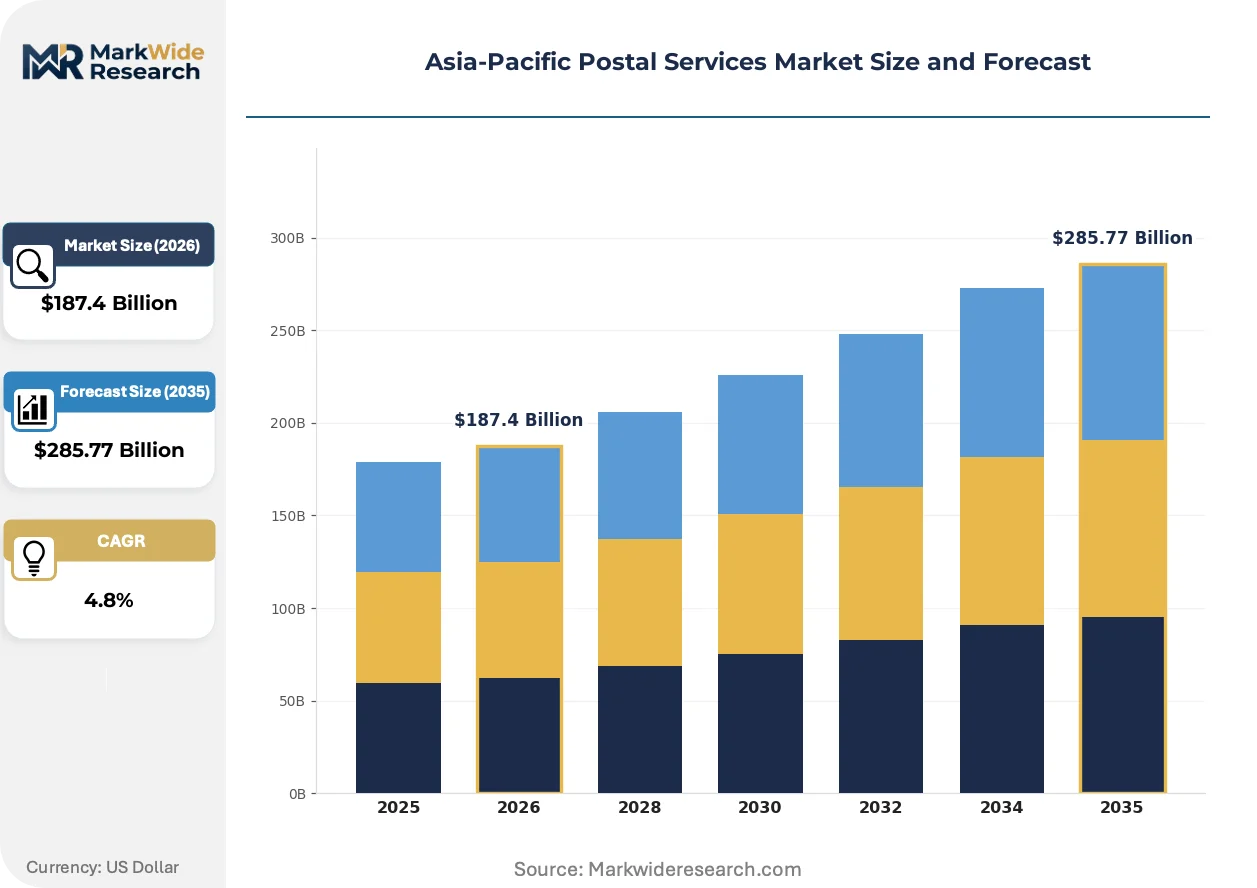
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Standard Mail, Logistics Services, E-commerce Solutions Delivery Mode: Air Freight, Ground Transport, Sea Freight, Last Mile Delivery Customer Type: Individuals, Businesses, Government Agencies, NGOs End User: Retail Sector, Manufacturing Industry, Financial Institutions, Healthcare Providers |
| Companies Covered | Australian Postal Corporation, Singapore Post Limited, China Post Group Corporation, Pos Indonesia, Pos Malaysia Berhad, Japan Post Co., Ltd., Korea Post, Thailand Post, India Post, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Postal Services Market Strategic Shifts
Automation, regulatory harmonization, and buyer behavior compression are restructuring competitive advantage in Asia-Pacific postal services, rewarding operators that integrate physical infrastructure with digital service layers.
Autonomous mobile robots in sorting hubs are rendering obsolete manual parcel handling and fixed conveyor belt configurations. E-commerce fulfillment centers in China's Yangtze River Delta deploy AMR fleets at scale, cutting sortation labor requirements by half while compressing processing windows to under two hours per parcel batch.
Japan's logistics deregulation under METI oversight permits private carriers to compete directly with Japan Post in letter-mail segments previously reserved for universal service operators. Pharmaceutical and financial document verticals face the steepest competitive pressure as specialized entrants capture premium same-day delivery contracts.
Platform sellers now bundle delivery speed guarantees into product listings, compressing carrier selection decisions to checkout-moment algorithms rather than annual procurement cycles. This shift concentrates volume with operators offering API-integrated real-time rate quoting, visible most acutely in Singapore's cross-border gateway corridors serving ASEAN-China trade lanes.
Asia-Pacific Postal Services Market Segmentation
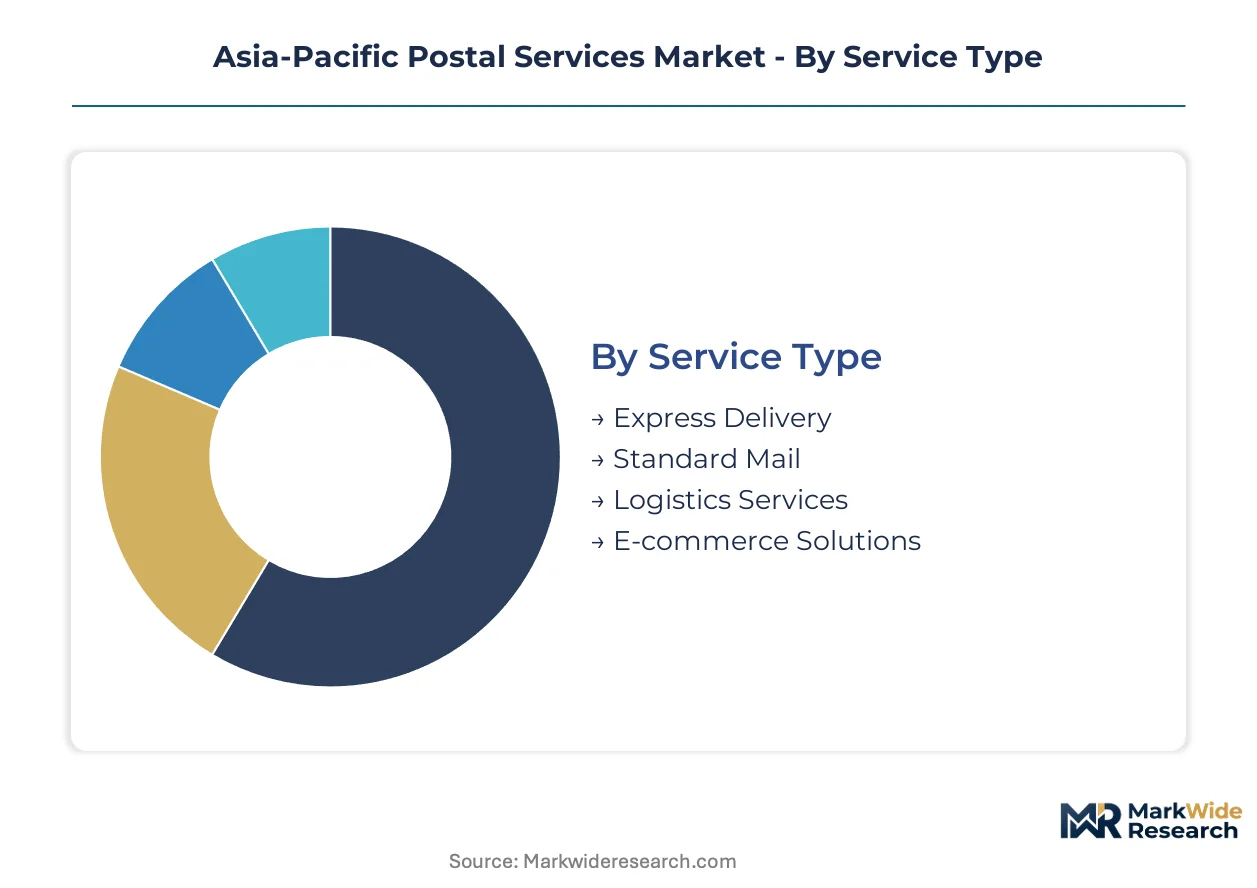
Postal service segmentation in Asia-Pacific reveals how delivery infrastructure fragments across speed requirements, cargo modes, and institutional buyer types. Understanding these divisions exposes where automation investments concentrate and which customer relationships command premium pricing power.
Service Type:
Time sensitivity and value density span from document exchange to integrated supply-chain management across the region's diverse economies.
- Express Delivery:Time-definite transportation with guaranteed delivery windows for manufacturing components and legal documentation. Japan's automotive supply chains and South Korea's electronics corridors absorb the highest premium volumes for same-day and next-morning service tiers.
- E-commerce Solutions:Platform-integrated parcel handling with API-connected tracking, returns processing, and customs pre-clearance. China's tier-one cities and their surrounding manufacturing belts generate the steepest volume growth as marketplace sellers bundle delivery guarantees into product listings.
- Standard Mail:Non-priority document and small parcel delivery operating on economy timelines with universal service obligations. Rural India and Indonesia's outer islands sustain this segment through postal banking and government benefit distribution mandates.
- Logistics Services:Contract warehousing, inventory management, and specialized handling for pharmaceutical cold chain and high-value electronics. Singapore and Thailand's free trade zones anchor regional distribution hub development for temperature-controlled cargo.
Established volume favors Standard Mail; emerging adoption favors E-commerce Solutions.
Delivery Mode:
Transport infrastructure investment tilts toward multimodal optimization as fuel costs and carbon regulations reshape routing decisions.
- Last Mile Delivery:Final-leg distribution to residential and commercial addresses through van fleets, motorcycle couriers, and locker networks. Vietnam's dense urban corridors and the Philippines' archipelago geography drive diverging fleet composition strategies.
- Air Freight:Time-critical cargo movement through belly-hold and dedicated freighter capacity connecting manufacturing clusters to consumer markets. Australia's remote population centers and Japan's island geography sustain premium air corridor development.
- Ground Transport:Surface freight via road and rail networks for cost-optimized bulk movement. China's highway system and India's Golden Quadrilateral route structure anchor regional trucking density.
- Sea Freight:Containerized and breakbulk maritime movement for non-urgent, high-volume cargo flows. Indonesia's inter-island trade and ASEAN manufacturing relocation patterns sustain archipelago-focused ferry and short-sea services.
Margin concentration sits with Last Mile Delivery; infrastructure scale advantages accrue to Ground Transport.
Customer Type:
Procurement sophistication varies sharply between individual consumers and institutional buyers with negotiated contract frameworks.
- Businesses:Corporate accounts with volume commitments, service-level agreements, and integrated supply-chain requirements. Manufacturing exporters in Vietnam's northern provinces and Malaysia's electronics zones drive B2B contract density.
- Government Agencies:Public sector procurement for administrative mail, benefit disbursement, and official document exchange. India's Department of Posts and Japan's Ministry of Internal Affairs and Communications sustain universal service mandates through state-affiliated operators.
- Individuals:Retail consumers purchasing single transactions through counter service or digital platforms. China's mobile-first consumer base and Southeast Asia's growing middle class expand C2C and B2C parcel origination.
- NGOs:Non-governmental organizations requiring humanitarian logistics, development program distribution, and mission-critical document handling. Disaster response corridors in the Philippines and Pacific Island territories sustain specialized service development.
Contract stability favors Government Agencies; volume expansion rates favor Businesses.
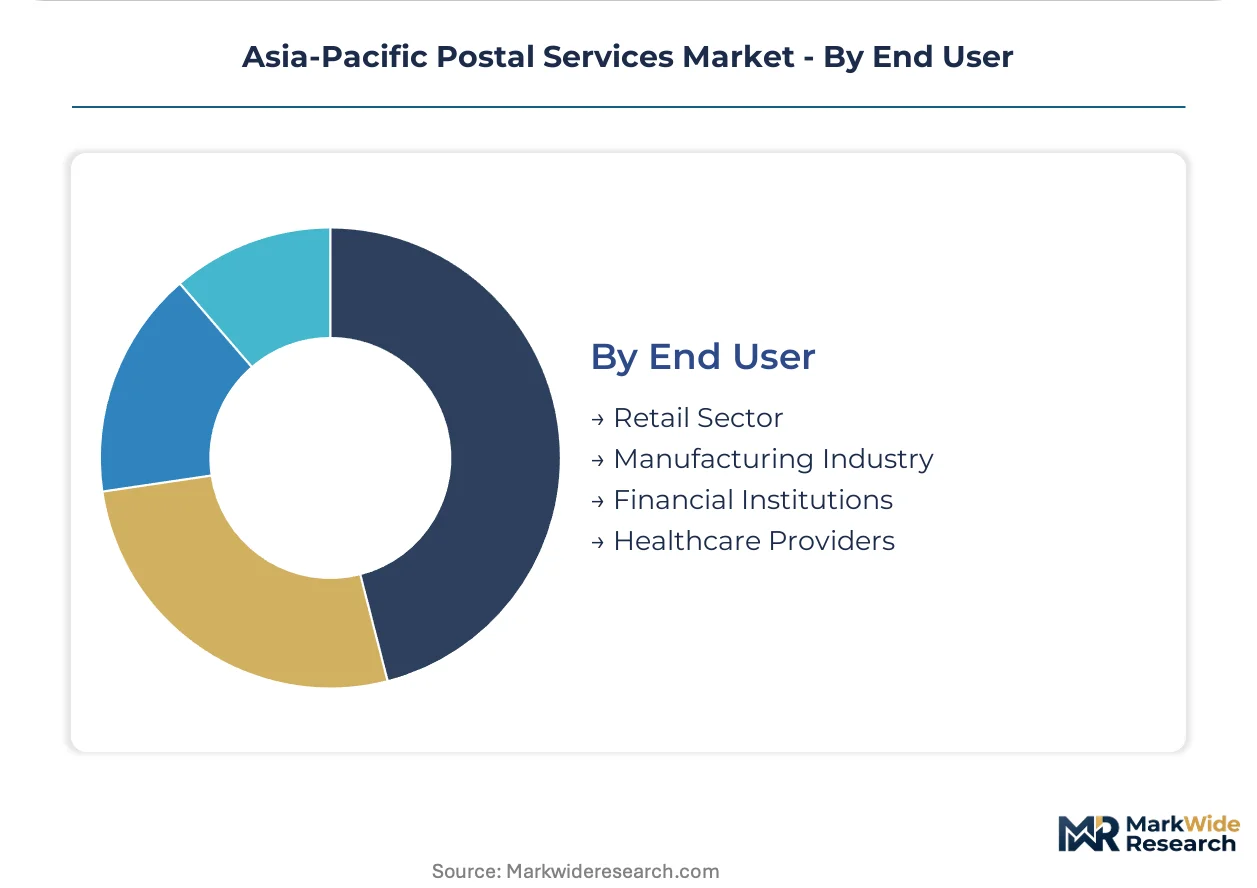
End User:
Industry-specific compliance requirements fragment service specifications across handling protocols and documentation standards.
- Healthcare Providers:Pharmaceutical distribution, clinical specimen transport, and medical device logistics with temperature monitoring and chain-of-custody documentation. Australia's TGA-equivalent pharmacovigilance requirements and Japan's PMDA cold chain standards shape certification demands.
- Financial Institutions:Secure document exchange, card delivery, and contractual instrument transportation with tamper-evident protocols. Singapore's banking sector and India's rural financial inclusion programs sustain specialized security service tiers.
- Retail Sector:Omnichannel fulfillment, returns processing, and inventory replenishment for brick-and-mortar and marketplace operations. China's live-commerce platforms and Southeast Asia's social commerce expansion drive fulfillment center proximity requirements.
- Manufacturing Industry:Just-in-time component delivery, spare parts distribution, and finished goods export logistics. South Korea's semiconductor supply chains and Thailand's automotive assembly corridors sustain time-definite manufacturing service tiers.
Compliance complexity favors Healthcare Providers; throughput scale favors Retail Sector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sorting hub capacity concentrates in China's eastern manufacturing belts, with secondary nodes emerging across Southeast Asian production corridors. State-affiliated operators leverage rural network density to preserve universal service coverage while commercial carriers capture premium express volumes in dense urban corridors.
China
Parcel throughput from Yangtze River Delta e-commerce fulfillment centers drives automated hub expansion at unprecedented scale. State Post Bureau tracking mandates force technology upgrades across tier-one and tier-two carrier networks. Shanghai and Shenzhen anchor last-mile density, though wage inflation erodes margin buffers for labor-intensive delivery operations.
Japan
Aging demographics sustain premium financial-services-integrated delivery demand through universal service obligations. Ministry of Internal Affairs and Communications delivery standards enforce strict service-level benchmarks that limit operational flexibility. METI logistics deregulation permits private carrier competition in letter-mail segments previously reserved for Japan Post.
India
Rural network digitization under the Digital India initiative transforms post offices into banking access points for unbanked populations. Department of Posts amendments to the Postal Act reshape market access thresholds for private competitors. Northern manufacturing provinces and the Golden Quadrilateral route structure anchor B2B contract density.
Vietnam
Factory relocation from China generates new origin-destination flows requiring integrated warehousing and customs brokerage. Dense urban corridors in Hanoi and Ho Chi Minh City drive diverging fleet composition strategies for last-mile optimization. The Vietnam-Indonesia manufacturing corridor sustains archipelago-focused logistics development.
Singapore
Cross-border e-commerce gateway positioning between ASEAN and China concentrates premium logistics margin pools. Free trade zone infrastructure anchors regional distribution hub development for temperature-controlled pharmaceutical cargo. API-integrated real-time rate quoting capabilities determine carrier selection at checkout moments for platform sellers.
Asia-Pacific Postal Services Market Competitive Environment
State-affiliated universal service operators and commercial express specialists split the market along regulatory access and speed-tier boundaries. Consolidation pressures concentrate around automated sorting infrastructure and last-mile network density. Three archetypes dominate: legacy postal administrations with rural banking integration, platform-aligned e-commerce logistics providers, and pharmaceutical cold chain specialists. Competitive moves center on hub automation capex cycles and strategic partnerships for customs-clearance integration.
Within the state-affiliated tier, China Post Group Corporation and Japan Post Co., Ltd. exemplify divergent modernization trajectories—one leveraging rural network density for financial inclusion, the other navigating banking-delivery hybrid complexity. Singapore Post Limited occupies a position at the cross-border gateway nexus, representing the platform-aligned archetype serving ASEAN-China trade lanes. These three entities anchor the competitive structure without exhausting its strategic variations.
| Leading Market Players |
|---|
| Australian Postal Corporation |
| Singapore Post Limited |
| China Post Group Corporation |
| Pos Indonesia |
| Pos Malaysia Berhad |
| Japan Post Co., Ltd. |
| Korea Post |
| Thailand Post |
| India Post |
| Others |
Value Chain & Pricing Dynamics
China's automated sorting equipment manufacturers anchor upstream supply concentration, directing margin pools toward operators with captive hub capacity and API-integrated rate quoting capabilities. State Post Bureau tracking mandates and platform seller checkout-moment algorithms compress pricing power toward real-time visibility compliance.
Pricing Analysis
Japan's Ministry of Internal Affairs and Communications delivery standards dictate the pricing tier structure across premium express and universal service obligations. Three-tier pricing structure across premium, standard, and economy levels segments buyers by time-definite guarantees and value-added financial integration. Price differentiation hinges on API connectivity for real-time tracking and customs pre-clearance bundling. Cost compression in tier-one Chinese last-mile operations is intensifying because wage inflation in Shanghai and Shenzhen erodes labor-intensive margins. E-commerce platform sellers exhibit the highest price sensitivity, while pharmaceutical cold chain buyers absorb premium tiers for EMA-equivalent pharmacovigilance certification.
Supply Chain Analysis
Extended payment terms from sorting equipment vendors and supply-chain finance facilities from Chinese state-affiliated banks shape upstream working capital dynamics. Hub automation hardware concentrates in China, Germany, and Japan. Robotics components and IoT sensor arrays draw from Taiwan and South Korea semiconductor foundries. Single-source vulnerability sits with proprietary sorting software licensing from dominant equipment OEMs. Distribution runs through tier-one city fulfillment centers with spoke-hub routing to ASEAN manufacturing corridors and rural India banking access points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital freight platforms and instant delivery apps represent the substitution threat that postal incumbents must navigate through infrastructure automation and financial services integration.
For Market Incumbents: Insulate core network density by accelerating rural post office digitization under India's Digital India template and securing pharmaceutical cold chain certification ahead of EMA-equivalent mandates. Automation technician training pipelines in India and Southeast Asia must expand to match robotics deployment speed. State-affiliated operators should leverage universal service obligations to defend against platform-aligned logistics entrants in cross-border gateway corridors. For New Entrants and Emerging Players: Vietnam-Indonesia manufacturing corridor warehousing and customs brokerage represent the most penetrable entry point for integrated origin-destination flow capture. Pharmaceutical cold chain certification gaps in Thailand and Singapore free trade zones offer specialized margin pool access. Go-to-market execution should anchor on API-integrated real-time rate quoting for platform seller checkout-moment algorithm placement. For Investors and Strategic Acquirers: Capital is best deployed toward automated sorting hub operators with ASEAN-China cross-border positioning and captive last-mile density in tier-two Chinese cities. Long-term viability rests on convergence of physical infrastructure with digital financial service layers. The signal to watch is METI logistics deregulation permitting private carrier letter-mail competition in Japan and similar regulatory shifts across ASEAN markets.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sorting Hub Expansion | China Post Group Corporation leverages Yangtze River Delta deployment to halve labor requirements per parcel batch. |
| Pharmaceutical Cold Chain Certification | Singapore free trade zone infrastructure anchors temperature-controlled cargo distribution for Australia's TGA-equivalent standards. |
| API-Integrated Rate Quoting | Platform seller checkout-moment algorithms concentrate volume with carriers offering real-time customs pre-clearance bundling. |
| Rural Network Digitization | India Post transforms 150,000 access points into banking channels for unbanked populations under Digital India mandates. |
| Cross-Border Gateway Positioning | Singapore Post Limited captures ASEAN-China trade lane premium through multimodal customs brokerage integration. |
Study Parameters
Initial hypotheses were tested against primary input from postal operations executives, e-commerce logistics procurement leads, pharmaceutical supply chain managers, and automation technology vendors and refined through secondary validation. Primary fieldwork encompassed structured interviews with China State Post Bureau regional directors, Japan Post Co., Ltd. financial services integration specialists, and India Department of Posts rural digitization officers. Secondary sources included State Post Bureau parcel tracking mandate filings, METI logistics deregulation notices, India Postal Act amendment records, and ASEAN customs harmonization protocols. Bottom-up volume modeling and top-down macroeconomic overlay triangulation converged on segment-level estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed service type, delivery mode, customer archetype, and end-use industry vertical with regional regulatory cluster overlay. CAGRs were derived from parcel throughput trajectory analysis and e-commerce platform GMV correlation. Forecast inputs incorporated fuel price volatility scenarios for surface and air freight segments and automation capex cycle timing from equipment vendor order backlogs.
Macroeconomic conditions sit as an overlay; deviation in diesel and aviation kerosene price trajectories, wage inflation in Chinese tier-one cities, or ASEAN manufacturing relocation velocity would shift the trajectory. Forecasts reflect assumptions on regulatory labor protection enforcement and platform seller delivery guarantee bundling persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Global Audio Communication Monitoring Market
Communication Services
Global Critical Communication Market
Communication Services
Managed Communication Services Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
Latin America Postal Service Market
Communication Services
Broadcasting Solutions Market
Communication Services
Walkie Talkie Market
Communication Services
Postal Services Market
Communication Services
Voip Services Market
Communication Services
Web Conferencing Market
Communication Services
Dispatch Console Market
Communication Services
Mobile Messaging Market
Communication Services
North America Postal Services Market
Communication Services
Outbound Telemarketing Market
Communication Services
Contact Center As a Service (Ccaas) Market