
 Global Audio Communication Monitoring Market | 2026-2036
Global Audio Communication Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Audio Communication Monitoring Market Analysis
Cloud-native speech analytics is reconfiguring how audio communication monitoring platforms are architected and delivered, shifting from legacy on-premise appliances to API-driven, elastic infrastructure. NICE Ltd leverages its established presence in workforce optimization to anchor cloud migration strategies for enterprise clients. Verint Systems competes through specialized compliance modules that address financial sector requirements. AudioCodes sustains hardware-software integration advantages in hybrid deployment environments.
Audio communication monitoring encompasses the capture, storage, transcription, and analysis of voice interactions using speech recognition engines, natural language processing pipelines, and real-time alerting algorithms to ensure regulatory compliance, quality assurance, and operational intelligence. The primary commercial purpose centers on transforming unstructured voice data into auditable, actionable records for risk management and customer experience optimization. Software solutions lead the product type landscape due to recurring revenue models and faster feature iteration cycles, while cloud-based deployment is expanding fastest as enterprises retire capital-intensive on-premise infrastructure. The call center application segment commands the largest current revenue pool, though surveillance applications are gaining traction in government and critical infrastructure settings where lawful intercept requirements intensify.
The Federal Communications Commission shapes market access through call recording consent frameworks, while the SEC and FINRA mandate retention and surveillance standards for broker-dealer voice communications. The EU AI Act introduces algorithmic transparency obligations for automated speech analysis systems processing biometric data. Stakeholders must monitor evolving cross-border data localization requirements that threaten to fragment cloud delivery architectures and force region-specific infrastructure investments.
Market Dynamics
Cloud-native speech analytics is collapsing the traditional on-premise appliance model, forcing vendors to rebuild architecture around API elasticity and consumption-based pricing. Financial services compliance mandates from the SEC and FINRA are accelerating this infrastructure transition.
Growth Catalysts
- EU AI Act algorithmic transparency rules:Biometric voice data processing requirements are expanding procurement of auditable speech analytics pipelines across European banking and insurance sectors.
- Real-time transcription engines:Latency improvements below 200 milliseconds are enabling live compliance alerting during broker-dealer calls, replacing post-hoc review workflows.
- United States contact center concentration:Large-scale operations in Texas, Florida, and Arizona are driving demand for scalable capture infrastructure handling millions of daily interactions.
Market Restraints
- GPU compute cost volatility:Speech recognition model inference depends on NVIDIA H100 availability, with pricing swings compressing vendor margins on cloud-hosted offerings.
- Cross-border data localization mandates:Germany, France, and India are imposing residency requirements that fragment cloud architectures and force redundant infrastructure deployment.
- Legacy PBX integration complexity:Hybrid environments combining SIP trunking with TDM circuits create audio quality degradation that undermines transcription accuracy.
Strategic Opportunities
- Brazilian financial sector modernization:ANVISA and B3 exchange compliance upgrades are opening procurement windows for cloud-native monitoring platforms in Latin America's largest economy.
- Convergence of voice biometrics with sentiment analysis:Unified pipelines detecting speaker identity and emotional state simultaneously are creating premium pricing tiers for fraud prevention applications.
- API-first distribution through CCaaS platforms:Native integrations with Genesys, Five9, and Amazon Connect are displacing direct enterprise sales cycles.
Industry Challenges
- Computational linguist talent scarcity:Recruitment of phoneticians and NLP engineers fluent in low-resource languages is bottlenecking product localization for Middle Eastern and Southeast Asian markets.
- FedRAMP authorization timelines:Cloud providers seeking US federal contracts face 12-18 month certification delays that freeze public sector revenue pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Audio Communication Monitoring Market |
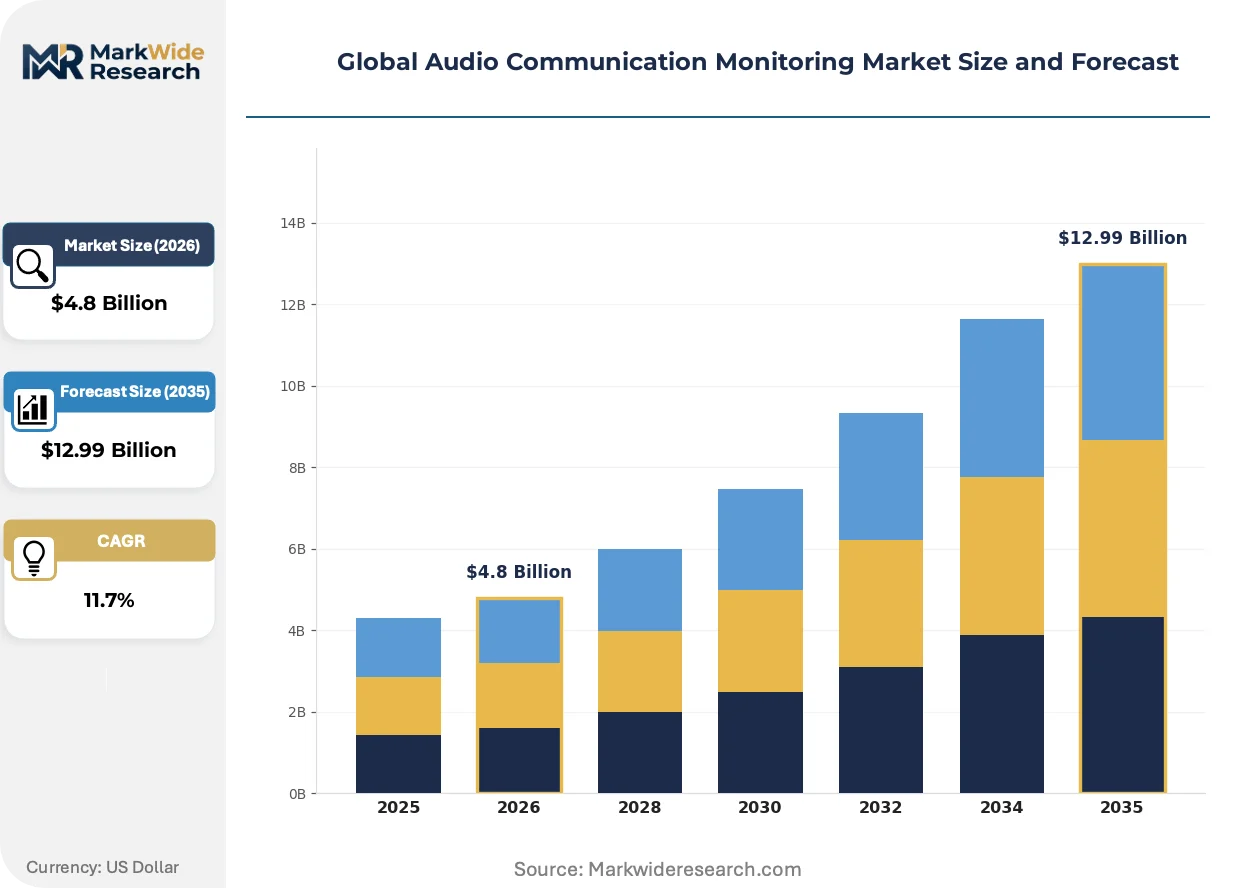
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Integrated Solutions, Accessories End User: Corporate, Government, Healthcare, Education Deployment: On-premise, Cloud-based, Hybrid, Remote Application: Call Center, Surveillance, Quality Assurance, Research |
| Companies Covered | Verint Systems, NICE Ltd, CallMiner, Cisco Systems, IBM Corporation, Enghouse Interactive, AudioCodes, Nexidia, Nuance Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Audio Communication Monitoring Market Emerging Trajectories
Audio communication monitoring is undergoing architectural decoupling, with capture, storage, and analytics layers separating into interchangeable components. This modularity is enabling vertical specialization and faster feature iteration.
Transformer-based speech recognition is collapsing the accuracy gap between cloud and edge deployment. On-device models from NVIDIA and Qualcomm are achieving word-error rates within 2% of datacenter baselines. Financial trading floors and air-gapped government facilities are adopting these edge configurations to satisfy latency and security requirements without sacrificing transcription quality.
The EU AI Act's biometric data classification is forcing disclosure of training datasets and model performance metrics for emotion detection systems. Vendors serving European enterprises must now document demographic bias testing and maintain algorithmic change logs. Compliance teams in Frankfurt and Paris are expanding headcount to manage these documentation burdens.
Subscription fatigue among enterprise buyers is compressing vendor switching cycles from multi-year contracts to annual or even quarterly evaluations. Procurement functions in US healthcare and insurance verticals are unbundling capture infrastructure from analytics software, creating openings for best-of-breed specialists. This fragmentation favors vendors with open APIs over integrated suite providers.
Global Audio Communication Monitoring Market Segmentation
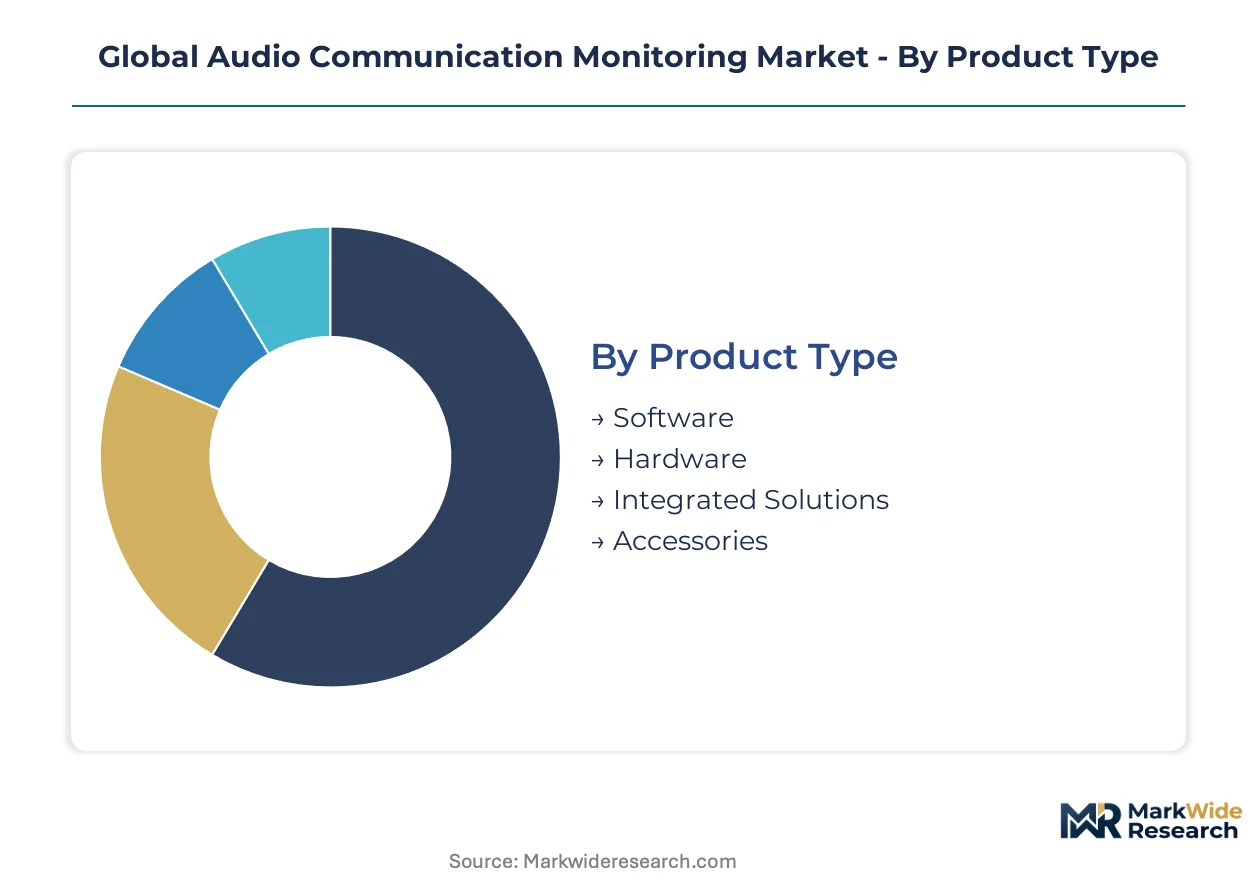
Audio communication monitoring vendors must navigate divergent buyer requirements across deployment architectures, compliance regimes, and operational scales. Segmentation reveals where cloud-native solutions displace legacy infrastructure and which verticals command premium pricing for specialized capture capabilities.
Product Type:
Mature on-premise hardware lines coexist with rapidly scaling software-as-a-service offerings, creating a bifurcated procurement landscape.
- Software:Cloud-native speech analytics platforms deliver API-driven capture, transcription, and alerting through consumption-based licensing. Financial services procurement teams in New York and London favor this model for FINRA and FCA compliance workflows.
- Hardware:Dedicated recording appliances with onboard storage and DSP processing serve air-gapped government facilities and trading floors where network egress is prohibited. German KBA-regulated automotive call centers retain these deployments for data sovereignty.
- Integrated Solutions:Bundled hardware-software stacks from single vendors reduce integration complexity for mid-market buyers.
- Accessories:Specialized microphones, logging adapters, and compliance-grade storage media address niche retrofit requirements.
Software retains volume leadership; integrated solutions hold the steepest expansion curve as hybrid buyers seek simplified procurement.
End User:
Cost-tier stratification separates compliance-heavy regulated industries from price-sensitive institutional buyers.
- Corporate:Multinational banks and insurers deploy enterprise-wide monitoring for SEC, FINRA, and GDPR adherence. JPMorgan Chase and similar institutions mandate retention periods exceeding seven years for voice communications.
- Government:Lawful intercept requirements and classified facility security protocols drive specialized procurement cycles. Saudi SFDA and UAE MOHAP facilities in Riyadh and Abu Dhabi require Arabic-language transcription with speaker diarization.
- Healthcare:HIPAA-covered entities in Texas and Florida monitor patient service lines for quality assurance and liability protection.
- Education:University contact centers and research institutions prioritize cost efficiency over advanced analytics.
Corporate spending dominates absolute revenue; government contracts deliver the highest per-seat pricing premiums.
Deployment:
Volume concentration tilts toward cloud migration, though latency-sensitive and sovereign-constrained workloads sustain alternative architectures.
- Cloud-based:Elastic infrastructure scales from thousands to millions of daily interactions without capital expenditure. Amazon Web Services and Microsoft Azure host the majority of new deployments for US healthcare and insurance verticals.
- On-premise:Captive data centers satisfy FedRAMP, GDPR, and sector-specific residency mandates. Swiss banking clients in Zurich and Geneva require on-site retention for FINMA oversight.
- Hybrid:Split architectures route sensitive traffic to private infrastructure while leveraging cloud analytics for non-regulated workloads.
- Remote:Edge-deployed capture agents serve distributed workforces without centralized infrastructure.
Cloud-based deployments capture the majority of new seats; hybrid configurations are climbing the fastest as enterprises navigate transitional compliance states.
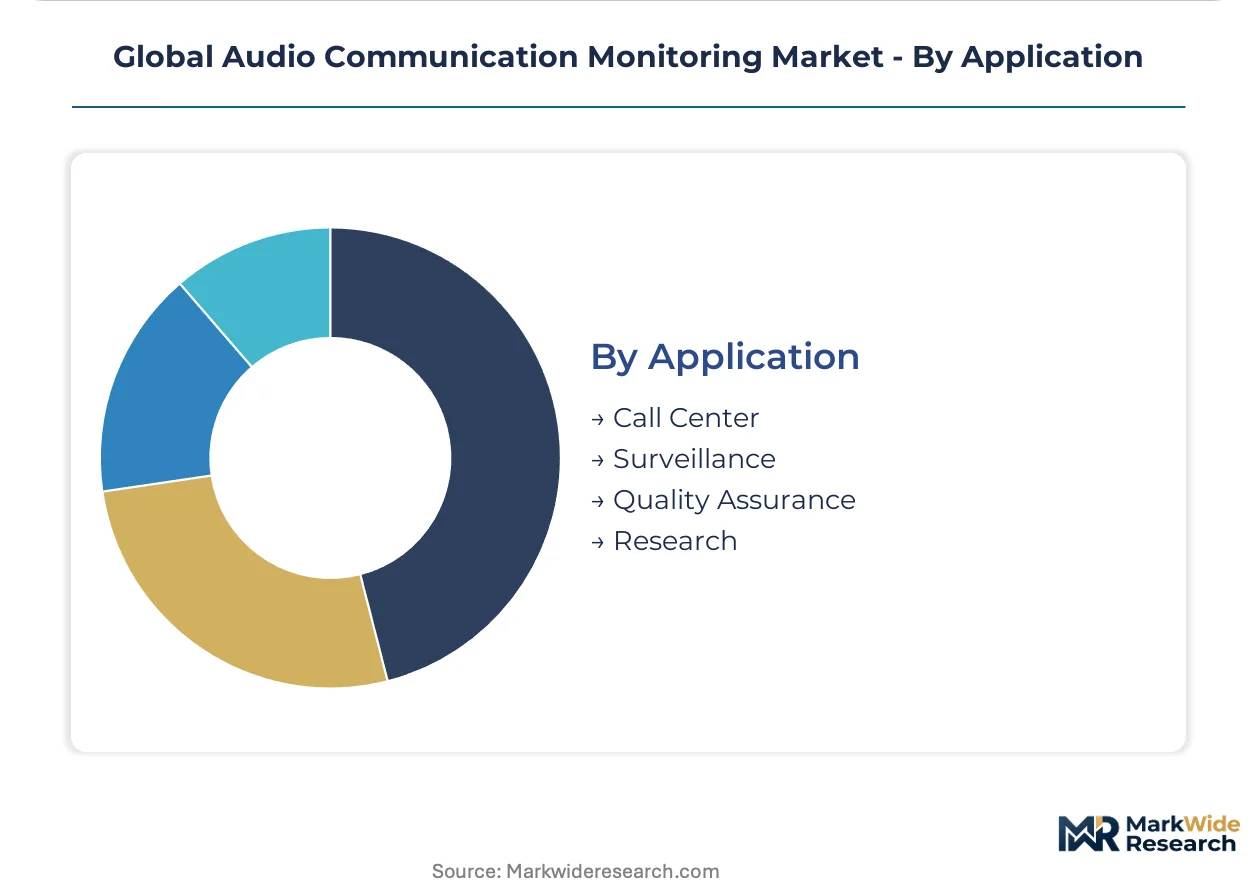
Application:
Customer-facing use cases generate recurring revenue through seat-based licensing, while surveillance applications demand project-based capital outlays.
- Call Center:Real-time quality monitoring, agent coaching, and customer satisfaction scoring drive the largest installed base. Philippine BPO clusters in Manila and Cebu deploy multi-tenant platforms serving US and Australian clients.
- Surveillance:Lawful intercept, critical infrastructure protection, and counter-terrorism applications require specialized metadata tagging and chain-of-custody documentation. Indian Ministry of Home Affairs facilities mandate domestic data residency under CERT-In guidelines.
- Quality Assurance:Post-call analytics identify compliance breaches and coaching opportunities in regulated sales environments.
- Research:Academic and commercial R&D teams apply conversation analysis to behavioral science and product development studies.
Call Center applications retain volume leadership; Surveillance holds the steepest expansion curve amid heightened critical infrastructure protection mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel exports speech recognition technology to financial services buyers in New York and London. German vendors supply compliance-grade recording infrastructure to Swiss banking clients in Zurich. Indian IT services firms deliver transcription platforms to Australian healthcare contact centers.
United States
SEC and FINRA enforcement actions drive broker-dealer procurement of real-time monitoring systems. The Federal Communications Commission maintains call recording consent frameworks that shape vendor compliance architecture. Texas and Florida contact center clusters deploy cloud-native capture infrastructure handling millions of daily customer interactions.
Germany
GDPR biometric data rules and the EU AI Act force disclosure of training datasets for emotion detection systems. KBA automotive regulations retain on-premise recording appliances for data sovereignty in Stuttgart and Munich call center operations. Frankfurt compliance teams expand headcount to manage algorithmic documentation burdens.
United Kingdom
FCA voice communication retention mandates accelerate replacement of legacy tape-based systems. The Financial Services and Markets Act shapes surveillance requirements for London trading floors. Scottish government facilities in Edinburgh adopt lawful intercept configurations for critical infrastructure protection.
India
CERT-In data localization guidelines mandate domestic residency for government surveillance deployments. RBI compliance requirements expand procurement of transcription platforms across Mumbai and Bangalore banking operations. Hyderabad BPO clusters serve US healthcare clients under HIPAA-aligned contractual frameworks.
Brazil
ANVISA pharmaceutical compliance and B3 exchange surveillance upgrades open procurement for cloud-native platforms. The country's national securities regulator tightens broker-dealer communication retention standards. São Paulo financial services firms modernize legacy infrastructure to satisfy cross-border audit requirements.
Global Audio Communication Monitoring Market Vendor Landscape
Channel-controlling players compete with product-specialist players across deployment architecture segments. The vendor base clusters around three tiers: workforce optimization incumbents with established enterprise relationships, compliance-focused specialists addressing financial sector requirements, and hardware-integrated providers serving hybrid infrastructure environments. Dominant competitive moves include API-first distribution partnerships with CCaaS platforms and M&A activity targeting real-time transcription capabilities.
Within the workforce optimization tier, NICE Ltd and Verint Systems occupy positions shaped by cloud migration service portfolios. AudioCodes anchors the hardware-software integration segment with hybrid deployment advantages. These three companies exemplify how competitive positioning diverges between API-driven elasticity and captive infrastructure control.
| Leading Market Players |
|---|
| Verint Systems |
| NICE Ltd |
| CallMiner |
| Cisco Systems |
| IBM Corporation |
| Enghouse Interactive |
| AudioCodes |
| Nexidia |
| Nuance Communications |
| Others |
Supply Flow & Price Mechanics
GPU compute cost volatility determines both pricing tier spreads and supply chain shape in audio communication monitoring, compressing margins on cloud-hosted offerings while forcing vendors toward hardware-software integration strategies that hedge against NVIDIA H100 availability constraints.
Pricing Analysis
Cloud-native speech analytics platforms command premium positioning over legacy on-premise appliances, with on-device edge models from NVIDIA and Qualcomm occupying a mid-tier value band. Three-tier pricing structure across premium, standard, and economy levels separates real-time compliance alerting with sub-200ms latency from batch transcription and basic capture-only configurations. Price differentiation rests on FINRA certification grade and customization depth for broker-dealer workflows. Cost compression in the economy tier is intensifying because API-first CCaaS distribution displaces direct enterprise sales cycles. Healthcare and insurance verticals exhibit the highest price sensitivity, while government surveillance buyers accept substantial premiums for air-gapped deployments.
Supply Chain Analysis
Extended payment terms from hyperscaler cloud providers are squeezing component suppliers and reshaping working capital requirements across the ecosystem. Hardware assembly concentrates in Taiwan, South Korea, and China, with specialized DSP processors and compliance-grade storage media sourced from Japanese and German manufacturers. Raw material dependencies include NVIDIA GPUs for inference acceleration, high-fidelity microphone arrays from Knowles and AAC Technologies, and encrypted solid-state drives for chain-of-custody retention. Single-source vulnerability around NVIDIA H100 supply threatens platform scalability for real-time transcription vendors. Distribution runs through direct enterprise sales teams for government and financial services accounts, while CCaaS platform partnerships increasingly handle mid-market volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as cloud-native migration accelerates and regulatory mandates from the EU AI Act and SEC enforcement actions expand addressable demand across banking, insurance, and government verticals.
For Market Incumbents: Entrench cloud infrastructure control by expanding FedRAMP authorization pipelines and deepening API integrations with Genesys, Five9, and Amazon Connect platforms. Acquire real-time transcription specialists to defend against edge-deployment challengers from NVIDIA and Qualcomm. Prioritize backward integration into GPU provisioning or secure long-term allocation agreements with NVIDIA to stabilize cost structures.
For New Entrants and Emerging Players: Build out specialized compliance modules for Brazilian ANVISA pharmaceutical requirements and Indian CERT-In data localization mandates, where incumbent presence remains thin. Target hybrid deployment architectures in German automotive and Swiss banking verticals as the most penetrable segment. Pursue channel partnerships with regional system integrators rather than direct enterprise sales to accelerate credibility.
For Investors and Strategic Acquirers: The market sits at an infrastructure-transition phase that favors vertical-specialist acquisition targets with proven regulatory certifications and API-first architectures. Long-term viability hinges on cloud-native delivery models that capture recurring revenue and escape capital-intensive hardware cycles. Monitor hyperscaler capex disclosure trends for GPU allocation as the signal to watch for platform scalability inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Transcription Engine Development | Sub-200ms latency enables live FINRA compliance alerting during broker-dealer calls. |
| API-First CCaaS Platform Integration | Native Genesys and Amazon Connect partnerships displace direct enterprise sales cycles. |
| Edge Deployment Architecture | On-device models from NVIDIA satisfy air-gapped government facility security requirements. |
| EU AI Act Compliance Documentation | Algorithmic transparency logs and bias testing expand Frankfurt and Paris compliance headcount. |
| Voice Biometrics-Sentiment Convergence | Unified pipelines detecting speaker identity and emotional state unlock fraud prevention premiums. |
Methodological Framework
Initial hypotheses were tested against primary input from compliance officers at multinational banks, contact center operations directors, government procurement managers, and speech recognition engineering leads, and refined through secondary validation against SEC enforcement records, FINRA regulatory filings, EU AI Act documentation, hyperscaler capex disclosures, and customs data for recording hardware imports. Bottom-up seat-count modeling across deployment architectures and verticals was triangulated against top-down market sizing from vendor revenue disclosures and channel partner interviews.
Demand-supply balance framing anchored the forecast framework, with elastic cloud capacity expansion modeled against GPU availability constraints and on-premise hardware refresh cycles across the projection horizon. Segmentation dimensions included deployment model, end-user vertical, application type, and geographic regulatory cluster. CAGRs were derived from fitted adoption curves weighted by compliance mandate effective dates and cloud migration velocity. Industry-specific inputs incorporated broker-dealer voice communication retention requirements and BPO seat concentration in Philippine and Indian delivery centers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed challengers or rapid edge-AI commoditization would shift outcomes beyond modeled ranges. Macroeconomic contraction in financial services hiring, accelerated EU AI Act enforcement, or sustained NVIDIA supply disruption would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Contact Center As a Service (Ccaas) Market
Communication Services
Voice Commerce Market
Communication Services
High Performance Message Infrastructure Market
Communication Services
Dispatch Console Market
Communication Services
Industrial Communication Market
Communication Services
Cloud Communication Platform Market
Communication Services
Walkie Talkie Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
Speech to Speech Translation Market
Communication Services
Asia-Pacific Postal Services Market
Communication Services
Enterprise Communication Infrastructure Market
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
Audio Conferencing Services Market
Communication Services
Global Passenger Information System Market
Communication Services
Global Call Center Platform Market
Communication Services
Video Conferencing Market