
 Cutting Equipment Market | 2026-2036
Cutting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cutting Equipment Market Analysis
EU CE marking under the Machinery Directive is recalibrating the cost-of-entry calculus for cutting equipment imports into European fabrication shops. Hypertherm, Inc. leverages its plasma power source specialization to sustain premium positioning across North American shipyards. TRUMPF SE + Co. KG anchors its competitive stance through in-house production of fiber laser resonators and beam delivery systems. ESAB Corporation differentiates via comprehensive welding-cutting integration and channel control in emerging industrial clusters.
Cutting equipment encompasses mechanized systems that sever workpiece materials through thermal, abrasive, or mechanical action, with fiber laser cutters achieving kerf widths below 0.2 millimeter at power densities exceeding 10^6 watts per square centimeter. These systems serve primary industrial purposes in metal fabrication, stone processing, and composite trimming where dimensional precision directly determines downstream assembly fit. Laser cutters command the dominant margin pool in advanced manufacturing, while water jet cutters represent the fastest-growing category for heat-sensitive alloys and stacked composites. Plasma cutters retain volume leadership in heavy structural steel, with CO2 technology yielding share to fiber optic platforms across automotive stamping operations.
FDA oversight of medical device manufacturing imposes particulate and validation standards that shape cutting equipment specifications for implant-grade titanium suppliers. EPA air emissions rules and OSHA metalworking fluid exposure limits further constrain wet cutting process selection in US job shops. Stakeholders must monitor how NHTSA lightweighting mandates for electric vehicle platforms redirect capital toward high-speed laser blanking versus traditional mechanical shear lines.
Market Dynamics
Fiber laser technology is consolidating market position as ISO 9013 tolerance requirements tighten across aerospace and automotive stamping operations, forcing capital redeployment away from CO2 platforms.
Growth Catalysts
- ISO 9013 Precision Mandates:Aerospace manufacturers in Germany and Japan are expanding fiber laser procurement to meet tighter kerf tolerance specifications for titanium and aluminum airframe components.
- China MIIT Domestic Substitution:China's Ministry of Industry and Information Technology certification push redirects public procurement toward locally certified plasma cutting platforms.
- EV Lightweighting Imperatives:NHTSA mandates for electric vehicle platform weight reduction accelerate laser blanking adoption versus traditional mechanical shear lines in US stamping operations.
Market Restraints
- Fiber Laser Resonator Supply Concentration:German and Japanese suppliers dominate high-power resonator production, creating input bottlenecks for systems above 6 kilowatts.
- CE Marking Compliance Burden:EU Machinery Directive recertification costs recalibrate cost-of-entry calculus for non-European equipment imports into European fabrication shops.
- Plasma Cutting Substitution Pressure:Water jet systems capture heat-sensitive alloy applications where thermal distortion risks disqualify plasma and laser alternatives.
Strategic Opportunities
- Medical Device Manufacturing Certification:FDA particulate and validation standards for implant-grade titanium create premium specification tiers for cutting equipment suppliers serving orthopedic implant manufacturers.
- Stacked Composite Trimming:Water jet abrasive cutting converges with robotic handling systems to address aerospace composite layup trimming where fiber laser heat damage remains prohibitive.
- Channel Control in Emerging Clusters:Direct service presence in Vietnamese and Indonesian fabrication hubs bypasses distributor margin stacking for high-volume shipyard and infrastructure steel cutting.
Industry Challenges
- Fiber Laser Technician Scarcity:Beam alignment and resonator maintenance expertise concentrates among technicians trained on specific German and Japanese OEM platforms.
- Legacy CO2 System Stranding:Integration complexity with existing mechanical shear lines and press brake workflows slows fiber laser adoption in job shops with depreciated capital equipment.
- EPA Wet Cutting Compliance:Metalworking fluid exposure limits and air emissions rules constrain process selection in US facilities running plasma and water jet systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutting Equipment Market |
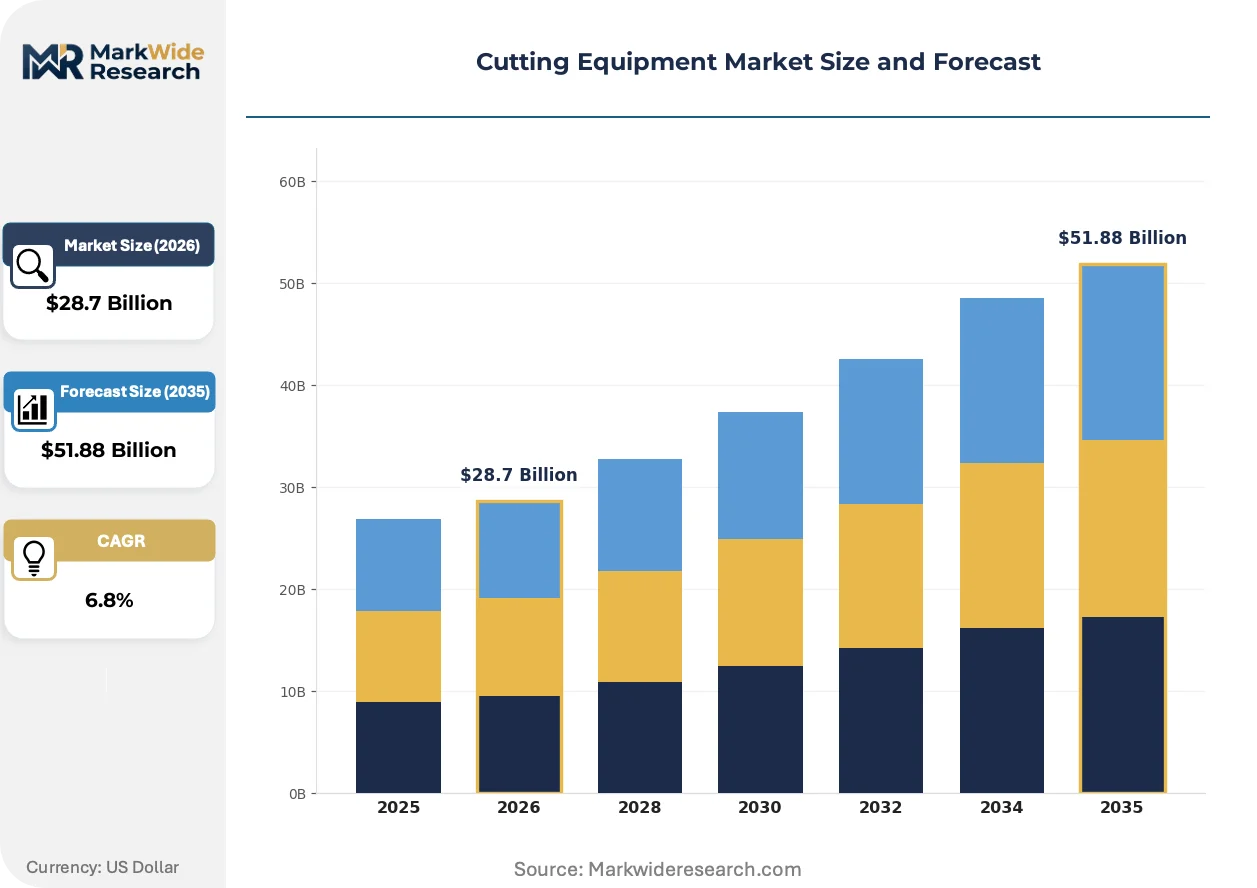
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Cutters, Plasma Cutters, Water Jet Cutters, Band Saws Technology: Fiber Optic, CO2, Mechanical, Electric End User: Manufacturing, Construction, Automotive, Aerospace Application: Metal Fabrication, Stone Cutting, Woodworking, Plastics |
| Companies Covered | Hypertherm, Inc., The Lincoln Electric Company, TRUMPF SE + Co. KG, ESAB Corporation, AMADA WELD TECH, Bystronic AG, Koike Aronson, Inc., Illinois Tool Works, OMAX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutting Equipment Market Emerging Trajectories
Equipment specification is pivoting toward multi-process integration as fabricators seek to consolidate vendor relationships and reduce floor space requirements across thermal and abrasive cutting modalities.
Fiber laser technology is consolidating its position in metal fabrication through power scaling above 12 kilowatts and beam delivery optimization. Automotive stamping operations in Germany and Japan are adopting these platforms at accelerated replacement cycles. This consolidation is compressing CO2 laser service revenue pools and forcing legacy suppliers to pivot toward aftermarket parts and retrofit kits.
REACH substance restrictions and RoHS compliance requirements are reshaping consumables specification for plasma cutting electrodes and nozzles. European fabricators face sourcing transitions for tungsten and hafnium-based components. Water jet garnet abrasive suppliers serving EU markets are accelerating certified supply chain documentation to preempt enforcement actions.
Buyer concentration among tier-one automotive and aerospace OEMs is compressing equipment procurement cycles and unbundling after-sales service contracts. Direct manufacturer service agreements are displacing independent distributor maintenance networks in North American and European markets. This pattern is most visible in German automotive stamping operations where single-source vendor relationships now cover cutting, welding, and automation integration.
Cutting Equipment Market Segmentation
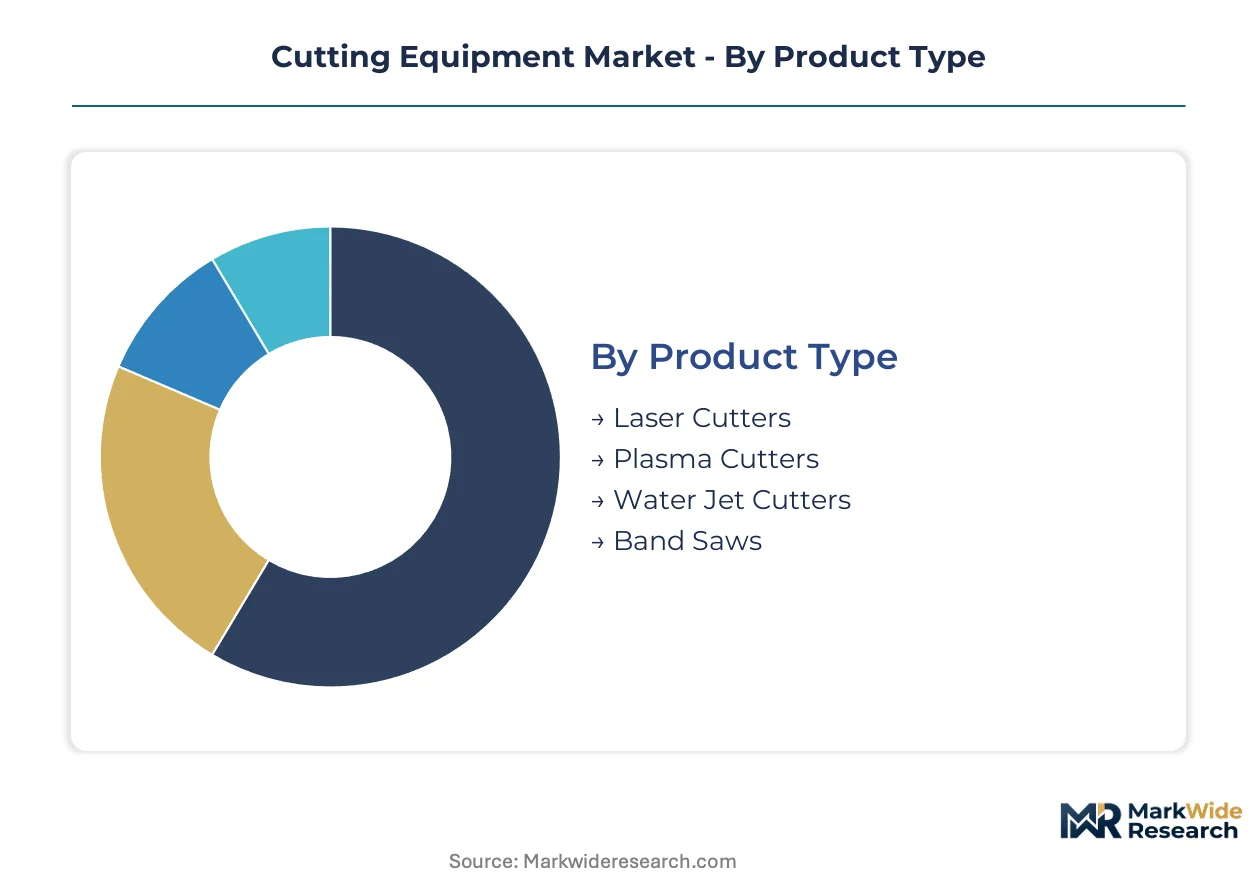
Cutting equipment procurement patterns diverge sharply across technology platforms and end-use specifications. Equipment selection hinges on material thickness tolerances, thermal sensitivity constraints, and integration complexity with existing fabrication workflows.
Product Type:
Technology specifications and power density thresholds define competitive positioning across mechanized severing platforms.
- Laser Cutters:Fiber laser systems achieve kerf widths below 0.2 millimeter at power densities exceeding 10^6 watts per square centimeter. Aerospace manufacturers in Germany and Japan are expanding procurement to meet tightening ISO 9013 tolerance requirements for titanium airframe components.
- Plasma Cutters:Thermal arc systems dominate heavy structural steel severing through compressed gas jet acceleration. China's MIIT domestic substitution push redirects public procurement toward locally certified plasma platforms for infrastructure steel processing.
- Water Jet Cutters:Abrasive jet systems address heat-sensitive alloys and stacked composites where thermal distortion risks disqualify thermal alternatives. EPA metalworking fluid exposure limits constrain wet process selection in US job shops.
- Band Saws:Mechanical tooth systems serve bulk material sectioning and rough dimensioning prior to precision finishing operations.
Mature deployment sits with plasma cutters in heavy structural applications. Newer deployment is concentrated in water jet systems for aerospace composite trimming.
Technology:
Resonator architecture and beam delivery mechanisms determine capital intensity and operating cost structures.
- Fiber Optic:Solid-state laser platforms consolidate market position through power scaling above 12 kilowatts. Automotive stamping operations in Germany and Japan are accelerating replacement cycles away from legacy CO2 systems.
- CO2:Gas laser technology yields share to fiber platforms across automotive stamping operations. Integration complexity with existing mechanical shear lines slows adoption in job shops with depreciated capital equipment.
- Mechanical:Physical force severing through saw blades and shears retains volume in rough dimensioning and bulk material breakdown.
- Electric:Arc-based thermal severing serves specialized alloy applications where precise heat input control determines metallurgical properties.
Volume concentration remains with fiber optic platforms in precision fabrication. Technology transition pressure concentrates in CO2 system retrofit demand.
End User:
Regulatory mandates and capital cycle timing reshape equipment specification across industrial clusters.
- Manufacturing:General fabrication shops face legacy CO2 system stranding as fiber laser technician scarcity concentrates expertise among German and Japanese OEM-trained specialists.
- Construction:Infrastructure steel processors prioritize plasma cutting throughput over precision tolerances. CE marking compliance burdens recalibrate cost-of-entry for non-European equipment imports into European fabrication shops.
- Automotive:NHTSA lightweighting mandates for electric vehicle platforms accelerate laser blanking adoption versus traditional mechanical shear lines in US stamping operations.
- Aerospace:FDA particulate and validation standards for implant-grade titanium create premium specification tiers for orthopedic implant manufacturers.
Specification complexity peaks in aerospace procurement. Capital redeployment velocity runs highest in automotive stamping.
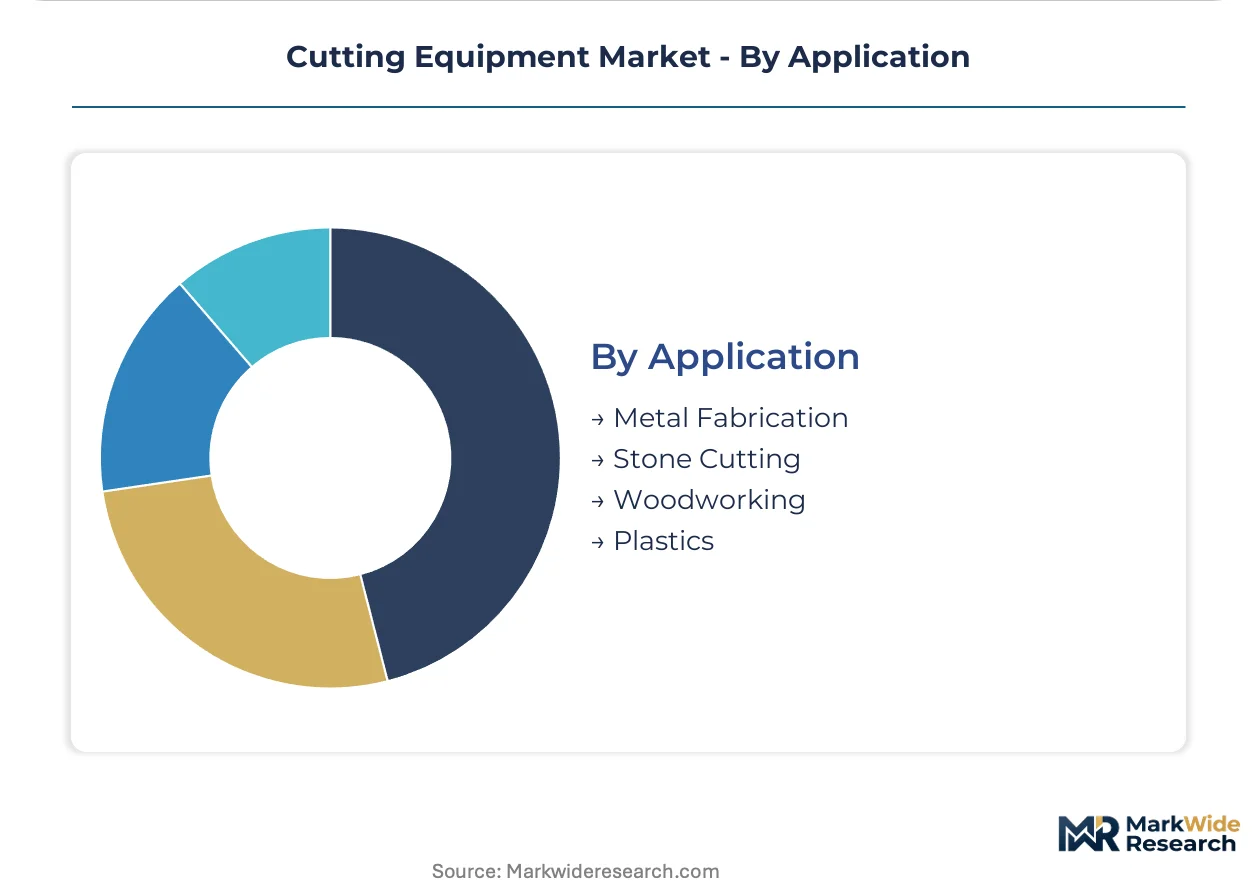
Application:
Material properties and dimensional precision requirements dictate process selection and consumables specification.
- Metal Fabrication:Thermal and abrasive severing systems serve primary industrial purposes where dimensional precision determines downstream assembly fit. REACH substance restrictions reshape consumables sourcing for plasma electrodes.
- Stone Cutting:Abrasive water jet systems dominate dimensional stone processing where thermal fracture risks disqualify laser alternatives.
- Woodworking:Mechanical sawing retains cost efficiency in dimensional lumber processing and millwork fabrication.
- Plastics:Thermal severing requires precise heat input control to prevent polymer degradation and edge quality deterioration.
Margin pool depth concentrates in metal fabrication. Process diversification pressure runs strongest in plastics applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial free-trade zones in Vietnam and Indonesia are drawing fabrication equipment procurement away from traditional Northeast Asian supply chains. Mexico's IMMEX program accelerates capital redeployment toward automotive stamping corridors serving US electric vehicle assembly.
United States
NHTSA lightweighting mandates for electric vehicle platforms accelerate laser blanking adoption versus traditional mechanical shear lines. EPA air emissions rules and OSHA metalworking fluid exposure limits constrain wet cutting process selection in Midwest job shops. Detroit-area stamping operations are consolidating vendor relationships around single-source cutting-welding-automation integration.
Germany
Aerospace manufacturers in Bavaria and Baden-Württemberg are expanding fiber laser procurement to meet tightening ISO 9013 tolerance requirements for titanium airframe components. CE marking under the EU Machinery Directive recalibrates cost-of-entry for non-European equipment imports into Stuttgart and Hamburg fabrication clusters. German automotive OEMs are unbundling after-sales service contracts in favor of direct manufacturer agreements.
China
MIIT domestic substitution certification redirects public procurement toward locally certified plasma cutting platforms for infrastructure steel processing. Yangtze River Delta fabricators face fiber laser resonator supply concentration above 6 kilowatts from German and Japanese sources. Shenzhen and Dongguan equipment assemblers are accelerating backward integration into beam delivery system production.
Japan
METI industrial technology roadmaps prioritize fiber laser power scaling above 12 kilowatts for automotive stamping operations in Aichi and Kanagawa prefectures. JIS standards alignment with ISO 9013 tolerances tightens specification windows for aerospace suppliers in Nagoya. Japanese OEM-trained technician scarcity concentrates beam alignment expertise among legacy platform specialists.
Vietnam
Deep-water port infrastructure in Hai Phong and Ba Ria-Vung Tau supports direct manufacturer service presence bypassing distributor margin stacking. Vietnamese shipyards and infrastructure steel processors prioritize plasma cutting throughput over precision tolerances. Foreign fabricators in northern industrial zones face CE marking compliance burdens for European-bound component exports.
Cutting Equipment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology platforms and geographic markets. The vendor base stratifies around three archetypes: German-Japanese resonator specialists controlling high-power fiber laser inputs, American plasma power source pure-plays dominating North American shipyards, and diversified welding-cutting integrators capturing emerging industrial clusters. Consolidation pressure concentrates in aftermarket service networks and multi-process automation integration.
Among German-based precision equipment fabricators, TRUMPF SE + Co. KG and Bystronic AG exemplify the resonator-specialist archetype through in-house production of beam delivery systems. American pure-plays Hypertherm, Inc. and ESAB Corporation occupy positions anchored in plasma power source specialization and welding-cutting integration respectively. These named entities represent competitive positioning vectors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Hypertherm, Inc. |
| The Lincoln Electric Company |
| TRUMPF SE + Co. KG |
| ESAB Corporation |
| AMADA WELD TECH |
| Bystronic AG |
| Koike Aronson, Inc. |
| Illinois Tool Works |
| OMAX Corporation |
| Others |
Supply Flow & Price Mechanics
Beam alignment technician scarcity in Baden-Württemberg and Aichi Prefecture compresses labor-cost differentials into pricing-tier spreads across fiber laser system procurement, with OEM-trained specialist premiums widening the gap between German-Japanese resonator platforms and third-party integrators.
Pricing Analysis
Short lead-time premiums for high-power fiber laser resonators above 6 kilowatts command substantial markups against spot inventory discounts for depreciated CO2 platforms. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9013-certified aerospace systems from general fabrication equipment and refurbished legacy units. Price differentiation hinges on certification grade and geographic delivery cost, with CE marking compliance burdens adding European-bound premiums. Cost compression in mid-tier plasma cutting is intensifying because China's MIIT domestic substitution redirects public procurement toward locally certified platforms. Job shops with depreciated capital equipment demonstrate highest price sensitivity, while tier-one automotive OEMs prioritize performance specifications over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for fiber laser resonators above 6 kilowatts mandate multi-supplier qualification across German and Japanese OEMs, constraining buyer leverage despite concentrated supply. Geographic supply concentration centers on Germany, Japan, and China for resonator production, beam delivery systems, and plasma power source assembly respectively. Raw material dependencies draw from rare-earth dopants for fiber lasers, tungsten and hafnium for plasma electrodes, and high-purity garnet abrasives for water jet systems. Single-source vulnerability in high-power resonator supply creates structural risk for systems integrators lacking backward integration. Distribution runs through direct manufacturer service agreements displacing independent distributor networks in North American and European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where fiber laser power scaling above 12 kilowatts forces capital redeployment that strands weaker CO2-focused competitors without resonator production capabilities.
For Market Incumbents: Acquire beam delivery system production capabilities to reduce dependency on German-Japanese resonator suppliers. Consolidate aftermarket service networks in Vietnamese and Indonesian fabrication hubs before distributor margin stacking erodes channel control. Anchor defensive positioning through in-house resonator production and direct service agreements that displace independent maintenance networks. For New Entrants and Emerging Players: Begin with water jet abrasive cutting integration for aerospace composite trimming, where fiber laser heat damage remains prohibitive and robotic handling convergence creates white-space opportunity. Target Vietnamese shipyards and infrastructure steel processors prioritizing plasma cutting throughput over precision tolerances. Pursue channel partnerships with local equipment assemblers in Shenzhen and Dongguan accelerating backward integration. For Investors and Strategic Acquirers: Re-rating potential sits with diversified welding-cutting integrators given NHTSA lightweighting mandates accelerating laser blanking adoption versus mechanical shear lines. Long-term viability over a multi-year window favors platforms with captive resonator supply and direct service presence in emerging industrial clusters. Monitor MIIT certification expansion as inflection indicator for domestic substitution trajectory in Chinese public procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resonator Production | In-house fiber laser resonator manufacturing reduces dependency on German-Japanese supply concentration. |
| Direct Service Presence in Vietnam | Hai Phong and Ba Ria-Vung Tau port infrastructure bypasses distributor margin stacking for shipyard contracts. |
| ISO 9013 Certification Investment | Aerospace tolerance mandates in Germany and Japan lock in premium positioning for titanium airframe components. |
| Water Jet-Robotic Handling Integration | Stacked composite trimming applications address aerospace layup damage constraints that disqualify thermal alternatives. |
| CE Marking Compliance Pathway | EU Machinery Directive recertification secures cost-of-entry position for European fabrication shop procurement. |
Methodological Framework
Independent corroboration across plant engineers at German automotive stamping operations, procurement leads at Vietnamese shipyards, and aftermarket service heads at North American distributors underwrites the qualitative findings. Primary interviews with maintenance directors, OEM procurement teams, and fiber laser technicians trained on specific platforms combined with secondary validation from SEC filings, customs trade data, and ISO certification registries. Bottom-up equipment shipment tracking and top-down industrial capex analysis triangulate market sizing across technology platforms.
Rate-of-change decomposition separates volume effects from mix-shift and pricing dynamics across the projection horizon. Segmentation dimensions modeled include technology platform, power density tier, end-use industry, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, technology transition velocities, and capital expenditure timing patterns. Industry-specific forecast inputs incorporate NHTSA lightweighting mandate compliance timelines and MIIT domestic substitution certification expansion rates.
Underlying measurement precision varies by segment; fiber laser system shipments carry tighter precision than fragmented water jet abrasive supply. Forecasts reflect documented assumptions regarding resonator supply concentration persistence and technician training pipeline expansion. Deviation in China MIIT certification enforcement intensity or EPA wet cutting rule implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Turning Tools Market
Tools
Concrete Saw Market
Tools
Thread Milling Machine Market
Tools
Power Tools Market
Tools
Rivet Busters Market
Tools
Machine Vise Market
Tools
Spray Gun Market
Tools
Global Protractor Market
Tools
Fiber Laser Cutting Machines Market
Tools
Orbital Recip Saw Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Lathe Machines Market
Tools
Digital Cutting Machine Market
Tools
Spindle Shaper Market
Tools
MIG Guns Market
Tools
Power Press Machines Market