
 Parting-Off Blades Market | 2026-2036
Parting-Off Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Parting-Off Blades Market Analytics
Buyer concentration among automotive tier-one suppliers is hardening as OEMs reduce their approved vendor lists for precision machining operations. Sandvik Coromant leverages its integrated materials-to-tools portfolio to sustain long-term supply agreements with major powertrain manufacturers. Kennametal Inc. anchors its position through captive tungsten carbide processing and direct service infrastructure across industrial clusters. Mitsubishi Materials Corp. competes on ceramic-insert innovation for high-speed parting applications in Japanese and Southeast Asian machining centers.
Parting-off blades are precision cutting tools designed to separate finished workpieces from bar stock during lathe operations, typically featuring widths from 0.5 mm to 6 mm with specialized chip-breaking geometries to prevent tool failure at narrow cross-sections. Indexable blades command the largest installed base due to their insert-change economics in high-volume production environments, while solid carbide blades capture premium-margin applications requiring maximum rigidity in deep-grooving and parting-off of superalloy components. Carbide blades lead material value pools given tungsten carbide's dominance in wear resistance, though ceramic inserts are gaining traction in aerospace heat-resistant alloy machining where elevated cutting speeds offset brittleness constraints.
ISO 13399 standards for cutting tool data exchange shape interoperability requirements between CAM systems and tool management platforms, while REACH restrictions on cobalt and nickel compounds in coatings push manufacturers toward alternative binder formulations and PVD coating architectures. In the United States, OSHA exposure limits for metalworking fluids influence dry-machining tool designs that demand enhanced thermal stability from blade substrates and edge preparations. Stakeholders must monitor evolving material compliance timelines and machine tool spindle power trends to align blade development with next-generation turning center capabilities.
Market Dynamics
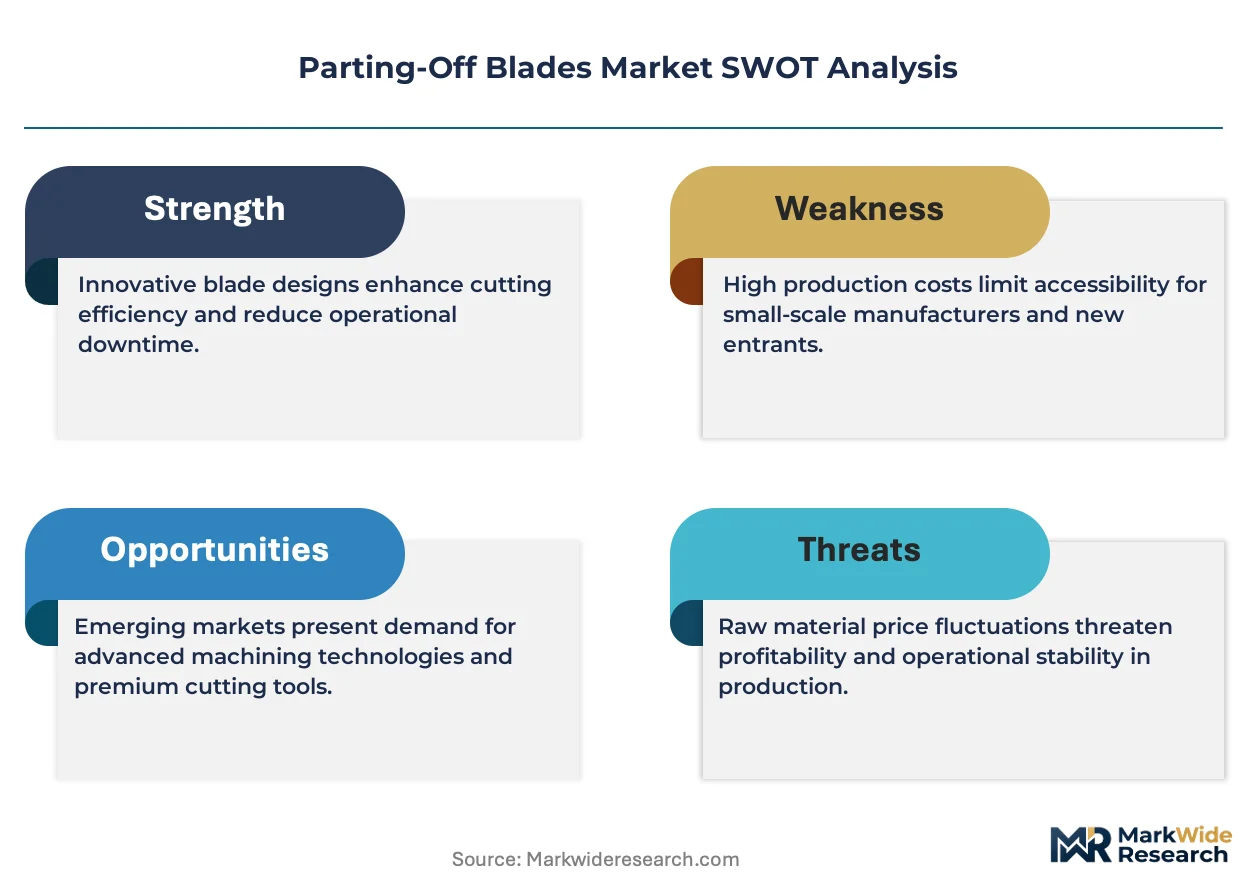
Automotive OEM consolidation of approved vendor lists for precision cutting tools is compressing procurement channels and forcing blade suppliers to demonstrate measurable tool life and dimensional repeatability under stricter supply agreements.
Growth Catalysts
- REACH and RoHS compliance mandates:European regulations on cobalt and nickel compounds in coatings are accelerating alternative binder formulation development and PVD coating adoption among blade manufacturers serving EU automotive tier-one suppliers.
- Machine tool spindle power advancement:Next-generation turning centers with elevated power density enable ceramic insert deployment for high-speed parting of heat-resistant superalloys in aerospace component machining.
- Germany's precision engineering corridor:Concentrated machine tool density and automotive component manufacturing in Baden-Württemberg and Bavaria sustain above-average consumption of indexable and solid parting-off systems.
Market Restraints
- Tungsten carbide supply concentration:Captive processing capabilities anchor with a limited set of integrated tool manufacturers, constraining independent blade producers' input cost flexibility and supply security.
- Ceramic insert brittleness constraints:Technical limitations in impact resistance restrict ceramic blade penetration to controlled high-speed applications, excluding interrupted cutting and rough machining environments.
- OSHA metalworking fluid exposure limits:United States occupational safety regulations are forcing accelerated dry-machining tool development, demanding enhanced thermal stability from blade substrates without commensurate price recovery mechanisms.
Strategic Opportunities
- Southeast Asian machining center expansion:Japanese and South Korean automotive component transplants in Thailand and Vietnam are generating demand for ceramic-insert innovation in high-speed parting applications.
- ISO 13399 interoperability:Standardized cutting tool data exchange between CAM systems and tool management platforms creates white space for digitally-native blade suppliers to capture specification-lock-in with engineering departments.
- China GB standards alignment:National cutting tool performance standards are reshaping material specifications, creating entry pathways for compliant foreign manufacturers in domestic precision engineering supply chains.
Industry Challenges
- Coating chemistry reconfiguration timelines:REACH substance restrictions require multi-year reformulation and requalification cycles, compressing R&D bandwidth while maintaining existing product lines.
- Chip-breaking geometry specialization:Narrow cross-section parting at widths below 1.0 mm demands application-specific edge preparation expertise that resides with a limited population of grinding specialists and metrology engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parting-Off Blades Market |
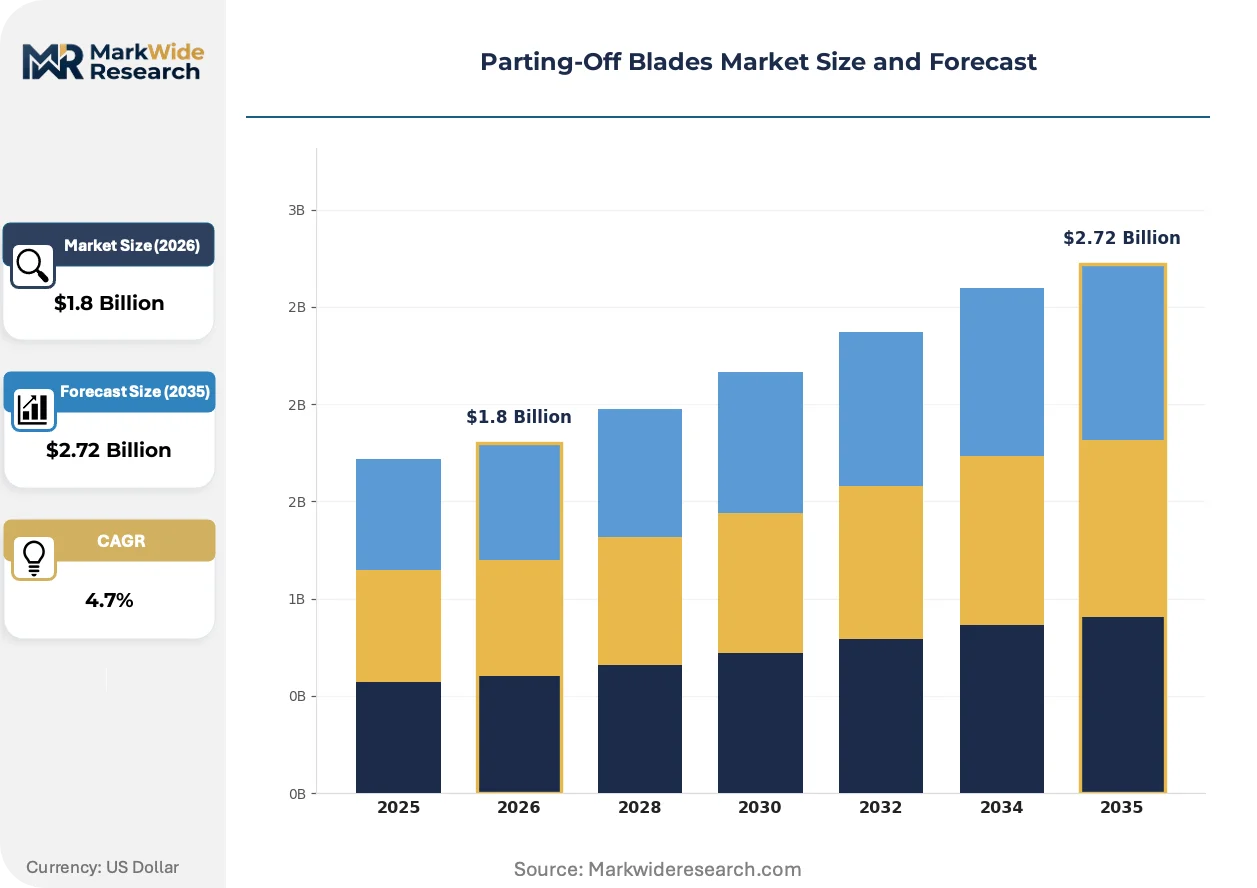
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indexable Blades, Solid Blades, Carbide Blades, HSS Blades End User: Metalworking, Aerospace, Automotive, Machinery Material: Tungsten Carbide, High-Speed Steel, Cobalt, Ceramic Application: Turning, Grooving, Threading, Parting |
| Companies Covered | Sandvik Coromant, ISCAR LTD., Taegutec, Whizcut, Thinbit, Kennametal Inc., IMCO Group, Mitsubishi Materials Corp., OSG Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parting-Off Blades Market Evolving Landscape
Dry-machining tool architectures and digital tool data standards are converging to redefine blade specification, procurement, and performance validation workflows across precision engineering supply chains.
Physical vapor deposition coatings with reduced cobalt binder dependency are overtaking conventional CVD architectures in European automotive supply chains. Tier-one powertrain manufacturers specify these chemistries to preempt REACH compliance exposure. The shift is overtaking legacy coating portfolios and forcing reformulation investments across mid-tier blade suppliers.
REACH restrictions on nickel and cobalt compounds in surface treatments are compelling coating architecture redesigns. Industrial consequence includes accelerated PVD platform adoption and alternative binder material qualification programs. German automotive component manufacturers are most affected, driving collaborative development agreements with integrated materials-to-tools suppliers.
Automotive OEM vendor list consolidation is compressing blade procurement channels toward direct long-term supply agreements with approved manufacturers. Distributor intermediaries are losing specification influence as engineering departments centralize tool selection authority. This concentration is most visible in Germany's precision engineering corridor and among Japanese automotive transplants in North American manufacturing clusters.
Parting-Off Blades Market Segmentation
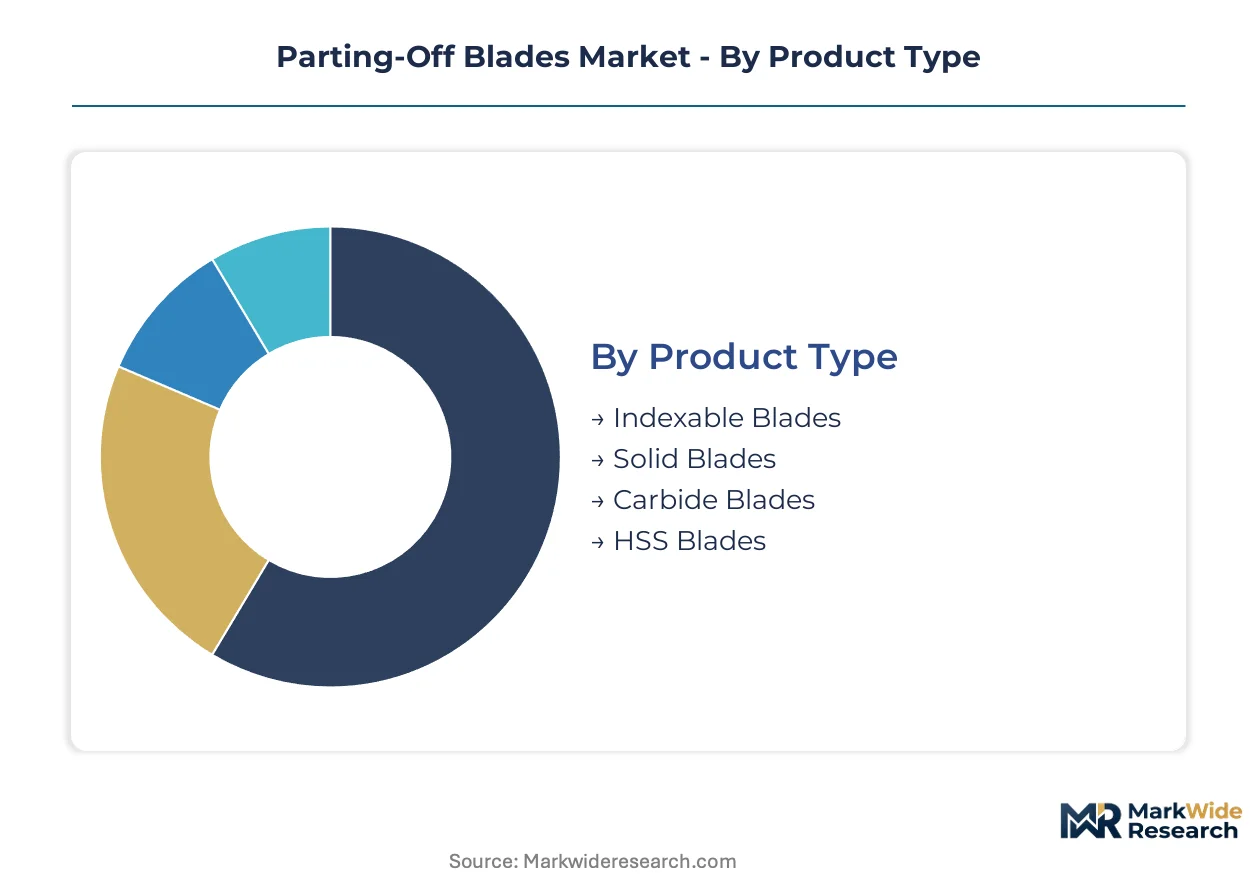
Parting-off blade segmentation reveals how procurement authority, application severity, and material compliance requirements split demand across divergent technical and commercial specifications. Buyers prioritize different performance metrics depending on whether they machine automotive powertrain components, aerospace superalloys, or general metalwork.
Product Type:
Cost tier separates buyers most sharply in this category, with high-volume manufacturers favoring replaceable cutting edges while precision specialists absorb upfront rigidity premiums.
- Indexable Blades:Modular systems accepting replaceable inserts dominate high-volume automotive and machinery production where tool-change economics outweigh per-unit substrate costs. German automotive tier-one suppliers specify these for crankshaft and camshaft machining lines where insert indexing minimizes spindle downtime.
- Solid Blades:Monolithic carbide construction delivers maximum rigidity for deep-grooving operations and superalloy parting where deflection tolerance approaches zero. Aerospace component manufacturers in the United States and Japan absorb price premiums to achieve dimensional repeatability in Inconel and titanium bar stock separation.
- Carbide Blades:Tungsten carbide substrates dominate wear-critical applications across all product configurations, with cobalt binder content varying by regional REACH exposure.
- HSS Blades:High-speed steel retains foothold in cost-sensitive general metalworking and educational machining environments where cutting speeds remain moderate.
Volume sits with indexable configurations; growth tilts toward solid carbide systems as aerospace superalloy machining expands.
End User:
Application severity and certification requirements create distinct procurement patterns across industrial buyer classes.
- Metalworking:General job shops and contract manufacturers drive baseline demand for versatile blade geometries across mixed material batches. Chinese GB standards compliance increasingly filters supplier eligibility for domestic precision engineering contracts.
- Aerospace:Heat-resistant superalloy machining demands ceramic-insert compatibility and thermal stability under dry-cutting conditions. Japanese and South Korean component transplants in Thailand and Vietnam specify blades qualified for titanium and nickel-based alloy parting at elevated speeds.
- Automotive:Powertrain manufacturers consolidate approved vendor lists and impose tool-life guarantees under direct long-term supply agreements. REACH-compliant coating specifications are mandatory for EU-facing production.
- Machinery:Capital equipment builders specify blades for in-house component production and aftermarket service part manufacturing.
Automotive buyers concentrate procurement volume; aerospace applications are expanding most quickly on superalloy machining intensity.
Material:
Regulatory pressure on binder chemistries is fragmenting material selection across geographic supply chains.
- Tungsten Carbide:Cobalt-bound cemented carbide delivers unmatched wear resistance for steel and cast iron parting, though ECHA substance restrictions are forcing binder reformulation timelines. Captive tungsten processing capabilities anchor with integrated tool manufacturers, constraining independent producers.
- High-Speed Steel:Molybdenum and tungsten grades retain cost advantage in interrupted cutting and rough machining where impact resistance outweighs speed capability.
- Cobalt:Binder phase concentration determines substrate toughness and heat resistance, with reduced-cobalt formulations accelerating under EU regulatory pressure.
- Ceramic:Silicon nitride and alumina-based inserts enable cutting speeds exceeding carbide limits in nickel superalloy applications, though brittleness excludes rough environments.
Tungsten carbide holds installed base dominance; ceramic substrates gain share fastest on aerospace thermal management requirements.
Application:
Process integration level determines whether buyers specify dedicated parting tools or multi-function blade systems.
- Turning:Combined turning and parting operations on multi-tasking lathes demand blades with chip-breaking geometries compatible with longitudinal and radial cutting. Japanese machining centers favor insert systems supporting rapid tool change between operations.
- Grooving:Deep-grooving applications require maximum blade rigidity and specialized edge preparations for chip evacuation at narrow cross-sections below 1.0 mm width.
- Threading:Thread-turning compatibility extends blade utility in small-batch production environments where tool variety minimization reduces inventory carrying costs.
- Parting:Dedicated parting-off remains the core specification, with workpiece separation reliability determining blade selection above all other performance metrics.
Standalone parting commands specification authority; turning-integrated blades show steepest expansion trajectory on multi-tasking machine tool adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's precision engineering corridor, where automotive component manufacturing and machine tool density sustain above-average consumption of indexable and solid parting-off systems. Supplier qualification requirements are tightening across all major manufacturing regions as OEMs consolidate approved vendor lists.
Germany
Baden-Württemberg and Bavaria host dense clusters of automotive tier-one suppliers machining crankshafts and camshafts with indexable blade systems. ECHA's REACH restrictions on cobalt and nickel compounds in coatings are compelling PVD coating adoption among blade manufacturers serving EU-facing production. Stuttgart's precision engineering corridor anchors specification authority for REACH-compliant coating architectures.
United States
Aerospace component manufacturers in the Midwest and Southeast absorb price premiums for solid carbide blades achieving dimensional repeatability in Inconel and titanium parting. OSHA exposure limits for metalworking fluids are accelerating dry-machining tool development. Michigan and Ohio machining centers specify enhanced thermal stability from blade substrates for powertrain production.
China
Domestic precision engineering supply chains are reshaping around GB standards for cutting tool performance, creating entry pathways for compliant foreign manufacturers. MIIT's industrial upgrading directives favor advanced carbide processing capabilities. Yangtze River Delta automotive component plants are consolidating procurement toward direct supplier relationships with integrated materials-to-tools providers.
Japan
METI-supported manufacturing technology programs sustain ceramic-insert innovation for high-speed parting applications in aerospace superalloy machining. Japanese automotive transplants in North American manufacturing clusters are extending vendor qualification standards to domestic suppliers. Nagoya-area machining centers favor insert systems supporting rapid tool change between turning and parting operations.
South Korea
Automotive component transplants in Thailand and Vietnam are generating demand for qualified blade suppliers through Korean parent company supply chain extension. MFDS-aligned industrial standards for precision components are filtering supplier eligibility. Seoul Capital Area tool distributors are losing specification influence as engineering departments centralize blade selection authority.
Parting-Off Blades Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ceramic-insert specialization for aerospace applications. The vendor base concentrates around integrated materials-to-tools suppliers with captive tungsten processing capabilities and independent blade producers dependent on external carbide supply. Three archetypes dominate: integrated conglomerates with backward control over raw materials, regional specialists in application-specific geometries, and coating technology innovators. Competitive moves center on long-term supply agreement capture with consolidated automotive OEMs and multi-year reformulation investments to meet REACH compliance timelines.
Within the integrated conglomerate tier, Sandvik Coromant and Kennametal Inc. exemplify the materials-to-tools model that anchors supply security through in-house carbide processing. Mitsubishi Materials Corp. occupies a position representing ceramic-insert innovation for heat-resistant superalloy applications. These three companies illustrate how geographic origin and corporate structure—Swedish, American, and Japanese respectively—map to distinct competitive positioning in a market where procurement authority is centralizing toward direct manufacturer relationships.
| Leading Market Players |
|---|
| Sandvik Coromant |
| ISCAR LTD. |
| Taegutec |
| Whizcut |
| Thinbit |
| Kennametal Inc. |
| IMCO Group |
| Mitsubishi Materials Corp. |
| OSG Corporation |
| Others |
Value Network & Pricing Analysis
Tungsten carbide powder price indices cascade through three distinct pricing tiers for parting-off blades, with cobalt binder content volatility and captive processing advantages concentrating margin capture among integrated manufacturers serving automotive tier-one suppliers.
Pricing Analysis
Volume concentrates in indexable blade configurations where per-unit margins compress under insert-change economics, while solid carbide systems retain premium pricing for aerospace superalloy applications. Price differentiation hinges on REACH-compliant coating certification and captive tungsten processing capabilities, with German automotive OEMs imposing strict tool-life guarantees that squeeze mid-tier suppliers. Cost compression in standard-grade carbide blades is intensifying because Chinese GB standards compliance is filtering supplier eligibility and expanding qualified domestic competition. General metalworking job shops exhibit highest price sensitivity, whereas aerospace component manufacturers absorb premiums for dimensional repeatability in Inconel and titanium machining.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Cleveland anchor hub-and-spoke patterns for blade inventory positioning near precision engineering clusters. Supply concentrates in Sweden, the United States, and Japan where captive carbide processing capabilities rest on tungsten ore access and cobalt refining infrastructure. Raw material dependencies include tungsten carbide powder, cobalt binder compounds, and ceramic substrate precursors. Single-source vulnerability around cobalt supply from the Democratic Republic of Congo exposes coating reformulation timelines to geopolitical disruption. Distribution runs through direct manufacturer relationships with consolidated automotive OEMs, bypassing traditional distributor intermediaries that once held specification influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The parting-off blades market is becoming a vertical-integration race, with captive tungsten carbide processing emerging as the decisive upstream lever separating integrated conglomerates from dependent independent producers.
For Market Incumbents: Hedge against REACH compliance exposure by accelerating PVD coating platform investments and locking in multi-year reformulation partnerships with ECHA-aligned research institutes. Defensive consolidation through backward integration into cobalt-reduced binder development will preempt regulatory displacement, while capacity positioning in Germany's precision engineering corridor secures specification authority with consolidating automotive OEMs. For New Entrants and Emerging Players: Begin with ceramic-insert specialization for aerospace superalloy applications in Southeast Asian machining centers, where Japanese and South Korean automotive transplants in Thailand and Vietnam are extending qualification standards to new suppliers. The most penetrable white space sits in dry-machining tool architectures for titanium parting, with ISO 13399 digital tool data compliance as the essential go-to-market credential for engineering department specification capture. For Investors and Strategic Acquirers: The window for entry favors mid-tier blade producers with captive coating capabilities and established REACH reformulation pipelines. Long-term viability hinges on supply security through upstream tungsten access rather than downstream brand positioning. The signal to watch is automotive OEM vendor list consolidation velocity, as accelerated approved supplier reduction will strand distribution-dependent independents without direct manufacturer relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Processing | Captive carbide supply secures margin control against cobalt price volatility and REACH reformulation costs. |
| PVD Coating Platform Expansion | Alternative binder architectures preempt ECHA substance restrictions while maintaining automotive tier-one supply eligibility. |
| Ceramic Insert Innovation Program | Silicon nitride and alumina-based substrates capture aerospace superalloy machining growth in Southeast Asian transplants. |
| ISO 13399 Digital Tool Data Certification | Standardized CAM interoperability creates specification lock-in with engineering departments at consolidated OEMs. |
| Direct Long-Term Supply Agreement Capture | Bypassing distributor intermediaries secures volume commitments with automotive powertrain manufacturers in Germany and North America. |
Research Methodology
SEC filings, ECHA substance restriction databases, and Japanese METI industrial technology reports formed the secondary backbone, supplemented by customs data on tungsten carbide powder trade flows and automotive production statistics from IHS Markit. Primary interviews with cutting tool procurement managers at German automotive tier-one suppliers, coating technology R&D directors, precision engineering plant managers, and aftermarket service heads validated demand assumptions and REACH compliance timelines. Bottom-up segment sizing across indexable and solid blade configurations triangulated against top-down market value estimates derived from integrated manufacturer revenue disclosures.
Historical trendline analysis of machine tool spindle power advancement and ceramic insert adoption rates informed growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, substrate material, and geographic production cluster, with particular attention to aerospace superalloy machining intensity and automotive OEM vendor consolidation patterns. CAGRs were derived from regression analysis of correlated industrial indicators rather than simple extrapolation, incorporating tool-life guarantee contract structures and dry-machining thermal stability requirements as industry-specific forecast inputs.
Underlying measurement precision varies by segment; automotive powertrain applications carry tighter precision than general metalworking given consolidated procurement data availability, while ceramic insert forecasts reflect greater uncertainty due to brittleness constraints limiting addressable applications. Forecasts reflect documented assumptions regarding REACH substance restriction timelines, machine tool spindle power advancement curves, and automotive OEM vendor list consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Automotive Torque Tools Market
Tools
Reamer Market
Tools
Nail Gun Market
Tools
Fine Blanking Tools Market
Tools
Scroll Saws Market
Tools
Gas Cutting Machine Market
Tools
Machine Tools Market
Tools
High-Speed Steel Metal Cutting Tools Market
Tools
Boring Tools Market
Tools
Grease Gun Market
Tools
End Mill Holder Market
Tools
Metal Cutting Tools Market
Tools
Level Floats Market
Tools
Cordless Planer Market
Tools
Grinding Discs Market
Tools
Wood-Sanding Machine Market