
 Global Sandblasting Media Market | 2026-2036
Global Sandblasting Media Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sandblasting Media Market Foresight
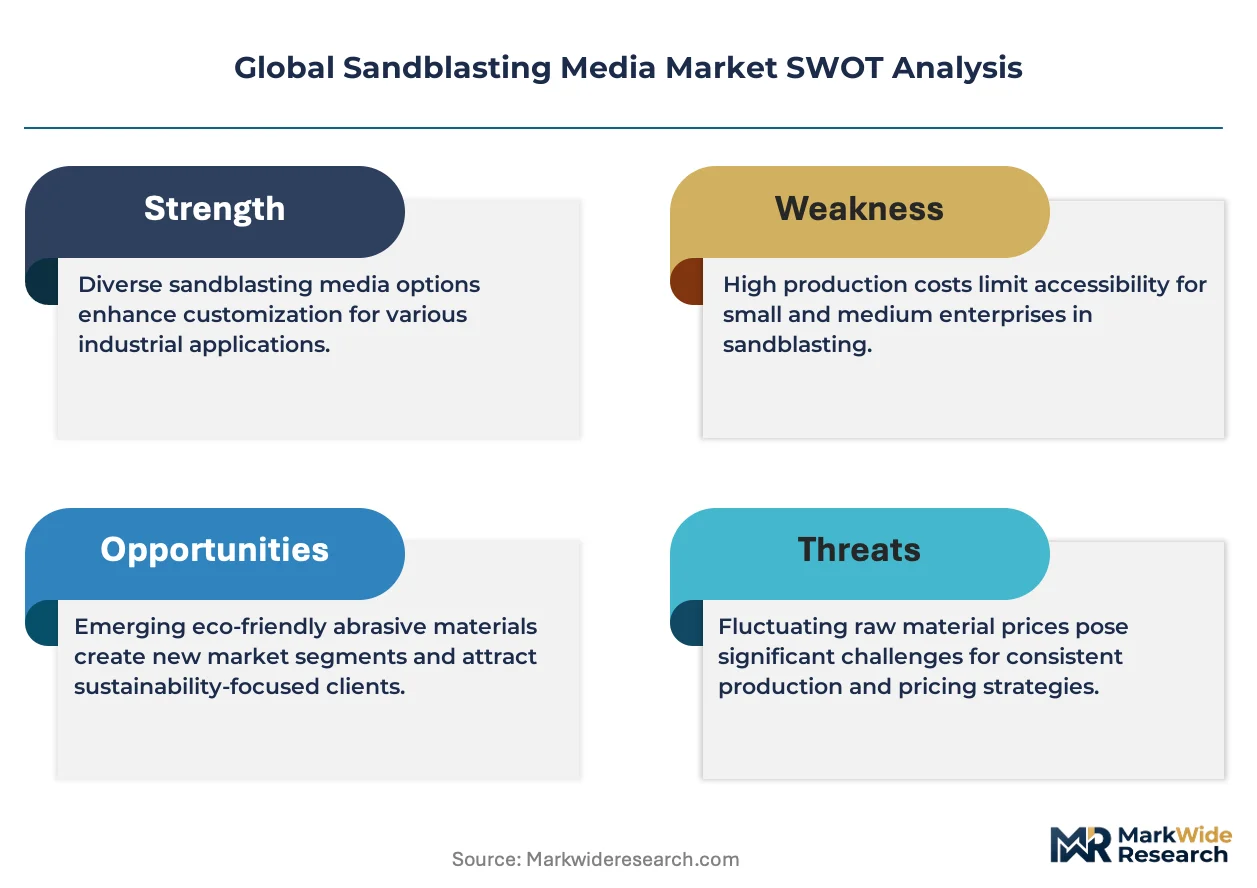
ISO 11126 certification for non-metallic blast-cleaning abrasives is reorganizing supplier qualification across the Global Sandblasting Media Market, forcing smaller producers to invest in testing infrastructure or exit tender pools. GMA Garnet Pty Ltd leverages its vertically integrated mining and processing operations in Western Australia to secure long-term contracts with shipyards requiring consistent garnet grades. Eisenwerk Wurth GmbH anchors Central European distribution through specialized steel grit and cut wire product lines tailored to automotive OEM surface preparation protocols.
Sandblasting media encompasses expendable and recyclable abrasive materials engineered to specific Mohs hardness ratings, particle size distributions measured in mesh or micron grades, and angular or spherical morphologies for controlled substrate impact. These materials strip coatings, deburr machined components, and impart specified surface roughness profiles measured as Ra or Rz values to prepare substrates for protective coating adhesion. Aluminum oxide and garnet command premium positioning in aerospace and precision metal fabrication due to their hardness consistency and low dust generation, while steel grit dominates high-volume shipbuilding and oilfield equipment maintenance where recyclability offsets per-cycle cost. Glass beads occupy a mature niche in cleaning and peening applications where substrate preservation outweighs aggressive material removal.
OSHA's respirable crystalline silica standard and REACH restrictions on carcinogenic dust classifications are reshaping product portfolios, compelling manufacturers to reformulate toward silica-free alternatives or invest in closed-loop blasting systems. The EPA's National Emission Standards for Hazardous Air Pollutants and China's GB standards on industrial particulate emissions add compliance layers that favor suppliers with certified low-dust media and documented environmental product declarations. Stakeholders must track evolving regional hazard classifications and recycling infrastructure investments to align procurement strategies with tightening occupational exposure limits and extended producer responsibility frameworks.
Market Dynamics
OSHA's respirable crystalline silica standard and REACH dust restrictions are forcing rapid formulation shifts toward non-silica abrasives, while ISO 11126 certification requirements concentrate supply among testing-capable producers.
Growth Catalysts
- REACH carcinogenic dust classifications:European regulatory pressure accelerates substitution from silica sand to garnet and aluminum oxide in shipyards across Germany, Netherlands, and Spain.
- Aerospace precision finishing:North American and European aircraft manufacturers expand specification of garnet media for turbine blade surface preparation and coating adhesion protocols.
- Infrastructure maintenance cycles:Bridge rehabilitation and highway repainting programs in the United States, China, and Germany sustain steel grit consumption for heavy-scale rust removal.
Market Restraints
- Alumina supply concentration:Bauxite processing bottlenecks in Guinea and Australia create input cost volatility for aluminum oxide media producers.
- Closed-loop system capex:EPA NESHAP compliance requires capital-intensive dust collection and media recovery infrastructure that small job shops cannot finance.
- Waterjet cutting substitution:Precision fabrication shops in aerospace and electronics increasingly specify abrasive waterjet systems that eliminate airborne media entirely.
Strategic Opportunities
- India infrastructure build-out:National highway expansion and port modernization under the PLI scheme create first-mover positioning for certified low-dust media suppliers.
- Automotive restoration premiumization:Collector vehicle markets in Germany, Italy, and the United States demand glass bead and ceramic media for substrate-preserving finishes.
- Extended producer responsibility frameworks:EU packaging and waste directives incentivize recyclable steel grit leasing models with integrated logistics and reclamation services.
Industry Challenges
- ISO 11126 testing infrastructure:Certification laboratories face 12-18 month backlogs for particle size distribution and hardness validation, delaying new product launches.
- Blast operator respiratory training:OSHA compliance requires documented fit-testing and medical surveillance programs that small contractors struggle to administer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sandblasting Media Market |
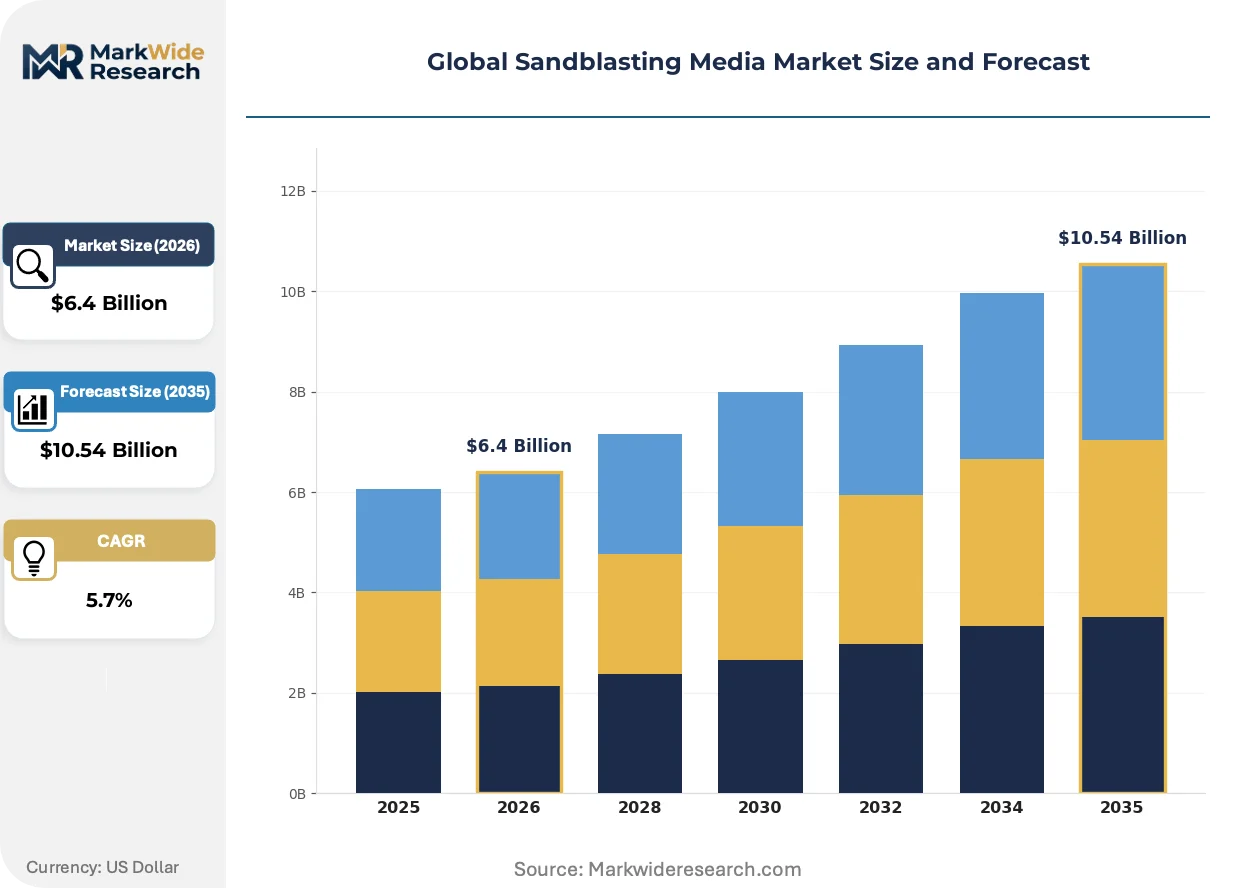
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.54 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Type: Garnet, Aluminum Oxide, Glass Beads, Steel Grit, Silicon Carbide, Walnut Shell Application: Surface Preparation, Rust Removal, Paint Stripping, Deburring, Cleaning, Finishing End User Industry: Shipbuilding, Aerospace, Construction, Metal Fabrication, Oilfield Equipment, Power Generation Form: Coarse Grit, Medium Grit, Fine Grit, Powdered, Slurry |
| Companies Covered | GMA Garnet Pty Ltd, Eisenwerk Wurth GmbH, Opta Group LLC, Synco Industries Ltd, Graco Inc, Paul Auer GmbH, Barton International, Clemco Industries Corp, Guyson Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sandblasting Media Market Shifts & Advancements
Closed-loop blasting systems and automated recovery equipment are compressing the viable supplier base while reshaping buyer specifications toward total-cost-of-ownership metrics rather than per-ton media pricing.
Spherical ceramic bead media engineered from zircon sand and alumina composites is fragmenting traditional glass bead applications in aerospace peening and medical implant finishing. European precision metal fabricators specify ceramic grades for repeatable surface compression without dimensional change. The technology is fragmenting established supply relationships as buyers qualify secondary sources.
REACH Annex XIV authorization requirements for crystalline silica are compelling reformulation across European abrasive portfolios. German and Italian producers accelerate garnet and olivine substitution in foundry and shipyard contracts. Surface preparation contractors in Poland and Czechia face compressed margins as they absorb testing and documentation costs for alternative media validation.
Specification consolidation among tier-one automotive OEMs now mandates environmental product declarations and documented recycling rates in abrasive procurement. Tier-two coating applicators in the United States and Germany switch from spot-buying to annual contracts with certified suppliers. Japanese shipbuilders pioneered this model and now dominate supplier scorecards for lifecycle transparency.
Global Sandblasting Media Market Segmentation
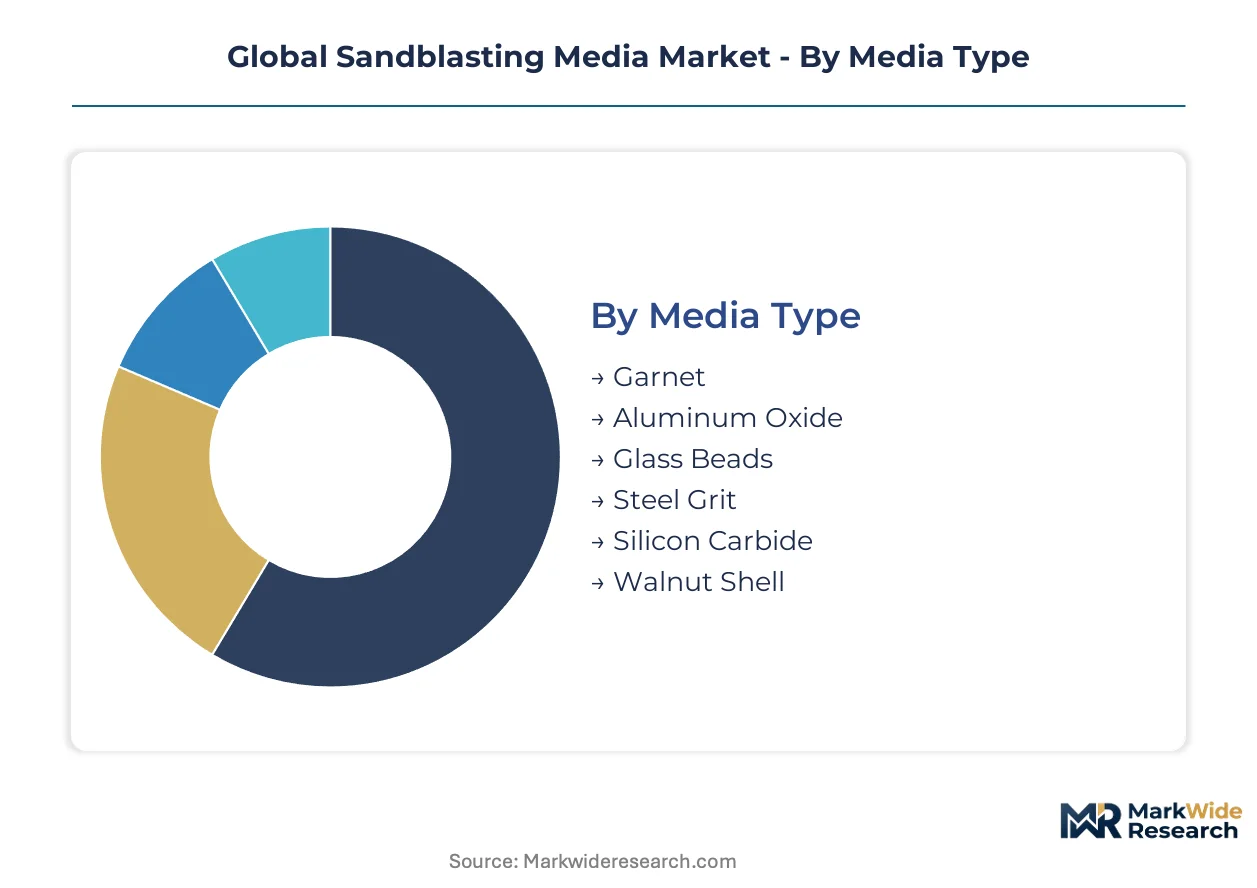
Sandblasting media segmentation reveals how technical specifications, recyclability economics, and regulatory compliance reshape procurement decisions across surface preparation workflows. Buyers segment by hardness, particle geometry, and dust generation profiles to match substrate sensitivity with operational throughput requirements.
Media Type:
Margin pools concentrate in premium hardness grades where aerospace and precision fabrication specifications command price premiums over commodity abrasives.
- Garnet:A natural silicate mineral with Mohs hardness 7.5-8.5 and sub-angular fracture geometry. Shipyards in Germany and the Netherlands specify Australian-mined alluvial garnet for ISO 11126-compliant blasting with minimal embedment. REACH silica restrictions accelerate substitution from silica sand in European surface preparation contracts.
- Aluminum Oxide:Synthetic fused alumina engineered to 8.5-9.0 Mohs hardness with sharp, blocky fracture patterns. Turbine blade manufacturers in the United States and France mandate virgin white aluminum oxide for repeatable Ra surface roughness profiles. Bauxite supply concentration in Guinea and Australia injects input cost volatility.
- Glass Beads:Spherical soda-lime glass media for peening and cleaning without dimensional change. Collector vehicle restoration shops in Italy and Germany specify glass bead for substrate-preserving finishes.
- Steel Grit:Angular cast steel particles with 40-65 HRC hardness ratings and multi-cycle recyclability. Bridge maintenance contractors in the United States and China consume high volumes for heavy-scale rust removal.
- Silicon Carbide:Synthetic ceramic with 9.0-9.5 Mohs hardness for aggressive material removal. Stone cutting and glass etching applications in Japan and South Korea drive specialized demand.
- Walnut Shell:Organic lignocellulosic media with 3.5-4.0 Mohs hardness for delicate substrate cleaning. Aircraft depainting operations in the United States specify walnut shell to avoid aluminum substrate damage.
Steel grit holds installed capacity across heavy industrial infrastructure. Garnet is rotating up the share rankings as silica substitution accelerates under tightening occupational exposure limits.
Application:
Volume concentrates in coating removal and substrate reconditioning where recurring maintenance cycles generate predictable demand streams.
- Surface Preparation:Controlled roughening to specified Ra or Rz profiles for protective coating adhesion. Offshore platform maintenance contractors in Norway and the United Kingdom specify garnet and aluminum oxide for salt-resistant coating systems.
- Rust Removal:Aggressive oxide scale stripping from carbon steel substrates. Railway infrastructure programs in India and Germany sustain steel grit consumption for track component rehabilitation.
- Paint Stripping:Coating elimination without substrate damage. Automotive OEM refinishing lines in the United States and Mexico deploy plastic and wheat starch media for e-coat removal.
- Deburring:Edge radiusing of machined components. Precision metal fabricators in Switzerland and Germany specify ceramic media for medical implant surface finishing.
- Cleaning:Non-destructive contaminant removal. Foundry mold cleaning operations in China and Brazil consume olivine and chromite sands.
- Finishing:Cosmetic surface texturing for aesthetic or functional purposes. Firearm manufacturers in the United States specify glass bead for uniform matte finishes.
Rust removal anchors volume throughput across infrastructure maintenance. Surface preparation is climbing the fastest as coating specifications tighten and inspection protocols intensify.
End User Industry:
Procurement sophistication varies sharply, with aerospace and shipbuilding mandating certified media lots while construction trades prioritize per-ton cost minimization.
- Shipbuilding:Hull preparation and tank coating for newbuild and repair cycles. Korean and Japanese shipyards specify garnet for IMO-compliant coating systems with documented environmental product declarations.
- Aerospace:Turbine blade surface finishing and airframe depainting. Airbus and Boeing tier-one suppliers in France and the United States mandate aluminum oxide with batch hardness certification.
- Construction:Bridge rehabilitation and structural steel repainting. State transportation departments in the United States and provincial agencies in Canada specify steel grit for highway infrastructure programs.
- Metal Fabrication:General-purpose weld cleaning and surface conditioning. Job shops across Poland and Czechia face compressed margins absorbing alternative media testing costs.
- Oilfield Equipment:Drill pipe and valve reconditioning for downhole service. Houston and Aberdeen service companies consume recyclable steel grit for cost-per-cycle optimization.
- Power Generation:Boiler tube cleaning and turbine maintenance. Coal and nuclear facilities in Germany and the United States specify controlled particle size distributions for precision cleaning.
Shipbuilding holds installed capacity from decades of maritime coating protocols. Aerospace is gaining share fastest as specification consolidation among tier-one OEMs mandates certified supplier relationships.
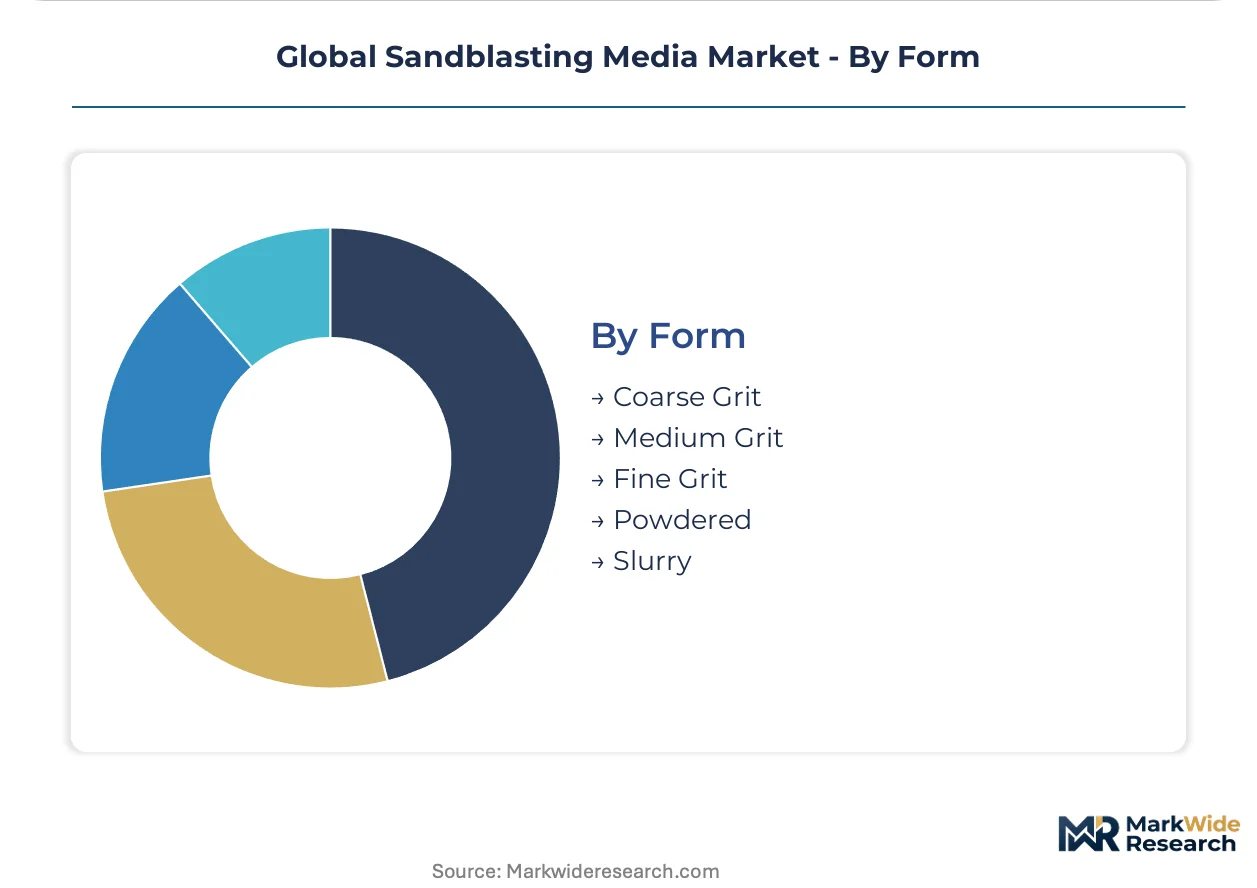
Form:
Particle size distribution determines cutting speed, surface profile depth, and dust generation rates, with coarse grades dominating heavy removal and fine grades penetrating precision niches.
- Coarse Grit:12-30 mesh particles for aggressive material removal and deep anchor patterns. Heavy equipment remanufacturing in the United States and Germany consumes coarse steel grit for casting cleanup.
- Medium Grit:30-60 mesh for balanced removal rate and surface finish. General industrial applications across India and Brazil standardize on medium grades for versatile job shop operations.
- Fine Grit:60-120 mesh for precision finishing and delicate substrates. Electronics and medical device manufacturers in Japan and Switzerland specify fine aluminum oxide for controlled material removal.
- Powdered:Sub-120 mesh for micro-abrasive blasting and precision cleaning. Dental and jewelry applications in Italy and the United States drive specialized demand.
- Slurry:Media suspended in water for wet blasting and dust suppression. EPA NESHAP compliance pressures in the United States accelerate wet system adoption for silica-containing substrates.
Medium grit holds installed capacity across general industrial job shops. Fine grit is rotating up the share rankings as precision fabrication and medical device finishing expand specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement sophistication concentrates among German shipyards, US aerospace tier-one suppliers, and Chinese infrastructure contractors, each driving distinct media specifications that fragment regional supply strategies.
United States
Bridge rehabilitation programs across state transportation departments sustain steel grit consumption for heavy-scale rust removal. OSHA's respirable crystalline silica standard accelerates contractor migration toward garnet and aluminum oxide alternatives. Houston oilfield service companies dominate drill pipe reconditioning demand, specifying recyclable media for cost-per-cycle optimization.
Germany
Automotive OEM surface preparation protocols mandate certified steel grit and cut wire product lines for coating adhesion compliance. REACH carcinogenic dust classifications force rapid silica sand substitution in Hamburg and Bremen shipyards. Bavarian precision metal fabricators specify ceramic bead media for medical implant finishing applications.
China
National highway expansion and port modernization under infrastructure stimulus programs drive sustained consumption of steel grit and glass bead formulations. GB standards on industrial particulate emissions favor suppliers with documented low-dust certifications. Yangtze River Delta shipyards specify garnet for IMO-compliant coating systems with environmental product declarations.
India
PLI scheme incentives for port modernization and railway infrastructure create first-mover positioning for certified low-dust media suppliers. The country's national industrial safety regulator tightens occupational exposure limits for crystalline silica. Maharashtra and Gujarat manufacturing clusters absorb testing costs for alternative media validation in metal fabrication job shops.
Japan
Shipbuilders pioneered environmental product declaration mandates and now dominate supplier scorecards for lifecycle transparency. METI industrial standards pressure coating applicators toward annual contracts with certified suppliers. Osaka-Kobe shipyard concentration specifies garnet media for precision surface finishing with documented recycling rates.
Global Sandblasting Media Market Competitive Landscape
Player mix skews toward vertically integrated mining operators and specialized steel abrasive foundries. Tier-one aerospace and shipbuilding OEMs consolidate procurement around ISO 11126-certified suppliers, compressing the viable vendor base. Three strategic archetypes dominate: Australian garnet miners with captive ore bodies, Central European steel grit specialists with automotive OEM relationships, and diversified abrasive distributors with regional blending capabilities. Capacity expansion and certification infrastructure investment represent the dominant competitive moves as regulatory barriers rise.
Among Australian mining-based operators, GMA Garnet Pty Ltd anchors the premium garnet supply tier through Western Australian alluvial deposits. Eisenwerk Wurth GmbH exemplifies the Central European foundry archetype with specialized steel grit distribution networks. Barton International occupies a position within the North American specialty abrasive segment. These three represent distinct geographic and structural approaches to media supply.
| Leading Market Players |
|---|
| GMA Garnet Pty Ltd |
| Eisenwerk Wurth GmbH |
| Opta Group LLC |
| Synco Industries Ltd |
| Graco Inc |
| Paul Auer GmbH |
| Barton International |
| Clemco Industries Corp |
| Guyson Corp |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles at Australian garnet mining operations concentrate pricing power among vertically integrated suppliers while compressing margins for spot-market buyers dependent on third-party blending. This lead-time asymmetry rewards producers with captive ore bodies and ISO 11126-certified processing infrastructure, while forcing smaller distributors toward annual offtake commitments to secure supply continuity.
Pricing Analysis
Cost-plus contracts indexed to bauxite and steel scrap benchmarks dominate aluminum oxide and steel grit procurement, with Australian garnet miners commanding fixed-price premiums for certified low-dust grades. Price differentiation hinges on ISO 11126 certification tier and volume scale, with aerospace-specified media carrying substantial premiums over commodity construction grades. Cost compression in standard-grade steel grit is intensifying due to Chinese capacity expansion and European energy cost differentials. Construction contractors exhibit highest price sensitivity, while aerospace tier-one suppliers prioritize batch consistency over per-ton economics.
Supply Chain Analysis
Sixty-to-ninety-day ocean freight lead times from Western Australian garnet mines to European shipyards create inventory carrying cost burdens that favor regional blending operations with local stockpiles. Supply concentrates in Australia for garnet, Guinea and Australia for bauxite-derived aluminum oxide, and Germany and China for steel grit production. Raw material dependencies encompass zircon sand for ceramic beads, bauxite for fused alumina, and scrap steel for grit foundries. Single-source vulnerability runs through Australian alluvial garnet deposits controlled by limited mining concessions. Distribution runs through specialized abrasive distributors with regional blending and certification capabilities, bypassing general industrial chemical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Sandblasting Media Market sits at a platform-economics inflection where closed-loop blasting system interoperability and media-as-a-service leasing models are reorganizing buyer-supplier relationships around total-cost-of-ownership metrics rather than commodity spot pricing.
For Market Incumbents: Shield certified supply relationships by deepening backward integration into captive ore bodies or long-term mining concessions, particularly as REACH silica restrictions accelerate garnet substitution demand. Prioritize ISO 11126 laboratory capacity additions to reduce certification backlogs that delay new product launches. Defend margin position by bundling media supply with automated recovery equipment and reclamation logistics, converting transactional spot sales into sticky annual service contracts. For New Entrants and Emerging Players: Wet blasting system integration services represent a service-layer gap where incumbents under-serve small and mid-sized job shops struggling with EPA NESHAP compliance capital requirements. Target Indian infrastructure contractors under PLI scheme port modernization programs, where certified low-dust media demand outstrips qualified local supply. Establish go-to-market positioning through equipment-financing partnerships that bundle media supply with wet system deployment, reducing customer capex barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because tightening occupational exposure limits across OSHA, REACH, and emerging GB standard regimes structurally favor suppliers with documented environmental product declarations and closed-loop system capabilities. Acquisition targets should display vertical integration into mining or foundry operations plus established certification infrastructure. Watch for ISO 11126 laboratory backlog resolution as the signal indicating supply base expansion and margin normalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Concessions | Captive garnet ore supply from Western Australian deposits secures long-term contract eligibility with Korean shipbuilders. |
| ISO 11126 Laboratory Capacity Expansion | In-house particle size and hardness validation accelerates product qualification for Airbus tier-one coating suppliers. |
| Closed-Loop System Leasing Models | Media-as-a-service bundling with reclamation logistics converts spot buyers to annual contracts under EU extended producer responsibility frameworks. |
| Wet Blasting System Partnership | Equipment financing alliances reduce customer capex barriers and capture EPA NESHAP-driven substitution demand in US job shops. |
| Regional Blending Hub Establishment | Local stockpiling in India and Germany compresses lead times and inventory carrying costs for infrastructure maintenance contractors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with surface preparation contractors, shipyard procurement managers, aerospace coating engineers, abrasive distribution channel heads, and regulatory compliance officers. Secondary validation drew from customs and trade flow databases, SEC filings of diversified industrial suppliers, ISO certification registry records, and OSHA enforcement action reports. Bottom-up demand modeling across end-use industries triangulated against top-down supply capacity assessments from mining and foundry operations.
Across the analysis window, volume and value projections segmented by media type, application workflow, end-user industry, particle size grade, and geographic consumption cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating substitution dynamics between silica and non-silica alternatives. Forecast inputs included infrastructure maintenance cycle timing, shipbuilding orderbook visibility, and regulatory compliance cost pass-through assumptions.
Forecasts assume regulatory continuity in OSHA respirable silica enforcement, REACH Annex XIV authorization timelines, and Chinese GB standard particulate emission regimes; material policy shifts would require re-modeling demand elasticity assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Portable Pressure Washer Market
Tools
Drain Cleaning Equipment Market
Tools
Stationary Wood Planer Market
Tools
High-Speed Steel Metal Cutting Tools Market
Tools
Tile Saw Market
Tools
Portable Milling Machine Market
Tools
Construction Anchors Market
Tools
Drill Set Market
Tools
Machine Bench Vices Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Gas Cutting Machine Market
Tools
Grinding Machines Market
Tools
Blowing Torch Market
Tools
North America Power Tools Market
Tools
Hacksaw Blades Market
Tools
Total Station Market