
 Shredder Blades Market | 2026-2036
Shredder Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Shredder Blades Market Insights
Buyer concentration in the recycling sector is consolidating as large waste management operators expand through long-term service contracts with municipalities. Metso leverages its aftermarket blade replacement programs to lock in recurring revenue from industrial shredder fleets. Kanefusa anchors its position through precision grinding capabilities that extend blade life in high-abrasion plastic shredding applications. American Cutting Edge competes on domestic manufacturing scale, sustaining shorter lead times for North American recycling centers and packaging firms.
Shredder blades are precision-engineered cutting tools, typically manufactured from tool steel or high-speed steel alloys hardened to 58-64 HRC, designed to shear, tear, or granulate materials in rotating drum or shaft assemblies. Their primary purpose is size reduction across waste streams, enabling downstream sorting, densification, and material recovery in recycling and resource recovery operations. Double-shaft configurations dominate the installed base due to torque efficiency and reduced jamming in mixed waste streams, while granulator blades command premium positioning in plastics recycling where particle uniformity directly determines reprocessing yields. Tool steel grades represent the fastest-growing material category as processors seek longer changeout intervals to minimize unplanned downtime in continuous-operation facilities.
EPA emissions standards for municipal waste combustors and OSHA machine guarding requirements shape blade housing design and access protocols in United States installations. The EU Waste Framework Directive and REACH chemical compliance frameworks drive blade material traceability and end-of-life recyclability specifications for European equipment suppliers. Stakeholders must monitor how extended producer responsibility expansions in North America and Asia-Pacific alter the volume and composition of material flowing into shredder-dependent recovery systems.
Market Dynamics
Extended producer responsibility mandates are forcing waste processors to upgrade shredding capacity for complex post-consumer streams, creating sustained pull for high-durability blade systems in continuous-operation facilities.
Growth Catalysts
- EU Waste Framework Directive:Tighter material recovery targets in Germany and France are accelerating shredder fleet modernization at municipal recycling centers.
- Electronic waste streams:WEEE directive compliance is expanding installed base of dual-shaft shredders for circuit board and cable granulation.
- Tool steel grades:Advanced alloy formulations with 60-64 HRC hardness are extending blade changeout intervals by 40% in high-abrasion plastic applications.
Market Restraints
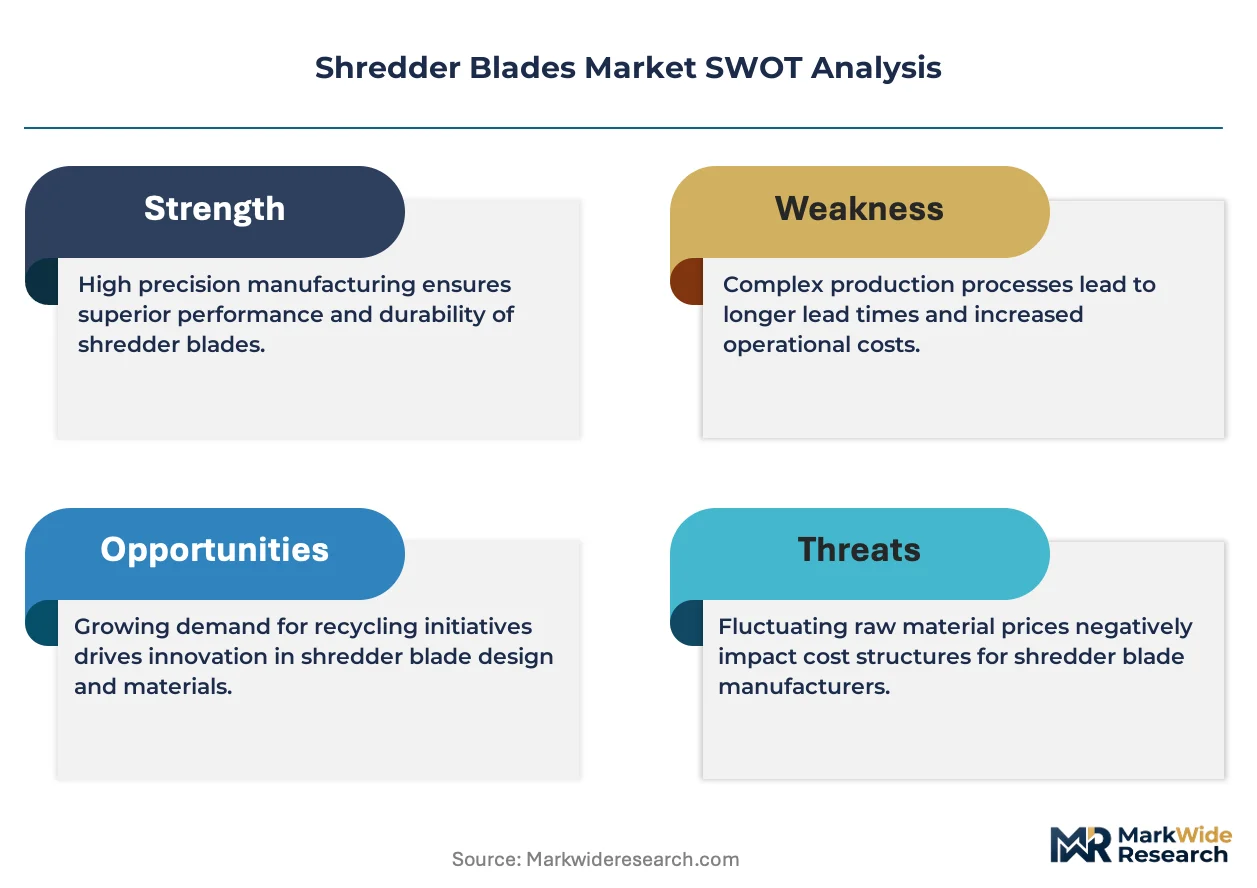
- Alloy supply concentration:Specialty tool steel production clusters in Sweden and Austria create single-source vulnerability for precision blade manufacturers.
- REACH compliance costs:Chemical traceability and end-of-life recyclability documentation adds 12-18% to blade certification overhead for European suppliers.
- Carbide insert substitution:Tungsten carbide tipping is displacing solid tool steel in abrasive mineral waste applications, compressing addressable market for conventional blade geometries.
Strategic Opportunities
- India's municipal solid waste infrastructure:Smart Cities Mission funding is unlocking tender opportunities for integrated shredding-sorting systems in Tier-2 urban clusters.
- Biomass co-processing:Agricultural residue densification for cement kiln fuel is creating demand for high-torque, low-speed shredder configurations.
- Remanufacturing services:Blade regrinding and recoating programs are capturing recurring revenue from industrial waste processors seeking to minimize capital deployment.
Industry Challenges
- Precision grinding workforce scarcity:CNC profile grinding expertise for complex blade geometries is concentrated among aging specialist technicians in Germany and Japan.
- Legacy equipment integration:Retrofitting modern blade systems into 1990s-era shredder housings requires custom adapter fabrication, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shredder Blades Market |
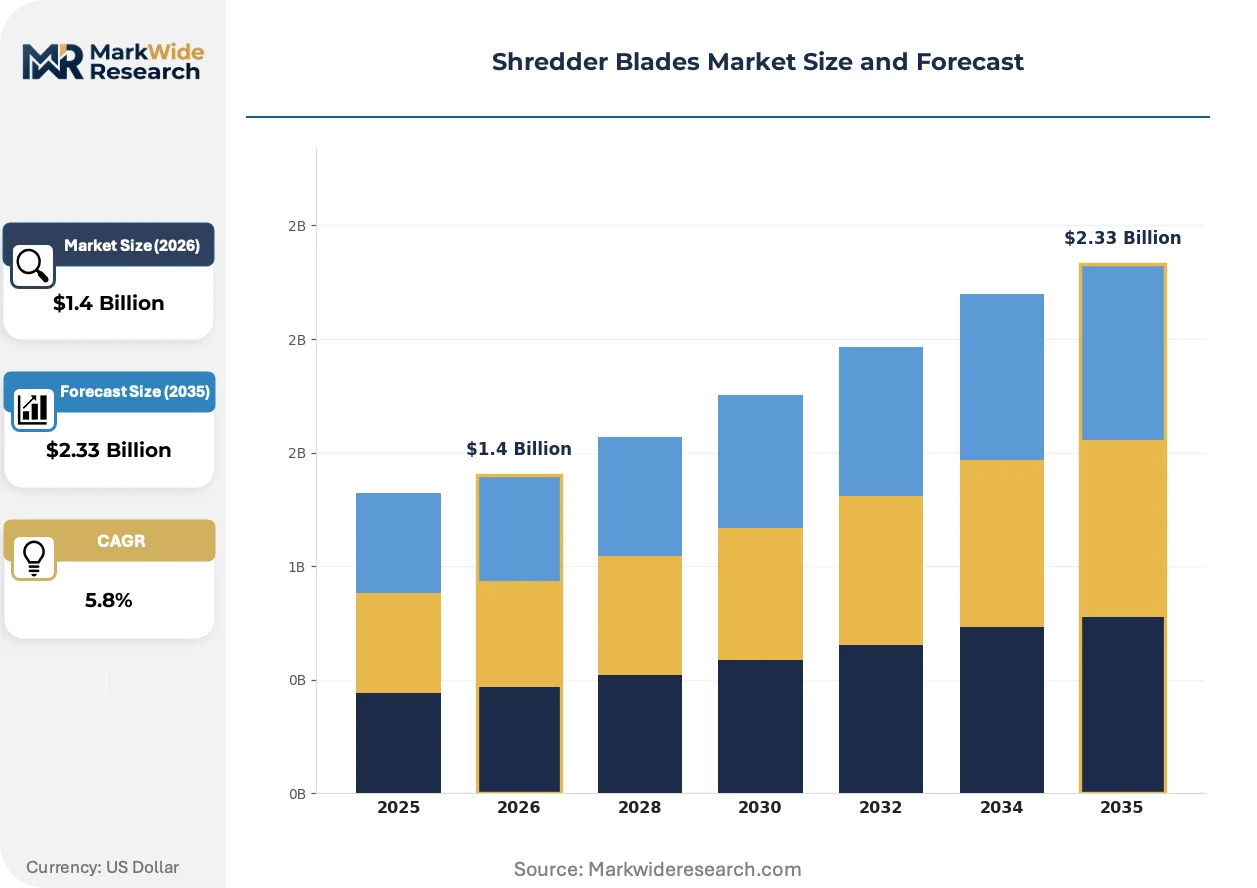
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-shaft, Double-shaft, Four-shaft, Granulator Material: High-speed Steel, Alloy Steel, Carbon Steel, Tool Steel Application: Waste Recycling, Paper Processing, Plastic Shredding, Metal Reduction End User: Manufacturers, Recycling Centers, Packaging Firms, Industrial Plants |
| Companies Covered | CutPro Blades, Metso, TKM Group, Kanefusa, Andritz, American Cutting Edge, SATURN MACHINE KNIVES, Miheu d.o.o., Zenith Cutter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shredder Blades Market Trends and Innovations
Active thermal management and predictive wear monitoring are converging with material science advances to redefine blade lifecycle economics across high-volume shredding operations.
Induction-hardened surface treatments with localized tempering zones are electrifying durability benchmarks in tire-derived fuel and rubber crumb applications. Cement producers in the US Gulf Coast and Mediterranean basin are specifying these treatments to achieve 8,000+ operating hours between regrinds. The technology is compressing total cost of ownership calculations for continuous-duty installations.
REACH Annex XIV authorization requirements for cobalt-containing hardfacing alloys are tightening material substitution timelines for European blade suppliers. Processors in Benelux and Northern Italy are accelerating qualification of iron-based alternatives to maintain compliance without sacrificing abrasion resistance. The regulatory pressure is elevating R&D intensity among mid-tier forging operations.
Performance-based blade supply contracts are displacing traditional unit-purchase arrangements at large integrated waste management groups. Operators in China's Yangtze River Delta and Germany's Ruhr corridor are contracting for guaranteed throughput-per-blade metrics, transferring wear-risk to manufacturers. The model is concentrating procurement authority among multi-site operators with standardized equipment platforms.
Shredder Blades Market Segmentation
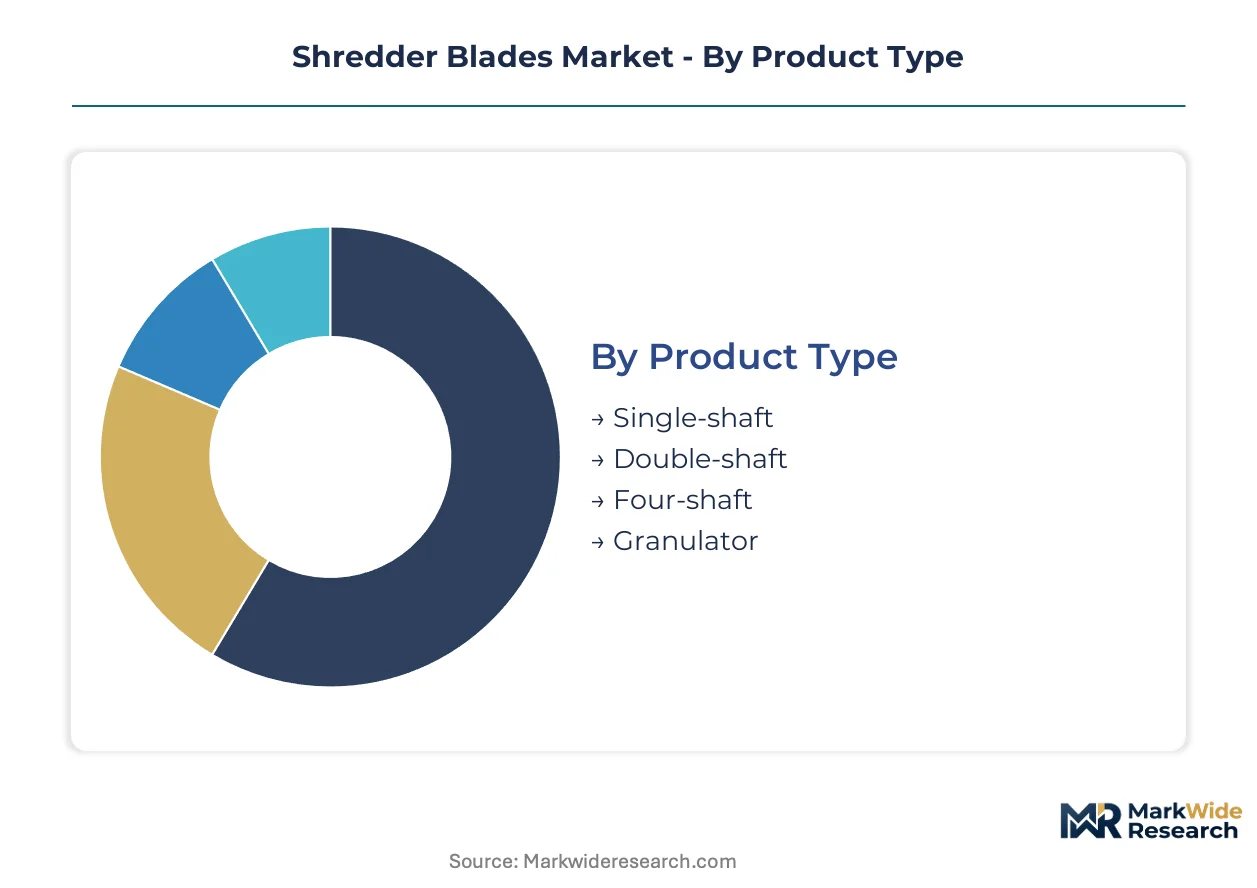
Segmentation in shredder blades reveals how equipment specifications align with material hardness, throughput requirements, and operational intensity across waste streams. Blade geometry, metallurgy, and mounting configurations determine compatibility with legacy shredder fleets versus new installations.
Product Type:
Standalone shredder configurations dominate municipal and industrial installations, while embedded blade systems integrate into mobile and compact processing units.
- Single-shaft:These configurations employ one rotating drum with stationary counter-blades, delivering high torque for bulky waste streams. Demand concentrates in German construction debris processing yards where hydraulic ram feeders manage irregular feedstock. The design suits applications requiring controlled particle size without secondary screening.
- Double-shaft:Intermeshing rotors with low-speed, high-torque operation reduce jamming in mixed municipal solid waste. China's Yangtze River Delta recycling clusters specify these for continuous-operation facilities handling post-consumer plastics and electronic scrap. Torque efficiency and self-feeding characteristics minimize operator intervention.
- Four-shaft:Quad-rotor systems with primary and secondary shredding stages in one housing. Volume placements concentrate in hazardous waste applications requiring uniform particle size for secure landfill disposal.
- Granulator:High-speed rotors with bed knives produce consistent flake geometry for plastics reprocessing. The steepest expansion trajectory appears in PET bottle-to-bottle recycling lines where particle uniformity directly determines extrusion yields.
Volume placements concentrate in Double-shaft; the faster expansion belongs to Granulator.
Material:
Cost tiering separates premium alloy formulations from commodity grades, with hardness specifications and heat treatment protocols driving procurement decisions.
- Tool Steel:Vacuum-degassed grades hardened to 60-64 HRC deliver extended changeout intervals in high-abrasion environments. Recycling centers in France's extended producer responsibility networks specify these for continuous plastic shredding operations. Advanced alloy formulations with vanadium carbide precipitation resist adhesive wear in sticky polymer streams.
- High-speed Steel:Tungsten-molybdenum alloys maintain cutting edge integrity at elevated temperatures generated by high-RPM granulator rotors. Japanese electronics waste processors favor these for circuit board pulverization where thermal cycling accelerates conventional steel degradation.
- Alloy Steel:Chromium-nickel formulations balance hardness and toughness for general-purpose shredding. Cost-sensitive municipal operators in India's Smart Cities Mission tenders specify these for initial fleet deployment.
- Carbon Steel:Water-hardened grades serve low-abrasion applications with frequent changeout tolerances. Paper processing mills in the US Southeast deploy these for cardboard and document destruction with minimal metal contamination risk.
Procurement volume tilts toward Tool Steel; margin expansion concentrates in High-speed Steel.
Application:
Application segmentation tracks how blade specifications adapt to material abrasiveness, contamination levels, and downstream recovery requirements.
- Waste Recycling:Mixed municipal streams with unpredictable metal contamination demand impact-resistant blade geometries with shear pin protection. German mechanical-biological treatment plants specify these for pre-sorting size reduction before ballistic separation.
- Plastic Shredding:Film and fiber applications require razor-edge profiles to prevent polymer melting from frictional heat. US Gulf Coast resin reclaimers specify cryogenic-compatible grades for handling engineering thermoplastics.
- Metal Reduction:Heavy-duty hook profiles shear ferrous and non-ferrous scrap for furnace charging. Turkish steel mills specify these for auto shredder residue processing.
- Paper Processing:Straight-edge configurations with precise bed knife clearance produce confetti-cut security destruction. Financial services compliance drives replacement cycles in major metropolitan document destruction contracts.
Installed base concentrates in Waste Recycling; specification intensity peaks in Plastic Shredding.
End User:
Customer type determines service model preferences, with integrated operators favoring performance contracts versus independent recyclers prioritizing unit economics.
- Recycling Centers:Municipal and private material recovery facilities operate continuous-duty fleets requiring predictive maintenance programs. Extended producer responsibility mandates in France and Germany accelerate blade upgrade cycles at these facilities.
- Industrial Plants:Captive shredding for manufacturing scrap and packaging waste demands quick-change blade systems minimizing production line interruption. Automotive stamping plants in the US Midwest specify these for just-in-time scrap management.
- Packaging Firms:Post-consumer and post-industrial film reclaimers prioritize particle consistency for extrusion-grade flake production. Flexible packaging converters in Italy's Emilia-Romagna cluster specify tight-tolerance granulator blades.
- Manufacturers:Original equipment manufacturers procure blade sets for new shredder assembly and aftermarket replacement. Chinese industrial corridor cities drive volume for domestic shredder production.
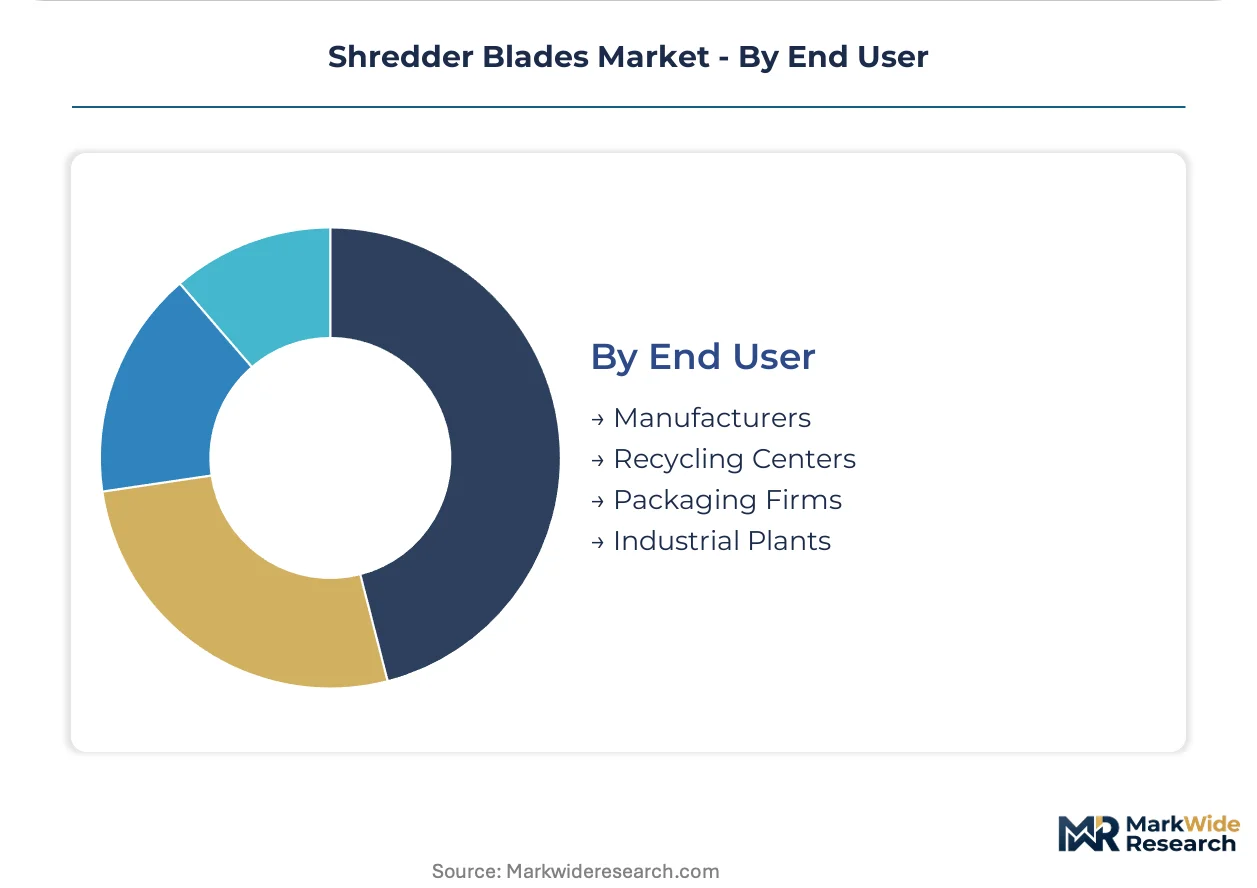
Contract value concentrates with Recycling Centers; margin capture favors Industrial Plants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial corridor cities concentrate the heaviest shredder blade procurement volume as municipal solid waste infrastructure expands at pace. Germany and the United States anchor developed-market demand through extended producer responsibility enforcement and recycling center modernization programs.
China
Yangtze River Delta recycling clusters specify double-shaft shredder systems for continuous-operation facilities handling post-consumer plastics and electronic scrap. The country's dual carbon goals tighten material recovery mandates under MEE oversight. Guangdong Province shredding equipment manufacturers scale blade production to serve domestic waste-to-energy plant rollouts.
Germany
Mechanical-biological treatment plants in North Rhine-Westphalia upgrade pre-sorting size reduction capacity for mixed municipal streams. REACH chemical traceability requirements drive blade material certification overhead for European equipment suppliers. The Ruhr corridor hosts concentrated procurement of performance-based blade supply contracts with guaranteed throughput metrics.
United States
Gulf Coast cement producers specify induction-hardened blade treatments for tire-derived fuel applications exceeding 8,000 operating hours. EPA emissions standards for municipal waste combustors shape blade housing design and access protocols. Midwest automotive stamping plants deploy quick-change blade systems for just-in-time scrap management.
India
Smart Cities Mission funding unlocks tender opportunities for integrated shredding-sorting systems in Tier-2 urban clusters. BIS standards govern equipment specification for municipal solid waste infrastructure tenders. Maharashtra and Gujarat material recovery facilities anchor initial fleet deployment of cost-sensitive alloy steel blade configurations.
Japan
Electronics waste processors favor high-speed steel alloys for circuit board pulverization under METI industrial recycling directives. Thermal cycling resistance determines blade specification for high-RPM granulator rotors. Kansai region industrial clusters concentrate precision grinding expertise for complex blade geometries.
Shredder Blades Market Competitive Landscape
German and Austrian producers anchor the premium alloy tier; Chinese fabricators hold volume positions in standard-grade supply. The vendor base splits between consolidated forging operations with captive heat treatment and specialized grinding houses serving aftermarket replacement cycles. Three archetypes dominate: precision metallurgy specialists, integrated shredder OEMs with captive blade production, and regional job shops serving municipal maintenance budgets. Capacity expansion and strategic partnerships represent the dominant competitive vectors as operators seek to lock in long-term service contracts.
Among European-based forging operations, Metso exemplifies the integrated OEM archetype through aftermarket blade replacement programs, while Kanefusa occupies a position within precision grinding specialists extending blade life in high-abrasion applications. American Cutting Edge represents domestic manufacturing scale advantages serving North American recycling centers with compressed lead times. These three anchors illustrate how competitive positioning stratifies across metallurgy capability, geographic proximity, and service model differentiation.
| Leading Market Players |
|---|
| CutPro Blades |
| Metso |
| TKM Group |
| Kanefusa |
| Andritz |
| American Cutting Edge |
| SATURN MACHINE KNIVES |
| Miheu d.o.o. |
| Zenith Cutter |
| Others |
Pricing and Supply Chain Analysis
Extended producer responsibility mandates in France and Germany are forcing blade suppliers to absorb REACH compliance documentation costs while maintaining price competitiveness against unregulated imports. This demand-side pressure compresses margins for European fabricators and accelerates procurement shifts toward certified Asian producers capable of bridging the cost-compliance gap.
Pricing Analysis
Volume procurement concentrates in standard-grade alloy steel configurations, while margin capture concentrates in precision-ground tool steel and high-speed steel tiers. Price differentiation rests on hardness certification tiers and guaranteed throughput metrics in performance-based contracts. Cost compression in standard-grade segments is intensifying because Chinese fabricators scale vacuum heat treatment capacity for export qualification. Municipal recycling centers in India and Southeast Asia exhibit highest price sensitivity; integrated waste management groups in Germany's Ruhr corridor and China's Yangtze River Delta demonstrate lowest sensitivity due to total-cost-of-ownership procurement frameworks.
Supply Chain Analysis
REACH Annex XIV authorization requirements for cobalt-containing hardfacing alloys function as qualification gates that filter out uncertified suppliers from European procurement channels. Specialty tool steel production draws from Sweden, Austria, and Japan, while precision grinding capacity concentrates in Germany and Japan. Single-source vulnerability exists in vacuum-degassed steel feedstock from Scandinavian mills. Distribution runs through OEM captive networks for new equipment and specialized grinding houses for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH chemical traceability and end-of-life recyclability documentation erects barrier-to-entry moats favoring European and Japanese incumbents with established certification infrastructure.
For Market Incumbents: Anticipate displacement pressure from tungsten carbide tipping in abrasive mineral waste applications by accelerating iron-based hardfacing alloy R&D. Defend position through backward integration into vacuum heat treatment capacity in Central Europe. Prioritize blade regrinding service contracts to lock in recurring revenue from municipal recycling center fleets. For New Entrants and Emerging Players: Capture tender opportunities in India's Smart Cities Mission Tier-2 urban clusters where BIS standards govern initial fleet deployment of cost-sensitive alloy steel configurations. Target biomass co-processing applications in Mediterranean cement markets requiring high-torque, low-speed shredder geometries with less entrenched incumbent presence. Lead with remanufacturing service capabilities to bypass capital-intensive forging barriers. For Investors and Strategic Acquirers: The window for entry favors precision grinding specialists with CNC profile expertise concentrated among aging technician populations in Germany and Japan. Long-term viability hinges on consolidation of mid-tier forging operations lacking captive heat treatment capacity. Watch for cobalt substitution acceleration in European blade formulations as inflection indicator for material science R&D intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Heat Treatment | Captive hardening capacity insulates margin from Swedish and Austrian steel mill pricing power. |
| Performance-Based Blade Supply Contracts | Guaranteed throughput metrics transfer wear-risk from China's Yangtze River Delta operators to manufacturers. |
| Blade Remanufacturing Service Expansion | Regrinding programs capture recurring revenue from continuous-operation facilities minimizing capital deployment. |
| Cobalt-Free Hardfacing Alloy Qualification | Iron-based alternatives maintain REACH compliance without sacrificing abrasion resistance in Benelux markets. |
| Precision Grinding Workforce Development | CNC profile expertise scarcity in Germany and Japan threatens blade geometry quality for complex applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with maintenance directors at municipal recycling centers, OEM procurement teams at shredder manufacturers, aftermarket service heads at industrial blade suppliers, and plant engineers at cement producers using tire-derived fuel were synthesized with ECHA REACH registration databases, EU Waste Framework Directive implementation reports, and BIS equipment certification records. Bottom-up blade volume estimates by shaft configuration and material grade were cross-validated against top-down waste processing capacity expansion data across the analysis window.
Reconciliation of customs export data, tender announcements from India's Smart Cities Mission, and capacity utilization surveys from German mechanical-biological treatment plants informed the projection framework. Segmentation modeling incorporated shaft configuration type, material hardness tier, application abrasiveness level, and end-user procurement sophistication across the projection horizon. CAGRs were derived from installed base expansion rates, replacement cycle compression factors, and alloy formulation upgrade penetration curves.
The model holds under stable REACH authorization timelines and continued extended producer responsibility enforcement in Europe; deviation in cobalt substitution acceleration or Chinese domestic demand absorption would shift volume and value trajectories. Forecasts reflect documented assumptions regarding blade life extension from induction-hardened surface treatments and workforce availability for precision grinding operations. A model refresh is warranted upon material change in EU chemical authorization requirements or MEE enforcement intensity under China's dual carbon goals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Wire Cutters Market
Tools
Cutting Equipment Market
Tools
Portable Grinders Market
Tools
Global Standard Parts for Tool Making Market
Tools
Power Tools Market
Tools
Surface Levelling Equipment Market
Tools
Belt File Sander Market
Tools
Post Drivers Market
Tools
Tool Storage Market
Tools
Europe Stump Cutter/Grinder Market
Tools
GCC Machine Tools Market
Tools
US Power Tools Market
Tools
Vinyl Bending Machine Market
Tools
Cordless Trim Routers Market
Tools
Diamond Hole Saw Market
Tools
Boring Tools Market