
 Drilling Tools Market | 2026-2036
Drilling Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Drilling Tools Market Intelligence
The application mix for drilling tools is shifting from a singular focus on oil and gas towards increased activity in geothermal drilling. Schlumberger leverages its extensive portfolio for complex directional drilling projects. Baker Hughes Company competes with integrated solutions for well construction and completion. NOV Inc. specializes in the design and manufacturing of high-performance downhole motors and equipment.
Drilling tools comprise a range of equipment designed to create boreholes by breaking or cutting rock formations. These tools, often featuring tungsten carbide or polycrystalline diamond compact (PDC) cutters, are engineered for specific lithologies and drilling conditions. PDC bits continue to gain share over traditional roller cone bits in many applications due to higher penetration rates. Within applications, onshore exploration remains the largest segment by volume, though offshore drilling requires more durable and technologically advanced components.
Equipment standards and operational safety are governed by international codes like ISO 10423 and national regulations from bodies such as the US Occupational Safety and Health Administration (OSHA). Environmental policies, including the EU Green Deal, indirectly steer tool development by incentivizing geothermal energy projects. Future profitability depends on balancing the development of durable, cost-effective tools for conventional drilling with high-performance solutions for emerging energy sectors.
Market Dynamics
The drilling tools market is being redefined by a fundamental diversification of energy applications. A structural shift away from a singular reliance on oil and gas exploration is creating parallel demand streams from geothermal energy and carbon sequestration projects, forcing tool development along divergent performance paths.
Growth Catalysts
- Geothermal Incentives:Policy frameworks like the EU Green Deal provide direct financial incentives and regulatory support for geothermal energy projects, stimulating demand for tools capable of drilling through hard, crystalline rock formations.
- PDC Cutter Technology:Continuous material science advancements in polycrystalline diamond compact (PDC) cutters are yielding higher rates of penetration and improved durability, expanding their application and displacing older bit technologies in onshore drilling.
- North American Exploration:Sustained exploration and production activities in the United States, spanning conventional oil and gas basins and emerging geothermal fields, create a large, consistent volume market for a wide range of drilling equipment.
Market Restraints
- Input Material Volatility:The price and supply of critical raw materials, particularly tungsten carbide and industrial-grade diamonds, are subject to significant market fluctuations and supply chain disruptions, impacting manufacturing costs and final product pricing.
- Extreme Environment Limitations:Tool durability remains a significant constraint in ultra-deepwater and high-pressure, high-temperature (HPHT) applications, where material degradation and component failure lead to costly non-productive time.
- Regulatory Compliance Burden:Stringent environmental regulations and operational safety standards, such as those enforced by the US Occupational Safety and Health Administration (OSHA), increase the complexity and cost of qualifying new drilling projects and equipment.
Strategic Opportunities
- Carbon Sequestration Drilling:The expansion of carbon capture, utilization, and storage (CCUS) initiatives creates a new application for specialized drilling tools designed for injecting CO2 into saline aquifers or depleted reservoirs.
- Digital Downhole Tools:Integrating real-time sensors and data analytics capabilities into downhole equipment offers a significant opportunity to provide predictive maintenance services and optimize drilling performance for operators.
- Geothermal Expansion:Underdeveloped geothermal resources, such as those in the East African Rift Valley or parts of Southeast Asia, represent significant greenfield opportunities for drilling service and tool providers.
Industry Challenges
- Specialized Talent Shortages:The industry faces a persistent shortage of experienced personnel, particularly directional drillers and measurement-while-drilling (MWD) engineers, capable of operating increasingly complex automated drilling systems.
- R&D Investment Intensity:Developing next-generation hybrid bits and high-torque downhole motors requires substantial and sustained capital investment in research, development, and testing, creating high barriers to entry.
- Certification Delays:The lengthy and rigorous process for achieving compliance with international standards like ISO 10423 can significantly delay the commercial launch of innovative tool designs, impacting first-mover advantage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drilling Tools Market |
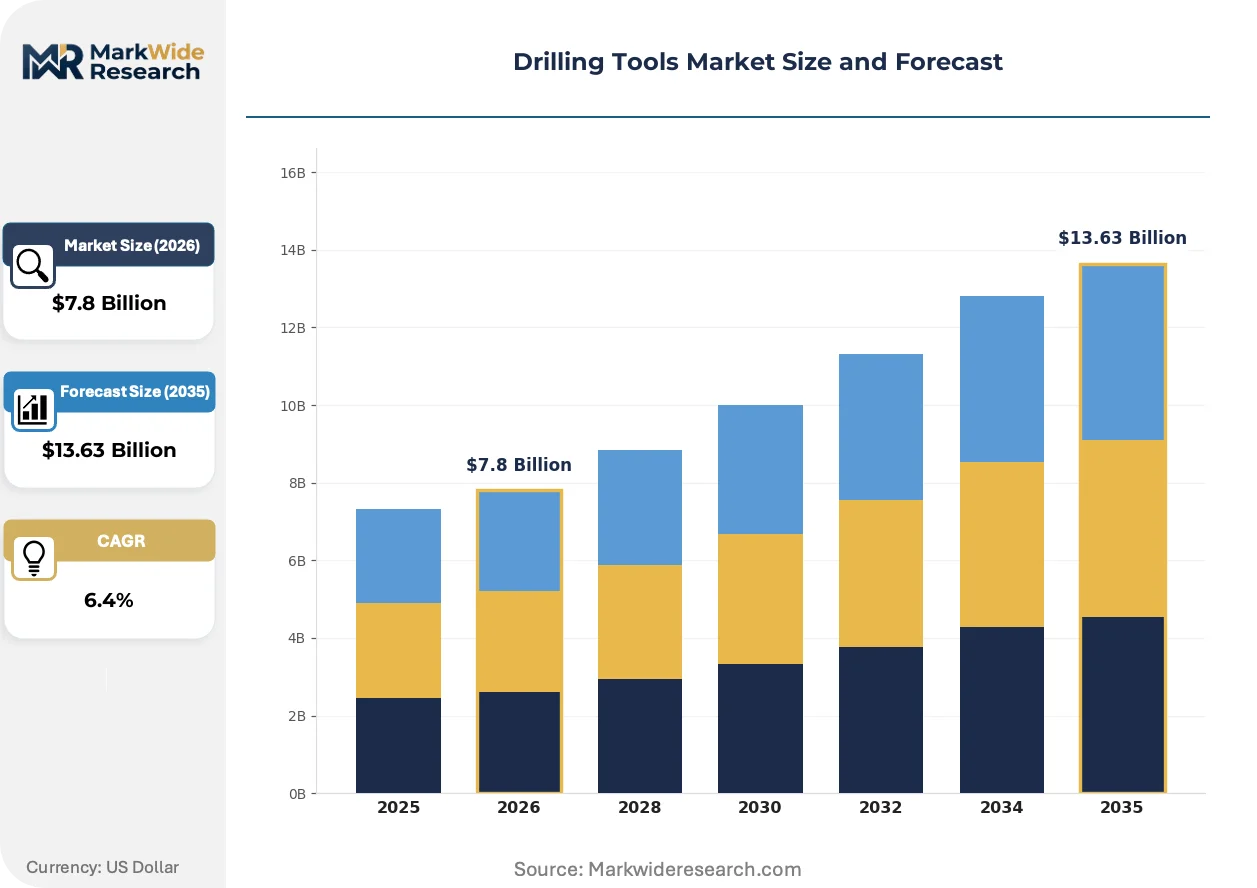
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Drilling Bits, Downhole Motors, Drill Collars, Stabilizers, Casing Accessories Technology: PDC Bits, Roller Cone Bits, Diamond Bits, Fixed Cutter Bits, Hybrid Bits Application: Onshore Exploration, Offshore Drilling, Directional Drilling, Geothermal Drilling, Mining Excavation End User: Oil & Gas Operators, Drilling Contractors, Well Service Companies, Energy Producers |
| Companies Covered | Schlumberger Limited, NOV Inc., Sandvik, Mincon, Weatherford International, Epiroc, Baker Hughes Company, LHS Rock Tools, Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drilling Tools Market Strategic Shifts & Innovations
The market is navigating a dual mandate, requiring manufacturers to enhance the cost-effectiveness of tools for conventional drilling while simultaneously pioneering high-performance solutions for emerging energy sectors. This dynamic fosters innovation in both materials and business models.
Hybrid bit technology combines the aggressive shearing action of PDC cutters with the impact-crushing force of traditional roller cone elements. Operators drilling through complex, interbedded formations are adopting these bits to reduce the number of trips needed to complete a well section. This technology is converging with advanced steerable motor assemblies to enable single-run drilling capabilities in previously uneconomic geological layers.
The US Inflation Reduction Act (IRA) provides substantial tax credits and financial support for developing geothermal energy and carbon sequestration projects. This policy directly stimulates investment in drilling campaigns outside of the traditional hydrocarbon sector, creating new revenue streams. Tool manufacturers are actively responding by engineering products optimized for the specific thermal gradients and lithologies encountered in these new applications.
Operators are increasingly adopting performance-based contracts for drilling tool services, moving away from standard day-rate rental agreements. This model directly links supplier compensation to operational metrics like rate of penetration (ROP) and overall drilling efficiency. The shift is most visible in high-cost offshore projects, particularly in the North Sea and the Gulf of Mexico, where maximizing rig time is critical.
Drilling Tools Market Segmentation
Understanding the segmentation of the drilling tools market is critical for manufacturers to align product development with evolving energy sector demands. This detailed breakdown highlights areas of established volume and emerging growth opportunities across diverse applications.
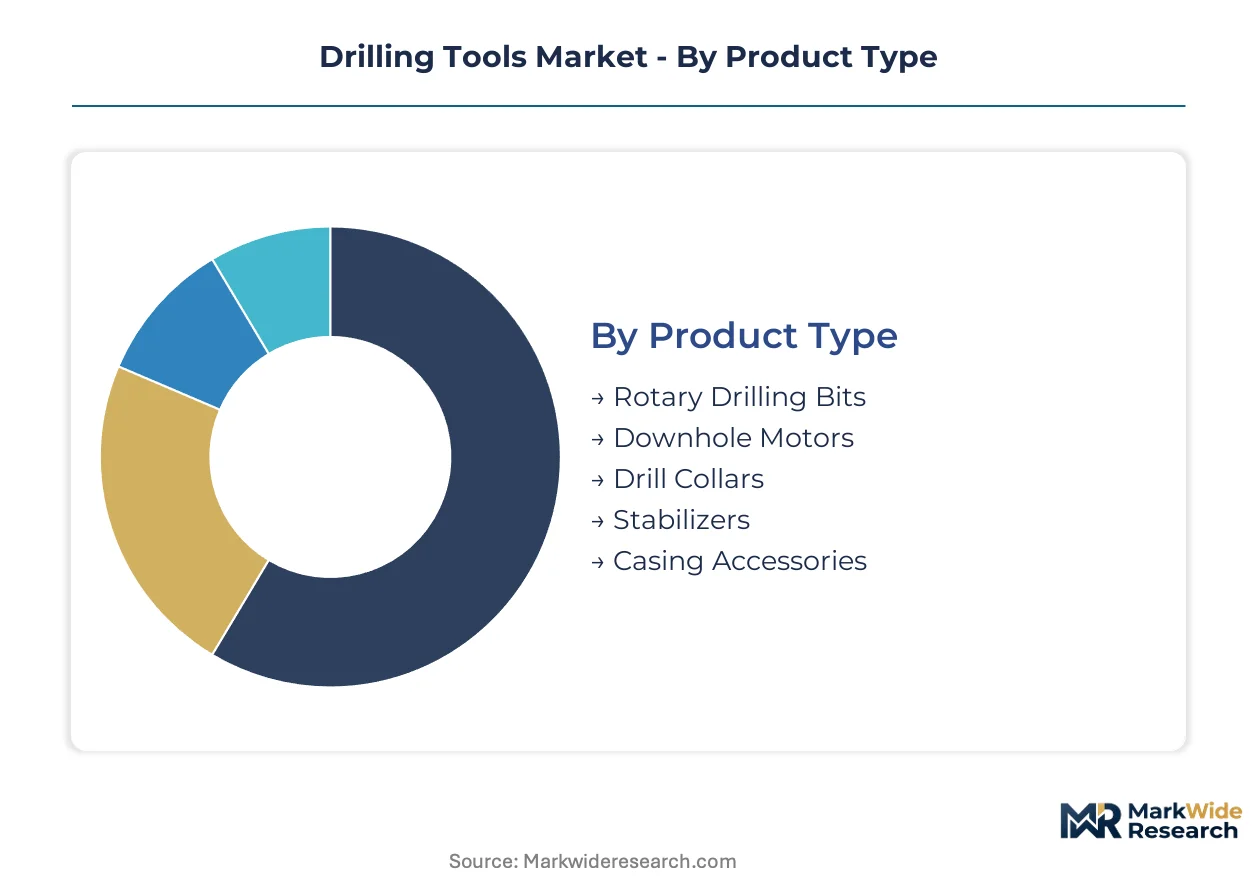
Product Type:
The market for drilling tools differentiates significantly by product type, reflecting the integration depth required for various drilling operations.
- Rotary Drilling Bits:These tools feature cutting structures designed to break rock through mechanical rotation, often incorporating tungsten carbide inserts or PDC cutters for optimal performance. Demand concentrates in conventional oil and gas exploration, driven by the need for cost-effective penetration rates in varied lithologies.
- Downhole Motors:These positive displacement motors convert drilling fluid hydraulic energy into mechanical power at the bit, enabling directional control and enhanced rate of penetration. Their application is expanding in complex well designs, particularly in unconventional shale plays across North America.
- Drill Collars:Heavy steel pipes provide weight on bit and stiffen the drill string, preventing buckling during drilling operations.
- Stabilizers:Components used to maintain borehole gauge and prevent drill string vibration, crucial for wellbore quality.
- Casing Accessories:Equipment like centralizers and float shoes support the integrity and placement of casing strings within the wellbore.
Volume placements concentrate in Rotary Drilling Bits; the faster expansion belongs to Downhole Motors.
Technology:
Technological advancements define distinct performance tiers within drilling tools, dictating efficiency and application scope.
- PDC Bits:Polycrystalline Diamond Compact bits utilize synthetic diamond cutters for superior abrasion resistance and high rates of penetration in various rock formations. These bits are gaining significant traction in onshore drilling, displacing older technologies due to enhanced durability and efficiency.
- Hybrid Bits:Combining PDC cutters with roller cone elements, these bits offer a balanced approach to drilling through interbedded and complex geological formations. Operators in the Gulf of Mexico are increasingly adopting hybrid designs for single-run capabilities in challenging deepwater environments.
- Roller Cone Bits:These bits employ rotating cones with teeth or inserts to crush and shear rock, suitable for a wide range of formations.
- Diamond Bits:Bits featuring natural or synthetic diamonds for drilling through extremely hard and abrasive formations, often used in mining and geothermal projects.
- Fixed Cutter Bits:Bits with no moving parts, relying on the shearing action of fixed cutters to remove rock, favored for stability and durability.
PDC Bits are gaining market share rapidly, while Hybrid Bits exhibit the steepest expansion trajectory.
Application:
Drilling tool applications range across diverse operational environments, each demanding specialized equipment capabilities.
- Onshore Exploration:This segment involves drilling wells on land for oil, gas, and geothermal resources, representing the largest volume market for standard and advanced drilling tools. Sustained activity in the Permian Basin drives consistent demand for a broad range of equipment.
- Geothermal Drilling:Specialized tools are required for drilling through hard, crystalline rock formations at high temperatures and pressures to access geothermal energy reservoirs. Policy frameworks like the EU Green Deal are stimulating investment in this application across Europe.
- Offshore Drilling:Operations conducted in marine environments, demanding highly durable and technologically advanced tools for deepwater and ultra-deepwater wells.
- Directional Drilling:The practice of steering a wellbore along a planned path, requiring specialized downhole motors and measurement-while-drilling (MWD) tools.
- Mining Excavation:Drilling tools used for creating boreholes in mining operations, distinct from oil and gas, focusing on mineral extraction.
Onshore Exploration continues to command the largest volume, with Geothermal Drilling expanding most quickly.
End User:
The end-user landscape for drilling tools reflects varying operational scales and procurement models across the energy sector.
- Oil & Gas Operators:These companies directly own and manage exploration and production activities, making significant capital investments in drilling tools and services. Major operators like ExxonMobil and Shell drive demand for high-performance solutions in complex projects.
- Drilling Contractors:Firms specializing in providing drilling services to operators, often owning and maintaining fleets of drilling rigs and associated tools. Schlumberger and Baker Hughes Company are prominent players in this segment, offering integrated solutions.
- Well Service Companies:Providers of specialized services for well construction, completion, and intervention, often requiring specific tools for their operations.
- Energy Producers:A broader category encompassing entities involved in electricity generation or other energy forms, including those developing geothermal or carbon sequestration projects.
Oil & Gas Operators represent the largest purchasing segment, though Drilling Contractors are increasingly influencing tool selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Inflation Reduction Act (IRA) significantly influences drilling tools demand by incentivizing geothermal and carbon sequestration projects. This policy framework directs investment towards non-traditional drilling applications, complementing established hydrocarbon exploration. Global energy transition initiatives are reshaping regional market dynamics across various continents.
United States
Sustained oil and gas activities in the Permian Basin drive consistent demand for drilling equipment. The US Occupational Safety and Health Administration (OSHA) mandates stringent safety standards for all drilling operations. Texas remains a central hub for oilfield services, with Houston serving as a major center for drilling technology development.
Germany
Geothermal energy projects are expanding across Germany, creating demand for specialized high-temperature drilling tools. The EU Green Deal provides policy support and financial incentives for these renewable energy initiatives. The Upper Rhine Graben region sees significant geothermal drilling activity, attracting tool manufacturers and service providers.
Saudi Arabia
Large-scale conventional oil and gas production projects continue to drive substantial demand for advanced drilling tools. The Kingdom's Vision 2030 initiatives include significant investment in carbon capture, utilization, and storage (CCUS) projects. Aramco's operations in the Eastern Province represent a major concentration of drilling and well construction activities.
China
Expanding domestic energy demand supports continuous exploration in both conventional and unconventional oil and gas fields. The national dual carbon goals are stimulating investment in CCUS and deep geothermal projects. The Sichuan Basin is a key area for unconventional gas drilling, requiring high-performance downhole equipment.
Australia
Extensive mining operations and offshore gas projects necessitate robust and durable drilling tools across diverse lithologies. Environmental regulations, including those from the Department of Climate Change, Energy, the Environment and Water, influence drilling practices. Western Australia remains a critical region for mining and offshore energy exploration, attracting significant investment.
Drilling Tools Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied operational complexities and customer requirements. The drilling tools market exhibits a tiered structure, with global service providers occupying the premium segment and specialized equipment manufacturers filling niche requirements. Strategic archetypes include integrated solution providers, pure-play equipment manufacturers, and regional specialists focusing on specific lithologies or applications. Companies frequently engage in portfolio diversification and technology licensing to maintain competitive positioning, while others pursue strategic partnerships to expand geographic reach.
Global service providers such as Schlumberger Limited exemplify the comprehensive solution archetype, leveraging extensive portfolios for complex directional drilling projects. Baker Hughes Company also occupies a significant position among integrated providers, competing with a broad range of well construction and completion solutions. These firms often target high-value offshore projects and unconventional plays. NOV Inc. sits within the specialized equipment manufacturer archetype, focusing on the design and manufacturing of high-performance downhole motors and other critical drilling equipment for global operators. These distinct approaches underscore the varied strategies employed by major industry participants.
| Leading Market Players |
|---|
| Schlumberger Limited |
| NOV Inc. |
| Sandvik |
| Mincon |
| Weatherford International |
| Epiroc |
| Baker Hughes Company |
| LHS Rock Tools |
| Halliburton Company |
| Others |
Cost & Logistics Intelligence
Hybrid bit technology, integrating PDC cutters and roller cone elements, simultaneously reshapes cost economics by reducing trip times and concentrates supply among specialized manufacturers with advanced material science capabilities.
Pricing Analysis
Premium pricing for short lead times characterizes the drilling tools market, with discounts for readily available inventory. Contract-based long-term agreements dominate for major operators, while smaller jobs often use transactional pricing. Certification level, particularly ISO 10423 compliance, and customization for specific lithologies drive price differentiation. Pricing softness reflects intense competition for conventional drilling projects. Smaller drilling contractors are most price-sensitive, while major oil & gas operators prioritize performance over cost in complex applications.
Supply Chain Analysis
Tungsten carbide and industrial-grade diamond supply rests on concentrated mining and processing hubs in China and South Africa. Key dependencies include high-purity steel for drill collars and specialized elastomers for downhole motor components. Commodity price volatility for critical raw materials poses a structural risk to manufacturing costs. Distribution runs through a network of specialized equipment manufacturers and global oilfield service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drilling tools market is a supply-constrained story, with specialized manufacturing capacity for high-performance PDC cutters currently propping pricing for advanced tools.
For Market Incumbents: Deploy advanced material science R&D to counter the threat of new hybrid bit technologies from agile specialists. Invest in next-generation PDC cutter development to maintain performance leadership in challenging formations. Deepen integration with key raw material suppliers to mitigate commodity price volatility. Prioritize certification investment for new tool designs, ensuring compliance with international standards like ISO 10423.
For New Entrants and Emerging Players: Enter via niche applications, targeting underdeveloped geothermal resources in regions like the East African Rift Valley. Focus on specialized tools for carbon sequestration drilling, addressing a growing demand for CCUS projects. The most penetrable segment remains geothermal drilling in emerging markets. Implement performance-based contracts for specialized equipment to build market share and demonstrate value.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated equipment manufacturers with strong intellectual property in downhole motor technology. Long-term viability hinges on diversification into renewable energy drilling applications. Acquisition targets should possess proprietary material science expertise or advanced digital downhole tool capabilities. Increased M&A activity for digital downhole tool providers signals a key inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding manufacturing for PDC cutters addresses supply bottlenecks for high-performance drilling tools. |
| Technology Licensing | Licensing hybrid bit designs accelerates market penetration for specialized drilling applications. |
| Strategic Partnership | Partnering with geothermal project developers secures early market access for specialized tools. |
| Product Launch | Introducing real-time sensor-equipped downhole tools enhances operational efficiency for operators. |
| Certification Investment | Achieving ISO 10423 compliance validates new tool designs for global drilling projects. |
Research Approach
Independent corroboration across regulatory filings, industry association reports, and trade publications underwrites the qualitative findings. Primary interviews with drilling engineers, procurement managers at E&P companies, R&D directors at tool manufacturers, and field service technicians informed market dynamics. Secondary validation utilized EIA data, IEA reports, and company annual reports. Bottom-up market sizing from regional demand drivers and top-down validation against global production capacities ensured accuracy.
Historical market performance across comparable periods anchored the forecast window, ensuring a robust baseline for future projections. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional energy policy impact. Compounded annual growth rates were derived from regression analysis of historical trends and projected demand shifts. Global energy demand forecasts and raw material cost projections served as key industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme commodity price volatility. Forecasts reflect assumptions regarding geopolitical stability and technological adoption rates. Supply chain disruptions for critical materials or unexpected regulatory shifts could revise projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Cordless Blind Rivet Gun Market
Tools
Electric Power Tools Market
Tools
Thickness Planers Market
Tools
Brazing Torch Market
Tools
Cordless Power Drill Market
Tools
Global Diamond Tools Market
Tools
Taps and Dies Market
Tools
Mallets and Sledgehammers Market
Tools
Wood-Sanding Machine Market
Tools
Woodworking Sanders Market
Tools
Workholding Tools Market
Tools
Auger Drill Bits Market
Tools
Indexable Tool Inserts Market
Tools
Scroll Saws Market
Tools
Power Tool Gears Market
Tools
Surface Planer Market