
 Striking Tools Market | 2026-2036
Striking Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Striking Tools Market Analytics
Modular head-and-handle configurations is decoupling traditional one-piece forged designs from buyer expectations, letting users swap fiberglass or composite shafts without replacing the entire tool. Milwaukee Tool leverages this shift through battery-integrated striking platforms that bridge corded and cordless jobsite workflows. DeWalt anchors its position with dense retail distribution across big-box home improvement channels. Estwing sustains loyalty among finish carpenters who prefer solid steel forging for balance and longevity.
Striking tools are percussive implements designed to deliver controlled impact force through hardened faces, with specifications typically covering head weight, handle length, and strike face hardness measured on the Rockwell C scale; they serve to drive fasteners, shape metal, demolish structures, or extract components in industrial and construction environments. Hammers and sledges occupy the largest volume tier, though margin pools concentrate in composite-handled variants where material science commands price premiums over basic steel or wood alternatives. The DIY end-user segment trails professional construction in absolute spend but shows faster velocity through online channels where first-time buyers compare material specifications before purchase.
OSHA vibration exposure limits and ISO 15601 hand-transmitted vibration standards are reshaping handle design requirements, pushing manufacturers toward dampened composites and ergonomic geometries that reduce repetitive strain liability. The EPA monitors foundry emissions from steel head production, adding compliance layers to domestic forging operations. Stakeholders must monitor how regulatory convergence on worker safety and environmental controls reshapes cost structures for material sourcing and product certification.
Market Dynamics
Modular head-and-handle architectures are fragmenting traditional forging economics, forcing manufacturers to choose between vertical integration into composite supply chains or surrendering margin to specialized shaft suppliers.
Growth Catalysts
- Federal infrastructure spending:The Infrastructure Investment and Jobs Act sustains above-average procurement volumes for professional-grade hammers and sledges across United States construction sites.
- OSHA vibration exposure limits:Workplace safety mandates tighten grip requirements and anti-vibration standards, accelerating replacement cycles for non-compliant legacy inventory.
- Composite material science:Fiberglass and carbon-fiber handle innovations command price premiums over basic steel or wood alternatives, expanding margin pools in the premium tier.
Market Restraints
- Steel price volatility:Foundry input costs for high-carbon and alloy steels fluctuate with scrap metal and energy markets, compressing forging margins unpredictably.
- Supply concentration in China:Dominant share of forged head production sits with integrated steel-and-tool manufacturers in Hebei and Shandong provinces, creating geopolitical and tariff exposure.
- Hand-transmitted vibration standards:ISO 15601 compliance requires expensive redesign of legacy product lines, raising R&D amortization burdens for mid-tier competitors.
Strategic Opportunities
- Underpenetrated India infrastructure:National highway and urban housing programs generate latent demand for contractor-grade striking tools as mechanization spreads beyond tier-one cities.
- Battery-integrated striking platforms:Convergence of cordless power tool ecosystems with traditional percussive implements opens hybrid workflows for demolition and framing crews.
- EU Green Deal procurement rules:Public works contracts increasingly specify low-carbon manufacturing credentials, rewarding early movers with domestic foundry emissions controls.
Industry Challenges
- Ergonomic design talent scarcity:Biomechanical engineering expertise for vibration-dampened handle geometries concentrates at a handful of specialized consultancies and university labs.
- Multi-standard certification timelines:Simultaneous pursuit of OSHA, ISO, and CE marking approvals extends product launch windows by 12-18 months for modular designs.
- Legacy distributor integration:Big-box retail partners resist SKU proliferation from modular component systems, demanding finished-goods packaging that undermines head-and-handle separability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Striking Tools Market |
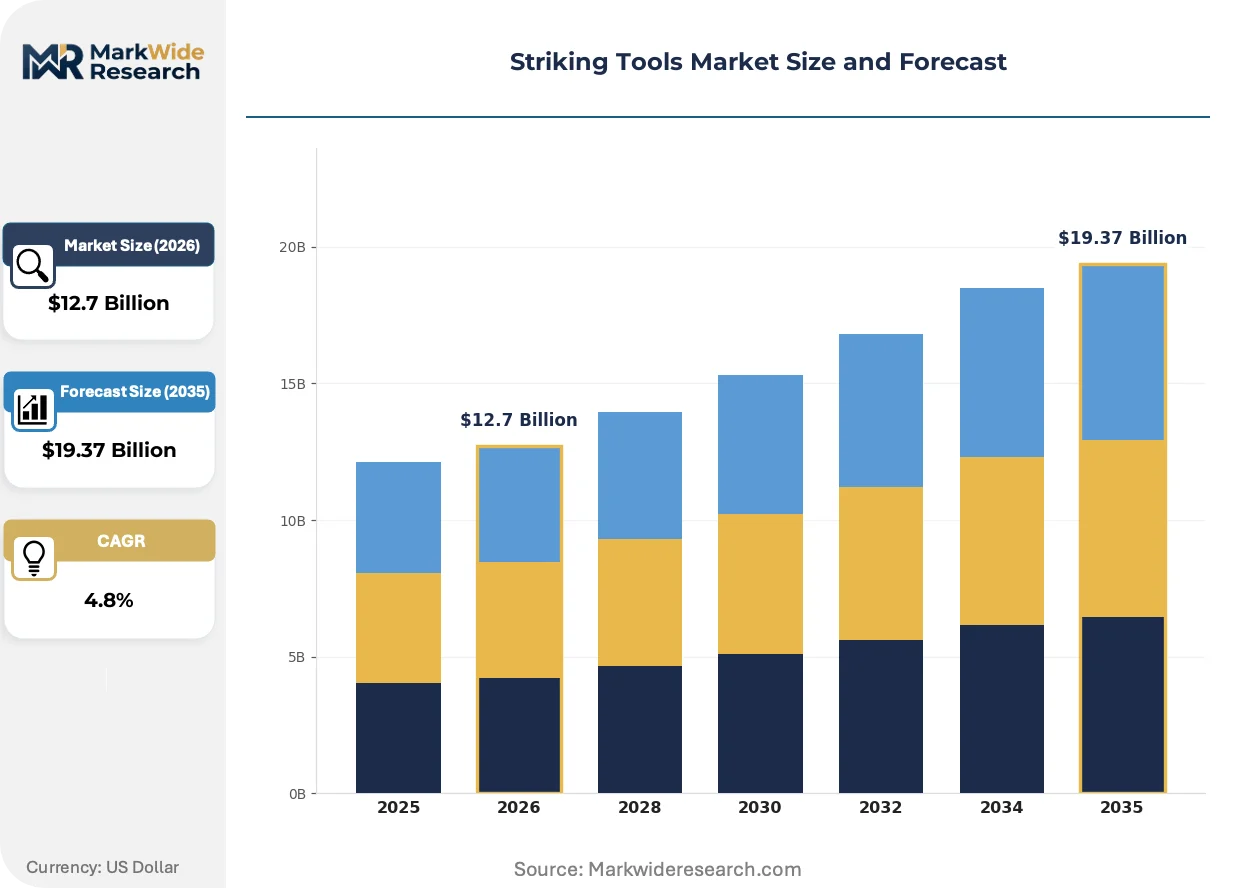
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $19.37 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Hammers, Mallets, Sledgehammers, Prying Tools Material: Steel, Aluminum, Fiberglass, Composite End User: Construction, Automotive, Manufacturing, DIY Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Milwaukee Tool, Makita, Estwing, Stahlwille, Hilti, Snap-on, RIDGID, Knipex, DeWalt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Striking Tools Market Evolving Landscape
Active redesign of the handle-to-head interface is collapsing traditional product lifecycles, creating new competitive terrain around material substitution and serviceable design rather than raw durability metrics.
Interchangeable composite shaft systems is modularizing the economics of tool ownership. Finish carpenters and restoration contractors now specify handle stiffness and grip geometry independently from head weight and face hardness. This technology is compressing replacement spending from full-tool purchases toward component-level refresh cycles, eroding the revenue predictability that solid-forged designs once guaranteed.
REACH substance restrictions on chromium VI in surface treatments are forcing European foundries to migrate toward trivalent chrome and ceramic-based corrosion protection. The industrial consequence is elevated processing cost for export-oriented manufacturers serving EU markets. Contractors in Germany and France now specify coating compliance certificates in competitive tenders, shifting procurement criteria beyond functional performance toward documented chemical safety.
Professional buyers are consolidating vendor relationships around suppliers offering lifecycle vibration monitoring and ergonomic certification documentation. Big-box retail channels face disintermediation pressure as direct-to-contractor digital platforms aggregate specification data and bulk pricing for multi-project fleet purchases. This behavioral pivot is most visible in United States residential construction, where general contractors increasingly bypass distributor markup for factory-direct procurement of certified tool fleets.
Striking Tools Market Segmentation
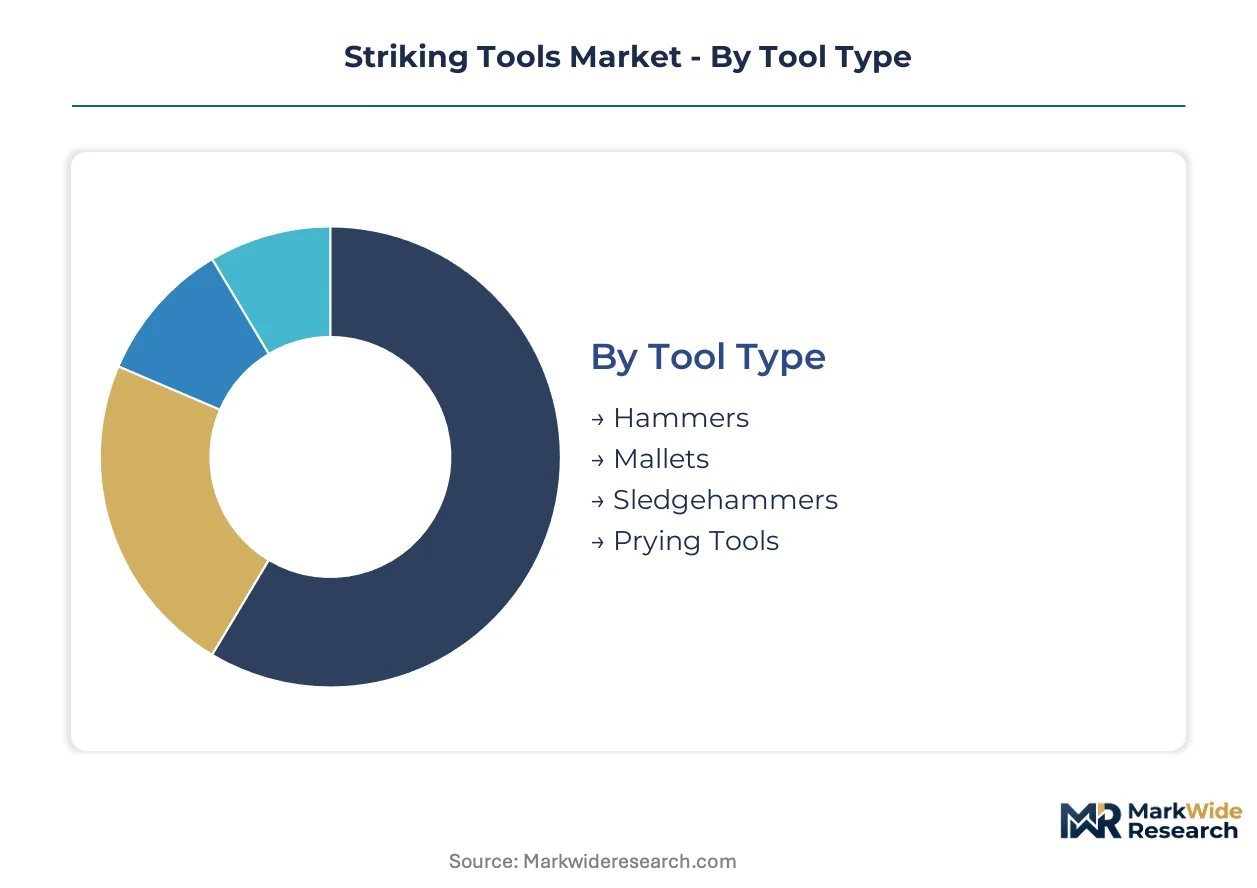
Striking tools fragment across four structural dimensions that reshape procurement economics and margin capture. Tool type and material composition determine capital deployment intensity, while end-user concentration and channel mix dictate pricing power and inventory velocity.
Tool Type:
Capital intensity varies sharply across tool categories, with forged steel heads demanding foundry investment while molded polymer faces require precision molding infrastructure.
- Hammers:Claw hammers and framing hammers dominate procurement volumes through hardened steel faces rated 50-55 Rockwell C. Residential construction contractors in the United States sustain replacement cycles as OSHA anti-vibration mandates accelerate retirement of legacy one-piece forged designs.
- Sledgehammers:Double-face sledges with head weights from 2.3 to 9.1 kilograms absorb the heaviest capital allocation in forging equipment due to alloy steel requirements and heat-treatment complexity. Federal infrastructure spending across United States highway and bridge projects sustains above-average fleet procurement for demolition and driving applications.
- Mallets:Soft-face implements with rubber, wood, or rawhide striking surfaces serve finish carpentry and metal forming where surface protection matters. Woodworking shops and automotive body repair facilities specify non-marring faces for assembly and panel alignment tasks.
- Prying Tools:Crowbars, wrecking bars, and alignment tools extend leverage rather than pure impact force. Industrial maintenance crews and salvage operators integrate these with striking implements for fastener extraction and structural dismantling.
Hammers absorb the bulk of installed capacity; sledgehammers are expanding most quickly through infrastructure procurement.
Material:
Raw material selection drives cost structure divergence, with commodity steel at one pole and engineered composites commanding price premiums through performance differentiation.
- Steel:High-carbon and alloy steel heads remain the baseline specification for professional-grade durability and face hardness retention. Foundry emissions compliance under EPA monitoring adds processing cost layers to domestic forging operations serving United States contractors.
- Composite:Fiberglass-reinforced polymer handles with steel or titanium heads concentrate margin expansion through vibration dampening and ergonomic geometry. ISO 15601 hand-transmitted vibration certification requirements push specification shifts in European and North American professional markets.
- Aluminum:Lightweight head alloys reduce operator fatigue in overhead applications and extended-use scenarios. Aviation maintenance and overhead electrical contractors specify aluminum for repetitive striking tasks where mass reduction improves productivity.
- Fiberglass:Pure fiberglass construction appears primarily in handle shafts rather than heads, offering electrical insulation and corrosion resistance for utility and marine environments.
Steel retains the dominant share of production volume; composite configurations climb the fastest through safety-mandated replacement cycles.
End User:
Customer type determines specification sophistication, with professional segments demanding certified performance documentation and DIY buyers prioritizing price accessibility.
- Construction:General contractors and specialty trades specify modular head-and-handle systems allowing field replacement and ergonomic customization. United States residential and commercial building permits correlate directly with professional-grade hammer and sledge procurement velocity.
- Manufacturing:Assembly lines and metal fabrication shops specify calibrated striking force for repetitive production tasks. Automotive stamping plants and machinery assembly operations integrate striking tools with torque-controlled fastening workflows.
- Automotive:Body repair, tire service, and maintenance bays require compact hammers and soft-face mallets for panel work and wheel mounting. Fleet maintenance operations standardize tool specifications across multiple service locations.
- DIY:Home improvement enthusiasts purchase through retail and online channels where first-time buyers compare material specifications before committing. E-commerce platforms aggregate reviews and certification data that influence brand selection.
Construction absorbs the bulk of installed capacity; DIY channels gain share fastest through digital procurement platforms.
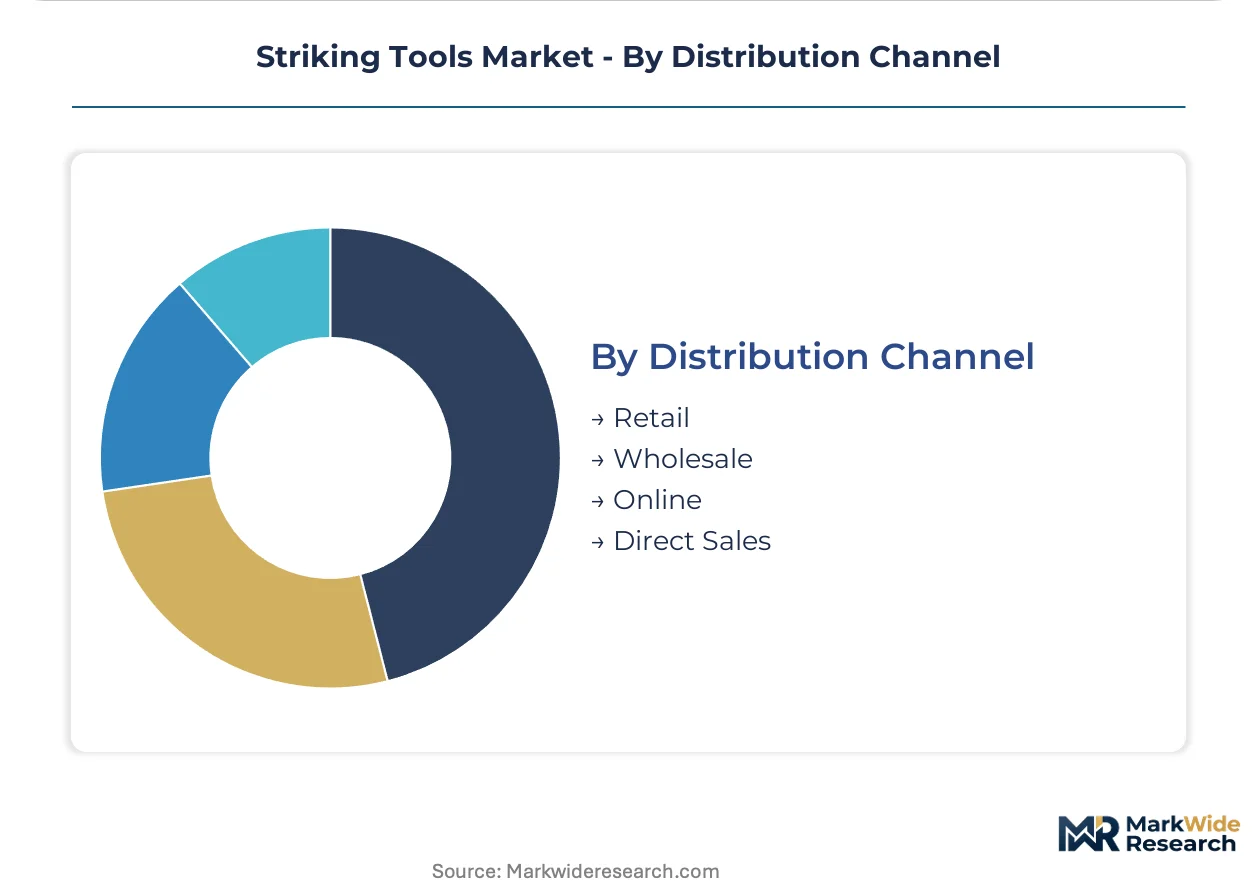
Distribution Channel:
Channel economics fragment between high-touch service models and low-margin volume throughput, with inventory carrying costs and technical consultation requirements driving structural separation.
- Retail:Big-box home improvement chains anchor consumer and light professional procurement through dense geographic coverage and immediate availability. DeWalt and competing brands leverage shelf placement for brand visibility among first-time buyers.
- Wholesale:Industrial distributors serve contractor fleets with volume pricing, consolidated billing, and jobsite delivery logistics. Multi-project general contractors in the United States consolidate vendor relationships around wholesale partners offering lifecycle certification documentation.
- Direct Sales:Factory-direct procurement bypasses distributor markup for large fleet purchases and custom specification orders. Professional buyers increasingly aggregate bulk pricing through direct digital platforms.
- Online:E-commerce channels aggregate specification comparison and review data that accelerates purchase decisions among research-oriented buyers. DIY segment velocity runs fastest through online channels where material science education precedes transaction.
Retail channels absorb the bulk of transaction volume; online platforms expand most quickly through specification transparency and review aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the United Arab Emirates concentrate high-volume distribution for Middle East and African markets, while bonded warehousing in Singapore anchors Asia-Pacific logistics. Regional procurement patterns diverge sharply between mature safety-regulated markets and emerging infrastructure economies.
United States
Residential housing starts and federal highway spending sustain professional-grade hammer procurement above replacement rates. OSHA vibration exposure mandates accelerate retirement of legacy forged designs among construction contractors. Tool distribution clusters around Chicago, Dallas-Fort Worth, and Atlanta metropolitan areas where big-box retail density supports immediate availability.
Germany
Automotive stamping plants and machinery assembly lines specify calibrated striking force for repetitive production workflows. REACH substance restrictions on chromium VI force migration toward trivalent chrome and ceramic-based corrosion protection. Industrial procurement concentrates in Baden-Württemberg and Bavaria where automotive OEMs standardize tool specifications across supplier networks.
China
National highway programs and urban housing construction generate demand for contractor-grade sledges as mechanization spreads beyond tier-one cities. Dual carbon goals and MEE emissions monitoring add compliance layers to foundry operations in Hebei and Shandong provinces. Production gravity sits with integrated steel-and-tool manufacturers serving export markets through Ningbo and Qingdao port zones.
India
National infrastructure corridors and smart city initiatives expand demand for demolition and framing implements. BIS certification requirements for hand tools create entry barriers for unorganized sector suppliers. Procurement velocity concentrates in Maharashtra and Gujarat where contractor fleets scale through direct-import arrangements from East Asian manufacturers.
United Arab Emirates
Expo legacy construction and renewable energy projects sustain above-average sledgehammer fleet turnover among demolition specialists. Dubai Municipality building codes specify anti-vibration equipment for worker protection on high-rise sites. Jebel Ali Free Zone warehousing positions the emirate as re-export hub for Saudi Arabian and Egyptian construction markets.
Striking Tools Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered structure where scale advantages clash with ergonomic design depth. The vendor base separates into three strategic archetypes: battery-integrated platform builders leveraging cordless ecosystems, heritage forging houses defending solid-steel loyalty, and composite material specialists capturing safety-mandated replacement cycles. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers balance vertical control against specialized shaft sourcing.
Among heritage forging specialists, Estwing and Stahlwille occupy positions defined by metallurgical tradition and geographic origin. Milwaukee Tool exemplifies the battery-integrated archetype, bridging corded and cordless jobsite workflows through power tool ecosystem convergence. These three anchors illustrate how competitive positioning fragments between durability-centric legacy positioning and technology-forward hybrid platforms.
| Leading Market Players |
|---|
| Milwaukee Tool |
| Makita |
| Estwing |
| Stahlwille |
| Hilti |
| Snap-on |
| RIDGID |
| Knipex |
| DeWalt |
| Others |
Value Network & Pricing Analysis
OSHA anti-vibration mandates among United States construction contractors are forcing rapid retirement of legacy one-piece forged designs, compelling supply chains to pivot toward composite handle sourcing and modular assembly economics that compress margins on basic steel configurations while expanding premium tier pricing power.
Pricing Analysis
Short lead-time premiums dominate contractor procurement decisions as United States infrastructure projects demand immediate jobsite availability, while spot inventory discounts attract price-sensitive DIY buyers through big-box retail channels. Pricing stratifies across premium, standard, and economy tiers where ISO 15601 certification commands measurable premiums over uncertified alternatives. Cost compression in steel-forged baselines is intensifying because foundry input volatility and EPA emissions compliance layers erode traditional margin structures. Professional construction fleets show lowest price sensitivity due to safety liability exposure, while first-time DIY buyers exhibit highest elasticity as online specification comparison drives brand switching.
Supply Chain Analysis
Workforce availability constraints in Hebei and Shandong provinces are tightening output elasticity for forged head production as China's dual carbon goals and MEE emissions monitoring reshape foundry labor requirements. Supply concentrates in China for integrated steel-and-tool manufacturing, with secondary capacity in India and Germany serving regional certification markets. Raw material feeds draw from high-carbon steel scrap markets, fiberglass polymer resin supply chains, and trivalent chrome surface treatment chemicals. Tariff exposure on Chinese forged heads creates structural vulnerability for North American distributors. Distribution runs through Jebel Ali Free Zone warehousing for Middle East re-export, bonded Singapore facilities for Asia-Pacific, and Chicago-Dallas-Atlanta clusters for United States retail density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around modular platform builders as ISO 15601 compliance costs and multi-standard certification timelines force mid-tier forging houses into distressed exit or acquisition.
For Market Incumbents: Cement ecosystem lock-in through battery-integrated striking platforms that bridge cordless power tool workflows, while capturing backward integration into composite shaft supply chains before specialized suppliers consolidate pricing power. Defend against emerging composite material specialists by accelerating ergonomic certification documentation that big-box retail partners increasingly demand for shelf placement. For New Entrants and Emerging Players: Begin with underpenetrated contractor fleet procurement in India where BIS certification barriers filter out unorganized competition and national infrastructure corridors expand demand. Target direct-to-contractor digital platforms that aggregate bulk pricing and specification transparency, bypassing wholesale distributor markups that incumbents rely upon for margin protection. For Investors and Strategic Acquirers: The window for entry favors heritage forging houses with solid-steel brand loyalty among finish carpenters, as safety-mandated replacement cycles create acquisition opportunities at compressed valuations. Watch for inflection when REACH substance restrictions on chromium VI surface treatments force European foundry consolidation, signaling broader regulatory convergence that rewards early movers with domestic emissions controls.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Shaft Supply | Captures margin from specialized fiberglass suppliers as modular designs displace one-piece forging economics. |
| Battery-Integrated Platform Development | Milwaukee Tool's cordless ecosystem convergence creates hybrid workflow lock-in among demolition and framing crews. |
| ISO 15601 Certification Acceleration | Expands premium tier pricing power as OSHA vibration mandates force professional fleet replacement cycles. |
| Direct-to-Contractor Digital Platform Launch | Bypasses wholesale distributor resistance to SKU proliferation from modular head-and-handle systems. |
| EU Green Deal Procurement Positioning | Rewards early movers with domestic foundry emissions controls as public works contracts specify low-carbon credentials. |
Research Methodology
Document review covered SEC filings from publicly traded tool manufacturers, EPA foundry emissions monitoring reports, and OSHA workplace safety enforcement data, complemented by interviews with procurement directors at United States general contracting firms, product managers at big-box retail chains, and composite material engineers at specialized shaft suppliers. Secondary validation drew from customs trade databases tracking forged head imports, infrastructure spending appropriations from the Infrastructure Investment and Jobs Act, and ISO certification registry records. Bottom-up demand modeling triangulated against top-down market sizing from production capacity estimates across Hebei and Shandong manufacturing zones.
Unit volume and value projections across the analysis window employed a segmented analytical framework spanning tool type, material composition, end-user concentration, and distribution channel mix. CAGRs derived from regression analysis against macroeconomic drivers including United States housing starts, federal highway obligation rates, and European automotive production indices. Industry-specific forecast inputs incorporated OSHA enforcement trajectory modeling and REACH substance restriction implementation timelines.
Underlying measurement precision varies by segment; professional construction and manufacturing end-use categories carry tighter precision than fragmented DIY channels where online purchase behavior shifts rapidly. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and infrastructure appropriation continuity. Material deviation in steel scrap price volatility or geopolitical tariff adjustments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Indexable Inserts Market
Tools
Wire Cutters Market
Tools
Drill Presses Market
Tools
Global Standard Parts for Tool Making Market
Tools
Cordless Trim Routers Market
Tools
Global Swaging Machine Market
Tools
Landscaping Tools Market
Tools
Reamer Market
Tools
Tool Pliers Market
Tools
CNC Leather Cutting Machine Market
Tools
Tool Hammer Market
Tools
Fine Blanking Tools Market
Tools
Tool Storage Market
Tools
Set Screw Market
Tools
Multi Wire Cutting Machine Market
Tools
Bearing Installation Tool Kit Market