
 Woodworking Sanders Market | 2026-2036
Woodworking Sanders Market Size, Share, and Industry Trends Forecast 2026-2036
Woodworking Sanders Market Analytics
Furniture manufacturing is consolidating its share of professional sanding equipment procurement as residential renovation cycles extend replacement timelines. Makita Corporation leverages its cordless platform to capture workshop and job-site transitions from pneumatic systems. Robert Bosch Tool Corporation anchors European demand through its integrated dust extraction ecosystem. Festool differentiates via precision-engineered orbital systems targeting high-end cabinetry workflows.
Woodworking sanders are abrasive finishing machines that employ rotating belts, orbital pads, or disc mechanisms to smooth timber surfaces through graduated grit sequences, typically operating between 8,000 and 22,000 orbits per minute for fine-finish applications. These systems remove mill marks, prepare substrates for coating adhesion, and achieve specified surface roughness values measured in Ra micrometers for visible furniture components. Belt sanders dominate volume in rough dimensioning and panel flattening where stock removal rates determine throughput economics. Cordless technology is capturing share fastest among professional woodworkers and on-site builders as lithium-ion platforms extend runtime beyond single-shift thresholds. Pneumatic systems retain margin concentration in fixed industrial installations where compressed air infrastructure amortizes across multiple workstations.
The Occupational Safety and Health Administration enforces permissible exposure limits for respirable crystalline silica and wood dust that mandate local exhaust ventilation on stationary sanding equipment. The EU Machinery Directive requires CE-marked sanders to incorporate automatic brake systems and dust-tight electrical enclosures. The EPA's National Emission Standards for Hazardous Air Pollutants for wood furniture manufacturing operations constrain finishing department configurations. Stakeholders must monitor battery platform interoperability standards and dust extraction certification convergence as these specifications increasingly determine equipment compatibility and facility compliance costs.
Market Dynamics
Residential construction spending in North America is consolidating demand toward professional-grade equipment, while the EU Machinery Directive and EPA wood dust exposure limits tighten compliance requirements for sanding equipment manufacturers worldwide.
Growth Catalysts
- Cordless lithium-ion platforms:Extended runtime beyond single-shift thresholds is capturing share among professional woodworkers and on-site builders transitioning from pneumatic systems.
- EPA National Emission Standards for Hazardous Air Pollutants:Wood furniture manufacturing operations face constrained finishing department configurations, mandating local exhaust ventilation upgrades on stationary equipment.
- Germany's Black Forest furniture cluster:Concentrated demand for precision-engineered orbital systems targeting high-end cabinetry workflows is anchoring European procurement volume.
Market Restraints
- Neodymium and lithium supply concentration:Rare earth element dependencies for high-performance motor magnets and battery cells create input cost volatility and geopolitical sourcing risk.
- Pneumatic infrastructure lock-in:Fixed industrial installations with amortized compressed air systems resist platform switching despite cordless performance gains.
- EU Machinery Directive brake system mandates:Automatic braking and dust-tight electrical enclosure requirements extend product development timelines and certification costs for smaller manufacturers.
Strategic Opportunities
- Italy's Brianza design district:Underpenetrated demand for integrated dust extraction ecosystems among boutique furniture ateliers offers premium positioning potential.
- Battery platform interoperability standards:Convergence specifications increasingly determine equipment compatibility, creating first-mover advantage for ecosystem architects.
- Workshop-to-jobsite mobility:Hybrid power architectures bridging corded, cordless, and pneumatic modalities address fragmented professional use cases.
Industry Challenges
- Surface roughness specification expertise:Qualified technicians capable of interpreting Ra micrometer values and graduated grit sequences for visible furniture components remain scarce.
- Dust extraction certification complexity:CE marking, OSHA compliance, and EPA emission standard convergence creates multi-jurisdictional testing bottlenecks.
- Legacy pneumatic integration:Retrofitting existing fixed installations with smart monitoring and extraction compatibility requires substantial capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woodworking Sanders Market |
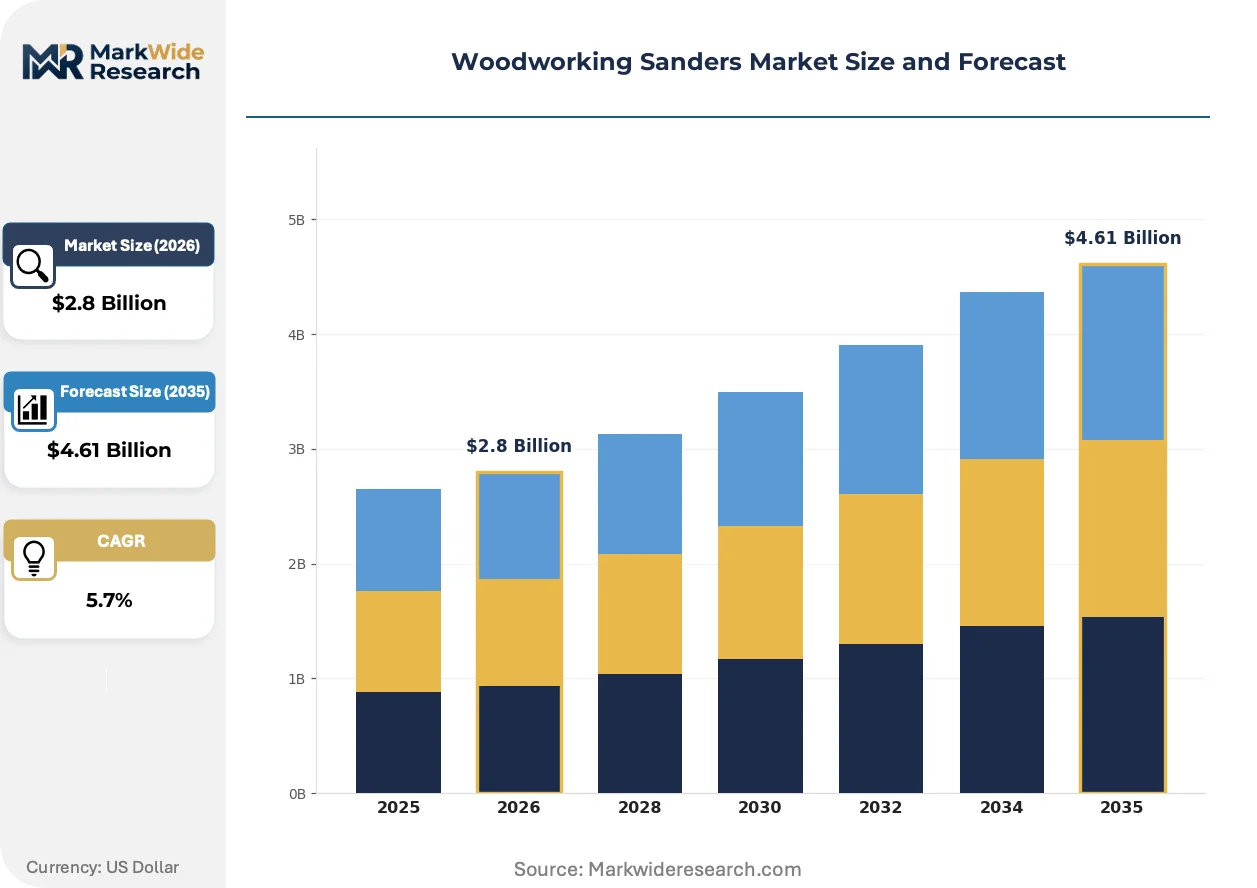
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Sanders, Orbital Sanders, Detail Sanders, Disc Sanders Technology: Pneumatic, Electric, Cordless, Magnetic End User: Professional Woodworkers, Hobbyists, Furniture Manufacturers, Builders Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | DEWALT, Makita Corporation, Robert Bosch Tool Corporation, Ingersoll Rand, 3M Company, Festool, Dynabrade, Metabo, Atlas Copco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woodworking Sanders Market Evolving Landscape
Orbital sanding technology is consolidating market structure as runtime and precision benchmarks shift, while regulatory pressure on respirable dust exposure accelerates ventilation integration requirements across manufacturing tiers.
Brushless DC motor architecture is consolidating performance standards in professional-grade equipment. Cabinetry workshops and custom furniture builders are adopting these systems at accelerating rates for sustained torque delivery under load. The technology is consolidating market share around platform ecosystems that lock in battery and accessory compatibility.
REACH restrictions on hazardous substances in electrical and electronic equipment are tightening material disclosure requirements for sanding machine housings and wiring insulation. Manufacturers face reformulation costs for legacy polymer compounds and supply chain requalification. Germany and France are driving enforcement, with Italian producers adapting fastest through pre-certified component sourcing.
Equipment-as-a-service models are emerging among commercial furniture contractors seeking to shift capital expenditure to operational budgets. Traditional distributor networks face disintermediation from manufacturer-direct rental platforms with embedded maintenance and compliance monitoring. This shift is most visible in North American metropolitan construction corridors where project-based demand fluctuates seasonally.
Woodworking Sanders Market Segmentation
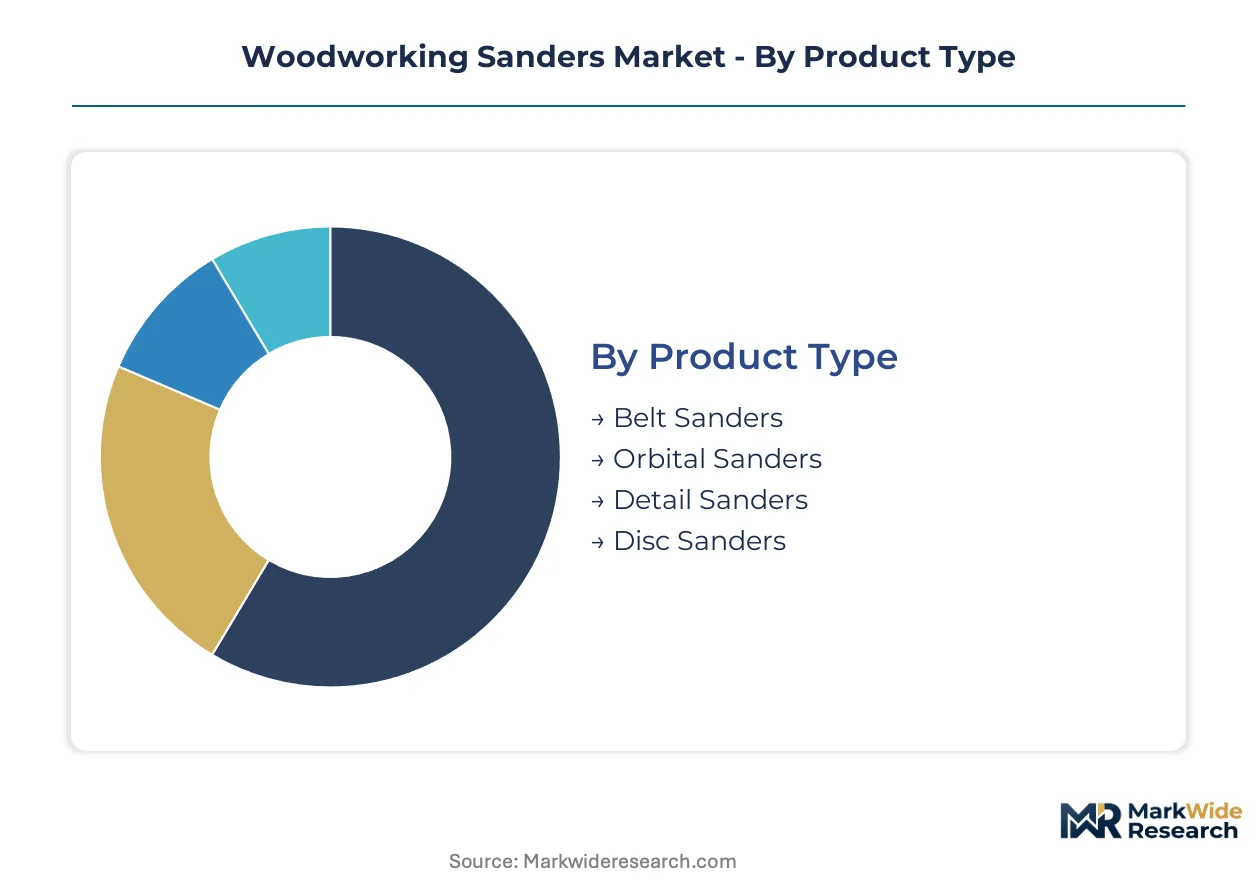
Woodworking sanders serve divergent workflows across rough dimensioning, precision finishing, and mobile job-site applications. Equipment specifications vary dramatically by stock removal rates, orbit speeds, and dust extraction integration requirements. Procurement patterns cluster around platform ecosystems that lock in battery compatibility and accessory interoperability.
Product Type:
Supply concentration in abrasive finishing equipment tilts toward belt and orbital configurations where manufacturing scale and motor platform standardization create cost advantages.
- Belt Sanders:Continuous abrasive belts rotating over drums and platens achieve aggressive stock removal rates measured in cubic inches per minute. Furniture manufacturers in Germany's Black Forest cluster deploy these systems for panel flattening and rough dimensioning where throughput economics dominate equipment selection.
- Orbital Sanders:Random-orbit mechanisms combining rotary and eccentric motion produce scratch-free finishes through graduated grit sequences. Precision-engineered variants from Festool and Bosch anchor European demand for high-end cabinetry workflows requiring specified surface roughness values.
- Detail Sanders:Compact triangular or finger-shaped pads access tight contours and interior corners inaccessible to standard formats. These units concentrate among custom furniture ateliers and restoration specialists handling intricate molding profiles.
- Disc Sanders:Rotating abrasive discs mounted on vertical or horizontal spindles excel at edge sanding and small component finishing. Stationary industrial installations favor these systems for repetitive shaping operations on standardized parts.
Belt sanders absorb the bulk of installed capacity in volume manufacturing environments; orbital sanders are expanding most quickly among professional woodworkers transitioning to cordless platforms.
Technology:
Cost tier stratification separates mature pneumatic infrastructure from emerging lithium-ion ecosystems competing on runtime and mobility metrics.
- Pneumatic:Compressed air systems deliver sustained torque without motor overheating in continuous-duty industrial settings. Fixed installations with amortized infrastructure resist platform switching despite cordless performance gains.
- Electric:Corded AC motors provide uninterrupted runtime for workshop environments with reliable grid access. These systems retain share among hobbyists and budget-conscious professionals prioritizing purchase price over mobility.
- Cordless:Brushless DC architectures on lithium-ion platforms extend runtime beyond single-shift thresholds. Makita's battery ecosystem captures workshop-to-jobsite transitions as professional woodworkers abandon pneumatic dependencies.
- Magnetic:Rare-earth magnet motors enable compact, high-torque designs with reduced heat generation. Neodymium supply concentration in China creates input cost volatility for manufacturers sourcing these components.
Electric technology retains the largest installed base; cordless configurations are climbing the fastest as battery chemistry improvements close the performance gap with corded alternatives.
End User:
Volume concentration among furniture manufacturers contrasts with margin opportunities in professional woodworking segments demanding precision and durability.
- Professional Woodworkers:Independent contractors and small-shop operators prioritize equipment mobility across workshop and job-site contexts. These users drive cordless adoption and integrated dust extraction requirements.
- Hobbyists:Consumer-grade purchasers prioritize acquisition cost over runtime specifications and dust collection efficiency. Price-sensitive demand concentrates in big-box retail channels and online marketplaces.
- Furniture Manufacturers:Production facilities specify equipment for throughput, repeatability, and compliance with OSHA respirable dust limits. EPA National Emission Standards constrain finishing department configurations at these operations.
- Builders:General contractors and finish carpenters require durable, transportable equipment for on-site installation work. Seasonal project demand fluctuation makes equipment-as-a-service models attractive in North American metropolitan construction corridors.
Furniture manufacturers command the greatest procurement volume; professional woodworkers represent the steepest expansion trajectory as cordless platforms capture workshop-to-jobsite mobility requirements.
Power Rating:
Application intensity determines motor specification, with high-amperage and ultra-high-amperage systems concentrating in industrial stock removal and heavy-duty panel processing.
- Low Power:Compact motors under 3 amps suit detail work and light finishing where precision outweighs material removal rates. Hobbyists and restoration specialists dominate this segment.
- Medium Power:3-6 amp configurations balance portability with sufficient torque for standard cabinet and furniture component sanding. Professional woodworkers in Italy's Brianza design district favor these specifications for boutique production.
- High Power:6-10 amp motors deliver sustained performance under load for production furniture manufacturing and commercial millwork. EU Machinery Directive brake system mandates extend development timelines for equipment in this class.
- Ultra High Power:Industrial-grade systems exceeding 10 amps handle continuous-duty panel flattening and aggressive stock removal. These installations require local exhaust ventilation compliance with OSHA permissible exposure limits.
Medium power ratings absorb the bulk of professional-grade procurement; high power configurations are gaining share fastest as brushless motor efficiency improvements enable compact industrial-grade designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures the majority of precision-engineered sanding systems exported worldwide, while the United States absorbs the greatest import volume for residential construction applications. China concentrates belt sander production for cost-sensitive industrial procurement. This production-consumption asymmetry shapes regional competitive dynamics.
United States
Residential construction spending concentrates demand for professional-grade cordless equipment among contractors and finish carpenters. OSHA enforces permissible exposure limits for respirable crystalline silica and wood dust that mandate local exhaust ventilation upgrades. Metropolitan construction corridors in Texas and Florida drive seasonal equipment-as-a-service adoption.
Germany
Precision-engineered orbital systems for high-end cabinetry workflows anchor European procurement volume from the Black Forest furniture cluster. The EU Machinery Directive requires CE-marked sanders to incorporate automatic brake systems and dust-tight electrical enclosures. Bavarian and Baden-Württemberg workshops represent the densest concentration of premium-grade equipment users.
Italy
Boutique furniture ateliers in the Brianza design district generate underpenetrated demand for integrated dust extraction ecosystems. REACH restrictions on hazardous substances in electrical equipment tighten material disclosure requirements for polymer housings. Lombardy-based producers adapt fastest through pre-certified component sourcing.
China
Domestic furniture manufacturing scales drive volume procurement of belt sanders for panel flattening and rough dimensioning. The country's national standards body enforces GB certification for electrical tool safety in woodworking applications. Zhejiang and Guangdong provinces concentrate OEM production for export markets.
Japan
Compact, high-precision finishing equipment serves domestic cabinetry and architectural woodwork segments. METI promotes battery platform interoperability standards through industrial policy coordination. Osaka and Nagoya manufacturing basins specialize in brushless motor integration for professional-grade tools.
Woodworking Sanders Market Competitive Landscape
Top-tier vendors anchor premium positioning through integrated dust extraction ecosystems and battery platform lock-in, while mid-tier specialists compete on component modularity and regional service density. The vendor base stratifies across three functional tiers: precision-engineered system architects, cordless platform ecosystem builders, and pneumatic infrastructure incumbents. Dominant competitive moves include backward integration into motor and battery cell manufacturing, plus strategic partnerships with abrasive consumables suppliers to secure recurring revenue streams.
Among Japanese and German precision specialists, Makita Corporation and Robert Bosch Tool Corporation exemplify the cordless platform ecosystem archetype, while Festool occupies a position representing the premium engineered-systems tier. These three anchors demonstrate how geographic manufacturing heritage translates into distinct competitive positioning without overlapping segment focus.
| Leading Market Players |
|---|
| DEWALT |
| Makita Corporation |
| Robert Bosch Tool Corporation |
| Ingersoll Rand |
| 3M Company |
| Festool |
| Dynabrade |
| Metabo |
| Atlas Copco |
| Others |
Value Network & Pricing Analysis
EU Machinery Directive brake system mandates and EPA wood dust exposure limits gate qualified supply access and premium-tier pricing power for sanding equipment manufacturers serving furniture production clusters in Germany, Italy, and North America.
Pricing Analysis
Margin tightening in professional-grade tiers reflects neodymium magnet cost volatility and lithium-ion cell supply concentration. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified precision orbital systems from pneumatic infrastructure and consumer-grade corded alternatives. Cost-down pressure on mid-tier configurations accelerates because furniture manufacturers consolidate procurement around platform ecosystems. Hobbyists exhibit greatest price sensitivity; high-end cabinetry workshops in Bavaria demonstrate least.
Supply Chain Analysis
Dual-sourcing requirements for brushless DC motors and battery pack assemblies are becoming standard among German and Japanese OEM procurement teams. Manufacturing concentration in China, Germany, and Japan feeds global equipment supply. Rare-earth magnet dependencies and polymer housing formulations rest on qualified supplier networks facing REACH disclosure requalification. Single-source vulnerability in neodymium processing creates exposure. Distribution runs through industrial distributor networks and emerging manufacturer-direct rental platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless DC motor platforms are displacing pneumatic infrastructure across professional woodworking segments, compressing transition timelines for equipment suppliers and buyers.
For Market Incumbents: Hedge pneumatic revenue erosion by accelerating cordless platform ecosystem lock-in through backward integration into battery cell qualification. Prioritize dust extraction certification convergence to defend specification control in EU and North American regulatory corridors. Anchor premium positioning via integrated motor-brake-extraction system architectures that exceed Machinery Directive minimums.
For New Entrants and Emerging Players: Boutique furniture ateliers in Italy's Brianza design district represent underpenetrated demand for modular, pre-certified component systems. Equipment-as-a-service models targeting North American metropolitan construction corridors offer white-space entry with lower capital barriers. Pursue go-to-market partnerships with abrasive consumables suppliers to secure recurring revenue attachment.
For Investors and Strategic Acquirers: Battery platform interoperability standard adoption by METI and EU standardization bodies is the leading indicator that ecosystem control will consolidate market structure. Five-to-ten year viability favors manufacturers with captive motor and extraction technology capabilities. Target acquisition archetypes: mid-tier specialists with pre-certified component sourcing relationships and regional service density in furniture manufacturing clusters. Monitor OSHA permissible exposure limit enforcement intensity as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Ecosystem Expansion | Lock-in professional woodworkers transitioning from pneumatic systems via runtime and accessory interoperability. |
| Integrated Dust Extraction Certification | Capture premium positioning in Germany's Black Forest cluster through CE marking and OSHA compliance bundling. |
| Backward Integration into Motor Manufacturing | Secure brushless DC supply against neodymium cost volatility and reduce dependency on Chinese magnet processors. |
| Equipment-as-a-Service Launch | Address seasonal demand fluctuation among North American finish carpenters through operational expenditure conversion. |
| Abrasive Consumables Partnership | Generate recurring revenue streams via graduated grit sequence bundling with precision orbital system sales. |
Research Methodology
Trade association filings, customs export records, and equipment registration databases formed the secondary backbone for demand quantification. Primary interviews with maintenance directors at furniture manufacturers, procurement leads at industrial distributors, aftermarket service heads, and plant engineers in Germany, Italy, and the United States combined with secondary validation. Bottom-up installation base analysis and top-down construction spending correlation established volume estimates.
Historical trendline analysis of residential construction cycles and furniture production indices anchored projection modeling across the analysis window. Segmentation dimensions included product type, power rating tier, technology platform, and end-user archetype. CAGRs derived from regression against construction spending and regulatory compliance cost trajectories. Brushless motor efficiency curves and battery chemistry improvement timelines informed technology transition assumptions.
Revisions become necessary when OSHA enforcement intensity, EU Machinery Directive amendment schedules, or rare-earth export restriction events materialize outside baseline assumptions. Forecasts reflect documented assumptions regarding platform switching velocity and certification timeline convergence. Deviation in neodymium supply concentration or lithium-ion cell qualification bottlenecks would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Log Splitters Market
Tools
Squeegee Market
Tools
Cold and Hot Tool Steel Market
Tools
Europe Stump Cutter/Grinder Market
Tools
Steel Measuring Tape Market
Tools
Cordless Multi Rotary Tools Market
Tools
Machine Tools Market
Tools
Global Construction Camera Market
Tools
United States Machine Tools Market
Tools
Hand and Power Tools Market
Tools
Circular Saw Blades Market
Tools
Painting Tools Market
Tools
Drain Cleaning Equipment Market
Tools
Portable Pressure Washer Market
Tools
Multi Spindle Machines Market
Tools
Grease Gun Market