
 Auger Drill Bits Market | 2026-2036
Auger Drill Bits Market Size, Share, and Industry Trends Forecast 2026-2036
Auger Drill Bits Market Outlook
Skilled equipment operator shortages across North American construction zones is redrawing competitive dynamics for auger bit suppliers. Lowe Manufacturing anchors its position through captive forging capacity and direct OEM relationships with utility contractors. Digga North America leverages Australian-engineered flighting designs to compete in the North American skid-steer attachment channel. IRWIN Tools sustains retail shelf dominance through brand recognition and broad distribution with home improvement chains.
Auger drill bits are helical cutting tools manufactured from forged steel bar stock with welded flighting, typically ranging from two to forty-eight inches in diameter, designed to excavate cylindrical holes in earth, wood, or composite substrates through rotary percussion or continuous rotation. The manufacturing process involves induction hardening of cutting edges followed by carbide tipping for abrasive material penetration. Earth augers and heavy-duty augers occupy the dominant share of product type revenue as infrastructure and mining applications drive replacement cycles. Steel and alloy steel materials lead the material segmentation while tungsten carbide represents the fastest-growing category due to extended service life in rocky substrates.
OSHA excavation safety standards and EPA stormwater management regulations shape product specifications by mandating precise boring depths and soil displacement containment in commercial applications. NHTSA transport rules for oversized tooling influence packaging and logistics costs for cross-state distribution. Buyers should monitor alloy price volatility and state-level infrastructure appropriations as primary determinants of procurement timing and supplier selection.
Market Dynamics
Foundation contractors are consolidating auger bit specifications around carbide-tipped alloy steel formulations as abrasive soil conditions accelerate replacement cycles and force material upgrades across infrastructure job sites.
Growth Catalysts
- OSHA Excavation Safety Standards:Mandated boring depth precision and soil displacement containment requirements in commercial applications are standardizing auger bit procurement specifications across US construction zones.
- Tungsten Carbide Cutting Edges:Extended service life in rocky substrates is driving material substitution decisions among mining and utility contractors operating in abrasive geologies.
- Utility Pole Installation:Grid hardening and broadband expansion programs are expanding demand for heavy-duty earth augers in electrical infrastructure applications.
Market Restraints
- Alloy Steel Price Volatility:Fluctuations in nickel and chromium input costs compress margin stability for forged bit manufacturers dependent on bar stock supply chains.
- NHTSA Transport Rules:Oversized tooling packaging requirements inflate cross-state logistics costs and constrain distributor inventory positioning strategies.
- Manual Drilling Substitution:Small-scale residential contractors in price-sensitive segments continue using standard twist drills for shallow applications below auger economic thresholds.
Strategic Opportunities
- EPA Stormwater Management Incentives:Contained soil displacement technologies qualify for infrastructure grant funding, creating specification pull for precision auger systems in municipal procurement.
- Skid-Steer Attachment Channel:Compact equipment rental fleets are expanding attachment compatibility requirements, opening distribution pathways for modular flighting designs.
- Induction Hardening Automation:Convergence of robotic welding and real-time heat treatment monitoring is enabling consistent edge hardness without manual operator variance.
Industry Challenges
- Certified Equipment Operator Scarcity:Skilled auger rig operators with hydraulic system expertise remain under-supplied relative to foundation drilling project backlogs across construction zones.
- Carbide Tipping Integration Complexity:Bonding tungsten inserts to alloy steel substrates requires capital-intensive vacuum brazing equipment that fragments supplier scale economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auger Drill Bits Market |
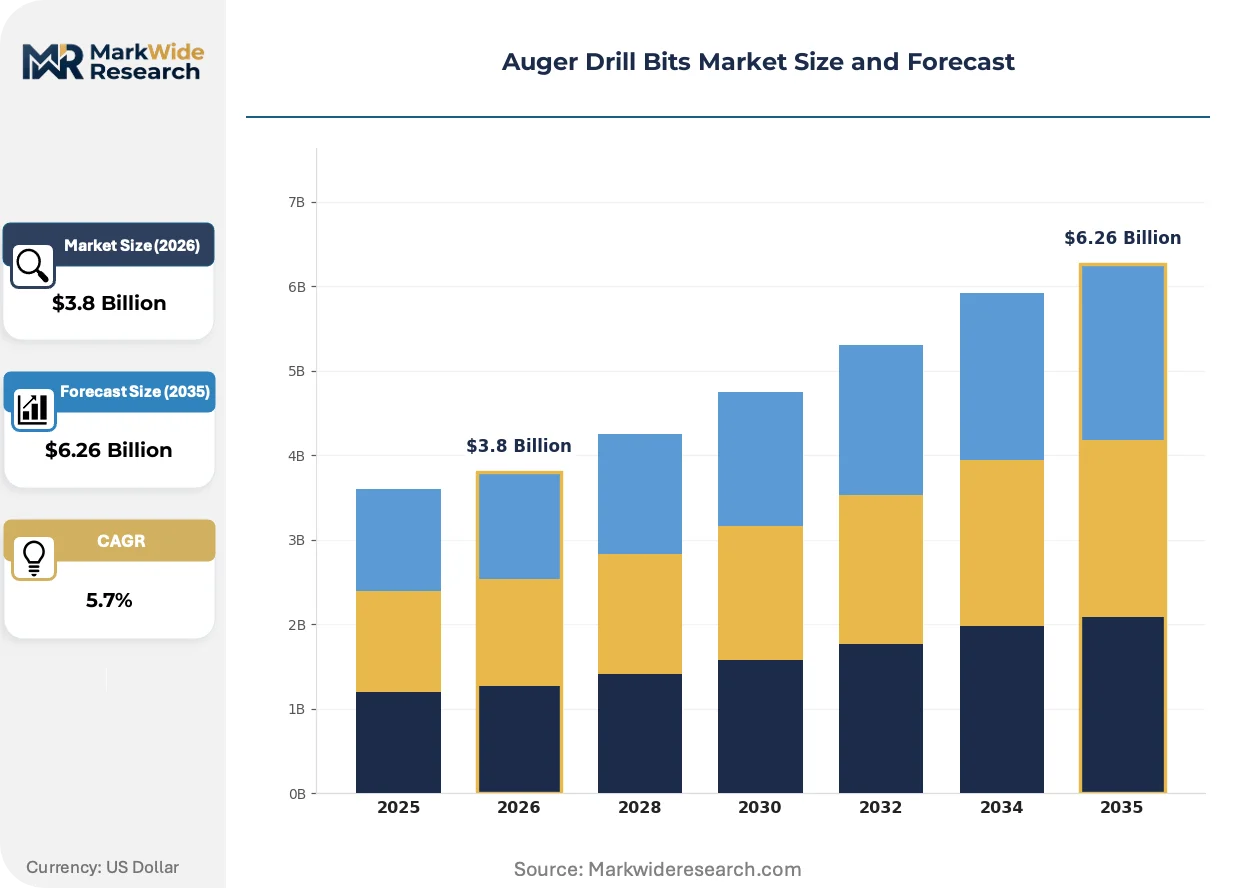
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spiral Augers, Post Hole Augers, Earth Augers, Heavy-Duty Augers Material: Steel, Carbon Steel, Alloy Steel, Tungsten Carbide Application: Construction, Agriculture, Mining, Landscaping End User: Contractors, Homeowners, Landscapers, Mining Companies |
| Companies Covered | Lowe Manufacturing, WoodOwl, Auger Torque USA, Spartan Equipment, Star-M, Digga North America, IRWIN Tools, The Attachment Company, Naipu Tools Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auger Drill Bits Market Strategic Shifts
Material science advances and regulatory precision mandates are compressing traditional equipment lifecycles while opening specification windows for automated manufacturing processes in auger bit production.
Carbide-tipped cutting edges deliver three-to-four times wear resistance against silica-rich soils compared to hardened steel alternatives. Mining contractors operating in granite and basalt formations are specifying these formulations as standard equipment. Standard alloy steel is supplanting conventional carbon steel in mid-tier product lines as price-performance ratios compress across supplier catalogs.
OSHA excavation safety standards now mandate documented soil stability verification and precise depth control in commercial boring operations. These requirements are forcing specification upgrades toward calibrated flighting designs with integrated measurement systems. Foundation drilling contractors in the United States are retrofitting existing rigs with compatible auger systems to maintain compliance without full equipment replacement.
Rental channel penetration is altering procurement patterns among residential and light commercial contractors who previously purchased dedicated equipment. Equipment rental chains are expanding auger attachment inventories for compact loaders and mini-excavators. This shift is most pronounced in suburban construction corridors where project scale variability favors operational flexibility over capital ownership.
Auger Drill Bits Market Segmentation
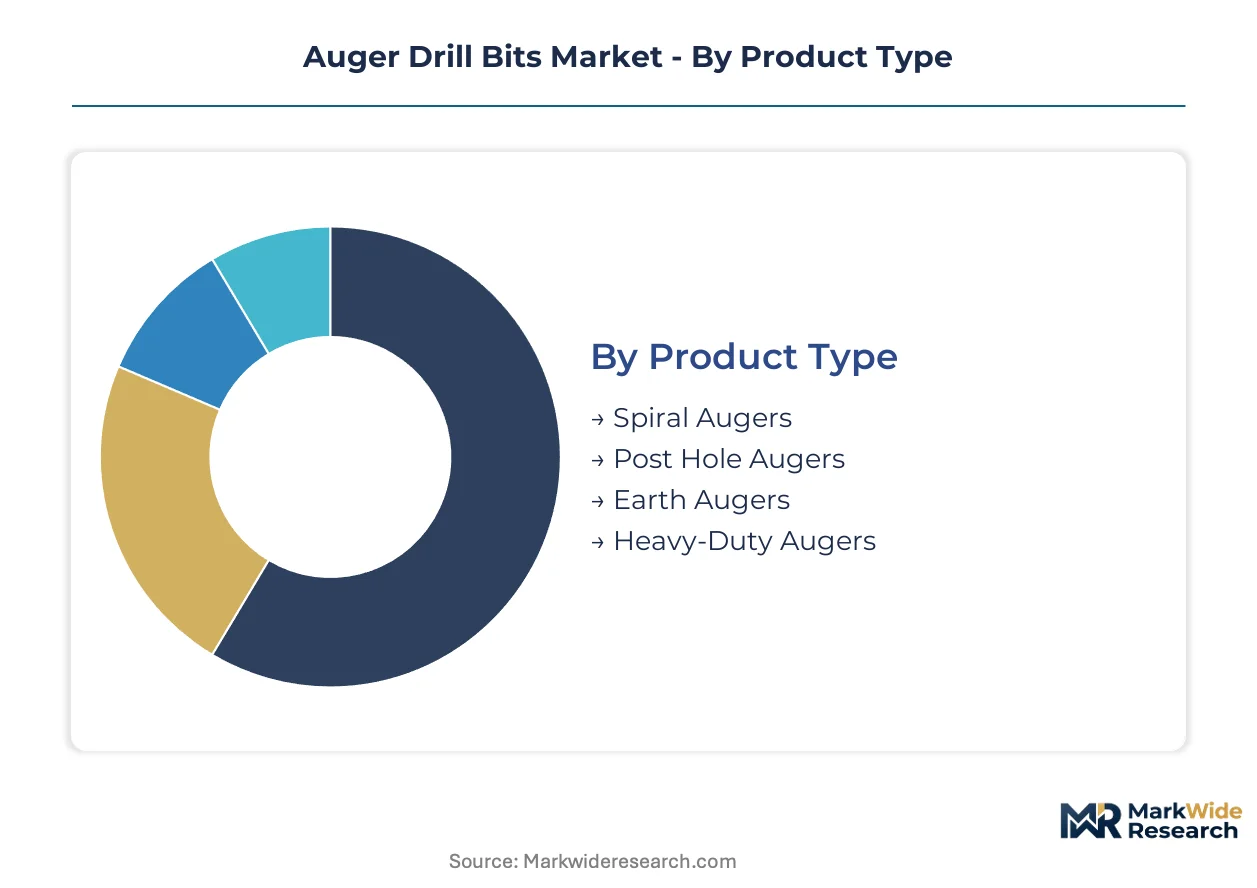
Auger drill bit procurement patterns diverge sharply across material grades and duty cycles, with substitution threats from manual drilling methods pressuring entry-level segments while premium formulations capture specification upgrades in regulated commercial environments.
Product Type:
Spiral augers face the most acute substitution pressure from standard twist drills in shallow residential applications, forcing suppliers to differentiate through flighting geometry and substrate-specific cutting edge configurations.
- Earth Augers:These helical tools feature welded flighting on forged steel shafts with carbide-tipped cutting edges designed for continuous rotation in cohesive soils. Demand concentrates with utility contractors across the United States executing grid hardening and broadband expansion programs where precise boring depth compliance with OSHA excavation standards is mandatory.
- Heavy-Duty Augers:Reinforced barrel construction with induction-hardened cutting edges handles rotary percussion in abrasive geologies including granite and basalt formations. Mining contractors operating in rocky substrates specify these formulations to extend replacement cycles and reduce rig downtime in remote extraction sites.
- Spiral Augers:Continuous flighting designs optimize soil removal in soft to medium ground conditions for foundation drilling and agricultural fencing.
- Post Hole Augers:Compact diameter ranges from two to twelve inches serve residential fencing and signage installation with portable powerhead compatibility.
Earth augers anchor the volume base while heavy-duty augers gain share at the steepest rate.
Material:
Cost tier stratification separates commodity carbon steel from premium carbide formulations, with alloy steel occupying the contested middle ground where price-performance tradeoffs determine procurement decisions.
- Tungsten Carbide:Vacuum-brazed inserts deliver three-to-four times wear resistance against silica-rich soils compared to hardened steel alternatives. Mining companies operating in basalt and granite formations specify carbide-tipped edges as standard equipment to minimize bit replacement frequency in remote job sites.
- Alloy Steel:Nickel-chromium formulations with induction-hardened cutting surfaces balance durability against input cost volatility in mid-tier commercial applications. Foundation contractors across the United States are consolidating procurement specifications around these formulations as abrasive soil conditions accelerate replacement cycles.
- Steel:Standard carbon-manganese grades serve price-sensitive residential and light commercial segments with shorter duty cycle expectations.
- Carbon Steel:Entry-level bar stock formulations dominate rental channel inventories and homeowner-direct sales through retail distribution.
Alloy steel anchors the volume base while tungsten carbide climbs the fastest on specification upgrades.
Application:
Customer type concentration varies by project scale, with commercial contractors driving premium material adoption while residential and agricultural segments prioritize equipment flexibility over capital ownership.
- Construction:Foundation drilling and utility pole installation require carbide-tipped alloy steel augers with calibrated flighting for OSHA-compliant depth precision. Contractors in the United States are retrofitting existing rigs with compatible systems to maintain regulatory compliance without full equipment replacement.
- Mining:Exploration drilling and blast hole preparation demand heavy-duty formulations with extended service life in abrasive geologies. Operators specify tungsten carbide cutting edges to reduce bit change frequency in continuous extraction environments.
- Agriculture:Fencing and irrigation system installation utilize mid-duty earth augers with portable powerhead mounting for seasonal use patterns.
- Landscaping:Tree planting and hardscape foundation work favor compact diameter augers compatible with skid-steer and mini-excavator attachment systems.
Construction anchors the volume base while mining shows the steepest expansion trajectory on material upgrade cycles.
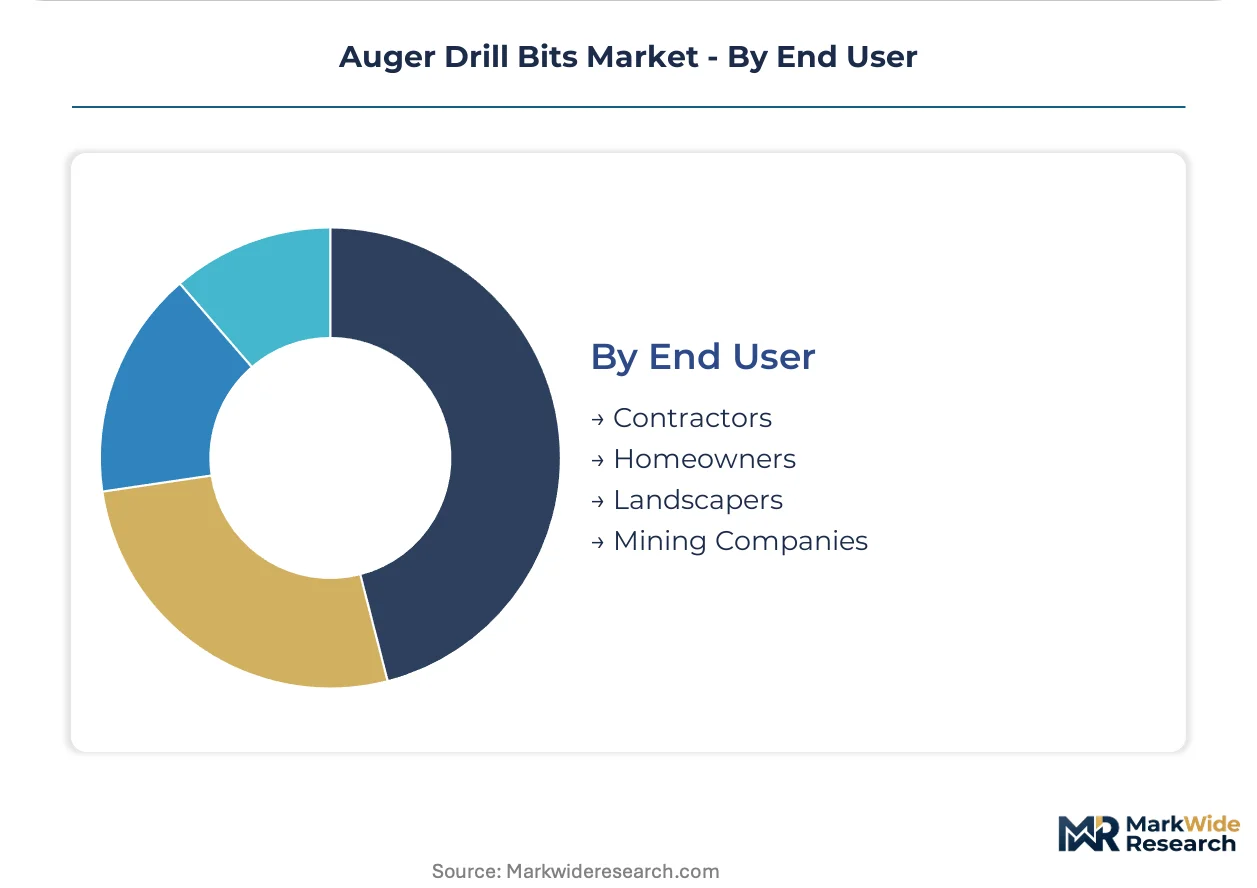
End User:
Procurement authority separates specification-driven commercial buyers from price-sensitive residential purchasers, with rental channel penetration altering ownership patterns among intermittent users.
- Contractors:Commercial construction and utility installation firms procure carbide-tipped alloy steel augers through direct OEM relationships and specialized distribution. These buyers prioritize documented compliance with OSHA excavation safety standards and EPA stormwater management requirements in municipal procurement.
- Mining Companies:Large-scale extraction operators specify heavy-duty formulations with integrated measurement systems for blast hole precision. Capital-intensive vacuum brazing capabilities in supplier operations influence vendor selection for critical path drilling equipment.
- Landscapers:Seasonal service providers favor rental channel access over equipment ownership to match variable project scales.
- Homeowners:Residential purchasers drive retail shelf demand for compact post hole augers through home improvement chains.
Contractors anchor the volume base while mining companies gain share fastest on specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums in the United States exceed those in Germany by roughly fifteen percent, reflecting divergent regulatory burdens and contractor consolidation patterns across Atlantic construction markets.
United States
Utility grid hardening and broadband expansion programs drive heavy-duty auger procurement across Texas and the Southeast. OSHA excavation safety standards mandate precise boring depth documentation, forcing specification upgrades toward calibrated flighting designs. Foundation contractors in Houston and Dallas-Fort Worth retrofit existing rigs with carbide-tipped systems to maintain compliance.
China
Mining exploration in Inner Mongolia and Shanxi Province accelerates demand for tungsten carbide cutting edges in abrasive geologies. GB standards for construction machinery safety shape product certification requirements for domestic and export markets. Zhengzhou and Xuzhou industrial clusters host forged bit manufacturers supplying belt-and-road infrastructure projects across Central Asia.
Germany
Foundation engineering firms specify alloy steel formulations with induction-hardened edges for Rhine-Ruhr megaproject sites. REACH chemical compliance and CE machinery directives constrain material sourcing and welding process emissions. Stuttgart and Munich anchor precision manufacturing clusters where automated heat treatment monitoring reduces operator variance in cutting edge production.
Australia
Iron ore and lithium extraction in Western Australia's Pilbara region drives replacement cycles for heavy-duty augers in continuous drilling environments. The country's national mining safety regulator mandates equipment traceability and operator certification for remote site operations. Perth-based fabricators supply flighting designs optimized for silica-rich laterite formations.
Canada
Arctic infrastructure and hydroelectric development in Quebec and British Columbia require cold-weather hardened formulations with extended service life. Transport Canada oversized load regulations influence packaging logistics for cross-provincial distribution to remote job sites. Edmonton and Calgary equipment distributors stock modular attachment systems for oil sands remediation contractors.
Auger Drill Bits Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where premium formulation specialists coexist with high-volume forged bit manufacturers. The vendor base spans captive forging operations, specialized flighting designers, and retail-brand distributors with distinct channel strategies. Three archetypes dominate: integrated manufacturers with in-house heat treatment, attachment-focused engineering houses, and brand-anchored retail suppliers. Competitive moves center on automated welding investments and direct OEM relationships with utility contractors.
Among North American fabricators, Lowe Manufacturing exemplifies the integrated forging archetype with captive bar stock processing capabilities. Digga North America represents the engineering-specialist position with Australian-origin flighting designs adapted for skid-steer compatibility. IRWIN Tools anchors the retail-brand tier through home improvement chain distribution and contractor recognition.
| Leading Market Players |
|---|
| Lowe Manufacturing |
| WoodOwl |
| Auger Torque USA |
| Spartan Equipment |
| Star-M |
| Digga North America |
| IRWIN Tools |
| The Attachment Company |
| Naipu Tools Company |
| Others |
Value Chain & Pricing Dynamics
OSHA excavation safety standards gate both supplier qualification and price differentiation simultaneously, mandating carbide-tipped alloy steel formulations that separate certified commercial contractors from price-sensitive residential purchasers.
Pricing Analysis
Price premiums in the United States exceed those in Germany by roughly fifteen percent, reflecting divergent regulatory burdens and contractor consolidation patterns. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with tungsten carbide formulations commanding top tier and carbon steel rental inventory occupying bottom tier. Pricing pressure stems from nickel and chromium input cost volatility compressing margin stability for forged bit manufacturers. Residential homeowners and small-scale contractors exhibit highest price sensitivity, while mining companies and utility contractors demonstrate lowest sensitivity due to downtime cost exposure.
Supply Chain Analysis
Strategic stockpile preferences dominate among foundation contractors facing project backlogs, while just-in-time inventory management prevails in rental channel distribution. Supply concentrates in the United States, China, and Germany, with Zhengzhou and Xuzhou industrial clusters supplying forged components and Stuttgart and Munich anchoring precision heat treatment capabilities. Raw material dependencies center on nickel-chromium alloy bar stock, tungsten carbide inserts, and induction hardening equipment. Single-source vulnerability in vacuum brazing equipment fragments supplier scale economics. Distribution runs through direct OEM relationships with utility contractors, specialized equipment distributors, and home improvement retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated foundation drilling contractors and mining operators, squeezing margin capture for suppliers without captive forging or direct specification influence.
For Market Incumbents: Consolidate specification control by deepening captive forging capacity and securing direct OEM relationships with utility contractors facing grid hardening mandates. Invest in automated induction hardening to reduce operator variance and defend against emerging engineering-specialist competitors with modular flighting designs. Prioritize vacuum brazing capability expansion to maintain carbide tipping integration advantages. For New Entrants and Emerging Players: Differentiate on skid-steer attachment compatibility to penetrate the compact equipment rental channel where operational flexibility favors modular designs over capital ownership. Target suburban construction corridors in Texas and the Southeast where project scale variability creates specification windows for Australian-engineered flighting adaptations. Pursue municipal procurement pathways by qualifying for EPA stormwater management grant funding through contained soil displacement technologies. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across tungsten carbide formulation segments as vacuum brazing equipment requirements fragment supplier economics. Long-term viability favors integrated manufacturers with in-house heat treatment and captive bar stock processing over pure distribution plays. Acquisition target archetype: mid-tier forged bit manufacturers with underutilized heat treatment capacity and established utility contractor relationships. Watch alloy steel price volatility as inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Welding Investment | Robotic flighting attachment reduces operator variance in OSHA-compliant depth precision systems. |
| Backward Integration into Forging | Captive bar stock processing insulates margin stability from nickel and chromium input volatility. |
| Carbide Tipping Capacity Expansion | Vacuum brazing equipment ownership gates specification access in mining and utility procurement. |
| Skid-Steer Attachment Engineering | Modular flighting designs capture rental channel growth in suburban construction corridors. |
| Direct OEM Relationship Development | Utility contractor partnerships secure volume anchoring for grid hardening and broadband expansion programs. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings, and equipment manufacturer technical specifications across the analysis window. Primary interviews engaged foundation drilling contractors, mining equipment procurement managers, utility infrastructure planners, and rental channel inventory directors. Secondary validation drew from OSHA regulatory filings, EPA stormwater management documentation, and NHTSA transport rule records. Bottom-up triangulation across product type, material grade, and application segments converged with top-down macroeconomic drivers to produce volume and value estimates.
Segmentation dimensions modeled include product type tier, material formulation grade, end-use application intensity, and regional regulatory cluster across the projection horizon. CAGRs were derived from replacement cycle analysis in abrasive geologies and infrastructure appropriation tracking. Industry-specific forecast inputs incorporated state-level infrastructure spending patterns and alloy steel price volatility indices.
Material uncertainties — alloy input cost spikes, regulatory enforcement intensity variations, and certified operator supply constraints — sit outside the modeled envelope. Forecasts reflect assumptions about continued OSHA excavation standard adherence and sustained utility grid hardening program funding. Revision becomes warranted when alloy steel price volatility crosses thresholds that accelerate substitution toward manual drilling methods in price-sensitive segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Bi-Metal Band Saw Blade Market
Tools
Handheld Blower Market
Tools
Power Press Machines Market
Tools
Grease Gun Market
Tools
Turning Centers Market
Tools
Steel Measuring Tape Market
Tools
Land Survey Equipment Market
Tools
Shape Moulding Machines Market
Tools
Dumpy Level Market
Tools
Fatigue Testing Machine Market
Tools
Woodworking Sanders Market
Tools
Sander Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Flooring Tools Market
Tools
Global Sandblasting Media Market
Tools
Orbital Sanders Market