
 Industrial Carbon Capture Performance and Verification Test Platforms Market | 2026-2036
Industrial Carbon Capture Performance and Verification Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Carbon Capture Performance and Verification Test Platforms Market Insights
Steel production is hardening as the fastest-growing end-use vertical for carbon capture verification, displacing traditional power generation deployments. ABB leverages its automation heritage to dominate integrated control architectures for pilot-scale platforms. Emerson sustains competitive positioning through distributed sensor networks that anchor real-time performance validation. SGS differentiates by occupying the third-party certification layer, where independent verification commands premium pricing.
Industrial carbon capture performance and verification test platforms comprise engineered systems designed to measure, validate, and document carbon dioxide removal efficiency across capture, transport, and storage stages, typically operating at pressure ranges from atmospheric to supercritical conditions and temperatures spanning cryogenic to post-combustion flue gas regimes. Pilot scale platforms lead current deployment volumes due to lower capital barriers, though commercial scale systems concentrate margin pools as operators seek bankable data for full-scale project financing. Post-combustion capture technology dominates existing installations, while chemical looping represents the fastest-growing segment as developers pursue energy penalty reductions below conventional amine-based systems.
The EPA enforces greenhouse gas reporting protocols that mandate documented capture efficiency for facilities exceeding emission thresholds, directly shaping hardware specifications for monitoring equipment. The EU Green Deal and REACH compliance frameworks impose additional verification burdens on importers and operators, creating dual-jurisdiction complexity for multinational platform vendors. Stakeholders must monitor evolving carbon border adjustment mechanisms and decide whether to prioritize modular system architectures that accommodate regulatory divergence across jurisdictions.
Market Dynamics
Steel producers now dominate new verification platform deployments, eclipsing power utilities as the primary demand anchor for pilot-scale test beds. This demand rotation concentrates procurement around blast furnace retrofits and direct reduction iron facilities seeking bankable capture data.
Growth Catalysts
- EU Green Deal compliance deadlines:Cement and steel operators in Germany, Poland, and the Netherlands accelerate verification platform procurement to document capture efficiency ahead of 2030 benchmarks.
- Chemical looping technology maturation:Developers pursue energy penalty reductions below amine-based systems, driving demand for specialized test beds operating at elevated temperatures and pressures.
- Industrial cluster concentration:The Rhine-Ruhr and Rotterdam-Antwerp corridors anchor Europe's densest pilot platform installations, creating network effects for shared verification infrastructure.
Market Restraints
- Supercritical CO2 compressor supply concentration:German and Japanese specialized machinery suppliers command 18-24 month lead times, throttling platform commissioning schedules.
- High-purity amine solvent cost volatility:Fluctuations in petrochemical feedstock prices directly impact operating expenditure models for post-combustion verification campaigns.
- REACH registration complexity:Novel capture solvents face extended toxicity assessment timelines, delaying platform validation for emerging chemical looping media.
Strategic Opportunities
- India's hard-to-abate industrial corridors:The steel and cement clusters around Jamshedpur and Chhattisgarh remain undersupplied with third-party verification capacity.
- Modular platform architectures:Containerized test beds enable rapid redeployment across regulatory jurisdictions, accommodating divergence between EPA greenhouse gas protocols and EU carbon border adjustment mechanisms.
- Carbon credit monetization integration:Verification platforms that embed ISO 14064-2 compliant quantification methods command premium positioning in voluntary carbon market offtake negotiations.
Industry Challenges
- Process control engineer scarcity:The intersection of chemical engineering, instrumentation, and carbon accounting expertise remains thinly staffed across platform vendors and operator teams.
- Multi-jurisdiction certification timelines:Simultaneous EPA protocol alignment and EU notified body approval extend platform qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Carbon Capture Performance and Verification Test Platforms Market |
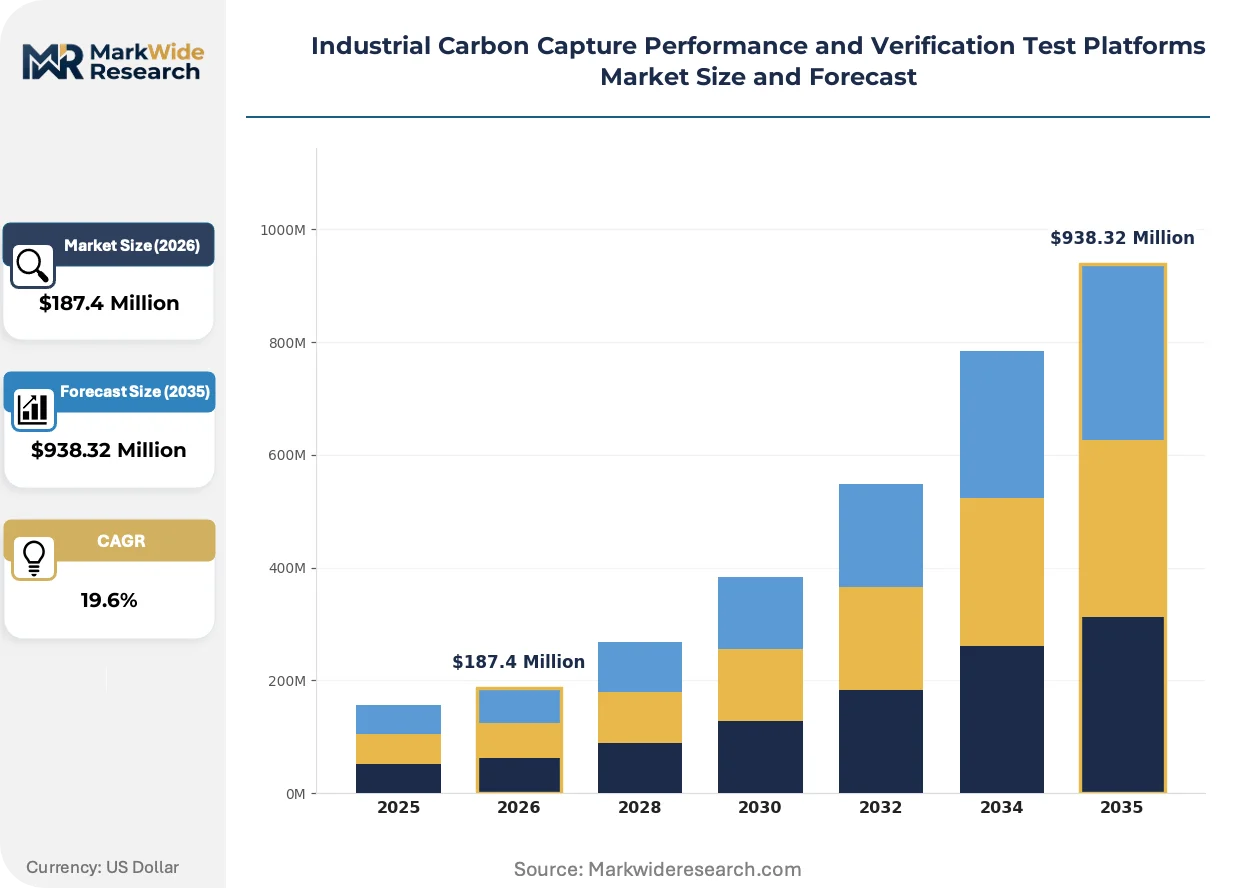
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $938.32 Million |
| CAGR (2026 – 2036) | 19.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Pilot Scale, Demonstration Unit, Commercial Scale, Modular System Technology: Post-Combustion Capture, Pre-Combustion Capture, Oxy-Fuel Combustion, Chemical Looping Application: Power Generation, Petrochemical Processing, Cement Manufacturing, Steel Production End User: Energy Producers, Chemical Manufacturers, Construction Material Plants, Metal Fabricators |
| Companies Covered | ABB, Emerson, Endress+Hauser, SICK, AMETEK Process Instruments, HORIBA, SGS, Baker Hughes, Shell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Carbon Capture Performance and Verification Test Platforms Market Trends and Innovations
Digital twin architectures are displacing physical pilot replication as the primary method for scale-up risk mitigation, compressing verification timelines while expanding data granularity. This convergence of virtual and physical testing layers reconfigures platform vendor value propositions toward software-integrated offerings.
Solid sorbent capture systems is expanding into cement plant retrofits, where high flue gas dust loads degrade conventional amine performance. Heidelberg Materials and similar operators pilot moving-bed configurations at German sites. The technology is expanding into commercial demonstration contracts faster than post-combustion liquid systems, compressing the traditional 5-7 year pilot-to-scale timeline.
EPA greenhouse gas reporting protocol amendments now mandate continuous emissions monitoring system validation for capture facilities above 25,000 metric tons annual CO2 throughput. This tightens hardware specifications for pressure transducers and gas analyzers. Platform vendors serving US industrial clusters reconfigure sensor arrays to meet enhanced calibration frequency requirements.
Integrated service contracts now bundle verification platform operation with third-party certification and carbon credit issuance, displacing equipment-only procurement. SGS and Bureau Veritas anchor this consolidated offering in European industrial clusters. Steel producers in the Ruhr region favor single-source accountability over fragmented vendor management.
Industrial Carbon Capture Performance and Verification Test Platforms Market Segmentation
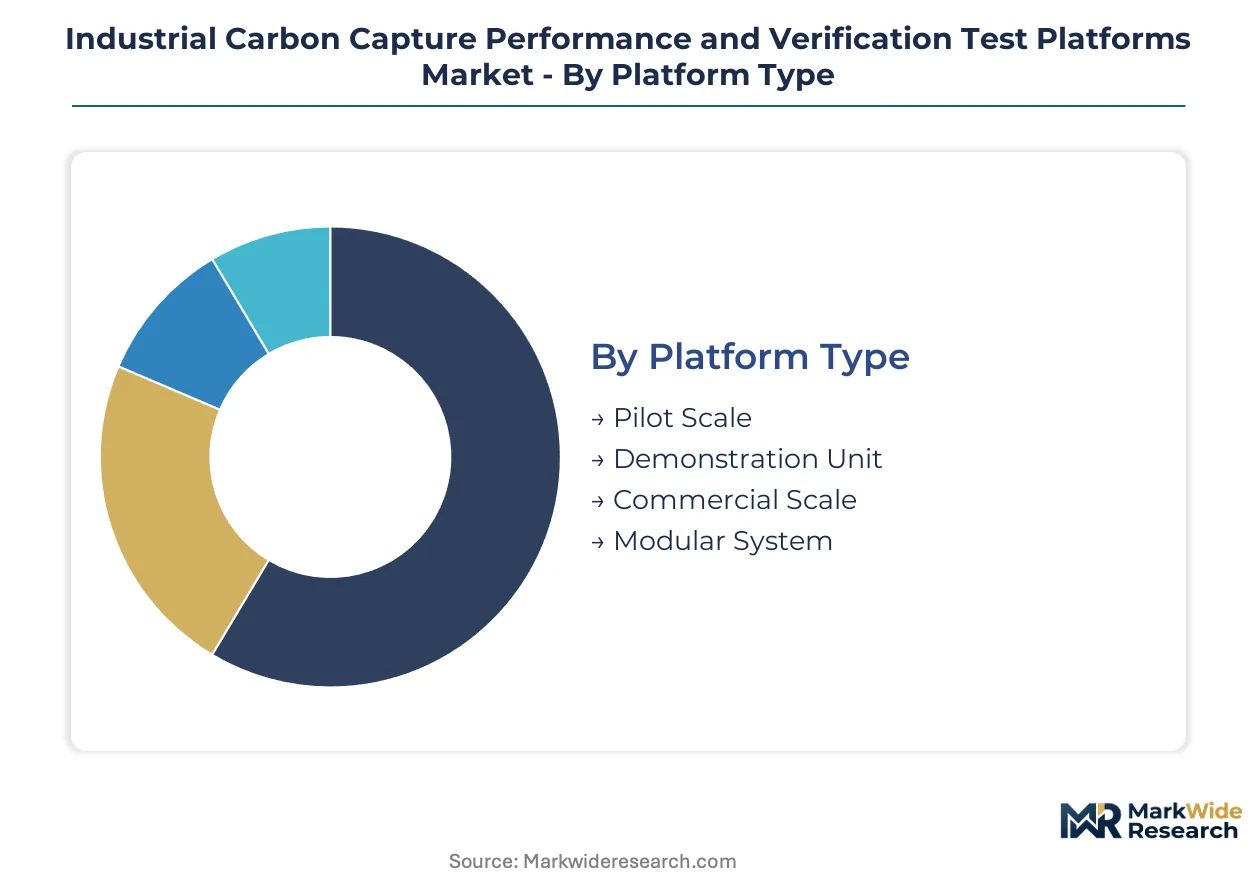
Platform configurations diverge sharply across deployment stages, with capital intensity and regulatory documentation requirements driving distinct procurement patterns. Each segmentation axis reveals how operators balance technical validation needs against financing timelines and compliance burdens.
Platform Type:
Upgrade cycles accelerate as pilot operators seek bankable data packages for commercial financing, compressing replacement timelines from seven years toward four.
- Pilot Scale:Systems process 1-10 tonnes CO2 daily, enabling solvent screening and parameter optimization at capital outlays below commercial thresholds. Cement operators in Germany's Rhine-Ruhr corridor deploy these units for EU Green Deal compliance documentation ahead of 2030 benchmarks.
- Demonstration Unit:Intermediate-scale platforms bridge 10-100 tonnes daily throughput, generating performance guarantees required by project financiers. Steel producers around Rotterdam-Antwerp anchor regional demand for these systems as blast furnace retrofits advance.
- Commercial Scale:Bankable validation infrastructure processing 100+ tonnes daily commands premium positioning.
- Modular System:Containerized architectures enable rapid redeployment across regulatory jurisdictions.
Pilot Scale sits at the top of the volume ranking, with Modular System climbing the fastest.
Technology:
Cost tiers stratify around energy penalty profiles, with high-efficiency alternatives commanding 40-60% capital premiums over baseline amine configurations.
- Post-Combustion Capture:Amine-based solvent systems dominate existing installations, operating at 40-60°C with established supply chains for monoethanolamine and proprietary blends. EPA greenhouse gas reporting protocols mandate continuous emissions monitoring validation for these facilities above 25,000 metric tons annual throughput.
- Chemical Looping:Oxygen carrier materials enable combustion without direct air contact, slashing energy penalties below conventional amine systems. Developers in the Netherlands and Germany pilot moving-bed configurations at elevated temperatures, with REACH registration complexity delaying solvent commercialization timelines.
- Pre-Combustion Capture:Syngas processing with water-gas shift reactors suits integrated gasification combined cycle plants.
- Oxy-Fuel Combustion:Pure oxygen combustion generates concentrated CO2 streams requiring less separation energy.
Post-Combustion Capture holds the installed base lead, with Chemical Looping gaining share fastest.
Application:
Volume concentration follows hard-to-abate process intensity, with thermal combustion regimes dictating platform specification requirements.
- Cement Manufacturing:Kiln flue gas streams at 300-400°C with high particulate loads demand specialized filtration and cooling trains. Heidelberg Materials and similar operators pilot solid sorbent moving-bed configurations at German sites, compressing traditional pilot-to-scale timelines.
- Steel Production:Blast furnace and direct reduction iron facilities generate variable CO2 concentrations requiring flexible capture architectures. The Ruhr region's steel cluster anchors Europe's densest verification platform installations for EU carbon border adjustment preparation.
- Power Generation:Natural gas combined cycle and coal residual fleets drive baseline demand.
- Petrochemical Processing:Ethylene crackers and hydrogen production units present high-purity CO2 opportunities.
Cement Manufacturing commands current procurement volumes, with Steel Production expanding most quickly.
End User:
Customer type determines contracting structure, with integrated industrial groups favoring bundled verification-certification services over equipment-only procurement.
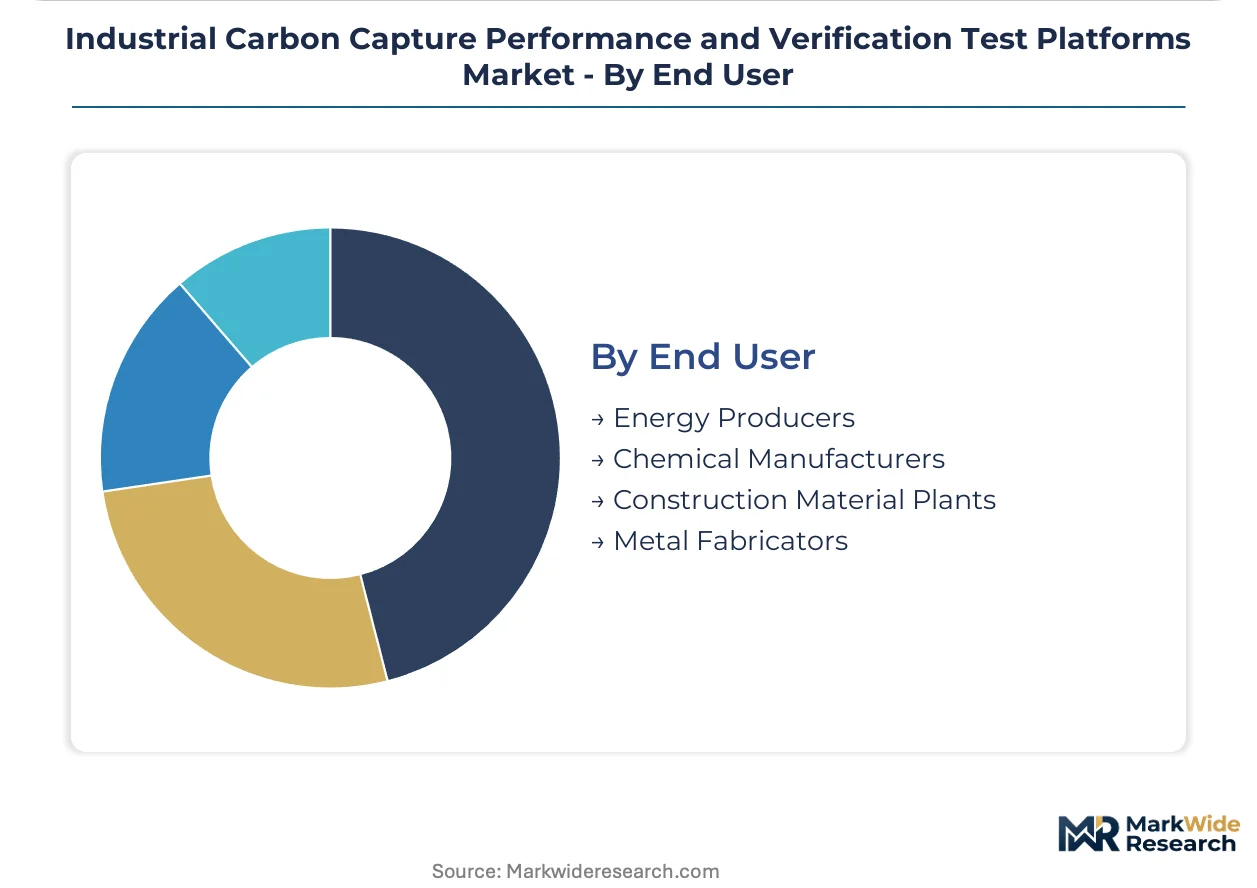
- Construction Material Plants:Cement and lime producers face the steepest EU Green Deal compliance trajectories, driving integrated service contract adoption. SGS and Bureau Veritas anchor consolidated offerings combining platform operation with third-party certification in European clusters.
- Metal Fabricators:Steel producers prioritize single-source accountability for blast furnace retrofit validation. Process control engineer scarcity at the intersection of chemical engineering and carbon accounting constrains operator team expansion.
- Energy Producers:Power utilities anchor legacy demand for post-combustion verification.
- Chemical Manufacturers:Petrochemical and fertilizer operators pursue pre-combustion and oxy-fuel configurations.
Construction Material Plants lead segment procurement, with Metal Fabricators showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting verification platform procurement toward jurisdictions where EU carbon border adjustment mechanisms and EPA greenhouse gas protocols create divergent compliance cost structures. Germany's industrial clusters absorb the densest concentration of pilot-scale deployments as operators front-load documentation ahead of 2030 benchmarks. India's hard-to-abate corridors remain undersupplied, attracting modular platform architectures designed for rapid redeployment.
Germany
Blast furnace retrofits and cement kiln upgrades in the Rhine-Ruhr corridor drive procurement volumes for demonstration-scale verification systems. The EU Green Deal and REACH compliance frameworks impose dual documentation burdens on capture efficiency. Heidelberg Materials operates solid sorbent pilots at multiple German sites, compressing traditional validation timelines.
United States
Steel producers in the Great Lakes region and petrochemical operators along the Gulf Coast anchor demand for EPA-compliant monitoring infrastructure. The EPA mandates continuous emissions monitoring system validation for facilities exceeding 25,000 metric tons annual CO2 throughput. Houston and Lake Charles industrial clusters host the densest pilot platform concentrations outside Europe.
Netherlands
Chemical looping developers pilot moving-bed configurations at elevated temperatures around the Rotterdam-Antwerp port complex. The EU Green Deal compliance deadlines accelerate procurement ahead of 2030. Shell and similar operators validate novel oxygen carrier materials at shared verification facilities.
India
Steel and cement clusters around Jamshedpur and Chhattisgarh lack third-party verification capacity for hard-to-abate emissions. The country's national environmental regulator is tightening documentation requirements for large industrial installations. Modular containerized platforms enable rapid deployment across scattered production sites.
China
Dual carbon goals and provincial emissions trading pilots drive verification platform adoption in the Yangtze River Delta and Shandong Peninsula. The Ministry of Ecology and Environment is strengthening monitoring requirements for steel and cement sectors. Baowu Steel operates pilot capture systems with integrated performance validation at Shanghai-area facilities.
Industrial Carbon Capture Performance and Verification Test Platforms Market Competitive Landscape
Strategic partnerships dominate the current landscape as platform vendors bundle hardware deployment with third-party certification services. The vendor base organizes around three tiers: integrated automation conglomerates, specialized instrumentation houses, and independent verification bodies. Automation specialists anchor the premium segment through control architecture integration. Instrumentation providers compete on sensor density and real-time data granularity. Certification bodies capture margin pools by embedding ISO-compliant quantification methods directly into platform operations.
Among Swiss-based verification specialists, SGS exemplifies the certification-integrated archetype. ABB and Emerson represent the automation-centric tier, anchoring competitive positioning through distributed control heritage. These three companies illustrate how competitive advantage concentrates at the intersection of hardware deployment and regulatory documentation capability.
| Leading Market Players |
|---|
| ABB |
| Emerson |
| Endress+Hauser |
| SICK |
| AMETEK Process Instruments |
| HORIBA |
| SGS |
| Baker Hughes |
| Shell |
| Others |
Pricing and Supply Chain Analysis
Solid sorbent capture maturation in cement plant retrofits simultaneously compresses validation timelines and concentrates procurement leverage among German and Dutch industrial clusters. This technology transition rewards operators with integrated control architectures while squeezing margins for standalone instrumentation vendors.
Pricing Analysis
Distributor margins on verification platform hardware range from 12-18 percent, with direct-to-OEM contracts commanding steeper discounts for volume commitments. Pricing stratifies across certification-integrated, standard instrumentation, and economy sensor tiers, with ISO 14064-2 compliant bundling capturing 35-45 percent premiums. Cost compression in standard sensor arrays is intensifying because EPA calibration frequency mandates are commoditizing baseline gas analyzer specifications. Cement operators in Germany's Rhine-Ruhr corridor exhibit the sharpest price sensitivity, while steel producers prioritize single-source accountability over procurement savings.
Supply Chain Analysis
Dual-sourcing requirements for supercritical CO2 compressors are mandating multi-supplier qualification across German and Japanese specialized machinery houses. Component supply draws from precision pressure vessel fabrication in Germany, advanced gas analyzer manufacturing in the United States, and oxygen carrier material synthesis in the Netherlands. Single-source vulnerability concentrates around 18-24 month lead times for cryogenic-grade compression equipment. Distribution runs through integrated automation conglomerates and third-party certification bodies rather than traditional industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on digital twin software integration that collapses physical pilot replication costs while embedding premium certification workflows.
For Market Incumbents: Acquire digital twin software capabilities to anchor recurring revenue streams as physical platform sales plateau. Cement and steel operators are consolidating procurement around bundled verification-certification contracts, threatening standalone instrumentation margins. Backward integration into oxygen carrier material synthesis secures supply security for chemical looping test bed deployments. For New Entrants and Emerging Players: Begin with modular containerized architectures targeting India's undersupplied steel and cement corridors around Jamshedpur and Chhattisgarh. The country's national environmental regulator is tightening documentation requirements without domestic verification capacity to match. A certification-integrated service model bypasses capital-intensive hardware manufacturing while capturing carbon credit monetization flows. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized instrumentation houses lacking software-integrated control heritage. Long-term viability favors vendors with EPA protocol alignment and EU notified body approval already embedded in platform operations. The signal to watch is REACH registration acceleration for novel chemical looping solvents, which would unlock demonstration-scale deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | SGS and Bureau Veritas embed virtual validation layers to compress client timelines. |
| Backward Integration into Sorbent Materials | Heidelberg Materials pilots captive oxygen carrier supply for German cement sites. |
| Modular Containerized Deployment | Container architectures enable rapid redeployment across EPA and EU regulatory jurisdictions. |
| Certification-Integrated Service Contracts | Steel producers in the Ruhr region favor single-source accountability over fragmented procurement. |
| Joint Venture for Shared Verification Infrastructure | Rotterdam-Antwerp port complex anchors network effects for chemical looping developers. |
Research Methodology
Multiple input streams — primary interviews with process control engineers, platform vendor technical directors, and steel procurement leads; secondary validation through EPA greenhouse gas reporting protocols, EU ETS compliance databases, and industrial cluster development filings; plus customs records for compression equipment trade flows — were reconciled through bottom-up and top-down triangulation. Field perspectives from Rhine-Ruhr corridor operators and Rotterdam-Antwerp chemical looping developers anchored demand-side calibration. SEC filings from automation conglomerates and notified body certification registers supplied vendor-side validation.
Historical deployment trajectories were cross-referenced against panel input from EPC contractors and project financiers to model adoption curves across the projection horizon. Segmentation dimensions included platform scale tier, capture technology type, end-use application intensity, and regulatory jurisdiction cluster. CAGRs were derived from installed base expansion rates and replacement cycle compression observed in pilot-to-demonstration upgrade patterns. Chemical looping technology maturation timelines and carbon border adjustment mechanism implementation velocity served as industry-specific forecast inputs.
Caveats apply where REACH registration delays for novel solvents or supercritical compressor supply bottlenecks could materially shift the outlook. Forecasts reflect assumptions around EU Green Deal compliance deadline adherence and EPA protocol amendment stability. Deviation in carbon credit monetization regulatory clarity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Global Water Quality Monitoring Market
Environment & Sustainability
Asia-Pacific Carbon Dioxide Market
Environment & Sustainability
Green Waterproofing Products Market
Environment & Sustainability
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environment & Sustainability
Green Coatings Market
Environment & Sustainability
Global Oil Spill Management Market
Environment & Sustainability
Testing, Inspection, and Certification for Natural Resources Market
Environment & Sustainability
Indonesia Gravity-Based Water Purifier Market
Environment & Sustainability
Carbon Management System Market
Environment & Sustainability
Water Ionizers Market
Environment & Sustainability
Global High End Greenhouse Market
Environment & Sustainability
LAMEA Emission Monitoring System Market
Environment & Sustainability
Global Mist Eliminator Market
Environment & Sustainability
Weather Modification Equipment Market
Environment & Sustainability
Electrocoagulation Market
Environment & Sustainability
Philippines Gravity-Based Water Purifier Market