
 LAMEA Emission Monitoring System Market | 2026-2036
LAMEA Emission Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Emission Monitoring System Market Insights
Market Dynamics
Power generation's grip on procurement is hardening as utilities retire manual sampling in favor of continuous stack monitoring. ABB Ltd. leverages its analyzer portfolio to dominate retrofit cycles across Middle Eastern combined-cycle plants. Emerson Electric Company sustains channel control through distributed control system bundling in African mining-power complexes. Siemens AG anchors its position with laser measurement integration into existing turbine control architectures.
Technology and Segment Structure
Emission monitoring systems comprise sensor arrays, data acquisition hardware, and compliance reporting software that quantify flue gas concentrations of SOx, NOx, CO, and particulate matter against permitted thresholds. Continuous emission monitors command the largest installed base due to regulatory mandates for hourly reporting, while laser measurement technology captures the fastest expansion as oil and gas operators seek single-digit ppm detection for leak detection programs. Software solutions represent an emerging margin pool as utilities outsource calibration management and regulatory filing automation.
Regulatory Environment
Saudi Arabia's General Authority for Meteorology and Environmental Protection and South Africa's Department of Forestry, Fisheries and the Environment enforce stack monitoring rules that directly determine capital allocation timelines. Brazil's IBAMA licensing conditions and Mexico's SEMARNAT emissions registry create compliance-driven replacement cycles for aging analyzers. Stakeholders must track how Gulf state net-zero commitments reshape inspection frequency requirements and whether African power pools harmonize cross-border emission disclosure standards.
Market Dynamics
Continuous emission monitoring mandates from Saudi Arabia's General Authority for Meteorology and Environmental Protection and Brazil's IBAMA are forcing power utilities across Latin America, the Middle East, and Africa to replace intermittent stack sampling with permanent analyzer installations. This regulatory compression is restructuring capital allocation timelines and vendor selection criteria throughout the region.
Growth Catalysts
- Gulf petrochemical corridor expansion:Saudi Arabia and UAE operators are installing laser-based leak detection systems to satisfy single-digit ppm detection requirements for methane and VOC monitoring in refinery complexes.
- South African coal basins:Eskom's fleet modernization and Department of Forestry, Fisheries and the Environment enforcement are triggering analyzer procurement cycles across Mpumalanga power stations.
- Net-zero alignment protocols:GCC state decarbonization commitments are mandating hourly emissions disclosure from combined-cycle plants, accelerating software and calibration service contracts.
Market Restraints
- Analyzer hardware import dependency:UV and infrared sensor modules concentrate in German and Japanese manufacturing bases, exposing LAMEA buyers to currency volatility and extended lead times.
- Technical calibration limitations:Reference gas standard availability remains restricted in sub-Saharan African markets, complicating CEMS certification and audit readiness.
- Substitution by predictive modeling:Some mining operators are piloting AI-based emission estimation to defer capital-intensive stack analyzer installations.
Strategic Opportunities
- Underpenetrated Nigerian power sector:Grid expansion and privatized generation assets create first-mover positioning for integrated monitoring-software bundles.
- Egyptian industrial zones:New regulatory filing requirements for cement and steel producers are opening retrofit windows for extractive and in-situ measurement technologies.
- Cloud-based compliance automation:Regulatory filing outsourcing is emerging as a margin pool as utilities seek to reduce in-house calibration management headcount.
Industry Challenges
- Specialized technician scarcity:CEMS installation and maintenance competency concentrates in Johannesburg, São Paulo, and Riyadh service hubs, creating field coverage gaps in secondary markets.
- Legacy DCS integration friction:Analyzer data handshake with existing turbine control architectures from the 1990s requires costly protocol translation and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Emission Monitoring System Market |
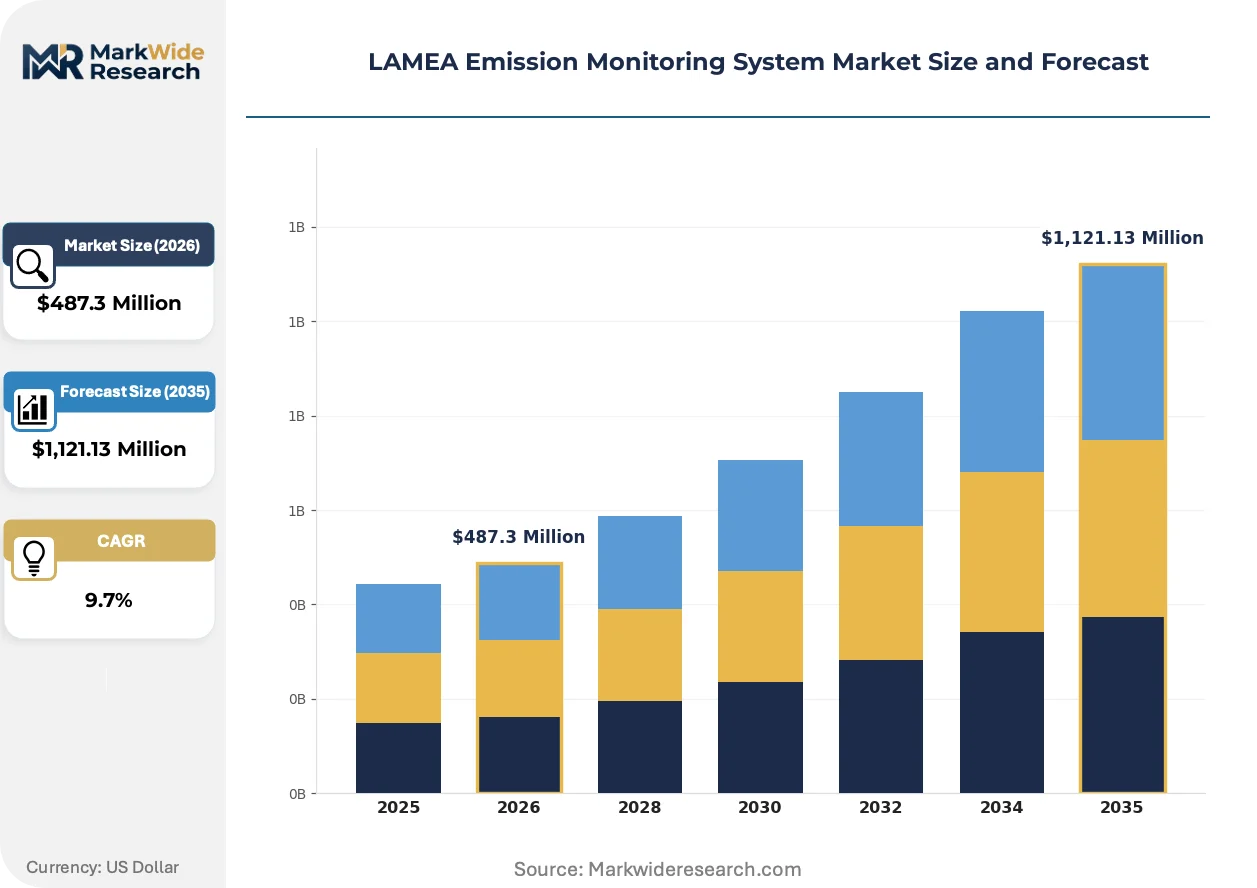
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,121.13 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Emission Monitors, Portable Emission Monitors, Software Solutions, Analyzers End User: Power Generation, Oil & Gas, Chemical Manufacturing, Waste Management Technology: Chemiluminescence, Infrared, UV Fluorescence, Laser Measurement Application: Regulatory Compliance, Process Optimization, Environmental Monitoring, Leak Detection |
| Companies Covered | ABB Ltd., AMETEK, Inc., Emerson Electric Company, Siemens AG, Honeywell International Inc., Horiba Ltd., Fuji Electric Co., Ltd., Teledyne Technologies, Sick AG, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Emission Monitoring System Market Trends and Innovations
Tunable diode laser absorption spectroscopy and quantum cascade infrared platforms are compressing detection limits while expanding the addressable application set beyond traditional stack monitoring. These hardware advances are converging with software-defined calibration workflows that reduce manual intervention.
Extractive CEMS architectures are overtaking dilution-based sampling systems in Middle Eastern combined-cycle applications. Saudi Aramco and ADNOC affiliates are specifying direct in-situ measurement for sub-5 ppm NOx resolution. This displacement is compressing the installed base of water-conditioned sampling trains and redirecting service revenue toward laser module replacement cycles.
South Africa's carbon tax regulations and impending border adjustment mechanisms are tightening disclosure granularity requirements for Scope 1 emissions. Industrial facilities above the reporting threshold must submit verified hourly data, forcing cement and steel producers to upgrade from quarterly manual testing. The compliance burden falls heaviest on Mpumalanga and KwaZulu-Natal manufacturing clusters.
Analyzer procurement is consolidating through engineering-procurement-construction contractors rather than direct utility purchasing. EPC firms in the GCC are bundling CEMS specifications into combined-cycle and refinery construction packages, compressing vendor access and favoring suppliers with established EPC qualification status. This channel shift is most pronounced in Saudi Arabia's Red Sea industrial city developments.
LAMEA Emission Monitoring System Market Segmentation
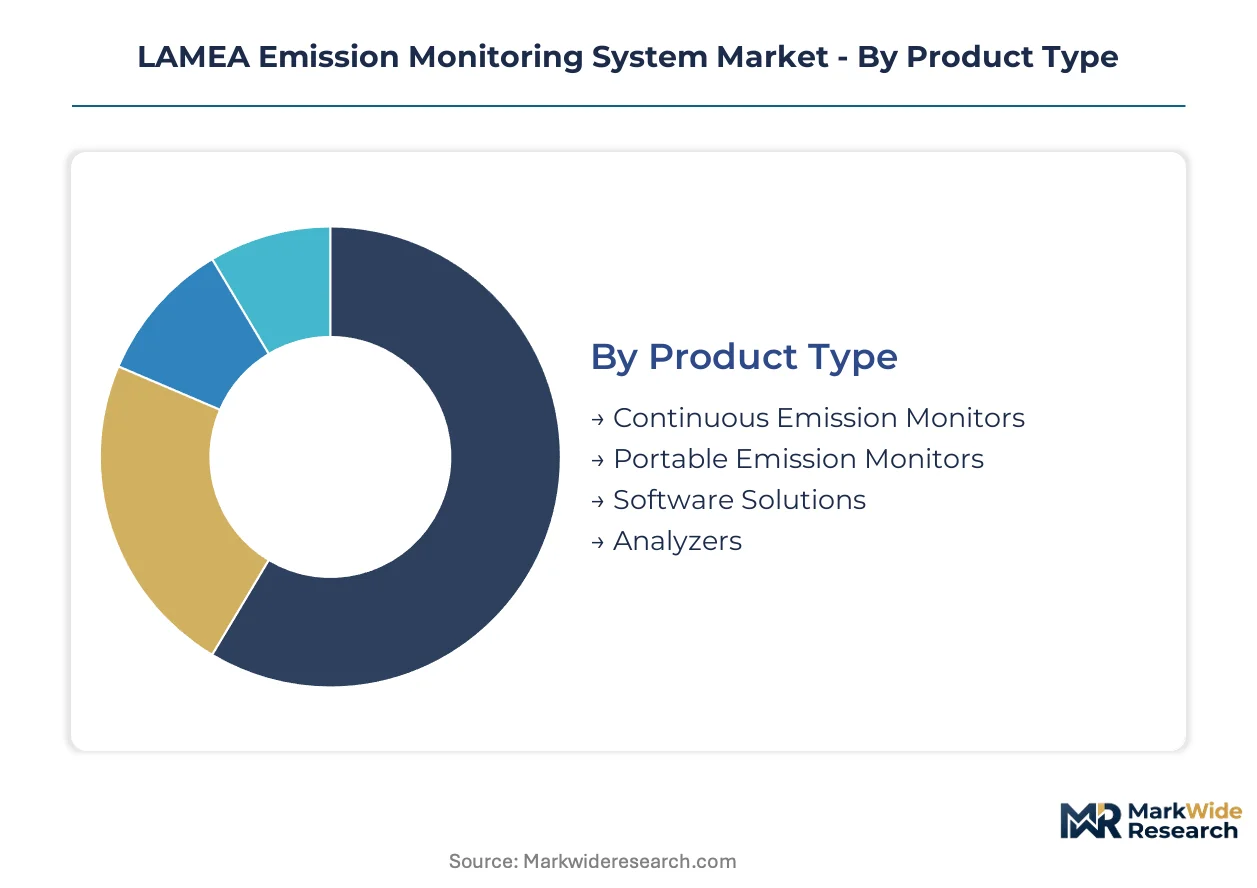
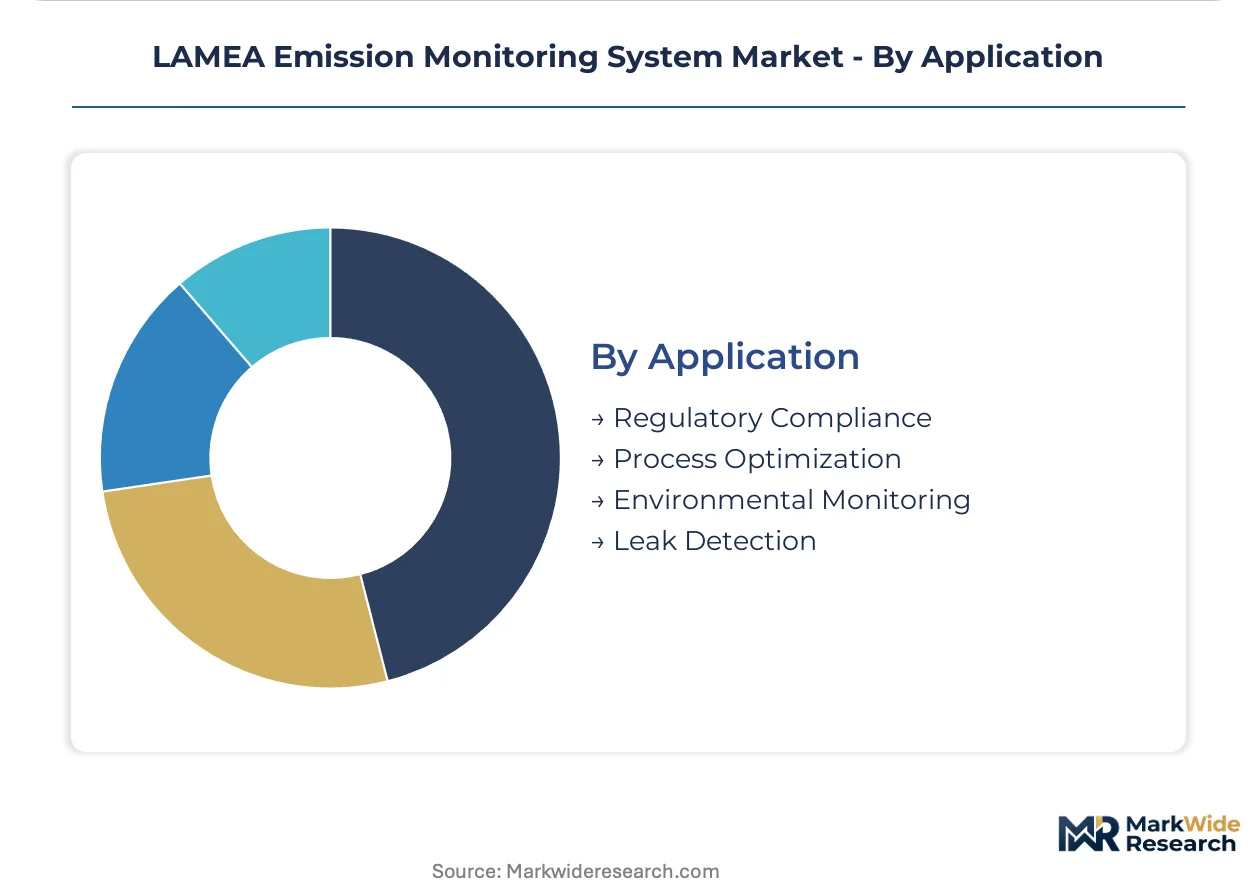
Segmentation in the LAMEA Emission Monitoring System Market reveals how regulatory pressure and industrial infrastructure shape procurement patterns. Technology choices vary sharply between Gulf petrochemical corridors and sub-Saharan power basins. Understanding these divides clarifies where hardware margins concentrate versus where software and services capture value.
Product Type:
Supply concentration in sensor manufacturing concentrates procurement leverage among German and Japanese component suppliers, forcing LAMEA buyers toward bundled system integrators.
- Continuous Emission Monitors:Permanent stack-mounted analyzer arrays deliver hourly SOx, NOx, CO, and particulate matter readings against permitted thresholds. Saudi Arabia's General Authority for Meteorology and Environmental Protection mandates these systems across combined-cycle plants, compressing replacement cycles for aging manual sampling infrastructure.
- Software Solutions:Calibration management platforms and regulatory filing automation tools reduce in-house compliance headcount. South African cement and steel producers facing carbon tax disclosure granularity are outsourcing verification workflows, creating recurring revenue pools distinct from hardware sales.
- Portable Emission Monitors:Mobile analyzer units serve audit verification and spot-checking requirements in Nigerian grid expansion zones where permanent installation remains uneconomical.
- Analyzers:Standalone sensor modules support retrofit upgrades and component replacement in existing CEMS architectures across Mpumalanga power stations.
Continuous Emission Monitors absorb the bulk of installed capacity; Software Solutions are expanding most quickly.
End User:
Customer concentration in state-linked utilities and national oil companies creates procurement patterns distinct from fragmented private manufacturing.
- Power Generation:Coal-fired basins in South Africa and combined-cycle fleets in Saudi Arabia drive analyzer demand as Eskom modernization and GCC decarbonization commitments force hourly disclosure. IBAMA licensing conditions in Brazil accelerate replacement of intermittent sampling at privatized generation assets.
- Oil & Gas:Methane and VOC monitoring requirements for single-digit ppm detection dominate refinery and upstream operations. ADNOC affiliates specify laser-based leak detection systems, redirecting capital from traditional extractive sampling trains.
- Chemical Manufacturing:Process control integration in Egyptian industrial zones creates demand for in-situ measurement technologies as new filing requirements take effect.
- Waste Management:Incineration facility monitoring in São Paulo metropolitan area follows IBAMA enforcement patterns for dioxin and furan stack emissions.
Power Generation commands the dominant share of procurement volume; Oil & Gas is climbing the fastest on leak detection program expansion.
Technology:
Detection limit compression in optical platforms is displacing legacy electrochemical methods across high-value applications.
- Laser Measurement:Tunable diode laser absorption spectroscopy achieves sub-5 ppm NOx resolution without water-conditioned sampling infrastructure. Saudi Aramco specifications favor direct in-situ installation, reducing commissioning timelines and maintenance burden.
- Infrared:Non-dispersive infrared analyzers remain cost-effective for standard CO and CO2 monitoring in African markets where reference gas standard availability constrains more complex certification.
- Chemiluminescence:Reference method for NOx quantification in regulatory compliance applications, particularly where Brazilian or South African audit protocols require documented traceability.
- UV Fluorescence:Sulfur dioxide detection in refinery and power plant applications maintains installed base despite laser platform encroachment.
Infrared platforms retain the largest installed base; Laser Measurement is gaining share fastest on petrochemical corridor specifications.
Application:
Margin structure diverges sharply between mandatory compliance spend and discretionary optimization investments.
- Regulatory Compliance:Mandatory hourly disclosure and quarterly filing requirements determine capital allocation timelines. South Africa's Department of Forestry, Fisheries and the Environment enforcement and Saudi net-zero alignment protocols leave no procurement discretion.
- Leak Detection:Methane emission reduction targets in GCC national oil companies drive laser-based system deployment beyond minimum regulatory requirements.
- Process Optimization:Combustion efficiency improvements in Egyptian cement and steel sectors create retrofit demand as producers seek fuel cost reduction alongside compliance.
- Environmental Monitoring:Ambient air quality networks in São Paulo and Johannesburg deploy analyzer stations for urban pollution mapping distinct from stack monitoring.
Regulatory Compliance captures the majority of current expenditure; Leak Detection is expanding most rapidly on voluntary decarbonization commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Red Sea industrial cities and special economic zones concentrate the Gulf's most intensive emission monitoring procurement cycles. These tax-incentive corridors bundle analyzer specifications into engineering-procurement-construction packages for combined-cycle plants and refinery complexes.
Saudi Arabia
ADNOC affiliates and Saudi Aramco operators specify laser-based leak detection systems for sub-5 ppm NOx resolution. The General Authority for Meteorology and Environmental Protection mandates hourly emissions disclosure from combined-cycle plants. Jazan and Yanbu industrial clusters anchor the region's fastest analyzer replacement cycles.
Brazil
Privatized generation assets and grid expansion trigger continuous emission monitor procurement across São Paulo and Minas Gerais. IBAMA licensing conditions for thermal power plants accelerate retirement of intermittent stack sampling. The São Paulo metropolitan area's waste incineration facilities face dioxin and furan monitoring enforcement.
South Africa
Eskom's fleet modernization and carbon tax regulations force hourly data disclosure from Mpumalanga coal-fired basins. The Department of Forestry, Fisheries and the Environment enforces verified emissions reporting for cement and steel producers above threshold limits. KwaZulu-Natal manufacturing clusters upgrade from quarterly manual testing to permanent analyzer installations.
United Arab Emirates
ADNOC specifications favor direct in-situ measurement technologies over water-conditioned sampling trains. The country's net-zero alignment protocols mandate software-defined calibration workflows for refinery and petrochemical corridors. Abu Dhabi and Dubai industrial zones redirect service revenue toward laser module replacement cycles.
Egypt
New regulatory filing requirements for cement and steel producers open retrofit windows for extractive and in-situ measurement technologies. The country's industrial zones in Suez and Alexandria face upgraded disclosure granularity for Scope 1 emissions. Egyptian engineering-procurement-construction contractors increasingly bundle CEMS specifications into construction packages.
LAMEA Emission Monitoring System Market Competitive Landscape
Top-tier vendors anchor premium-tier analyzer supply, while mid-scale system integrators capture retrofit and maintenance contracts. The market structure concentrates procurement leverage among German and Japanese component suppliers, forcing LAMEA buyers toward bundled offerings. Three strategic archetypes dominate: full-stack analyzer manufacturers, software-defined calibration platforms, and EPC-qualified system integrators. Competitive moves center on EPC qualification status acquisition and laser measurement technology licensing.
Within the full-stack analyzer tier, ABB Ltd., Siemens AG, and Emerson Electric Company represent the dominant competitive anchors. ABB Ltd. exemplifies the European industrial conglomerate archetype with integrated analyzer portfolios. Siemens AG occupies a position as a German engineering group with turbine control architecture integration capabilities. Emerson Electric Company anchors the North American automation specialist segment through distributed control system bundling strategies. These three companies collectively illustrate how vendor selection criteria in LAMEA markets favor established EPC relationships and legacy system compatibility over pure technology performance metrics.
| Leading Market Players |
|---|
| ABB Ltd. |
| AMETEK, Inc. |
| Emerson Electric Company |
| Siemens AG |
| Honeywell International Inc. |
| Horiba Ltd. |
| Fuji Electric Co., Ltd. |
| Teledyne Technologies |
| Sick AG |
| Others |
Pricing and Supply Chain Analysis
State-linked utilities and national oil companies across Saudi Arabia, South Africa, and Brazil concentrate procurement volumes and enforce project-based pricing with extended payment terms. Their bundling of analyzer specifications into engineering-procurement-construction packages compresses vendor margins while elevating qualification barriers.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to UV and infrared sensor modules when German and Japanese manufacturing bases face capacity constraints. Project-based pricing dominates as EPC contractors consolidate procurement, with price differentiation resting on certification grade and after-sales service bundling. Cost compression in standard analyzer tiers intensifies as Chinese component suppliers expand module availability. Mining-power complexes in African markets exhibit highest price sensitivity; Gulf petrochemical operators show least sensitivity due to regulatory deadline pressure.
Supply Chain Analysis
Certification gating restricts supply to vendors holding Saudi Aramco and ADNOC pre-qualification status, compressing qualified supplier pools. Manufacturing concentrates in Germany, Japan, and China for sensor modules and analyzer assemblies. Raw material dependencies include specialized optical components, reference gas standards, and precision electronics. Single-source vulnerability runs through Japanese tunable diode laser suppliers. Distribution feeds from EPC contractor bundling into combined-cycle and refinery construction packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analyzer hardware import dependency and specialized technician scarcity create structural supply constraints that prop pricing power for qualified vendors. Capacity bottlenecks in certification-ready installation crews across sub-Saharan Africa extend project timelines.
For Market Incumbents: Deepen backward integration into reference gas standard production to reduce audit readiness friction in African markets. Expand captive calibration service hubs in Lagos and Nairobi to close field coverage gaps. Laser measurement technology licensing from German component suppliers anchors defensive positioning against emerging software-defined entrants. For New Entrants and Emerging Players: Capture cloud-based compliance automation white space as South African cement and steel producers outsource verification workflows. Target Nigerian grid expansion zones with portable emission monitor rental programs where permanent installation remains uneconomical. Partner with Egyptian engineering-procurement-construction contractors to embed analyzer specifications into construction packages. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale system integrators with established EPC qualification status in Saudi Arabia's Red Sea industrial city developments. Long-term viability hinges on software-defined calibration platform adoption across Gulf Cooperation Council decarbonization commitments. Watch for ADNOC and Saudi Aramco laser specification shifts as inflection indicator for technology displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EPC Qualification Acquisition | Pre-qualification with Saudi Aramco and ADNOC unlocks bundled procurement in Red Sea industrial corridors. |
| Laser Measurement Licensing | Tunable diode laser absorption spectroscopy partnerships compress detection limits for sub-5 ppm NOx specifications. |
| Calibration Service Hub Expansion | Regional certification centers in Johannesburg and São Paulo close technician scarcity gaps in secondary markets. |
| Cloud Compliance Platform Development | Regulatory filing automation captures recurring revenue as South African carbon tax enforcement tightens disclosure. |
| Reference Gas Standard Production | In-house production of calibration gases reduces import dependency and audit friction in sub-Saharan markets. |
Research Methodology
Regulatory filings from Saudi Arabia's General Authority for Meteorology and Environmental Protection, South Africa's Department of Forestry, Fisheries and the Environment, and Brazil's IBAMA formed the secondary backbone for compliance requirement mapping. Primary interviews with utility planning officers, EPC procurement leads, analyzer maintenance directors, and environmental compliance managers at petrochemical operators were combined with customs data and SEC filings from listed automation vendors. Bottom-up installation base estimates and top-down regulatory mandate projections were triangulated to anchor market sizing.
Historical analyzer procurement cycles across Eskom modernization, Saudi combined-cycle expansions, and Brazilian privatization waves established trendline parameters for projection modeling. Segmentation dimensions included technology platform, end-use vertical, application type, and regional regulatory cluster. CAGRs were derived from regulatory deadline phasing and replacement cycle compression. Forecast inputs incorporated carbon tax enforcement trajectories and laser specification adoption curves from national oil company tender documents.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Gulf state net-zero commitment pacing and African power pool harmonization progress. Forecasts reflect documented assumptions regarding regulatory inspection frequency and EPC bundling penetration. A model refresh is warranted upon material change in Saudi Aramco or ADNOC laser specification mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
Environmental Technology Market
Environmental Monitoring
US Cloud Seeding Market
Environmental Monitoring
Environmental Testing Market
Environmental Monitoring
Water Pipeline Leak Detection System Market
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
Smart Water Monitoring Market
Environmental Monitoring
Environmental Radiation Monitor Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Global Environmental Remediation Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
Europe Air Quality Monitoring Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Water Quality Analyzer Market
Environmental Monitoring
Latin America Cloud Seeding Market