
 Weather Modification Equipment Market | 2026-2036
Weather Modification Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Weather Modification Equipment Market Insights
Agricultural water security is broadening the addressable base for weather modification services beyond traditional municipal buyers. Weather Modification International anchors its position through decades of operational flight programs across the American West. Snowy Hydro Limited leverages government-backed infrastructure scale to sustain long-term cloud seeding contracts in Australia. Cloud Technologies GmbH differentiates through specialized ground-based generator systems designed for alpine terrain.
Weather modification equipment comprises engineered systems that introduce nucleating agents into atmospheric conditions to alter precipitation patterns, typically operating at altitudes between 4,000 and 12,000 meters with silver iodide or hygroscopic flares as standard active materials. The primary commercial purpose is to augment freshwater supply or suppress hail damage in targeted catchment zones. Aircraft-based technology leads current deployment value owing to superior coverage area per operation, while drone technology represents the fastest-expanding segment as autonomous platforms reduce crew risk and enable precision targeting in complex terrain. Cloud seeding occupies the mature product category with established protocols, whereas precipitation enhancement commands the deepest margin pools due to recurring drought-response contracts.
The FAA governs aircraft-based dispersal operations through Part 137 agricultural aircraft certifications adapted for atmospheric release missions, while EPA oversight governs silver iodide deposition thresholds in watersheds. China's MEE enforces dual carbon-aligned water security mandates that accelerate state-funded seeding procurement. Stakeholders must monitor evolving unmanned aircraft regulations and nucleating agent environmental thresholds as these frameworks determine both market access boundaries and permissible operational expansion.
Market Dynamics
Autonomous platform deployment is compressing crew requirements and expanding operational windows in terrain previously inaccessible to manned aircraft, fundamentally restructuring cost economics across precipitation enhancement services.
Growth Catalysts
- Silver iodide flare protocols:Mature nucleating agent standards enable rapid regulatory clearance for new equipment entrants in drought-response programs across the American West.
- China MEE dual carbon mandates:State-funded water security procurement accelerates cloud seeding infrastructure deployment under carbon-aligned policy frameworks.
- Alpine catchment zones:Ground-based generator demand concentrates in mountainous terrain where aircraft access remains operationally constrained.
Market Restraints
- FAA Part 137 certification:Agricultural aircraft adaptation for atmospheric release missions imposes multi-year approval timelines and specialized aircrew requirements.
- Silver iodide supply concentration:Nucleating agent production clusters in limited chemical processing regions, exposing operators to input cost volatility.
- EASA operational restrictions:European aviation safety protocols constrain cross-border seeding missions and equipment mobility.
Strategic Opportunities
- Unmanned aircraft convergence:Autonomous platforms integrating precision targeting systems with real-time atmospheric sensors unlock complex terrain penetration.
- Australian Snowy Hydro model:Government-backed infrastructure scale sustains long-term contracting frameworks replicable in other drought-prone jurisdictions.
- Agricultural water districts:Crop insurance linkage creates new procurement channels beyond traditional municipal buyers in irrigation-dependent regions.
Industry Challenges
- Atmospheric physicist scarcity:Specialized flight program design expertise concentrates in legacy operators, constraining new entrant technical capacity.
- EPA watershed deposition thresholds:Silver iodide environmental compliance requires continuous monitoring infrastructure and documentation systems.
- Legacy aircraft integration:Retrofitting manned platforms with modern dispersal systems demands airframe-specific engineering and extended downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weather Modification Equipment Market |
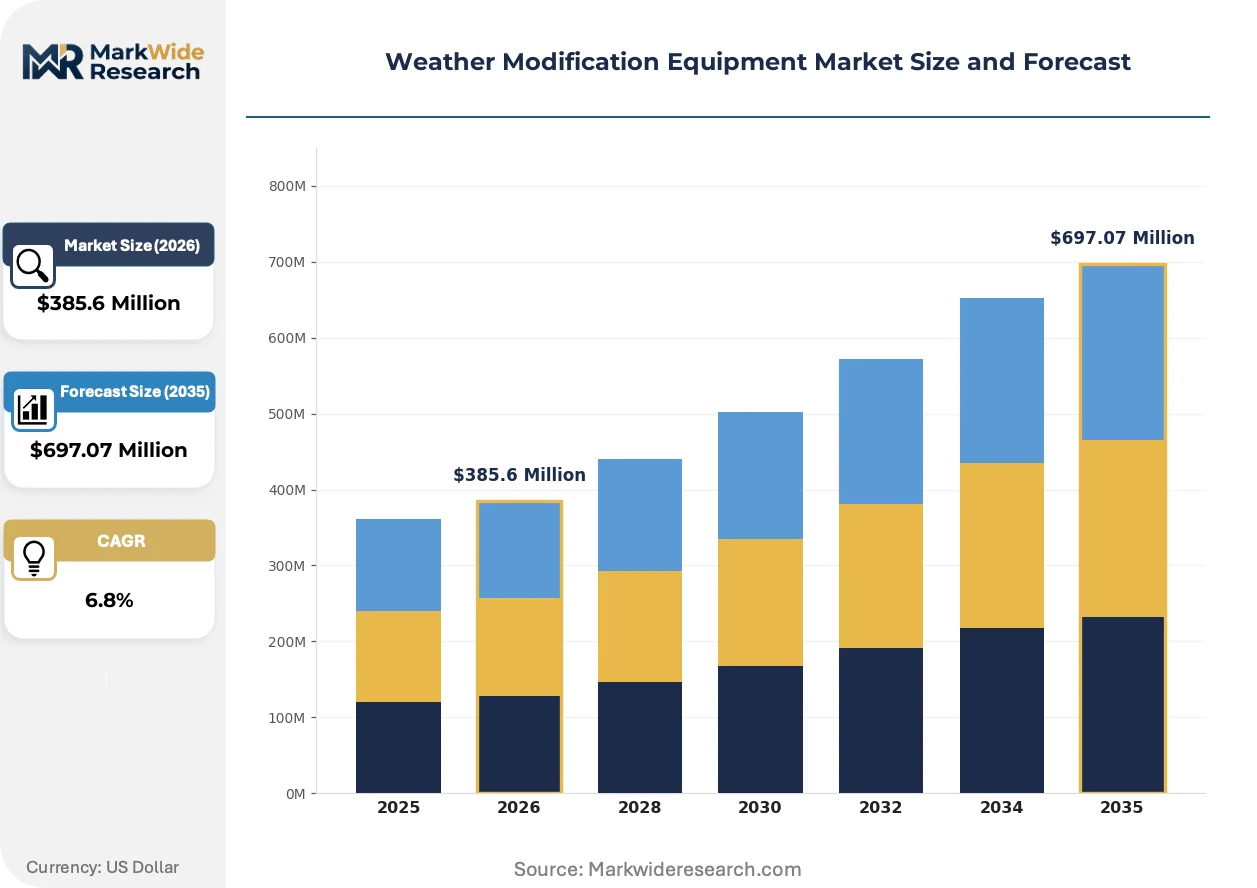
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud Seeding, Fog Dispersal, Precipitation Enhancement, Weather Control Technology: Rocket-Based, Aircraft-Based, Ground-Based, Drone Technology Application: Agriculture, Water Resource Management, Disaster Relief, Research End User: Government Agencies, Private Companies, Research Institutions, Non-Profits |
| Companies Covered | Snowy Hydro Limited, RHS Consulting, Weather Modification International, Cloud Technologies GmbH, Mettech S.p.A., North American Weather Consultants, Meteo Systems, Seeding Operations & Atmospheric Research, Ice Crystal Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weather Modification Equipment Market Trends and Innovations
Precision targeting capabilities and autonomous flight systems are displacing broad-area dispersal methods, compressing operational costs while expanding addressable terrain profiles for precipitation enhancement services.
Drone-based seeding platforms is automating nucleating agent release in complex alpine terrain previously requiring high-risk manned flights. State water districts in Colorado and Wyoming are adopting these systems for targeted catchment augmentation. The technology is automating crew reduction and enabling extended operational windows beyond daylight limitations.
REACH chemical registration requirements in Europe are tightening nucleating agent environmental documentation standards. Manufacturers must now submit comprehensive fate-and-transport studies for silver compound deposition. Ground-based generator suppliers serving alpine regions are reformulating hygroscopic alternatives to preempt regulatory friction.
Service unbundling is separating equipment ownership from flight operations in municipal procurement. Water districts increasingly contract for precipitation outcomes rather than capital equipment acquisition. This shift concentrates most visibly in Texas and New Mexico, where drought emergency declarations accelerate performance-based contracting adoption.
Weather Modification Equipment Market Segmentation
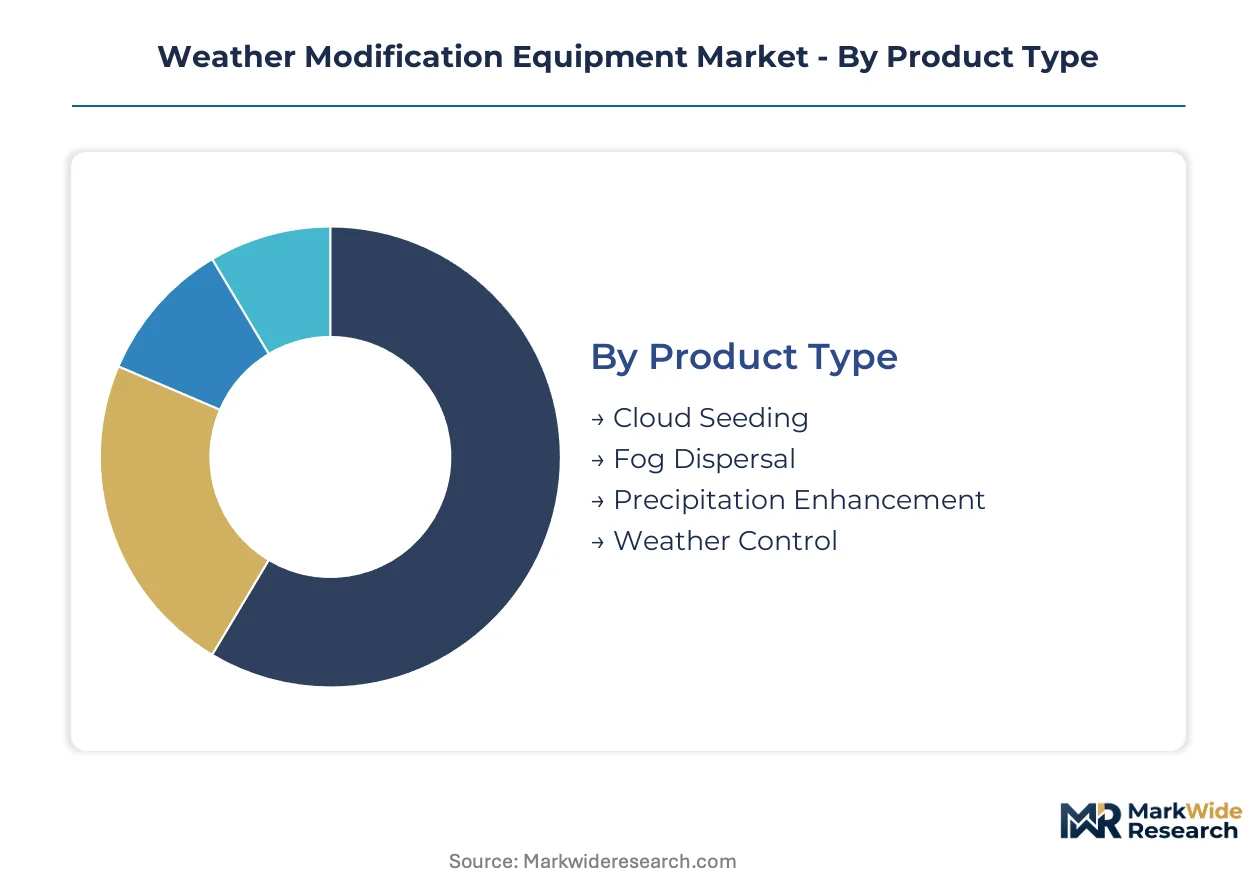
Equipment segmentation in weather modification reveals how regulatory pathways and operational constraints fragment procurement decisions across distinct technology platforms and institutional buyers. Understanding these divisions exposes where certification burdens concentrate and which customer types drive volume.
Product Type:
FAA Part 137 agricultural aircraft certifications apply primarily to cloud seeding and precipitation enhancement operations, while ground-based fog dispersal systems face lighter environmental review thresholds.
- Cloud Seeding:Established protocols using silver iodide or hygroscopic flares released at 4,000-12,000 meter altitudes. Demand concentrates in western United States state water districts funding recurring drought-response programs, constrained by EPA watershed deposition monitoring requirements.
- Precipitation Enhancement:Outcome-based contracting for freshwater augmentation in targeted catchment zones. State emergency declarations in Texas and New Mexico accelerate performance-based procurement, deepening margin pools through recurring drought-response frameworks.
- Fog Dispersal:Airport visibility restoration using thermal or hygroscopic methods.
- Weather Control:Hail suppression and storm modification for agricultural protection.
Leading the category by volume: Cloud Seeding. Expanding most quickly: Precipitation Enhancement.
Technology:
Cost tier separation runs steep between crew-intensive aircraft systems and autonomous alternatives, with capital recovery timelines stretching 3-7 years for manned platforms versus 18-24 months for drone deployments.
- Aircraft-Based:Manned platforms delivering superior coverage area per operation through wing-mounted or belly-mounted dispersal systems. Western United States water districts anchor procurement volume, though FAA Part 137 certification imposes multi-year approval timelines and specialized aircrew requirements.
- Drone Technology:Autonomous platforms integrating precision targeting with real-time atmospheric sensors. Colorado and Wyoming state water districts adopt these for alpine terrain penetration, compressing crew requirements and extending operational windows beyond daylight limitations.
- Ground-Based:Fixed or mobile generators for alpine catchment zones where aircraft access is operationally constrained.
- Rocket-Based:Artillery-launched nucleating agents for regional hail suppression programs.
Climbing the fastest: Drone Technology. Dominating current deployment value: Aircraft-Based.
Application:
Customer type determines procurement rhythm, with agricultural water districts moving on crop insurance cycles and government agencies responding to emergency declarations.
- Water Resource Management:Municipal and regional water district procurement for reservoir augmentation and aquifer recharge. Australia's Snowy Hydro model demonstrates government-backed infrastructure scale sustaining long-term contracting frameworks.
- Agriculture:Crop insurance-linked procurement channels emerging in irrigation-dependent regions, broadening addressable base beyond traditional municipal buyers.
- Disaster Relief:Emergency fog dispersal and flood mitigation deployments.
- Research:Atmospheric physics validation programs and nucleating agent efficacy studies.
Deepest contract tenure: Water Resource Management. Fastest procurement acceleration: Agriculture.
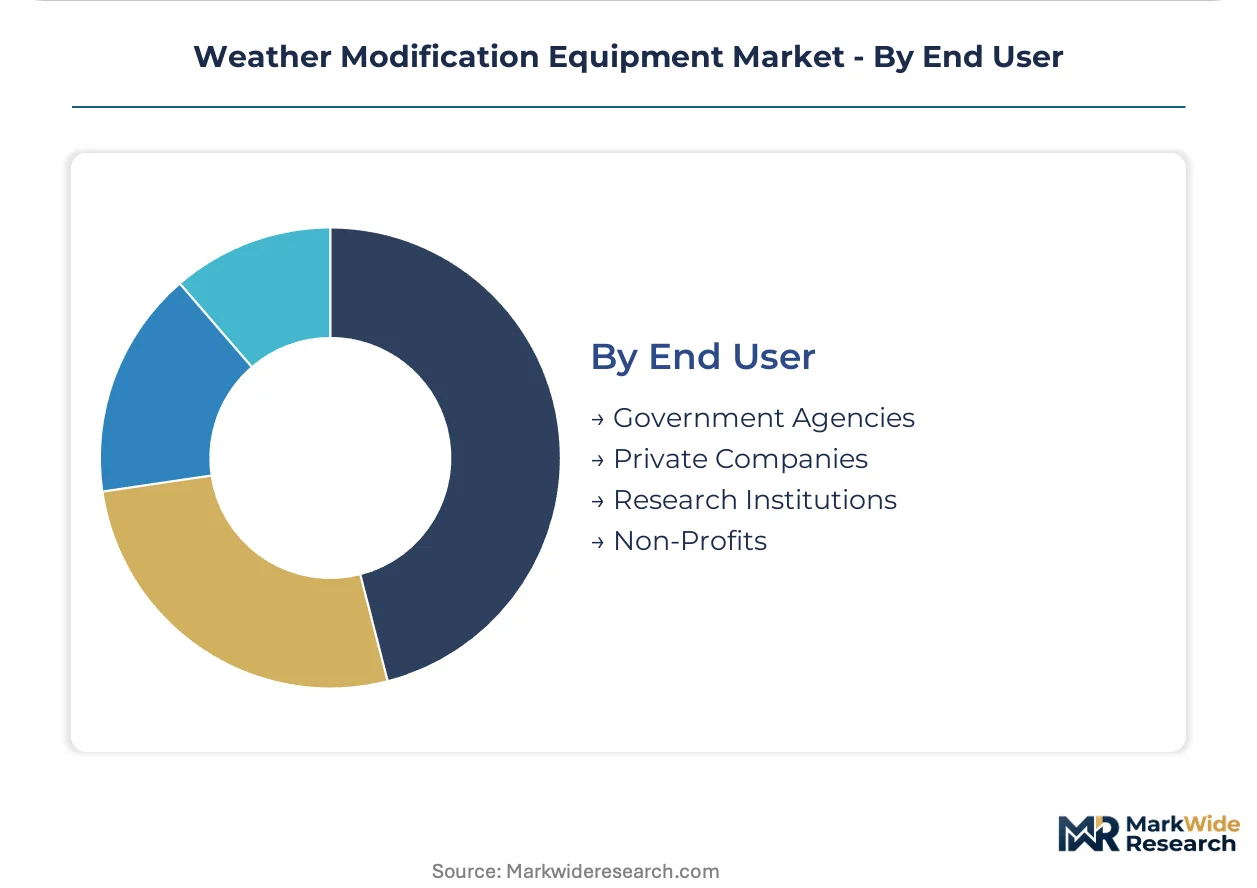
End User:
Volume concentration skews toward entities with sovereign borrowing capacity and multi-year budget visibility.
- Government Agencies:State water districts, national meteorological services, and drought response authorities. China's MEE dual carbon mandates accelerate state-funded seeding procurement under carbon-aligned water security frameworks.
- Private Companies:Agricultural conglomerates and insurance-linked service providers. Performance-based outcome contracting concentrates procurement risk with operators rather than capital buyers.
- Research Institutions:Universities and national laboratories conducting atmospheric physics validation.
- Non-Profits:Conservation organizations funding catchment-specific freshwater augmentation.
Anchor procurement volume: Government Agencies. Gaining share fastest: Private Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-designated water security zones in the western United States concentrate procurement authority for cloud seeding programs, while China's carbon-aligned special economic corridors accelerate state-funded atmospheric modification infrastructure.
United States
Colorado and Wyoming water districts deploy drone-based seeding platforms for alpine terrain penetration. FAA Part 137 agricultural aircraft certifications govern atmospheric release missions with multi-year approval timelines. The Intermountain West anchors operational flight program density, where state emergency declarations in Texas and New Mexico accelerate performance-based contracting adoption.
China
Provincial meteorological bureaus scale cloud seeding procurement under MEE dual carbon mandates linking water security to emissions reduction frameworks. The national environmental ministry enforces state-funded infrastructure deployment across drought-prone northern provinces. The Yangtze River Delta region concentrates ground-based generator manufacturing capacity for domestic alpine programs.
Australia
Snowy Hydro Limited sustains government-backed long-term contracting frameworks for catchment augmentation across the Snowy Mountains scheme. The Bureau of Meteorology coordinates state-level precipitation enhancement with federal infrastructure funding. New South Wales and Victoria anchor alpine water district procurement for reservoir recharge operations.
United Arab Emirates
The National Center of Meteorology operates one of the world's most active cloud seeding programs targeting arid climate water security. Federal research partnerships with atmospheric physics institutions accelerate drone technology adoption for precision targeting. Dubai and Abu Dhabi anchor operational command centers coordinating cross-emirate seeding missions.
Germany
REACH chemical registration requirements tighten nucleating agent environmental documentation standards for silver compound deposition. EASA operational restrictions constrain cross-border seeding missions and equipment mobility across Alpine catchments. Bavaria concentrates ground-based generator demand for terrain-constrained precipitation programs.
Weather Modification Equipment Market Competitive Landscape
Top-tier vendors anchor decades-long operational flight programs, while mid-tier specialists compete on alpine terrain penetration and autonomous platform integration. The vendor base stratifies across legacy manned aircraft operators, drone technology entrants, and ground-based generator fabricators. Three archetypes dominate: established flight program operators with regulatory certification depth, autonomous platform developers compressing crew economics, and alpine terrain specialists leveraging ground-based systems. Competitive moves concentrate on strategic partnerships with state water districts and technology licensing for unmanned aircraft convergence.
Among established flight program operators, Weather Modification International exemplifies the legacy certification archetype through decades of western United States operational density. Cloud Technologies GmbH occupies a position within the alpine terrain specialist tier, reflecting German engineering concentration in ground-based generator systems. Snowy Hydro Limited anchors the government-backed infrastructure model, representing long-term contracting frameworks replicable across drought-prone jurisdictions. These three entities collectively illustrate how regulatory depth, terrain specialization, and sovereign funding access structure competitive positioning.
| Leading Market Players |
|---|
| Snowy Hydro Limited |
| RHS Consulting |
| Weather Modification International |
| Cloud Technologies GmbH |
| Mettech S.p.A. |
| North American Weather Consultants |
| Meteo Systems |
| Seeding Operations & Atmospheric Research |
| Ice Crystal Engineering |
| Others |
Pricing and Supply Chain Analysis
Atmospheric physicist scarcity in the American West drives labor-cost differentials that widen pricing-tier spreads between legacy flight program operators and emerging autonomous platform providers.
Pricing Analysis
Short lead-time premiums apply to FAA Part 137-certified aircraft availability during drought emergency windows, while spot inventory of silver iodide flares trades at discounts during off-peak meteorological seasons. Three-tier pricing structure across premium certified-flight programs, standard equipment lease arrangements, and economy ground-based generator rentals separates tiers by crew specialization and regulatory documentation depth. Pricing pressure stems from drone technology entrants compressing crew economics in alpine terrain contracts. Agricultural water districts exhibit highest price sensitivity due to crop insurance cycle constraints, whereas government emergency procurement shows lowest sensitivity.
Supply Chain Analysis
Domestic-content mandates in China's MEE procurement frameworks are reshaping sourcing patterns for nucleating agent manufacturing toward Yangtze River Delta chemical processors. Silver iodide production concentrates in China, the United States, and Germany, with hygroscopic flare fabrication anchored in European REACH-compliant facilities. Raw material dependencies span silver nitrate feedstock, potassium iodide, and specialized pyrotechnic casings. Single-source vulnerability runs through limited silver iodide purification capacity. Distribution runs through state water district procurement offices and agricultural cooperative buying consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play. FAA certification timelines and atmospheric physicist scarcity are forcing weaker equipment vendors into distressed exits.
For Market Incumbents: Cement regulatory certification depth through accelerated FAA Part 137 renewal investments and captive training pipelines for flight program designers. Threat from drone technology entrants demands defensive patent positioning in precision targeting algorithms. Backward integration into silver iodide compound manufacturing secures input cost stability against chemical processing volatility. For New Entrants and Emerging Players: Launch via performance-based outcome contracting with Texas and New Mexico agricultural water districts facing recurring drought declarations. White-space targets include alpine terrain penetration in Colorado and Wyoming where crew risk limits incumbent aircraft deployment. Go-to-market angle centers on autonomous platform-as-a-service models separating equipment ownership from operational risk. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated specialists combining drone hardware fabrication with atmospheric physics expertise given unmanned aircraft regulatory convergence. Long-term viability framing favors entities with sovereign contract tenure exceeding five years. Acquisition target archetype: alpine terrain specialists with ground-based generator installed base. Signal to watch: EPA silver iodide deposition threshold tightening as inflection indicator for hygroscopic alternative demand.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Platform Certification | FAA Part 137 adaptation for unmanned aircraft unlocks alpine terrain penetration in Colorado. |
| Backward Integration into Nucleating Agents | In-house silver iodide production insulates margins from chemical processing concentration in China. |
| Performance-Based Contracting | Outcome-linked procurement with Texas water districts transfers operational risk from municipal buyers. |
| Alpine Terrain Specialization | Ground-based generator systems designed for Bavarian catchments address aircraft access constraints. |
| Regulatory Documentation Infrastructure | Continuous EPA watershed monitoring systems preempt silver deposition compliance friction. |
Research Methodology
Document review covered FAA certification databases, EPA environmental compliance filings, and state water district procurement records, complemented by interviews with cloud seeding program directors, atmospheric physicists, agricultural water district procurement officers, and unmanned aircraft systems engineers. Secondary validation drew from EASA operational safety directives, China's MEE policy frameworks, and Snowy Hydro Limited contract disclosures. Bottom-up equipment shipment estimates triangulated against top-down government funding appropriations.
Segmentation outputs across product type, technology platform, application, and end-user categories fed into analytical frameworks spanning the projection horizon. CAGRs derived from equipment deployment trajectories, regulatory approval velocity, and sovereign procurement cycle timing. Industry-specific forecast inputs included drought emergency declaration frequency and unmanned aircraft regulatory pathway maturation.
The model assumes a particular technology adoption path; alternative pathways for drone-based seeding platform certification would alter the outlook. Forecasts reflect assumptions around FAA regulatory adaptation timelines and silver iodide environmental threshold stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Real-Time Flood Monitoring and Warning System Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Global Environmental Remediation Market
Environmental Monitoring
Smart Water Monitoring Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market
Environmental Monitoring
Soil Remediation Technologies Market
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
Water Quality Analyzer Market
Environmental Monitoring
Environmental Radiation Monitor Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
South America Air Quality Monitoring Market
Environmental Monitoring
Cloud Seeding System Market
Environmental Monitoring
Environmental Technology Market
Environmental Monitoring
United States Erosion Sediment Control Market