
 Testing, Inspection, and Certification for Natural Resources Market | 2026-2036
Testing, Inspection, and Certification for Natural Resources Market Size, Share, and Industry Trends Forecast 2026-2036
Testing, Inspection, and Certification for Natural Resources Market Insights
Copper assay protocols is recalibrating lithium brine certification economics as battery-grade purity thresholds tighten. SGS SA leverages its Santiago laboratory network to anchor South American geochemistry workflows. Bureau Veritas competes through integrated mine-site inspection camps that reduce sample transit times. Intertek Group plc differentiates via digital chain-of-custody platforms that trace specimens from pit to certified report.
Testing, inspection, and certification for natural resources encompasses independent verification of physical properties, chemical composition, environmental impact, and regulatory compliance across extractive and cultivated commodities, typically employing atomic absorption spectroscopy, X-ray fluorescence, and inductively coupled plasma mass spectrometry to quantify elemental content with detection limits reaching parts per billion. The primary industrial purpose is risk mitigation for commodity traders, insurers, and end-manufacturers who require defensible documentation of quality, origin, and sustainability credentials before releasing payment or accepting delivery. Quality control services dominate revenue as miners and agribusinesses prioritize lot consistency and grade reconciliation against offtake agreements. Remote sensing is displacing manual survey methods in forestry and open-pit monitoring, compressing inspection timelines while expanding geographic coverage. Lab analysis retains premium pricing power where arbitration-grade precision is contractually mandated, particularly for conflict minerals and organic certification disputes.
The EU Green Deal and REACH frameworks now require documented supply chain due diligence for critical raw materials entering European processing facilities. EPA and FDA standards in the United States govern residual contaminant thresholds in agricultural exports and reclaimed mining waters. China's SAMR enforces GB standards for imported iron ore and coal quality declarations at port of entry. Stakeholders must monitor how divergent national accreditation regimes fragment mutual recognition agreements and multiply testing redundancy costs.
Market Dynamics
EU Green Deal due diligence mandates for critical raw materials are forcing third-party verification into binding contractual clauses across copper, lithium, and rare earth supply chains, compressing procurement timelines while elevating certification costs.
Growth Catalysts
- REACH and EU Green Deal compliance deadlines:European processors now require documented chain-of-custody for conflict minerals and battery metals, mandating independent assay verification before customs clearance.
- Lithium brine extraction expansion:Chilean and Argentine salares are commissioning dedicated on-site laboratories to meet battery-grade purity thresholds for cathode manufacturers.
- Remote sensing deployment:Forestry and open-pit operators are replacing manual survey crews with satellite-based biomass and topography monitoring, expanding inspectable acreage per analyst.
Market Restraints
- Accreditation fragmentation:Divergent national recognition regimes between ISO member bodies multiply redundant testing costs for cross-border shipments.
- Specialized consumables volatility:High-purity argon and certified reference materials for ICP-MS analysis face supply concentration from Ukrainian and Russian production facilities.
- Sample degradation windows:Remote mine sites in Western Australia and the Atacama exceed viable transit times for moisture-sensitive coal and lithium brine specimens.
Strategic Opportunities
- Indonesian nickel laterite verification:Emerging battery precursor plants require local geochemistry capacity that currently ships samples to Australian or Singaporean labs.
- Drone-based magnetic survey integration:Convergence of UAV platforms with quantum magnetometers enables rapid subsurface ore body delineation without ground crew deployment.
- China SAMR import declaration mandates:GB standard compliance for iron ore and coal quality at port of entry creates captive demand for pre-shipment inspection contracts.
Industry Challenges
- Geochemist talent scarcity:Universities are producing insufficient ICP-MS and XRF specialists to staff expanding mine-site laboratory networks.
- Legacy LIMS integration:Digital chain-of-custody platforms face interoperability friction with decades-old laboratory information management systems at established assay facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Testing, Inspection, and Certification for Natural Resources Market |
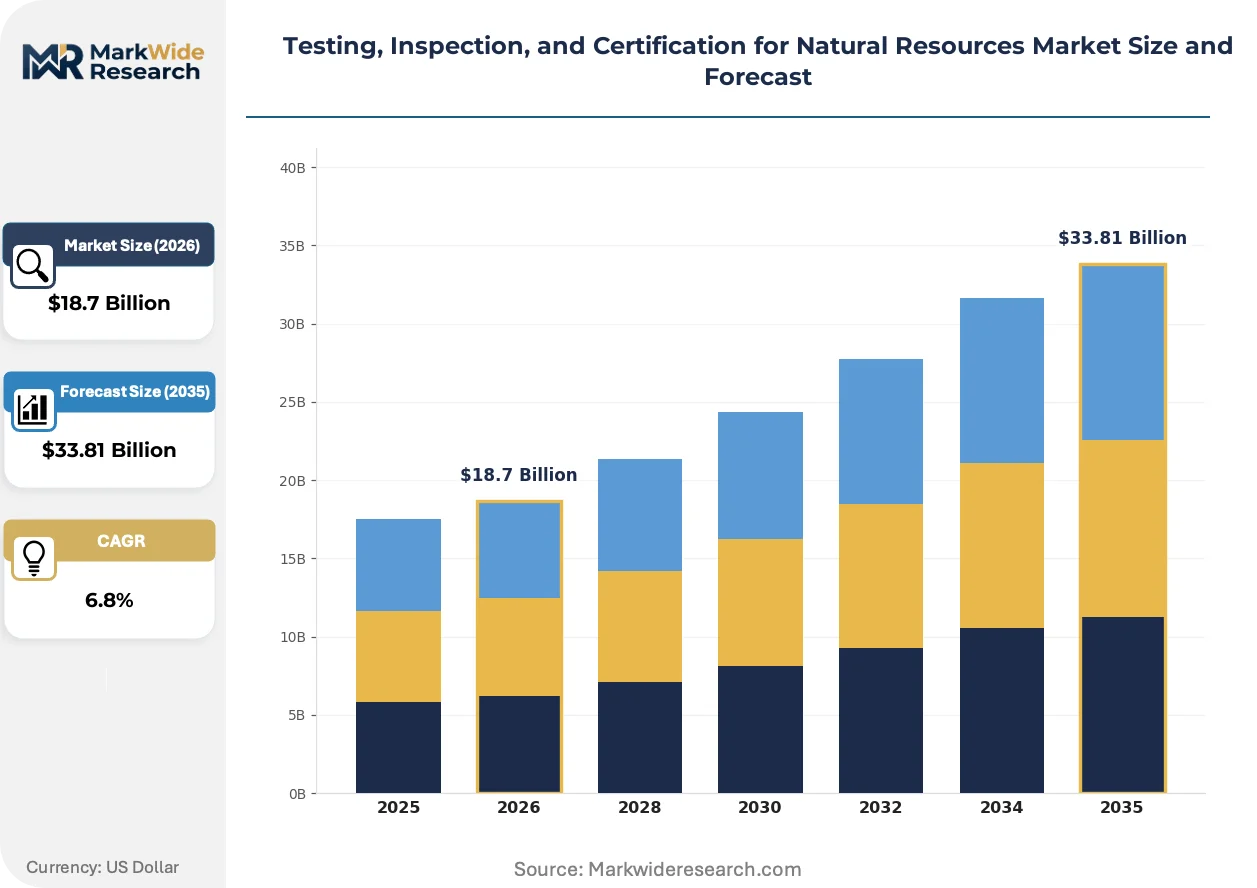
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quality Control, Environmental Testing, Compliance Verification, Safety Assessment Industry Vertical: Mining, Agriculture, Forestry, Oil & Gas Technology: Non-Destructive Testing, Remote Sensing, Lab Analysis, Field Testing Certification Type: ISO 14001, Certified Organic, LEED, CE Marking |
| Companies Covered | SGS SA, Bureau Veritas, Intertek Group plc, TÜV SÜD, TÜV Rheinland, DEKRA SE, DNV GL, Applus+, ALS Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Testing, Inspection, and Certification for Natural Resources Market Trends and Innovations
Portable and autonomous analytical technologies are collapsing the distance between extraction points and certification-grade data, while regulatory frameworks harden documentation requirements into enforceable supply chain conditions.
Containerized X-ray fluorescence units are modularizing field assay operations by embedding laboratory-grade precision within shipping-container footprints deployable to remote mine sites. Junior exploration companies in Canada's Athabasca Basin are leasing these units on campaign-based contracts rather than building permanent facilities. This architecture is modularizing capital deployment for tier-two miners who previously outsourced all analysis to urban hubs.
China's SAMR enforcement of GB standards for iron ore and coal quality declarations at port of entry is mandating pre-shipment inspection contracts with accredited third parties before vessel loading. Australian exporters to Chinese steel mills now face rejection risk for lots lacking documented compliance. The Pilbara-to-Qingdao route is experiencing the densest adoption of digital certificate transmission to accelerate customs processing.
Asian battery manufacturers are unbundling certification requirements from traditional trading house arrangements, contracting directly with SGS, Bureau Veritas, and Intertek for pit-to-plant lithium and cobalt verification. This disintermediation compresses the number of touchpoints where sample integrity risk accumulates. Korean cathode producers are driving the strictest purity thresholds, specifying sub-ppm detection limits for magnesium and calcium contaminants in Chilean lithium carbonate.
Testing, Inspection, and Certification for Natural Resources Market Segmentation
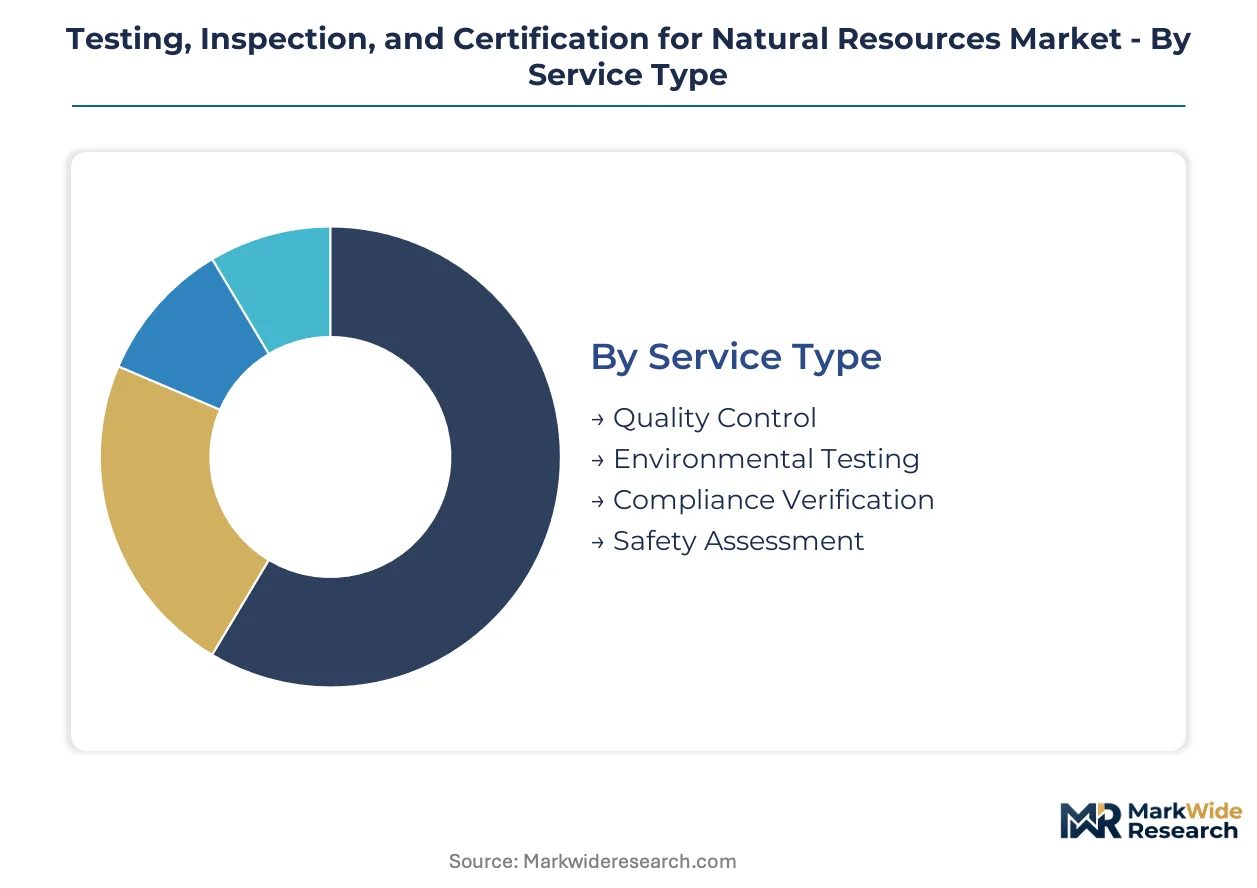
Testing, inspection, and certification for natural resources fragments across service modalities, extraction industries, analytical technologies, and accreditation frameworks. Each axis carries distinct margin profiles and regulatory tethering points that reshape vendor positioning.
Service Type:
Service modalities diverge by technical intensity, liability exposure, and contractual recurrence patterns.
- Quality Control:Lot consistency verification against offtake specifications employs atomic absorption spectroscopy and X-ray fluorescence for elemental quantification. Mining operators in Chile and Australia prioritize grade reconciliation services to prevent arbitration disputes with Asian smelters.
- Environmental Testing:Residual contaminant analysis in tailings water and reclaimed soils uses inductively coupled plasma mass spectrometry with parts-per-billion detection limits. EPA and MEE enforcement of discharge thresholds is elevating contract values for perpetual monitoring arrangements at copper and coal operations.
- Compliance Verification:Documented chain-of-custody for EU Green Deal due diligence mandates independent third-party attestation before customs clearance.
- Safety Assessment:Structural integrity evaluation of processing infrastructure and tailings dams reduces catastrophic failure liability for insurers.
Quality control leads on scale; environmental testing leads on momentum.
Industry Vertical:
Vertical concentration tracks commodity price volatility and jurisdictional regulatory intensity.
- Mining:Copper assay protocols and lithium brine certification dominate revenue as battery-grade purity thresholds tighten. Chilean and Peruvian operators are expanding third-party verification contracts to satisfy Korean cathode manufacturer specifications.
- Agriculture:Organic certification and pesticide residue testing for export markets employs chromatographic methods against EU and FDA maximum residue limits.
- Forestry:Biomass quantification and chain-of-custody documentation for sustainable sourcing claims.
- Oil & Gas:Hydrocarbon fingerprinting and pipeline integrity assessment for midstream infrastructure operators.
Mining anchors revenue concentration; agriculture shows steepest expansion trajectory from organic export mandates.
Technology:
Analytical deployment modes reshape capital requirements and geographic reach.
- Non-Destructive Testing:Ultrasonic and radiographic inspection of processing equipment preserves operational continuity while detecting fatigue cracks.
- Remote Sensing:Satellite-based biomass and topography monitoring compresses inspection timelines while expanding inspectable acreage per analyst.
- Lab Analysis:Arbitration-grade precision for conflict minerals and organic certification disputes retains premium pricing power where contractual mandates apply.
- Field Testing:Containerized X-ray fluorescence units modularize capital deployment for junior exploration companies in Canada's Athabasca Basin.
Lab analysis commands highest margins; remote sensing gains share fastest from forestry and open-pit adoption.
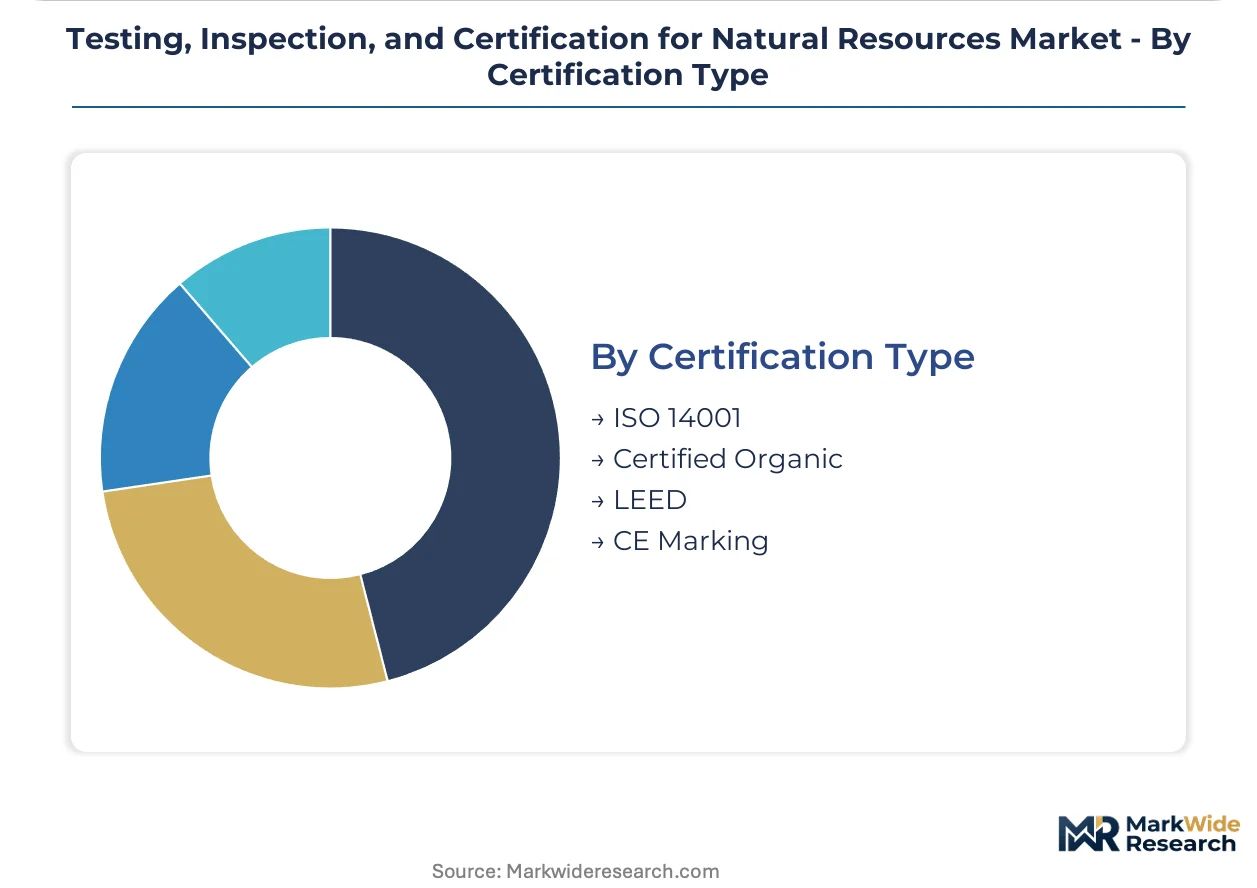
Certification Type:
Accreditation frameworks determine market access and customer procurement eligibility.
- ISO 14001:Environmental management system certification for mining and agribusiness operations seeking ESG-aligned capital.
- Certified Organic:Agricultural export qualification for EU and North American retail channels.
- LEED:Sustainable site development recognition for resource extraction infrastructure.
- CE Marking:European market access for processing equipment and analytical instrumentation.
ISO 14001 dominates contract volume; certified organic climbs fastest from Asian buyer ESG scrutiny.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara iron ore belt drives pre-shipment inspection contract density along Australia's northwest coast. Chilean lithium salares and Indonesian nickel laterite provinces concentrate laboratory network expansion investments.
Australia
Iron ore exporters to Chinese steel mills face mandatory GB standard compliance documentation before vessel loading. SAMR enforcement at Qingdao port creates inspection demand at Pilbara mine sites. Perth-based laboratory networks anchor geochemistry workflows for moisture-sensitive coal specimens.
Chile
Atacama Desert lithium brine operations commission dedicated on-site laboratories for battery-grade purity verification. Korean cathode manufacturers specify sub-ppm detection limits for magnesium and calcium contaminants. Santiago laboratory clusters anchor South American geochemistry capacity for copper assay protocols.
China
Iron ore and coal import declarations at port of entry require accredited third-party quality verification. GB standards enforcement creates captive demand for pre-shipment inspection contracts. Yangtze River Delta processing facilities face EU Green Deal due diligence documentation requirements for critical raw materials.
Indonesia
Nickel laterite extraction for battery precursor plants requires local geochemistry capacity expansion. Current sample flows to Australian or Singaporean laboratories create transit time vulnerabilities. Sulawesi and Halmahera mining concessions drive demand for modular containerized assay units.
Peru
Copper concentrate exporters expand third-party verification contracts to satisfy Asian smelter specifications. Mine-site inspection camps reduce sample degradation risks for remote Andean operations. Lima-based laboratory networks coordinate with Santiago hubs for arbitration-grade precision documentation.
Testing, Inspection, and Certification for Natural Resources Market Competitive Landscape
Global majors compete with regional champions across laboratory network density and mine-site proximity. The vendor base concentrates around three strategic tiers: integrated multinationals with Santiago-to-Singapore coverage, specialized geochemistry firms anchored in mining provinces, and modular field-service operators leasing containerized equipment. Consolidation pressure intensifies as tier-two miners seek campaign-based contracts rather than permanent facility investments. Capacity expansion and digital chain-of-custody platform deployment represent dominant competitive moves.
Within the integrated multinational tier, SGS SA, Bureau Veritas, and Intertek Group plc occupy positions defined by geographic network architecture rather than technology differentiation. SGS SA exemplifies the South American-anchored archetype through its Santiago laboratory density. Bureau Veritas represents the mine-site proximity strategy with inspection camp deployments. Intertek Group plc sits within the digital traceability vector through chain-of-custody platform investments. These three entities collectively illustrate how certification-grade precision, reduced sample transit times, and documented custody trails constitute distinct competitive positioning axes rather than overlapping capabilities.
| Leading Market Players |
|---|
| SGS SA |
| Bureau Veritas |
| Intertek Group plc |
| TÜV SÜD |
| TÜV Rheinland |
| DEKRA SE |
| DNV GL |
| Applus+ |
| ALS Limited |
| Others |
Pricing and Supply Chain Analysis
LME copper price volatility cascades through assay service tiers, compressing margins on routine grade verification while amplifying premiums for arbitration-grade precision demanded by Korean cathode manufacturers and EU Green Deal compliance documentation.
Pricing Analysis
Input-cost pass-through from high-purity argon and certified reference materials anchors pricing stratification across premium, standard, and economy service tiers. Price differentiation hinges on detection limit thresholds and ISO 17025 accreditation status, with battery-grade lithium certification commanding substantial premiums over base metals assay. Pricing pressure stems from containerized XRF unit leasing models that undercut permanent laboratory economics. Junior exploration companies exhibit highest price sensitivity; integrated miners with offtake arbitration exposure show lowest.
Supply Chain Analysis
Specialized consumables supply rests on Ukrainian and Russian production facilities for high-purity gases and certified reference materials, creating single-source vulnerability amplified by geopolitical disruption. Chile, Australia, and Indonesia concentrate laboratory network expansion investments for copper, iron ore, and nickel laterite verification respectively. Logistics chokepoints emerge at Pilbara-to-Qingdao and Atacama-to-Busan shipping corridors where sample degradation windows compress viable transit times. Distribution runs through accredited third-party networks rather than direct mine-to-manufacturer arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory documentation hardens from voluntary standard into binding contractual clause across critical raw material supply chains.
For Market Incumbents: Anticipate margin compression from modular containerized assay units by embedding digital chain-of-custody platforms into long-term offtake agreements. Counter geochemist talent scarcity through Santiago-to-Singapore laboratory network automation. Prioritize EU Green Deal due diligence certification investment over commodity-grade volume expansion. For New Entrants and Emerging Players: Launch via campaign-based containerized XRF leasing to tier-two miners in Canada's Athabasca Basin and Indonesian nickel laterite provinces. Target Indonesian geochemistry capacity gaps where current sample flows to Australian laboratories create transit vulnerability. Differentiate through drone-based magnetic survey integration for rapid ore body delineation without ground crew deployment. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized geochemistry firms possessing mine-site proximity in Chilean lithium salares and Peruvian copper belts. Five-to-ten year viability favors accreditation-dense operators with ISO 17025 scope expansion capability. Watch EU Green Deal enforcement consistency as inflection indicator for compliance verification contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Containerized Laboratory Deployment | Modular XRF units reduce capital barriers for junior miners in remote basins. |
| Digital Chain-of-Custody Platform Investment | Intertek-style specimen traceability satisfies EU Green Deal documentation mandates. |
| Mine-Site Inspection Camp Expansion | Bureau Veritas proximity strategy cuts sample degradation risks in Atacama operations. |
| Geochemist Talent Pipeline Development | ICP-MS specialist scarcity threatens laboratory network scaling across South America. |
| Accreditation Scope Expansion | ISO 17025 coverage for battery-grade lithium purity unlocks Korean cathode manufacturer contracts. |
Research Methodology
Multiple input streams — primary interviews with laboratory operations directors, mine-site geologists, and cathode manufacturer procurement leads; secondary validation through SAMR GB standard filings, EU Green Deal compliance documentation, and customs trade data; plus SEC disclosures from listed service providers — were reconciled through bottom-up and top-down triangulation.
Historical contract value trajectories were cross-referenced against panel input from certification body executives to model growth across service type, industry vertical, technology deployment mode, and accreditation framework dimensions. CAGRs were derived from segmented volume and pricing assumptions, with particular weighting applied to lithium brine extraction expansion rates and REACH enforcement timelines.
Several conditions sit outside the modeled scope, including abrupt accreditation regime fragmentation, argon supply disruption severity, and autonomous analytical technology substitution velocity. Forecasts reflect stated assumptions about regulatory enforcement consistency and commodity price stability. A small set of named triggers — EU due diligence deadline acceleration, SAMR inspection mandate expansion, and ICP-MS consumables supply concentration — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Europe Air Quality Monitoring Market
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
Global Water Quality Monitoring Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Soil Remediation Technologies Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Water Quality Analyzer Market
Environmental Monitoring
Weather Modification Equipment Market
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
Environmental Monitoring (Surface Water) Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Water Pipeline Leak Detection System Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
LAMEA Emission Monitoring System Market