
 Global Oil Spill Management Market | 2026-2036
Global Oil Spill Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oil Spill Management Market Foresight
The divergence between premium integrated response services and commodity equipment leasing is hardening as coastal authorities demand guaranteed response-time contracts while petrochemical buyers prioritize cost-per-barrel containment metrics. BP plc leverages its in-house Oil Spill Response Limited subsidiary to sustain vertically controlled emergency coverage across North Sea and Gulf of Mexico assets. Clean Harbors, Inc. anchors its position through hazardous waste infrastructure that extends into post-spill soil remediation, while Elastec, Inc. differentiates via American-manufactured skimmer systems that dominate municipal harbor procurement.
Oil spill management encompasses the coordinated detection, containment, recovery, and disposal of petroleum discharges into marine or terrestrial environments, employing booms with draft specifications typically ranging from 18 to 48 inches, weir skimmers rated for viscosity gradients between 2 and 2,000 centistokes, and dispersant application systems calibrated to droplet spectra of 400–700 microns for optimal oil-water contact. Mechanical Recovery commands the largest installed base due to regulatory preference for physical removal over chemical intervention, while Bioremediation represents the fastest-expanding technique category as genetically enhanced microbial consortia demonstrate efficacy in low-temperature Arctic conditions where mechanical access proves impractical. The Spill Source dimension shows Pipeline Ruptures generating the most predictable maintenance-driven demand, whereas Offshore Platforms concentrate the highest-margin emergency response contracts due to remote-access premiums and stricter operator liability under post-Deepwater Horizon frameworks.
The U.S. Coast Guard enforces Facility Response Plan mandates under OPA 90 that shape equipment stockpiling requirements and contractor pre-qualification standards for marine facilities, while the EPA's National Contingency Plan governs inland spill notification thresholds and approved dispersant product lists. The EU's Environmental Liability Directive and REACH chemical registration requirements constrain dispersant formulation choices in European waters, creating dual-track product development obligations for multinational service providers. Stakeholders must monitor how autonomous aerial surveillance platforms and satellite-based synthetic aperture radar detection reshape the economics of early-stage response activation versus traditional manned patrol models.
Market Dynamics
Autonomous detection and recovery systems are compressing response activation timelines while coastal authorities demand guaranteed arrival contracts that lock in pre-positioned equipment and trained crews.
Growth Catalysts
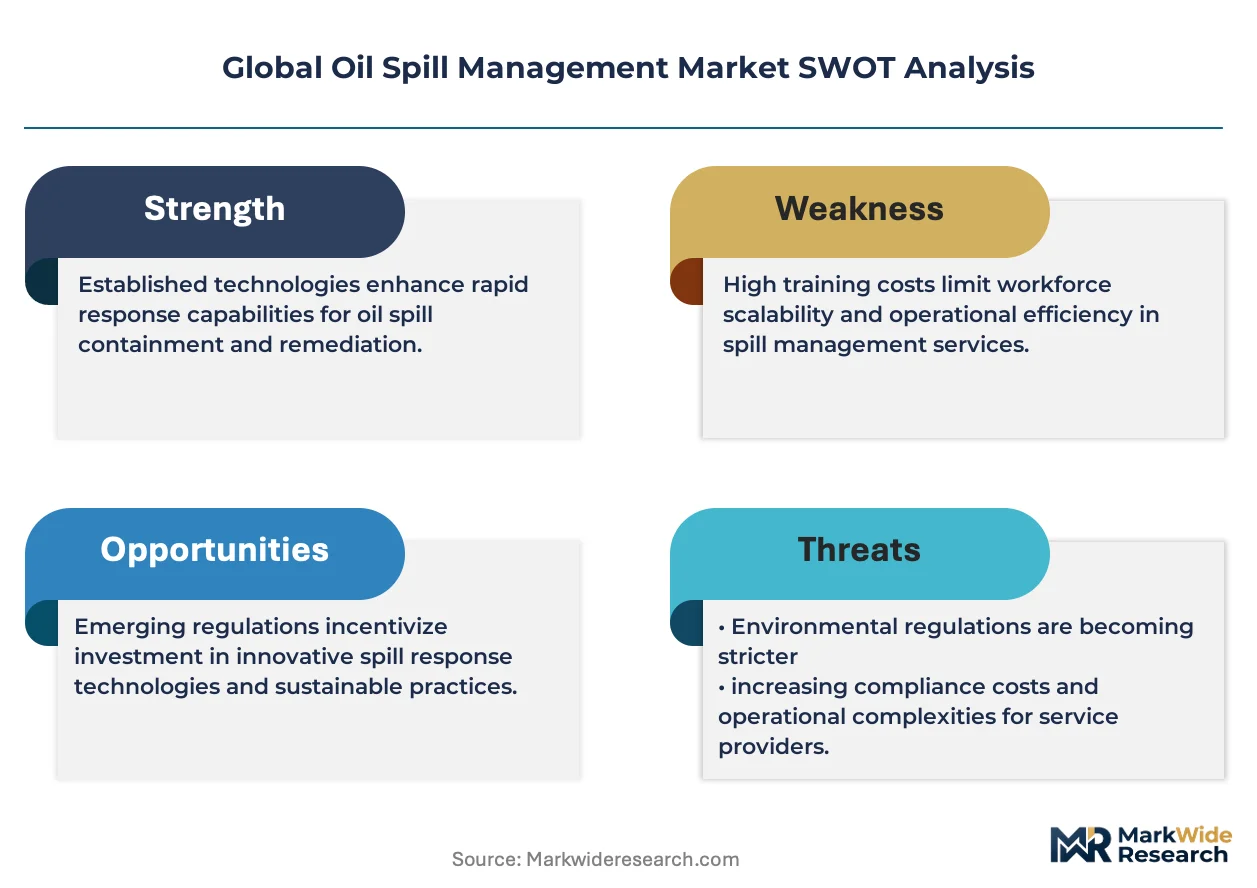
- Post-Deepwater Horizon liability frameworks:The U.S. Coast Guard's updated Facility Response Plan mandates under OPA 90 compel marine terminal operators to maintain certified contractor relationships and minimum equipment stockpiles.
- Deepwater exploration in the Gulf of Mexico:Ultra-deep drilling activity generates recurring demand for high-capacity mechanical recovery systems and helicopter-deployable dispersant platforms.
- Genetically enhanced microbial consortia:Bioremediation advances enable effective hydrocarbon degradation in Arctic temperatures where mechanical access remains impractical.
Market Restraints
- Specialized polymer supply concentration:Boom and skimmer manufacturers depend on narrow sources of oil-resistant elastomers subject to petrochemical feedstock volatility.
- Dispersant formulation constraints:ECHA's REACH registration requirements and the EU's Environmental Liability Directive block certain chemical compositions from European waters.
- Arctic mechanical limitations:Ice cover and extreme cold render conventional weir skimmers and boom systems inoperable for substantial portions of the year.
Strategic Opportunities
- Brazilian pre-salt basin expansion:ANVISA and environmental licensing processes for offshore platforms create demand for integrated response services with local content requirements.
- Satellite-based synthetic aperture radar:Integration with autonomous aerial surveillance platforms enables detection of sub-surface slicks before visual confirmation.
- Post-spill soil remediation bundling:Hazardous waste infrastructure operators can extend service contracts from marine containment into terrestrial cleanup and long-term site monitoring.
Industry Challenges
- Certified response technician shortages:The specialized training required for offshore dispersant application and high-seas boom deployment outpaces vocational program output in key producing regions.
- Legacy vessel integration:New autonomous skimmer systems require retrofit compatibility with existing supply boats and work vessels, complicating fleet modernization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oil Spill Management Market |
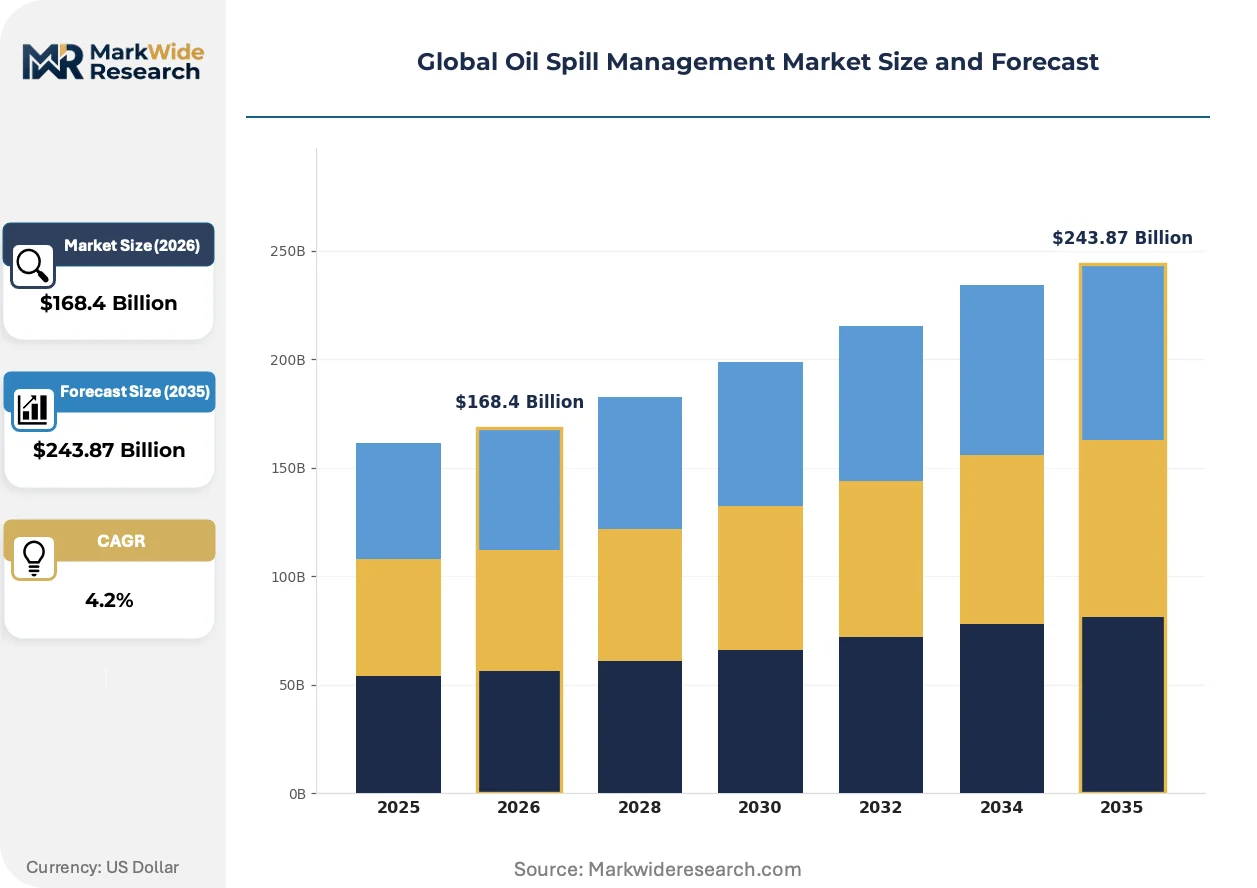
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $243.87 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Response Technique: Mechanical Recovery, Chemical Dispersants, Bioremediation, In-situ Burning Service Provider: Consultants, Remediation Contractors, Environmental Engineers, Emergency Response Teams Spill Source: Pipeline Ruptures, Offshore Platforms, Tanker Accidents, Storage Facility Leaks End User Industry: Petrochemical Plants, Maritime Operations, Coastal Authorities, Waste Management Entities |
| Companies Covered | Exxon Mobil Corporation, BP plc, Chevron Corporation, TotalEnergies SE, Lamor Corporation, Clean Harbors, Inc., Oil Spill Response Limited, Elastec, Inc., NRC Group Holdings Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oil Spill Management Market Shifts & Advancements
Detection and recovery technologies are converging with real-time data analytics to shift spill response from reactive mobilization toward predictive positioning of assets before discharge events occur.
Autonomous skimmer drone swarms are rewriting the economics of early-stage containment by enabling continuous mechanical recovery without crewed vessel exposure. Offshore platform operators in the Gulf of Mexico are piloting these systems for sub-24-hour response guarantees. The technology is compressing the window between detection and first oil recovery from days to hours.
REACH chemical registration requirements in Europe are forcing dual-track product development for dispersant manufacturers. Formulations approved under EPA's National Contingency Plan face reformulation barriers for ECHA compliance. Service providers with multinational contracts must maintain separate inventory and application protocols for Atlantic versus European operations.
Guaranteed response-time contracts are displacing traditional equipment-leasing arrangements in coastal authority procurement. Municipal harbor managers in Norway, Singapore, and Australia now specify maximum arrival windows rather than equipment specifications. Petrochemical buyers counter with cost-per-barrel containment metrics that favor scalable, modular recovery systems over fixed infrastructure commitments.
Global Oil Spill Management Market Segmentation
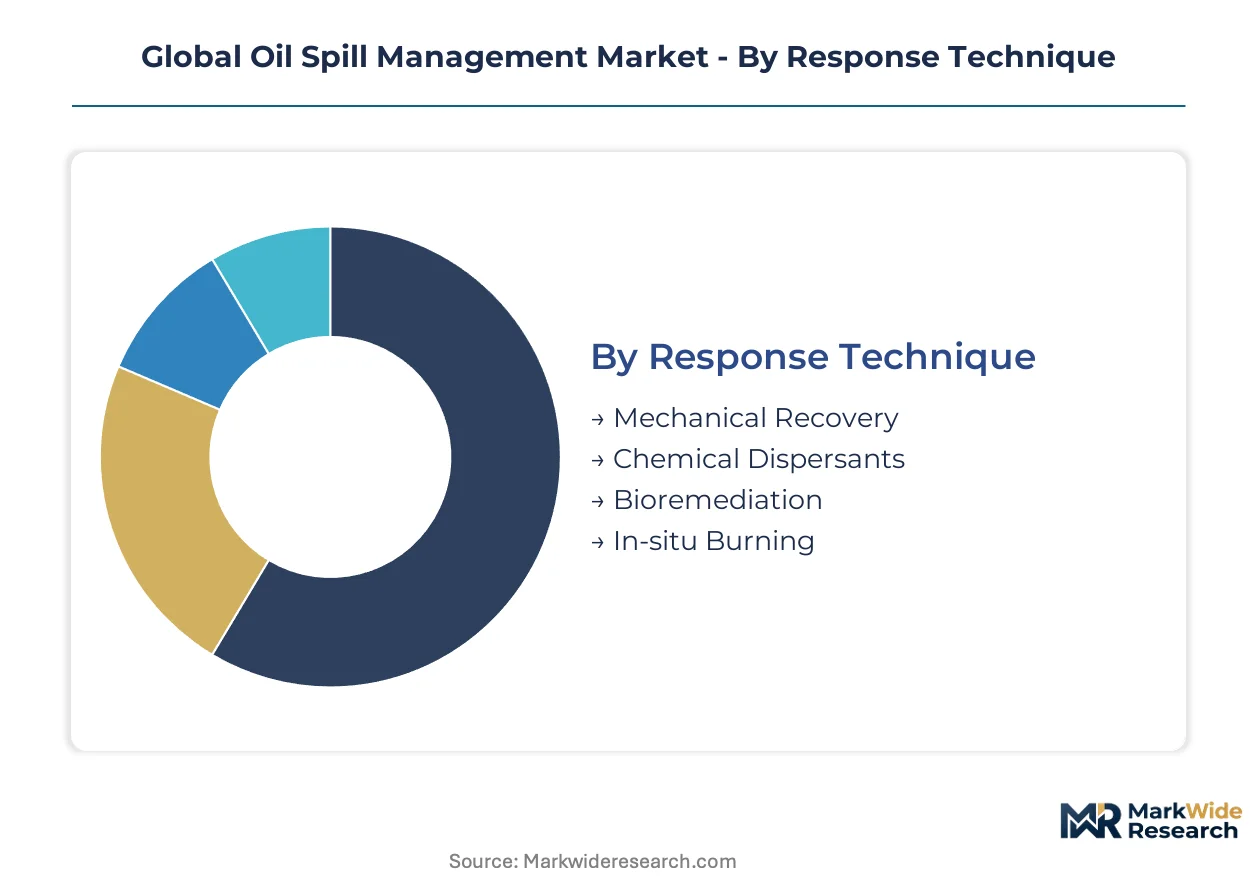
Oil spill management procurement splits sharply between integrated service bundles and discrete equipment procurement, with regulatory frameworks dictating which buyers favor vertical integration versus modular sourcing. Understanding these segment boundaries clarifies where technology vendors compete on specification compliance versus where service providers win on response-time guarantees.
Response Technique:
Standalone deployment dominates mechanical and chemical systems, while bioremediation and burning protocols embed within broader remediation workflows.
- Mechanical Recovery:Booms, skimmers, and vacuum systems physically remove petroleum from water surfaces. Gulf of Mexico operators maintain the densest equipment stockpiles under U.S. Coast Guard Facility Response Plan mandates.
- Chemical Dispersants:Surfactant formulations break oil slicks into droplets for microbial degradation. REACH registration barriers force dual-track inventory for Atlantic versus European operations.
- Bioremediation:Genetically enhanced microbial consortia degrade hydrocarbons in temperature-stressed environments.
- In-situ Burning:Controlled ignition eliminates thick slicks when weather windows permit safe combustion.
Volume placements concentrate in Mechanical Recovery; the faster expansion belongs to Bioremediation.
Service Provider:
Cost stratification separates premium guaranteed-response contracts from commodity technical consulting.
- Consultants:Risk assessment and contingency planning for pre-incident compliance. Norwegian and Singapore harbor authorities now specify maximum arrival windows rather than advisory scopes.
- Remediation Contractors: Field execution of containment and cleanup operations. Brazil's ANVISA licensing creates local-content requirements that favor established regional operators.
- Environmental Engineers:Post-spill site characterization and long-term monitoring protocol design.
- Emergency Response Teams:Pre-positioned crews with certified technician credentials for offshore dispersant application.
Revenue pools concentrate in Remediation Contractors; Emergency Response Teams are climbing the fastest.
Spill Source:
Geographic remoteness and liability exposure create divergent margin profiles across incident types.
- Pipeline Ruptures:Terrestrial and subsea conduit failures generate predictable maintenance-driven demand. EPA National Contingency Plan notification thresholds shape equipment staging requirements across U.S. pipeline corridors.
- Offshore Platforms:Remote-access premiums and stricter post-Deepwater Horizon liability concentrate the highest-margin emergency contracts. Helicopter-deployable dispersant platforms command premium pricing in ultra-deep Gulf of Mexico fields.
- Tanker Accidents:Vessel-grounding incidents trigger international compensation fund activation.
- Storage Facility Leaks:Terminal and refinery tank failures drive soil remediation bundling opportunities.
Contract value concentrates in Offshore Platforms; Storage Facility Leaks show steepest expansion trajectory.
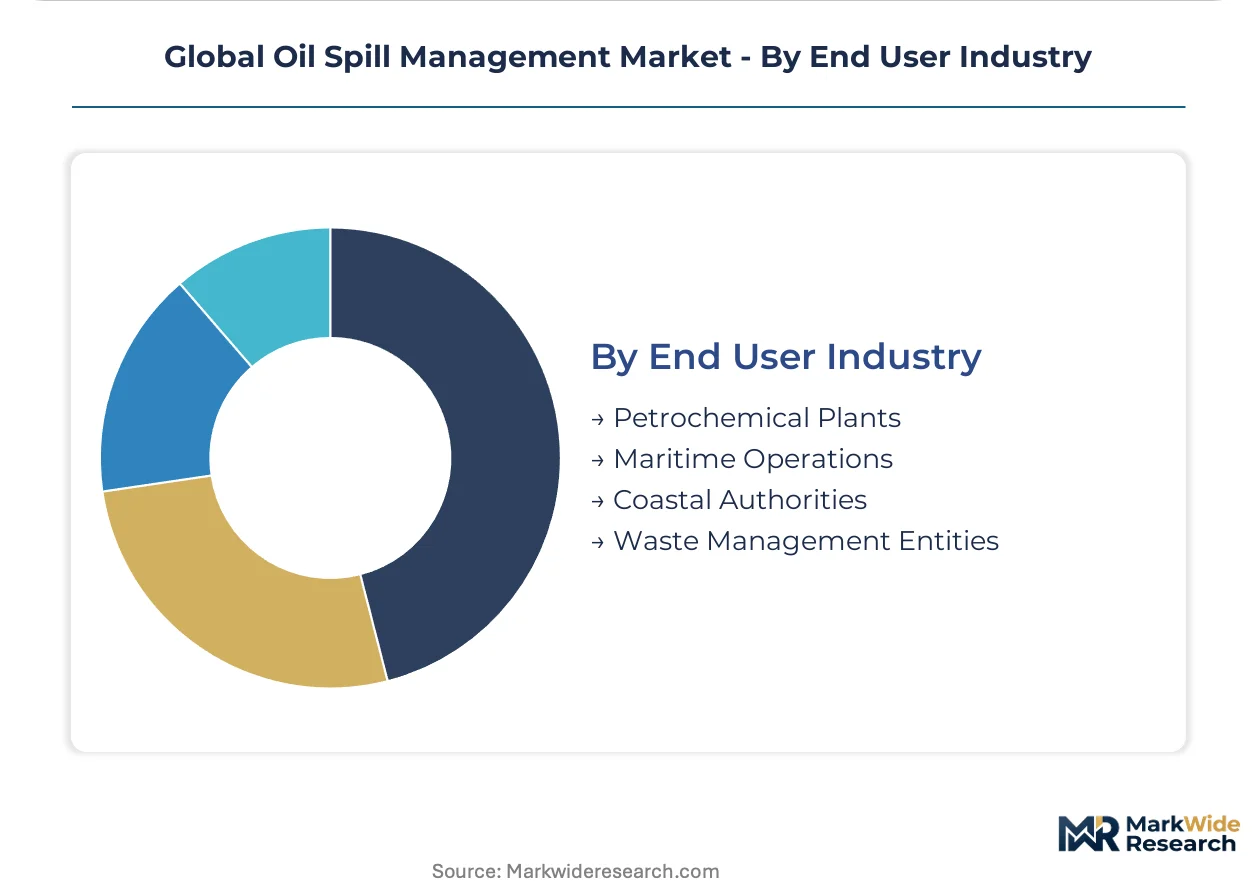
End User Industry:
Buyer sophistication separates specification-driven petrochemical procurement from outcome-based municipal contracting.
- Petrochemical Plants:Vertically integrated operators like BP plc sustain captive response subsidiaries for North Sea and Gulf of Mexico assets. Cost-per-barrel containment metrics favor scalable modular systems over fixed infrastructure.
- Maritime Operations:Terminal operators and vessel managers face OPA 90 equipment stockpiling mandates. Australian port authorities specify autonomous aerial surveillance integration for early detection.
- Coastal Authorities:Municipal harbor managers in Norway and Singapore prioritize guaranteed arrival contracts over equipment ownership.
- Waste Management Entities:Hazardous waste infrastructure operators extend from marine containment into terrestrial cleanup and long-term site monitoring.
Procurement volume concentrates in Maritime Operations; Waste Management Entities are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the densest concentration of oil spill response infrastructure, with the Gulf of Mexico basin driving equipment procurement volumes that exceed any other single metropolitan cluster worldwide.
United States
Ultra-deepwater drilling in the Gulf of Mexico sustains demand for helicopter-deployable dispersant platforms and high-capacity mechanical recovery systems. The U.S. Coast Guard's updated Facility Response Plan mandates under OPA 90 compel marine terminal operators to maintain certified contractor relationships and minimum equipment stockpiles. Houston hosts the largest concentration of response service headquarters, with operators maintaining dedicated staging yards along the Texas and Louisiana coastlines.
Brazil
Pre-salt basin expansion generates demand for integrated response services with stringent local content requirements. ANVISA and environmental licensing processes for offshore platforms create procurement barriers that favor established regional operators. Rio de Janeiro serves as the operational hub, with service providers positioning equipment to meet helicopter-range coverage requirements across the Santos Basin.
Norway
Arctic exploration activity and harsh weather preparedness drive investment in bioremediation and low-temperature mechanical systems. Municipal harbor managers specify maximum arrival windows rather than equipment specifications, favoring guaranteed response-time contracts. Stavanger and Bergen cluster specialized response vessel operators and microbial consortium suppliers for North Sea and Barents Sea coverage.
Singapore
Strait of Malacca tanker traffic and regional bunkering operations sustain demand for rapid-response harbor protection systems. Port authorities mandate autonomous aerial surveillance integration for early detection protocols. The Jurong industrial zone concentrates equipment maintenance facilities serving Southeast Asian offshore markets.
Australia
Northwest Shelf LNG exports and cyclone-season preparedness drive recurring investment in mechanical recovery stockpiles. State maritime safety agencies specify equipment certification standards that exceed baseline international conventions. Perth anchors the primary response coordination center for offshore platform coverage across the Timor Sea.
Global Oil Spill Management Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the oil spill management value chain, with equipment manufacturers maintaining foundry-like fabrication facilities while response service specialists operate without fixed asset ownership. The market exhibits moderate consolidation at the premium tier, where integrated operators bundle detection, containment, and disposal capabilities under single-contract structures. Three archetypes dominate: vertically integrated energy majors with captive response subsidiaries, specialized hazardous waste contractors extending into marine services, and dedicated equipment fabricators focused on skimmer and boom manufacturing. Competitive dynamics center on strategic partnerships for geographic expansion and portfolio diversification into adjacent environmental remediation services.
Among energy-major service operators, BP plc and Oil Spill Response Limited occupy positions exemplifying captive vertical integration, while Clean Harbors, Inc. represents the hazardous waste infrastructure archetype extending from terrestrial cleanup into marine containment. Elastec, Inc. anchors the specialized equipment fabrication tier.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| BP plc |
| Chevron Corporation |
| TotalEnergies SE |
| Lamor Corporation |
| Clean Harbors, Inc. |
| Oil Spill Response Limited |
| Elastec, Inc. |
| NRC Group Holdings Corp. |
| Others |
Supply & Pricing Matrix
Sovereign-backed response contractors and family-owned equipment fabricators anchor supply-side discipline across the oil spill management value chain, with U.S. Coast Guard certification requirements and Brazilian local-content mandates creating pricing power for pre-qualified operators while compressing margins for commodity equipment lessors.
Pricing Analysis
Outcome-based pricing tied to guaranteed response-time contracts dominates premium procurement, with municipal harbor authorities in Norway and Singapore specifying maximum arrival windows rather than equipment specifications. Price differentiation rests on U.S. Coast Guard certification tier and helicopter-deployable capability, with offshore platform operators showing least price sensitivity due to post-Deepwater Horizon liability exposure. Cost compression in mechanical recovery equipment is intensifying because petrochemical buyers prioritize cost-per-barrel containment metrics over fixed infrastructure commitments.
Supply Chain Analysis
Skilled technician shortages in Louisiana, Texas, and Stavanger constrain manufacturing throughput for specialized boom and skimmer systems. Production draws from oil-resistant elastomer feedstocks, precision-machined weir components, and helicopter-lift certified dispersant platforms. Single-source vulnerability in specialized polymer supply creates disruption risk. Distribution runs through certified response contractor networks and direct municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where certified response technician shortages prop pricing for guaranteed-arrival contracts above commodity equipment leasing rates.
For Market Incumbents: Deploy backward integration into microbial consortium cultivation to capture bioremediation growth while securing Arctic-capable service lines. Lock in exclusive elastomer supply agreements to defend against feedstock volatility threatening boom and skimmer margins. Counter autonomous drone entrants by bundling legacy vessel retrofit compatibility into long-term facility response plans. For New Entrants and Emerging Players: The premium-to-economy price gap in mechanical recovery equipment opens entry paths through modular, scalable skimmer systems targeting mid-size petrochemical buyers. Target Brazilian pre-salt basin local-content requirements where ANVISA licensing creates procurement barriers favoring new regional partnerships. Lead with drone-deployable dispersant platforms as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor hazardous waste infrastructure operators with terrestrial-to-marine extension capability in Gulf Coast and North Sea geographies. Long-term viability hinges on regulatory compliance depth rather than equipment manufacturing scale. Watch autonomous aerial surveillance platform adoption rates as the inflection signal for traditional manned response model displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Technician Training Program Expansion | Addresses U.S. Coast Guard credential shortages constraining response capacity activation. |
| Autonomous Skimmer Drone Fleet Deployment | Compresses detection-to-recovery timelines for Gulf of Mexico ultra-deepwater operators. |
| Dual-Track Dispersant Formulation Development | Enables EPA and ECHA compliance without inventory duplication across Atlantic operations. |
| Soil Remediation Service Bundling | Extends hazardous waste infrastructure from marine containment into terrestrial cleanup contracts. |
| Brazilian Local Content Partnership | Satisfies ANVISA licensing requirements for pre-salt basin integrated response services. |
Research Methodology
Regulatory filings, trade customs data, and equipment certification databases formed the secondary backbone, supplemented by primary interviews with U.S. Coast Guard response planners, offshore platform operations managers, municipal harbor procurement officers, and hazardous waste remediation contractors. Bottom-up and top-down triangulation validated segment-level estimates against aggregate market sizing.
Bottom-up modeling built from individual country equipment stockpile mandates and contractor certification counts, while top-down analysis cross-checked against energy major disclosed contingency spending and coastal authority budget allocations. Segmentation dimensions included response technique, service provider type, spill source, and end-user industry across the projection horizon. CAGRs derived from equipment refresh cycle analysis and regulatory mandate implementation timelines, with autonomous technology adoption curves and bioremediation efficacy data informing technique-level growth differentials.
Inputs from EPA National Contingency Plan records and ECHA REACH registration databases were available through the study window; gaps in proprietary contractor pricing data introduce uncertainty bands around service revenue estimates. Forecasts reflect assumptions about regulatory enforcement continuity and deepwater exploration permit issuance rates. Material deviation in OPA 90 mandate stringency or Brazilian environmental licensing velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Vietnam Waste Management Market
Waste Management & Pollution Control
Industrial Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Qatar Solid Waste Management Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
US Municipal Solid Waste Management Market
Waste Management & Pollution Control
India Municipal Solid Waste Management Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
Construction and Demolition Waste Management Market
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
Europe Plastic Waste Management Market