
 Global High End Greenhouse Market | 2026-2036
Global High End Greenhouse Market Size, Share, and Industry Trends Forecast 2026-2036
Global High End Greenhouse Market Analysis
CE marking under the EU Construction Products Regulation is redrawing competitive boundaries for greenhouse structural suppliers. Certhon leverages its Dutch engineering heritage to dominate turnkey glasshouse projects across Europe. Priva sustains technology leadership through climate control software integration. Rough Brothers Inc. anchors North American market presence with aluminum gutter-connected designs.
High end greenhouses are engineered enclosed agricultural structures employing climate-controlled environments with specified light transmission above 90 percent and thermal screens achieving U-values below 2.5 W per square meter Kelvin, designed to optimize crop yield per hectare across non-native growing seasons. Glasshouses command premium positioning in the product type category due to longevity and optical clarity advantages over polycarbonate alternatives. Automated nutrient delivery represents the fastest-expanding technology segment as growers pursue labor reduction and precision dosing consistency. Commercial growers constitute the dominant end user category, absorbing systems at scale for tomato, cucumber, and pepper production.
The EU Green Deal and F-Gas Regulation constrain hydrofluorocarbon-based climate systems, redirecting investment toward CO2 heat pumps and geothermal exchange. EPA agricultural emission guidelines in the United States shape ventilation and energy recovery specifications for imported Dutch systems. Stakeholders must monitor evolving carbon border adjustment mechanisms and their impact on cross-border greenhouse component trade flows.
Market Dynamics
The EU F-Gas Regulation is forcing a wholesale replacement of hydrofluorocarbon climate systems with CO2 heat pumps and geothermal exchange, compressing margins for incumbent HVAC suppliers while opening procurement windows for low-carbon equipment specialists.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Mandatory pesticide reduction targets in the Netherlands and Spain are accelerating investment in fully enclosed hydroponic glasshouses with integrated biological pest control systems.
- Automated nutrient delivery:Commercial tomato and cucumber growers in Westland and Almeria are deploying precision dosing systems to cut labor costs and eliminate human error in fertigation timing.
- Geothermal exchange clusters:Dutch greenhouse operators in the Westland region are tapping shallow geothermal reservoirs to displace natural gas heating, securing long-term energy cost stability.
Market Restraints
- Specialized glass supply concentration:Ultra-clear low-iron glass for high-transmission roofs relies on a limited number of European float-glass producers, creating vulnerability to energy cost spikes.
- CO2 heat pump technical limitations:Current systems struggle to deliver sufficient heating capacity below minus 15 degrees Celsius, constraining deployment in Nordic climates without backup boilers.
- CE marking compliance friction:The EU Construction Products Regulation requires extensive structural testing for wind and snow loads, extending project timelines by four to six months for non-European suppliers.
Strategic Opportunities
- Underpenetrated Saudi Arabia:Neom and Riyadh megaprojects are specifying high-end greenhouse infrastructure for domestic food security, creating first-mover advantages for turnkey European contractors.
- Carbon border adjustment tailwind:The EU's CBAM mechanism will penalize imported aluminum and steel with high embodied emissions, favoring domestic European greenhouse frame manufacturers with verified low-carbon supply chains.
- AI-vision pollination convergence:Computer vision systems combined with robotic arms are enabling automated tomato pollination in facilities where bumblebee deployment faces regulatory restrictions.
Industry Challenges
- Controls integration complexity:Legacy Priva and Hoogendoorn climate computers require custom API bridges to connect with new sensor networks, extending commissioning timelines.
- Skilled horticultural technician shortage:The Netherlands faces acute competition for glasshouse managers capable of optimizing VPD setpoints and integrated pest management protocols simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High End Greenhouse Market |
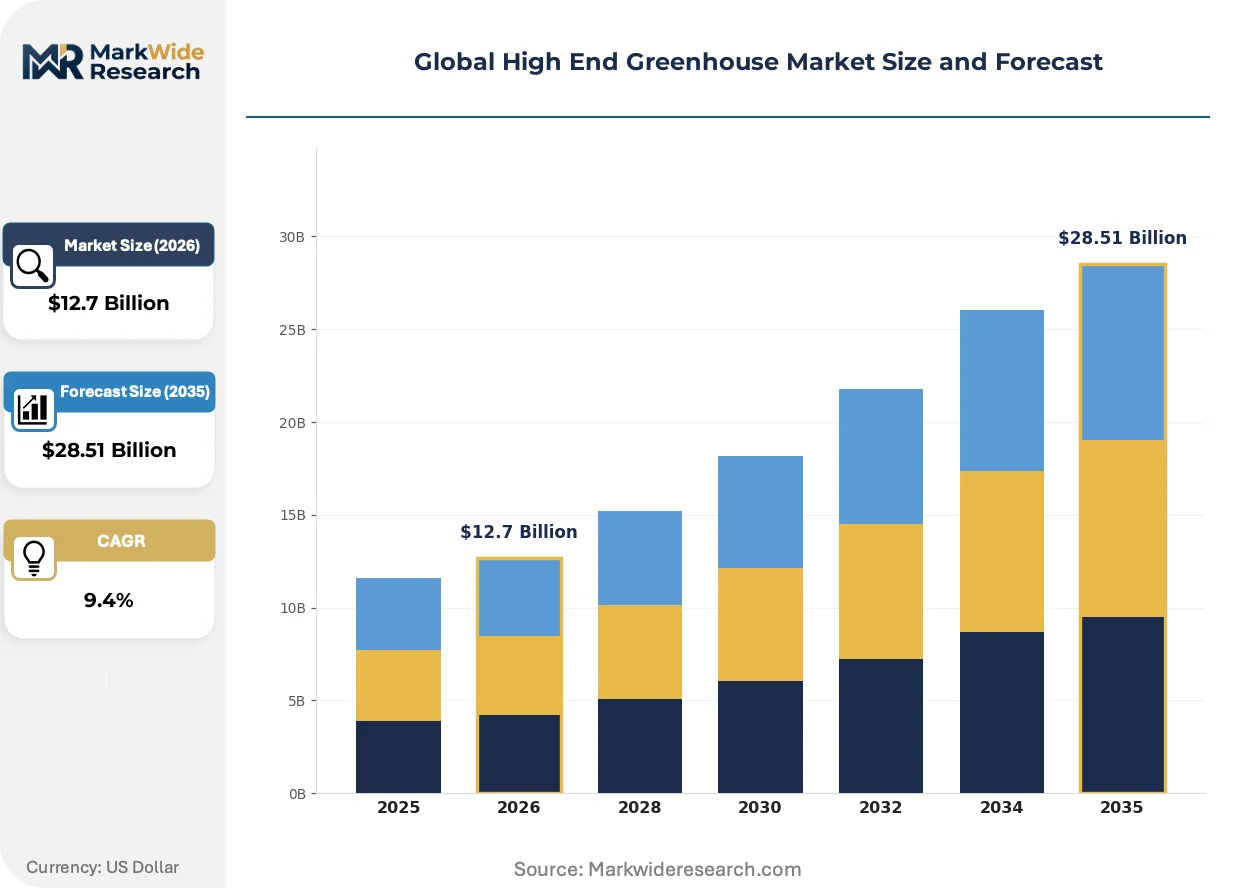
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $28.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroponics, Vertical Farms, Glasshouses, Polycarbonate Structures Technology: Climate Control Systems, LED Grow Lights, Irrigation Systems, Automated Nutrient Delivery End User: Commercial Growers, Research Institutions, Government Facilities, Hobbyists Delivery Mode: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Certhon, Priva, Rough Brothers Inc., Richel Group, Netafim, Argus Control Systems, Dalsem, Nexus Corporation, GreenTech Agro LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High End Greenhouse Market Emerging Trajectories
Climate control architecture is splitting into two distinct design philosophies as energy costs and carbon accountability reshape grower priorities. Equipment suppliers are racing to serve diverging buyer segments with incompatible system specifications.
Supplemental LED interlighting is bifurcating the tomato production segment. Top-tier Dutch and Spanish commercial growers are installing full-spectrum LED arrays between plant rows to boost Brix levels and accelerate fruit set in winter months. This technology is compressing the payback period for high-CAPEX glasshouse investments while marginalizing operations reliant solely on high-pressure sodium lamps.
The EU F-Gas Regulation is banning new hydrofluorocarbon installations above specific Global Warming Potential thresholds from 2027. Greenhouse operators in the Netherlands and Belgium are pre-emptively specifying transcritical CO2 heat pumps and closed-loop geothermal systems to avoid stranded asset risk. Spanish Almeria facilities with milder heating loads are accelerating adoption of ambient air-source heat pumps with thermal storage.
Service unbundling is fragmenting the traditional turnkey model. Large commercial growers in the Netherlands are separating structural procurement from climate control integration, sourcing aluminum frames directly from Dutch manufacturers while contracting Priva or Hoogendoorn separately for automation software. This pattern is most visible among Westland cluster operations with in-house engineering capabilities, compressing margins for full-service contractors.
Global High End Greenhouse Market Segmentation
Structural specifications in high-end greenhouse procurement diverge sharply across regulatory jurisdictions. CE marking requirements under the EU Construction Products Regulation create compliance tiers that reshape supplier selection and technology deployment patterns.
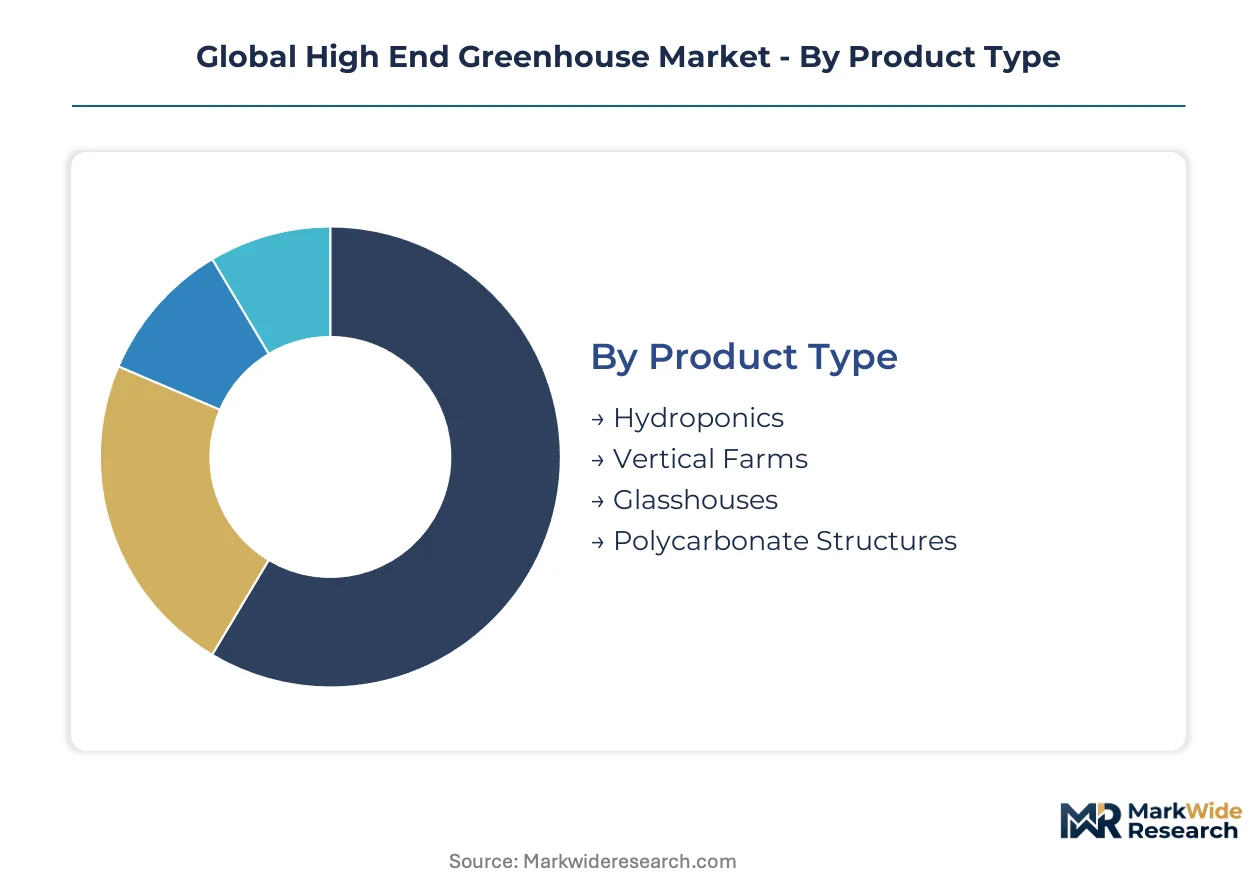
Product Type:
EU F-Gas Regulation and national building codes impose divergent thermal performance standards on enclosed agricultural structures.
- Glasshouses:Engineered with ultra-clear low-iron glass achieving light transmission above 90 percent and thermal screens with U-values below 2.5 W per square meter Kelvin. Dutch Westland cluster operations and Almeria province facilities in Spain specify these for tomato, cucumber, and pepper production, prioritizing longevity and optical clarity over first-cost considerations.
- Hydroponics:Fully enclosed systems with integrated biological pest control and precision nutrient delivery. Mandatory pesticide reduction targets under the EU Green Deal's Farm to Fork strategy are accelerating deployment across Netherlands and Spanish commercial operations.
- Vertical Farms:Multi-tiered enclosed cultivation with artificial lighting and climate control.
- Polycarbonate Structures:Lightweight alternatives with diffused light transmission for lower thermal load regions.
Established volume favors glasshouses; emerging adoption favors hydroponics.
Technology:
Capital intensity and labor cost trajectories determine technology prioritization across grower segments.
- Automated Nutrient Delivery:Precision dosing systems eliminating human error in fertigation timing. Commercial tomato and cucumber growers in Westland and Almeria deploy these to cut labor costs while maintaining consistency across hectare-scale operations.
- Climate Control Systems:CO2 heat pumps and geothermal exchange displacing hydrofluorocarbon-based equipment. EU F-Gas Regulation bans on high-GWP refrigerants are redirecting procurement toward transcritical CO2 systems and closed-loop geothermal networks.
- LED Grow Lights:Full-spectrum arrays including interlighting configurations between plant rows.
- Irrigation Systems:Water recirculation and drainage infrastructure for soilless cultivation.
Climate control systems absorb the largest capital allocation; automated nutrient delivery is climbing the fastest.
End User:
Scale economies and technical capability thresholds separate addressable buyer segments.
- Commercial Growers:Hectare-scale operations with in-house engineering staff capable of optimizing VPD setpoints and integrated pest management protocols. These buyers dominate procurement volume for tomato, cucumber, and pepper production systems.
- Research Institutions:Controlled environment agriculture facilities requiring precise replicability for crop science studies.
- Government Facilities:Domestic food security projects including Neom and Riyadh megaprojects in Saudi Arabia.
- Hobbyists:Small-scale residential and educational installations.
Commercial growers command procurement volume; government facilities present the steepest expansion trajectory.
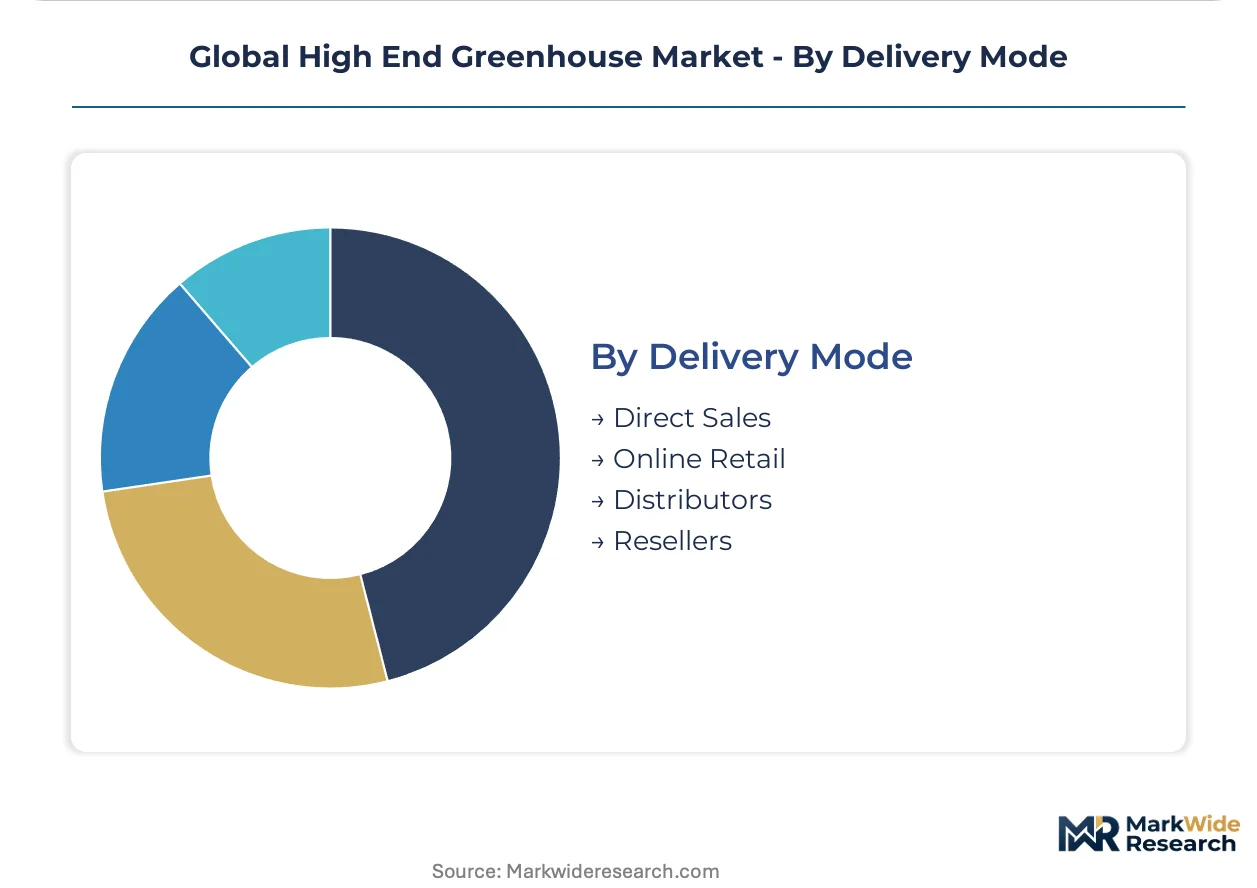
Delivery Mode:
Service unbundling is fragmenting traditional procurement channels among sophisticated buyers.
- Direct Sales:Turnkey project delivery from engineering specialists. Large commercial growers in the Netherlands are separating structural procurement from climate control integration, compressing margins for full-service contractors.
- Distributors:Regional inventory and logistics networks for standardized components.
- Resellers:Value-added integration of hardware and software subsystems.
- Online Retail:Transactional channels for smaller-scale equipment and replacement parts.
Direct sales retain the largest project value; distributor relationships are gaining share fastest among mid-scale operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial growers with hectare-scale operations and in-house engineering capabilities concentrate procurement volume across four distinct national markets, each shaped by divergent regulatory frameworks and energy cost trajectories.
Netherlands
The Westland cluster drives continental demand for glasshouse infrastructure with integrated climate control and biological pest management systems. EU F-Gas Regulation mandates phase-out of hydrofluorocarbon refrigerants above specified Global Warming Potential thresholds from 2027, redirecting capital toward transcritical CO2 heat pumps and shallow geothermal exchange networks. Dutch operators in Westland and Aalsmeer are tapping geothermal reservoirs to displace natural gas heating and secure long-term energy cost stability.
Spain
Almeria province facilities absorb substantial volume for tomato and pepper production systems with precision nutrient delivery infrastructure. The EU Green Deal's Farm to Fork strategy tightens pesticide reduction targets, accelerating investment in fully enclosed hydroponic operations with integrated biological pest control. Commercial growers across Almeria and Granada are deploying automated fertigation systems to eliminate human error in timing and dosing consistency.
United States
EPA agricultural emission guidelines shape ventilation and energy recovery specifications for imported Dutch climate systems. The Inflation Reduction Act directs capital toward energy-efficient agricultural infrastructure through tax credit mechanisms. California's Central Valley and Florida's tomato-growing regions anchor North American demand for aluminum gutter-connected greenhouse designs.
Saudi Arabia
Neom and Riyadh megaprojects specify high-end greenhouse infrastructure for domestic food security objectives, creating first-mover procurement windows for turnkey European contractors. The national food security program under Vision 2030 prioritizes enclosed agricultural structures with climate control capabilities. Operators in the Riyadh region and NEOM Northwest development zone are commissioning glasshouse projects with integrated desalination and renewable energy coupling.
China
Dual carbon goals and provincial agricultural modernization programs redirect investment toward energy-efficient enclosed cultivation infrastructure. The Ministry of Ecology and Environment constrains agricultural emission intensity through regional performance targets. Shandong Peninsula and Yangtze River Delta greenhouse operators are specifying LED interlighting arrays and automated climate control systems for vegetable production.
Global High End Greenhouse Market Vendor Landscape
Player mix skews toward engineering-intensive turnkey specialists with Dutch heritage dominating European procurement and North American fabricators anchoring regional supply. Market structure concentrates around three strategic tiers: full-service contractors delivering integrated structural and automation packages, component specialists supplying climate control software and sensor networks, and regional fabricators focused on aluminum frame production. Competitive dynamics center on technology licensing arrangements and geographic expansion into underpenetrated Middle Eastern markets.
Among Dutch engineering specialists, Certhon and Dalsem occupy positions exemplifying the full-service turnkey archetype with integrated structural and climate control capabilities. Priva sits within the automation software tier, representing technology leadership through climate computer integration. Rough Brothers Inc. anchors the North American fabricator segment. Richel Group and Netafim occupy intermediate positions spanning structural and irrigation system supply.
| Leading Market Players |
|---|
| Certhon |
| Priva |
| Rough Brothers Inc. |
| Richel Group |
| Netafim |
| Argus Control Systems |
| Dalsem |
| Nexus Corporation |
| GreenTech Agro LLC |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Dutch turnkey contractors and commercial growers in the Westland cluster lock in aluminum frame supply and climate control system pricing, insulating procurement budgets from spot volatility in energy-intensive float-glass production.
Pricing Analysis
Cost-plus contracts with aluminum indexation dominate structural procurement, tying frame pricing to London Metal Exchange benchmarks while software and automation components command fixed project fees. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked Dutch engineering from non-certified alternatives and basic polycarbonate designs. Price differentiation hinges on thermal performance certification and after-sales service bundling. Cost compression in mid-tier glasshouse packages is intensifying because Spanish Almeria growers are consolidating orders to extract volume discounts. Hobbyist segments exhibit highest price sensitivity; government food security projects in Saudi Arabia demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of ultra-clear low-iron glass prevails among Dutch frame manufacturers, buffering against energy cost spikes at European float-glass plants. Supply concentrates in the Netherlands for aluminum gutter-connected structures, Germany for precision climate control hardware, and Belgium for CO2 heat pump assembly. Raw material dependencies include low-iron silica sand, extruded aluminum profiles, and transcritical CO2 compressor units. Single-source vulnerability runs through specialized glass float lines. Distribution runs through direct sales for turnkey projects and regional distributors for replacement components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high-end greenhouse sector sits in early-cycle expansion, with EU F-Gas Regulation mandates forcing wholesale climate system replacement across existing Dutch and Spanish infrastructure.
For Market Incumbents: Compound technology licensing advantages by embedding proprietary climate control APIs into third-party sensor networks, defending against modular unbundling. Secure captive supply of CE-certified aluminum extrusion capacity in the Netherlands before carbon border adjustment mechanisms penalize imported steel. Vertical integration into shallow geothermal drilling operations locks in energy cost arbitrage for Westland cluster clients. For New Entrants and Emerging Players: Anchor in Saudi Arabian government food security tenders, where European engineering credibility commands premium positioning against untested local fabricators. Target mid-scale commercial growers in China's Shandong Peninsula, where provincial agricultural modernization programs subsidize imported greenhouse technology. Lead with desalination-coupled climate control packages that address Gulf region water scarcity. For Investors and Strategic Acquirers: Automation software specialists with established API ecosystems and recurring service revenue represent the most defensible acquisition profile. Long-term viability hinges on regulatory compliance capabilities rather than structural fabrication scale. Watch for inflection when EU carbon border adjustment mechanism enforcement triggers wholesale supply chain reconfiguration among aluminum frame suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Geothermal Exchange Cluster Development | Dutch Westland operators tap shallow reservoirs to displace natural gas heating under EU emission constraints. |
| CE Marking Fast-Track Certification | Non-European structural suppliers compress project timelines by pre-certifying wind and snow load specifications. |
| AI-Vision Pollination Integration | Computer vision systems with robotic arms enable automated tomato pollination where bumblebee deployment faces regulatory restrictions. |
| Service Unbundling Separation | Large commercial growers split structural procurement from climate control integration, compressing turnkey contractor margins. |
| Carbon Border Adjustment Compliance | Domestic European frame manufacturers with verified low-carbon supply chains gain procurement preference over imports. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured interviews with commercial greenhouse managers, climate control system engineers, agricultural procurement officers at government food security agencies, and aluminum frame manufacturing executives. Secondary validation drew from EU F-Gas Regulation implementation documents, CE marking compliance databases, EIA agricultural energy consumption statistics, and customs trade data for greenhouse component imports. Bottom-up project pipeline tracking across Netherlands, Spain, Saudi Arabia, and China was triangulated against top-down market sizing from equipment supplier revenue disclosures.
Across the analysis window, forecasts were derived from segmented modeling of glasshouse versus hydroponic structure deployment, climate control technology substitution patterns, and end-user scale distributions. Analytical framework incorporated automated nutrient delivery adoption curves, geothermal exchange penetration rates in Dutch operations, and LED interlighting intensity per hectare. CAGRs were computed from annual installation volume trajectories and average project value evolution.
Material uncertainties — regulatory enforcement timing, energy cost volatility, and skilled technician availability — sit outside the modeled envelope. Forecasts reflect assumptions about EU Green Deal implementation pace and Saudi Vision 2030 project commitment stability. Revision becomes warranted when carbon border adjustment mechanism scope expansion crosses thresholds affecting aluminum trade flows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Europe Green Carbon Market
Environment & Sustainability
Anti-Pollution Toner Market
Environment & Sustainability
Industrial Waste Management Market
Environment & Sustainability
Brazil Organic Dinnerware Market
Environment & Sustainability
Recycling Equipment Market
Environment & Sustainability
Water Ionizers Market
Environment & Sustainability
Industrial Air Quality Control Systems Market
Environment & Sustainability
Outdoor Flooring Market
Environment & Sustainability
Weather Modification Equipment Market
Environment & Sustainability
Water Trading Market
Environment & Sustainability
Waste Paper Recycling Market
Environment & Sustainability
Europe Municipal Solid Waste Management Market
Environment & Sustainability
Global Water and Wastewater Treatment Equipment Market
Environment & Sustainability
Sustainable and Green Building Materials Market
Environment & Sustainability
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environment & Sustainability
Solar Frames Market