
 US Automotive Sensors Market | 2026-2036
US Automotive Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
US Automotive Sensors Market Analytics
Software-defined subscription services for over-the-air sensor calibration is hardening as a permanent revenue layer for component vendors. Robert Bosch GmbH leverages its tier 1 relationships to bundle firmware updates with hardware shipments. Continental AG anchors its US strategy around Detroit-area engineering centers that co-develop sensor suites with domestic OEMs. Texas Instruments Incorporated competes by specializing in high-temperature MEMS controllers for powertrain applications.
Automotive sensors are electromechanical transducers that convert physical variables—pressure, temperature, proximity, or airflow—into electrical signals readable by vehicle control modules, typically operating across temperature ranges from minus 40 to 150 degrees Celsius and communicating via LIN, CAN, or Ethernet protocols. Their primary purpose is to feed real-time data into engine management, safety, and chassis systems that govern vehicle performance and occupant protection. Pressure sensors occupy the largest revenue pool among product types due to their ubiquity in fuel injection and tire monitoring systems, while MEMS technology leads growth because of shrinking form factors and falling unit costs in safety and transmission control applications. Passenger vehicles dominate end-user demand, though heavy-duty trucks are pulling disproportionate sensor volume per vehicle as federal emissions enforcement tightens.
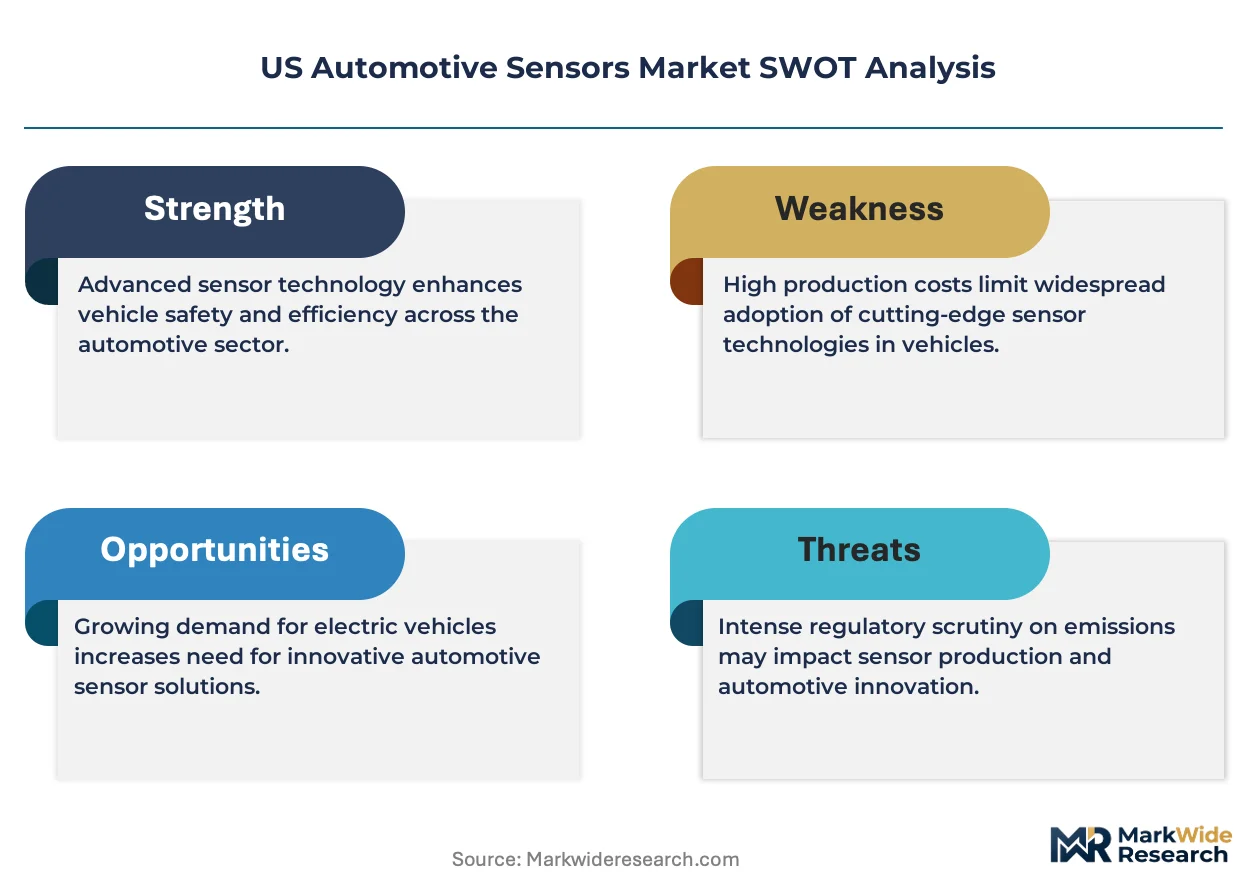
NHTSA, EPA, and the California Air Resources Board collectively shape product standards by mandating crash-avoidance capabilities and emissions monitoring that require redundant sensor arrays. The EPA's greenhouse gas rules for light-duty vehicles force OEMs to install precision mass airflow and exhaust temperature sensors that feed closed-loop engine control. Stakeholders must monitor how NHTSA's advancing automatic emergency braking requirements expand sensor count per vehicle platform without eroding module-level margins.
Market Dynamics
The US automotive sensors market is being fundamentally restructured by NHTSA's escalating automatic emergency braking mandates, which are forcing Detroit-area OEMs to replace legacy analog sensor architectures with digital platforms that support redundant, high-fidelity data streams for safety-critical decision-making.
Growth Catalysts
- EPA Greenhouse Gas Rules:Light-duty vehicle emissions standards mandate precision mass airflow and exhaust temperature sensors for closed-loop engine control, expanding sensor count per powertrain platform.
- Heavy-Duty Truck Electrification:Federal emissions enforcement on commercial fleets is driving disproportionate sensor volume per vehicle as diesel-aftertreatment and battery-thermal monitoring systems proliferate.
- MEMS Technology Maturation:Shrinking form factors and falling unit costs in safety and transmission control applications are accelerating replacement cycles across passenger vehicle platforms.
Market Restraints
- Semiconductor Input Volatility:Silicon wafer and MEMS foundry capacity constraints in East Asia create pricing instability for sensor controller ICs.
- Tier 1 Supply Concentration:Detroit-area procurement decisions cluster among three dominant system integrators, limiting pricing leverage for specialized sensor vendors.
- Functional Safety Certification Friction:ISO 26262 ASIL-D compliance timelines extend product development cycles by 18-24 months for safety-critical applications.
Strategic Opportunities
- California EV Engineering Clusters:Electric vehicle thermal management and battery state-of-health monitoring create greenfield demand for multi-physics sensor fusion platforms.
- Software-Defined Calibration Services:Over-the-air firmware update subscriptions for sensor drift compensation represent recurring revenue streams decoupled from hardware shipment cycles.
- NHTSA V2X Mandate Trajectory:Vehicle-to-everything communication standards will require roadside infrastructure sensors, opening adjacent municipal and federal procurement channels.
Industry Challenges
- Embedded Systems Talent Scarcity:Shortages of firmware engineers with automotive safety-critical experience constrain development velocity for digital sensor platforms.
- Legacy CAN Bus Integration Complexity:New Ethernet-based sensor architectures must coexist with 20-year-old vehicle network topologies, multiplying validation testing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Automotive Sensors Market |
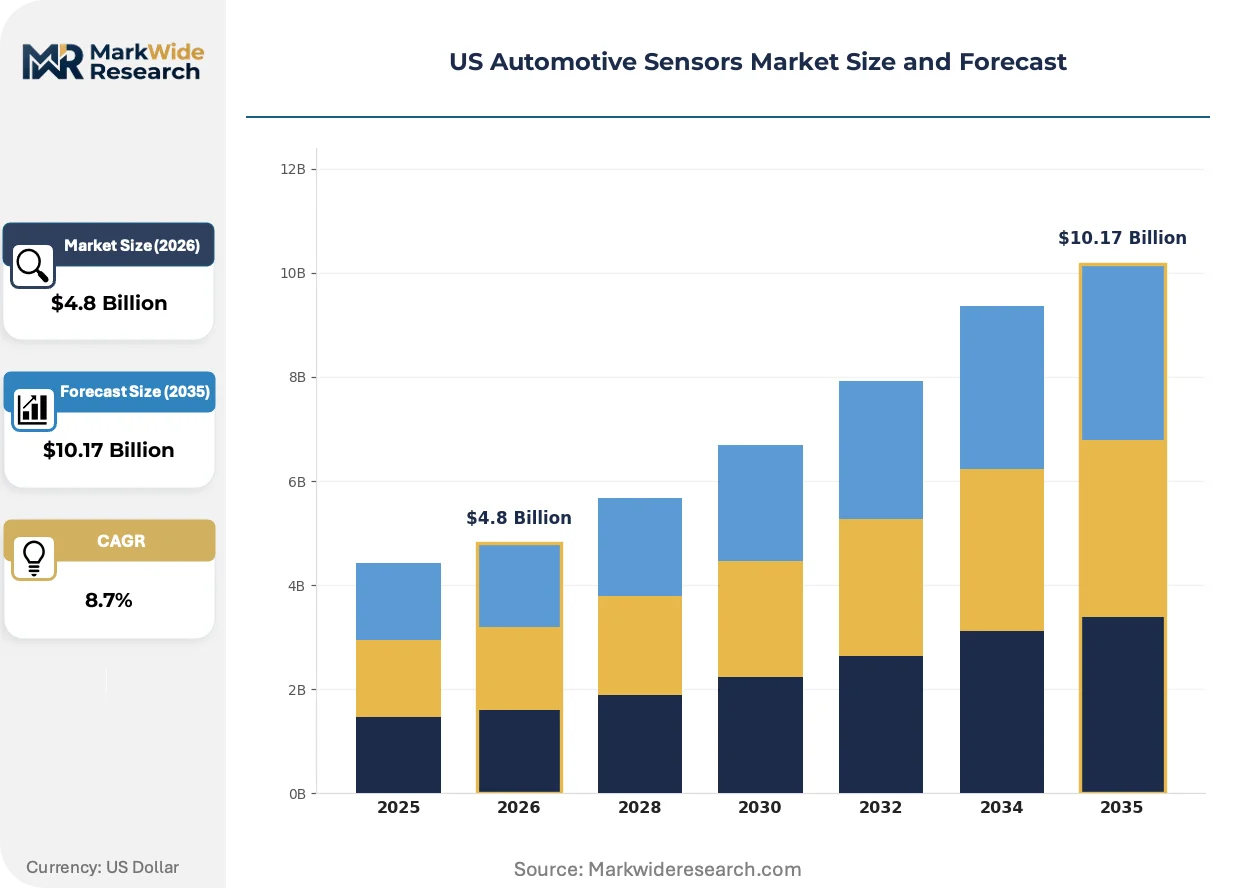
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Proximity Sensors, Mass Air Flow Sensors Technology: MEMS, Analog, Digital, Optical End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks Application: Engine Control, Safety Systems, Transmission Control, Cabin Comfort |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, Texas Instruments Incorporated, Infineon Technologies, Analog Devices, Inc., Aptiv, Sensata Technologies, Inc., Autoliv, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Automotive Sensors Market Evolving Landscape
Digital sensor architectures are displacing analog predecessors as the foundational layer for software-defined vehicles, with firmware-upgradable transducers becoming the default specification in Detroit OEM procurement cycles. Three convergent forces are compressing product lifecycles and rewiring competitive advantage.
Solid-state LiDAR is expanding into mid-range ADAS applications as MEMS-based beam-steering arrays from tier 1 suppliers achieve automotive-grade temperature stability. General Motors and Ford Motor Company are qualifying these units for highway pilot systems, collapsing the price-performance gap that previously restricted LiDAR to luxury full-size SUVs. The technology is expanding into volume production platforms by 2026, forcing incumbent radar and camera suppliers to defend their sensor fusion slots with superior all-weather reliability claims.
NHTSA's automatic emergency braking mandate for passenger vehicles and light trucks is compressing deployment timelines for multi-modal sensor suites. The regulation requires pedestrian and cyclist detection capabilities that single-sensor systems cannot reliably deliver, compelling OEMs to standardize on camera-radar fusion stacks even in entry trim levels. Michigan-based engineering centers are absorbing the bulk of validation workload as domestic manufacturers race to certify 2026 model year compliance.
Fleet operators are unbundling sensor calibration from dealer service networks, creating independent aftermarket channels for mobile recalibration technicians. Rental car companies and commercial trucking fleets in Texas and Florida are contracting directly with specialty service providers to minimize vehicle downtime. This procurement pattern is most visible in Sun Belt states where fleet density and temperature-induced sensor drift create recurring demand for rapid turnaround services outside traditional OEM-controlled infrastructure.
US Automotive Sensors Market Segmentation
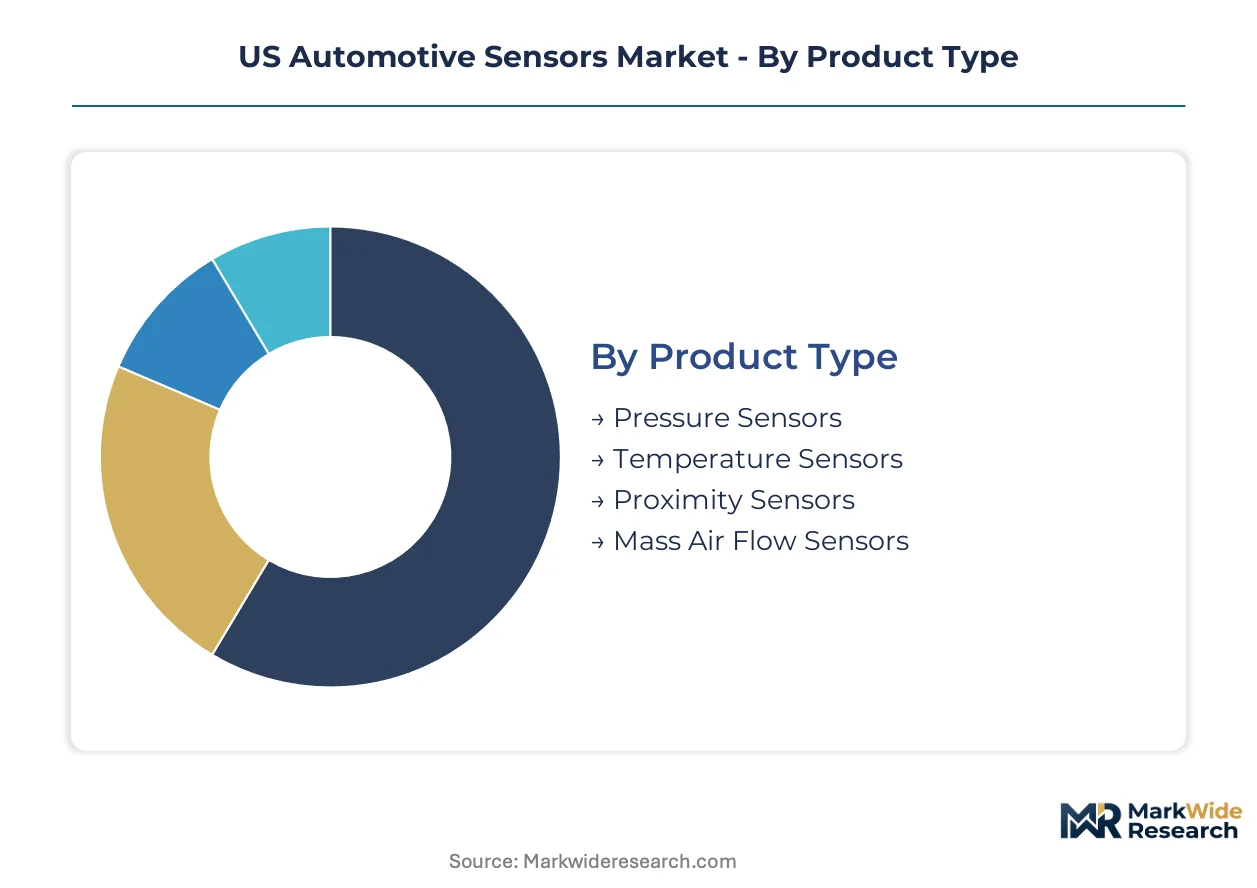
Sensor segmentation in the US automotive market reflects divergent integration architectures. Standalone modules serve legacy powertrain functions while embedded multi-sensor arrays dominate ADAS and electric vehicle platforms.
Product Type:
Integration depth varies sharply across product types, with some sensors operating as discrete bolt-on modules and others fused into consolidated control units.
- Pressure Sensors:Piezoresistive or capacitive transducers measure fluid and gas pressure in fuel rails, brake lines, and HVAC systems. Demand concentrates in Michigan's powertrain engineering corridors where EPA emissions rules mandate precision manifold absolute pressure sensing for closed-loop engine control.
- Temperature Sensors:Thermistors and resistance temperature detectors monitor exhaust gas, battery pack, and cabin thermal states. California EV clusters pull disproportionate volume as battery state-of-health monitoring requires redundant thermal sensing arrays.
- Proximity Sensors:Ultrasonic and capacitive units detect object distance for parking assistance and gesture recognition.
- Mass Air Flow Sensors:Hot-wire and vane-type meters measure intake air volume for fuel injection calibration.
Pressure sensors lead volumes today; temperature sensors are gaining share fastest.
Technology:
Cost tiers separate legacy analog implementations from premium digital platforms capable of firmware-defined functionality.
- MEMS:Microelectromechanical systems integrate mechanical elements with semiconductor fabrication, enabling miniaturized accelerometers, gyroscopes, and pressure transducers. Heavy-duty truck electrification in Texas and Florida drives above-average sensor count per vehicle as diesel aftertreatment and battery thermal management multiply MEMS deployment points.
- Digital:Firmware-upgradable architectures with embedded processing and Ethernet connectivity support over-the-air calibration. NHTSA automatic emergency braking mandates force Detroit OEMs toward digital platforms that deliver redundant, high-fidelity data streams.
- Analog:Voltage-output transducers without onboard processing persist in cost-sensitive auxiliary applications.
- Optical:Photodiode and image sensor arrays enable LiDAR and camera-based perception systems.
MEMS leads volumes today; digital platforms are expanding most quickly.
End User:
Application maturity and regulatory exposure create distinct customer segments with diverging procurement specifications.
- Passenger Vehicles:Light-duty cars and SUVs carry standardized sensor suites across trim levels. Michigan-based OEMs anchor procurement volume as NHTSA mandates spread advanced driver-assistance systems from premium to mass-market platforms.
- Heavy-Duty Trucks:Class 8 commercial vehicles require disproportionate sensor density for emissions compliance and fleet telematics. Federal enforcement of greenhouse gas standards forces installation of precision exhaust temperature and particulate matter sensors.
- Commercial Vehicles:Light and medium-duty trucks and vans serve vocational and delivery applications.
- Two-Wheelers:Motorcycles and scooters carry minimal sensor content focused on engine management.
Passenger vehicles lead volumes today; heavy-duty trucks show the steepest expansion trajectory.
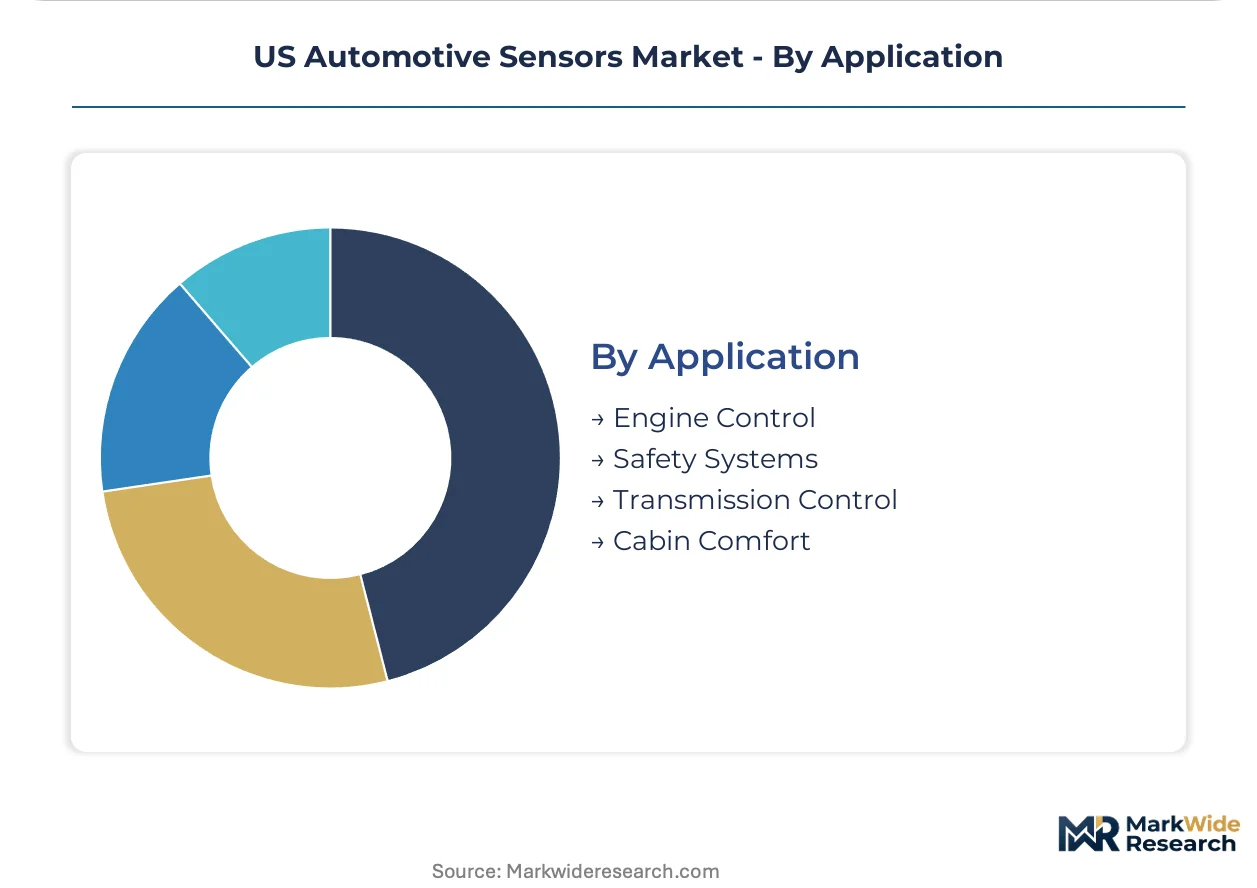
Application:
Functional safety requirements and margin profiles segment applications into safety-critical and comfort-ancillary categories.
- Safety Systems:Automatic emergency braking, lane-keeping, and occupant detection arrays demand ISO 26262 ASIL-D certification. California EV engineering centers co-develop multi-modal fusion stacks combining radar, camera, and LiDAR inputs.
- Engine Control:Powertrain management sensors feed real-time data to engine control modules for fuel injection timing and emissions optimization. EPA greenhouse gas rules for light-duty vehicles mandate precision mass airflow and exhaust temperature sensing.
- Transmission Control:Gear position, shaft speed, and fluid condition sensors enable automated shifting.
- Cabin Comfort:Climate control and ambient lighting sensors serve occupant convenience functions with lower certification burdens.
Engine control leads volumes today; safety systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive sensor procurement concentrates on premium powertrain applications, whereas China's volume demand centers on electric vehicle battery management systems. Japan maintains specialized strength in MEMS fabrication for safety-critical deployments. South Korea leverages domestic OEM relationships to scale camera-radar fusion platforms. India's emerging EV manufacturing clusters are pulling imported sensor content for thermal and current sensing arrays.
Germany
Precision pressure and exhaust gas sensors dominate procurement from domestic OEMs targeting EU emissions compliance. KBA vehicle type approval mandates redundant sensing architectures for automated driving functions. Stuttgart engineering centers co-develop digital sensor platforms with tier 1 suppliers for next-generation powertrain management.
China
Battery state-of-health monitoring and thermal runaway detection sensors drive disproportionate volume in NEV platforms. MIIT new energy vehicle regulations mandate multi-point temperature sensing for lithium-ion pack certification. Yangtze River Delta manufacturing clusters host domestic MEMS foundries scaling automotive-grade accelerometer output.
Japan
High-reliability gyroscopes and pressure transducers serve hybrid powertrain and chassis control applications. METI automotive technology roadmaps prioritize sensor fusion for highway automated driving. Nagoya-area tier 1 suppliers maintain captive MEMS fabrication for proprietary safety system integration.
South Korea
Camera and radar module procurement accelerates for domestic OEM highway pilot programs. MFDS automotive safety guidelines align with global NCAP pedestrian detection requirements. Seoul Capital Area engineering centers specialize in compact sensor packaging for A-pillar and mirror integration.
India
Current sensors and battery thermal monitors comprise the fastest-growing import categories for domestic EV assembly. Automotive Research Association of India certification timelines compress for indigenized sensor designs. Tamil Nadu and Gujarat manufacturing corridors attract component vendors establishing local calibration facilities.
US Automotive Sensors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier 1 system integrators consolidating procurement leverage in Detroit-area supply chains. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive semiconductor fabrication, pure-play sensor specialists focused on automotive safety certification, and fabless designers outsourcing MEMS production to Asian foundries. Competitive moves center on backward integration into MEMS wafer processing and strategic partnerships with EV platform architects.
Within the diversified industrial tier, Robert Bosch GmbH and Continental AG exemplify integrated players combining tier 1 system integration with in-house sensor manufacturing. Texas Instruments Incorporated occupies a position among semiconductor specialists leveraging high-temperature controller expertise for powertrain applications. Sensata Technologies, Inc. represents the pure-play sensor archetype with concentrated automotive safety and electrification exposure.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| Texas Instruments Incorporated |
| Infineon Technologies |
| Analog Devices, Inc. |
| Aptiv |
| Sensata Technologies, Inc. |
| Autoliv |
| Others |
Value Network & Pricing Analysis
EPA greenhouse gas rules for light-duty vehicles gate qualified supply access and premium-tier pricing power, as only sensor vendors with ISO 26262 ASIL-D certification and precision mass airflow manufacturing capabilities can serve Detroit OEM procurement cycles. Tier 1 suppliers leverage this regulatory filter to maintain margin premiums on digital architectures while analog competitors face price compression in auxiliary applications.
Pricing Analysis
Capacity additions in Michigan and California are reshaping price floors for firmware-upgradable sensor platforms. Three-tier pricing structure across ASIL-D certified, ASIL-B compliant, and non-safety-critical levels separates Detroit OEM contracts from aftermarket service tiers. Price differentiation stems from certification grade and volume scale, with heavy-duty truck procurement showing lowest sensitivity due to federal emissions enforcement. Cost compression in standard-tier MEMS controllers is intensifying because Asian foundry output expansion outpaces domestic packaging capacity.
Supply Chain Analysis
Domestic-content mandates in the Inflation Reduction Act are reshaping sourcing for battery thermal monitoring arrays, pushing OEMs toward North American component qualification. Silicon wafer fabrication concentrates in Taiwan, South Korea, and the United States, while MEMS foundry output draws from China and Malaysia. Raw material dependencies span high-purity silicon, rare-earth magnets for position sensing, and ceramic substrates for high-temperature applications. Single-source vulnerability in automotive-grade Ethernet PHY chips creates bottleneck exposure. Distribution runs through Tier 1 system integrators co-located in Detroit-area engineering corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US automotive sensors hinges on software-defined calibration subscriptions decoupling revenue from hardware shipment cycles, while MEMS miniaturization reduces bill-of-material costs across safety-critical platforms.
For Market Incumbents: Extend firmware-update subscription penetration among fleet operators to lock out independent aftermarket calibration services. Deepen backward integration into MEMS wafer processing to offset foundry pricing volatility. Fortify Detroit-area engineering co-development relationships against emerging fabless competitors targeting California EV clusters with multi-physics fusion platforms. For New Entrants and Emerging Players: Enter via battery state-of-health monitoring for commercial trucking fleets in Texas and Florida, where temperature-induced sensor drift creates recurring service demand. Target heavy-duty truck electrification applications with diesel-aftertreatment and thermal management arrays. Pursue direct fleet procurement relationships bypassing Tier 1 system integrators. For Investors and Strategic Acquirers: Roll-up economics work for pure-play sensor specialists with concentrated automotive safety certification because Tier 1 procurement consolidation limits standalone scaling. Five-to-ten year viability favors vendors with captive MEMS fabrication and over-the-air software capabilities. Monitor NHTSA V2X mandate advancement as inflection signal for roadside infrastructure sensor demand.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Robert Bosch GmbH bundles firmware subscriptions with hardware to capture recurring revenue streams. |
| Battery Supply Agreement | Continental AG secures lithium-ion pack sensor slots through co-development with California EV engineering centers. |
| Platform Standardization | Texas Instruments leverages high-temperature MEMS controller specialization across multiple powertrain platforms. |
| Geographic Manufacturing Footprint | Sensata Technologies anchors production in Michigan corridor to minimize logistics friction with Detroit OEMs. |
| Charging Infrastructure Partnership | Aptiv positions thermal monitoring arrays for DC fast-charging station battery management integration. |
Research Methodology
Coverage spans the United States with primary inputs from Michigan automotive corridor and California EV engineering clusters, combining interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership service operations with secondary validation. Secondary sources include NHTSA regulatory filings, EPA emissions compliance databases, vehicle production registries, and SEC disclosures from component vendors. Bottom-up sensor content-per-vehicle estimates triangulate against top-down market value reconstruction.
Granularity-level modeling disaggregates volume and value across the projection horizon by product type, technology tier, vehicle class, propulsion architecture, and regional production cluster. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate NHTSA mandate implementation trajectories, MEMS cost curves, and fleet electrification penetration patterns without year-specific milestones.
Inputs from Tier 1 supplier procurement officers and OEM engineering directors were available through the study window; gaps in pre-production platform sensor specifications introduce uncertainty bands around content-per-vehicle assumptions for unreleased vehicle architectures. Forecasts reflect documented regulatory and technology assumptions; semiconductor input volatility or NHTSA mandate timeline shifts could revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Grille Guard Market
Vehicle Components
Motorcycle Connectors Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
Vehicle Exhaust Hose Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
Bicycle Components Aftermarket Market
Vehicle Components
Europe Automotive Lightweight Car Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Rail Components Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Air Brake Reservoirs Market
Vehicle Components
Canada Automotive Carbon Fiber Composites Market
Vehicle Components
UK Automotive Glass Fiber Composites Market
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
Exhaust Gas Recirculation (EGR) Valve Market