
 Forklift Seats Market | 2026-2036
Forklift Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Forklift Seats Market Foresight
The capital-intensity divergence between full-line seating suppliers and regional fabricators is rotating competitive advantage toward integrated manufacturers with in-house suspension testing. Grammer AG leverages its automotive-derived vibration engineering to dominate premium forklift seat configurations for export markets. Be-Ge Group sustains Scandinavian manufacturing scale across mechanical and air suspension lines. K&M Manufacturing anchors North American aftermarket replacement through direct distribution to material handling dealers.
A forklift seat is an operator support assembly engineered with steel or composite frames, foam cushioning systems, and optional suspension mechanisms designed to attenuate whole-body vibration during repetitive load-transport cycles. Suspension seats incorporate hydraulic or air-dampened pedestals that isolate frequencies between 2 and 12 Hz, the range most associated with spinal compression injuries in industrial truck operation. Standard seats retain volume leadership in cost-sensitive emerging fleet segments where base specifications predominate. Ergonomic seats with adjustable lumbar support represent the fastest-expanding technology tier as warehousing employers address retention-driven operator wellness mandates. Heavy-duty seats command concentrated margin pools in port terminal and construction applications where 24-hour shift patterns accelerate wear cycles.
OSHA enforces operator protection standards that indirectly mandate seat integrity through powered industrial truck safety rules, while the EU Machinery Directive requires CE-marked seats to meet vibration emission limits under harmonized EN 13059 protocols. The EPA and California Air Resources Board shape demand indirectly by driving electric forklift penetration, whose smoother torque profiles reduce vibration exposure and enable lighter seat specifications. Stakeholders must monitor how ISO 2631-1 whole-body vibration measurement standards evolve, since revised exposure limits would force suspension technology upgrades across installed fleets regardless of replacement timing.
Market Dynamics
Whole-body vibration exposure limits are compressing replacement cycles and forcing suspension technology upgrades across installed forklift fleets, regardless of scheduled maintenance timing.
Growth Catalysts
- OSHA workplace ergonomics enforcement:Powered industrial truck safety rules indirectly mandate seat integrity, compelling fleet operators to upgrade seating configurations during routine equipment inspections.
- E-commerce fulfillment center expansion:Third-party logistics operators in Germany and the United States are specifying suspension-equipped seating to reduce operator fatigue during extended shift patterns.
- Air suspension technology maturation:Hydraulic and air-dampened pedestal systems now isolate frequencies between 2 and 12 Hz, directly addressing spinal compression injury risks in repetitive load-transport cycles.
Market Restraints
- Steel and polyurethane foam input volatility:Raw material cost swings compress margin pools for regional fabricators lacking long-term supply agreements with integrated chemical producers.
- EU Machinery Directive compliance friction:CE-marking requirements under harmonized EN 13059 protocols extend product development timelines for non-integrated manufacturers without in-house vibration testing capabilities.
- Standard seat substitution in cost-sensitive segments:Base specification procurement in emerging fleet segments limits average selling price realization for premium suspension configurations.
Strategic Opportunities
- ISO 2631-1 standard revision tailwind:Anticipated tightening of whole-body vibration exposure limits will force technology upgrades across installed fleets, accelerating replacement demand independent of wear cycles.
- Electric forklift penetration:EPA and California Air Resources Board emissions regulations are driving smoother torque profiles that reduce vibration exposure and enable lighter, cost-optimized seat specifications.
- Aftermarket direct distribution:Material handling dealers are consolidating procurement through single-source distributors, creating channel consolidation opportunities for manufacturers with captive North American distribution networks.
Industry Challenges
- Vibration engineering talent scarcity:Automotive-derived suspension expertise concentrates among a limited pool of specialists, constraining product development velocity for mid-tier manufacturers.
- Dual certification timeline compression:Simultaneous OSHA compliance and CE-marking requirements for export-configured machines extend validation cycles and strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forklift Seats Market |
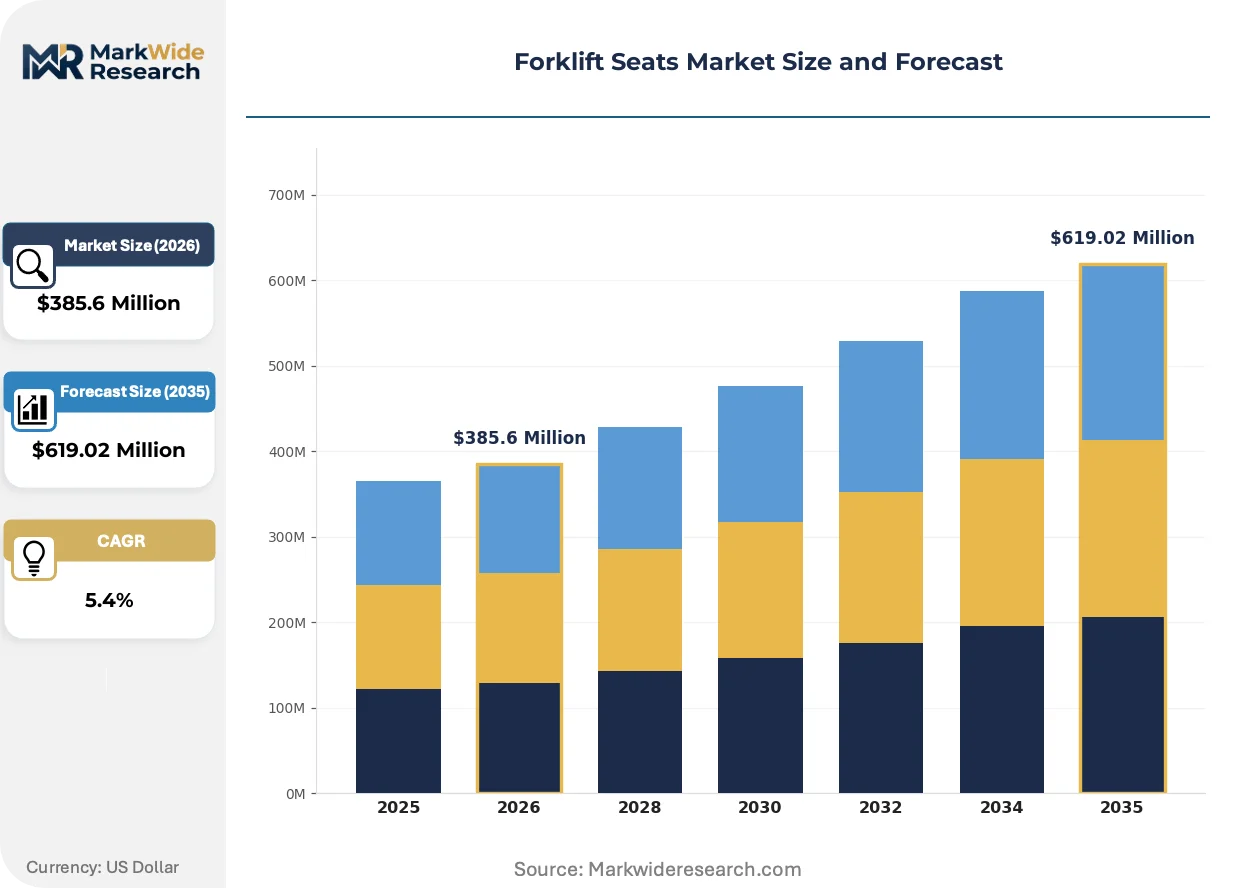
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Suspension Seats, Standard Seats, Ergonomic Seats, Heated Seats, Heavy-Duty Seats Technology: Hydraulic Suspension, Mechanical Suspension, Air Suspension, Vibration Dampening, Adjustable Lumbar Support Application: Warehousing, Manufacturing Plants, Construction Sites, Logistics Parks, Ports & Terminals End User: Material Handling Companies, Freight Operators, Industrial Contractors, Distribution Centers |
| Companies Covered | Commercial Vehicle Group, Seat Industries, K&M Manufacturing, Tidd Ross Todd Limited, Be-Ge Group, Grammer AG, Sears Seating, Pilot Seats, Thomas Scott Seating Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forklift Seats Market Shifts & Advancements
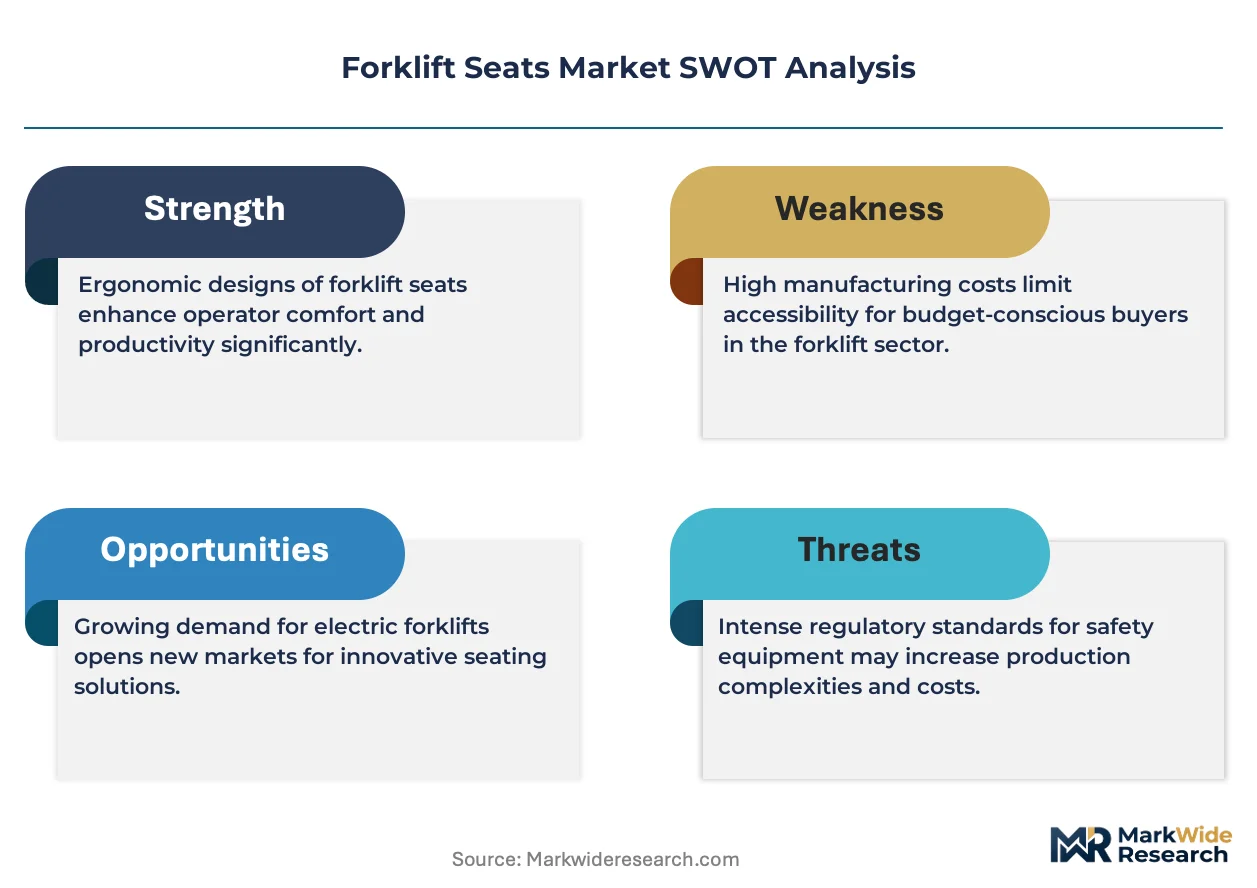
Seating technology is pivoting toward operator wellness mandates as warehousing employers confront retention pressures and regulatory exposure limits tighten across major industrial economies.
Adjustable lumbar support mechanisms are supplanting fixed foam configurations in premium forklift seat specifications. E-commerce fulfillment operators in Germany and the United States are specifying these ergonomic configurations for new fleet procurement. The shift is compressing demand for legacy standard seats in high-turnover warehousing applications while expanding margin pools for integrated manufacturers with in-house biomechanical engineering capabilities.
REACH chemical safety protocols and evolving EU Machinery Directive harmonization standards are reshaping foam formulation requirements for CE-marked seating. Industrial truck OEMs serving export markets must now validate polyurethane cushioning systems against restricted substance lists. German OEM specification practices are transmitting these requirements through supply chains to component suppliers lacking European regulatory affairs infrastructure.
Fleet operators are unbundling seat replacement from complete truck refurbishment cycles. Third-party logistics providers in North American distribution corridors are contracting direct with seating manufacturers for operator wellness programs. This pattern is most visible in California and Texas warehousing clusters where OSHA inspection frequency and workers compensation costs concentrate procurement attention on ergonomic specifications.
Forklift Seats Market Segmentation
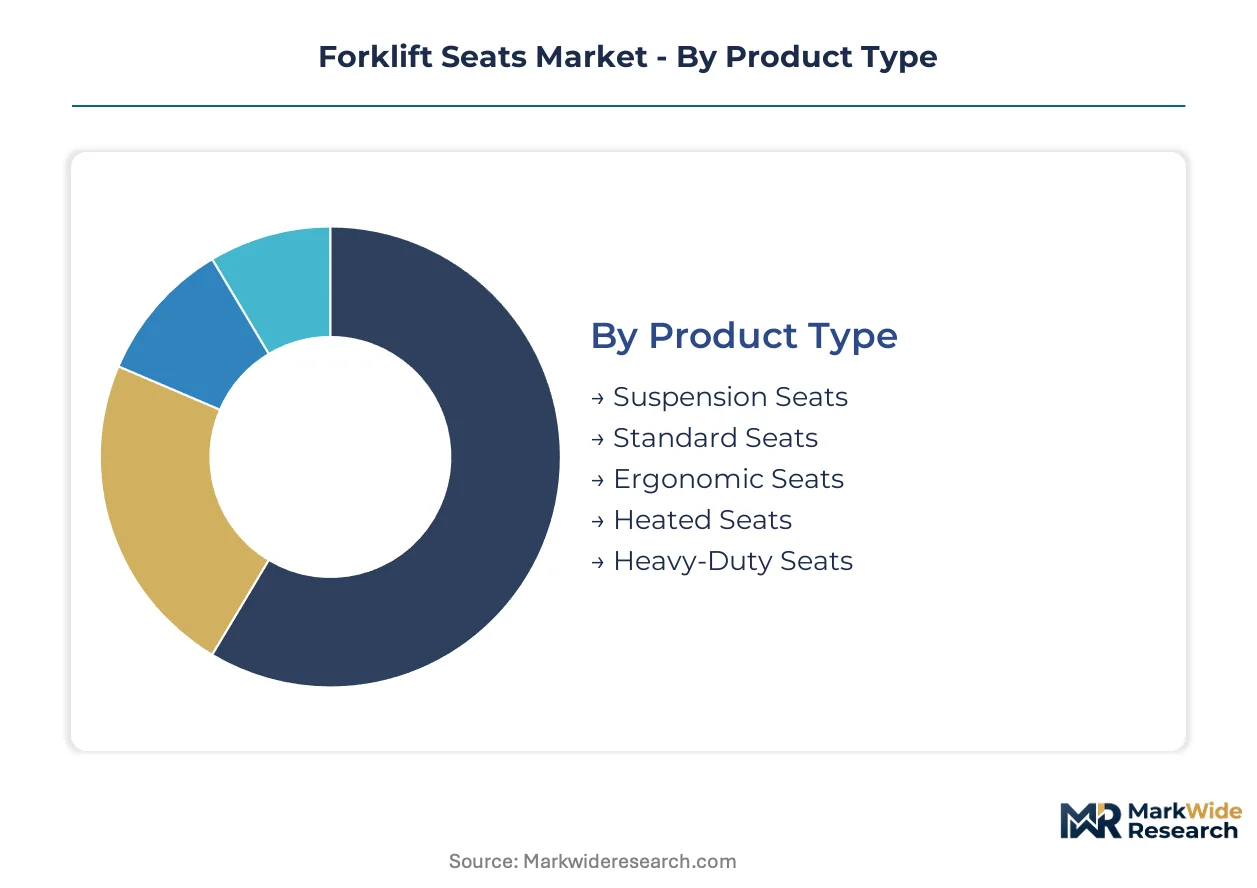
Forklift seat procurement patterns diverge sharply across regulatory environments and operational intensity levels. Understanding these segment boundaries clarifies where specification premiums materialize and where cost engineering dominates purchasing decisions.
Product Type:
OSHA workplace ergonomics enforcement and EU Machinery Directive vibration limits create divergent certification requirements across seat configurations, with CE-marked suspension systems commanding specification premiums in export-configured machines.
- Suspension Seats:Hydraulic or air-dampened pedestal systems isolate frequencies between 2 and 12 Hz, the range most associated with spinal compression injuries. German industrial truck OEMs specify these configurations for machines destined for EU regulatory jurisdictions where EN 13059 protocols apply.
- Standard Seats:Fixed foam cushioning on steel or composite frames retains procurement dominance in cost-sensitive emerging fleet segments. Base specifications predominate where OSHA inspection frequency remains low and operator turnover costs do not justify ergonomic premiums.
- Ergonomic Seats:Adjustable lumbar support mechanisms represent the fastest-expanding technology tier as warehousing employers address retention-driven operator wellness mandates in high-turnover distribution corridors.
- Heated Seats:Climate-controlled cushioning systems concentrate in cold-storage warehousing and outdoor construction applications where operator comfort directly impacts shift completion rates.
- Heavy-Duty Seats:Reinforced frame construction and extended-duty foam formulations serve port terminal and construction applications where 24-hour shift patterns accelerate wear cycles and replacement frequency.
Standard seats handle the majority of throughput; ergonomic seats are gaining share fastest on specification intensity in e-commerce fulfillment.
Technology:
Cost tier stratification separates integrated manufacturers with captive vibration engineering from regional fabricators dependent on outsourced suspension components.
- Hydraulic Suspension:Oil-dampened pedestal systems deliver consistent isolation performance across temperature variations. These configurations dominate outdoor construction and port applications where environmental conditions fluctuate.
- Mechanical Suspension:Spring-based isolation mechanisms occupy the mid-market price band where procurement balances durability concerns against capital expenditure constraints. Manufacturing plant fleets in the United States specify these for indoor duty cycles.
- Air Suspension:Pneumatic dampening systems enable real-time stiffness adjustment for operator weight variance. Scandinavian manufacturers sustain production scale across this technology tier for export markets.
- Vibration Dampening:Passive foam and elastomer formulations attenuate high-frequency transmission without active suspension mechanisms. These solutions serve electric forklift applications where smoother torque profiles reduce baseline vibration exposure.
- Adjustable Lumbar Support:Biomechanically engineered backrest mechanisms address operator retention in third-party logistics operations. California and Texas warehousing clusters concentrate procurement of these specifications where workers compensation costs drive ergonomic investment.
Mechanical suspension retains the largest installed base; air suspension is climbing the fastest on specification migration toward premium configurations.
Application:
Volume concentration follows e-commerce infrastructure buildout patterns, with shift duration and inspection intensity determining specification premiums.
- Warehousing:Multi-shift fulfillment operations drive suspension-equipped seating procurement to reduce operator fatigue. Extended shift patterns in automated distribution facilities accelerate replacement cycles regardless of physical wear.
- Manufacturing Plants:Integrated production environments specify seats matching facility-wide ergonomic standards. OSHA inspection frequency in United States automotive and electronics assembly plants compels proactive seating upgrades.
- Construction Sites:Outdoor duty cycles and irregular terrain exposure demand heavy-duty frame construction and weather-resistant cushioning formulations.
- Logistics Parks:Consolidated distribution infrastructure concentrates fleet procurement decisions among third-party operators with standardized specification protocols across multiple facilities.
- Ports & Terminals:24-hour operational requirements and container handling intensity create concentrated margin pools for manufacturers with extended-duty product lines.
Warehousing commands the largest specification volume; logistics parks are expanding most quickly on e-commerce fulfillment center construction.
End User:
Customer type determines procurement channel structure, with direct manufacturer relationships replacing dealer intermediaries in wellness-program-driven replacement cycles.
- Material Handling Companies:Fleet operators with captive maintenance capabilities unbundle seat replacement from complete truck refurbishment. These entities contract directly with seating manufacturers for volume procurement.
- Freight Operators:Cross-dock and line-haul logistics providers specify standardized configurations across mixed forklift fleets to simplify parts inventory and maintenance training.
- Industrial Contractors:Project-based procurement patterns favor rental fleet configurations where durability and theft resistance outweigh ergonomic premiums.
- Distribution Centers:E-commerce fulfillment operators in Germany and the United States specify suspension-equipped seating to reduce operator fatigue during extended shift patterns and address retention pressures.
Material handling companies direct the largest procurement volume; distribution centers are moving fastest on ergonomic specification adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-configured forklift seat procurement concentrates in manufacturing economies with established industrial truck OEMs. Import dependency shapes aftermarket dynamics in warehousing-intensive markets lacking domestic suspension engineering capabilities.
Germany
KBA vehicle safety protocols and EU Machinery Directive harmonization drive specification intensity for CE-marked seating. Industrial truck OEMs in Baden-Württemberg and Bavaria source Grammer AG and Be-Ge Group configurations for machines destined for regulated European jurisdictions. Stuttgart and Munich manufacturing clusters transmit these requirements through supply chains to component suppliers.
United States
OSHA powered industrial truck enforcement and California warehousing density accelerate ergonomic seat replacement cycles. Third-party logistics operators in the Inland Empire and Dallas-Fort Worth distribution corridors specify suspension-equipped seating to address workers compensation cost pressures. EPA emissions regulations indirectly shape demand through electric forklift penetration.
China
Domestic forklift production scale and GB standards compliance create volume demand for base specification seating. Yangtze River Delta manufacturing plants supply cost-optimized configurations for emerging fleet segments across Asia-Pacific. Shanghai and Suzhou industrial zones concentrate fabrication capacity for mechanical suspension tiers.
Japan
METI industrial productivity guidelines and aging workforce demographics elevate ergonomic investment in material handling operations. Toyota and Mitsubishi forklift specifications transmit JIS-compliant seating requirements through keiretsu supply structures. Nagoya and Osaka manufacturing clusters emphasize vibration dampening technologies for precision logistics applications.
India
PLI scheme incentives for material handling equipment and BIS safety standard adoption expand domestic seating demand. Maharashtra and Gujarat warehousing buildouts specify mid-tier mechanical suspension configurations as e-commerce fulfillment infrastructure scales. Mumbai-Pune industrial corridor concentrates procurement attention on cost-engineered durability specifications.
Forklift Seats Market Competitive Landscape
Concentration sits with integrated manufacturers possessing captive vibration engineering capabilities and automotive-derived suspension expertise. Regional fabricators without in-house testing infrastructure face margin compression from raw material volatility and extended certification timelines. Three archetypes dominate: full-line seating suppliers with multinational OEM relationships, Scandinavian specialists in air suspension systems, and North American aftermarket distributors with direct dealer networks. Competitive moves center on backward integration into foam formulation and strategic partnerships with electric forklift OEMs.
Among German-based integrated manufacturers, Grammer AG and Be-Ge Group exemplify the premium-tier archetype with export-market specification dominance. K&M Manufacturing anchors the North American aftermarket vector through material handling dealer channel consolidation. Commercial Vehicle Group occupies a position spanning automotive and industrial seating applications. These three entities represent the structural divide between vibration-engineering-intensive configurations and cost-optimized regional supply.
| Leading Market Players |
|---|
| Commercial Vehicle Group |
| Seat Industries |
| K&M Manufacturing |
| Tidd Ross Todd Limited |
| Be-Ge Group |
| Grammer AG |
| Sears Seating |
| Pilot Seats |
| Thomas Scott Seating Ltd |
| Others |
Supply & Pricing Matrix
Polyurethane foam substitution for legacy rubber cushioning simultaneously concentrates formulation expertise in Germany and compresses margin pools for regional fabricators lacking captive chemical engineering. This input shift reshapes procurement geography toward integrated manufacturers with in-house polymer development while pricing pressure intensifies across standard seat tiers dependent on spot-market resin purchases.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. CE-marked suspension configurations command premiums over base mechanical tiers due to EN 13059 certification costs and vibration testing infrastructure. Pricing pressure stems from steel and polyurethane input volatility squeezing regional fabricators without long-term supply agreements. Fleet operators in emerging markets exhibit highest price sensitivity, while German export-configured OEMs demonstrate lowest sensitivity due to specification-locked procurement protocols.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for suspension component imports into North American assembly operations. Manufacturing gravity centers on Germany, China, and the United States for frame fabrication and final seat assembly. Supply chains draw from specialized steel mills in Sweden, polyurethane chemical producers in Belgium, and vibration damper specialists in Japan. Single-source vulnerability concentrates in air suspension pedestal mechanisms sourced from Scandinavian engineering houses. Distribution runs through material handling dealer networks and direct OEM supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forklift seating sits at an early-cycle expansion story driven by ISO 2631-1 standard revision tailwinds accelerating replacement demand independent of physical wear cycles.
For Market Incumbents: Compound automotive-derived vibration engineering advantages through backward integration into foam formulation and captive suspension testing infrastructure. Defend specification dominance in German export markets by accelerating CE-marking validation cycles before EN 13059 harmonization tightens. Counter margin compression from steel input volatility through long-term offtake agreements with integrated chemical producers. For New Entrants and Emerging Players: Anchor in aftermarket direct distribution channels serving North American material handling dealers consolidating procurement through single-source distributors. Target mid-tier mechanical suspension white space in Indian warehousing buildouts where PLI scheme incentives expand domestic fleet procurement. Pursue operator wellness program partnerships with third-party logistics providers unbundling seat replacement from complete truck refurbishment. For Investors and Strategic Acquirers: The market sits at a technology-upgrade phase that favors integrated manufacturers with in-house biomechanical engineering and regulatory affairs infrastructure. Long-term viability across the projection horizon rests on acquisition targets possessing captive vibration testing capabilities and established OEM specification relationships. Monitor ISO 2631-1 exposure limit revision timing as the critical inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Formulation | REACH compliance and restricted substance validation secure CE-marking pathways for export-configured machines. |
| Air Suspension Technology Licensing | Pneumatic dampening expertise from Scandinavian manufacturers enables real-time stiffness adjustment specifications. |
| Direct Distribution Network Expansion | Channel consolidation with material handling dealers captures unbundled replacement procurement from fleet operators. |
| ISO 2631-1 Testing Infrastructure Investment | In-house whole-body vibration measurement capabilities accelerate certification timelines for regulatory revision readiness. |
| Electric Forklift OEM Partnership | Smoother torque profiles from EPA-driven electrification enable lighter, cost-optimized seat specifications. |
Research Methodology
Operator-level perspectives from fleet maintenance directors, OEM procurement teams, aftermarket service heads, and warehousing operations managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation from OSHA enforcement records, EU Machinery Directive harmonization documents, SEC filings of listed seating suppliers, and customs trade data on steel and polyurethane imports. Bottom-up seat replacement volume estimates triangulated against top-down industrial truck production forecasts.
Sensitivity analysis tested forecast robustness across alternative ISO 2631-1 revision scenarios and electric forklift penetration rates. The analytical framework modeled segmentation dimensions including suspension technology tier, application intensity level, end-user procurement channel, and regional regulatory cluster. CAGRs derived from replacement cycle compression analysis and specification migration patterns. Industry-specific inputs incorporated whole-body vibration exposure limit trajectories and e-commerce fulfillment center construction pipelines.
Material uncertainties — regulatory revision timing, raw material cost volatility, and trade lane disruption — sit outside the modeled envelope. Forecasts reflect documented assumptions about enforcement intensity and technology adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Bicycle Components Aftermarket Market
Vehicle Components
Sideloaders Market
Vehicle Components
Rear Axle Market
Vehicle Components
Snowplows Market
Vehicle Components
Bicycle Chain Market
Vehicle Components
Idler Arm Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
Transmission Components Market
Vehicle Components
Car Sunshade Market
Vehicle Components
South Africa Automotive Thermoplastic Polymer Composites Market
Vehicle Components
Steering Gear Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Trailer Canopy Market