
 Industrial Biocides Market | 2026-2036
Industrial Biocides Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Biocides Market Foresight
ISO 9001 certification is unwinding competitive access across the industrial biocides sector, raising barriers for new entrants lacking documented quality management systems. Ecolab Inc. leverages its integrated service model to anchor recurring revenue streams in water treatment applications. BASF SE sustains broad portfolio depth across synthetic and natural biocide chemistries. LANXESS AG specializes in halogenated biocide production, occupying defensible positions in cooling water and oilfield segments.
Industrial biocides comprise antimicrobial chemical formulations—typically isothiazolinones, quaternary ammonium compounds, or halogenated organics—engineered to inhibit microbial growth in process water, coatings, and preserved materials at concentrations between 50 and 1000 ppm active ingredient. Their primary industrial purpose centers on preventing biofouling, corrosion-induced microbial activity, and product spoilage across continuous manufacturing operations. Synthetic biocide technology dominates current value generation due to established efficacy profiles and predictable performance economics, while natural and hybrid formulations are gaining structural traction as REACH and BPR restrictions tighten on chloromethylisothiazolinone and other legacy actives. Water treatment chemicals command the largest application share, though coatings biocides carry superior margin profiles driven by architectural and industrial OEM specification requirements.
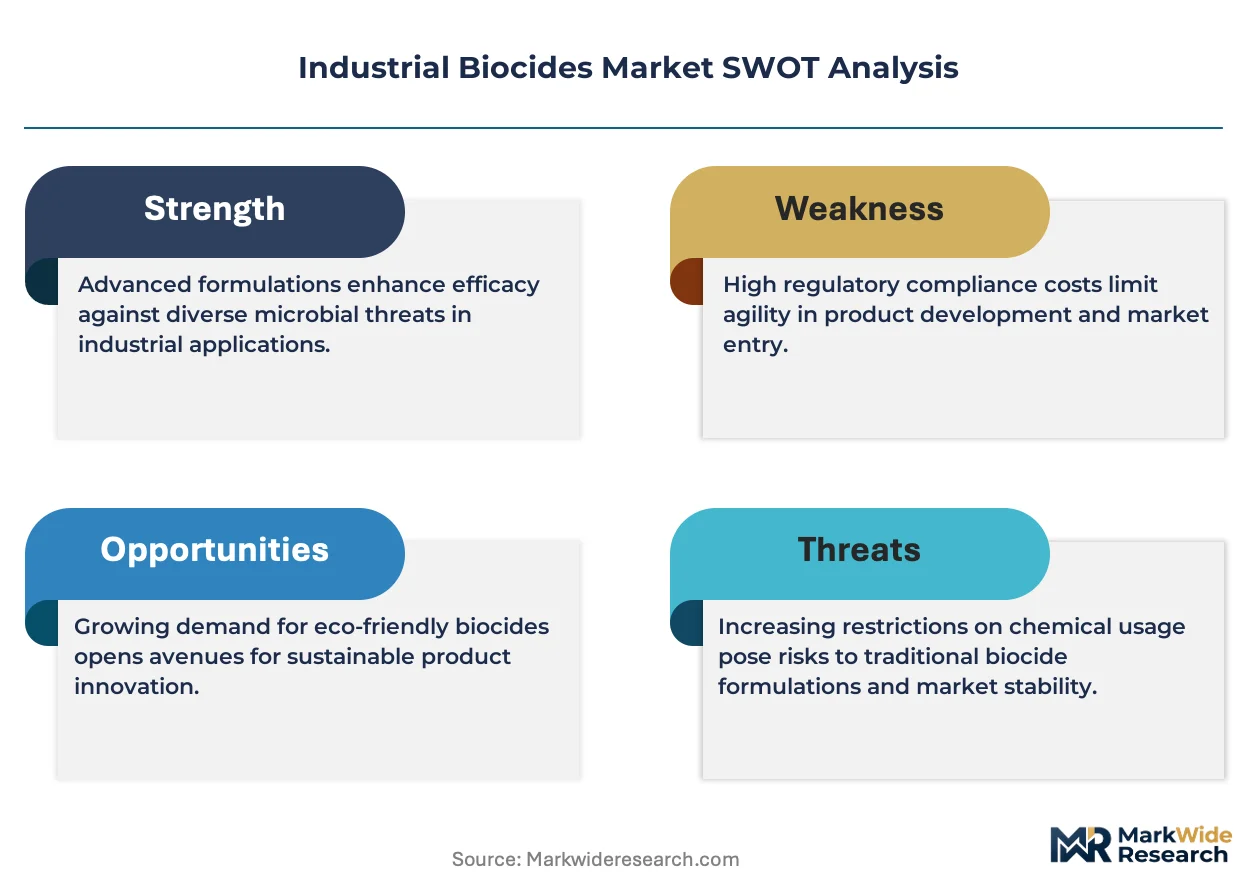
EPA registration under FIFRA and EU BPR authorization under Regulation 528/2012 govern active substance approval and product-level market access, forcing reformulation investments as substance evaluations progress. ECHA's biocidal products committee reviews are systematically excluding CMIT/MIT combinations from multiple product types, redirecting R&D expenditure toward compliant alternative chemistries. FDA oversight of food-contact biocide residues adds a parallel compliance layer for processors serving North American packaged goods channels. Stakeholders must monitor the trajectory of BPR substance approvals and EPA re-registration timelines to anticipate portfolio obsolescence risks and reposition technical resources accordingly.
Market Dynamics
ECHA's systematic exclusion of CMIT/MIT combinations from EU BPR product-type approvals is forcing wholesale reformulation across water treatment and coatings applications, compressing margins for legacy suppliers while opening technical white space for compliant alternatives.
Growth Catalysts
- EU BPR authorization timelines:Regulatory pressure is accelerating R&D investment in non-isothiazolinone chemistries as substance evaluations progress through ECHA's biocidal products committee.
- Municipal wastewater infrastructure:Tightening discharge standards across German, French, and Dutch treatment plants is expanding specification demand for high-performance halogenated biocides in secondary clarification systems.
- Cooling water systems:Power generation and petrochemical facilities are upgrading microbial control protocols to prevent biofouling-induced corrosion in heat exchange networks.
Market Restraints
- Active substance supply concentration:Chinese manufacturers dominate intermediate production for quaternary ammonium precursors, creating input vulnerability for European formulators.
- REACH registration costs:Full substance dossier preparation for novel biocidal actives requires €2-4 million per substance, excluding SME entrants from authorization pathways.
- Natural extract performance gaps:Plant-derived antimicrobial formulations exhibit inconsistent efficacy against sulfate-reducing bacteria in anaerobic oilfield environments.
Strategic Opportunities
- Hybrid biocide platforms:Convergence of synthetic actives with bio-based synergists offers pathway to maintain efficacy while reducing regulatory risk exposure.
- Food-contact packaging:FDA-compliant biocide incorporation into fiber-based packaging materials addresses microbial shelf-life concerns for fresh protein distribution.
- Digital dosing systems:Integration of real-time biofilm monitoring with automated feed controls creates service-based revenue attachment in industrial water treatment.
Industry Challenges
- Toxicology data generation:GLP-compliant chronic toxicity studies for BPR substance approval require 18-36 month timelines, delaying market entry for reformulated products.
- Cross-contamination protocols:Multi-product manufacturing facilities face validation complexity when switching between food-contact and industrial-grade biocide batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Biocides Market |
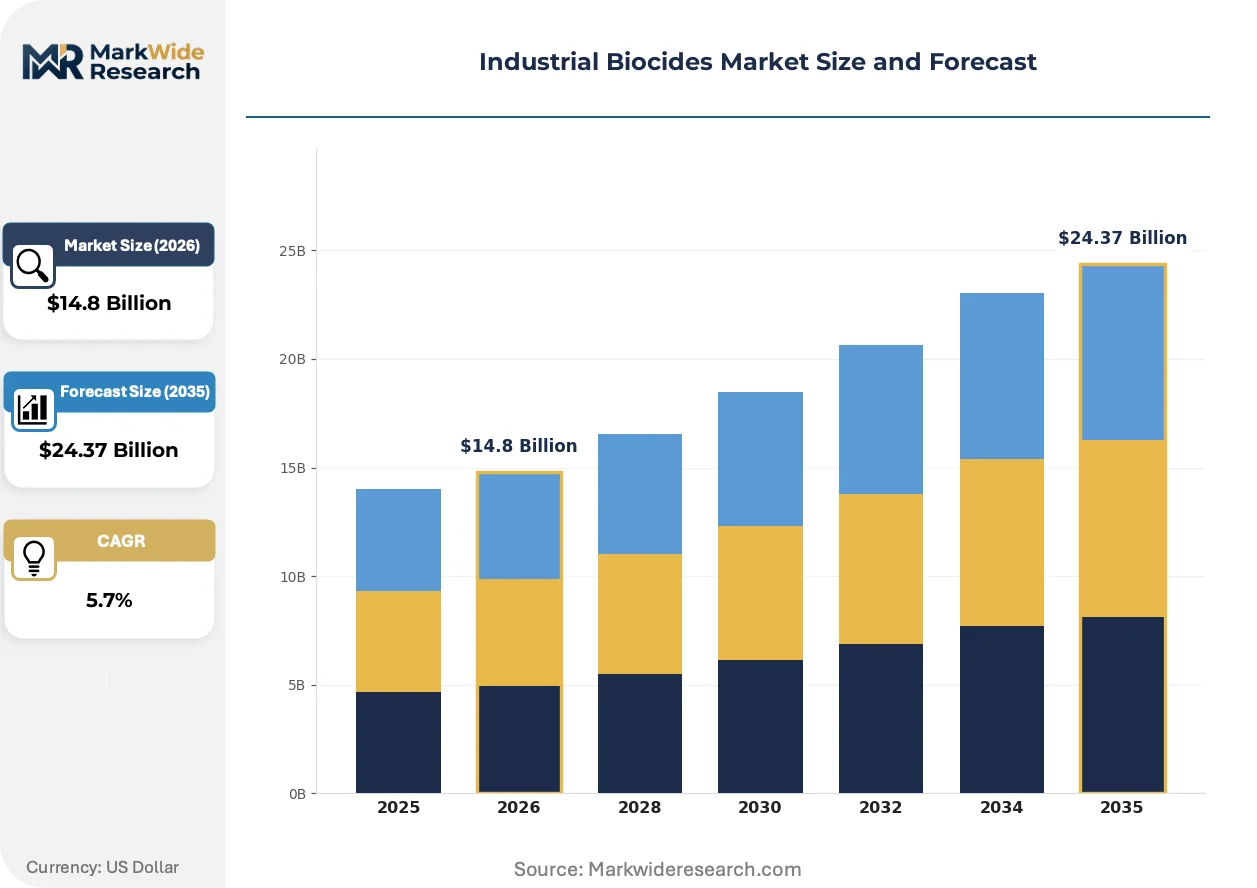
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Preservatives, Coatings, Water Treatment Chemicals, Adhesives Application: Food Processing, Oil & Gas, Wood Preservation, Textile Industry End User: Manufacturers, Construction, Energy Sector, Agriculture Technology: Biochemical, Synthetic, Natural, Hybrid |
| Companies Covered | Ecolab Inc., BASF SE, Solenis LLC, LANXESS AG, Nouryon, Kemira Oyj, DuPont de Nemours, Inc., Arxada AG, Troy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Biocides Market Shifts & Advancements
Reformulation imperatives are intersecting with digital process control and sustainability metrics to reshape how biocide value is delivered, measured, and contracted across industrial end-uses.
Encapsulated release technologies are decomposing traditional dosing paradigms in cooling water applications. Mining and pulp mill operators are adopting microencapsulated isothiazolinone formulations to extend active residence time and reduce feed frequency. This technology is decomposing the historical volume-based procurement model by enabling outcome-guaranteed supply contracts tied to microbial control performance rather than chemical throughput.
EPA's updated Ecological Hazard Assessment guidelines under FIFRA are elevating aquatic toxicity thresholds for new active substance registrations. Industrial laundries and oilfield service companies face expanded environmental fate testing requirements that extend registration timelines by 12-18 months. Cooling water treatment products containing halogenated organics are experiencing the most pronounced compliance cost inflation as EPA prioritizes persistent bioaccumulative substance screening.
Specification authority is migrating from plant engineers to corporate sustainability procurement functions with mandated Scope 3 emission tracking. Coatings manufacturers and building material producers now require full supply chain carbon disclosure for biocide inputs, favoring suppliers with verified LCA documentation. This shift is most advanced in German automotive OEM supply chains, where BASF and LANXESS have established preferred supplier status through certified environmental product declarations.
Industrial Biocides Market Segmentation
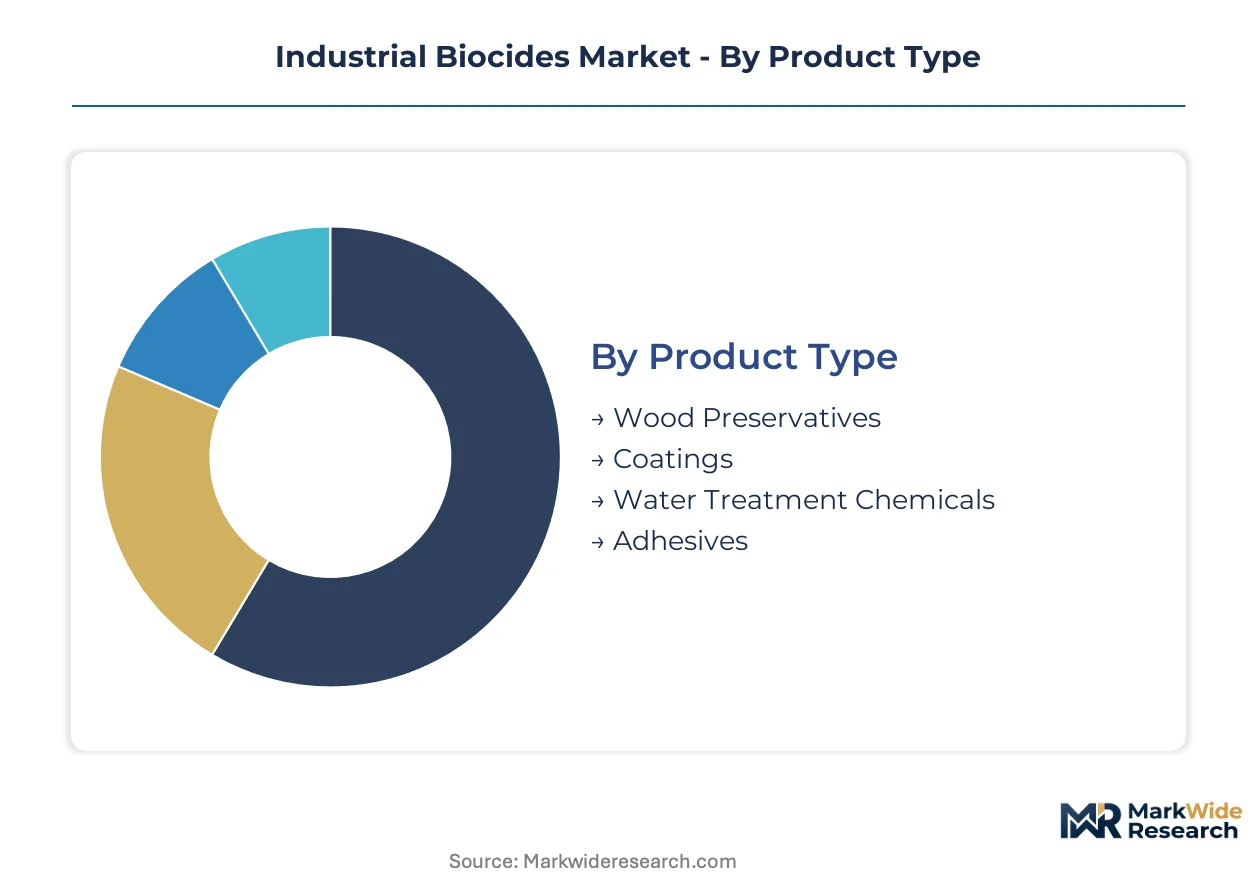
Industrial biocide procurement decisions split across functional chemistry, regulatory exposure, and end-use performance requirements. Formulators must align portfolio architecture with these intersecting dimensions to capture specification authority in high-margin applications.
Product Type:
Margin pools concentrate in coatings and water treatment chemicals where regulatory compliance creates pricing power for authorized suppliers.
- Water Treatment Chemicals:Halogenated organics and isothiazolinone formulations dominate cooling tower and municipal wastewater applications. German chemical manufacturing clusters and Dutch discharge enforcement drive premium pricing for EPA- and BPR-compliant solutions in secondary clarification systems.
- Coatings:Film-preserving biocides command superior margins through architectural and industrial OEM specification lock-in. Automotive OEM supply chains in Germany now mandate full supply chain carbon disclosure, favoring suppliers with verified LCA documentation.
- Wood Preservatives:Pressure-treatment applications for construction and utility poles rely on copper-azole and quaternary ammonium systems.
- Adhesives:In-can preservation for water-based formulations prevents spoilage during manufacturing and shelf storage.
The dominant share belongs to Water Treatment Chemicals, while Coatings is closing the gap fastest through sustainability-linked procurement mandates.
Application:
Volume concentration tracks industrial water intensity and microbial corrosion risk in capital-intensive process environments.
- Oil & Gas:Sulfate-reducing bacteria control in produced water and hydraulic fracturing fluids requires high-efficacy halogenated and quaternary ammonium biocides. North American shale basins and North Sea production platforms sustain demand despite natural extract performance gaps in anaerobic conditions.
- Food Processing:FDA-compliant biocide incorporation addresses microbial shelf-life concerns for fresh protein distribution in fiber-based packaging materials.
- Wood Preservation:Utility pole and marine piling treatments face pressure from alternative materials in European construction markets.
- Textile Industry:Antimicrobial finishing for technical textiles and apparel encounters REACH restriction scrutiny on durable biocide releases.
Oil & Gas retains the largest application footprint, though Food Processing is expanding most quickly through packaging integration opportunities.
End User:
Procurement sophistication varies sharply between consolidated energy majors and fragmented construction subcontractors.
- Energy Sector:Power generation and petrochemical facilities upgrade microbial control protocols to prevent biofouling-induced corrosion in heat exchange networks. Digital dosing systems with real-time biofilm monitoring create service-based revenue attachment opportunities.
- Manufacturers:Coatings and adhesives producers face specification migration from plant engineers to corporate sustainability functions with mandated Scope 3 emission tracking.
- Construction:Wood treatment demand correlates with residential and infrastructure investment cycles across European markets.
- Agriculture:Biocide use in irrigation systems and equipment sanitation remains constrained by runoff regulations and soil microbiome concerns.
Energy Sector end users command the dominant procurement volume, while Manufacturers are gaining specification influence fastest through supply chain disclosure requirements.
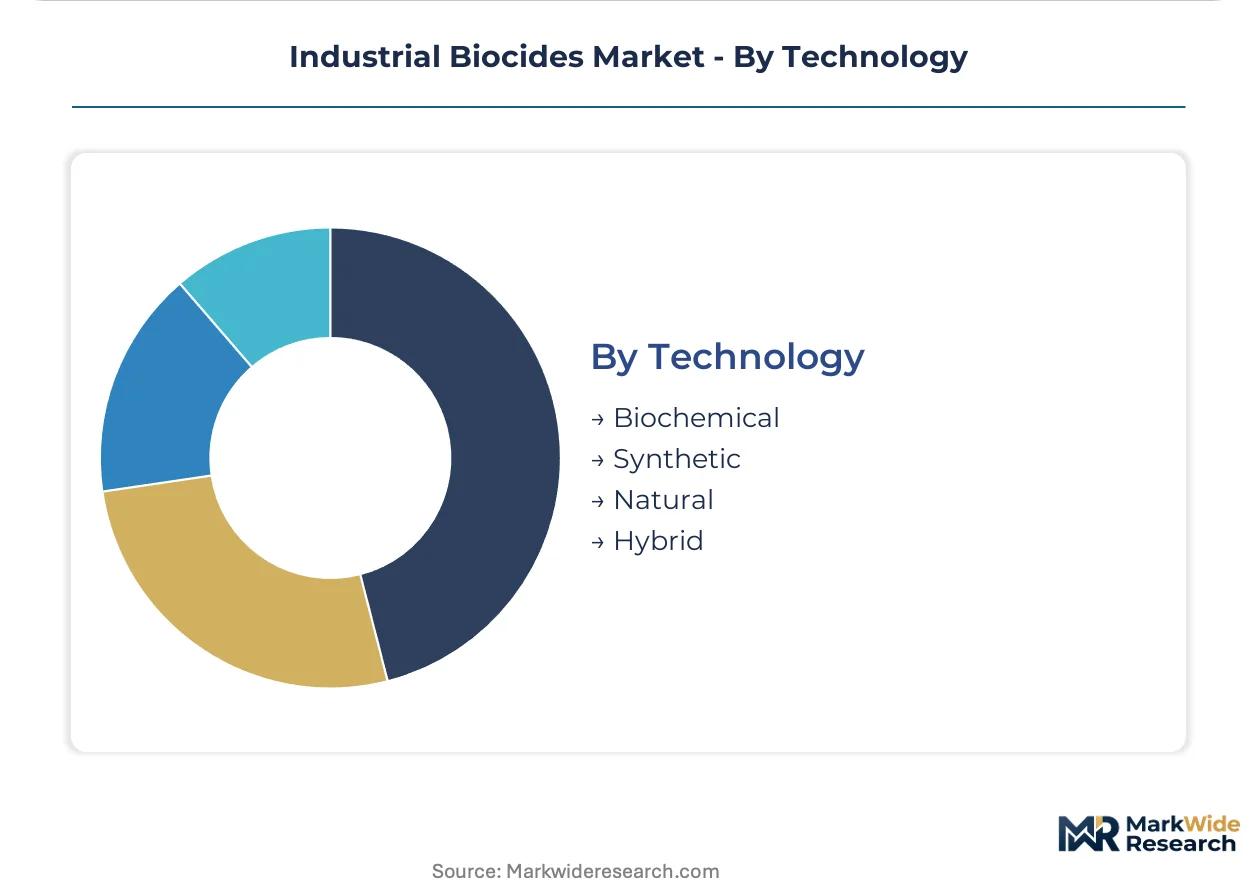
Technology:
Regulatory authorization timelines are restructuring competitive position across chemistry platforms.
- Synthetic:Established efficacy profiles and predictable performance economics sustain current value generation despite ECHA's systematic exclusion of CMIT/MIT combinations forcing wholesale reformulation.
- Hybrid:Convergence of synthetic actives with bio-based synergists offers pathway to maintain efficacy while reducing regulatory risk exposure in water treatment and coatings applications.
- Natural:Plant-derived antimicrobial formulations exhibit inconsistent efficacy against sulfate-reducing bacteria, limiting penetration in oilfield and heavy industrial settings.
- Biochemical:Enzyme-based and peptide approaches remain niche due to stability challenges in high-temperature process streams.
Synthetic technology holds the dominant position, while Hybrid platforms are climbing the fastest as reformulation imperatives accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical procurement teams in Germany, the United States, and China command the dominant specification authority for industrial biocide formulations. Their technical requirements cascade through global supply chains.
Germany
Cooling water treatment demand from BASF's Ludwigshafen complex and Bayer's Leverkusen operations sustains premium pricing for BPR-compliant halogenated biocides. ECHA substance evaluations systematically exclude CMIT/MIT combinations from product-type approvals. The Rhine-Ruhr chemical corridor concentrates reformulation R&D investment as legacy suppliers pivot toward hybrid chemistries.
United States
EPA FIFRA re-registration timelines for oilfield biocides drive procurement uncertainty across Permian Basin operators and Gulf Coast refineries. The agency's updated Ecological Hazard Assessment guidelines elevate aquatic toxicity thresholds for new active substances. Houston's energy sector procurement offices now mandate 18-24 month supply security commitments from authorized suppliers.
China
Quaternary ammonium intermediate production clusters in Jiangsu and Shandong provinces supply European formulators with concentrated input vulnerability. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emissions standards at biocide manufacturing facilities. The Yangtze River Delta water treatment chemical sector faces capacity consolidation as smaller producers exit under environmental compliance costs.
Netherlands
Municipal wastewater discharge enforcement in Rotterdam and Amsterdam treatment plants expands specification demand for high-performance halogenated biocides. The national implementation of EU BPR authorization requirements redirects procurement toward fully compliant suppliers. The Port of Rotterdam's industrial water treatment cluster serves as a testing ground for digital dosing system integration.
India
Textile finishing mills in Gujarat and Tamil Nadu encounter REACH-equivalent scrutiny on durable biocide releases under BIS chemical safety guidelines. Central Pollution Control Board tightening of effluent standards for dyeing operations creates specification openings for compliant antimicrobial formulations. The Surat textile cluster represents the fastest-growing demand node for water treatment biocides in South Asia.
Industrial Biocides Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive raw material positions and specialized water treatment service providers. The vendor base separates into three functional tiers: multinational diversified chemical producers controlling upstream active substance synthesis, mid-cap formulation specialists with regional authorization depth, and equipment-integrated service operators capturing recurring revenue through dosing system contracts. Consolidation pressure concentrates among authorization-heavy European suppliers facing synchronized BPR compliance deadlines. Competitive positioning hardens around regulatory dossier ownership and validated toxicology data packages rather than manufacturing scale alone.
Among diversified chemical conglomerates, BASF SE and LANXESS AG exemplify the integrated archetype with broad synthetic biocide portfolios spanning multiple product types under BPR authorization. Ecolab Inc. occupies a distinct service-integrated position where chemical supply attaches to equipment monitoring and performance-guaranteed contracts. These three entities anchor the competitive structure by representing the dominant strategic models: upstream-integrated chemistry control, regulatory authorization depth, and outcome-based service bundling.
| Leading Market Players |
|---|
| Ecolab Inc. |
| BASF SE |
| Solenis LLC |
| LANXESS AG |
| Nouryon |
| Kemira Oyj |
| DuPont de Nemours, Inc. |
| Arxada AG |
| Troy Corporation |
| Others |
Supply & Pricing Matrix
Hybrid biocide formulation substitution for legacy isothiazolinone chemistries simultaneously shifts intermediate sourcing from Chinese quaternary ammonium clusters toward European specialty chemical producers and compresses margin structures as reformulation R&D costs embed into contract pricing. This substitution dynamic redistributes value capture upstream while forcing downstream formulators to absorb compliance-driven cost inflation.
Pricing Analysis
Cost-plus contracts with ethylene and propylene indexation dominate halogenated biocide procurement in German chemical manufacturing clusters. Three-tier pricing structure across BPR-authorized premium, REACH-registered standard, and transitional economy tiers separates compliant suppliers from authorization-lagged competitors. Pricing pressure stems from ECHA's CMIT/MIT exclusion timeline accelerating as dual-registered alternatives command scarcity premiums. Municipal wastewater treatment plants exhibit highest price sensitivity due to budget-constrained procurement cycles, while automotive OEM coatings specifications show lowest sensitivity given performance-guaranteed outcome contracts.
Supply Chain Analysis
Jiangsu and Shandong province intermediate production clusters in China constitute the dominant chokepoint for European quaternary ammonium biocide formulators. Active substance synthesis draws from bromine extraction in Israel, chlorine alkali output in Germany, and amine intermediates from BASF's Ludwigshafen complex. Single-source vulnerability concentrates in Chinese quaternary ammonium precursor supply, exposing European formulators to MEE environmental enforcement disruptions. Distribution runs through authorized distributor networks with BPR dossier custody requirements, supplemented by direct mill supply relationships in Rotterdam's port industrial cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against natural extract and biochemical platform encroachment as regulatory pressure on synthetic actives creates temporary white space for alternative chemistries.
For Market Incumbents: Compound regulatory authorization depth with hybrid chemistry R&D investment to deflect natural biocide substitution threats in water treatment applications. BASF and LANXESS should extend BPR dossier ownership into adjacent product types while accelerating captive amine intermediate production to reduce Chinese supply dependency. Certification investment in ISO 9001 quality management systems raises competitive barriers against emerging hybrid platform specialists. For New Entrants and Emerging Players: Anchor in food-contact packaging biocide applications where FDA compliance requirements and sustainability procurement mandates create specification openings underserved by legacy oilfield-focused incumbents. The most penetrable segment lies in fiber-based fresh protein distribution materials, where microbial shelf-life concerns intersect with Scope 3 carbon disclosure requirements. A go-to-market angle through certified environmental product declarations targets German automotive OEM supply chain migration. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap formulation specialists with regional BPR authorization depth and validated toxicology data packages rather than manufacturing scale alone. Long-term viability across the analysis window hinges on regulatory dossier ownership as synchronized compliance deadlines concentrate competitive position. The signal to watch is ECHA substance evaluation acceleration timelines as inflection indicators for portfolio obsolescence risk and M&A pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Intermediates | BASF's Ludwigshafen complex reduces Chinese quaternary ammonium supply vulnerability for European formulators. |
| BPR Authorization Expansion | LANXESS extends halogenated biocide approvals into additional product types ahead of CMIT/MIT exclusion deadlines. |
| Hybrid Platform Development | Convergence of synthetic actives with bio-based synergists addresses REACH restriction pressure while maintaining efficacy. |
| Digital Dosing System Integration | Ecolab attaches recurring service revenue to real-time biofilm monitoring in Rotterdam's industrial water treatment cluster. |
| Food-Contact Compliance Investment | FDA-compliant biocide incorporation opens fiber-based packaging specifications for fresh protein distribution channels. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plant managers at German chemical manufacturing facilities, ECHA regulatory affairs specialists, municipal wastewater procurement leads, and coatings R&D directors; and secondary validation through customs trade data, Cefic sector reports, SEC 10-K filings, and BPR authorization databases. Bottom-up volume triangulation across water treatment, coatings, and preservation applications converged with top-down value estimates derived from active substance pricing indices and formulation cost structures.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning synthetic-hybrid-natural technology tiers, water treatment versus coatings versus preservation end-uses, and German-Dutch-US-China regional production clusters. CAGRs were derived from installed base growth in cooling water systems, municipal infrastructure investment cycles, and regulatory-driven reformulation velocity. Industry-specific forecast inputs incorporated ECHA substance evaluation timelines and EPA FIFRA re-registration progressions.
Material uncertainties — ECHA acceleration of CMIT/MIT exclusions, MEE enforcement intensity in Chinese intermediate production, and automotive OEM sustainability procurement mandate adoption rates — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as BPR authorization timelines and dual-carbon policy implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
India Thermic Fluid Market
Industrial Chemicals
Global Molluscicides Market
Industrial Chemicals
Chlorine Market
Industrial Chemicals
Rust Preventive Oil Market
Industrial Chemicals
Butadiene Extraction Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Tallow Fatty Acid Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Asia Pacific Rotomoulding Powder Market
Industrial Chemicals
Flame-Retardant Phosphate Esters for EV E-Drivetrains Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market
Industrial Chemicals
Rotomolding Powder Market