
 Rotomolding Powder Market | 2026-2036
Rotomolding Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Rotomolding Powder Market Analytics
China is reconfiguring regional supply dynamics through new polyethylene compounding facilities serving rotomolding compounders. BASF leverages its European R&D footprint to sustain technology leadership in UV-stabilized powder grades for outdoor tanks. LyondellBasell anchors North American supply through integrated polyolefin production and direct-to-molder distribution channels. Dow competes on material science breadth, extending its resin portfolio into specialty linear low-density grades optimized for rotational molding cycle times.
Rotomolding powder consists of finely ground thermoplastic resins, predominantly polyethylene with melt flow indices between 2 and 10 g/10min, formulated for hollow-part fabrication without internal stress. The material transforms inside a heated biaxially-rotated mold, producing seamless tanks, toys, and industrial housings with uniform wall thickness and zero weld lines. PE grades dominate volume due to their processability and chemical resistance, though nylon powders command premium positioning in industrial components requiring elevated temperature performance. Advanced rotomolding technology is displacing conventional methods as IoT-enabled thermal monitoring reduces cycle variability and scrap rates in tank production. Automated systems represent the fastest-growing technology segment as labor cost pressures intensify across manufacturing clusters.
EPA regulations on chemical storage containment and REACH substance restrictions are elevating compliance costs for powder formulations across US and European supply chains. China's SAMR enforces GB standards for plastic chemical resistance that filter non-certified imports from Southeast Asian traders. ISO 9001 quality management and ISO 14001 environmental certification function as baseline market access credentials for compounders supplying automotive and marine end users. Stakeholders must evaluate backward integration into resin production versus specialty compounding partnerships as feedstock volatility reshapes margin structures.
Market Dynamics
Marine vessel operators are systematically replacing metal buoyancy tanks with rotomolded polyethylene alternatives, compressing procurement cycles and redirecting powder specifications toward certified chemical-resistant grades.
Growth Catalysts
- EPA Containment Mandates:Chemical storage regulations in the United States are mandating double-wall tank construction, expanding specification volumes for rotomolded powder in industrial applications.
- Marine Lightweighting:Fuel efficiency requirements are accelerating adoption of polyethylene buoyancy tanks across commercial fishing and recreational vessel fleets.
- IoT Thermal Monitoring:Sensor-integrated molding systems are reducing scrap rates in tank production, improving powder yield economics for compounders.
Market Restraints
- Polyethylene Feedstock Volatility:Ethylene monomer price swings are compressing compounding margins and destabilizing long-term supply agreements.
- REACH Substance Restrictions:European chemical regulations are limiting additive formulations and forcing costly reformulation of UV-stabilized grades.
- Metal Fabrication Cost Competition:Steel tank prices in Southeast Asia are undercutting rotomolded alternatives in non-regulated storage applications.
Strategic Opportunities
- India Infrastructure Buildout:Water storage tank demand under the country's rural sanitation programs is creating new specification channels for certified powder grades.
- Automated Molding Convergence:Integration of robotic demolding with IoT process control is opening premium service contracts for technical powder supply.
- China GB Certification Arbitrage:Tightened SAMR standards are filtering uncertified imports and creating protected market space for compliant compounders.
Industry Challenges
- Rotational Molding Technician Scarcity:Skilled operator shortages in Vietnam and Indonesia are constraining capacity utilization at relocated manufacturing facilities.
- ISO 14001 Compliance Timelines:Environmental certification requirements for automotive and marine suppliers are extending qualification periods by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotomolding Powder Market |
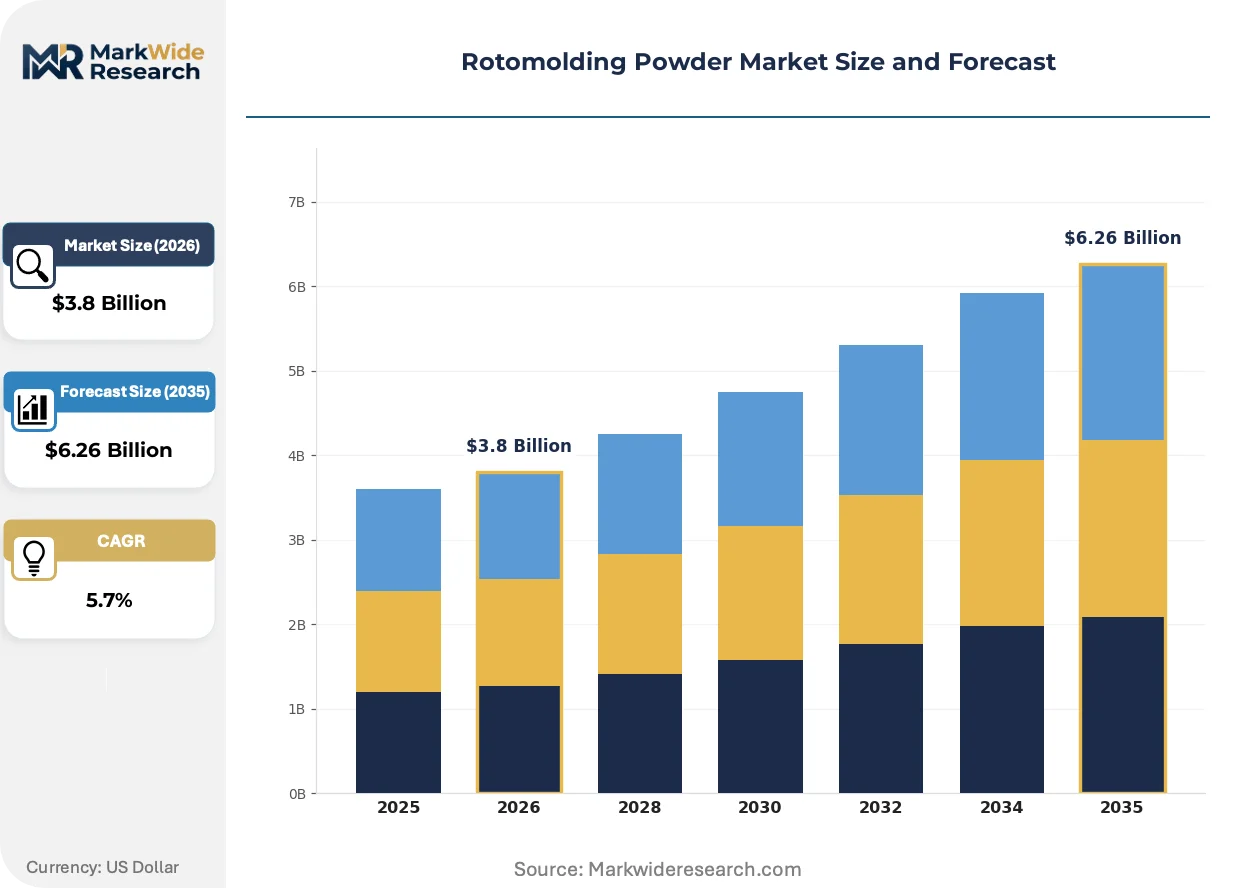
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PE, PVC, Nylon, Others Application: Automotive Parts, Industrial Components, Toys, Tanks Technology: Conventional Rotomolding, Advanced Rotomolding, Internet of Things Integration, Automated Systems End User: Aerospace, Construction, Healthcare, Marine |
| Companies Covered | BASF, LyondellBasell, Dow, ExxonMobil Chemical, Chevron Phillips Chemical, SABIC, Reliance Industries, INEOS Group, Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotomolding Powder Market Evolving Landscape
Process automation and material science advances are compressing cycle times while regulatory chemical restrictions are reshaping formulation portfolios across supply chains.
Hybrid polyethylene-nylon powder blends are hybridizing rotomolding applications by delivering elevated temperature performance in industrial housings. Automotive underhood component manufacturers are piloting these materials at accelerated qualification schedules. The technology is hybridizing the traditional split between commodity tank production and engineering-grade industrial applications.
REACH substance restrictions are systematically eliminating certain phthalate-based additives from European powder formulations. Compounders are reformulating UV stabilizer packages to maintain performance thresholds under tightened ECHA guidelines. Marine and outdoor tank segments in Germany and France are absorbing the highest compliance costs while accelerating alternative additive adoption.
Direct-to-molder distribution channels are displacing traditional regional distributor networks in North American supply chains. Large tank fabricators are consolidating procurement through integrated polyolefin producers, compressing intermediary margins. This pattern is most pronounced in Texas and Ohio manufacturing clusters where captive resin supply anchors volume pricing leverage.
Rotomolding Powder Market Segmentation
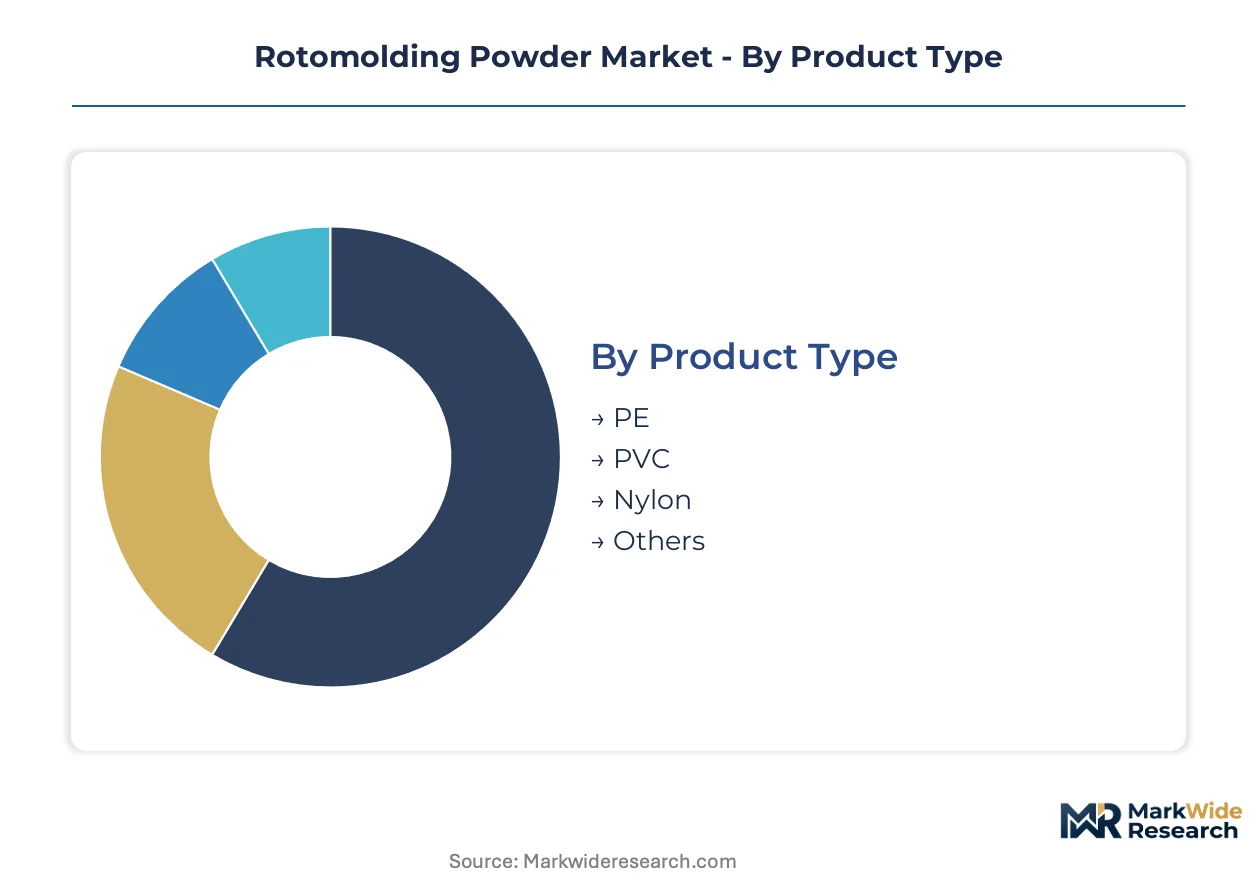
Rotomolding powder specifications diverge sharply across end-use requirements, with marine and automotive sectors demanding certified chemical resistance while toy manufacturers prioritize process consistency over performance grades. Technology choices separate commodity producers from premium compounders as IoT-enabled systems compress cycle variability.
Product Type:
Cost tier determines formulation complexity and margin structure across the four material categories, with commodity grades anchoring volume and engineering polymers capturing premium positioning.
- PE:Linear low-density and crosslinked polyethylene grades dominate tonnage, formulated with melt flow indices between 2 and 10 g/10min for optimal hollow-part fabrication. Marine buoyancy tank fabricators in the United States and Southeast Asia are consolidating procurement around UV-stabilized PE grades certified to EPA containment mandates.
- Nylon:Polyamide powders command price premiums through elevated temperature performance in industrial housings and underhood automotive components. German automotive suppliers are accelerating qualification schedules for hybrid PE-nylon blends as REACH substance restrictions eliminate legacy phthalate-based formulations.
- PVC:Specialized grades serve chemical-resistant applications requiring rigid wall structures and flame-retardant properties in industrial tank construction.
- Others:Specialty thermoplastics including polycarbonate and EVA copolymers address niche medical device and flexible toy segments with distinct processing windows.
PE holds installed capacity. Nylon is rotating up the share rankings.
Application:
Application focus reveals divergent specification intensity, with regulated storage and transportation segments demanding certified grades while consumer goods prioritize throughput economics.
- Tanks:Industrial and agricultural storage vessels represent the most specification-intensive segment, requiring double-wall construction under EPA containment mandates and GB standard chemical resistance certification for Chinese market access. Texas and Ohio manufacturing clusters are consolidating procurement through direct-to-molder channels with integrated polyolefin producers.
- Automotive Parts:Fuel tanks, air ducts, and underhood housings require heat-resistant formulations with dimensional stability across thermal cycling. Japanese automotive Tier-1 suppliers are piloting automated molding convergence with robotic demolding to reduce labor dependency in component fabrication.
- Industrial Components:Housings, enclosures, and material handling equipment utilize hybrid material approaches blending commodity processability with engineering-grade performance.
- Toys:Recreational products and playground equipment emphasize rotational consistency and color stability over mechanical performance, with Vietnamese and Indonesian manufacturers absorbing fastest capacity additions from relocation trends.
Tank applications anchor specification revenue. Automotive parts are expanding most quickly through electrification-driven underhood redesign.
Technology:
Technology maturity separates established process methods from emerging automation platforms that compress labor content and scrap rates.
- Automated Systems:Robotic demolding integrated with sensor-integrated thermal monitoring represents the steepest expansion trajectory, reducing cycle variability and enabling premium service contracts for technical powder supply. Labor cost pressures in Vietnam and Indonesia are accelerating adoption despite skilled technician scarcity constraining utilization rates.
- Internet of Things Integration:Real-time mold temperature profiling and predictive maintenance algorithms are displacing conventional operator-dependent process control in high-volume tank production.
- Advanced Rotomolding:Modified heating profiles and mold materials optimize cycle times for engineering-grade powders in industrial component applications.
- Conventional Rotomolding:Established biaxial rotation methods persist in toy and simple tank fabrication where capital constraints limit automation investment.
Conventional rotomolding holds installed capacity. Automated systems are climbing the fastest through labor substitution economics.
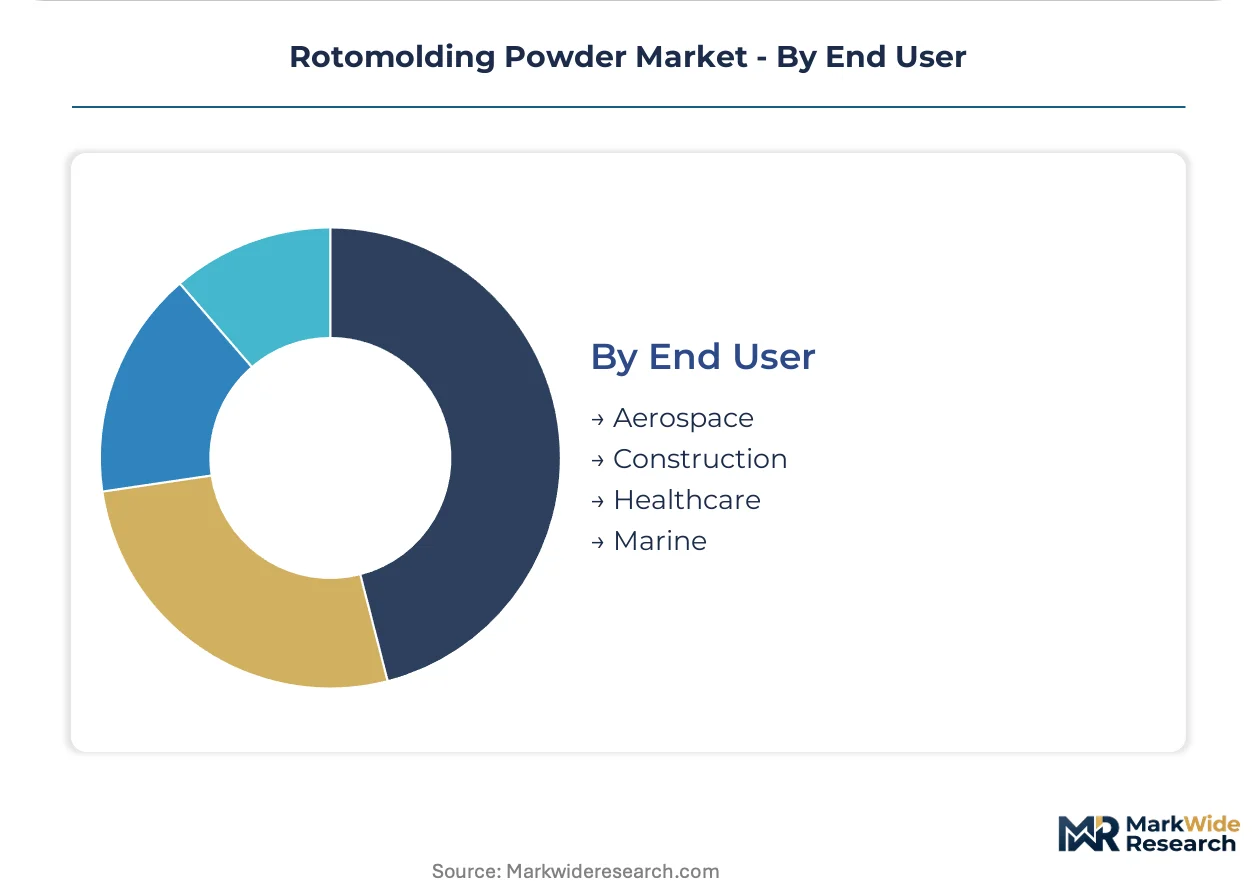
End User:
End-user concentration maps regulatory exposure and certification requirements, with marine and aerospace segments demanding highest compliance rigor.
- Marine:Commercial fishing and recreational vessel operators are systematically replacing metal buoyancy tanks with rotomolded polyethylene alternatives to capture fuel efficiency gains. US and European fleets are compressing procurement cycles toward certified chemical-resistant grades as lightweighting mandates intensify.
- Construction:Water storage infrastructure under India's rural sanitation programs is creating specification channels for certified powder grades with BIS compliance credentials.
- Aerospace:Interior components and fuel system housings require flame-retardant formulations meeting FAA certification standards with traceable material documentation.
- Healthcare:Medical device housings and pharmaceutical storage vessels demand cleanroom-compatible processing with FDA-validated material streams.
Marine holds installed capacity. Construction is gaining share fastest through infrastructure buildout programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel anchors North American polyethylene supply chains, channeling Gulf Coast resin production toward rotomolding compounders serving tank manufacturers across Texas and Ohio industrial clusters.
United States
EPA containment mandates for chemical storage are expanding double-wall tank procurement through Texas and Ohio manufacturing clusters. LyondellBasell anchors North American supply through integrated polyolefin production with direct-to-molder distribution channels. Marine vessel operators in Louisiana and Florida are compressing procurement cycles toward certified chemical-resistant grades as lightweighting mandates intensify.
China
Polyethylene compounding facilities along the Yangtze River Delta are reconfiguring regional supply dynamics for rotomolding compounders. SAMR-enforced GB standards for plastic chemical resistance are filtering non-certified imports from Southeast Asian traders. Zhejiang and Jiangsu province manufacturers are absorbing fastest capacity additions as tank and toy producers consolidate procurement around certified powder grades.
Germany
REACH substance restrictions are eliminating phthalate-based additives from powder formulations across Bavaria and North Rhine-Westphalia industrial zones. ECHA guidelines are forcing costly reformulation of UV-stabilized grades for outdoor tank segments. BASF leverages its Ludwigshafen R&D footprint to sustain technology leadership in compliant powder grades serving marine and automotive underhood applications.
India
Rural sanitation programs under national infrastructure buildout are creating specification channels for certified powder grades in water storage tank applications. BIS compliance credentials function as baseline market access requirements for compounders supplying construction end users. Gujarat and Maharashtra manufacturing clusters are absorbing capacity additions as tank fabricators consolidate procurement toward certified suppliers.
Vietnam
Relocated toy and tank manufacturers from higher-cost bases are driving fastest capacity additions across Southeast Asian supply chains. Skilled rotational molding technician scarcity is constraining utilization rates at relocated facilities despite labor cost advantages. Ho Chi Minh City and Hanoi industrial zones are absorbing automation investments as IoT-enabled thermal monitoring systems reduce cycle variability.
Rotomolding Powder Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The rotomolding powder market structures around integrated polyolefin producers with captive resin supply, specialty compounders with formulation expertise, and regional distributors facing margin compression. Three archetypes dominate: scale-driven resin-integrated suppliers, technology-focused specialty compounders, and logistics-anchored regional distributors. Competitive moves concentrate on backward integration into resin production and direct-to-molder channel expansion.
Among European-based chemical conglomerates, BASF and INEOS Group exemplify the technology-focused specialty compounder archetype with R&D-intensive positioning in UV-stabilized formulations. Dow occupies a position within the scale-driven resin-integrated tier, extending material science breadth into specialty linear low-density grades. These three companies represent divergent strategic postures across the competitive spectrum, anchoring commentary on how formulation expertise versus captive supply shapes market access.
| Leading Market Players |
|---|
| BASF |
| LyondellBasell |
| Dow |
| ExxonMobil Chemical |
| Chevron Phillips Chemical |
| SABIC |
| Reliance Industries |
| INEOS Group |
| Clariant |
| Others |
Value Network & Pricing Analysis
Gulf Coast ethylene cracker concentration in Texas and Louisiana anchors polyethylene resin supply, directing margin capture toward integrated polyolefin producers with captive feedstock access while forcing compounders toward specialty formulation differentiation.
Pricing Analysis
EPA containment mandates dictate the pricing tier structure across rotomolding powder grades, separating certified double-wall tank formulations from commodity buoyancy applications. Three-tier pricing structure across premium certified, standard industrial, and economy toy-grade levels reflects ISO 14001 compliance costs and UV-stabilizer package complexity. Cost compression in economy grades is intensifying because Vietnamese manufacturers are consolidating procurement volumes. Tank fabricators in Texas and Ohio show least price sensitivity due to regulatory liability exposure, while Indonesian toy producers absorb highest price elasticity.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian trading partners dominates supply chain risk assessment for rotomolding powder flows. Manufacturing concentration centers on China, Vietnam, and the United States, with polyethylene resin feeds from Gulf Coast crackers and Yangtze River Delta compounding facilities. Raw material dependencies rest on ethylene monomer, UV stabilizer additives, and color masterbatch supply. Single-source vulnerability runs through Chinese SAMR-certified additive suppliers. Distribution runs through direct-to-molder channels displacing traditional regional distributors in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large tank fabricators in Texas and Ohio, compressing intermediary margins and forcing compounders toward technical service differentiation or backward integration into resin production.
For Market Incumbents: Pre-empt margin erosion from direct-to-molder channel consolidation by deepening captive resin supply relationships with Gulf Coast producers. Secure SAMR GB certification ahead of tightened Chinese import standards to filter uncertified Southeast Asian competitors. Prioritize automated molding convergence partnerships that lock in premium technical service contracts. For New Entrants and Emerging Players: Establish a beachhead in India's rural sanitation water storage segment where BIS compliance credentials function as baseline market access barriers. Target Gujarat and Maharashtra manufacturing clusters with certified powder grades ahead of infrastructure buildout peak demand. Lead with technical powder supply bundled with IoT thermal monitoring integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty compounders holding formulation expertise but lacking captive resin supply. Five-to-ten-year viability hinges on feedstock volatility management and regulatory compliance scalability. Watch for SAMR enforcement intensity as inflection indicator for Chinese market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive ethylene supply from Gulf Coast crackers secures margin control against monomer volatility. |
| GB Certification Investment | SAMR compliance opens protected market space in Zhejiang and Jiangsu province manufacturing clusters. |
| Automated Molding Partnership | IoT thermal monitoring integration reduces scrap rates for Vietnamese tank fabricators facing technician scarcity. |
| Direct-to-Molder Channel Expansion | Bypassing regional distributors captures intermediary margins in Texas and Ohio consolidation zones. |
| Hybrid PE-Nylon Formulation Development | REACH-compliant UV stabilizer packages access German automotive underhood qualification schedules. |
Research Methodology
Cross-validation between primary interviews with rotomolding plant managers, procurement leads at tank OEMs, distribution channel partners, and technical R&D directors anchors the qualitative findings. Secondary validation draws from customs/trade data, ACC industry reports, SEC 10-K filings of integrated polyolefin producers, and SAMR regulatory bulletins. Bottom-up segment sizing triangulates against top-down resin consumption estimates across the analysis window.
Calibration against historical polyethylene price cycles and rotomolding equipment installation rates shapes the analytical framework. Segmentation dimensions span material grade tier, end-use application intensity, technology automation level, and regional production hub classification. CAGRs derive from fitted trend extrapolation moderated by regulatory phase-in schedules and capacity addition timelines. Forecast inputs incorporate ethylene cracker operating rates and marine vessel lightweighting adoption curves.
Stress conditions across ethylene monomer price bands, SAMR enforcement intensity, and REACH additive restriction scope were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about infrastructure program continuity and trade flow stability. Material shifts in Chinese import certification requirements or EPA containment mandate expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
Blown Oils Market
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
Diesel Exhaust Fluid Market
Industrial Chemicals
Toluene Diisocyanates (TDI) Market
Industrial Chemicals
Permethrin Market
Industrial Chemicals
Adblue Market
Industrial Chemicals
General Industrial Oils Market
Industrial Chemicals
Silicates Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Powder Coating Guns Market
Industrial Chemicals
Global Industrial Separators Market
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Global Desalting and Buffer Exchange Market
Industrial Chemicals
Babassu Oil Market
Industrial Chemicals
2,3-Butanediol Market