
 Rust Preventive Oil Market | 2026-2036
Rust Preventive Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Rust Preventive Oil Market Analytics
The EU Green Deal's industrial emissions targets is broadening demand for bio-based and water-based rust preventive formulations across European metalworking. Shell plc leverages its integrated base oil supply chain to sustain cost advantages in synthetic formulations. FUCHS Group anchors its position through specialized corrosion inhibitor R&D for automotive stamping operations. Cortec Corporation differentiates via vapor-phase corrosion inhibitor technology that reduces post-application cleaning requirements.
Rust preventive oil denotes a surface-active fluid formulated with mineral or synthetic base stocks, corrosion inhibitors, and film-forming agents that deposit a protective barrier against moisture and oxygen on ferrous and non-ferrous metals. These formulations typically achieve salt spray resistance of 500–2,000 hours per ASTM B117 and serve primarily to eliminate oxidation-related rejects during storage, transit, and inter-process manufacturing. Oil-based products retain dominance in heavy industrial equipment applications where extended outdoor exposure demands thick, tenacious films, while bio-based segments gain traction as vegetable oil derivatives achieve parity in biodegradability metrics without sacrificing humidity cabinet performance. Water-based dilutable concentrates capture expanding share in automotive body-in-white operations where low-residue requirements and wastewater compliance dominate procurement criteria.
REACH registration requirements and the EU F-Gas Regulation constrain formulation chemistry choices for suppliers accessing European industrial markets, while EPA toxicity reduction mandates under the Toxic Substances Control Act shape product development priorities for US-facing manufacturers. India's BIS corrosion protection standards and China's GB/T rust prevention specifications create divergent compliance thresholds that fragment product portfolios across export destinations. Stakeholders must monitor evolving biocide restrictions under the EU Biocidal Products Regulation and assess backward integration into additive chemistry to preserve margin pools as regulatory complexity intensifies.
Market Dynamics
REACH restrictions on volatile organic compounds are forcing automotive OEMs across Europe to abandon solvent-based formulations, while solvent-free and water-based alternatives capture procurement share in steel processing and precision component manufacturing clusters.
Growth Catalysts
- REACH VOC limits:European automotive stamping operations now mandate low-emission rust preventive oils, accelerating solvent-free formulation adoption across Germany, France, and Italy.
- Precision component exports:Indian and Southeast Asian manufacturing hubs require high-performance corrosion protection for steel destined for European and North American markets.
- Water-based concentrates:Body-in-white operations favor dilutable formulations that reduce residue and simplify wastewater compliance.
Market Restraints
- Base oil price volatility:Mineral and synthetic feedstock costs fluctuate with crude oil markets, compressing formulation margins for mid-tier suppliers.
- Biocide restrictions:EU Biocidal Products Regulation compliance timelines extend product registration cycles and raise R&D overhead.
- Performance parity gaps:Bio-based vegetable oil derivatives still trail petroleum-based products in salt spray resistance for heavy outdoor equipment applications.
Strategic Opportunities
- India BIS standards expansion:Domestic corrosion protection certification requirements create localized formulation demand for steel processing in Gujarat and Maharashtra.
- Vapor-phase inhibitor integration:VpCI technology reduces post-application cleaning costs, opening automotive and electronics assembly applications.
- EU Green Deal industrial emissions targets:Bio-based and water-based formulations qualify for preferential procurement scoring in public tenders.
Industry Challenges
- Corrosion inhibitor chemistry talent:Formulation chemists with expertise in film-forming agents and additive synergies remain scarce across European and North American R&D centers.
- Multi-jurisdiction registration:Separate compliance pathways for EPA Toxic Substances Control Act, REACH, and China's GB/T specifications fragment product portfolios and extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rust Preventive Oil Market |
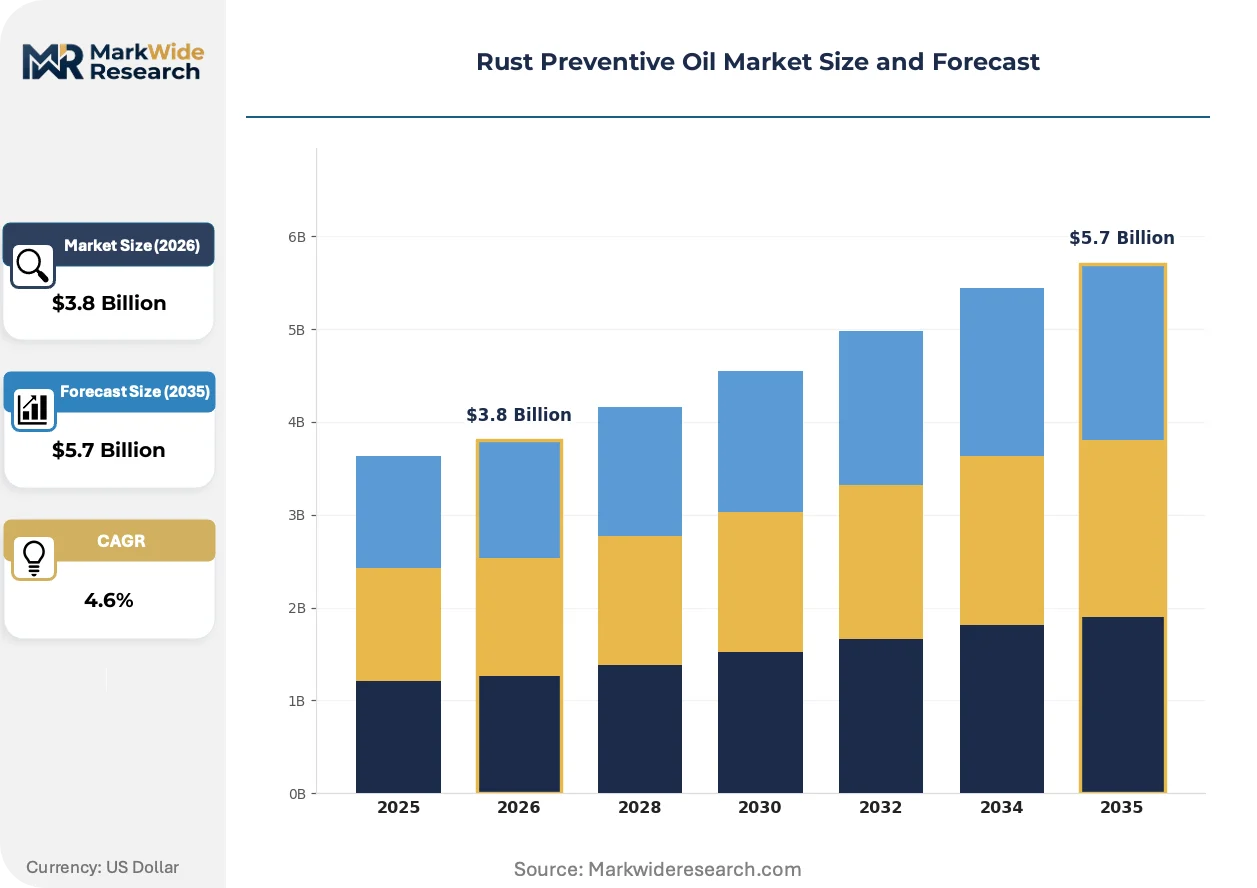
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Based, Water-Based, Bio-Based, Synthetic Application: Automotive, Marine, Industrial Equipment, Household Ingredient Type: Mineral Oil, Vegetable Oil, Additives, Metal Soaps Packaging Type: Drum, Bottle, Can, Sachet |
| Companies Covered | Houghton International, Ashland Global Holdings, WD-40 Company, Shell plc, Cortec Corporation, FUCHS Group, The Lubrizol Corporation, ExxonMobil Corporation, Quaker Houghton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rust Preventive Oil Market Evolving Landscape
Formulation chemistry is pivoting toward bio-derived and water-based systems as regulatory pressure intersects with automotive sector demand for low-residue protection. Three developments are restructuring competitive positioning.
Solvent-free synthetic formulations are consolidating market share in European automotive OEM supply chains. These products achieve 1,000+ hour salt spray resistance without volatile organic compound emissions. German and French stamping operations now specify solvent-free systems exclusively, compressing demand for traditional mineral oil-based alternatives.
EU F-Gas Regulation and Biocidal Products Registration requirements are constraining additive chemistry choices for suppliers accessing European industrial markets. Formulators must substitute legacy biocides and film-forming agents with compliant alternatives, extending development cycles. Water-based concentrate suppliers are responding by backward integrating into corrosion inhibitor synthesis to preserve formulation control.
Automotive procurement departments are bundling rust preventive oil specifications with broader metalworking fluid contracts, reducing supplier counts. Tier-1 component manufacturers now demand single-source accountability for stamping, cleaning, and protection chemistries. This concentration is most visible in German and Japanese automotive supply chains, where OEMs audit formulation consistency across multi-plant networks.
Rust Preventive Oil Market Segmentation
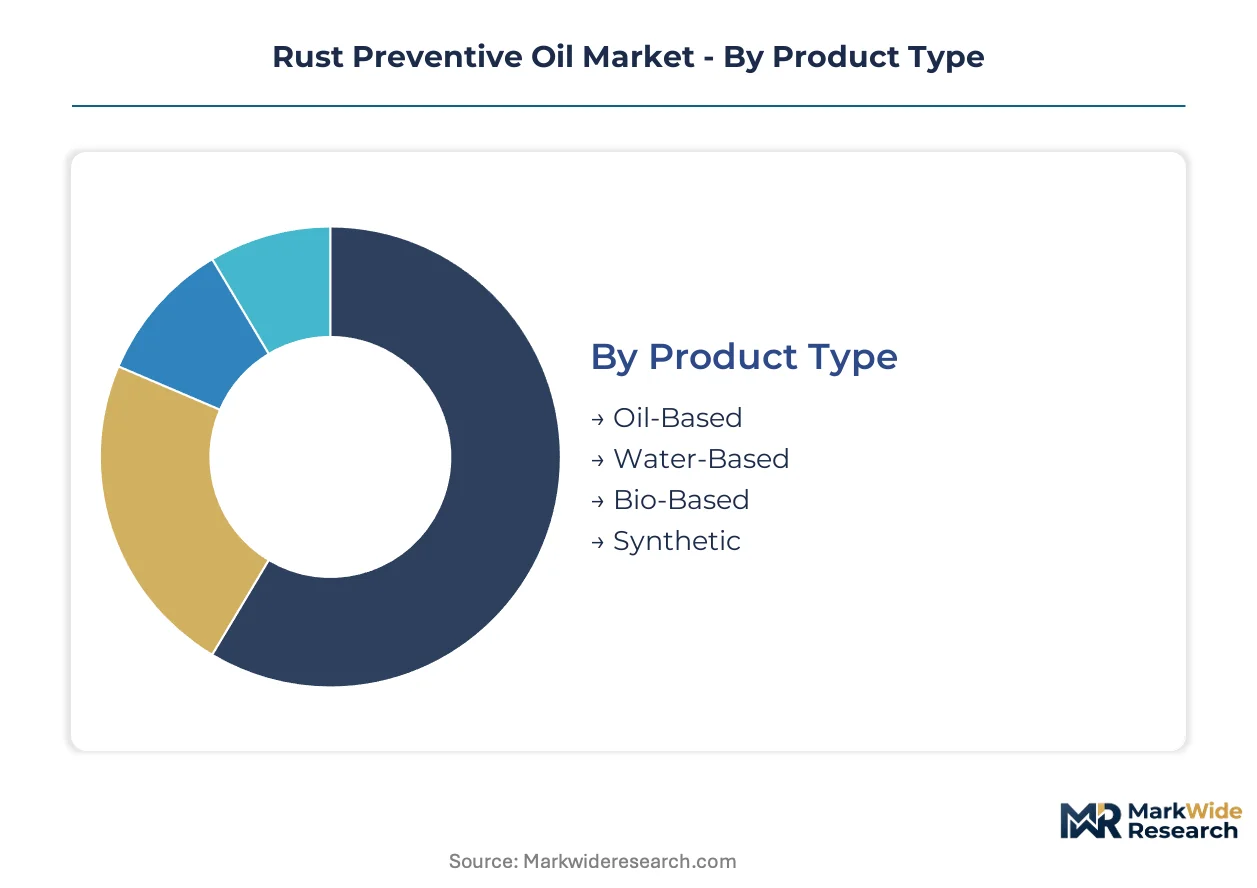
Rust preventive oil procurement diverges sharply across end-use contexts, with automotive OEMs, steel processors, and precision component exporters each imposing distinct performance thresholds and compliance burdens. Segmentation reveals how formulation chemistry, application environment, and packaging economics fragment supplier strategies across industrial, marine, and consumer channels.
Product Type:
Oil-based formulations require REACH registration for mineral base stocks and corrosion inhibitor packages, while bio-based and water-based alternatives face separate EFSA and EPA toxicity evaluations depending on export destination.
- Oil-Based:Mineral or synthetic base stocks blended with film-forming agents deliver 1,000–2,000 hour salt spray resistance per ASTM B117. Heavy equipment manufacturers in Germany and outdoor machinery producers in the US specify these for extended exposure protection despite VOC compliance costs.
- Water-Based:Dilutable concentrates with low-residue profiles dominate automotive body-in-white operations in France and Italy, where wastewater discharge limits under EU Industrial Emissions Directive constrain solvent alternatives. REACH biocide restrictions extend registration timelines for these formulations.
- Bio-Based:Vegetable oil derivatives achieve biodegradability parity with petroleum-based products in humidity cabinet testing. Demand concentrates in European public tenders where EU Green Deal procurement scoring rewards renewable content.
- Synthetic:Engineered base stocks with customized additive packages serve precision component exports from Indian manufacturing clusters to North American markets, meeting dual compliance with BIS corrosion standards and customer-specific salt spray protocols.
Leading the category by volume: Oil-Based. Expanding most quickly: Water-Based.
Application:
Application segments separate by corrosion severity, cleaning requirements, and regulatory exposure — automotive and marine buyers impose the most stringent film residue and environmental discharge standards.
- Automotive:Stamping operations and body-in-white protection demand solvent-free or water-based formulations with rapid evaporation and minimal post-process cleaning. German and Japanese OEM supply chains now audit formulation consistency across multi-plant supplier networks.
- Marine:Salt-laden environments require thick, tenacious films with 1,500+ hour salt spray resistance. Offshore equipment servicing hubs in Norway and Louisiana prioritize corrosion inhibitor packages that withstand tidal exposure and temperature cycling.
- Industrial Equipment:Steel processing in Gujarat and Maharashtra relies on high-performance oils meeting BIS certification for intermediate storage and export transit protection.
- Household:Small-format packaging for tool maintenance and DIY applications favors convenience over extended protection, with sachet and bottle formats dominating retail channels.
Automotive generates the highest formulation R&D investment. Marine commands the steepest performance premiums.
Ingredient Type:
Raw material sourcing strategies diverge by margin structure — mineral oil dependence ties margins to crude volatility, while additive backward integration preserves formulation control.
- Mineral Oil:Petroleum-derived base stocks remain cost-advantaged for heavy industrial applications. Price volatility in crude markets compresses margins for mid-tier suppliers without captive refining capacity.
- Vegetable Oil:Rapeseed and palm derivatives supply bio-based segments, with sustainability certification requirements from European automotive OEMs driving procurement specifications.
- Additives:Corrosion inhibitors, biocides, and film-forming agents face constrained chemistry choices under EU Biocidal Products Regulation and EPA Toxic Substances Control Act. Formulators with in-house additive synthesis gain registration timeline advantages.
- Metal Soaps:Barium, calcium, and lithium soaps provide film tenacity in oil-based formulations, with REACH restrictions on heavy metal content shifting demand toward calcium complexes.
Additives capture the highest value share per liter. Vegetable oil derivatives are climbing fastest on sustainability-linked procurement.
Packaging Type:
Packaging economics scale with volume concentration — drum formats dominate industrial procurement, while consumer and precision applications fragment toward smaller units.
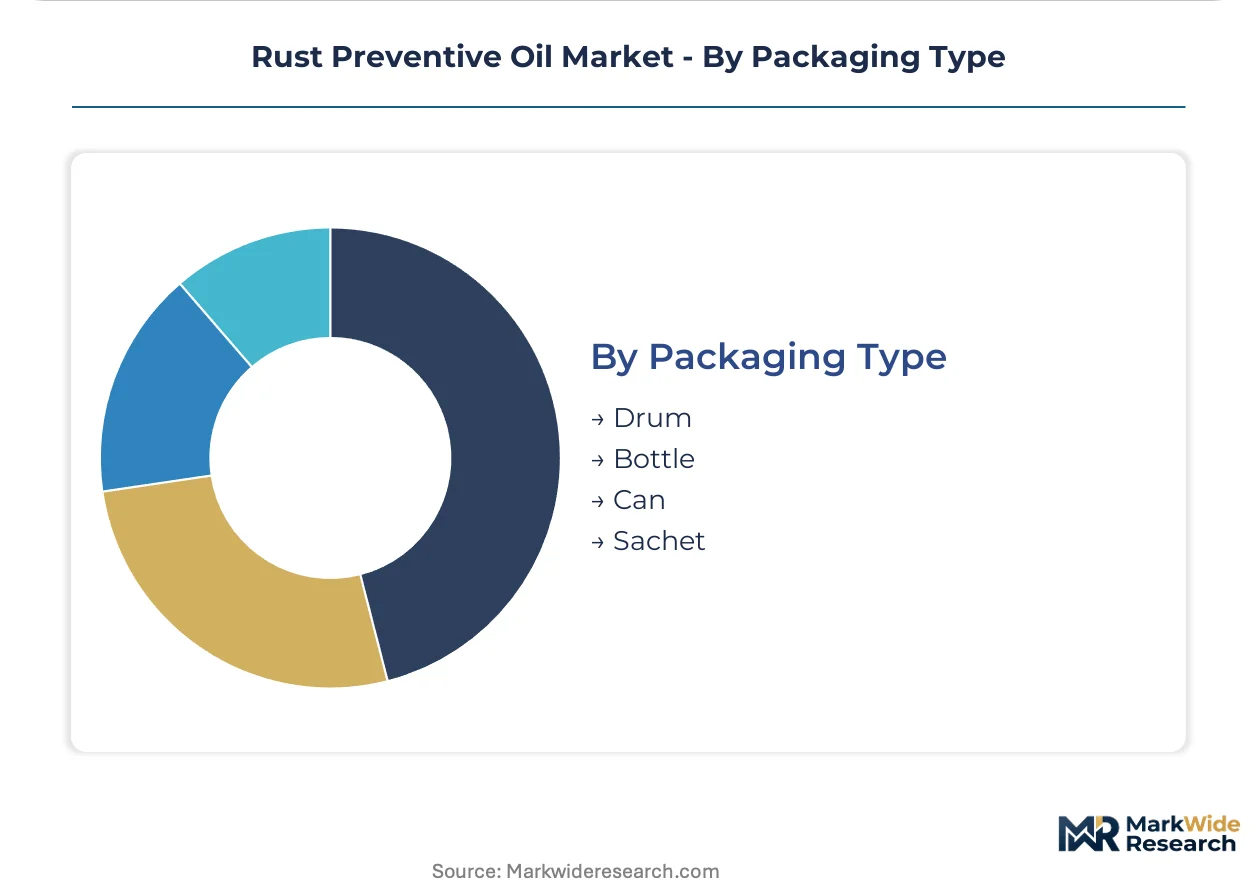
- Drum:200-liter steel and polymer drums serve steel mills, automotive stamping plants, and marine equipment yards in high-volume, centralized application settings.
- Bottle:1–5 liter containers target maintenance workshops and precision component manufacturers requiring controlled dispensing for small-batch protection.
- Can:Aerosol and pressurized formats enable targeted application in automotive repair and electronics assembly where vapor-phase corrosion inhibitor integration reduces cleaning costs.
- Sachet:Single-use packets serve export packaging for precision components and consumer retail, with Cortec Corporation's VpCI technology differentiating through embedded vapor-phase protection.
Drum formats lead by volume. Sachet formats are gaining share fastest in precision component export packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany, the United States, and China, while consumption concentrates in European automotive stamping corridors and Indian steel export zones. This geographic split shapes formulation chemistry requirements and compliance burdens across supplier networks.
Germany
Automotive OEM stamping operations in Stuttgart and Wolfsburg drive solvent-free formulation procurement as REACH VOC limits tighten. The EU F-Gas Regulation constrains corrosion inhibitor chemistry choices for suppliers serving Bavarian and Baden-Württemberg manufacturing clusters. Steel processors in the Ruhr region now specify bio-based alternatives for intermediate storage protection.
United States
EPA Toxic Substances Control Act mandates reshape product development priorities for rust preventive oil manufacturers targeting Detroit automotive suppliers and Gulf Coast marine equipment yards. Offshore servicing hubs in Louisiana demand thick-film formulations with extended salt spray resistance for tidal exposure protection. Midwest steel mills concentrate procurement of mineral oil-based products for heavy industrial applications.
China
GB/T rust prevention specifications create divergent compliance thresholds that fragment export-bound product portfolios. Yangtze River Delta precision component manufacturers require high-performance protection for steel destined for European and North American markets. The country's national environmental regulator enforces dual carbon goals that accelerate water-based concentrate adoption in Shanghai and Jiangsu stamping plants.
India
BIS corrosion protection standards expansion creates localized formulation demand for steel processing in Gujarat and Maharashtra manufacturing corridors. Precision component exporters in Pune and Ahmedabad require high-performance rust preventive oils meeting dual compliance with domestic certification and customer-specific salt spray protocols. The Directorate General of Foreign Trade monitors import substitution trends in specialty chemical formulations.
Japan
METI industrial emissions guidelines favor low-residue water-based formulations in Nagoya and Toyota City automotive body-in-white operations. JIS standards compliance remains mandatory for suppliers integrated into Japanese OEM supply chains. Kansai region steel processors specify synthetic formulations for precision component export protection.
Rust Preventive Oil Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical majors and specialized additive formulators. Market concentration remains moderate, with top-tier suppliers commanding automotive OEM contracts while mid-tier players serve steel processing and industrial equipment segments. Two strategic archetypes dominate: backward-integrated base oil producers with captive additive synthesis, and technology-focused specialists with proprietary corrosion inhibitor packages. Capacity expansion and geographic licensing agreements represent the primary competitive moves as suppliers seek to defray multi-jurisdiction registration costs.
Among integrated petrochemical majors, Shell plc and ExxonMobil Corporation anchor the scale-driven tier through captive base oil supply chains that sustain cost advantages in synthetic formulations. FUCHS Group occupies a specialist position exemplifying the R&D-intensive archetype focused on automotive stamping chemistry. Cortec Corporation represents the technology-differentiated segment through vapor-phase corrosion inhibitor expertise that reduces post-application cleaning requirements for precision component and electronics assembly applications.
| Leading Market Players |
|---|
| Houghton International |
| Ashland Global Holdings |
| WD-40 Company |
| Shell plc |
| Cortec Corporation |
| FUCHS Group |
| The Lubrizol Corporation |
| ExxonMobil Corporation |
| Quaker Houghton |
| Others |
Value Network & Pricing Analysis
Captive additive synthesis by integrated petrochemical majors anchors both supply security and pricing power in rust preventive oil markets, with Shell plc and ExxonMobil Corporation leveraging backward integration into corrosion inhibitor chemistry to buffer margin compression from volatile mineral oil feedstock costs. This structural concentration allows scale-driven suppliers to sustain cost advantages in synthetic formulations while mid-tier formulators absorb base oil price volatility without equivalent formulation control.
Pricing Analysis
Margin tightening in mid-tier supplier segments reflects crude oil price volatility and REACH registration cost burdens that scale-driven competitors defray through captive base oil production. Three-tier pricing structure across premium synthetic, standard mineral oil, and economy bio-based levels separates automotive OEM contracts from steel processing procurement. Cost-down pressure on water-based concentrates accelerates as automotive body-in-white operations consolidate metalworking fluid contracts. Steel processors in Gujarat and Maharashtra exhibit highest price sensitivity; German automotive stamping operations prioritize solvent-free certification over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore coordinate hub-and-spoke delivery patterns for drum-format industrial procurement while precision component exporters rely on direct sachet shipments. Manufacturing concentrates in Germany, the United States, and China, with Yangtze River Delta facilities serving export-bound formulations. Formulation draws from mineral oil, vegetable oil derivatives, and corrosion inhibitor packages, with biocide restrictions under EU Biocidal Products Regulation creating single-source vulnerability for compliant additive supply. Distribution runs through authorized chemical distributors serving automotive OEMs and steel mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rust preventive oil supply is tightening around corrosion inhibitor chemistry talent scarcity and multi-jurisdiction registration bottlenecks, propping pricing power for integrated formulators with captive additive synthesis capabilities.
For Market Incumbents: Lock in automotive OEM supply chain consolidation gains by bundling stamping, cleaning, and protection chemistries under single-source contracts. Defend against bio-based displacement by accelerating solvent-free synthetic formulation R&D for salt spray parity. Prioritize backward integration into corrosion inhibitor chemistry to preserve margin pools as EU Biocidal Products Regulation compliance timelines extend.
For New Entrants and Emerging Players: Capture white-space opportunity in India BIS-certified formulations for Gujarat and Maharashtra steel processing corridors. Target vapor-phase corrosion inhibitor integration for precision component export packaging where Cortec Corporation's technology dominance remains penetrable. Pursue licensing agreements with established distributors to defray REACH and EPA registration costs.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated petrochemical majors seeking additive synthesis capabilities and regional formulation assets. Long-term viability favors suppliers with corrosion inhibitor R&D depth and multi-plant OEM audit compliance. Watch for EU Green Deal procurement scoring shifts as inflection indicator for bio-based formulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Synthesis | Captive corrosion inhibitor production preserves margin pools under REACH biocide restrictions. |
| Water-Based Concentrate Capacity Expansion | Low-residue formulations capture automotive body-in-white procurement in France and Italy. |
| Vapor-Phase Inhibitor Technology Licensing | VpCI integration reduces post-application cleaning costs for electronics assembly customers. |
| Regional Distribution Hub Establishment | Rotterdam and Singapore centers serve steel processing and marine equipment clusters. |
| Bio-Based Formulation Certification Investment | EU Green Deal procurement scoring rewards renewable content in public tenders. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving formulation chemists, automotive OEM procurement directors, steel mill technical managers, and chemical distribution channel partners. ECHA REACH registrations, EPA Toxic Substances Control Act submissions, and BIS certification databases provided compliance pathway validation. Bottom-up volume estimates triangulated against top-down petrochemical feedstock consumption trends.
Reconciliation of production capacity disclosures, import-export flows, and end-use consumption surveys informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, application severity class, packaging format scale, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating automotive stamping output and steel processing volume trajectories. Industry-specific inputs encompassed salt spray resistance testing protocols and wastewater discharge compliance cost indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biocide regulatory revisions and base oil price volatility. Outputs reflect documented assumptions around REACH enforcement timelines and automotive OEM consolidation patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Emulsion Explosive Market
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
Quenching Fluids and Salts Market
Industrial Chemicals
Isononanol (INA) Market
Industrial Chemicals
Global Ethylene Carbonate Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Propylene Oxide Market
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Mining Explosives Market
Industrial Chemicals
Aerosol Refrigerants Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Sulphur Recovery Technologies Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market