
 Biocides Market | 2026-2036
Biocides Market Size, Share, and Industry Trends Forecast 2026-2036
Biocides Market Analysis
European specialty chemical producers is realigning biocide supply chains toward low-hazard active substances after the EU Biocidal Products Regulation restricted several legacy chemistries. BASF SE leverages its integrated isothiazolinone platform to sustain European manufacturing presence despite regulatory headwinds. Lonza anchors global supply for quaternary ammonium compounds through Swiss-based fermentation and synthesis assets. Nouryon competes in halogenated biocides with dedicated capacity serving Nordic pulp and paper markets.
Biocides are chemical agents formulated to destroy, deter, or control harmful organisms through toxic or growth-inhibiting mechanisms, with active concentrations typically ranging from parts-per-million in preservatives to percent-level doses in disinfectants. Industrial applications span water treatment, coatings, personal care, and agriculture, where microbial control prevents product degradation, equipment fouling, and pathogen transmission. Preservatives dominate value contribution due to their integration into high-volume coatings and cosmetics formulations with recurring purchase cycles. Disinfectants are expanding fastest in healthcare and food processing end uses where sanitation protocols intensified post-pandemic. Water treatment represents a mature but stable demand pool tied to industrial cooling towers and municipal systems with predictable replacement rates.
The EU Biocidal Products Regulation and REACH framework govern active substance approval and environmental release thresholds across European markets, forcing reformulation investments and dossier resubmissions. The EPA regulates antimicrobial pesticides under FIFRA in the United States, requiring efficacy data and ecological risk assessments that extend product development timelines. China's MEE enforces discharge standards for biocide-containing effluents from chemical manufacturing clusters, adding compliance layers for domestic producers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure multi-region product registrations.
Market Dynamics
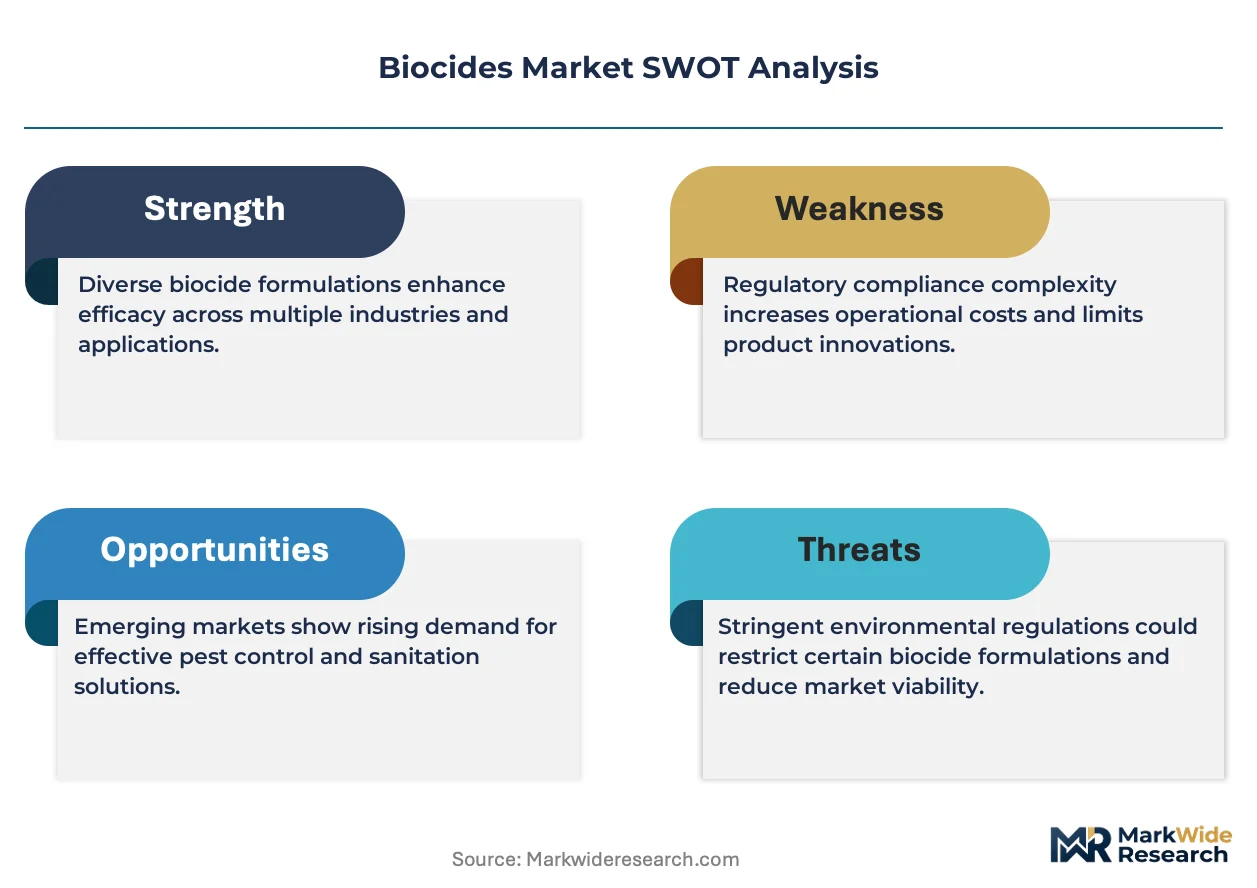
The EU Biocidal Products Regulation is forcing a wholesale chemistry transition as legacy active substances lose approval, compelling formulators to rebuild product portfolios around compliant molecules with shorter efficacy histories and higher raw material costs.
Growth Catalysts
- Water treatment infrastructure expansion:Municipal utilities in China and industrial cooling tower operators across the United States are scaling biocide dosing programs to combat biofilm accumulation in aging distribution networks.
- REACH compliance deadlines:The European Chemicals Agency's accelerated substance review timelines are pulling forward replacement demand for reformulated preservatives in coatings and personal care applications.
- Peracetic acid adoption:Food processing facilities are converting chlorine-based sanitation protocols to peracetic acid systems for residual-free disinfection in ready-to-eat product lines.
Market Restraints
- Active substance concentration:Three Chinese manufacturers control the majority of isothiazolinone intermediate supply, creating vulnerability to export quota disruptions and price volatility.
- Dossier resubmission costs:The EU Biocidal Products Regulation requires extensive toxicological and environmental fate data packages that can exceed seven-figure euro investments per active substance.
- Enzyme-based alternatives:Industrial cleaning applications are experimenting with biofilm-dispersing enzyme cocktails that reduce reliance on traditional biocidal chemistries.
Strategic Opportunities
- Indian agricultural expansion:Crop protection distributors in Maharashtra and Punjab are building cold chain networks that require preservative-treated packaging films and post-harvest disinfectant protocols.
- Green chemistry incentives:The EU Green Deal's sustainable chemistry funding streams are accelerating development of bio-based active substances derived from agricultural waste streams.
- Digital dosing integration:Water treatment operators are deploying IoT-enabled biocide injection systems that optimize consumption and enable predictive maintenance contracts.
Industry Challenges
- Formulation chemist scarcity:The specialized expertise required to balance efficacy, stability, and regulatory compliance across multiple jurisdictions is concentrated among a shrinking pool of experienced professionals.
- Multi-region registration complexity:Securing concurrent approvals under EPA FIFRA, EU BPR, and China's MEE frameworks demands parallel dossier preparation with divergent data requirements and review timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biocides Market |
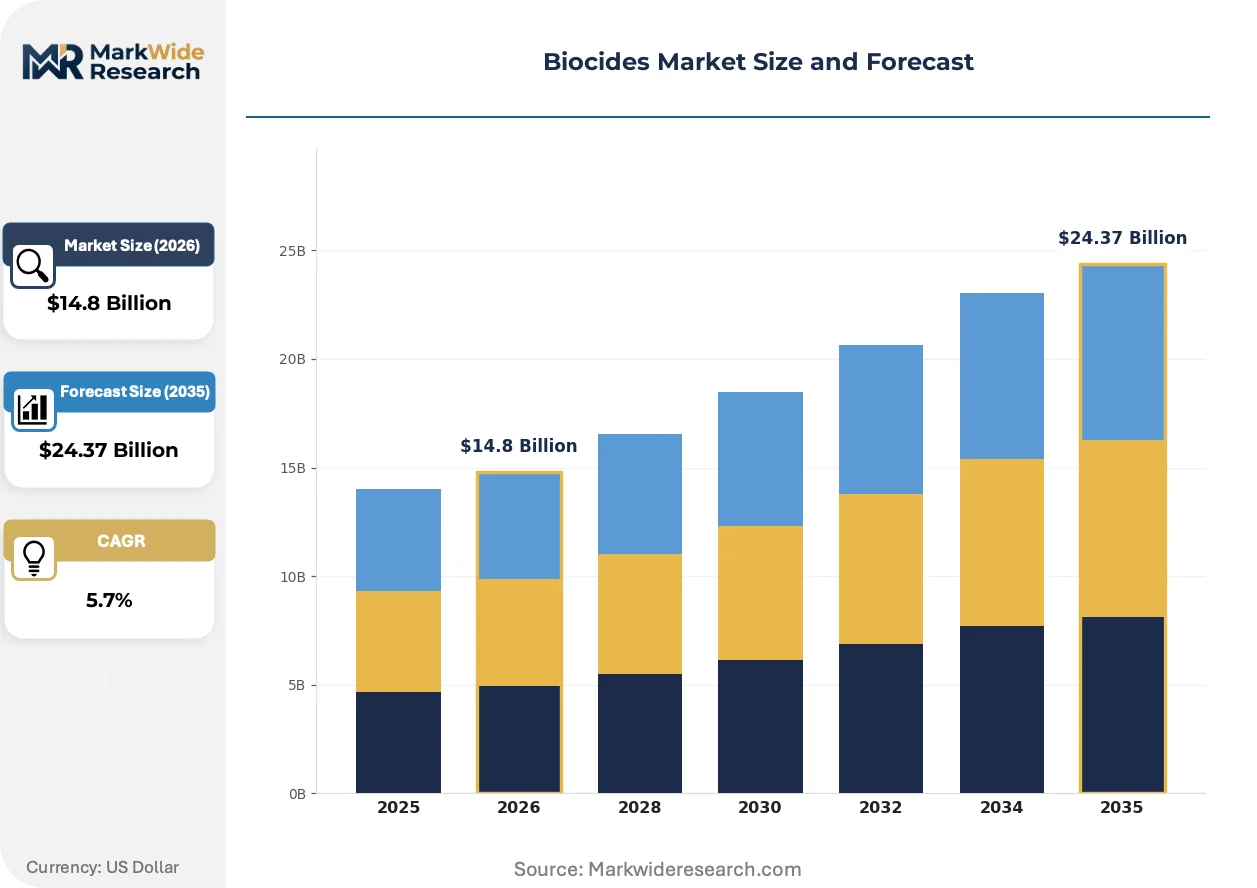
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Disinfectants, Pesticides, Antifouling Agents End User: Healthcare, Agriculture, Food Processing, Water Treatment Form: Liquid, Solid, Gel, Powder Application: Sanitization, Pest Control, Industrial Cleaning, Wood Treatment |
| Companies Covered | Ecolab, LANXESS, BASF SE, Dow, Arxada, Nouryon, Lonza, Clariant, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biocides Market Emerging Trajectories
Formulation science is pivoting toward combination biocide systems that deliver broad-spectrum efficacy while reducing individual active substance concentrations below regulatory trigger thresholds.
Silver nanoparticle composites are overtaking traditional organic biocides in medical device coatings and textile applications. Hospital procurement groups in Germany and Japan are specifying antimicrobial surfaces with sustained-release silver ion technology. This transition is compressing demand for conventional quaternary ammonium compound surface treatments in acute care environments.
REACH authorization requirements are extending review timelines for halogenated biocides used in pulp and paper processing. Finnish and Swedish mills are pre-emptively qualifying alternative chemistries ahead of anticipated substance restrictions. The Nordic pulp sector is accelerating trials of enzymatic slime control systems that reduce dependence on oxidizing biocides.
Food safety auditors are tightening sanitation documentation requirements across European meat and dairy processing facilities. Third-party certification bodies in the Netherlands and Denmark are mandating real-time biocide concentration monitoring as a condition of facility accreditation. This behavioral shift is driving capital investment in automated dosing and verification systems among mid-sized processors.
Biocides Market Segmentation
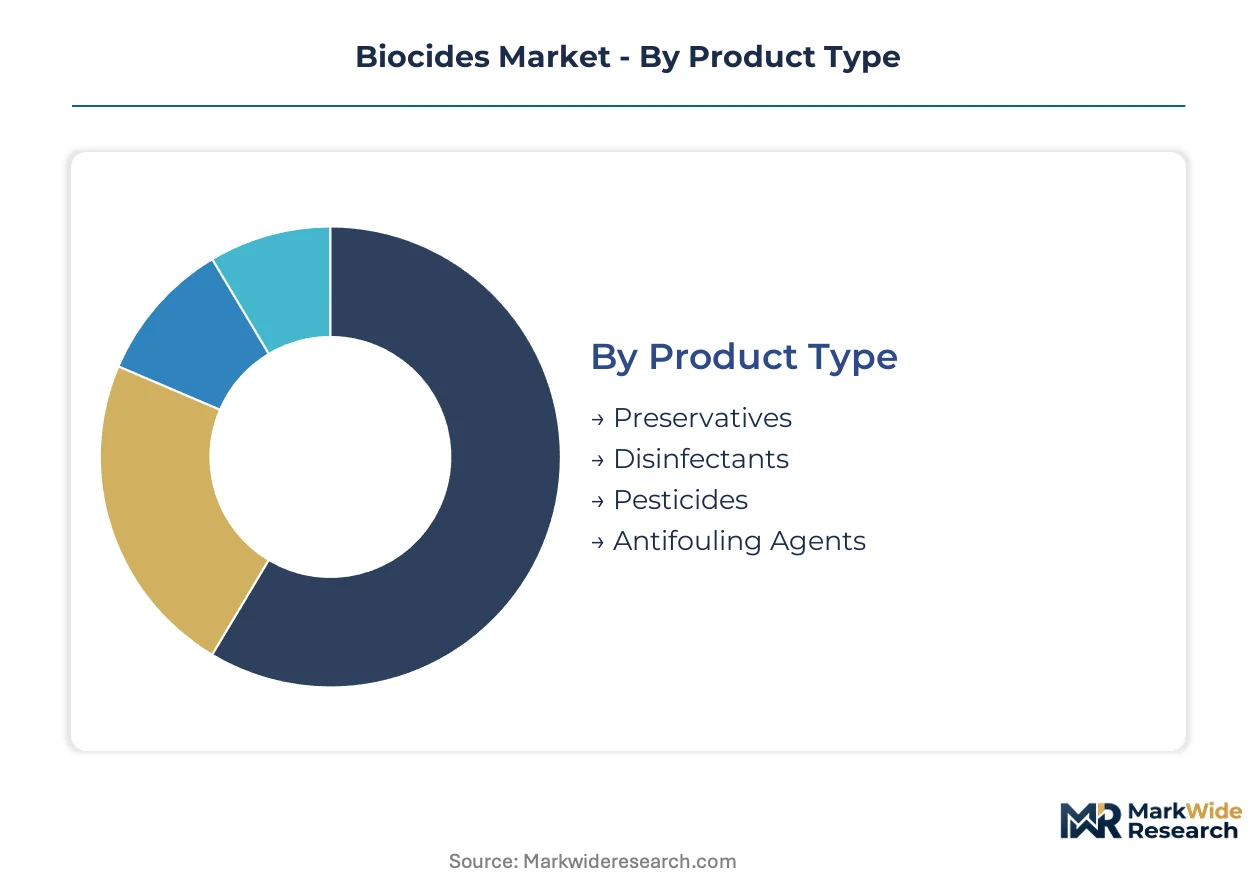
Biocide procurement decisions diverge sharply across end-use contexts, with regulatory compliance timelines and dosing infrastructure requirements creating distinct purchasing workflows for each segment cluster. Formulators must align product architectures with these decision pathways to secure specification approvals.
Product Type:
Buyers prioritize efficacy history and dossier completeness when selecting active substance categories, particularly under tightening EU BPR and EPA FIFRA review schedules.
- Preservatives:These chemistries integrate into coatings, cosmetics, and personal care formulations at parts-per-million concentrations to prevent microbial degradation during shelf life. Demand concentrates in China and Germany where high-volume manufacturing of water-based paints and rinse-off products requires recurring preservative procurement with established supply contracts.
- Disinfectants:Surface and equipment sanitation agents deploy at percent-level concentrations in healthcare and food processing environments. Healthcare facilities in the United States and Japan are converting to peracetic acid and accelerated hydrogen peroxide systems to meet residual-free sanitation protocols.
- Pesticides:Agricultural biocides control crop pests and post-harvest pathogens through foliar application and storage treatment.
- Antifouling Agents:Marine coatings incorporate these chemistries to prevent biofilm accumulation on vessel hulls and offshore infrastructure.
Preservatives lead on scale; disinfectants lead on momentum.
End User:
Volume procurement patterns separate capital-intensive industrial operators from specification-driven institutional buyers with divergent technical support requirements.
- Healthcare:Hospitals and long-term care facilities deploy surface disinfectants and medical device sterilants under Joint Commission and CDC protocol mandates. German and Japanese procurement groups specify silver-ion antimicrobial surfaces, displacing conventional quaternary ammonium treatments in acute care.
- Water Treatment:Municipal utilities and industrial cooling tower operators maintain continuous biocide dosing programs to control biofilm in distribution networks. Chinese municipal authorities are scaling programs to manage aging infrastructure contamination.
- Agriculture:Crop protection and post-harvest preservation drive demand for fungicides and bactericides in grain storage and cold chain packaging.
- Food Processing:Meat and dairy facilities in the Netherlands and Denmark face third-party auditor mandates for real-time biocide concentration monitoring as a condition of facility accreditation.
Water treatment commands the largest volume commitments; healthcare shows the steepest expansion trajectory.
Form:
Physical state determines dosing equipment compatibility and storage logistics, with liquid concentrates dominating continuous-flow industrial applications.
- Liquid:Pumpable concentrates and ready-to-use solutions integrate with automated injection systems in cooling towers and CIP (clean-in-place) equipment. Water treatment operators in the United States are deploying IoT-enabled liquid dosing systems that optimize consumption rates.
- Solid:Tablets and briquettes serve remote or intermittent dosing applications where liquid storage poses logistical constraints.
- Powder:Dry formulations support agricultural dusting and specific industrial cleaning applications requiring precise weight-based measurement.
- Gel:Viscous preparations cling to vertical surfaces and complex geometries in specialized sanitization protocols.
Liquid formulations dominate installed base; solid forms are gaining share in remote infrastructure.
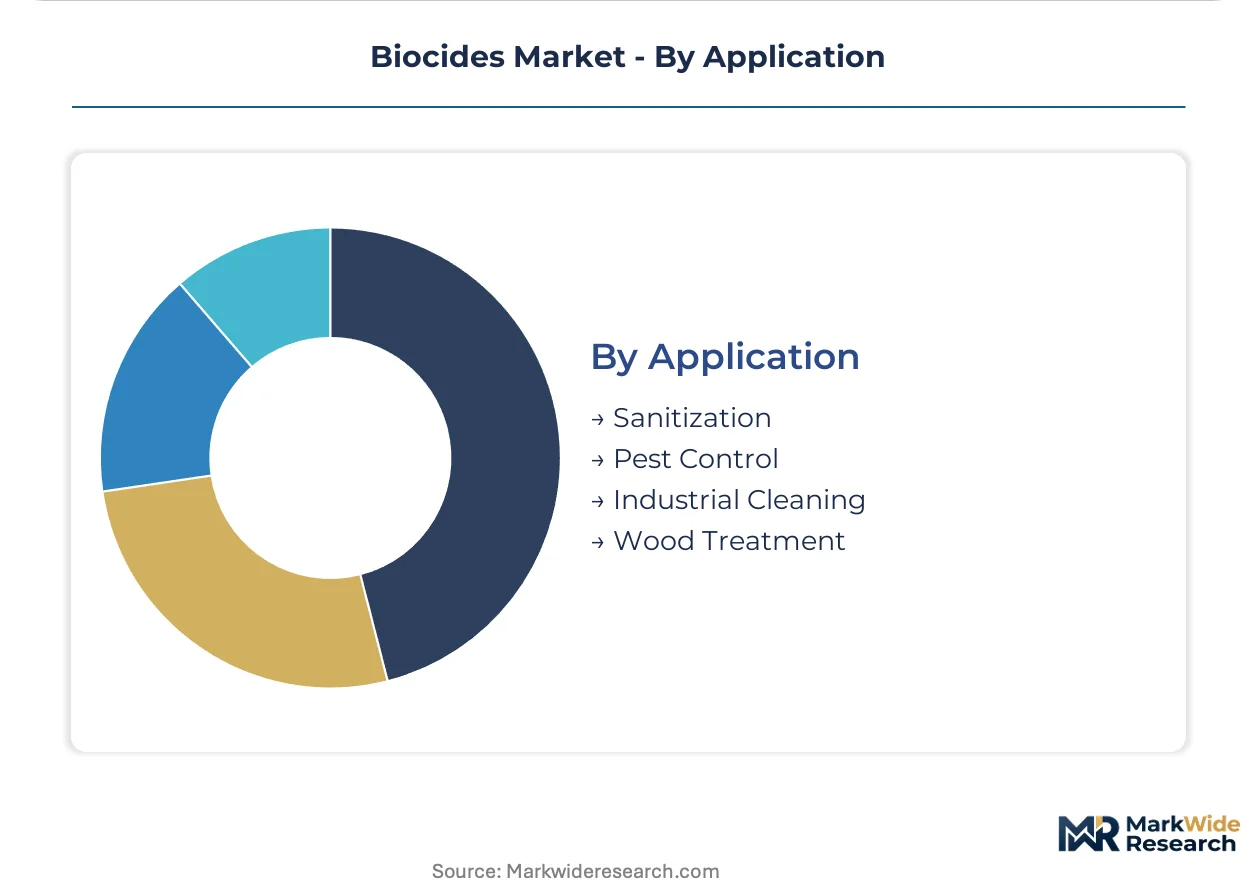
Application:
Performance specifications and contact time requirements separate high-frequency surface sanitation from intermittent pest management and material preservation protocols.
- Sanitization:Food contact surface and healthcare equipment disinfection demands rapid kill kinetics and residue-free breakdown profiles. European meat processors are converting chlorine-based protocols to peracetic acid systems for ready-to-eat product lines.
- Industrial Cleaning:Biofilm removal in heat exchangers and process equipment combines biocidal action with mechanical dispersal. Finnish and Swedish pulp mills are trialing enzymatic slime control to reduce oxidizing biocide dependence ahead of REACH authorization restrictions.
- Pest Control:Structural and agricultural pest management applies rodenticides and insecticides with extended residual activity.
- Wood Treatment:Pressure-treated lumber and engineered wood products incorporate fungicides and insecticides to prevent decay and infestation.
Sanitization anchors current revenue; industrial cleaning is climbing the fastest on regulatory replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial water treatment expansion outpaces Germany's regulatory-driven replacement cycle, while the United States maintains steady demand from healthcare sanitation protocols. Regulatory divergence across these three markets is fragmenting procurement strategies for multinational formulators.
China
Municipal utilities in Jiangsu and Guangdong provinces are scaling chlorine-dioxide and isothiazolinone dosing programs to combat biofilm in aging distribution networks. The Ministry of Ecology and Environment enforces discharge standards for biocide-containing effluents from chemical manufacturing clusters in the Yangtze River Delta. Industrial parks in Ningbo and Shanghai are consolidating wastewater treatment infrastructure, pulling demand for bulk preservative and disinfectant formulations.
Germany
Coatings manufacturers in North Rhine-Westphalia are reformulating water-based paints ahead of EU Biocidal Products Regulation deadlines for legacy active substance phase-outs. The European Chemicals Agency's accelerated substance review timelines are compressing product development cycles for specialty chemical producers. BASF SE anchors isothiazolinone production at Ludwigshafen, supplying preservative actives to domestic formulators navigating compliance transitions.
United States
Healthcare systems in Texas and Florida are converting surface disinfection protocols to peracetic acid systems under Joint Commission sanitation mandates. The EPA regulates antimicrobial pesticides under FIFRA, requiring efficacy data packages that extend registration timelines for new active substances. Industrial cooling tower operators across the Gulf Coast are deploying IoT-enabled biocide injection systems to optimize consumption and enable predictive maintenance contracts.
India
Crop protection distributors in Maharashtra and Punjab are building cold chain networks that require preservative-treated packaging films and post-harvest disinfectant protocols. The Food Safety and Standards Authority of India mandates sanitation documentation for meat and dairy processing facilities in Haryana and Delhi-NCR. Agricultural biotechnology clusters in Hyderabad and Bengaluru are trialing enzyme-based biofilm control as alternatives to traditional biocidal chemistries in food processing applications.
Japan
Hospital procurement groups in Tokyo and Osaka are specifying silver-ion antimicrobial surfaces, displacing conventional quaternary ammonium treatments in acute care environments. The Ministry of Economy, Trade and Industry promotes sustainable chemistry funding streams aligned with antimicrobial material innovation. Medical device manufacturers in the Kansai region are integrating sustained-release silver nanoparticle composites into coating formulations for export markets.
Biocides Market Vendor Landscape
European producers anchor the premium formulation tier; Chinese intermediate suppliers hold cost-advantaged positions in bulk active substance manufacturing. The vendor base separates into three strategic archetypes: integrated chemical conglomerates with captive active substance production, specialized biocide formulators serving regulated end-uses, and regional distributors with blending and logistics assets. Competitive moves concentrate on portfolio diversification into compliant chemistries and backward integration into key intermediate supply.
Among European integrated producers, BASF SE and LANXESS occupy positions exemplifying the conglomerate archetype with cross-divisional biocide capabilities. Lonza represents the specialized manufacturer model with fermentation-based quaternary ammonium compound production. Nouryon sits within the Nordic-focused formulator tier, serving pulp and paper markets with halogenated biocide capacity. These three companies illustrate how geographic origin and corporate structure shape competitive positioning without guaranteeing segment dominance.
| Leading Market Players |
|---|
| Ecolab |
| LANXESS |
| BASF SE |
| Dow |
| Arxada |
| Nouryon |
| Lonza |
| Clariant |
| Solvay |
| Others |
Supply Flow & Price Mechanics
Isothiazolinone intermediate costs from Chinese manufacturers cascade through three distinct pricing tiers before reaching European formulators, with distributor markups widening as regulatory compliance burdens accumulate downstream.
Pricing Analysis
Distributor margins absorb the steepest compression in the biocides trade, particularly for EU-bound shipments where ECHA dossier resubmission costs get embedded in landed pricing. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-sourced quaternary ammonium compounds from Chinese isothiazolinone intermediates and spot-market halogenated biocides. Price differentiation hinges on REACH dossier completeness and ISO certification tier. Cost compression in economy-tier preservatives is intensifying because Indian agricultural distributors negotiate volume offtakes with minimal technical service. Municipal water utilities in China show highest price sensitivity; Japanese medical device manufacturers show least.
Supply Chain Analysis
Reverse logistics for biocide-containing effluents are tightening as MEE discharge standards in China's Yangtze River Delta force manufacturers to recover and reprocess spent active substances. Supply concentrates in China for isothiazolinone intermediates, Switzerland for fermentation-based quaternary ammonium compounds, and Germany for halogenated specialties. Raw material flows draw from chlor-alkali feedstocks, agricultural waste streams for bio-based actives, and silver bullion for nanoparticle composites. Single-source vulnerability looms over Chinese intermediate supply where three producers control export quotas. Distribution runs through regional blending facilities with captive logistics networks serving pulp mills and coatings plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biocides market functions as a geographic-arbitrage play between EU regulatory compliance costs and Chinese manufacturing scale, with formulators capturing margin by qualifying Chinese-sourced actives for European dossier submissions.
For Market Incumbents: Cement supply security through backward integration into isothiazolinone intermediate production or long-term offtake agreements with Zhejiang and Jiangsu manufacturers. ECHA's accelerated substance review timelines threaten stranded inventory for formulators dependent on legacy active substances. Priority lever: captive supply of compliant chemistries ahead of BPR deadline clustering. For New Entrants and Emerging Players: EU Green Deal sustainable chemistry funding in Germany and France opens a window for bio-based active substance developers targeting coatings preservatives. White-space targets include enzyme-based biofilm control for Nordic pulp mills and silver-ion antimicrobial coatings for Japanese medical device exports. Go-to-market angle: third-party dossier preparation services for mid-sized formulators lacking in-house regulatory affairs capacity. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-region registration complexity exceeds internal capabilities of mid-tier formulators. Long-term viability favors specialists with captive active substance production and established EPA FIFRA plus EU BPR dossier libraries. Acquisition target archetype: regional distributors with blending assets and existing channel relationships in water treatment or food processing verticals. Signal to watch: ECHA substance review acceleration triggering distressed divestiture of legacy biocide portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isothiazolinone Intermediates | Captive supply secures margin against Chinese export quota volatility and ECHA compliance deadlines. |
| Bio-Based Active Substance Development | EU Green Deal funding accelerates agricultural waste stream conversion into REACH-compliant preservative chemistries. |
| Multi-Region Dossier Registration | Concurrent EPA FIFRA and EU BPR approvals expand addressable market for disinfectant and sanitizer formulations. |
| IoT-Enabled Dosing System Integration | Predictive maintenance contracts lock in recurring revenue from U.S. Gulf Coast cooling tower operators. |
| Silver Nanoparticle Composite Scale-Up | Japanese medical device specifications drive displacement of quaternary ammonium compounds in acute care procurement. |
Methodological Framework
Direct dialogue with plant managers at European coatings manufacturers, procurement leads at Chinese municipal water utilities, distribution channel partners in Indian agricultural sectors, and technical R&D directors at specialty chemical producers grounded qualitative findings. Secondary validation drew from ECHA substance review databases, EPA FIFRA registration filings, Chinese customs trade data, and Cefic industry reports. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Segment-level projections across preservatives, disinfectants, pesticides, and antifouling agents were generated over the projection horizon, with end-use splits for water treatment, healthcare, agriculture, and food processing applications. CAGRs were derived from weighted average growth across active substance categories, with inputs including ECHA review timeline acceleration, Chinese industrial water treatment infrastructure spending, and peracetic acid adoption curves in U.S. meat processing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden ECHA substance restrictions or Chinese environmental enforcement surges. Practitioners should monitor ECHA substance review acceleration schedules and Chinese MEE discharge standard enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Fixing Agent Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
Global Metal Chelates Market
Specialty Chemicals
Multimodal Chromatography Columns Market
Specialty Chemicals
Divinylbenzene (DVB) Market
Specialty Chemicals
Undecylenic Acid Market
Specialty Chemicals
Organo-Modified Bentonite Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Lignin Products Market
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
Arginine Market