
 Global Molluscicides Market | 2026-2036
Global Molluscicides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molluscicides Market Outlook
Aftermarket technical advisory and resistance-management program revenue is rewriting margin capture in the molluscicide value chain. Lonza Group leverages its copper-based formulation expertise to sustain premium positioning in European horticulture. BASF SE anchors its competitive stance through granular delivery system specialization. Syngenta AG competes on integrated pest management bundling that extends beyond standalone molluscicide sales.
Molluscicides are pest control agents formulated to target gastropod species—snails and slugs—through contact toxicity, bait ingestion, or repellent action, with active ingredients ranging from metaldehyde and iron phosphate to copper compounds and biological extracts such as ferric sodium EDTA. Their primary commercial purpose centers on protecting high-value agricultural output, ornamental plantings, and aquatic infrastructure from yield loss and contamination damage. Copper-based formulations occupy the largest volume share due to established efficacy in perennial crop systems, while biological molluscicides represent the fastest-expanding category as residue-sensitive export markets tighten maximum residue limits. Pellet and granular formulations dominate field application channels, though liquid formulations gain traction in precision-spray greenhouse operations where labor costs drive automation adoption.
The EPA regulates molluscicide registration under FIFRA, with re-registration reviews intensifying scrutiny of metaldehyde ecotoxicity in watershed-adjacent agricultural zones. The EU REACH framework and EFSA residue assessments constrain active ingredient portfolios, while India's Central Insecticides Board mandates local efficacy trials before import clearance. Brazil's national health surveillance agency, ANVISA, governs agricultural chemical approvals with escalating documentation requirements for aquatic toxicity. Stakeholders must monitor regulatory divergence between jurisdictions that increasingly fragments product registration strategies and forces parallel formulation development tracks.
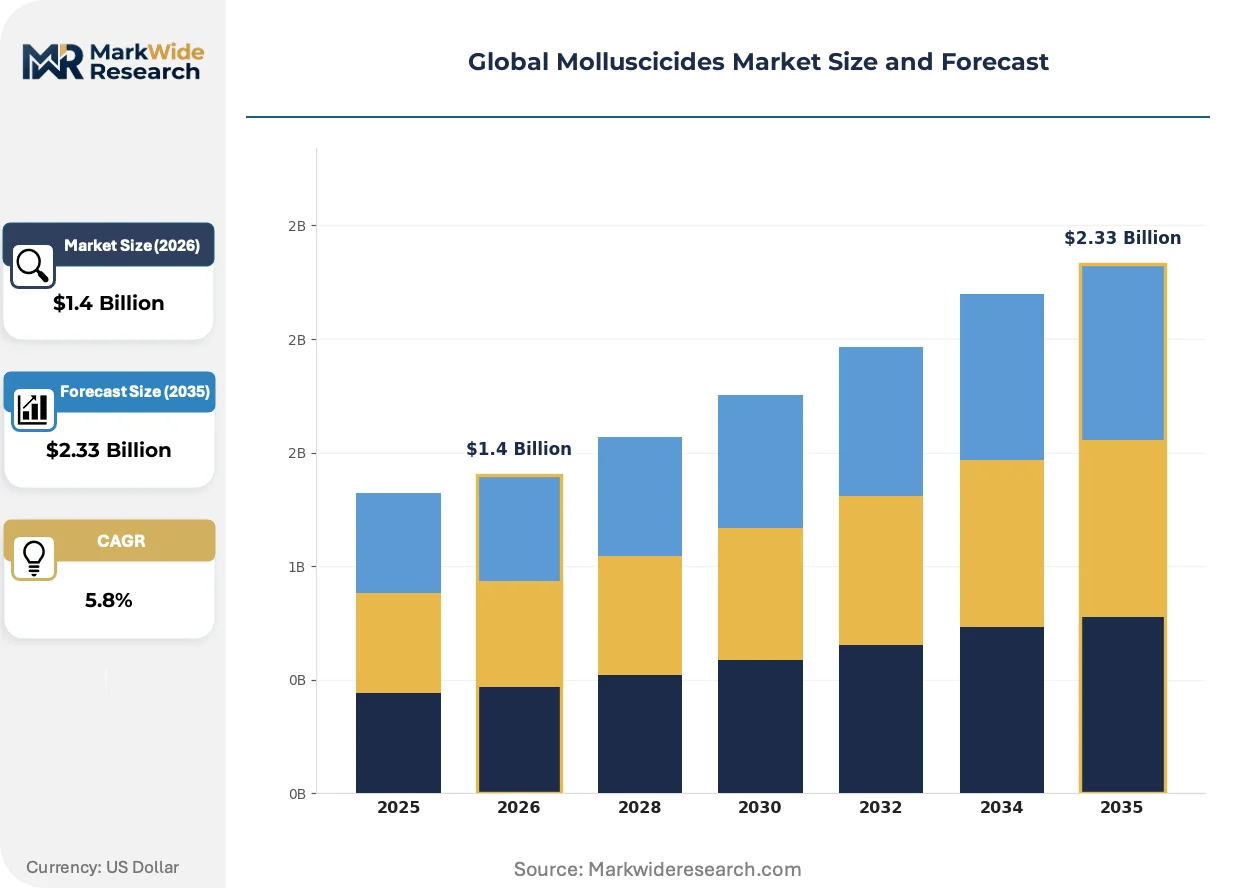
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing active ingredient approval timelines while specialty crop growers in California and Mediterranean horticulture zones expand application rates. This regulatory tightening against established chemistries is forcing parallel formulation development tracks across copper-based and biological alternatives.
Growth Catalysts
- Export market residue limits:Maximum residue limit tightening in residue-sensitive destination markets is pulling biological molluscicide adoption in Brazil's soybean frontier and Australia's protected vegetable sector.
- Protected cultivation expansion:Labor cost pressures in precision-spray greenhouse operations are accelerating automated liquid formulation deployment over manual pellet application.
- Integrated pest management bundling:Grower demand for reduced chemical input portfolios is extending molluscicide value capture into resistance-management program revenue streams.
Market Restraints
- Active ingredient volatility:Metaldehyde ecotoxicity reviews under EPA FIFRA re-registration are constraining watershed-adjacent agricultural use zones in the United States.
- Supply concentration:Copper compound sourcing depends on Chilean and Peruvian mining output concentration, exposing formulation costs to concentrate supply disruptions.
- Regulatory fragmentation:Divergent aquatic toxicity documentation requirements between ANVISA in Brazil and India's Central Insecticides Board are fragmenting product registration strategies.
Strategic Opportunities
- Biological formulation white space:Ferric sodium EDTA and botanical extract categories remain underpenetrated in Southeast Asian rice paddy systems and African horticulture export zones.
- Aftermarket service unbundling:Technical advisory and resistance-monitoring programs represent separable revenue streams from standalone product sales in European perennial crop systems.
- Granular delivery innovation:Precision agriculture integration is creating channel openings for sensor-triggered bait deployment systems in California vineyard and orchard operations.
Industry Challenges
- Formulation chemist scarcity:Expertise in copper chelation stability and biological extract standardization is concentrating among aging specialist workforces in Basel and Mumbai research clusters.
- Parallel track capex burden:Simultaneous development of conventional and biological formulations for jurisdiction-specific approval is stretching R&D facility utilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molluscicides Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper-Based, Iron-Based, Metaldehyde, Biological Application: Agricultural Crops, Residential, Aquatic, Public Health Formulation: Granular, Liquid, Pellet, Emulsifiable Concentrate Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Lonza Group, Bayer AG, BASF SE, AMVAC Chemical Corporation, Adama Agricultural Solutions, Syngenta AG, Marrone Bio Innovations, PI Industries, American Vanguard Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molluscicides Market Strategic Shifts
Digital agriculture infrastructure is virtualizing traditional application methods while regulatory chemistry reviews accelerate biological alternative development. These shifts are compressing product lifecycles and expanding service-anchored revenue models.
Encapsulated ferric sodium EDTA formulations with moisture-activated release mechanisms are virtualizing conventional metaldehyde bait stations in European greenhouse operations. Dutch and Spanish protected vegetable growers are adopting these systems at accelerated pace to preempt REACH authorization sunsets. The technology is virtualizing legacy contact-toxicity application schedules into precision-timed, labor-minimized protocols.
EFSA residue assessments under the EU Green Deal are systematically narrowing approved active ingredient portfolios for molluscicide formulations. This regulatory compression is forcing manufacturers to maintain dual registration tracks for copper-based and biological alternatives simultaneously. Perennial crop systems in Italy and Greece face the steepest reformulation timelines as existing authorizations expire without renewal pathways.
Aftermarket resistance-monitoring subscriptions are displacing transactional product sales in high-value horticulture supply chains. Brazilian soybean cooperatives and Australian vegetable exporter associations are consolidating procurement around integrated pest management providers offering bundled advisory services. This service-layer capture is most visible in contract farming arrangements where yield guarantees depend on documented resistance prevention protocols.
Global Molluscicides Market Segmentation
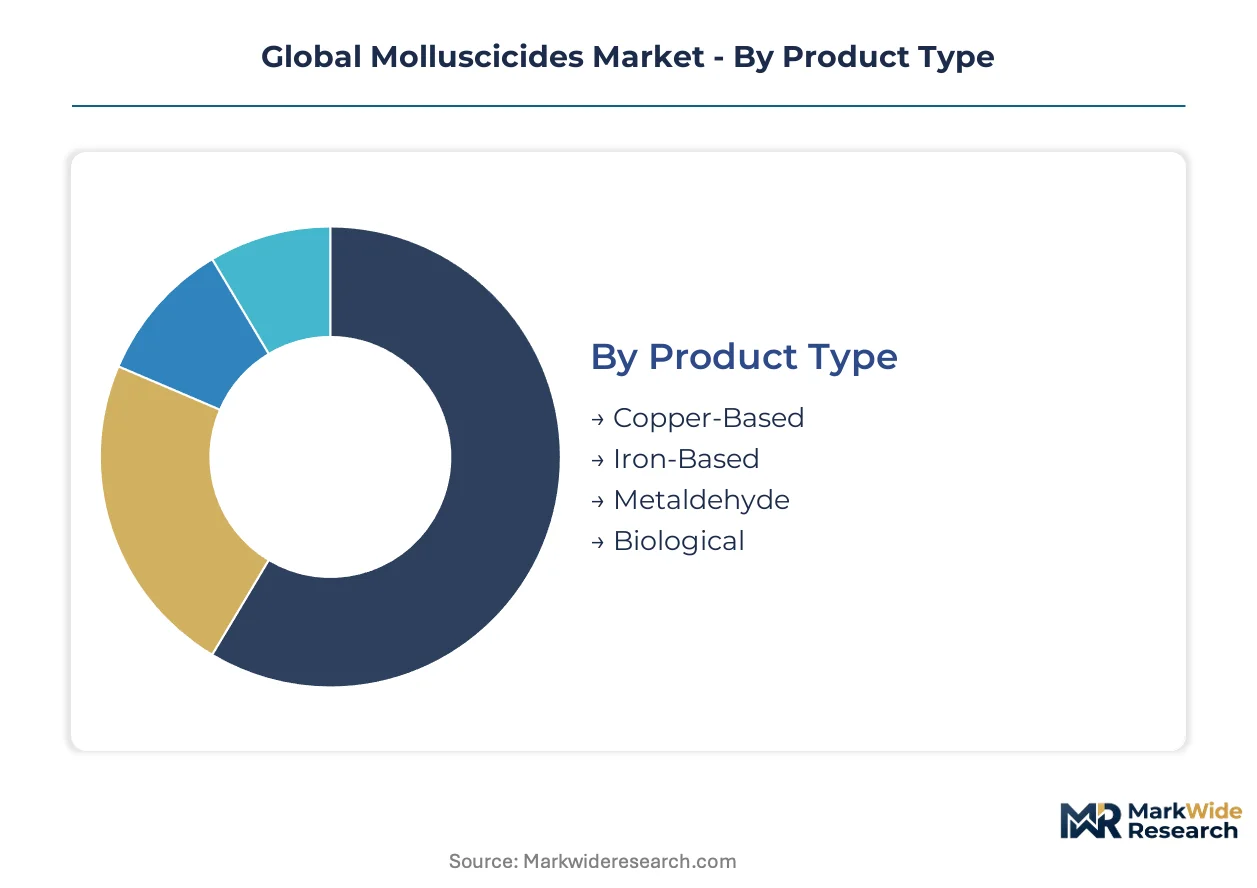
Segmentation in molluscicides reveals how formulation chemistry, application environment, and procurement channel each dictate distinct margin structures and regulatory exposure. Copper-based granules for perennial orchards carry fundamentally different cost-to-serve profiles than biological liquids for greenhouse automation.
Product Type:
Cost tier stratification across active ingredient categories separates premium biological formulations from commodity metaldehyde positions, with copper-based products occupying the volume-heavy middle ground.
- Copper-Based:Formulations leverage copper sulfate pentahydrate and copper hydroxide complexes with established efficacy in vineyard and citrus perennial systems. Demand concentrates in Italian and Greek horticulture export zones where residue-sensitive destination markets enforce strict maximum limits on synthetic alternatives.
- Biological:Ferric sodium EDTA and botanical extract formulations target residue-zero certification requirements in Dutch and Spanish protected vegetable operations. Adoption accelerates in Brazil's soybean frontier as European import standards tighten.
- Iron-Based:Ferric phosphate baits serve residential and organic-certified agricultural segments with lower ecotoxicity profiles than metaldehyde.
- Metaldehyde:Contact-toxicity baits face EPA FIFRA re-registration constraints in watershed-adjacent zones of California and the Pacific Northwest.
Copper-based formulations command the established base. The steepest expansion runs through biological alternatives.
Application:
Application environment determines formulation stability requirements, with aquatic and public health segments imposing distinct dissolution-rate specifications versus terrestrial agricultural use.
- Agricultural Crops:Field and protected cultivation systems in California's Central Valley and Australia's Lockyer Valley vegetable belt drive pellet and granular consumption. Yield loss prevention in high-value horticulture justifies premium pricing.
- Residential:Home garden and ornamental applications favor ready-to-use pellet formats with reduced application complexity for non-professional users.
- Aquatic:Submerged and shoreline treatments for irrigation infrastructure and recreational water bodies require specialized slow-release formulations meeting ANVISA aquatic toxicity documentation.
- Public Health:Vector control programs target snail intermediate hosts of schistosomiasis and other parasitic diseases, primarily in African and Southeast Asian health interventions.
Agricultural crop applications anchor volume demand. Public health programs represent the fastest-climbing trajectory as tropical disease control funding expands.
Formulation:
Physical delivery format shapes labor economics and precision agriculture compatibility, with liquid formulations gaining automation advantage in capital-intensive greenhouse operations.
- Granular:Broadcast-applied granules with rainfast binding agents dominate California vineyard and almond orchard floor management. Established equipment compatibility sustains grower preference despite higher labor intensity.
- Liquid:Precision-spray formulations integrate with automated greenhouse infrastructure in Dutch Venlo systems and Australian hydroponic facilities. Labor cost pressures accelerate displacement of manual pellet application.
- Pellet:Molded bait products with moisture-activated release serve residential and small-scale agricultural channels through retail distribution.
- Emulsifiable Concentrate:Concentrated liquid formulations for professional dilution and application in large-scale agricultural and aquatic treatment programs.
Granular formats retain the installed base. Liquid formulations are gaining share fastest through protected cultivation automation.
Distribution Channel:
Channel structure reflects customer scale and technical advisory requirements, with direct sales capturing integrated pest management bundling opportunities in cooperative procurement.
- Direct Sales:Manufacturer-to-grower relationships in Brazilian soybean cooperatives and Australian vegetable exporter associations bundle resistance-monitoring subscriptions with product supply. Technical advisory services anchor long-term contracts.
- Wholesale:Agricultural supply distributors serve mid-scale specialty crop operations in Mediterranean horticulture zones with inventory buffering and local agronomic support.
- Retail:Garden center and farm supply store channels reach residential users and smallholder producers with standardized pellet and ready-to-use formats.
- Online:E-commerce penetration remains limited by regulatory shipping restrictions on active ingredient classifications and grower preference for localized technical consultation.
Direct sales channels capture the highest-margin advisory-anchored relationships. Online distribution shows the steepest expansion trajectory as regulatory clarity improves for biological formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: European growers prioritize residue-zero certification for export compliance, while Brazilian and Australian producers emphasize yield protection in expanding agricultural frontiers. Mediterranean horticulture and California's specialty crop belts anchor premium formulation demand.
United States
California's Central Valley vineyards and Pacific Northwest berry operations drive pellet and granular consumption for orchard floor management. EPA FIFRA re-registration reviews intensify scrutiny of metaldehyde ecotoxicity in watershed-adjacent zones, constraining established chemistry deployment. The Salinas Valley vegetable belt concentrates biological formulation trials as residue limits tighten for Asian export markets.
Brazil
Soybean frontier expansion in Mato Grosso and Goiás pulls molluscicide demand for seedling protection against slug damage in no-till systems. ANVISA aquatic toxicity documentation requirements escalate for irrigation-adjacent applications, fragmenting registration strategies. São Paulo-state cooperatives consolidate procurement around integrated pest management providers bundling advisory services with product supply.
Italy
Po Valley citrus and stone fruit export zones enforce strict maximum residue limits for Northern European destination markets, favoring copper-based formulations. EU REACH framework and EFSA residue assessments systematically narrow approved active ingredient portfolios. Emilia-Romagna's protected vegetable operations accelerate ferric sodium EDTA adoption ahead of authorization sunsets.
Australia
Lockyer Valley protected vegetable belt and New South Wales greenhouse operations drive liquid formulation demand for automated precision-spray infrastructure. TGA agricultural chemical registrations align with residue-sensitive Asian export protocols. Queensland's expanding protected cultivation sector concentrates biological molluscicide trials for premium horticulture export chains.
India
Maharashtra and Karnataka horticulture export zones mandate local efficacy trials under Central Insecticides Board protocols before import clearance. Grape and pomegranate operations in Nashik district adopt copper-based formulations for European market compliance. Andhra Pradesh's expanding greenhouse vegetable sector represents underpenetrated terrain for biological alternatives.
Global Molluscicides Market Competitive Environment
Capability concentration sits with specialty formulation developers; scale advantage sits with diversified agricultural chemical portfolios. The vendor base stratifies across three tiers: integrated multinationals with granular delivery system specialization, biological extract specialists targeting residue-zero segments, and regional distributors capturing service-layer revenue through resistance-monitoring subscriptions. Dominant competitive moves include parallel registration track maintenance for jurisdiction-specific approvals and aftermarket service unbundling from standalone product sales.
Within the integrated multinational tier, Lonza Group, BASF SE, and Syngenta AG exemplify divergent strategic positioning. Lonza Group leverages copper-based formulation expertise to sustain premium positioning in European horticulture. BASF SE anchors competitive stance through granular delivery system specialization. Syngenta AG competes on integrated pest management bundling that extends beyond standalone molluscicide sales. These three entities represent distinct archetypes: metal chelation specialists, physical delivery innovators, and service-layer integrators respectively.
| Leading Market Players |
|---|
| Lonza Group |
| Bayer AG |
| BASF SE |
| AMVAC Chemical Corporation |
| Adama Agricultural Solutions |
| Syngenta AG |
| Marrone Bio Innovations |
| PI Industries |
| American Vanguard Corporation |
| Others |
Value Chain & Pricing Dynamics
Chilean and Peruvian copper concentrate output concentration anchors formulation cost structures for copper-based molluscicides, pushing margin pools downstream toward biological extract standardization and resistance-management service bundling in European perennial crop systems.
Pricing Analysis
Long-term offtake contracts dominate procurement between Brazilian soybean cooperatives and integrated pest management providers, while spot purchases persist for smallholder horticulture operators in Mediterranean zones. Price differentiation hinges on residue-zero certification tier and bundled advisory service depth, with biological formulations commanding premium positioning over commodity metaldehyde positions. Pricing pressure intensifies in watershed-adjacent agricultural zones where EPA FIFRA re-registration constrains established chemistry deployment. Smallholder producers exhibit highest price sensitivity; export-oriented cooperative buyers prioritize compliance guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing capacity for encapsulated ferric sodium EDTA concentrates in Basel and Mumbai research clusters, with toll formulation partnerships extending to Dutch and Spanish greenhouse supply zones. Active ingredient sourcing draws from Chilean copper mining, Indian botanical extract cultivation, and Chinese iron phosphate processing. Single-source vulnerability concentrates in copper concentrate supply channels exposed to Andean mining disruptions. Distribution runs through agricultural supply distributors with inventory buffering for Mediterranean horticulture zones, direct sales channels for Brazilian cooperative procurement, and retail garden center networks for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
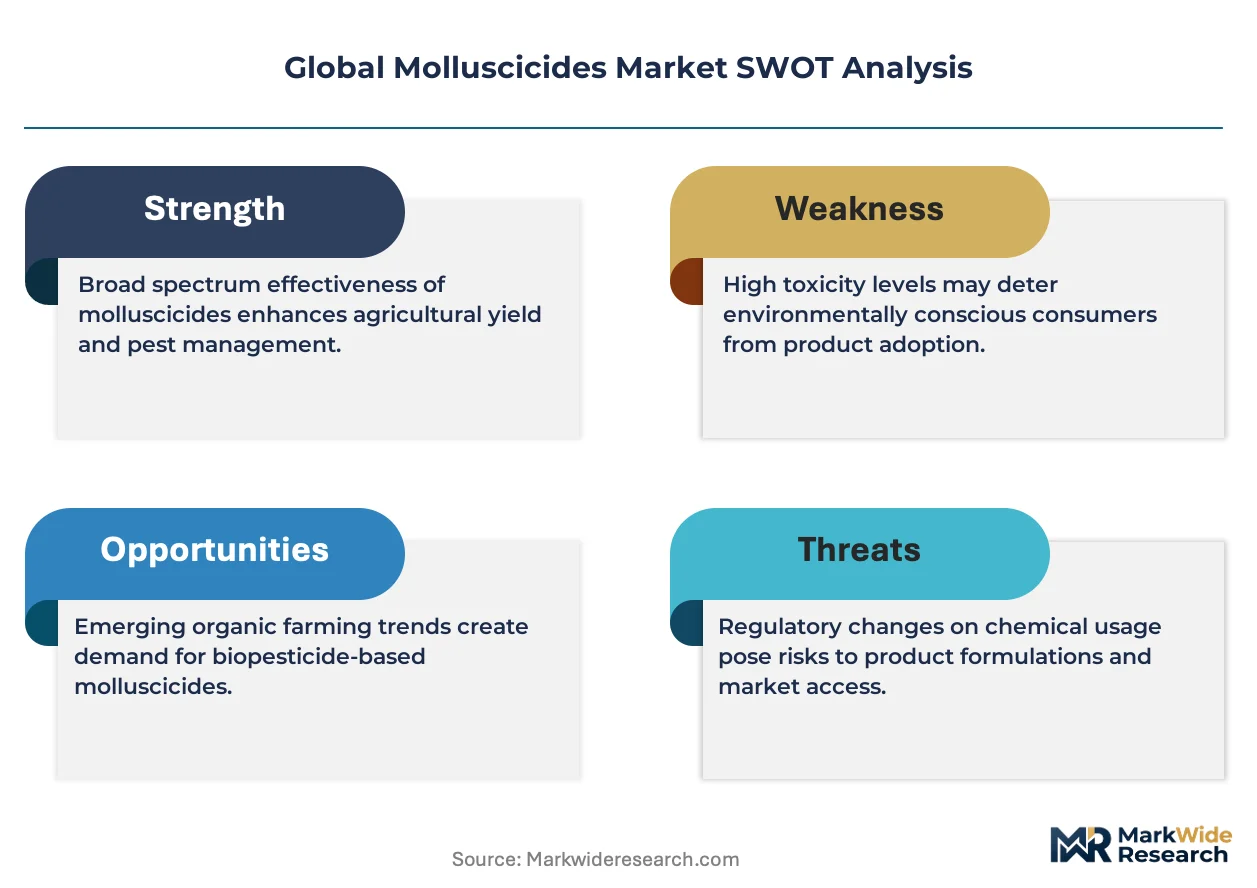
This market functions as a defensive-moat story anchored in regulatory entrenchment: EFSA residue assessments and EPA FIFRA re-registration timelines create asymmetric barriers that favor incumbents with parallel formulation development capabilities and jurisdiction-specific registration expertise.
For Market Incumbents: Pre-empt biological formulation white space in Southeast Asian rice paddy systems before REACH authorization sunsets accelerate competitive displacement in European markets. Deepen backward integration into copper chelation stability expertise and botanical extract standardization capabilities to offset formulation chemist scarcity in aging Basel and Mumbai research clusters. Lock in long-term offtake agreements with Brazilian soybean cooperatives to anchor volume visibility against emerging biological specialists. For New Entrants and Emerging Players: Establish a beachhead in Andhra Pradesh's expanding greenhouse vegetable sector, where Central Insecticides Board efficacy trial requirements have constrained multinational penetration and local formulation partnerships unlock faster import clearance. Target Queensland's protected cultivation sector with ferric sodium EDTA liquid formulations optimized for automated precision-spray infrastructure. Pursue co-development arrangements with Dutch Venlo system integrators to bypass direct competition with established granular delivery incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed biological extract specialists holding residue-zero certification pipelines but lacking integrated pest management bundling capabilities to capture service-layer revenue. Five-to-ten-year viability hinges on successful navigation of EU Green Deal authorization sunsets and EPA watershed ecotoxicity constraints. Monitor ANVISA aquatic toxicity documentation requirement escalations as inflection indicator for registration strategy fragmentation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Parallel Registration Track Maintenance | Dual copper-based and biological formulation development secures jurisdiction-specific approvals ahead of EFSA authorization sunsets. |
| Backward Integration into Extract Cultivation | In-house botanical supply chains reduce dependency on Indian raw material sourcing volatility for residue-zero formulations. |
| Resistance-Monitoring Subscription Launch | Aftermarket service unbundling captures recurring revenue from Brazilian cooperatives and Australian exporter associations. |
| Precision Agriculture Partnership | Sensor-triggered bait deployment integration opens California vineyard channels beyond commodity granular positions. |
| Greenhouse Automation Formulation Development | Liquid formulation optimization for Dutch Venlo systems accelerates displacement of labor-intensive pellet application. |
Study Parameters
Operator-level perspectives from specialty crop growers in California and Mediterranean horticulture zones, formulation chemists at copper chelation and biological extract research clusters, procurement leads at Brazilian soybean cooperatives, and regulatory affairs specialists navigating EPA FIFRA and EU REACH frameworks anchored the qualitative base. Secondary validation drew from EPA registration databases, EFSA residue assessment publications, ANVISA aquatic toxicity documentation filings, and customs trade data for copper concentrate and botanical extract flows. Bottom-up demand modeling across application segments triangulated against top-down value chain margin analysis.
Scenario-bracketing across regulatory authorization timelines, copper concentrate supply disruptions, and biological adoption curves framed the analytical envelope. Segmentation dimensions modeled encompassed active ingredient chemistry tier, application environment stability requirements, formulation physical delivery format, and procurement channel technical advisory intensity. CAGRs were derived from installed base erosion rates for constrained chemistries and penetration curves for biological alternatives, with greenhouse automation adoption and export market residue limit tightening as primary demand drivers.
Stress conditions across EFSA authorization sunset acceleration, Andean mining supply disruptions, and Central Insecticides Board import clearance delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory trajectory and technology substitution elasticities. Quarterly review of EPA FIFRA re-registration comment periods, ANVISA documentation requirement bulletins, and EU Green Deal implementation guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
Cooling Tower Chemicals Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
Global Dodecanedioic Acid Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
Synthetic Gypsum Market